
 HR Tech Market | 2026-2036
HR Tech Market Size, Share, and Industry Trends Forecast 2026-2036
HR Tech Market Outlook
The gap between premium all-in-one workforce platforms and point-solution commodity tools is restructuring competitive dynamics in HR technology. Rippling leverages its unified payroll, benefits, and IT management stack to anchor enterprise accounts with complex global operations. HiBob competes through specialized mid-market positioning with strong employee engagement and people analytics capabilities. Gusto sustains dominance among small enterprises through streamlined payroll processing and intuitive self-service interfaces.
HR technology encompasses software systems, cloud infrastructure, and algorithmic tools designed to automate human capital functions including recruitment, compensation administration, performance evaluation, and workforce analytics, typically deployed through multi-tenant SaaS architectures with API-first integration protocols. Payroll Processing and Applicant Tracking System segments occupy established revenue positions due to regulatory complexity and high switching costs, while Learning Management and Employee Engagement functionalities represent faster-growing margin pools as reskilling imperatives intensify. Cloud-Based and SaaS deployment models lead volume expansion, though Hybrid configurations persist in regulated industries requiring localized data residency.
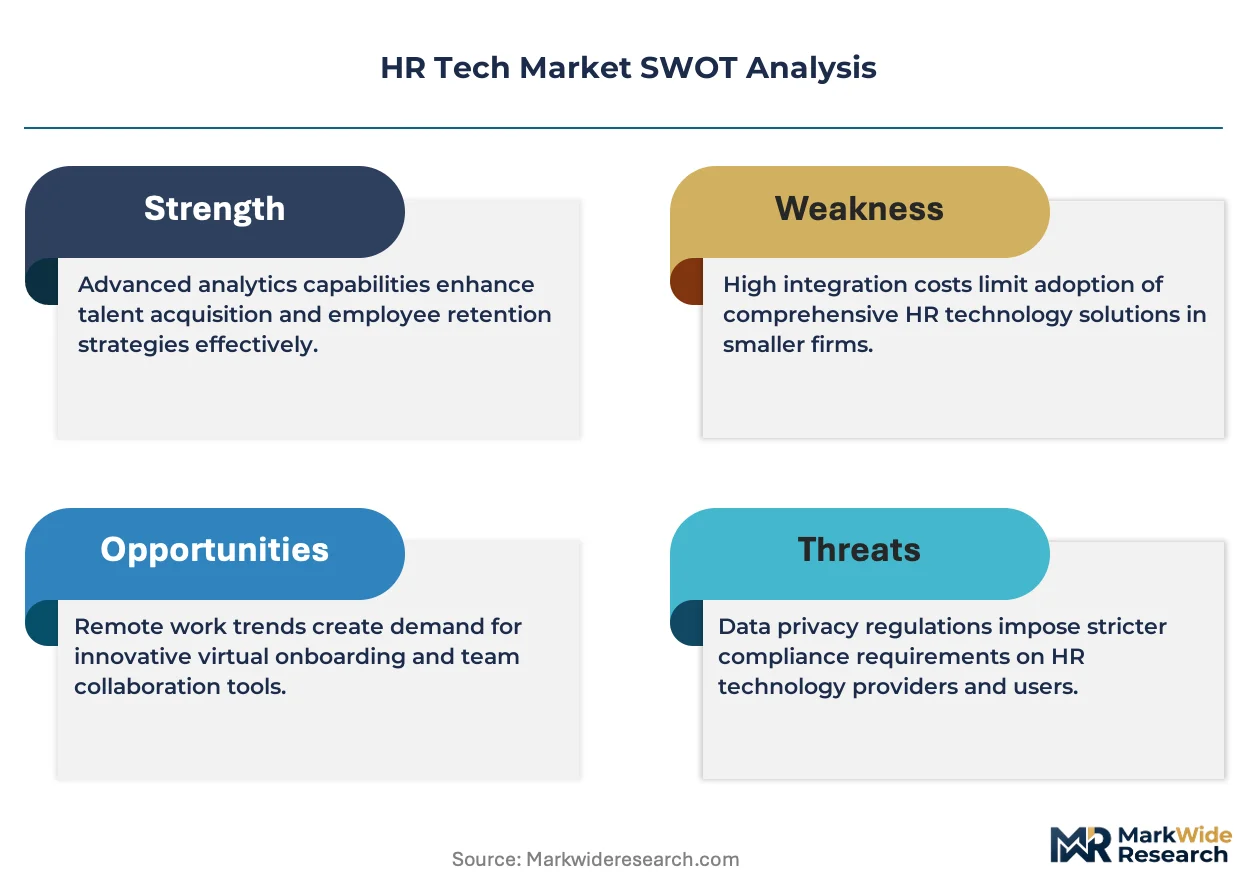
FDA oversight of AI-enabled hiring tools, EU GDPR constraints on employee data processing, and emerging SEC human capital disclosure requirements collectively elevate compliance module demand across vendor portfolios. OSHA recordkeeping digitization mandates and ISO 30414 human capital reporting standards further shape product development roadmaps for analytics functionality. Stakeholders must evaluate whether algorithmic transparency investments will become table stakes or sustainable differentiators as procurement criteria evolve.
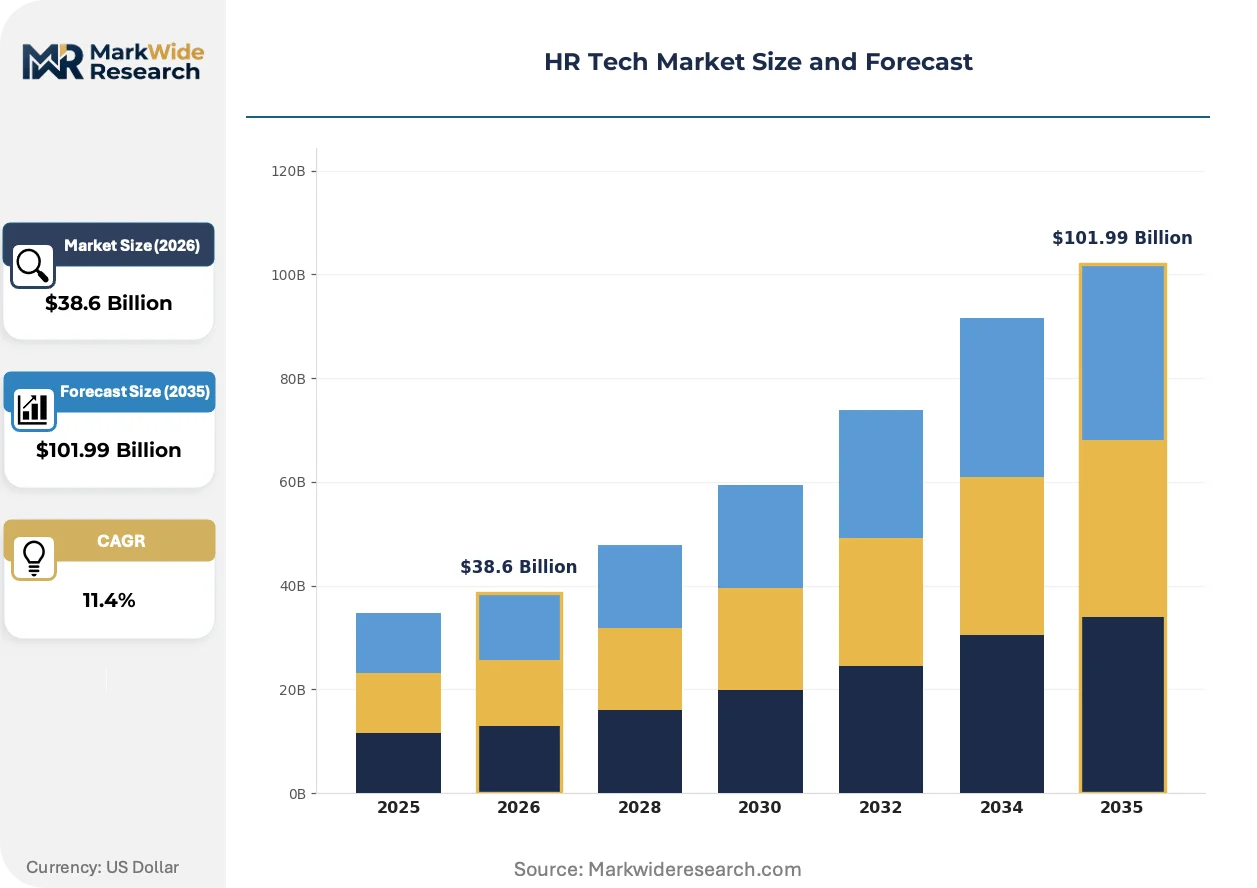
Market Dynamics
Cloud-native workforce management platforms are compressing the addressable market for on-premise HR systems while simultaneously expanding total spend through embedded financial services and cross-border compliance modules.
Growth Catalysts
- EU AI Act algorithmic accountability mandates:Employers deploying automated hiring and performance evaluation tools face mandatory bias auditing requirements, creating sustained demand for compliance-integrated HR platforms across European operations.
- Reskilling imperatives in manufacturing and healthcare:Workforce transformation programs in industrial verticals are accelerating Learning Management System procurement as employers address technical skill obsolescence.
- India's PLI scheme workforce scale-up:Electronics and pharmaceutical manufacturing incentives are driving massive hiring waves that require scalable applicant tracking and onboarding infrastructure.
Market Restraints
- Data localization requirements:Russia, China, and Vietnam mandate in-country server residency for employee records, fragmenting vendor architectures and inflating infrastructure costs for multinational deployments.
- High switching costs in payroll:Tax filing history and benefits enrollment data lock enterprises into incumbent providers despite superior feature sets from challengers.
- Talent scarcity in AI ethics and bias auditing:The specialized skill set required for algorithmic compliance outstrips supply, constraining vendor ability to certify products rapidly.
Strategic Opportunities
- Embedded finance convergence:Integration of earned wage access, micro-insurance, and retirement savings tools into payroll workflows creates new revenue pools beyond SaaS subscriptions.
- OSHA digitization mandates:US employers must modernize incident reporting and safety training documentation, opening compliance automation modules for injury prevention platforms.
- ISO 30414 human capital reporting:Standardized workforce metrics disclosure requirements in Europe and Asia-Pacific create demand for analytics dashboards that aggregate engagement, diversity, and productivity data.
Industry Challenges
- API integration complexity:Enterprise IT departments struggle to maintain connectivity between legacy ERP systems and modern HR platforms, delaying implementation timelines and eroding ROI.
- Cross-border benefits harmonization:Multi-country employers face fragmented regulatory requirements for health insurance, parental leave, and retirement contributions that resist platform standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HR Tech Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Software Type: Applicant Tracking System, Performance Management, Payroll Processing, Learning Management Deployment Model: Cloud-Based, On-Premises, Hybrid, SaaS End User: Small Enterprises, Medium Enterprises, Large Corporations, Staffing Agencies Functionality: Recruitment, Employee Engagement, Analytics, Compliance |
| Companies Covered | Ashby, Findem, Rippling, Paylocity, Workhuman, Deel, HiBob, Jobandtalent, Gusto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HR Tech Market Strategic Shifts
Generative AI is penetrating core HR workflows from job description drafting to performance feedback synthesis, compressing administrative labor while raising governance stakes around hallucination risk and discriminatory outputs.
Agentic AI systems that autonomously execute multi-step workforce processes are rewriting how mid-market employers manage scheduling, leave approvals, and expense reimbursement. HR departments at professional services firms and retail chains are piloting these tools to reduce manager administrative burden. The technology is rewriting cost structures by collapsing tier-one support roles into self-service interfaces while elevating strategic HR business partner headcount.
The EU AI Act's risk classification framework for employment-related algorithms is forcing vendors to rearchitect product roadmaps around explainability and human-in-the-loop design. High-risk systems for recruitment and performance evaluation now require conformity assessments before market entry. North American vendors with European client bases are accelerating investment in bias detection tooling and audit trail functionality to maintain market access.
Subscription fatigue among finance and HR buyers is consolidating procurement around unified platforms that displace point solutions for recruiting, onboarding, and workforce analytics. Mid-market employers in Germany and the United States are negotiating enterprise-wide contracts that bundle previously separate vendor relationships. This consolidation is most visible in technology and healthcare verticals where CFOs are mandating vendor reduction programs to streamline integration overhead and contract management.
HR Tech Market Segmentation
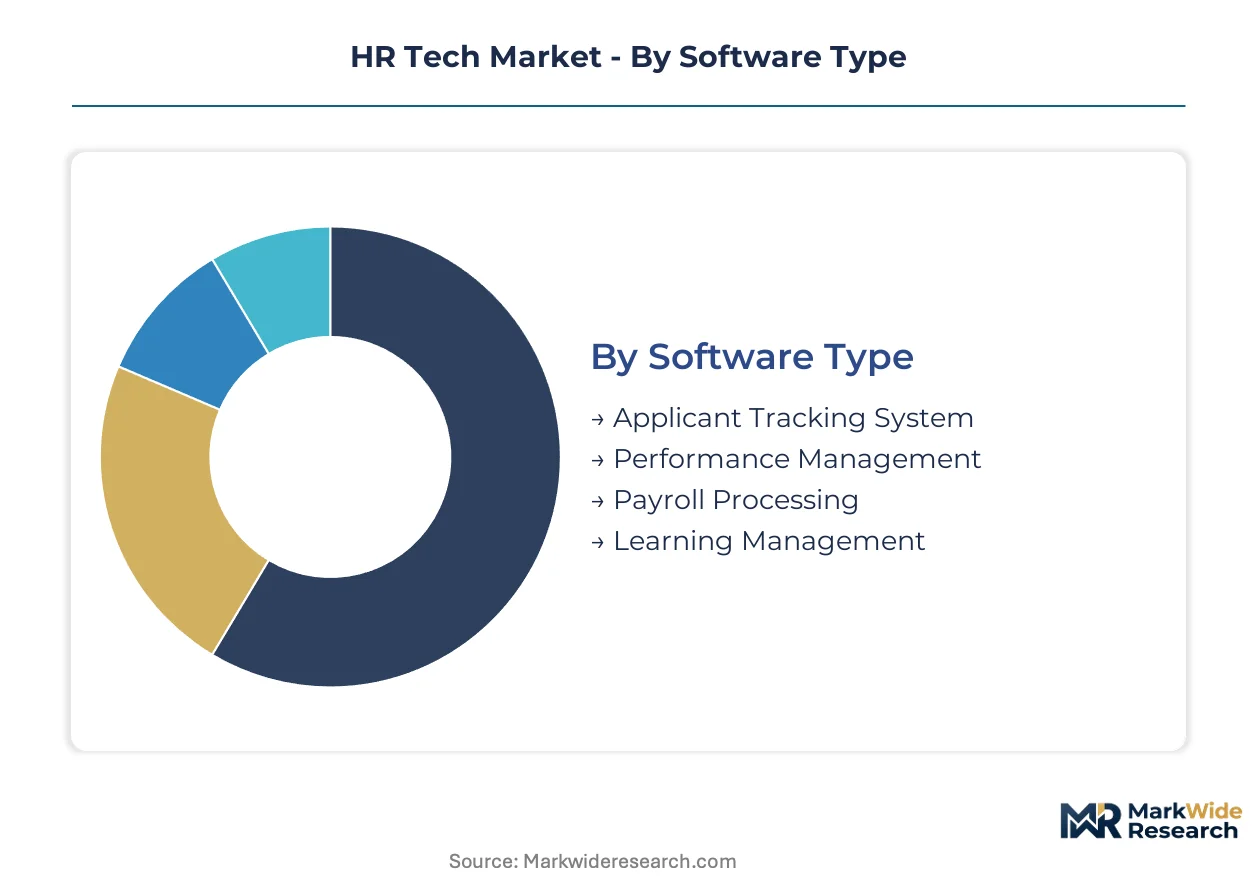
Segmentation in HR technology reveals how vendor architectures align with employer operational complexity and regulatory exposure. Procurement patterns diverge sharply between integrated platform buyers and specialized point-solution adopters.
Software Type:
Integration depth varies substantially across software categories, with some functions operating as embedded modules within unified suites while others persist as standalone deployments.
- Payroll Processing:Tax calculation engines and benefits administration workflows form the core financial infrastructure for workforce operations. Demand concentrates among mid-market employers in Germany and the United States facing multi-jurisdictional compliance complexity. High switching costs and regulatory filing histories lock enterprises into incumbent providers despite feature gaps.
- Applicant Tracking System:Candidate sourcing pipelines and interview scheduling automation reduce time-to-hire metrics for high-volume recruiting operations. India's electronics manufacturing PLI scheme beneficiaries are scaling ATS infrastructure to manage workforce expansion. EU AI Act bias auditing mandates are reshaping vendor certification requirements for European deployments.
- Performance Management:Goal-setting frameworks and continuous feedback mechanisms support talent development programs.
- Learning Management:Reskilling platforms address technical skill obsolescence in manufacturing and healthcare verticals.
Payroll Processing leads volumes today; Learning Management is gaining share fastest.
Deployment Model:
Cost tier structures separate enterprise-grade infrastructure investments from streamlined subscription offerings targeting resource-constrained buyers.
- Cloud-Based:Multi-tenant architectures with API-first integration protocols enable rapid scaling without capital expenditure. Technology and healthcare verticals in the United States are consolidating procurement around cloud-native platforms to displace legacy on-premise installations. Subscription economics align with CFO-mandated vendor reduction programs.
- SaaS:Browser-accessible workforce tools with automatic feature updates reduce IT maintenance burden for mid-market employers. Germany's Mittelstand segment favors SaaS deployments for cross-border compliance standardization across European operations. Embedded finance modules create incremental revenue pools beyond base subscriptions.
- Hybrid:Regulated industries requiring localized data residency maintain on-premise components for sensitive employee records.
- On-Premises:Legacy installations persist in organizations with specialized security requirements or sunk infrastructure investments.
Cloud-Based deployments dominate new procurement; SaaS is expanding most quickly among mid-market converts.
End User:
Application intensity scales with organizational complexity, from streamlined payroll for simple structures to multi-entity workforce orchestration for global operations.
- Large Corporations:Global workforce platforms integrating payroll, benefits, and IT management across dozens of jurisdictions. Complex entity structures in the United States and Germany demand embedded compliance modules for cross-border tax and regulatory harmonization. Procurement teams negotiate enterprise-wide contracts bundling previously separate vendor relationships.
- Medium Enterprises:Mid-market positioning with strong people analytics and employee engagement capabilities. Growth-stage technology companies prioritize scalable infrastructure that accommodates rapid headcount expansion without system replacement.
- Small Enterprises:Streamlined payroll processing with intuitive self-service interfaces minimizes administrative overhead for owner-operators.
- Staffing Agencies:High-velocity onboarding and credential verification tools support contingent workforce management.
Large Corporations anchor vendor revenue today; Medium Enterprises are climbing the fastest as digital transformation programs mature.
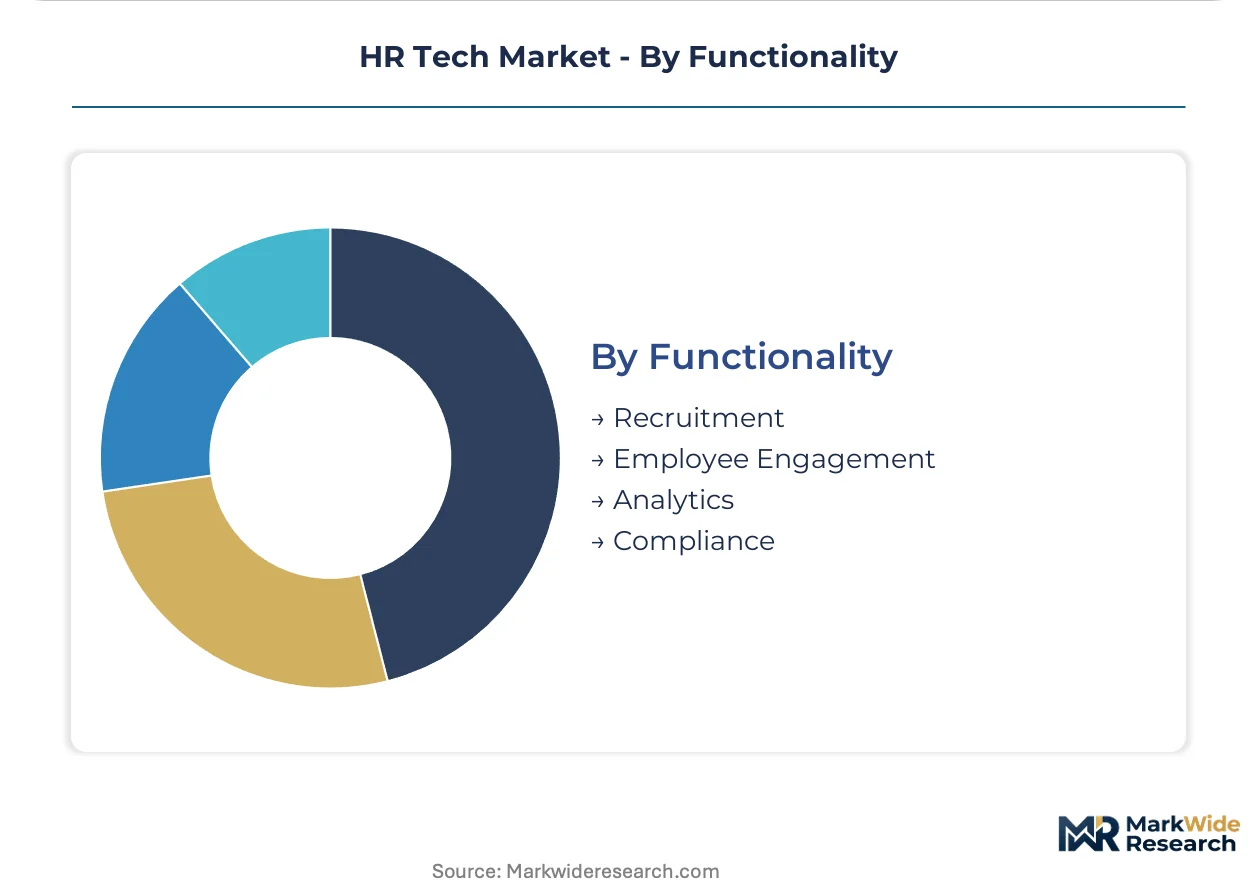
Functionality:
Margin concentration shifts toward analytics and engagement modules as reskilling imperatives and human capital disclosure requirements intensify.
- Analytics:Workforce metrics dashboards aggregating engagement, diversity, and productivity data for executive decision support. ISO 30414 human capital reporting standards in Europe and Asia-Pacific create procurement pull for standardized disclosure tooling. CFOs demand ROI visibility on talent investments previously treated as cost centers.
- Compliance:Algorithmic transparency modules and audit trail functionality address EU AI Act mandates for high-risk employment systems. OSHA digitization requirements in the United States drive safety training documentation automation. Regulatory fragmentation across jurisdictions resists platform standardization.
- Recruitment:Sourcing and screening automation reduces administrative burden for high-volume hiring.
- Employee Engagement:Pulse surveys and recognition platforms support retention strategies in competitive labor markets.
Recruitment functionality leads installed base today; Analytics is expanding most quickly as disclosure requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Workforce technology procurement concentrates in the United States, Germany, and India, where employer scale and regulatory complexity create sustained infrastructure investment cycles.
United States
Enterprise adoption of cloud-native platforms accelerates among mid-market employers consolidating previously fragmented vendor relationships. OSHA digitization mandates for incident reporting and safety training documentation drive demand for compliance automation modules. Technology clusters in Silicon Valley and Greater Boston pilot agentic AI systems for scheduling and leave approvals.
Germany
Mittelstand manufacturers scale applicant tracking infrastructure to manage workforce expansion under industrial transformation programs. EU AI Act algorithmic accountability requirements reshape vendor certification obligations for automated hiring tools deployed across European operations. Bavaria and Baden-Württemberg automotive suppliers integrate workforce analytics with production planning systems.
India
Electronics and pharmaceutical manufacturing incentives under the PLI scheme generate massive hiring waves requiring scalable onboarding infrastructure. BIS standards for data localization constrain cloud architecture choices for multinational employers operating in-country. Karnataka's Bengaluru tech corridor and Gujarat's industrial zones anchor concentrated demand for integrated talent platforms.
United Kingdom
Financial services firms in London prioritize embedded finance modules integrating earned wage access and retirement savings into payroll workflows. GDPR constraints on employee data processing elevate demand for audit trail functionality and consent management tooling. Fintech clusters in Manchester and Edinburgh experiment with AI-enabled performance feedback systems.
Japan
Aging workforce demographics intensify reskilling imperatives driving Learning Management System procurement in manufacturing and healthcare verticals. METI guidelines on human capital disclosure create pull for standardized workforce metrics dashboards. Osaka-based industrial conglomerates and Tokyo professional services firms anchor platform adoption.
HR Tech Market Competitive Environment
Capital-heavy platform developers compete with asset-light point-solution specialists across tiered market positions. Unified suite vendors anchor enterprise accounts through embedded compliance and cross-border payroll capabilities, while specialized tools capture niche workflows with superior user experience. Three archetypes dominate: vertically integrated workforce platforms, mid-market people analytics specialists, and streamlined small-business payroll processors. Consolidation pressures intensify as CFO-mandated vendor reduction programs displace point solutions, and embedded finance convergence creates new revenue pools beyond subscription economics.
Among the unified platform tier, Rippling and Deel exemplify global-first architectures designed for complex multi-jurisdictional operations. HiBob occupies a specialized position serving growth-stage employers with strong engagement and analytics capabilities. Gusto anchors the small-business segment through intuitive self-service interfaces that minimize administrative overhead for owner-operators.
| Leading Market Players |
|---|
| Ashby |
| Findem |
| Rippling |
| Paylocity |
| Workhuman |
| Deel |
| HiBob |
| Jobandtalent |
| Gusto |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure costs cascade through HR technology pricing tiers as vendors negotiate multi-tenant hosting agreements with hyperscalers in the United States, Germany, and India before embedding margins into per-employee-per-month subscription rates. The concentration of certified data center capacity in these jurisdictions shapes how platforms tier their compliance-ready offerings versus stripped-down small-business packages.
Pricing Analysis
The bundled-vs-unbundled service split defines competitive positioning as unified platforms like Rippling and HiBob capture premium pricing through payroll-benefits-IT convergence while point-solution vendors compete on module-specific subscriptions. Pricing stratifies across global enterprise, mid-market growth, and small-business economy tiers based on jurisdictional coverage breadth and embedded compliance depth. Cost compression in the small-business tier is intensifying because Gusto and challengers automate onboarding workflows that previously required implementation fees. Mid-market employers exhibit highest price sensitivity due to procurement consolidation mandates, while large corporations with multi-country operations accept premium rates for cross-border tax harmonization.
Supply Chain Analysis
ISO 27001 and SOC 2 certification gating restricts vendor access to enterprise procurement pipelines, concentrating qualified platform development in the United States, Germany, and Israel where specialized security audit ecosystems mature. The technology stack draws from hyperscaler compute in the United States, identity management components from European specialists, and AI/ML inference infrastructure from cloud regions in India and Singapore. Single-source vulnerability concentrates in payment processing APIs where Stripe and Adyen dominance creates downstream dependency. Distribution runs through direct enterprise sales teams, channel partnerships with benefits brokers, and self-service digital acquisition for sub-200 employee accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in HR technology rests on automation compressing implementation labor costs while compliance modules command pricing premiums. Vendors capturing embedded finance revenue pools beyond SaaS subscriptions widen unit economics fastest.
For Market Incumbents: Extend platform stickiness through deeper integration into IT asset management and device provisioning workflows that increase switching costs beyond payroll data lock-in. Acquire specialized bias-auditing firms to accelerate EU AI Act certification timelines before procurement gates close. Threat substitution from agentic AI-native challengers demands preemptive feature parity investment. For New Entrants and Emerging Players: Enter via vertical-specific compliance automation for OSHA digitization mandates in US manufacturing and construction where incumbent platforms lack tailored safety-training modules. White-space concentrates in mid-market employers with 500-2,000 employees managing multi-state operations without dedicated HR technology procurement expertise. Go-to-market leverage rests on embedded partnerships with industry-specific insurance carriers bundling platform access with workers compensation policies. For Investors and Strategic Acquirers: Consolidation pressure builds where vendor count exceeds procurement team capacity at mid-market employers, creating rollup opportunity for platforms with unified data architectures. Long-term viability favors vendors with embedded finance revenue diversification beyond pure SaaS multiples. Acquisition target archetype: regional payroll specialists with deep tax filing history in fragmented jurisdictions like Brazil or Southeast Asia. Signal to watch is CFO-mandated vendor reduction program announcements accelerating from technology and healthcare into industrial verticals.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Finance Integration | Earned wage access and micro-insurance modules in payroll workflows create recurring revenue beyond SaaS subscriptions in the United States. |
| AI Compliance Certification | EU AI Act conformity assessment investment opens enterprise procurement pipelines across German and French manufacturing employers. |
| Vertical Payroll Acquisition | Specialized construction and healthcare payroll platforms provide tax filing history that locks mid-market accounts against churn. |
| Agentic AI Deployment | Autonomous scheduling and leave approval tools reduce manager administrative burden at retail chains and professional services firms. |
| Cross-Border Infrastructure Expansion | Localized data residency in India and Vietnam satisfies BIS and cybersecurity law mandates for multinational manufacturing clients. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CHROs, CFOs, HR technology procurement officers, and benefits administrators at employers across the United States, Germany, and India with secondary validation against SEC filings, EU regulatory transparency databases, and PLI scheme workforce expansion disclosures. Bottom-up sizing of vendor-reported subscription metrics and top-down triangulation against employer technology spend surveys anchored volume estimates.
Comparable historical periods spanning cloud migration cycles and regulatory implementation phases grounded projection assumptions across the modeling period. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical industry, jurisdictional complexity, and functionality depth. CAGRs derived from fitted growth curves incorporating vendor sales pipeline data and employer replacement cycle timing. Forecast inputs included EU AI Act enforcement trajectory and India's electronics manufacturing workforce scaling under PLI incentives.
Inputs from regulatory filing databases and vendor financial disclosures were available through the study window; gaps in private company subscription metrics and mid-market employer technology spend allocation introduce uncertainty bands around growth rate estimates. Forecasts reflect documented assumptions about compliance timeline adherence and cloud infrastructure cost trajectories. A model refresh is warranted upon material change in EU AI Act enforcement intensity or hyperscaler pricing recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
SRM Software Market
Software & Services
Streaming Server Software Market
Software & Services
Mobile Speech Recognition Software Market
Software & Services
Federal Government Software Market
Software & Services
Poultry Farm Management Software Market
Software & Services
Skills Management Software Market
Software & Services
Quality and Lifecycle Management Software Market
Software & Services
Middle East and Africa Automotive Software Market
Software & Services
Decision Support System (DSS) Software Market
Software & Services
Business Rules Management System Market
Software & Services
Email Applications Market
Software & Services
Global Core Banking Software Market
Software & Services
Construction Software As A Service Market
Software & Services
Africa Sports Management Software Market
Software & Services
Global Log Management Software Market
Software & Services
Gym Motion Tracking Software Market