
 IT Services Market | 2026-2036
IT Services Market Size, Share, and Industry Trends Forecast 2026-2036
IT Services Market Intelligence
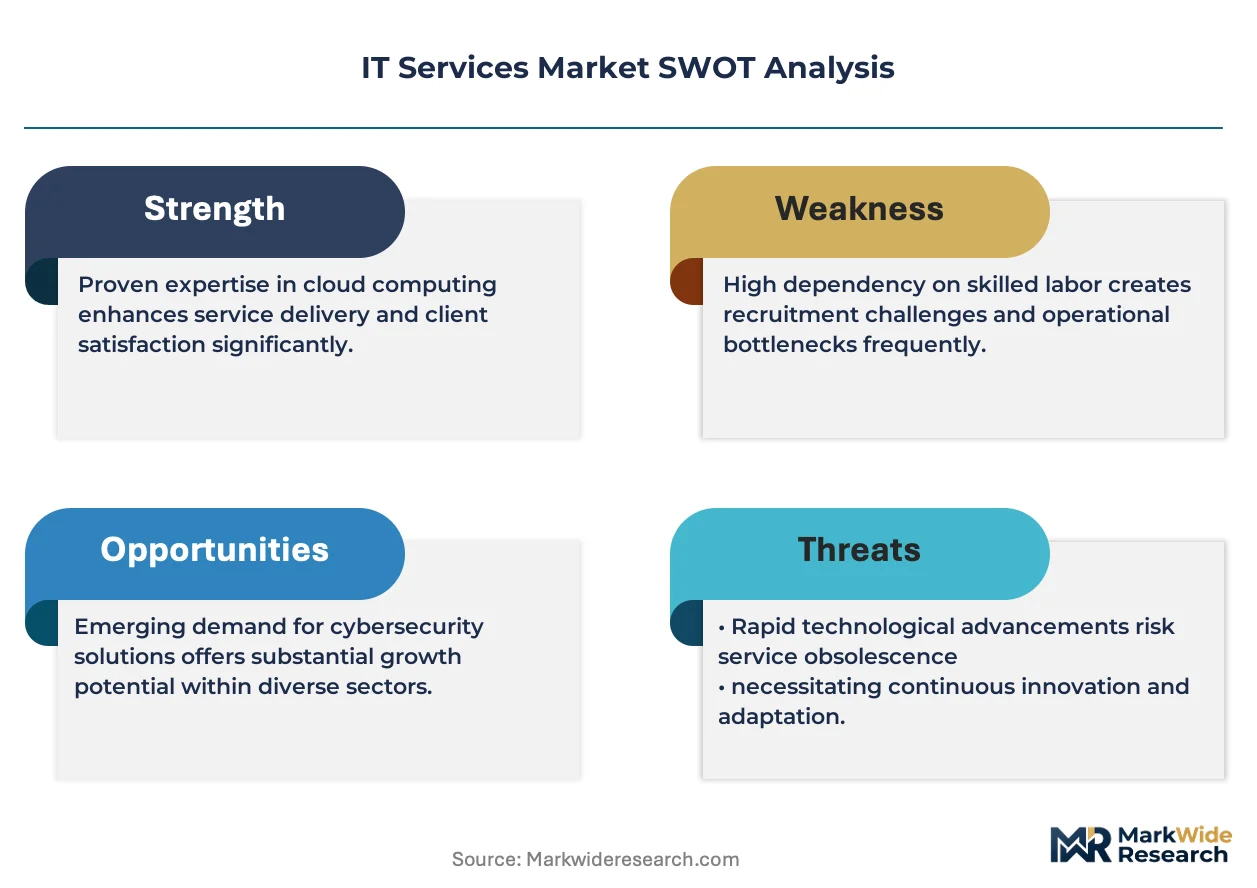
Cloud architecture talent is rotating toward generative AI and platform engineering specializations, tightening supply for legacy infrastructure roles. Accenture leverages its consulting-to-operations continuum to capture multi-year transformation contracts. Tata Consultancy Services anchors its competitive position through scale advantages in delivery center networks across Indian metropolitan corridors. IBM differentiates via hybrid cloud integration expertise and proprietary automation platforms.
IT Services encompass the design, deployment, management, and optimization of information technology infrastructure, applications, and business processes delivered through on-site, remote, or cloud-based modalities, typically governed by service-level agreements specifying uptime thresholds, response times, and security protocols. The primary commercial purpose is enabling organizations to access specialized technical capabilities without maintaining full in-house capacity. Cloud Services represents the fastest-expanding revenue pool as enterprises migrate workload estates away from owned data centers. Managed IT maintains mature, recurring revenue characteristics with strong renewal rates but compressed margins. Cybersecurity commands premium pricing due to capability scarcity and escalating threat complexity.
The EU AI Act imposes conformity assessment requirements on high-risk AI systems deployed by service providers, directly affecting European delivery contracts and vendor qualification processes. In the United States, SEC cybersecurity disclosure rules and NIST frameworks shape enterprise procurement standards for publicly traded clients. India's Digital Personal Data Protection Act introduces cross-border data transfer constraints that restructure offshore delivery architectures. Stakeholders must monitor regulatory divergence across jurisdictions when architecting multi-country service delivery models and compliance investments.
Market Dynamics
Generative AI is decomposing traditional service delivery models across the IT services value chain, forcing vendors to restructure talent deployment and pricing architectures while clients demand outcome-contingent engagements over time-and-material contracts.
Growth Catalysts
- EU AI Act:The conformity assessment mandate for high-risk algorithmic systems creates specialized compliance service demand across European banking and healthcare sectors, requiring vendor certification investments that deepen client switching costs.
- Cloud workload migration:Financial services firms in the United States are accelerating data center exits, generating multi-year transformation contracts for hybrid infrastructure deployment and legacy application refactoring.
- Bengaluru-Hyderabad-Mumbai corridor:Concentrated delivery center networks in these Indian metropolitan clusters enable 24-hour development cycles and specialized talent pools that attract global enterprise outsourcing decisions.
Market Restraints
- Specialized talent scarcity:Platform engineering and MLOps expertise commands 40-60% wage premiums over legacy infrastructure roles, compressing margins on fixed-price contracts and forcing vendor investment in automated delivery tools.
- Cross-border data friction:India's Digital Personal Data Protection Act imposes localization and transfer constraints that rearchitect offshore delivery models, adding compliance overhead to multi-country service architectures.
- Generative AI substitution:Code generation and automated documentation tools threaten commoditization of entry-level programming and testing services, pressuring the pyramid model that sustains margin structures.
Strategic Opportunities
- Sovereign cloud expansion:Germany and France are mandating data residency for public sector and critical infrastructure workloads, creating captive delivery requirements that favor European-located service centers and specialized compliance expertise.
- Cybersecurity convergence:The integration of zero-trust architecture with managed detection and response services opens integrated revenue streams as enterprise CISOs consolidate vendor relationships under single accountability frameworks.
- Edge computing deployment:Manufacturing and logistics verticals in Japan and South Korea are distributing compute to factory floors and warehouse networks, requiring localized integration services that bypass traditional centralized delivery models.
Industry Challenges
- Generative AI skill acquisition:Prompt engineering and model fine-tuning capabilities remain concentrated among a narrow talent pool, forcing vendors into aggressive retention programs and partnership structures with foundation model providers.
- Legacy system entanglement:Mainframe and COBOL-dependent financial infrastructure in North American and European institutions resists cloud-native refactoring, extending project timelines and complicating value realization metrics.
- Multi-jurisdiction compliance orchestration:Simultaneous adherence to SEC cybersecurity disclosure rules, EU AI Act conformity assessments, and India's data protection requirements demands specialized legal-technical hybrid roles that inflate delivery costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IT Services Market |
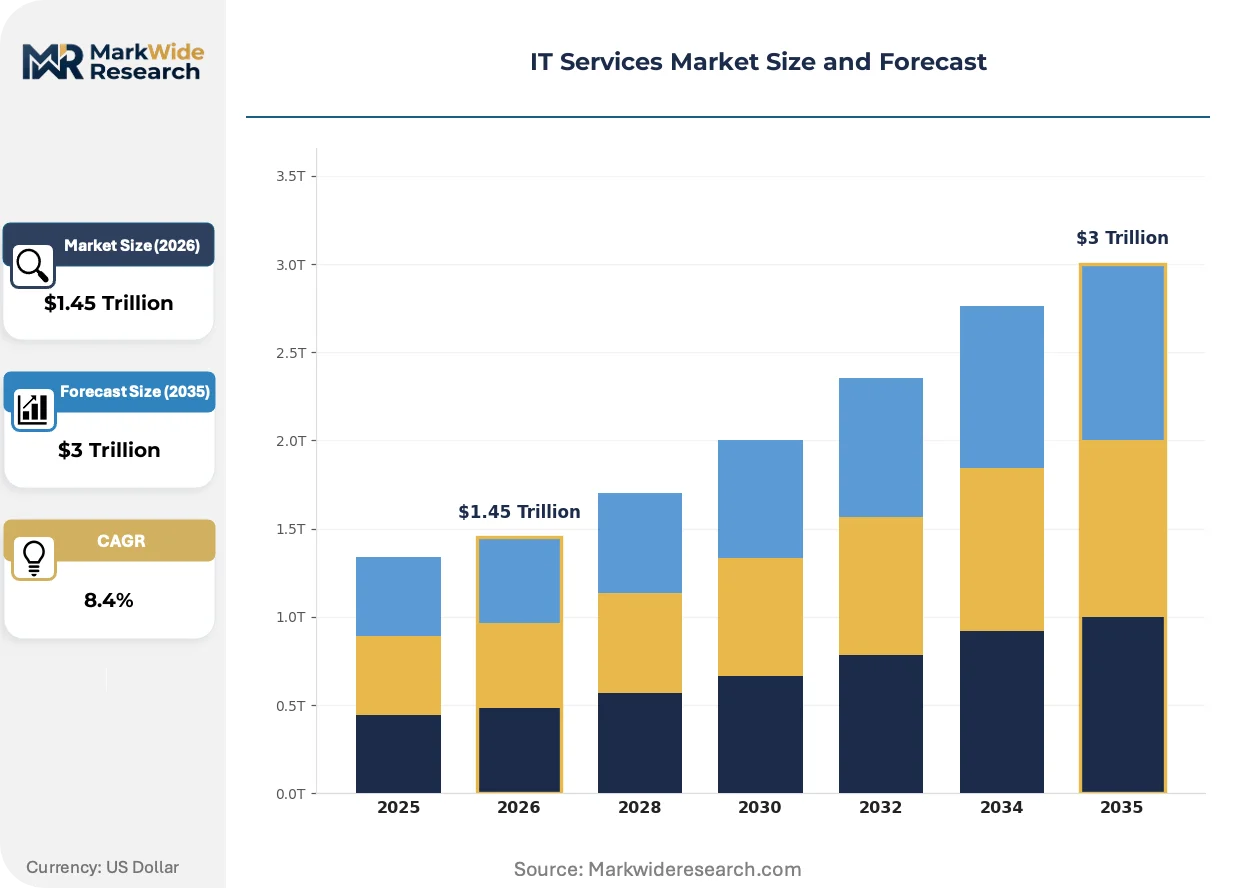
| Market Size in 2026 | $1.45 Trillion |
| Market Size in 2035 | $3 Trillion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Services, Managed IT, Consulting, Cybersecurity Deployment: On-Premises, Cloud-Based, Hybrid, Remote End User: SMEs, Enterprises, Government, Non-Profit Industry Vertical: Healthcare, Finance, Education, Retail |
| Companies Covered | Accenture, Tata Consultancy Services, IBM, Cognizant, Infosys, Capgemini, Wipro, HCL Technologies, DXC Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IT Services Market Strategic Shifts & Innovations
Service delivery architectures are fragmenting from monolithic outsourcing contracts toward composable, API-integrated capability stacks that clients assemble across multiple specialized providers rather than consolidating with single vendors.
Platform engineering is decomposing traditional DevOps and infrastructure management functions into self-service internal developer platforms. Enterprise technology organizations in banking and telecommunications are adopting these standardized tooling layers at accelerating pace. This shift compresses demand for conventional system administration while elevating vendor roles toward platform product management and developer experience optimization.
The EU AI Act's risk-based classification system imposes documentation and human oversight requirements on algorithmic decision systems deployed by service providers. European financial services and healthcare clients now mandate vendor conformity assessments as contractual preconditions. Delivery organizations are responding by embedding legal-technical compliance roles within account teams and pre-certifying solution architectures.
Enterprise buying committees are unbundling transformation programs into discrete capability purchases rather than awarding consolidated multi-year contracts. Technology procurement in United States manufacturing and German automotive sectors now separates strategy consulting, cloud migration, and managed operations into competitive sourcing events. This fragmentation favors specialized vendors with demonstrated expertise in specific technology domains over generalist service portfolios.
IT Services Market Segmentation
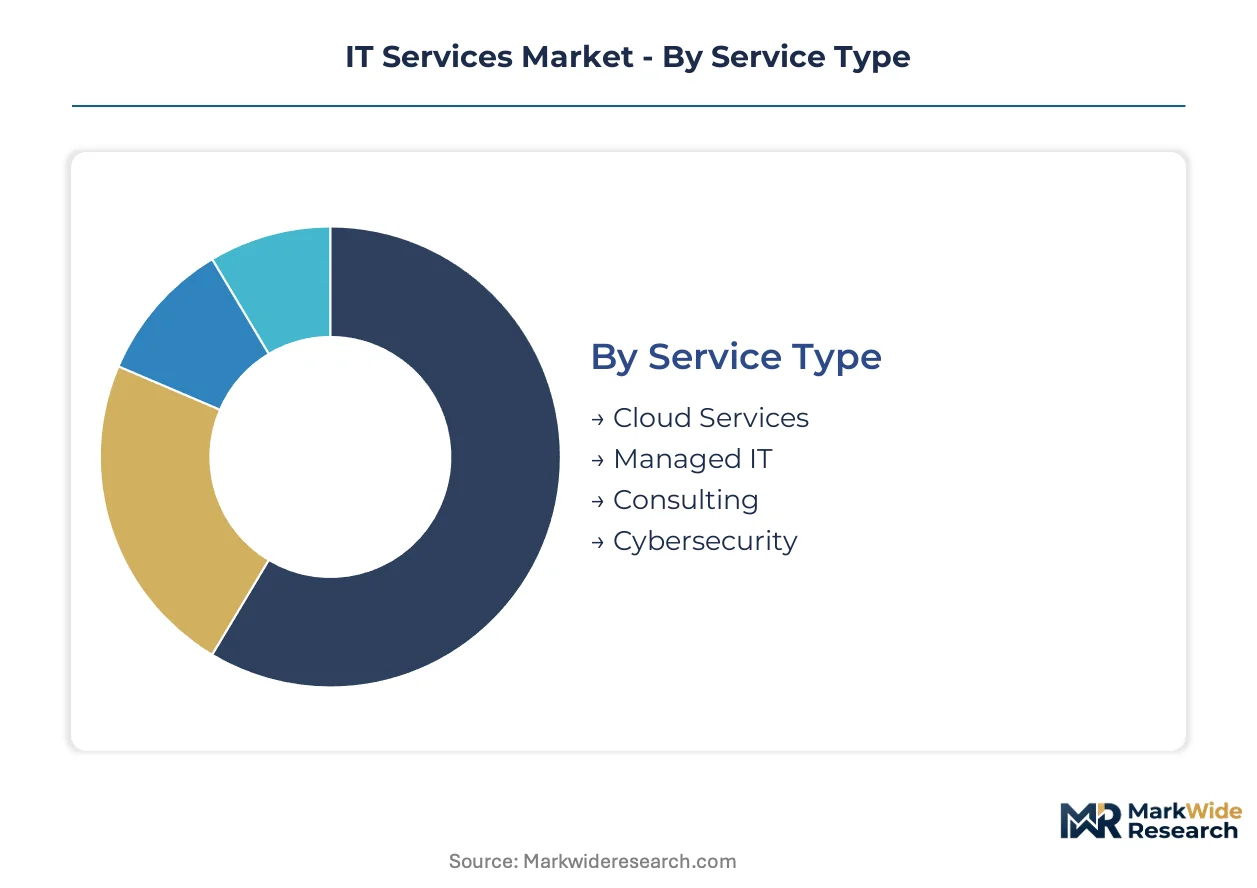
IT Services Market segmentation reveals how regulatory frameworks, deployment architectures, and client scale reshape vendor capabilities and pricing structures. Distinct compliance obligations across the EU AI Act, SEC cybersecurity rules, and India's data protection regime fragment service delivery models by geography and client type.
Service Type:
The EU AI Act's conformity assessments create divergent compliance burdens across service categories, with high-risk algorithmic systems facing mandatory documentation and human oversight requirements.
- Cloud Services:Encompasses infrastructure-as-a-service, platform-as-a-service, and software-as-a-service delivery models with multi-tenant architectures. Demand concentrates among United States financial services firms executing data center exits, driven by SEC disclosure rules mandating resilient infrastructure and rapid incident reporting capabilities.
- Cybersecurity:Spans managed detection and response, zero-trust architecture implementation, and compliance monitoring services. European banking and healthcare procurement teams now require vendor conformity assessments as contractual preconditions under EU AI Act high-risk system classifications.
- Managed IT:Recurring infrastructure monitoring, helpdesk operations, and legacy system maintenance governed by uptime SLAs.
- Consulting:Strategy advisory, transformation roadmapping, and vendor selection support for technology procurement decisions.
Established volume favors Managed IT; emerging adoption favors Cloud Services.
Deployment:
Cost tier differentiation separates capital-intensive on-premises estates from consumption-priced cloud models, with hybrid architectures commanding premium integration fees for workload orchestration complexity.
- Cloud-Based:Fully outsourced infrastructure with pay-as-you-scale economics and shared security responsibility models. United States manufacturing firms in the Midwest and Southeast are migrating ERP and supply chain systems to cloud-native architectures, accelerating demand for refactoring services.
- Hybrid:Distributed workloads across owned data centers and public cloud environments with unified management planes. German automotive manufacturers mandate data residency for proprietary design data, creating sovereign cloud requirements that restructure vendor delivery footprints.
- On-Premises:Client-owned infrastructure with dedicated hardware and localized security controls.
- Remote:Workforce-centric delivery of desktop virtualization, collaboration platforms, and endpoint security.
Customer concentration in finance and healthcare tilts procurement toward Hybrid; SME cost pressure accelerates Cloud-Based.
End User:
Application complexity scales with organizational size, with enterprises demanding multi-jurisdiction compliance orchestration while SMEs prioritize standardized, rapidly deployable service tiers.
- Enterprises:Multi-national organizations with complex governance requirements and specialized security mandates. India's Digital Personal Data Protection Act imposes cross-border transfer constraints that rearchitect offshore delivery models for enterprise contracts spanning Bengaluru, Hyderabad, and Mumbai delivery centers.
- Government:Public sector procurement with sovereign data requirements and certified vendor qualification processes. France and Germany mandate data residency for critical infrastructure workloads, favoring European-located service centers with specialized compliance expertise.
- SMEs:Mid-market organizations with constrained IT budgets and standardized service requirements.
- Non-Profit:Mission-driven organizations with donor accountability and grant-funded technology investments.
Contract value concentration favors Enterprises; volume expansion favors SMEs.
Industry Vertical:
Margin structure varies by sector-specific compliance intensity, with finance and healthcare commanding premium pricing for regulatory expertise while retail competes on operational efficiency metrics.
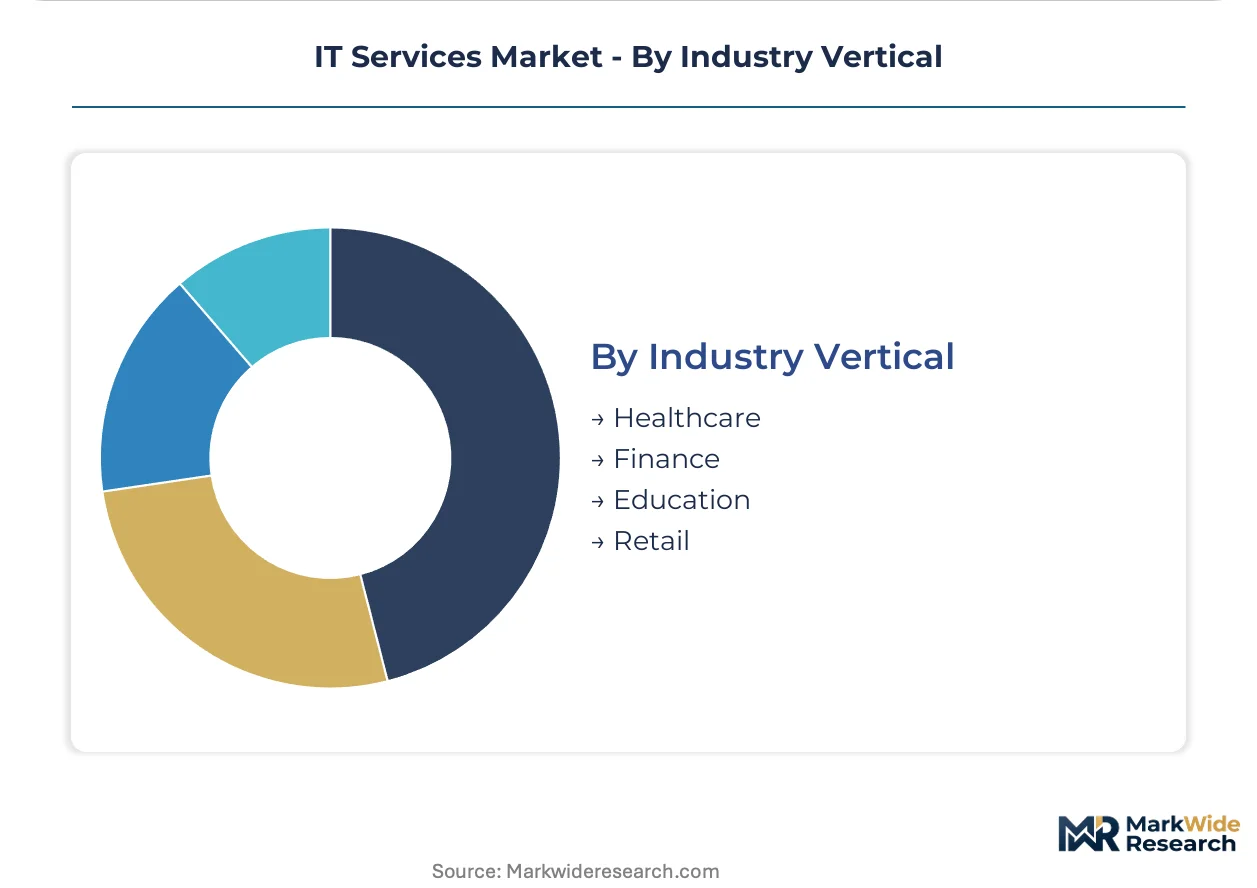
- Finance:Banking, insurance, and capital markets with algorithmic trading and customer scoring systems. The EU AI Act's risk-based classification imposes documentation requirements on credit decisioning algorithms, embedding legal-technical compliance roles within vendor account teams.
- Healthcare:Provider networks, payers, and life sciences with patient data governance and clinical system interoperability. United States HIPAA requirements and FDA software-as-medical-device regulations shape procurement standards for publicly traded health systems.
- Retail:Omnichannel commerce, supply chain optimization, and customer analytics platforms.
- Education:K-12 districts and higher education institutions with learning management systems and research computing.
Regulatory premium capture favors Finance; platform standardization favors Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEC cybersecurity disclosure rules and NIST frameworks anchor United States procurement standards, while the EU AI Act and India's Digital Personal Data Protection Act reshape delivery architectures across their respective jurisdictions.
United States
Financial services firms in New York and Chicago are accelerating data center exits, generating multi-year transformation contracts for hybrid infrastructure deployment. SEC cybersecurity disclosure rules mandate resilient infrastructure and rapid incident reporting capabilities for publicly traded clients. The Dallas-Fort Worth corridor hosts expanding delivery centers serving domestic enterprise contracts with specialized cloud migration expertise.
Germany
Automotive manufacturers in Stuttgart and Munich mandate data residency for proprietary design data, creating sovereign cloud requirements that restructure vendor delivery footprints. The EU AI Act imposes conformity assessment mandates on high-risk algorithmic systems deployed by service providers. Frankfurt's financial district drives demand for compliance-integrated managed services under strict Bundesbank oversight protocols.
India
The Digital Personal Data Protection Act introduces cross-border data transfer constraints that rearchitect offshore delivery models for enterprise contracts. Bengaluru, Hyderabad, and Mumbai form the primary delivery cluster enabling 24-hour development cycles and specialized talent pools. These metropolitan corridors attract global enterprise outsourcing decisions through concentrated delivery center networks and platform engineering expertise.
France
Public sector procurement mandates data residency for critical infrastructure workloads, favoring European-located service centers with specialized compliance expertise. The EU AI Act's risk-based classification system imposes documentation requirements on algorithmic decision systems. Paris hosts expanding delivery operations serving continental banking and healthcare clients with embedded legal-technical compliance roles.
United Kingdom
London's financial services sector demands multi-jurisdiction compliance orchestration spanning SEC, EU AI Act, and domestic regulatory frameworks. The Information Commissioner's Office shapes data governance standards for cross-border service delivery. The Thames Valley corridor concentrates cybersecurity and cloud consulting capabilities serving both domestic and European enterprise clients post-Brexit.
IT Services Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the IT services value chain. Global systems integrators command premium pricing for transformation consulting and complex multi-cloud orchestration. India-headquartered scale players anchor delivery through metropolitan corridor networks with concentrated talent pools. Boutique cybersecurity specialists capture margin premiums through capability scarcity in zero-trust architecture and managed detection services. Dominant competitive moves include strategic partnerships with hyperscale cloud providers and aggressive acquisition of generative AI engineering talent.
Within the global systems integrator tier, Accenture and IBM occupy positions representing consulting-to-operations continuum capabilities. Among India-based scale specialists, Tata Consultancy Services anchors competitive positioning through delivery center network density across Bengaluru, Hyderabad, and Mumbai. These named entities exemplify archetype differentiation rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Accenture |
| Tata Consultancy Services |
| IBM |
| Cognizant |
| Infosys |
| Capgemini |
| Wipro |
| HCL Technologies |
| DXC Technology |
| Others |
Cost & Logistics Intelligence
Delivery center utilization rates above 85% in Bengaluru, Hyderabad, and Mumbai create scale economies that compress unit costs while elevating price floors for specialized platform engineering talent. This concentration of offshore capacity simultaneously anchors global pricing benchmarks and constrains margin flexibility for vendors competing on legacy infrastructure contracts.
Pricing Analysis
Hourly rate spreads between Indian metropolitan delivery centers and European onshore operations span 3-4x multiples for equivalent cloud architecture roles. Three-tier pricing structure across premium, standard, and economy levels segments engagements by compliance intensity and customization depth. Cost compression in entry-level programming services intensifies as generative AI tools automate code generation workflows. SME buyers exhibit acute price sensitivity, while financial services enterprises prioritize regulatory certification over rate negotiation.
Supply Chain Analysis
Broadband submarine cable chokepoints through the Strait of Malacca and Red Sea corridors expose offshore delivery models to latency degradation and redundancy costs. Talent supply concentrates in India, Poland, and the Philippines as primary delivery geographies. Raw inputs draw from university pipeline partnerships, foundation model API licenses, and hyperscaler cloud credits. Single-source vulnerability in foundation model provider relationships threatens service continuity. Distribution runs through direct enterprise sales, systems integrator partnerships, and cloud marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IT Services Market recovery tracks enterprise cloud migration cycles, with financial services data center exits providing the current cyclical impetus. Vendors must align capability investments with this capital expenditure wave to capture transformation contract flows.
For Market Incumbents: Fortify delivery center density in the Bengaluru-Hyderabad-Mumbai corridor through targeted campus expansions and university pipeline lock-ups. Deepen vertical integration into proprietary automation platforms to offset generative AI substitution threats in entry-level service tiers. Prioritize EU AI Act pre-certification investments to embed switching costs in European banking relationships. For New Entrants and Emerging Players: Lead with sovereign cloud compliance expertise targeting German automotive and French public sector procurement mandates. White-space availability concentrates in edge computing integration for Japanese manufacturing and South Korean logistics verticals. Go-to-market execution should anchor on hyperscaler partnership tiers rather than direct enterprise sales infrastructure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors boutique cybersecurity specialists with zero-trust architecture capabilities and demonstrated CISO relationship depth. Long-term viability hinges on defensible talent retention mechanisms and recurring revenue concentration. Monitor foundation model provider pricing volatility as the critical inflection signal for automated service tier economics.| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Talent Acquisition | Foundation model fine-tuning expertise commands retention premiums that reshape vendor cost structures. |
| EU AI Act Pre-Certification | Conformity assessment investments embed switching costs in European financial services procurement. |
| Hyperscaler Partnership Tiers | Cloud marketplace listings reduce customer acquisition friction for specialized service providers. |
| Sovereign Cloud Delivery Centers | German and French data residency mandates favor European-located compliance expertise. |
| Platform Engineering Capability Buildout | Internal developer platforms displace conventional DevOps demand while elevating vendor strategic positioning. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, EU regulatory submissions, and Indian trade data. Primary interviews engaged cloud architects, enterprise IT procurement officers, platform engineering leads, and compliance specialists across financial services, automotive, and healthcare verticals. Secondary validation drew from service provider financial disclosures, cloud marketplace transaction data, and regulatory filing analysis. Bottom-up contract value aggregation triangulates against top-down market sizing from vendor revenue disclosures.
Segmentation dimensions modeled span service type, deployment architecture, organization scale, and industry vertical across the projection horizon. CAGRs derive from trend extrapolation of contract value growth, talent supply elasticity, and technology substitution rates. Forecast inputs incorporate cloud workload migration velocity, foundation model adoption curves, and cross-border data transfer constraint evolution.
Forecasts assume regulatory continuity in SEC cybersecurity disclosure regimes, EU AI Act implementation timelines, and India's Digital Personal Data Protection Act enforcement; material policy shifts would require re-modeling of offshore delivery economics and compliance cost structures. Technology disruption from code generation automation and sovereign cloud mandates present scenario-dependent forecast variance. Practitioners should keep alternative scenarios live as foundation model provider pricing and data localization enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Mobile Middleware Market
Software & Services
Global Brain Training Software Market
Software & Services
Smartphone OS Market
Software & Services
Global Voting Software Market
Software & Services
Web Framework Software Market
Software & Services
Managed Information Services Market
Software & Services
MRP Software Market
Software & Services
Supplier Relationship Management Software Market
Software & Services
Technology CAD Software Market
Software & Services
Global Reporting Software Market
Software & Services
Software Containers Market
Software & Services
Global Jewelry Store Management Software Market
Software & Services
Emotion Recognition and Sentiment Analysis Software Market
Software & Services
Global Florist Software Market
Software & Services
Case Management Software (CMS) Market
Software & Services
Global Architect Software Market