
 Composite Metal Finishing Market | 2026-2036
Composite Metal Finishing Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Metal Finishing Market Intelligence
The transition toward co-deposition of nanoparticles within metallic matrices is narrowing the performance gap between traditional plating and advanced composite coatings. Element Solutions Inc. leverages its extensive chemical portfolio across multiple surface treatment technologies. Atotech specializes in integrated production systems and advanced electroplating chemistries for high-tech applications. UYEMURA differentiates with its focus on high-reliability finishes for the consumer electronics and semiconductor industries.
Composite metal finishing is a surface engineering process that co-deposits fine, non-metallic particles into a metallic matrix during plating. This technique enhances specific surface properties such as wear resistance, hardness, and lubricity for industrial components. Electroplating remains the primary process type, valued for its scalability and control over deposit characteristics. The aerospace components and automotive parts applications command significant attention due to stringent performance requirements and higher margin potential.
Regulatory frameworks, including the European Union's REACH and standards set by the US EPA, are fundamentally shaping material selection. These rules strictly limit or ban hazardous substances like hexavalent chromium and cadmium, creating significant market opportunities for compliant composite alternatives. The key strategic decision for applicators involves balancing the capital investment in new processes against the long-term benefits of superior performance and guaranteed market access.
Market Dynamics
The central dynamic in the composite metal finishing market is the regulatory-driven substitution of hazardous materials, such as hexavalent chromium, which is simultaneously creating demand for higher-performance, multifunctional coatings required by advanced manufacturing sectors like aerospace and electronics.
Growth Catalysts
- Advanced Material Science:The co-deposition of nanoparticles like PTFE, silicon carbide, or diamond into metal matrices is creating coatings with superior wear resistance and lubricity, meeting the stringent demands of the aerospace components industry.
- Regulatory Mandates:Frameworks including the EU's REACH and rules from the US EPA are banning or restricting legacy materials, creating a direct and non-negotiable catalyst for the adoption of compliant composite alternatives.
- Electronics Miniaturization:China's electronics manufacturing ecosystem requires advanced composite finishes to provide corrosion protection, EMI shielding, and wear resistance for increasingly small and complex components in consumer and industrial devices.
Market Restraints
- High Capital Investment:Upgrading or replacing existing electroplating lines to handle nanoparticle slurries and meet new environmental controls requires significant upfront capital expenditure, acting as a barrier for smaller applicators.
- Process Control Complexity:Achieving uniform dispersion of reinforcement particles within the metallic matrix is technically challenging, and failure to do so results in inconsistent coating performance and high scrap rates.
- Specialized Input Materials:The market depends on a limited number of suppliers for high-purity, nano-grade particles, creating potential supply chain bottlenecks and price volatility for critical raw materials.
Strategic Opportunities
- Electric Vehicle Components:Developing specialized composite coatings for EV battery casings, connectors, and busbars offers a new market for enhancing corrosion resistance, thermal management, and electrical conductivity.
- Smart Coatings Development:Integrating sensor particles into the composite matrix enables the creation of surfaces that can self-monitor for stress, wear, or corrosion, opening applications in structural health monitoring.
- Bio-Compatible Finishes:There is an opportunity to develop composite coatings using biocompatible metals and particles for medical devices and implants, addressing a high-value niche with stringent performance criteria.
Industry Challenges
- Talent Scarcity:A persistent shortage of process engineers and material scientists with dual expertise in electrochemistry and nanoparticle technology constrains R&D and operational excellence.
- Lack of Standardization:The absence of universally accepted testing protocols for composite coatings makes it difficult for end-users to reliably compare performance claims from different suppliers, slowing adoption.
- Compliance Documentation Burden:Qualifying new, compliant coatings for critical applications, particularly in aerospace and automotive, involves extensive and time-consuming testing and documentation to meet OEM and regulatory standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Metal Finishing Market |
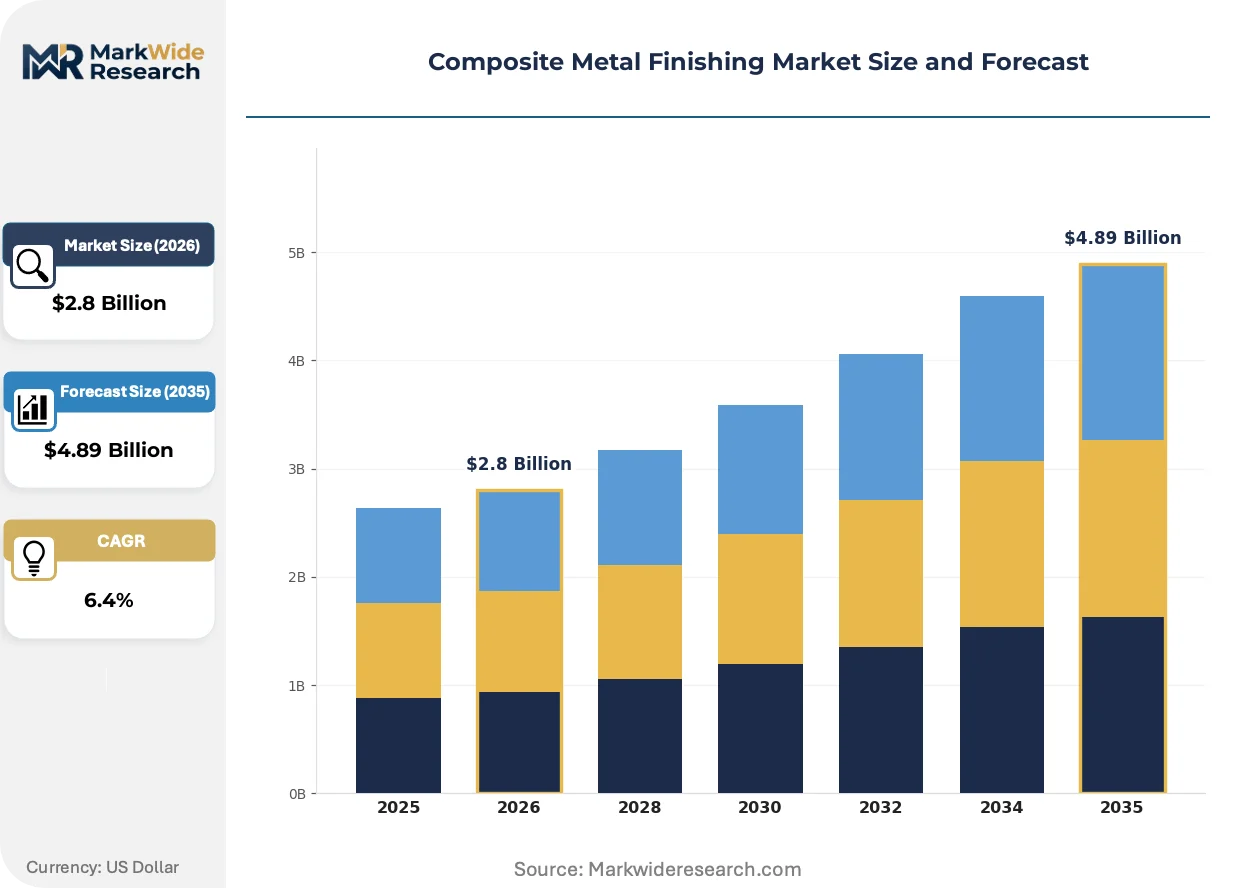
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Process Type: Electroplating, Anodizing, Painting, Powder Coating Application: Aerospace Components, Automotive Parts, Industrial Equipment, Consumer Electronics Material Type: Aluminum Alloys, Stainless Steel, Copper Alloys, Titanium Alloys End User: Manufacturers, OEMs, Repair Shops, Contractors |
| Companies Covered | Atotech, Asterion LLC, Metal Finishing Technologies LLC, Coventya International, Quaker Houghton, Element Solutions Inc., UYEMURA, Endura Coatings, Chemetall GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Metal Finishing Market Strategic Shifts & Innovations
The market is evolving from providing simple protective layers to engineering multifunctional surfaces. This transition is propelled by material science advancements in nanoparticle dispersion and a definitive regulatory push away from hazardous legacy chemistries, forcing innovation in process control and coating formulation.
In-situ process monitoring technology employs sensors to track plating bath chemistry, temperature, and current density in real time. Aerospace and semiconductor manufacturers are early adopters, driven by a need for absolute repeatability and zero-defect tolerance. This integration of data feedback is digitizing the historically analog electroplating process, enabling predictive quality control and reducing reliance on post-process inspection.
Restrictions under the European Union's REACH regulation continue to tighten on substances of very high concern, most notably hexavalent chromium. This directive forces a phase-out in many industrial applications, creating a hard deadline for applicators to adopt compliant alternatives. The automotive sector in Germany is most impacted, accelerating the qualification of trivalent chromium and advanced nickel-composite coatings to ensure production continuity.
End-users are shifting from specifying simple metrics like coating thickness to defining functional performance outcomes, such as a target coefficient of friction or a maximum wear rate over a set number of cycles. This change disrupts the traditional commodity-based sales model, transferring responsibility for complex formulation and process optimization to the finishing applicator. This trend is most prominent within the aerospace supply chain, where performance guarantees are critical for component safety and reliability.
Composite Metal Finishing Market Segmentation
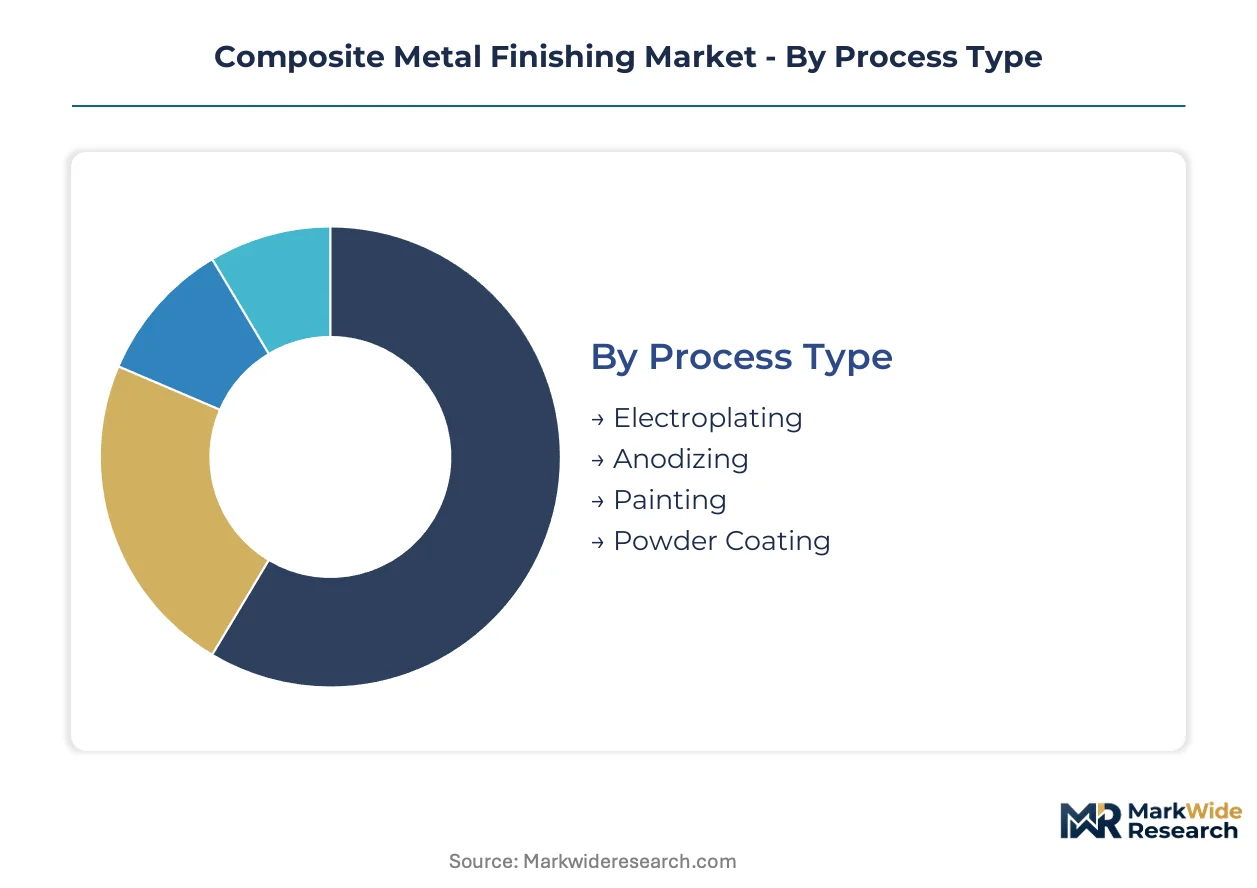
Market segmentation provides a granular view of the composite metal finishing industry, revealing specific demand drivers and technological preferences across various dimensions. Understanding these segments allows stakeholders to identify high-growth niches and optimize product development strategies for distinct end-user requirements.
Process Type:
The market's operational methodologies are primarily categorized by the process type employed for co-depositing particles into metallic matrices, defining both capability and cost structures.
- Electroplating:This electrochemical process involves immersing a substrate in an electrolyte bath containing dissolved metal ions and suspended nanoparticles, using an electric current to deposit a composite layer. Demand concentrates in Germany's automotive manufacturing sector, driven by the need for enhanced wear resistance on engine components.
- Anodizing:An electrolytic passivation process converts the surface of a metal part into a durable, corrosion-resistant, anodic oxide finish, often incorporating particles for added functionality. Aerospace components in the United States increasingly utilize anodizing for lightweight aluminum alloys, requiring superior hardness and fatigue resistance.
- Painting:This process applies a liquid coating containing metallic particles and binders, which then cures to form a protective and decorative layer.
- Powder Coating:Fine powder particles, including metallic composites, are electrostatically applied to a surface and then heated to form a smooth, hard finish.
Electroplating commands the established base. The steepest expansion runs through Anodizing.
Application:
End-use demand structures the market by application, highlighting critical performance requirements and regulatory compliance pressures for finished components.
- Aerospace Components:This sector demands finishes with exceptional wear resistance, corrosion protection, and fatigue strength for critical parts like landing gear and turbine blades. Stringent FAA regulations in the US and EASA standards in Europe drive material innovation.
- Automotive Parts:Composite finishes for automotive components improve durability, reduce friction, and enhance corrosion resistance for engine parts, brake systems, and chassis elements. China's electric vehicle manufacturing relies on advanced coatings for battery enclosures and connectors.
- Industrial Equipment:Coatings for industrial machinery extend operational life and reduce maintenance costs by providing superior resistance to abrasion and chemical exposure.
- Consumer Electronics:Miniaturization in devices like smartphones and laptops requires thin, highly conductive, and corrosion-resistant composite finishes, particularly in China's vast electronics production.
Aerospace Components holds the largest share. Consumer Electronics gains share fastest.
Material Type:
The underlying substrate material significantly influences finishing requirements, dictating compatibility with various plating chemistries and the functional properties achievable.
- Aluminum Alloys:These lightweight materials benefit from composite finishes that enhance surface hardness, wear resistance, and corrosion protection without significantly increasing weight. The aerospace industry's demand for lighter airframes drives this segment.
- Stainless Steel:Composite coatings on stainless steel improve its inherent corrosion resistance and can add properties like lubricity or extreme hardness for specialized industrial applications. Medical device manufacturers in Germany prioritize these enhanced properties for surgical instruments.
- Copper Alloys:Finishes on copper alloys often focus on improving electrical conductivity, corrosion resistance, and wear for connectors and heat sinks.
- Titanium Alloys:High-performance composite coatings for titanium enhance its biocompatibility and wear resistance, particularly for medical implants and demanding aerospace applications.
Aluminum Alloys represents the largest volume. Titanium Alloys shows the strongest growth trajectory.
End User:
Customer profiles delineate the market by end-user type, reflecting distinct procurement patterns, scale of operations, and technical expertise in applying composite finishes.
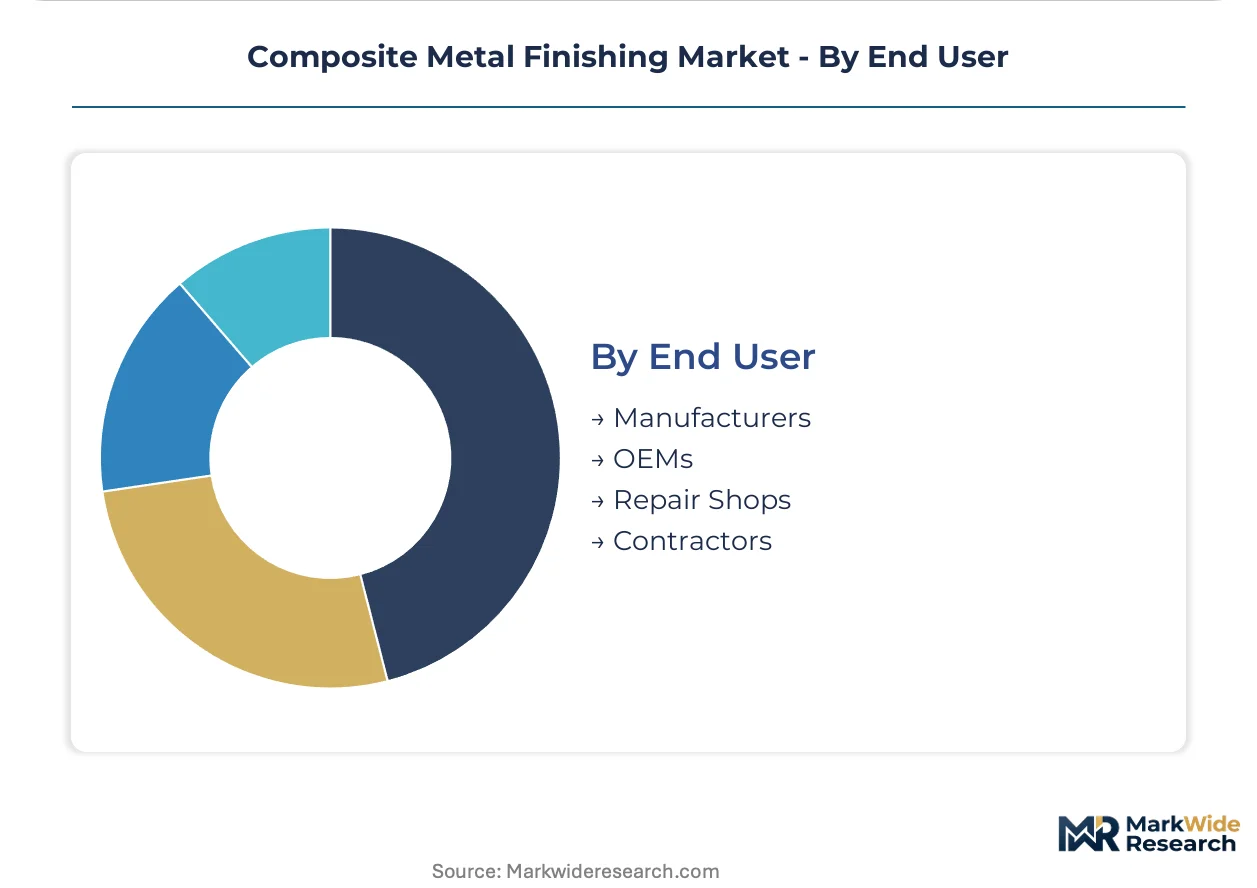
- Manufacturers:Large-scale industrial producers integrate composite finishing processes into their production lines for high-volume component output. Automotive manufacturers in Germany are key customers for in-house or dedicated external finishing services.
- OEMs:Original Equipment Manufacturers specify composite finishes for components supplied by their vendor networks, ensuring compliance with strict performance and regulatory standards. Aerospace OEMs in the United States demand rigorous qualification processes for new coating solutions.
- Repair Shops:These entities apply composite finishes for restoration, maintenance, and enhancement of components, often dealing with smaller batches and specialized requirements.
- Contractors:Independent service providers offer specialized composite finishing services to various industries, leveraging expertise in diverse plating technologies and material science.
Manufacturers constitute the primary demand. OEMs exhibit the most dynamic expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration in composite metal finishing centers on regions with advanced manufacturing capabilities and stringent regulatory environments. Germany's automotive sector and China's electronics production drive substantial demand for enhanced surface properties. The aerospace industry in the United States also presents significant requirements for durable, lightweight coatings.
Germany
Demand for composite finishes in Germany's automotive manufacturing sector focuses on wear resistance for engine components. The EU's REACH framework heavily influences material selection, restricting hexavalent chromium. Bavaria's automotive hubs, including Munich and Stuttgart, accelerate the adoption of compliant alternatives for critical parts.
China
China's vast electronics manufacturing ecosystem requires advanced composite finishes for miniaturized components, ensuring corrosion protection and EMI shielding. The country's dual carbon goals and MEE regulations push for greener plating processes. The Yangtze River Delta region, particularly around Shanghai and Shenzhen, concentrates production of these high-performance electronic devices.
United States
Aerospace components in the United States demand finishes with exceptional wear resistance and fatigue strength for critical parts like landing gear. FAA regulations mandate rigorous testing and qualification processes for new coating solutions. Seattle's aerospace cluster, home to major aircraft manufacturers, drives innovation in high-performance composite applications.
Japan
Japan's advanced manufacturing industries, including automotive and industrial equipment, seek composite coatings for improved durability and reduced friction. METI initiatives support research into new materials and surface engineering techniques. The Kanto region, with its high-tech industrial parks, focuses on integrating these finishes into precision components.
India
India's growing automotive and electronics sectors are increasing demand for composite metal finishing solutions that offer better wear and corrosion resistance. BIS standards are evolving to align with global environmental and performance benchmarks. The Chennai-Bengaluru industrial corridor is witnessing investments in advanced plating facilities to serve these expanding industries.
Composite Metal Finishing Market Key Industry Players
Channel-controlling players compete with product-specialist players across the composite metal finishing market. The market exhibits a tiered structure, with established chemical suppliers offering comprehensive portfolios alongside niche applicators focusing on high-performance segments. Strategic archetypes include integrated chemical and equipment providers, specialized finishing service houses, and raw material innovators. Dominant competitive moves involve strategic partnerships for new material qualification and continuous portfolio diversification into compliant chemistries.
Specialists in surface treatment technologies include Atotech, a German-based company known for integrated production systems and advanced electroplating chemistries. Element Solutions Inc., a US-based entity, leverages its extensive chemical portfolio across multiple surface treatment technologies. Japan-based UYEMURA exemplifies a focus on high-reliability finishes for the consumer electronics and semiconductor industries, anchoring the high-performance niche. These companies represent the diverse approaches to innovation and market penetration within the composite metal finishing sector.
| Leading Market Players |
|---|
| Atotech |
| Asterion LLC |
| Metal Finishing Technologies LLC |
| Coventya International |
| Quaker Houghton |
| Element Solutions Inc. |
| UYEMURA |
| Endura Coatings |
| Chemetall GmbH |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta region's extensive electronics manufacturing capacity influences pricing for advanced composite finishes. This concentration of production drives efficiency but also creates competitive pricing pressures for specialized coatings.
Pricing Analysis
Cost-plus contracts, often indexed to raw material prices like nano-grade silicon carbide, dominate long-term agreements in composite metal finishing. Price differentiation stems from certification levels required by aerospace OEMs and the customization level for specific industrial equipment applications. Pricing softness reflects intense competition for high-volume automotive parts contracts in Germany. Aerospace component manufacturers exhibit the least price sensitivity, prioritizing performance guarantees over cost, while general industrial equipment buyers are more price-sensitive.
Supply Chain Analysis
Export controls on specialized chemicals and nano-grade particles, particularly from China, limit the flow of critical inputs for composite metal finishing. The supply chain draws from concentrated production hubs in China and Germany for essential electroplating chemistries and high-purity nanoparticles. Single-source vulnerability for advanced PTFE and diamond particle suppliers represents a significant structural risk. Distribution runs through specialized chemical distributors and direct sales to large applicators or OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The composite metal finishing market presents a fragmentation opportunity, driven by end-users shifting from specifying simple coating thickness to demanding functional performance outcomes. This creates numerous high-value niches for specialized applicators and material suppliers.
For Market Incumbents: Insulate core market share by investing in advanced in-situ process monitoring technologies to ensure consistent quality for aerospace components. Pursue strategic partnerships with OEMs to co-develop next-generation compliant coatings, mitigating the threat of regulatory-driven material substitution. Vertical integration into specialized raw material production, particularly nano-grade particles, can secure supply and improve cost control.
For New Entrants and Emerging Players: Pursue niche applications in electric vehicle components, focusing on specialized coatings for battery enclosures and busbars. Target the medical device sector in Germany, developing bio-compatible finishes for high-value implants and surgical instruments. A go-to-market strategy centered on performance-based guarantees and extensive compliance documentation will accelerate adoption in these critical applications.
For Investors and Strategic Acquirers: Long-term, this sits as a technology-driven consolidation play because regulatory pressures and advanced material science demand significant R&D investment. Focus on acquiring specialized finishing service houses with proprietary chemistries and established OEM qualifications in aerospace or medical devices. The signal to watch is the accelerated qualification of new, non-hexavalent chromium composite coatings by major automotive manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Bio-Compatible Finishes | Addresses a high-value niche in medical devices with stringent performance criteria. |
| Invest in In-Situ Process Monitoring | Ensures absolute repeatability and zero-defect tolerance for aerospace and semiconductor manufacturers. |
| Formulate Trivalent Chromium Alternatives | Secures market access in automotive components, especially in Germany, due to REACH regulations. |
| Expand Nanoparticle Sourcing Network | Mitigates supply chain bottlenecks and price volatility for critical raw materials like PTFE. |
| Acquire Specialized Finishing Service House | Gains proprietary expertise and OEM qualifications in high-margin sectors like aerospace. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through extensive primary interviews with material scientists, OEM procurement leads, and finishing applicators. Secondary validation drew from industry association reports, patent databases, and regulatory filings from the US EPA and EU ECHA. This approach combined qualitative insights with quantitative data, employing both bottom-up market sizing and top-down validation for robust estimates.
Volume and value outputs reflect a triangulated approach, calibrating historical data against future projections across the analysis window. Segmentation dimensions modeled include process type, application, material type, and regional regulatory impact. Compound Annual Growth Rates were derived from an assessment of technological adoption rates and end-user performance requirements. Forecast inputs included projected aerospace build rates and electric vehicle production forecasts.
Macroeconomic conditions sit as an overlay; deviation in global manufacturing output or raw material commodity prices would shift the trajectory. Forecasts reflect assumptions regarding regulatory enforcement and technological advancements in nanoparticle dispersion. Material shifts in hexavalent chromium substitution timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Balsa Core Materials Market
Composite Materials
Composites Testing Market
Composite Materials
Fiber-Reinforced Plastic (FRP) Grating Market
Composite Materials
China Marine Composites Market
Composite Materials
Global Sports Composites Market
Composite Materials
Epoxy Composite Market
Composite Materials
Europe Composites Market
Composite Materials
Glass Fiber Reinforced Plastic (GFRP) Market
Composite Materials
Marine Composites Market
Composite Materials
Molded Underfill Material Market
Composite Materials
Pressure Vessel Composite Materials Market
Composite Materials
Reinforced Nonwoven Plastics Market
Composite Materials
Composite Market
Composite Materials
Pultrusion Market
Composite Materials
Wall Cladding Materials Market
Composite Materials
LAMEA Composite Process Material Kits Market