
 Asia-Pacific Construction Adhesives and Sealants Market | 2026-2036
Asia-Pacific Construction Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Construction Adhesives and Sealants Market Outlook
China's Yangtze River Delta manufacturing corridor is reconfiguring regional supply dynamics for construction-grade polymers. Sika AG leverages its Swiss-engineered formulation heritage to dominate high-performance waterproofing specifications across Shanghai and Shenzhen infrastructure tenders. Henkel AG & Co. KGaA anchors its position through localized production of reactive polyurethane systems serving Japanese commercial contractors. Dow competes on silicone technology leadership, extending its materials science portfolio into photovoltaic-integrated building envelopes.
Asia-Pacific construction adhesives and sealants comprise formulated polymer systems—typically epoxy, polyurethane, silicone, or acrylic bases—engineered to bond, seal, or structurally join building materials under variable climatic stress, with tensile adhesion strength and elastomeric recovery serving as critical performance parameters for curtain wall and flooring applications. Silicone formulations command premium positioning in glazing and weatherseal applications where UV stability and movement accommodation define specification value. Water-based technology segments gain share as China's MEE and India's central pollution control authorities tighten volatile organic compound discharge limits on solvent-borne systems. Reactive technology, encompassing moisture-cure polyurethanes and two-component epoxies, captures the fastest growth trajectory in industrial and infrastructure end-use segments where load-bearing performance outweighs material cost sensitivity.
China's SAMR enforces GB standards for structural silicone sealants in curtain wall applications, while India's BIS mandates certification for construction chemical imports under revised quality control orders. Japan's METI coordinates JIS standards alignment with building energy efficiency codes that specify adhesive thermal performance in insulated panel assemblies. Stakeholders must monitor divergent national compliance timelines and pre-position formulation registration strategies across multiple Asia-Pacific jurisdictions.
Market Dynamics
China's MEE enforcement of volatile organic compound discharge limits is forcing solvent-borne formulation obsolescence across the Asia-Pacific construction adhesives and sealants market, compressing legacy supply chains while accelerating water-based and reactive technology substitution.
Growth Catalysts
- India's BIS certification mandate:Revised quality control orders for construction chemical imports are elevating compliance barriers that favor established formulation suppliers with testing infrastructure.
- Reactive polyurethane systems:Moisture-cure and two-component technologies capture specification preference in Japanese commercial infrastructure where load-bearing performance outweighs material cost sensitivity.
- Tier-one Chinese megacities:Retrofit intensity converging with green building codes in Shanghai and Shenzhen is concentrating demand for advanced bonding systems in curtain wall and flooring applications.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane and silicone precursor costs fluctuate with regional naphtha and methanol pricing, compressing margin predictability for formulated product manufacturers.
- Structural silicone supply concentration:Premium-grade polymer production clusters in Japan and South Korea, creating geographic single-source risk for high-performance glazing specifications.
- GB standard compliance friction:China's SAMR enforcement timelines for curtain wall sealant certification create registration bottlenecks that delay product commercialization.
Strategic Opportunities
- Photovoltaic-integrated building envelopes:Silicone technology convergence with solar module sealing applications opens specification pathways in China's distributed energy retrofit programs.
- Southeast Asian residential high-rise:Underpenetrated premium bonding demand in Vietnam and Indonesia offers first-mover positioning as advanced construction methods displace traditional mechanical fastening.
- Japan's METI energy efficiency codes:JIS standards alignment specifying adhesive thermal performance in insulated panel assemblies creates mandate-driven demand for certified formulation suppliers.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in moisture-cure polyurethane systems and silicone rheology remains concentrated among aging technical workforces in Japan and South Korea.
- Multi-jurisdiction registration complexity:Divergent national compliance timelines across China, India, and Japan force redundant testing expenditure and extended product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Construction Adhesives and Sealants Market |
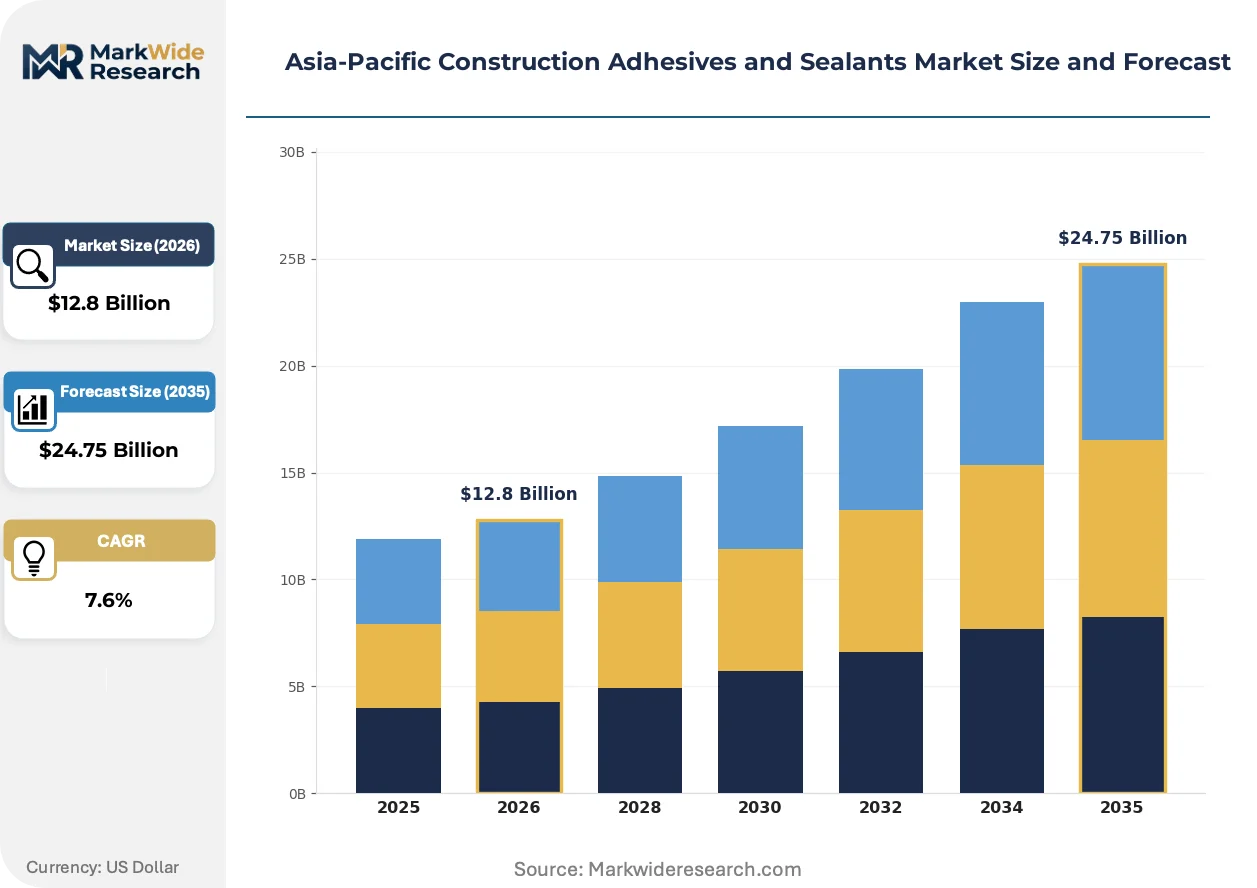
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $24.75 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Silicone, Acrylic Application: Woodworking, Flooring, Roofing, Waterproofing End User: Residential, Commercial, Industrial, Infrastructure Technology: Water-Based, Solvent-Based, Hot Melt, Reactive |
| Companies Covered | 3M, Sika AG, Henkel AG & Co. KGaA, Arkema Group, H.B. Fuller Company, BASF SE, Dow, Pidilite Industries Ltd., Aica Kogyo Co. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Construction Adhesives and Sealants Market Strategic Shifts
Digital formulation platforms are compressing product development cycles across the Asia-Pacific construction adhesives and sealants market, while regulatory tightening on chemical discharge and energy performance is reshaping specification criteria for bonding systems.
AI-assisted rheology modeling is digitizing silicone sealant formulation optimization, enabling predictive performance mapping under variable climatic stress before physical prototyping. Japanese commercial contractors and Chinese state-owned infrastructure developers are adopting these platforms at accelerating pace. The technology is digitizing traditional empirical testing workflows, compressing time-to-certification for curtain wall and weatherseal applications.
China's MEE volatile organic compound discharge regulations are eliminating solvent-borne acrylic and rubber-based systems from state-funded construction tenders. Industrial consequence includes forced capital redeployment toward water-based emulsion and reactive hot-melt production lines. Water-based technology segments gain share fastest in interior flooring and panel bonding specifications where movement accommodation requirements are less severe.
Specification authority is migrating from general contractors to facade engineering consultants in China's tier-one megacities and Tokyo's commercial development sector. Design-build contracts are unbundling material selection from bulk procurement, replacing volume-based supplier relationships with performance-certified product nominations. This shift concentrates decision leverage in Shanghai, Shenzhen, and Osaka building envelope specialist firms.
Asia-Pacific Construction Adhesives and Sealants Market Segmentation
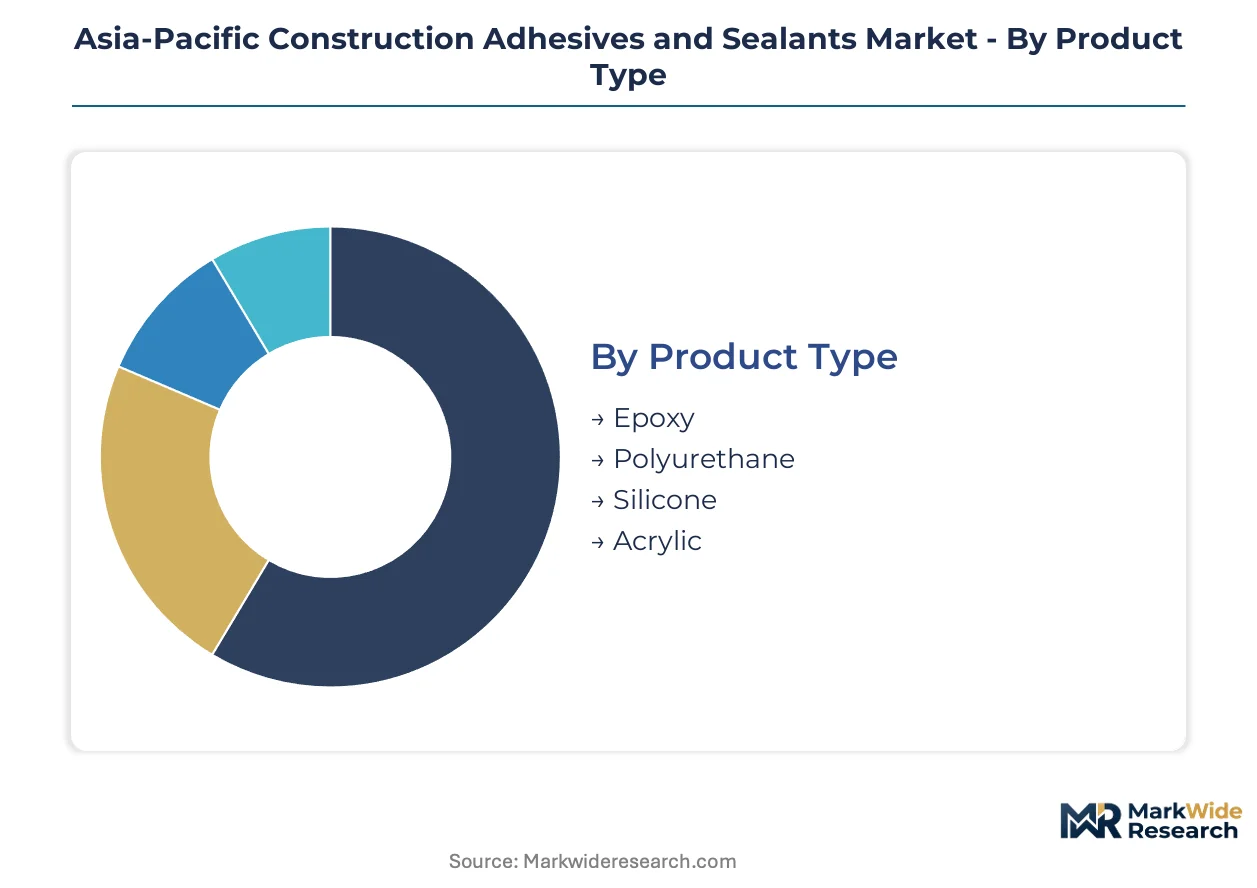
Segmentation in the Asia-Pacific construction adhesives and sealants market reveals how formulation chemistry, application stress, and regulatory pressure intersect to create distinct competitive arenas. Each dimension carries different service intensity requirements, technical support demands, and specification authority structures that reshape supplier economics.
Product Type:
After-sales-service intensity varies sharply across polymer chemistries, with structural specifications demanding ongoing technical support that commodity formulations cannot support.
- Epoxy:Two-component thermosetting systems deliver exceptional compressive strength and chemical resistance for structural anchoring and industrial flooring. Demand concentrates in Japanese commercial infrastructure and Chinese state-owned industrial projects where load-bearing certification requirements mandate pre-installation testing support and on-site mixing supervision.
- Polyurethane:Moisture-cure and two-component elastomeric formulations dominate curtain wall and expansion joint applications across Shanghai and Shenzhen high-rise construction. India's BIS certification mandates for structural sealants are elevating compliance costs for imported polyurethane systems, favoring suppliers with localized testing infrastructure.
- Silicone:UV-stable elastomeric sealants command premium positioning in glazing and weatherseal specifications where movement accommodation exceeds 25%.
- Acrylic:Water-based emulsion systems serve interior panel bonding and decorative trim applications with lower performance thresholds.
Silicone holds the largest share; momentum sits with polyurethane as reactive technology specifications expand.
Application:
Cost tier stratification separates specification-grade applications from commodity procurement, with facade engineering consultants increasingly controlling material selection in premium segments.
- Waterproofing:Below-grade and podium deck membrane systems require continuous elastomeric performance under hydrostatic pressure and thermal cycling. Specification concentrates in China's tier-one megacity retrofit programs and Tokyo commercial redevelopment where JIS standards alignment with METI energy codes mandates certified thermal performance in insulated assemblies.
- Roofing:Single-ply membrane bonding and metal seam sealing demand UV-stable formulations with 20-plus year service life guarantees. India's accelerating commercial construction in Bengaluru and Hyderabad is driving specification of SBS-modified bitumen adhesives and silicone weatherseals for podium-level mechanical equipment screening.
- Flooring:Reactive polyurethane systems capture industrial and commercial specifications where point-load resistance and chemical spill tolerance define value.
- Woodworking:Interior joinery and furniture assembly applications favor water-based emulsions and hot-melt systems with lower capital equipment requirements.
Waterproofing commands the highest margin tier; flooring applications are expanding most quickly as industrial construction accelerates across Vietnam and Indonesia.
End User:
Volume concentration patterns diverge sharply, with infrastructure and commercial segments consolidating procurement authority while residential remains fragmented.
- Infrastructure:State-funded transportation, energy, and water projects in China and India specify certified structural bonding systems with mandatory pre-qualification testing. China's MEE volatile organic compound discharge limits are eliminating solvent-borne options from state tender eligibility, forcing technology transitions toward water-based and reactive systems.
- Commercial:High-rise office, retail, and hospitality developments across Southeast Asia are accelerating displacement of mechanical fastening by advanced bonding in curtain wall and interior fit-out applications. Design-build contract unbundling in Tokyo and Osaka is migrating specification authority to facade engineering consultants who nominate performance-certified products.
- Industrial:Manufacturing facility construction and maintenance drives demand for chemical-resistant epoxy and polyurethane systems.
- Residential:Fragmented contractor bases across India and Southeast Asia sustain price-competitive procurement of standard-grade acrylic and hot-melt formulations.
Commercial captures the highest specification value; infrastructure delivers the steepest expansion trajectory as government capital deployment accelerates.
Technology:
Supply concentration in reactive polymer precursors creates geographic dependency risks that reshape formulation sourcing strategies.
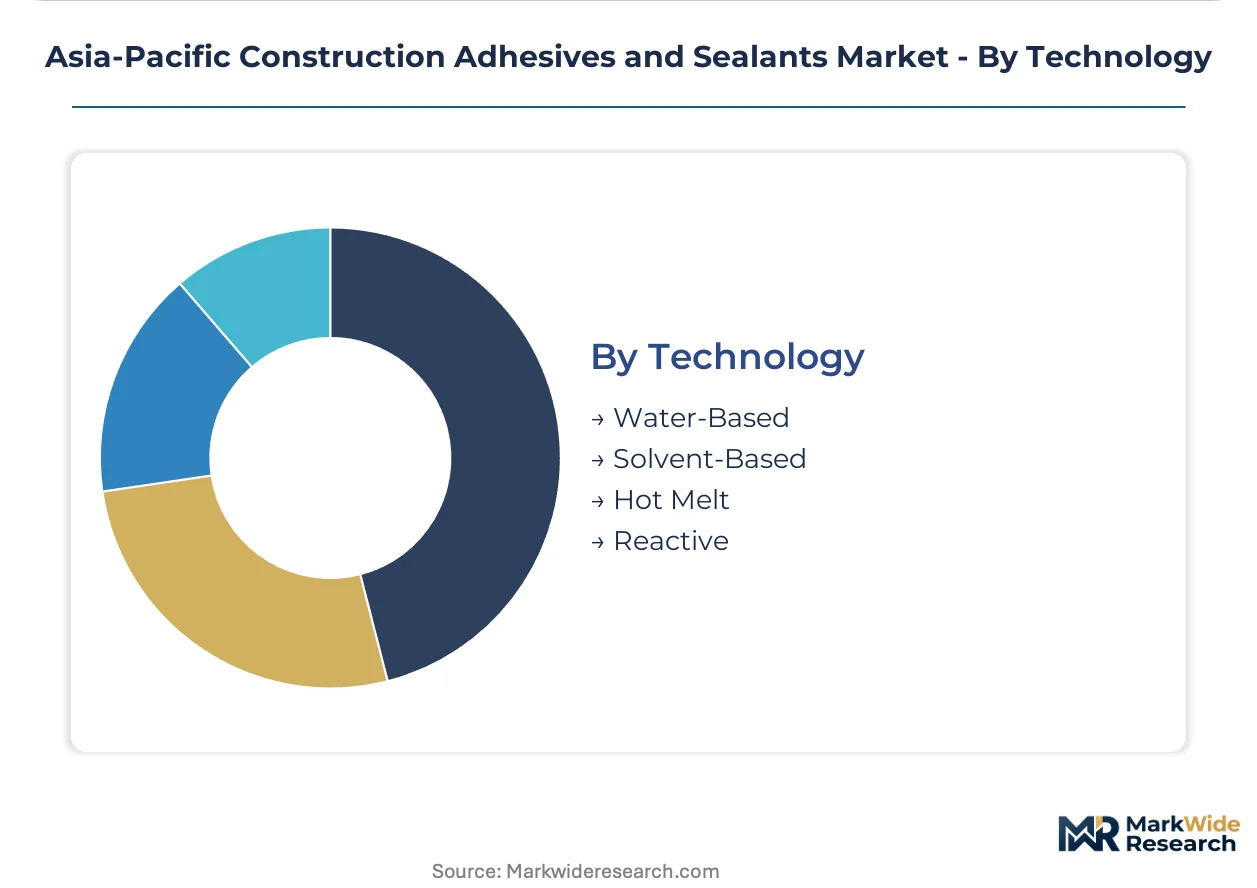
- Reactive:Moisture-cure polyurethanes and two-component epoxies deliver load-bearing performance for structural and industrial applications where material cost sensitivity is secondary to certification reliability. Production of specialized isocyanate and amine hardener components clusters in Japan and South Korea, creating single-source exposure for Asia-Pacific formulators.
- Water-Based:Acrylic and polyurethane dispersions gain share fastest in interior applications as China's MEE and India's central pollution control authorities tighten discharge limits on solvent-borne systems. Formulation expertise in emulsion stability and film formation remains concentrated among aging technical workforces.
- Solvent-Based:Rapid-evaporation systems persist in field repair and cold-weather applications where water-based alternatives fail.
- Hot Melt:Reactive polyurethane hot-melts serve automated panel bonding lines in prefabricated construction with instant green strength and subsequent moisture cure.
Water-based technology holds the largest share; reactive systems are gaining share fastest in specification-grade infrastructure and commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer precursor production clusters in Japan and South Korea, creating geographic dependency for Asia-Pacific formulators seeking certified structural sealant inputs. China's Yangtze River Delta manufacturing corridor dominates formulated product output for regional distribution. India's BIS certification infrastructure remains concentrated in Mumbai and Delhi testing laboratories.
China
Shanghai and Shenzhen megacities drive retrofit demand for curtain wall bonding systems as green building codes tighten energy performance specifications. SAMR enforces GB standards for structural silicone sealants with mandatory pre-installation testing protocols. The Yangtze River Delta manufacturing corridor reconfigures supply dynamics as MEE volatile organic compound discharge limits force solvent-borne formulation obsolescence.
Japan
Tokyo and Osaka commercial developments accelerate specification of reactive polyurethane systems for load-bearing curtain wall applications. METI coordinates JIS standards alignment with building energy efficiency codes mandating certified adhesive thermal performance in insulated panel assemblies. Kanto region technical workforces concentrate specialized expertise in moisture-cure polymer rheology.
India
Bengaluru and Hyderabad commercial construction drives demand for SBS-modified bitumen adhesives and silicone weatherseals in podium-level applications. BIS mandates certification for construction chemical imports under revised quality control orders elevating compliance barriers. Mumbai and Delhi testing laboratories concentrate formulation registration infrastructure for imported systems.
South Korea
Seoul Capital Area infrastructure projects specify certified structural bonding systems with mandatory pre-qualification testing for state-funded transportation tenders. MFDS alignment with international chemical safety standards shapes import compliance protocols for polyurethane precursors. Busan-Ulsan industrial corridor concentrates premium-grade polymer production creating single-source exposure for regional formulators.
Vietnam
Hanoi and Ho Chi Minh City residential high-rise construction accelerates displacement of mechanical fastening by advanced bonding systems. Central pollution control authority discharge limits on solvent-borne systems gain enforcement traction in state-funded tenders. Underpenetrated premium bonding demand offers first-mover positioning as advanced construction methods penetrate Southeast Asian markets.
Asia-Pacific Construction Adhesives and Sealants Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream on precursor supply. The vendor base organizes around three strategic tiers: multinational formulation platforms with localized production assets, regional specialists with certified testing infrastructure, and commodity suppliers serving price-sensitive residential segments. Consolidation pressure concentrates among mid-scale formulators lacking reactive technology expertise or multi-jurisdiction registration capabilities. Capacity expansion and portfolio diversification toward water-based and reactive systems represent dominant competitive vectors as regulatory discharge limits eliminate solvent-borne alternatives.
Among Swiss-engineered formulation platforms, Sika AG occupies a position exemplifying heritage-driven specification dominance in high-performance waterproofing tenders. German chemical conglomerates Henkel AG & Co. KGaA and BASF SE represent archetypes of localized production strategies serving regional compliance requirements. Dow sits within the materials science tier, anchoring silicone technology leadership for photovoltaic-integrated building envelope applications. These three entities illustrate how geographic origin and corporate structure shape competitive positioning across certification-intensive specification channels.
| Leading Market Players |
|---|
| 3M |
| Sika AG |
| Henkel AG & Co. KGaA |
| Arkema Group |
| H.B. Fuller Company |
| BASF SE |
| Dow |
| Pidilite Industries Ltd. |
| Aica Kogyo Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Premium-grade silicone precursor production clusters in Japan and South Korea, anchoring margin pools downstream with formulators who control certified structural sealant specifications across Shanghai and Shenzhen infrastructure tenders. China's MEE discharge limits on solvent-borne systems are compressing legacy supply chains while elevating pricing power for reactive technology holders with localized water-based production assets.
Pricing Analysis
China's GB standards for structural silicone sealants dictate the pricing tier structure across curtain wall applications, separating certified pre-installation testing bundles from commodity procurement. Three-tier pricing structure across premium certification-grade, standard compliance-tier, and economy solvent-borne levels reflects divergent after-sales service intensity and technical support bundling. Price differentiation hinges on BIS certification status for Indian imports and JIS thermal performance alignment for Japanese insulated panel specifications. Cost compression in solvent-borne tiers is intensifying because MEE enforcement eliminates state tender eligibility, while reactive polyurethane specifications in Tokyo commercial projects show lowest buyer price sensitivity due to load-bearing performance mandates.
Supply Chain Analysis
Export-control regimes on specialized isocyanate and amine hardener technologies limit precursor flows from Japanese and South Korean producers to regional formulators, creating licensing friction for moisture-cure polyurethane systems. Geographic supply concentration rests on Japan, South Korea, and China's Yangtze River Delta manufacturing corridor for formulated product output. Raw material dependencies draw from regional naphtha and methanol pricing for polyurethane precursors, plus specialized silicone monomer feeds from Busan-Ulsan industrial clusters. Single-source vulnerability runs through premium-grade polymer production concentration in Japan and South Korea. Distribution runs through facade engineering consultants in tier-one Chinese megacities and Tokyo who unbundle specification authority from bulk procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-based and reactive technology substitution is disrupting legacy solvent-borne supply chains as China's MEE enforcement eliminates state-funded tender eligibility, compressing product development cycles and reshaping competitive positioning across the Asia-Pacific construction adhesives and sealants market.
For Market Incumbents: Pre-empt formulation obsolescence by accelerating capital redeployment toward reactive polyurethane and water-based emulsion production lines in the Yangtze River Delta manufacturing corridor before MEE discharge limits fully eliminate solvent-borne alternatives from state tenders. Secure BIS certification infrastructure in Mumbai and Delhi testing laboratories to defend Indian import compliance barriers against emerging regional specialists. Backward integration into specialized isocyanate precursor supply from Japanese producers reduces single-source exposure for moisture-cure systems. For New Entrants and Emerging Players: Build out certified testing infrastructure in Vietnam and Indonesia to capture first-mover positioning in underpenetrated residential high-rise bonding specifications as advanced construction methods displace mechanical fastening across Southeast Asia. Target Hanoi and Ho Chi Minh City commercial developments with reactive polyurethane systems for curtain wall applications where load-bearing performance mandates override material cost sensitivity. Partner with facade engineering consultants in tier-one Chinese megacities to secure specification nomination authority unbundled from general contractor procurement. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-scale formulators lacking reactive technology expertise or multi-jurisdiction registration capabilities across China and India, presenting consolidation targets for platform integrators seeking certified testing infrastructure. Long-term viability over a multi-year horizon favors suppliers with localized water-based production assets and JIS-BIS-GB standard alignment capabilities. Monitor MFDS chemical safety standard alignment announcements as signal for polyurethane precursor import compliance friction that would reshape regional sourcing economics.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Localized water-based emulsion production in Yangtze River Delta secures MEE compliance for state tenders. |
| Backward Integration | Captive isocyanate precursor supply from Japanese producers reduces single-source dependency for moisture-cure systems. |
| Green Manufacturing Transition | Reactive hot-melt line conversion eliminates solvent-borne discharge exposure under tightening MEE enforcement. |
| Long-term Supply Agreement | Silicone monomer offtake contracts with Busan-Ulsan producers stabilize premium-grade sealant input costs. |
| Joint Venture | Facade engineering consultant partnerships in Shanghai and Shenzhen secure unbundled specification nomination authority. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, and chemical industry association reports to construct segment-level demand estimates. Primary interviews with plant managers at formulated product facilities, procurement leads at Japanese commercial contractors, distribution channel partners across Southeast Asia, and technical R&D directors specializing in moisture-cure polymer rheology inform supply-side validation. Bottom-up triangulation against top-down macroeconomic indicators ensures cross-verification of volume and value outputs.
Forecast inputs include modeled projections across product type, application stress tier, end-use segment, and technology chemistry dimensions throughout the forecast period. CAGRs derive from segment-level growth rate reconciliation against regional construction activity indices and regulatory compliance timeline assumptions. Industry-specific inputs incorporate MEE enforcement trajectory for solvent-borne formulation phase-out and BIS certification mandate expansion for Indian construction chemical imports.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion moves by Chinese state-owned chemical conglomerates would shift outcomes beyond modeled supply-demand balances. Material shifts in MFDS chemical safety standard alignment or SAMR GB standard revision timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Middle East and Africa Human Fibrin Glue Market
Adhesives & Sealants
Metal Bonding Adhesives Market
Adhesives & Sealants
Chemical Anchors Market
Adhesives & Sealants
North America Cyanoacrylate Adhesives Market
Adhesives & Sealants
MS Polymer Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Global Construction Adhesive Tapes Market
Adhesives & Sealants
Global Medical Adhesives Market
Adhesives & Sealants
Windscreen Adhesive Market
Adhesives & Sealants
Global Concrete Bonding Agents Market
Adhesives & Sealants
Middle-East and Africa Waterborne Adhesives Market
Adhesives & Sealants
Spain Adhesives Market
Adhesives & Sealants
Timber Laminating Adhesives Market
Adhesives & Sealants
Global Vascular Sealant Market
Adhesives & Sealants
Japan Adhesives Market
Adhesives & Sealants
Spray Fluxer Market
Adhesives & Sealants
UV Adhesives Market