
 Drum Filters Market | 2026-2036
Drum Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Drum Filters Market Analytics
Direct OEM-to-municipality procurement is tilting toward bundled service contracts that include remote monitoring and spare-part guarantees. Pentair leverages its digital water platform to anchor long-term municipal relationships across North American utilities. Veolia Water Technologies competes through integrated design-build-operate frameworks that reduce client capital burden. Andritz dominates large-scale mining installations with customized drum diameters and throughput configurations.
A drum filter is a continuous rotary vacuum or pressure filtration device consisting of a cylindrical screen drum partially submerged in a slurry tank, with filtrate passing through the screen medium while solids cake on the exterior surface for subsequent discharge by knife, blowback, or string mechanism. The drum operates at rotational speeds typically between 0.1 and 3 rpm, with filtration areas ranging from 0.5 to 120 square meters depending on industrial duty. Water treatment applications lead installed base volume globally, though mining tailings recovery represents the fastest-expanding margin pool as pressure filtration technology displaces legacy thickening circuits. Stainless steel product types command premium positioning in chemical management environments where corrosion resistance extends operational cycles beyond polymer alternatives.
EPA effluent limitation guidelines under the Clean Water Act shape municipal procurement specifications for tertiary filtration systems in US wastewater plants. EU Urban Wastewater Treatment Directive revisions and REACH substance restrictions on filter media coatings jointly determine product compliance pathways for European suppliers. China's MEE discharge standards for industrial wastewater tighten annually, forcing domestic facilities toward automated backwash drum systems with real-time turbidity feedback. Stakeholders must weigh capex-opex trade-offs between gravity and pressure technologies as energy pricing volatility and carbon accounting requirements reshape total cost of ownership calculations.
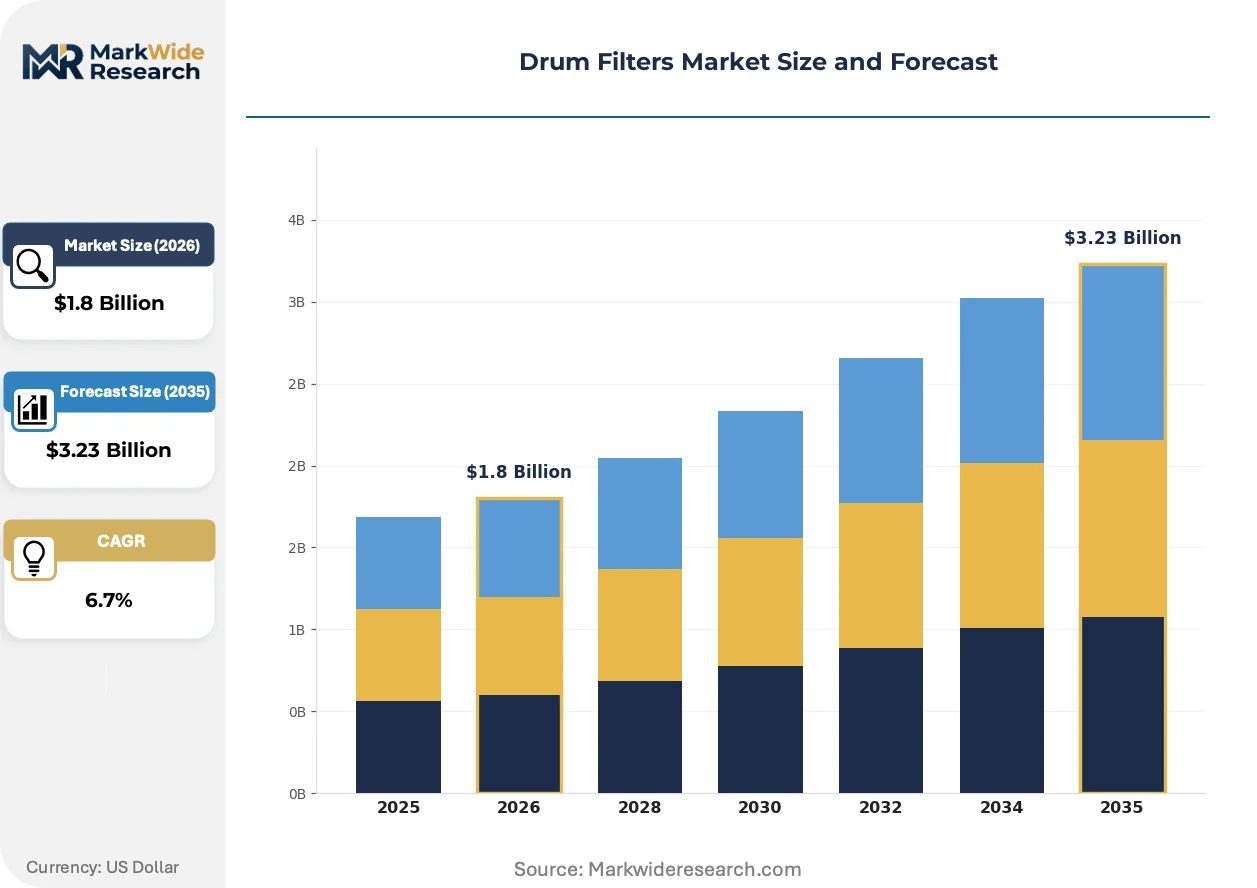
Market Dynamics
Pressure filtration technology is collapsing the installed base of gravity thickening circuits in mining tailings recovery, while EU Urban Wastewater Treatment Directive discharge limits force municipal utilities toward tertiary drum filtration upgrades.
Growth Catalysts
- REACH substance restrictions:European filter media coating compliance requirements are accelerating stainless steel mesh substitution for polymer alternatives in chemical management environments.
- Mining tailings recovery:Pressure filtration technology is displacing legacy thickening circuits as the fastest-expanding margin pool for drum filter suppliers.
- China MEE discharge standards:Annual tightening of industrial wastewater rules forces domestic facilities toward automated backwash drum systems with real-time turbidity feedback.
Market Restraints
- Nickel price volatility:Stainless steel mesh production costs fluctuate with London Metal Exchange nickel futures, compressing margins for corrosion-resistant product lines.
- Gravity technology lock-in:Municipal utilities face stranded asset risk from existing thickening infrastructure, slowing pressure filtration conversion timelines.
- Polymer filter belt substitution:Lower-capex belt press systems capture budget-constrained wastewater projects in emerging economies.
Strategic Opportunities
- Digital twin integration:Remote monitoring platforms bundled with spare-part guarantees are capturing long-term municipal service contracts.
- Scandinavian food processing corridors:EFSA hygiene standards enforcing material traceability create premium positioning for certified stainless steel variants.
- EU Green Deal carbon accounting:Energy-efficient pressure filtration systems qualify for green procurement preferences in public utility tenders.
Industry Challenges
- Filtration engineer scarcity:Specialized expertise in rotary vacuum drum optimization remains concentrated among aging technician cohorts in Germany and the Netherlands.
- Legacy SCADA integration:Real-time turbidity feedback systems require costly retrofitting of 1990s-era municipal control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drum Filters Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Nylon, Stainless Steel, Composite Application: Water Treatment, Mining, Food Processing, Chemical Management End User: Municipalities, Industrial Facilities, Aquaculture, Wastewater Plants Technology: Gravity Filtration, Pressure Filtration, Automated Systems, Manual Operation |
| Companies Covered | Andritz, Pentair, FLSmidth A/S, Veolia Water Technologies, Xylem, Buhler AG, Alteyco, BHS-Sonthofen, PRAB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drum Filters Market Evolving Landscape
Automation and material science advances are compressing operational cycles while digital service models restructure buyer-supplier relationships across water treatment and mining verticals.
Self-cleaning wedge wire screen technology is collapsing maintenance intervals for high-solids mining applications. Rio Tinto and BHP installations in Western Australia now specify automated backwash cycles triggered by differential pressure sensors rather than fixed timers. The resulting labor cost compression is reshaping total cost of ownership calculations against belt press alternatives.
EPA effluent limitation guidelines under the Clean Water Act now mandate tertiary filtration for phosphorus removal in Chesapeake Bay watershed utilities. Wisconsin and Maryland wastewater authorities specify drum filters with sub-10 micron absolute rating for combined sewer overflow treatment. Equipment suppliers are engineering compact skid-mounted configurations to fit legacy plant footprints.
Service unbundling is fragmenting traditional OEM procurement patterns. North American utilities now separate capital equipment purchases from 10-year maintenance agreements, enabling third-party remote monitoring specialists to capture recurring revenue streams. This shift is most pronounced in California and Texas municipal markets where staff retirements accelerate outsourcing decisions.
Drum Filters Market Segmentation
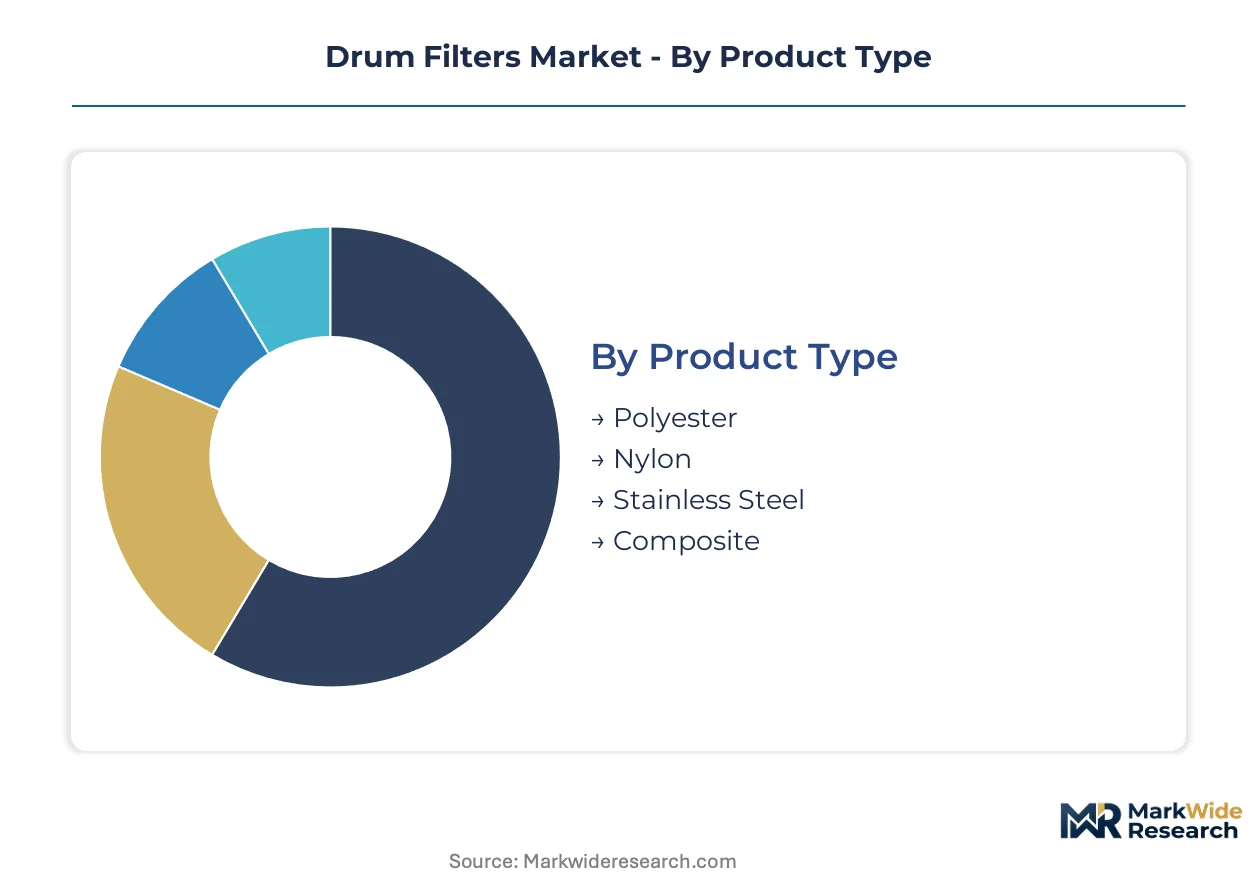
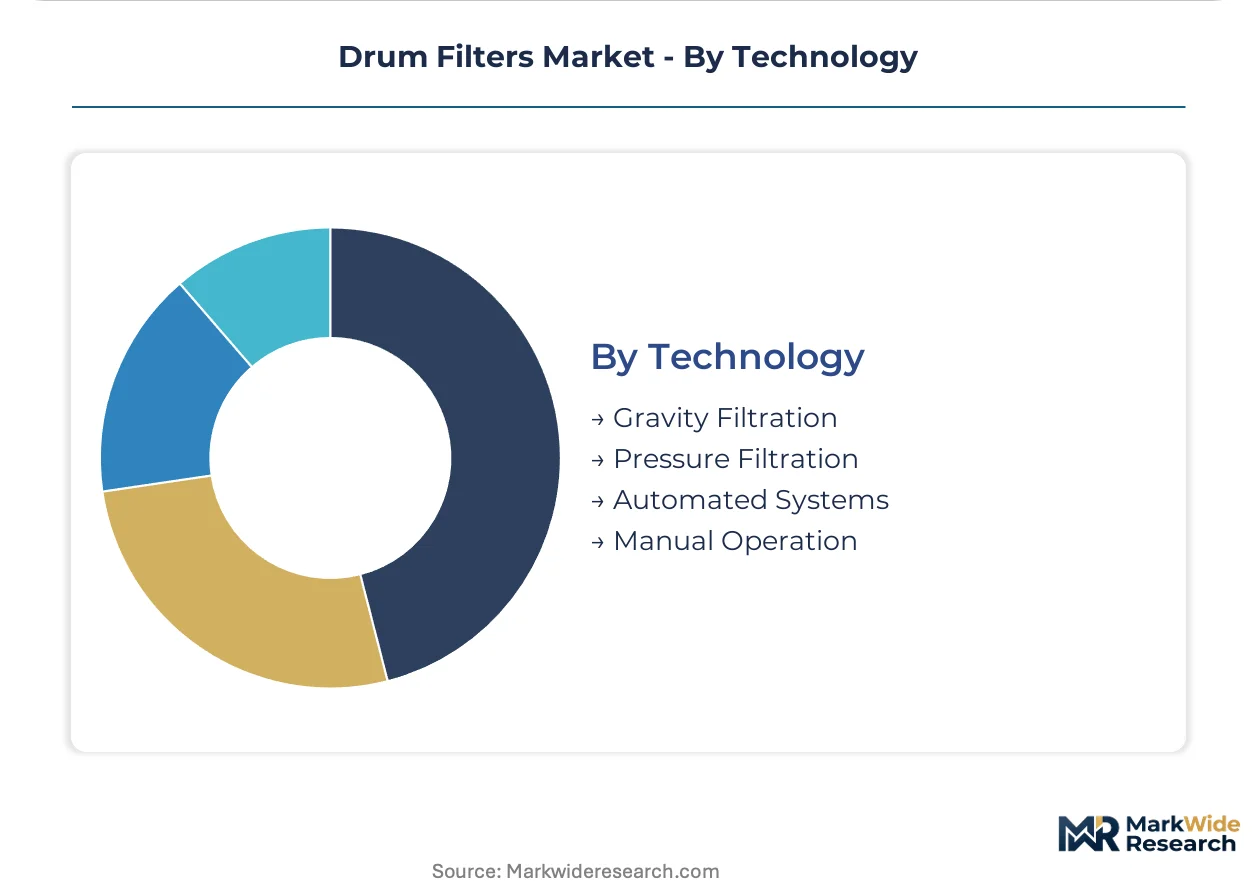
Drum filter procurement patterns diverge sharply across material specifications, operational environments, and automation requirements. Understanding these segment boundaries clarifies why stainless steel variants command premium positioning in chemical-intensive settings while gravity systems retain municipal utility preference despite pressure filtration advances.
Product Type:
Use-case spectrum spans from cost-sensitive bulk filtration in emerging economies to corrosion-resistant precision applications in regulated chemical corridors.
- Polyester:Woven synthetic mesh delivers sub-100 micron filtration at lowest capex entry point. Budget-constrained wastewater plants in India and Brazil specify polyester for primary solids separation where chemical exposure remains minimal.
- Stainless Steel:Corrosion-resistant austenitic grades extend operational cycles beyond polymer alternatives in aggressive pH environments. REACH substance restrictions on filter media coatings accelerate stainless steel substitution across EU chemical management facilities.
- Nylon:Abrasion-resistant polymer handles high-solids mining tailings with moderate chemical loading. Western Australian iron ore operations favor nylon for its fatigue resistance under cyclic loading conditions.
- Composite:Hybrid constructions combine polymer substrates with metallic surface treatments for specialized food processing hygiene requirements. EFSA traceability mandates in Scandinavian dairy corridors drive certified composite specifications.
Established volume favors polyester; emerging adoption favors stainless steel.
Application:
Margin concentration follows regulatory stringency, with discharge limit enforcement determining technology upgrade urgency across verticals.
- Water Treatment:Municipal tertiary filtration for phosphorus removal dominates installed base volume globally. EPA effluent limitation guidelines in Chesapeake Bay watershed utilities mandate sub-10 micron absolute ratings for combined sewer overflow treatment.
- Mining:Tailings recovery represents the steepest expansion trajectory as pressure filtration displaces legacy thickening circuits. Rio Tinto and BHP installations in Western Australia specify automated backwash cycles triggered by differential pressure sensors.
- Food Processing:Hygiene-critical dairy and beverage applications require material traceability documentation. EFSA standards enforce stainless steel or certified composite variants in Scandinavian processing corridors.
- Chemical Management:Aggressive solvent exposure demands corrosion-resistant construction. EU REACH compliance pathways restrict coated polymer alternatives in pharmaceutical and specialty chemical facilities.
Water treatment anchors current revenue; mining drives forward margin expansion.
End User:
Procurement authority fragmentation separates capital-budget municipal purchasers from opex-optimized industrial operators with distinct service expectations.
- Municipalities:Public utility tenders prioritize energy-efficient pressure filtration systems qualifying for EU Green Deal carbon accounting preferences. Wisconsin and Maryland authorities specify compact skid-mounted configurations to fit legacy plant footprints.
- Industrial Facilities:Private operators favor bundled service contracts with remote monitoring and spare-part guarantees. California and Texas markets accelerate outsourcing decisions amid staff retirements.
- Aquaculture:Recirculating aquaculture systems demand continuous filtration with minimal biological disruption. Norwegian salmon farming clusters specify automated drum filters with real-time turbidity feedback.
- Wastewater Plants:Tertiary treatment upgrades respond to tightened discharge limits. Germany and Netherlands facilities expand drum filter installations to meet revised EU Urban Wastewater Treatment Directive standards.
Municipalities dominate tender volume; industrial facilities pioneer service-contract restructuring.
Technology:
Energy pricing volatility and carbon accounting requirements reshape total cost of ownership calculations across gravity-to-pressure migration paths.
- Gravity Filtration:Passive operation eliminates pumping energy but requires larger footprint and longer retention times. Existing thickening infrastructure in mature municipal markets creates stranded asset risk slowing conversion timelines.
- Pressure Filtration:Forced-flow operation compresses cycle times and enables higher solids capture efficiency. Mining tailings recovery applications favor pressure systems for water recovery rates exceeding gravity alternatives.
- Automated Systems:Real-time sensor feedback triggers backwash cycles optimizing media lifespan. China MEE discharge standard tightening forces domestic industrial facilities toward automated configurations with turbidity monitoring.
- Manual Operation:Lowest first-cost option persists in small-scale aquaculture and remote mining camps. Labor availability constraints limit expansion outside emerging economy markets.
Gravity filtration retains legacy dominance; automated pressure systems capture specification momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor positions Germany as the logistics backbone for drum filter distribution across Central Europe. Municipal procurement clusters along this inland shipping network benefit from consolidated spare-part warehousing and rapid technician deployment.
Germany
Ruhr Valley wastewater authorities are retrofitting gravity thickening circuits with automated pressure filtration systems. The EU Urban Wastewater Treatment Directive revisions mandate tertiary phosphorus removal, accelerating drum filter specifications in North Rhine-Westphalia. Stuttgart's industrial equipment fabricators supply customized stainless steel variants to chemical management facilities along the Upper Rhine.
United States
Chesapeake Bay watershed utilities drive specification intensity for sub-10 micron absolute rating systems. EPA effluent limitation guidelines under the Clean Water Act now require phosphorus capture at 39 municipal plants across Maryland and Virginia. Wisconsin's dairy processing corridor favors compact skid-mounted configurations to fit legacy plant footprints.
China
Yangtze River Delta industrial parks are deploying real-time turbidity feedback systems under tightening MEE discharge standards. The dual carbon goals framework rewards energy-efficient pressure filtration with green procurement preferences in Jiangsu and Zhejiang tenders. Shanghai's equipment distributors stock automated backwash configurations for domestic pharmaceutical facilities.
Australia
Pilbara iron ore operations specify self-cleaning wedge wire screen technology for high-solids tailings recovery. Rio Tinto and BHP installations near Port Hedland trigger automated backwash cycles through differential pressure sensors rather than fixed timers. Perth-based service contractors capture recurring revenue through unbundled maintenance agreements.
Netherlands
Randstad municipal utilities expand drum filter installations to meet tightened EU discharge limits ahead of 2027 compliance deadlines. The country's dense waterway network enables barge-mounted equipment delivery to Rotterdam and Amsterdam treatment plants. Eindhoven's automation specialists integrate legacy SCADA architectures with real-time sensor feedback systems.
Drum Filters Market Competitive Landscape
On the supply side, the industry is bifurcated between integrated water technology conglomerates and specialized filtration fabricators. Tiered competitive positioning separates premium stainless steel specialists from volume-oriented polymer mesh suppliers. Strategic archetypes include design-build-operate integrators, component-focused OEMs, and third-party service unbundlers. Dominant competitive moves encompass geographic expansion through distribution partnerships and backward integration into wedge wire screen manufacturing.
Among Austrian-headquartered industrial equipment groups, Andritz exemplifies the large-scale mining specialist archetype through customized drum diameter configurations. Pentair and Xylem occupy positions within the digital water platform tier, anchoring long-term municipal relationships through bundled remote monitoring contracts. Veolia Water Technologies represents the integrated operator model, reducing client capital burden through comprehensive service frameworks.
| Leading Market Players |
|---|
| Andritz |
| Pentair |
| FLSmidth A/S |
| Veolia Water Technologies |
| Xylem |
| Buhler AG |
| Alteyco |
| BHS-Sonthofen |
| PRAB |
| Others |
Value Network & Pricing Analysis
Austenitic stainless steel production concentrates in Germany and China's Jiangsu province, anchoring premium drum filter pricing power in chemical management corridors while polyester mesh sourcing from India's Surat textile belt compresses margins at the economy tier. Buyers face asymmetric leverage: municipal utilities with consolidated procurement authority extract volume concessions, whereas fragmented aquaculture operators absorb spot-market volatility.
Pricing Analysis
Volume-discount tiering separates municipal framework agreements from spot purchases by remote mining camps. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—EFSA traceability documentation commands 15-25% premiums in Scandinavian food processing. Cost compression in the polyester segment intensifies as Indian weavers expand capacity. Municipal utilities exhibit lowest price sensitivity due to EU Green Deal procurement preferences, while emerging-market wastewater plants negotiate aggressively on capex.
Supply Chain Analysis
Supplier-financing facilities from German equipment fabricators extend 180-day payment terms to anchor distributor loyalty in Central Europe. Wedge wire screen manufacturing concentrates in Austria, Germany, and China's Shandong province. Nickel and chromium feedstock costs hinge on London Metal Exchange futures. Single-source vulnerability persists for precision-woven mesh below 50 microns. Distribution runs through Rhine-Main-Danube barge networks and Shanghai's Yangtze River port clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal procurement consolidation across Germany and the Netherlands shifts buyer power toward framework-tender dominance, fragmenting supplier pricing autonomy. This concentration demands strategic repositioning across three stakeholder archetypes.
For Market Incumbents: Build switching-cost moats through embedded digital twin platforms that lock utilities into decade-long service contracts. Backward integration into wedge wire screen manufacturing secures margin capture against nickel volatility. Defend against polymer belt press substitution by emphasizing total cost of ownership in EU carbon-accounting frameworks.
For New Entrants and Emerging Players: Pursue white-space penetration in China's Yangtze River Delta pharmaceutical corridor, where MEE discharge tightening outpaces domestic automation supply. Target manual-operation replacement cycles in Vietnam and Indonesia's emerging aquaculture clusters. Lead with turbidity-feedback retrofit kits compatible with legacy SCADA architectures.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed water technology platforms seeking exit liquidity in North American municipal service contracts. Five-to-ten-year viability favors automated pressure filtration specialists with recurring revenue density above 60%. Watch for nickel price stabilization as inflection signal for stainless steel margin recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wedge Wire Manufacturing | Austrian and German fabricators capture margin pools currently leaking to specialized mesh suppliers. |
| Digital Twin Platform Deployment | Pentair and Xylem anchor municipal relationships through predictive maintenance algorithms. |
| EFSA Certification Investment | Scandinavian dairy processors mandate material traceability documentation for supplier qualification. |
| Automated Backwash Configuration Launch | Rio Tinto and BHP specifications in Western Australia validate differential-pressure sensor triggering. |
| Compact Skid-Mounted System Development | Wisconsin and Maryland utilities retrofit legacy plant footprints without civil expansion. |
Research Methodology
Desk research of EU regulatory filings, EPA effluent limitation guidelines, and China MEE discharge standards preceded structured interviews with municipal procurement officers, mining tailings engineers, food processing hygiene managers, and filtration equipment distributors. Bottom-up unit economics triangulated against top-down industry association data from VDMA and Water Environment Federation sources.
Assumption sets held nickel price volatility and EU Urban Wastewater Treatment Directive compliance deadlines fixed across the projection horizon, while varying mining capex cycles and municipal outsourcing penetration rates. Segmentation modeling spanned material grade, automation tier, application vertical, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to tertiary filtration upgrade timelines and pressure filtration displacement rates in tailings recovery.
Sensitivities concentrate around nickel futures trajectory, REACH substance restriction expansion, and Chinese pharmaceutical discharge enforcement intensity. Forecasts reflect documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Hydraulic Filters Market
Filters
Homopolymer Acrylic Filter Bags Market
Filters
Europe Activated Carbon Market
Filters
Global Filter Press Market
Filters
Global Cartridge Filters Market
Filters
GCC Industrial Air Filtration Market
Filters
Industrial Air Filtration Market
Filters
Canada Filtration and Separation Market
Filters
Global Baghouse Filters Market
Filters
Fiberglass Filters Market
Filters
Coolant Filtration Skids Market
Filters
Furnace Filters Market
Filters
Filtration and Separation Market
Filters
Chloramine Filter Market
Filters
Global Liquid Filtration Market
Filters
Aerospace Filter Market