
 Foldable and Collapsible Pallets Market | 2026-2036
Foldable and Collapsible Pallets Market Size, Share, and Industry Trends Forecast 2026-2036
Foldable and Collapsible Pallets Market Analysis
Market Context
A capital-intensity divergence between injection-molding specialists and metal-fabrication incumbents is reorganizing competitive tiers in foldable pallet supply. Schoeller Allibert leverages large-scale European production networks to dominate reusable plastic pooling systems. CABKA Group anchors its position through proprietary recycled-polymer compounds that lower per-unit material costs. ORBIS Corporation extends its North American footprint via dedicated automotive-sector logistics programs.
Technical and Structural Dimensions
Foldable and collapsible pallets are engineered transport platforms with hinged or detachable components that reduce return-trip volume by up to 75 percent, typically manufactured through high-pressure injection molding of polypropylene or structural foam processes to achieve specified dynamic load ratings. Their primary purpose centers on closed-loop supply chains where empty pallet backhaul costs erode margins. Plastic pallets lead the product type category due to moisture resistance and consistent dimensional stability, while four-way entry designs capture premium positioning in automated warehouse environments. The logistics end-use segment sustains the deepest volume pools, though agriculture applications in perishable cold chains represent the fastest-expanding demand pocket.
Regulatory Environment and Outlook
REACH compliance in Europe governs chemical content in recycled polymer feedstocks, while FDA regulations in the United States dictate material safety for pallets contacting food and pharmaceutical products. The EU Green Deal's circular economy action plan is tightening extended producer responsibility for packaging materials, directly shaping pallet reusability specifications and market access conditions. Stakeholders must monitor how diverging regional sustainability certification schemes reshape cross-border equipment pooling eligibility and asset depreciation schedules.
Market Dynamics
The EU's Packaging and Packaging Waste Regulation is tightening reusability mandates, forcing logistics operators to accelerate closed-loop pallet pooling investments and retire single-use alternatives ahead of compliance deadlines.
Growth Catalysts
- EU Green Deal circular economy action plan:Extended producer responsibility rules now mandate minimum reusability thresholds for transport packaging, compelling automotive and retail chains to convert fleet bases to foldable formats.
- Automotive logistics corridor concentration:Germany's dense OEM supplier networks generate sustained demand for four-way entry foldable pallets optimized for just-in-sequence assembly line feeds.
- High-pressure injection molding advances:Structural foam processing improvements enable thinner-wall designs without load rating degradation, reducing per-unit polymer consumption and return-trip freight costs simultaneously.
Market Restraints
- Recycled polymer feedstock volatility:Post-industrial polypropylene flake prices fluctuate with packaging waste collection rates, compressing margin stability for compound-dependent producers.
- Tooling capex concentration:Large-tonnage injection molds for 1200x800mm pallet platforms require dedicated capital commitments that lock suppliers into multi-year production cycles with limited flexibility.
- Steel pallet substitution in heavy-load segments:Metal fabrication incumbents retain cost advantages in static loads exceeding 2000kg, constraining plastic foldable penetration in industrial machinery distribution.
Strategic Opportunities
- Perishable agriculture cold chains:Temperature-stable foldable pallets with RFID tracking integration address traceability requirements in seafood and fresh produce export corridors from Spain and the Netherlands.
- CSRD-aligned sustainability reporting:Corporate sustainability reporting directive mandates create procurement preference for pooled asset providers with verified carbon footprint methodologies.
- Automated warehouse convergence:Machine vision compatibility and consistent dimensional tolerances position four-way entry designs for rapid adoption in AS/RS installations across Benelux distribution hubs.
Industry Challenges
- REACH compliance timeline compression:Chemical content verification for recycled polymer feedstocks delays new compound qualification, extending product development cycles by four to six months.
- Asset tracking integration complexity:Embedding IoT sensors into foldable hinge mechanisms requires redesigning stress-bearing components without compromising collapse cycle durability ratings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foldable and Collapsible Pallets Market |
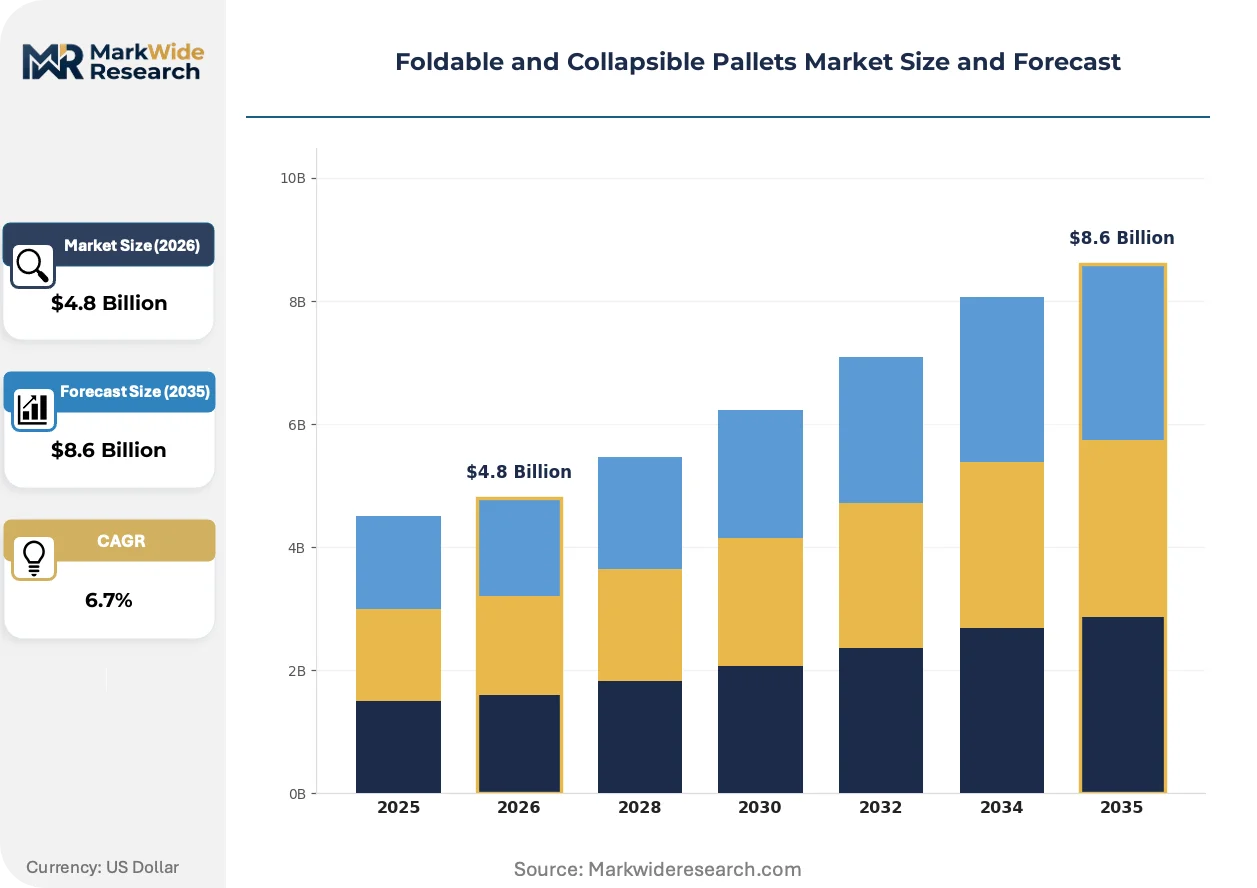
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Pallets, Wooden Pallets, Metal Pallets, Composite Pallets End Use Industry: Retail, Logistics, Agriculture, Manufacturing Design Type: Two-way Entry, Four-way Entry, Stackable, Non-stackable Load Capacity: Light-weight, Medium-duty, Heavy-duty, Custom-duty |
| Companies Covered | Schoeller Allibert, CHEP, ORBIS Corporation, CABKA Group, Nilkamal Limited, Robinson Industries, Justrite Mfg. Co. L.L.C, UltraTech International, Eagle Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foldable and Collapsible Pallets Market Emerging Trajectories
Material science breakthroughs and regulatory compliance automation are converging to reshape foldable pallet specifications, with weight reduction and digital traceability emerging as simultaneous design imperatives rather than trade-offs.
Structural foam polypropylene formulations with glass-fiber reinforcement are miniaturizing wall thicknesses while maintaining dynamic load ratings above 1000kg. Tier-one automotive suppliers in Stuttgart and Wolfsburg are specifying these lightweight platforms for inbound parts logistics. The technology is compressing freight tonnage per empty pallet return by an additional twelve to fifteen percent beyond standard foldable designs.
REACH substance restriction updates through ECHA are mandating full material disclosure for recycled content above thirty percent. Compounders must now submit SCIP database entries for every polymer batch entering EU circulation. Food-contact and pharmaceutical logistics segments are responding fastest, with dedicated audit trails becoming standard contract requirements.
Leasing and pooling contracts are displacing direct equipment purchases among mid-sized retailers managing seasonal inventory surges. Third-party logistics providers in the Netherlands and northern France are consolidating pallet fleet management under single-source agreements with embedded maintenance and compliance certification. This shift is most visible in grocery and electronics distribution, where asset utilization rates and working capital efficiency now dominate procurement scoring.
Foldable and Collapsible Pallets Market Segmentation
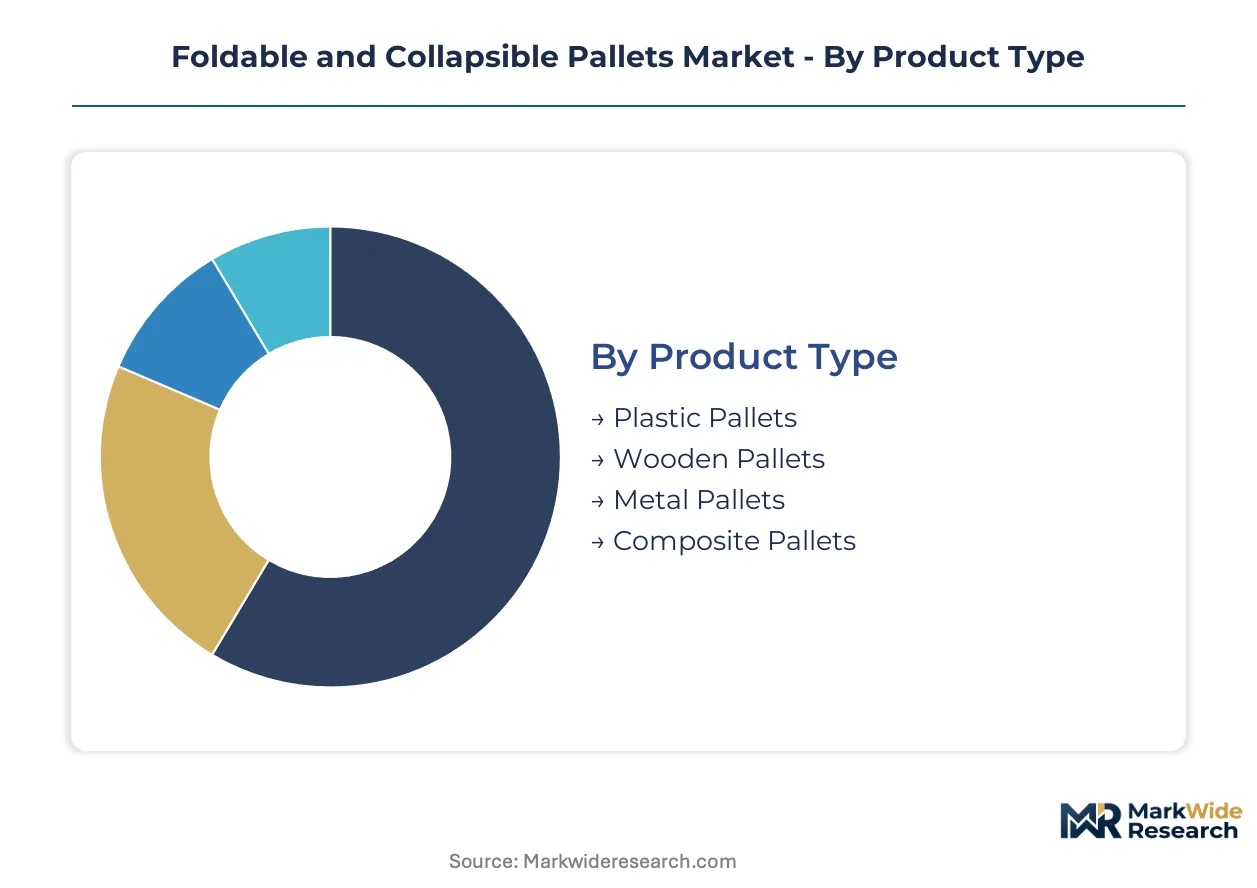
Segmentation in the foldable and collapsible pallets market reveals distinct procurement patterns across material technologies and operational requirements. Manufacturers configure production lines around load capacity tiers and entry design specifications that align with regional logistics infrastructure standards.
Product Type:
Domestic consumption concentrates in plastic and wooden formats across European pooling networks, while metal and composite variants serve specialized export corridors requiring extreme durability or lightweight performance.
- Plastic Pallets:High-pressure injection-molded polypropylene or structural foam construction delivers moisture resistance and dimensional stability for automated warehouse environments. Demand clusters in Germany's automotive logistics corridor and Dutch cold-chain export hubs, driven by EU reusability mandates under the Packaging and Packaging Waste Regulation.
- Wooden Pallets:Engineered timber or plywood platforms with hinged collapse mechanisms offer lower unit costs for single-season retail surges. Procurement concentrates in France and Spain for agricultural produce distribution, constrained by ISPM-15 phytosanitary certification requirements for cross-border shipments.
- Metal Pallets:Steel or aluminum fabrication dominates heavy machinery distribution with static loads exceeding 2000kg.
- Composite Pallets:Hybrid polymer-fiber formulations target aerospace and pharmaceutical logistics requiring electrostatic discharge protection.
Plastic pallets command the established base. The steepest expansion runs through composite formulations.
End Use Industry:
Cost tier differentiation separates capital-intensive pooling contracts from seasonal spot purchases, with premium four-way entry designs capturing automated facilities while economy two-way formats serve manual handling operations.
- Logistics:Third-party providers in the Netherlands and northern France consolidate foldable fleet management under single-source agreements with embedded maintenance protocols. Four-way entry plastic platforms dominate AS/RS installations across Benelux distribution hubs.
- Retail:Grocery and electronics chains deploy collapsible pallets for seasonal inventory surges, favoring leasing models over direct purchase to preserve working capital. RFID-tracked pooling systems from Schoeller Allibert and CABKA Group capture recurring revenue streams.
- Agriculture:Temperature-stable foldable designs with integrated tracking address seafood and fresh produce export requirements from Spain and the Netherlands.
- Manufacturing:Just-in-sequence assembly line feeds in Stuttgart and Wolfsburg specify glass-fiber reinforced structural foam platforms.
Logistics commands the established base. The steepest expansion runs through agriculture cold chains.
Design Type:
Volume concentration in four-way entry formats reflects automated warehouse convergence, while two-way designs retain share in legacy manual operations with limited material handling equipment.
- Four-way Entry:Open deck configurations allow forklift and pallet jack access from all sides, enabling tighter racking density and reduced aisle width requirements. Machine vision compatibility drives specification in German and Dutch automated storage facilities.
- Two-way Entry:Solid deck or stringer designs optimize for unidirectional conveyor systems and lower-cost handling equipment.
- Stackable:Interlocking feet or rim features enable vertical nesting of loaded units, maximizing trailer cube utilization in return-trip logistics.
- Non-stackable:Flat-bottom platforms suit ground-level storage and manual handling operations with minimal infrastructure investment.
Four-way entry commands the established base. The steepest expansion runs through stackable configurations.
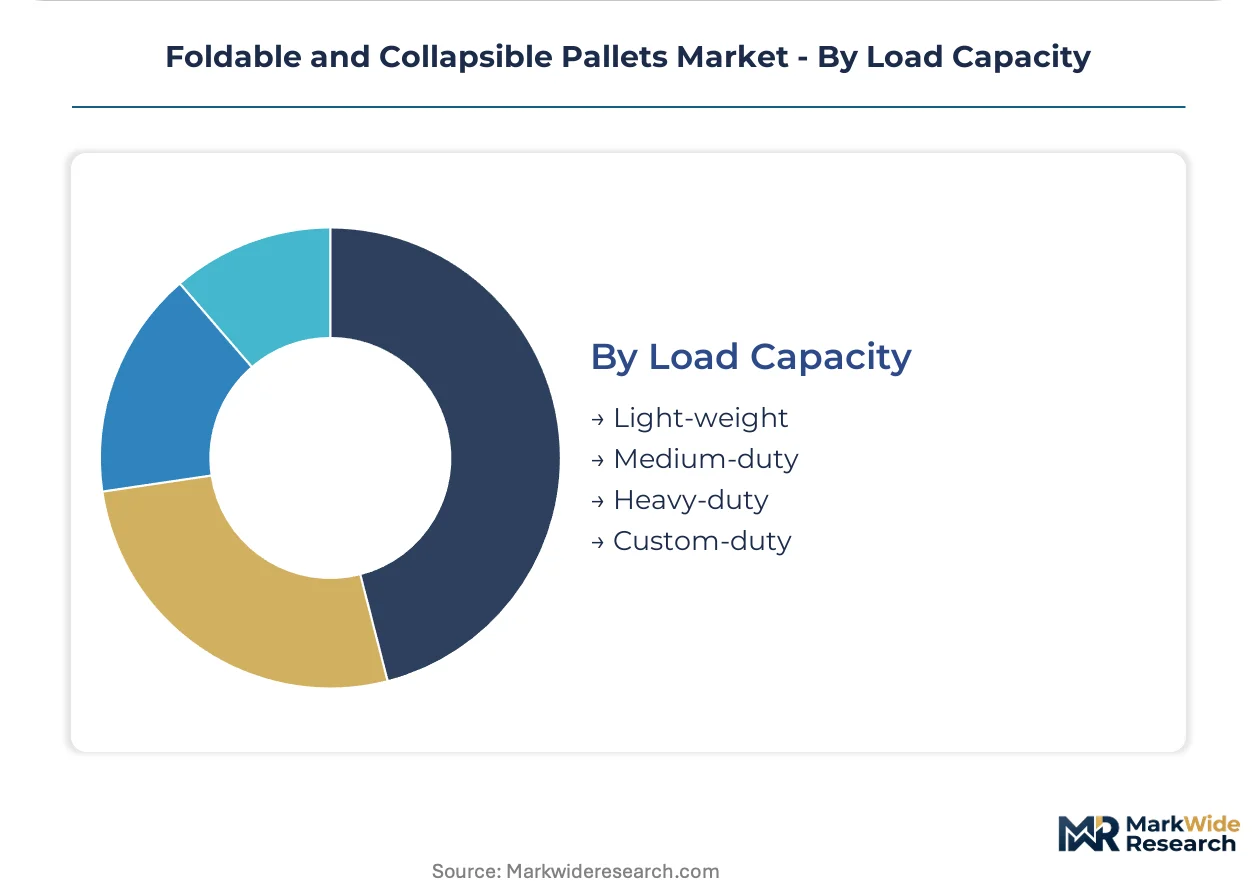
Load Capacity:
Customer type stratification separates automotive OEMs specifying heavy-duty platforms from pharmaceutical distributors requiring lightweight, hygienic formats for cleanroom environments.
- Heavy-duty:Reinforced base structures and thickened wall sections support dynamic loads above 1000kg for industrial machinery and automotive component distribution. German OEM supplier networks generate sustained demand for 1200x800mm Euro-format platforms.
- Medium-duty:Standard wall thickness polypropylene designs serve general merchandise and packaged goods logistics with 500-1000kg ratings.
- Light-weight:Miniaturized structural foam formulations reduce per-unit freight tonnage for air cargo and parcel post applications.
- Custom-duty:Application-specific engineering addresses unique dimensional or load distribution requirements for aerospace and defense contractors.
Medium-duty commands the established base. The steepest expansion runs through heavy-duty specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German automotive buyers absorb premium pricing for precision-engineered platforms, while Spanish agricultural operators prioritize unit economics over feature depth.
Germany
Just-in-sequence assembly feeds at Stuttgart and Wolfsburg OEM plants sustain demand for 1200x800mm Euro-format platforms with glass-fiber reinforcement. The EU Green Deal's extended producer responsibility rules mandate minimum reusability thresholds for transport packaging. Bavaria's automotive supplier corridor concentrates specification authority with tier-one logistics coordinators.
United States
FDA material safety regulations govern pallets contacting food and pharmaceutical products, driving specification divergence from European REACH frameworks. The EPA's emerging sustainable packaging guidelines are reshaping procurement scoring for retail chains. Midwest distribution hubs around Chicago anchor automated warehouse adoption of four-way entry designs.
Netherlands
Third-party logistics providers consolidate foldable fleet management under single-source agreements with embedded maintenance protocols. CSRD-aligned sustainability reporting mandates create procurement preference for pooled asset providers with verified carbon footprint methodologies. Rotterdam's cold-chain export infrastructure drives temperature-stable pallet specification for seafood and fresh produce corridors.
Spain
Agricultural produce distribution concentrates procurement in lower-cost wooden formats with hinged collapse mechanisms for single-season retail surges. ISPM-15 phytosanitary certification requirements constrain cross-border shipment flexibility for timber-based platforms. Valencia's citrus export cooperatives represent the fastest-expanding demand pocket for RFID-tracked pooling systems.
China
Dual carbon goals and MIIT circular economy directives are tightening domestic reusability standards for logistics equipment manufacturers. GB standards for plastic pallet dimensional tolerances diverge from ISO specifications, fragmenting export compatibility. Yangtze River Delta electronics exporters are converting fleet bases to foldable formats for air cargo freight tonnage reduction.
Foldable and Collapsible Pallets Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence between injection-molding and metal-fabrication camps reorganizing competitive tiers. The upper tier commands reusable pooling networks and proprietary compound formulations, while mid-scale fabricators compete on tooling flexibility and regional service density. Two archetypes dominate: large-scale European production network operators and recycled-polymer compound specialists. Competitive moves concentrate on capacity expansion in automotive corridor proximity and technology licensing for structural foam processing improvements.
Within the integrated production network tier, Schoeller Allibert and ORBIS Corporation exemplify divergent geographic anchoring strategies. Schoeller Allibert occupies a position reflecting large-scale European reusable plastic pooling systems. ORBIS Corporation sits within the North American automotive logistics program specialization. CABKA Group represents the recycled-polymer compound archetype, with positioning derived from proprietary feedstock cost advantages.
| Leading Market Players |
|---|
| Schoeller Allibert |
| CHEP |
| ORBIS Corporation |
| CABKA Group |
| Nilkamal Limited |
| Robinson Industries |
| Justrite Mfg. Co. L.L.C |
| UltraTech International |
| Eagle Manufacturing Company |
| Others |
Supply Flow & Price Mechanics
Long-term pooling contracts with embedded maintenance clauses lock in supply access for logistics operators while anchoring price visibility across multi-year fleet depreciation schedules. These arrangements concentrate procurement power with Schoeller Allibert and CABKA Group in Germany and the Netherlands, compressing spot-market flexibility for mid-scale retailers.
Pricing Analysis
After-sales revenue from embedded RFID tracking and compliance certification drives lifetime value beyond per-unit pallet sales. Leasing models with usage-based tiers separate premium pooled assets from standard purchase options and economy spot rentals. Pricing pressure stems from recycled polypropylene feedstock volatility, which squeezes compound-dependent producers when packaging waste collection rates fluctuate. Automotive OEMs in Stuttgart show least price sensitivity, prioritizing load rating precision and dimensional tolerance over unit economics.
Supply Chain Analysis
Strategic stockpiling of post-industrial polymer flake dominates over just-in-time raw material flows, given REACH compliance delays that extend compound qualification cycles. Manufacturing concentrates in Germany, the Netherlands, and China, with injection-molding capacity clustering near automotive corridors and export logistics hubs. Supply chains draw from virgin polypropylene suppliers and post-consumer waste aggregators simultaneously. Single-source vulnerability runs through specialized large-tonnage mold fabrication, where limited European toolmakers constrain capacity expansion timelines. Distribution feeds through third-party logistics providers consolidating fleet management under single-source agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarce expertise in structural foam processing with glass-fiber reinforcement is concentrating margin capture among integrated compounders with captive R&D facilities, leaving pure-play molders exposed to commodity polymer cycles.
For Market Incumbents: Shield market position by deepening backward integration into recycled polymer compounding to offset feedstock volatility, and expand capacity within 150 kilometers of Stuttgart and Wolfsburg assembly corridors. The priority lever sits with proprietary formulation IP that locks automotive OEMs into multi-year platform specifications. For New Entrants and Emerging Players: Differentiate on temperature-stable designs with integrated IoT tracking for Spanish and Dutch perishable agriculture exporters, where pooling penetration remains shallow and compliance audit trails command premium positioning. Target Valencia citrus cooperatives and Rotterdam seafood distributors with lease-to-own structures that transfer asset ownership after depreciation. For Investors and Strategic Acquirers: Capital is best deployed toward compound specialists with verified SCIP database workflows and established ECHA pre-registration pathways, as REACH timeline compression extends qualification moats. The inflection signal to monitor is EU Green Deal extended producer responsibility enforcement intensity, which accelerates closed-loop pooling conversion rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Polymer Compounding | CABKA Group's proprietary formulations demonstrate margin protection against post-industrial flake price swings. |
| Capacity Expansion in Automotive Corridor Proximity | ORBIS Corporation's Midwest positioning captures FDA-regulated food and pharmaceutical logistics demand. |
| RFID Tracking and Compliance Certification Bundling | Schoeller Allibert's embedded audit trails satisfy CSRD-aligned sustainability reporting mandates. |
| Structural Foam Processing Technology Licensing | Thin-wall design improvements reduce return-trip freight tonnage for Benelux distribution hubs. |
| Long-Term Pooling Contract Consolidation | Single-source agreements with embedded maintenance displace direct equipment purchases among seasonal retailers. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, encompassing logistics procurement directors at German automotive OEMs, pooling fleet managers at Dutch third-party providers, compound R&D leads at recycled-polymer specialists, and aftermarket service heads at plastic pallet fabricators. Secondary validation drew from ECHA SCIP database disclosures, EU Packaging and Packaging Waste Regulation implementation timelines, customs trade data for polypropylene flake movements, and SEC filings of listed pooling operators. Bottom-up unit economics and top-down sector sizing were triangulated against production capacity disclosures.
Across the analysis window, forecasts were constructed by modeling load capacity tiers, material technology segments, entry design specifications, and end-use industry adoption curves. CAGRs were derived from segment-level volume trajectories weighted by regional regulatory enforcement intensity. Industry-specific inputs included automotive production schedules for Stuttgart and Wolfsburg assembly plants, and cold-chain export volumes through Rotterdam and Valencia corridors.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or stable recycled polymer feedstock availability would require recalibration. Forecasts reflect assumptions regarding REACH compliance timeline adherence and pooling contract renewal rates. Revision becomes warranted when ECHA substance restriction updates accelerate beyond current four-to-six month qualification cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Wire Cage Pallet Collar Market
Pallets Packaging
Italy Pallets Market
Pallets Packaging
UK Pallets Market
Pallets Packaging
Single Use Pallet Market
Pallets Packaging
Empty Fruit Bunch Pallets Market
Pallets Packaging
Paper Pallet Market
Pallets Packaging
Pallet Packaging Market
Pallets Packaging
China Pallets Market
Pallets Packaging
Pallet Pooling Market
Pallets Packaging
Spill Pallets Market
Pallets Packaging
Pallet Displays Market
Pallets Packaging
Pallet Boxes Market
Pallets Packaging
Wooden Pallets Market
Pallets Packaging
Europe Pallet Market
Pallets Packaging
Mexico Pallets Market
Pallets Packaging
Pallet Wraps Market