

Port-to-Door Container Journey Orchestration Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Port-to-Door Container Journey Orchestration Platforms Market Insights
Multi-source visibility procurement is broadening as enterprises abandon single-carrier tracking systems. project44 leverages API-first architecture to sustain real-time data density across ocean and rail modes. FourKites anchors North American intermodal coverage with sensor networks spanning drayage and over-the-road segments. e2open competes through backward integration into customs filing and trade compliance software.
Port-to-Door Container Journey Orchestration Platforms are cloud-native software systems that aggregate telemetry from vessel AIS transponders, container RFID tags, and GPS-enabled chassis to generate unified ETAs and exception alerts across modal handoffs. Their primary commercial purpose is eliminating information latency between maritime terminals and consignee dock doors. Cloud-Based deployment dominates current infrastructure spending as freight forwarders replace on-premise legacy stacks. AI Analytics capabilities represent the fastest-expanding technology segment, with predictive arrival algorithms now standard in tender optimization workflows. Last-Mile Delivery use cases command premium pricing due to the density of stakeholder handoffs and penalty exposure.
The EU Green Deal and its delegated emissions reporting acts compel platform vendors to embed carbon accounting modules directly into journey records. The Federal Maritime Commission's interpretive rules on detention and demurrage billing transparency in the United States are reshaping data retention and audit trail specifications for cross-Pacific trade lanes. Stakeholders must weigh the trade-off between vertical integration of compliance tools and interoperability with carrier-native portals as regulatory fragmentation deepens across trading blocs.
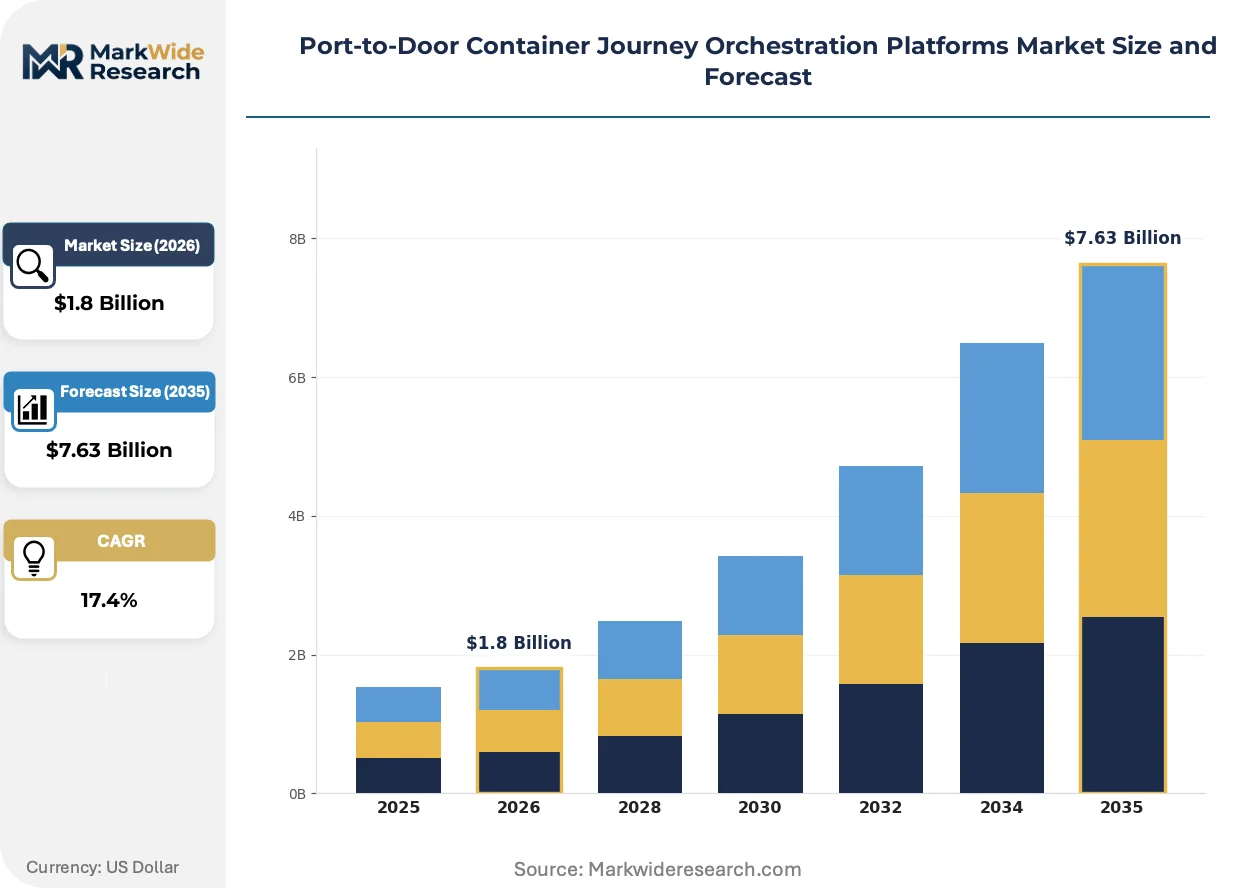
Market Dynamics
The Port-to-Door Container Journey Orchestration Platforms Market is being fundamentally restructured by regulatory mandates on emissions transparency, which force freight forwarders to replace fragmented carrier portals with unified data layers that can audit carbon across modal handoffs.
Growth Catalysts
- EU Green Deal delegated acts:Mandatory emissions reporting for maritime and road transport is compelling shippers to adopt platforms with embedded carbon accounting modules that automate audit trails across the Hamburg-Rotterdam corridor.
- Third-party logistics provider consolidation:Large 3PLs are unifying visibility across acquired regional networks, creating procurement pull for API-first orchestration layers that normalize data from disparate carrier systems.
- RFID-GPS sensor fusion:Container-mounted telemetry devices now transmit location, temperature, and shock data through cellular and satellite networks, enabling real-time exception management at rail yards and inland depots.
Market Restraints
- Cloud infrastructure cost concentration:Hyperscaler bandwidth and storage pricing volatility in European data centers compresses margins for platform vendors serving mid-sized freight forwarders.
- Carrier data sovereignty resistance:Ocean carriers in Asia-Pacific markets restrict API access to container status, preserving information asymmetry that limits third-party platform accuracy on trans-Pacific lanes.
- Legacy EDI protocol entrenchment:ANSI X12 and EDIFACT message standards still dominate port community systems, creating translation overhead that delays real-time telemetry ingestion.
Strategic Opportunities
- Indian port modernization:Jawaharlal Nehru Port and Mundra Port are digitizing customs clearance and terminal operations, creating first-mover advantage for platforms that integrate with the country's national logistics portal.
- Predictive detention pricing:Machine learning models that forecast demurrage exposure based on vessel schedule reliability are enabling new subscription tiers for beneficial cargo owners with high penalty risk.
- Blockchain-IoT convergence:Distributed ledger architectures that immutably record container handoff events are attracting investment from commodity traders requiring tamper-proof custody documentation.
Industry Challenges
- Maritime data science talent scarcity:Platforms struggle to hire engineers with combined expertise in AIS signal processing, stochastic optimization, and international trade documentation workflows.
- Multi-modal integration complexity:Synchronizing vessel ETAs with rail drayage dispatch requires harmonizing incompatible data frequencies across ocean carrier schedules, terminal operating systems, and chassis pool managers.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Port-to-Door Container Journey Orchestration Platforms Market Trends and Innovations
Telemetry fusion and predictive algorithm deployment are compressing information latency between maritime terminals and consignee facilities, while regulatory pressure on emissions documentation accelerates platform replacement cycles.
Digital twin architectures for container journeys are absorbing historical voyage data, weather patterns, and terminal congestion signals to simulate arrival windows before vessels berth. Large beneficial cargo owners in chemicals and automotive verticals are deploying these simulations to pre-position chassis and warehouse labor. This capability is absorbing the planning function previously performed by manual spreadsheet-based ETA tracking, compressing staff hours per shipment.
The EU Green Deal's delegated act on monitoring and reporting CO2 emissions from maritime transport is mandating granular fuel consumption data collection from vessels calling at European ports. Platform vendors must now integrate automatic identification system messages with noon reports and bunker delivery notes to generate verified emissions statements. Container lines serving the Asia-Europe trade are responding by pre-certifying data feeds for third-party platform ingestion.
Beneficial cargo owners are consolidating vendor relationships around platforms that bundle ocean visibility with customs filing and trade compliance functions. Mid-sized freight forwarders in Germany and the Netherlands are displacing point solutions that handled only single modes or trade lanes. This consolidation is most visible among shippers managing apparel and electronics supply chains originating in Vietnam and Bangladesh.
Port-to-Door Container Journey Orchestration Platforms Market Segmentation
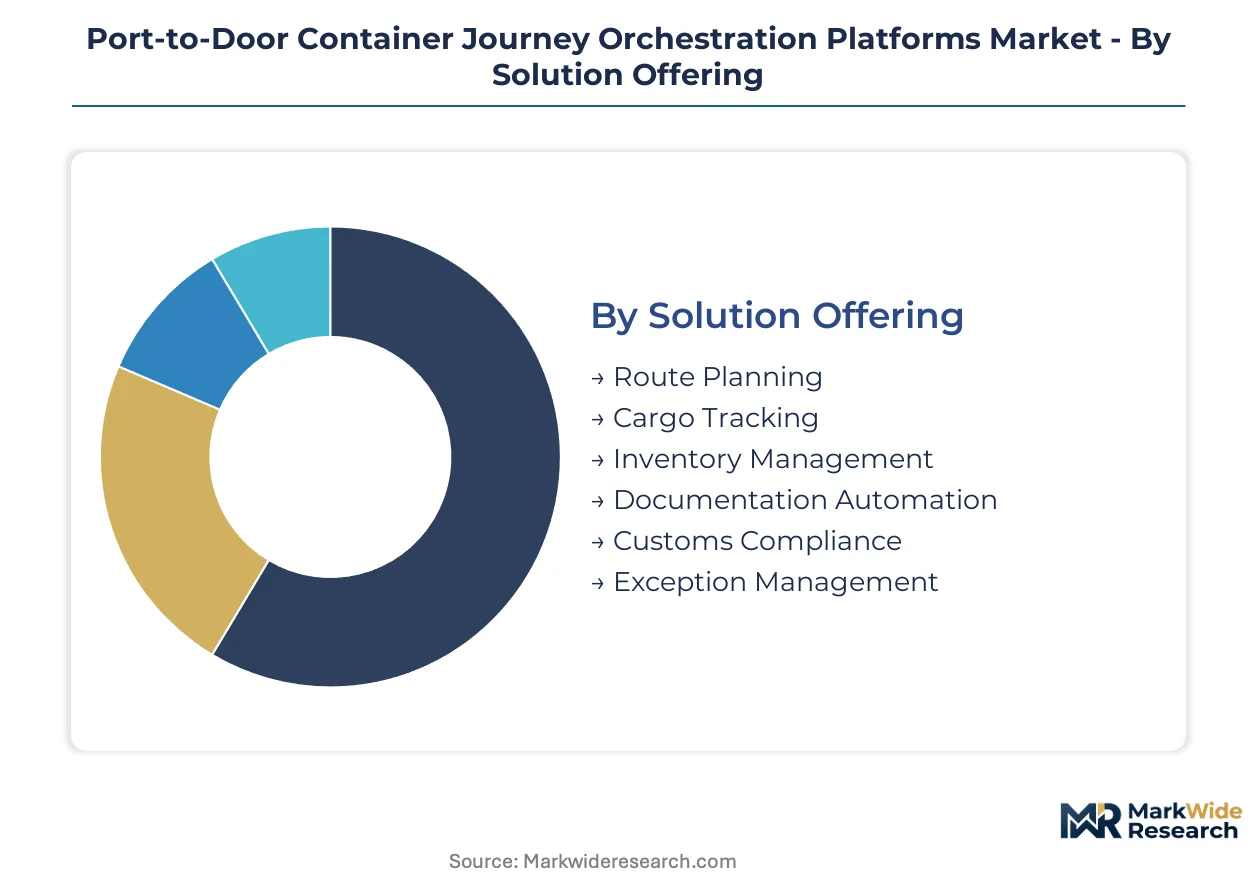
Segmentation in container journey orchestration reveals how procurement decisions cluster around compliance automation, sensor density requirements, and modal complexity. Buyers select solution bundles based on whether their cargo flows trigger EU Green Deal reporting, US FMC detention rules, or customs pre-clearance mandates.
Solution Offering:
EU Green Deal emissions audits and US FMC detention transparency rules impose distinct certification burdens: carbon accounting modules require MRV (Monitoring, Reporting, Verification) compliance, while billing automation demands audit-trail standards for dispute resolution.
- Route Planning:Algorithms synthesize vessel AIS signals, rail schedules, and chassis availability to generate dynamic ETAs across modal handoffs. Demand concentrates among German automotive shippers navigating Hamburg-Rotterdam corridor congestion, driven by just-in-time assembly line penalties.
- Cargo Tracking:Multi-source telemetry fusion from RFID tags, GPS chassis, and cellular sensors delivers unified location intelligence. Third-party logistics providers in the Netherlands deploy these systems to unify visibility across acquired regional networks, constrained by carrier API access restrictions in Asia-Pacific lanes.
- Inventory Management:Yard and depot stock-level monitoring tied to vessel discharge sequences.
- Documentation Automation:Trade document digitization including bills of lading and customs declarations.
- Customs Compliance:Automated filing with national logistics portals and pre-arrival clearance systems.
- Exception Management:Alert engines for detention risk, temperature excursions, and schedule deviations.
Leading the category by volume: Cargo Tracking. Growing fastest: Route Planning.
Technology:
Deployment architecture determines infrastructure cost exposure and data sovereignty compliance, with cloud-native stacks replacing on-premise legacy systems among mid-sized freight forwarders.
- Cloud-Based:Scalable compute resources for real-time telemetry ingestion and predictive analytics. Freight forwarders in Germany and the Netherlands dominate procurement, replacing legacy EDI stacks to meet EU data localization requirements under GDPR and CSRD.
- AI Analytics:Machine learning models forecasting vessel reliability, demurrage exposure, and optimal tender timing. Beneficial cargo owners in chemicals and automotive verticals absorb these capabilities to pre-position chassis and warehouse labor, constrained by scarcity of engineers combining AIS signal processing with trade documentation expertise.
- IoT Integration:Sensor fusion from container-mounted devices transmitting location, temperature, and shock data.
- Blockchain:Distributed ledger architectures for immutable custody documentation.
- Machine Learning:Pattern recognition for schedule reliability and congestion prediction.
- Mobile Application:Driver and dispatcher interfaces for exception reporting and proof-of-delivery capture.
Cloud-Based deployments anchor current infrastructure spending. AI Analytics capabilities are expanding most quickly as predictive arrival algorithms become standard in tender optimization workflows.
Use Case:
Pricing premiums align with stakeholder handoff density and penalty exposure, with last-mile segments commanding higher subscription tiers due to detention and demurrage risk concentration.
- Last-Mile Delivery:Final-leg coordination spanning drayage dispatch, chassis pool management, and consignee dock scheduling. US beneficial cargo owners facing Federal Maritime Commission billing transparency mandates drive adoption, pressured by demurrage penalties at Los Angeles and Long Beach terminals.
- Real-Time Visibility:Unified dashboards aggregating ocean, rail, and road telemetry for exception management. Large 3PLs consolidating acquired networks deploy these systems across the Hamburg-Rotterdam corridor, constrained by legacy EDI protocol entrenchment in port community systems.
- Cross-Dock Optimization:Synchronized inbound and outbound freight flows at inland terminals.
- Automated Billing:Detention and demurrage calculation with audit-trail documentation.
- Predictive Maintenance:Container and chassis condition monitoring to prevent in-service failures.
- Supply Chain Coordination:Multi-stakeholder workflow management across forwarders, carriers, and customs brokers.
Last-Mile Delivery commands premium pricing. Real-Time Visibility is gaining share fastest as multi-source procurement displaces single-carrier tracking systems.
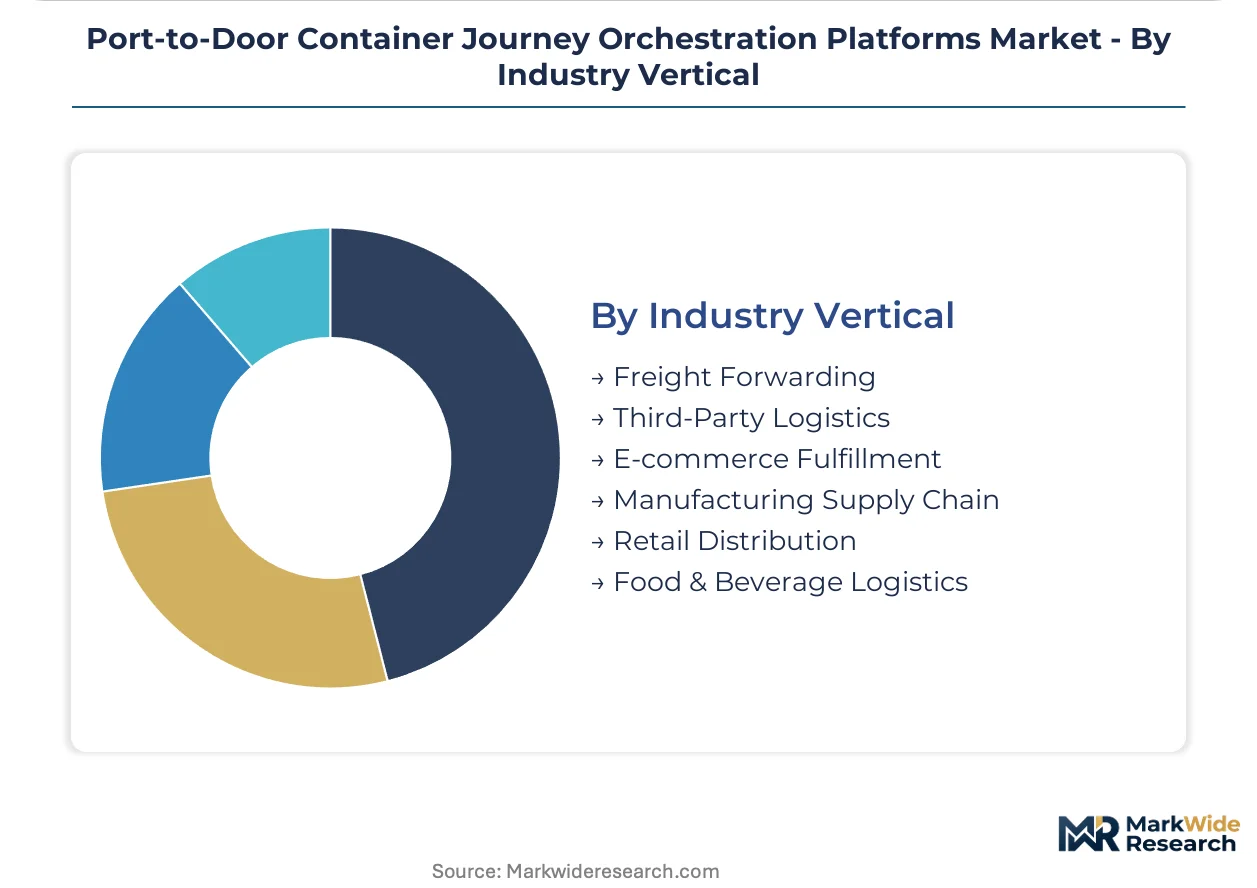
Industry Vertical:
Vertical selection hinges on shipment volume predictability, regulatory touchpoint density, and tolerance for information latency.
- Third-Party Logistics:Unified visibility platforms spanning acquired regional networks and disparate carrier systems. Large 3PLs in Germany and the Netherlands consolidate procurement around API-first orchestration layers, driven by network unification post-acquisition.
- Freight Forwarding:End-to-end journey management with customs filing and trade compliance bundling. Mid-sized forwarders in Vietnam and Bangladesh trade lanes displace point solutions, constrained by cloud infrastructure cost volatility in European data centers.
- E-commerce Fulfillment:High-velocity inventory positioning with consumer delivery promise management.
- Manufacturing Supply Chain:Just-in-time component flows with assembly line synchronization.
- Retail Distribution:Seasonal volume surge handling with store-level allocation.
- Food & Beverage Logistics:Temperature-controlled cargo with cold chain integrity documentation.
Third-Party Logistics leads vertical deployment by platform volume. Freight Forwarding is climbing the fastest as mid-sized players consolidate vendor relationships around bundled solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, where Hamburg and Rotterdam corridor traffic drives platform deployment for automotive and chemicals shippers navigating just-in-time assembly penalties.
Germany
Automotive manufacturers in Stuttgart and Wolfsburg anchor demand for predictive arrival algorithms that synchronize component flows with assembly line schedules. The EU Green Deal's delegated act on maritime emissions reporting compels platforms to integrate MRV-compliant carbon accounting modules. Hamburg's container terminals and the Rhine-Alpine rail corridor generate dense telemetry requirements for real-time exception management.
United States
Beneficial cargo owners facing demurrage exposure at Los Angeles and Long Beach terminals drive adoption of detention forecasting tools. The Federal Maritime Commission's interpretive rules on billing transparency reshape data retention specifications for cross-Pacific trade lanes. Chicago's intermodal rail hubs and the drayage networks of Southern California concentrate deployment of sensor-fusion tracking systems.
Netherlands
Third-party logistics providers in Rotterdam unify visibility across acquired regional networks, creating procurement pull for API-first orchestration layers. GDPR and CSRD data localization requirements push freight forwarders toward cloud-native stacks hosted in European data centers. The port of Rotterdam and its inland barge connections to the German industrial heartland generate multi-modal integration complexity.
India
Jawaharlal Nehru Port and Mundra Port digitization programs create first-mover advantage for platforms integrating with the national logistics portal. The country's central logistics regulator mandates pre-arrival customs clearance data standards that favor unified journey orchestration over fragmented point solutions. Maharashtra's manufacturing clusters and Gujarat's port infrastructure concentrate early deployment of container-mounted telemetry devices.
China
Dual carbon goals from the Ministry of Ecology and Environment pressure exporters to document emissions across the Asia-Europe trade lane. Ningbo-Zhoushan and Shanghai container terminals generate vessel AIS signal density that feeds predictive algorithm training. Yangtze River Delta manufacturers demand synchronized ETAs to pre-position warehouse labor and chassis pools.
Port-to-Door Container Journey Orchestration Platforms Market Competitive Landscape
API-first architecture acquisition dominates the current landscape as established logistics software vendors absorb specialized visibility providers to unify data layers across modal handoffs. The vendor base stratifies between cloud-native challengers with sensor network density and incumbent enterprise suites with customs filing integration. Two archetypes prevail: telemetry-heavy platforms anchored in North American intermodal coverage, and trade-compliance bundlers with backward integration into documentation workflows. M&A activity and geographic expansion through carrier API partnerships constitute the primary competitive vectors.
Within the API-native tier, project44 and FourKites exemplify contrasting geographic anchoring strategies—project44 sustaining real-time data density across ocean and rail modes, FourKites concentrating sensor networks on drayage and over-the-road segments. e2open occupies a position representing the compliance-bundler archetype, with backward integration into customs filing software distinguishing its procurement appeal for mid-sized freight forwarders consolidating vendor relationships.
| Leading Market Players |
|---|
| project44 |
| FourKites |
| e2open |
| IBM |
| Oracle |
| SAP |
| Manhattan Associates |
| Kinaxis |
| Blue Yonder |
| Others |
Pricing and Supply Chain Analysis
Hyperscaler bandwidth pricing in European data centers cascades through cloud-native platform tiers, compressing margins for vendors serving mid-sized freight forwarders while premium AI Analytics modules absorb cost pass-through at large beneficial cargo owners.
Pricing Analysis
Volume concentrates in standardized Cargo Tracking subscriptions while margin pools in AI Analytics and Last-Mile Delivery tiers. Price differentiation hinges on MRV compliance certification for EU Green Deal reporting and sensor density coverage across modal handoffs. Pricing pressure intensifies in Cloud-Based deployments as hyperscaler storage volatility feeds through to mid-market freight forwarders. Small forwarders in Vietnam and Bangladesh trade lanes exhibit highest price sensitivity; automotive shippers in Germany absorbing predictive algorithm bundles show lowest.
Supply Chain Analysis
Maritime data science talent scarcity in Germany and the Netherlands constrains platform engineering capacity, forcing vendors to source AIS signal processing expertise from Singapore and Shanghai satellite analytics clusters. Cloud infrastructure draws from hyperscaler regions in Frankfurt, Amsterdam, and Dublin, while container-mounted telemetry devices feed from Shenzhen and Taipei sensor manufacturing bases. Single-source vulnerability concentrates in Asia-Pacific carrier API access restrictions. Distribution runs through API-first integration layers sold direct to large 3PLs and via channel partners to mid-sized forwarders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container journey orchestration sits in a forced transition from EDI protocol stacks to API-native telemetry fusion, with RFID-GPS sensor convergence displacing legacy ANSI X12 message standards.
For Market Incumbents: Deepen backward integration into customs filing software to match e2open's trade compliance bundling, defending against displacement by mid-sized freight forwarders consolidating vendor relationships. Fortify sensor network density across the Hamburg-Rotterdam corridor to preserve premium positioning against cloud-native challengers. Anchor capacity in GDPR-compliant European data centers to preempt regulatory fragmentation costs. For New Entrants and Emerging Players: Enter via Jawaharlal Nehru Port and Mundra Port digitization programs, where national logistics portal integration creates first-mover whitespace absent entrenched incumbents. Target Indian manufacturing clusters in Maharashtra and Gujarat with container-mounted telemetry bundles priced below established API-first platforms. Lead with blockchain-IoT custody documentation for commodity traders requiring tamper-proof handoff records. For Investors and Strategic Acquirers: Carrier pre-certification of data feeds for third-party platform ingestion is the leading indicator that EU Green Deal MRV compliance has shifted from cost center to competitive moat. Long-term viability favors vendors combining ocean visibility with customs filing integration. Monitor detention and demurrage billing transparency rulemaking by the Federal Maritime Commission as inflection signal for US market platform replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Unifies telemetry from Hamburg-Rotterdam corridor rail yards with ocean carrier schedules. |
| Carbon Accounting Module Launch | Automates EU Green Deal MRV audit trails for maritime emissions reporting mandates. |
| Sensor Network Geographic Expansion | Densifies RFID-GPS coverage across Los Angeles and Long Beach drayage networks. |
| Acquisition of Customs Filing Specialist | Backward integration into trade compliance software matches e2open's bundling appeal. |
| Predictive Detention Pricing Tier | Machine learning demurrage forecasting targets beneficial cargo owners at penalty-risk terminals. |
Research Methodology
Multi-period observation of vessel AIS signal density, carrier API access policies, and port terminal digitization timelines anchored the trend analysis, supplemented by interviews with freight forwarder procurement directors, third-party logistics network operations managers, maritime terminal systems engineers, and customs brokerage technology leads. Secondary validation drew from Federal Maritime Commission interpretive rule filings, EU delegated acts on emissions monitoring, national logistics portal technical specifications in India, and customs/trade data from Hamburg and Rotterdam port authorities. Bottom-up platform deployment estimates triangulated against top-down logistics software spending benchmarks.
The input-output matrix framed demand drivers across solution offering, technology architecture, use case intensity, and industry vertical adoption patterns. Segmentation dimensions modeled encompass deployment model, organization scale, modal complexity, and regional regulatory cluster. CAGRs derived from slope analysis of platform procurement trajectories against infrastructure spending cycles. Forecast inputs incorporated hyperscaler pricing volatility indices and carrier API access restriction frequency by trade lane.
Forecast precision tightens around the base case; tail outcomes carry wider variance under carrier data sovereignty resistance intensification or legacy EDI protocol entrenchment in Asian port community systems. Material deviation in EU Green Deal enforcement timing or Federal Maritime Commission rule finalization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.