
 Storage Dewar and Dry Shipper Market | 2026-2036
Storage Dewar and Dry Shipper Market Size, Share, and Industry Trends Forecast 2026-2036
Storage Dewar and Dry Shipper Market Analytics
Advanced vacuum insulation technology is reshaping how cryogenic vessels achieve extended hold times and reduced evaporative losses. Thermo Fisher Scientific leverages its global service network to sustain leadership in biological sample transport solutions. Worthington Industries anchors North American manufacturing capacity through specialized stainless steel fabrication capabilities. Haier Biomedical competes aggressively on cost-engineered dry shippers for emerging market laboratories.
Storage dewars and dry shippers are double-walled vacuum-insulated vessels designed to contain cryogenic fluids or maintain sub-zero temperatures for biological specimens, typically constructed with stainless steel inner chambers and multi-layer insulation achieving thermal retention measured in weeks rather than days. Their primary purpose centers on preserving cell lines, tissues, and pharmaceutical materials across research, clinical, and industrial workflows. Liquid nitrogen dewars command the largest installed base among product types due to universal laboratory dependency on passive cryogenic storage. Dry shippers represent the fastest-expanding category as air freight regulations tighten around hazardous materials transport. Biological sample storage applications generate the deepest margin pools given compliance burdens and recurring consumable attachment.
The FDA enforces 21 CFR Part 11 validation requirements for temperature-critical biological shipments, while EMA's Good Distribution Practice guidelines mandate continuous monitoring documentation across European cold chains. ISO 20387 biobanking standards and IATA Dangerous Goods Regulations collectively shape product design specifications and market access thresholds for manufacturers. Stakeholders must monitor evolving pharmacopeial temperature mapping requirements and assess regional certification gaps before committing to capacity expansion.
Market Dynamics
Vacuum insulation technology maturation is compressing hold-time differentials between premium and standard-grade vessels, forcing manufacturers to compete on validation documentation and service attach rates rather than raw thermal performance.
Growth Catalysts
- EMA Good Distribution Practice mandates:European pharmaceutical logistics now require continuous temperature monitoring documentation for biological shipments, expanding the addressable market for validated dry shippers.
- Cell and gene therapy manufacturing scale-up:Commercial production of CAR-T therapies and viral vectors requires cryogenic preservation at multiple supply chain nodes, from apheresis collection to final patient administration.
- Stainless steel multi-layer insulation:Advanced fabrication techniques are extending passive hold times beyond 21 days, opening air freight routes previously restricted by IATA time limitations.
Market Restraints
- Liquid helium supply concentration:Qatar and the United States control over 80% of global helium refining capacity, exposing superconducting magnet users to price volatility and allocation risk.
- FDA 21 CFR Part 11 validation costs:Electronic records compliance for temperature-critical shipments adds $15,000-$50,000 per qualification protocol, creating barriers for small research laboratories.
- Mechanical refrigeration substitution:Stirling engine-based portable freezers achieving -80°C without cryogenic fluids are capturing specimen transport applications where hold times exceed 72 hours.
Strategic Opportunities
- India biobanking infrastructure:The country's national cancer grid and stem cell registry expansion creates demand for cost-engineered dry shippers compliant with CDSCO import regulations.
- Carbon composite vessel technology:Glass-fiber reinforced epoxy dewars are reducing weight by 40% compared to stainless steel, enabling drone-based last-mile delivery of temperature-critical specimens.
- ISO 20387 biobank certification wave:Quality management system mandates across European research infrastructures are triggering replacement cycles for non-validated legacy storage equipment.
Industry Challenges
- Cryogenic safety technician scarcity:Qualified personnel for liquid nitrogen handling and vessel maintenance are concentrated in established pharmaceutical clusters, constraining field service expansion.
- Multi-modal validation complexity:Demonstrating thermal stability across truck-to-airport-to-airport-to-truck handoffs requires sensor integration and data continuity protocols that differ by carrier and jurisdiction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Storage Dewar and Dry Shipper Market |
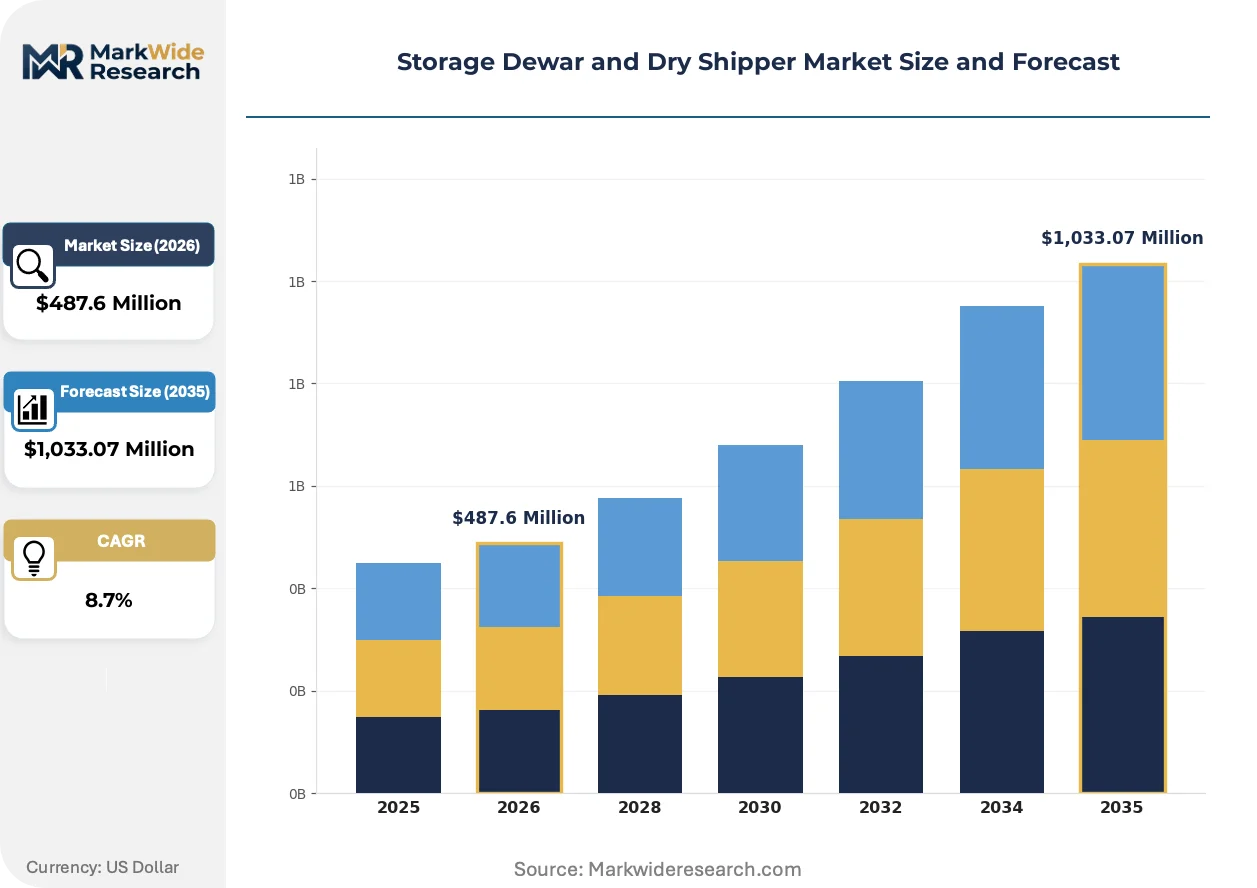
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Nitrogen Dewar, Dry Shipper, Cryogenic Storage Tank, Insulated Container End User: Research Laboratories, Healthcare Facilities, Biotechnology Companies, Educational Institutions Application: Biological Sample Storage, Cryopreservation, Industrial Manufacturing, Aerospace Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | VWR International, LLC, Statebourne Cryogenics Ltd, Worthington Industries, Wessington Cryogenics, Taylor-Wharton, Thermo Fisher Scientific, Cole-Parmer Instrument Company, LLC, Haier Biomedical, Air Products and Chemicals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Storage Dewar and Dry Shipper Market Evolving Landscape
Passive thermal protection systems are converging with active monitoring and cloud-based chain-of-custody documentation, transforming cryogenic vessels from commodity hardware into compliance-enabling platforms.
Multi-layer vacuum super insulation incorporating aerogel composite barriers is rendering obsolete traditional perlite-filled dewar designs for transport applications exceeding 14 days. Gene therapy contract manufacturers are specifying aerogel-based shippers for intercontinental viral vector movements. The technology is compressing the premium tier pricing umbrella by eliminating the hold-time advantage previously commanded by specialized European fabricators.
REACH regulation amendments restricting perfluorinated compounds are forcing reformulation of vacuum jacket sealants and valve packing materials used in cryogenic vessel manufacturing. ECHA substance evaluation has flagged specific fluoropolymers for authorization listing, compelling suppliers to qualify hydrocarbon-based alternatives. European OEMs are accelerating validation of new sealant chemistries ahead of anticipated sunset dates, with German and Swiss manufacturers leading qualification timelines.
Biopharmaceutical procurement teams are consolidating vendor panels around full-service cold chain partners capable of providing vessels, monitoring hardware, and compliance documentation through single contracts. This behavior is displacing the historical model of separate procurement for hardware, logistics, and quality assurance functions. The shift is most visible among mid-cap gene therapy developers in the Boston and San Diego clusters, where capital efficiency priorities favor operational expenditure structures over vessel ownership.
Storage Dewar and Dry Shipper Market Segmentation
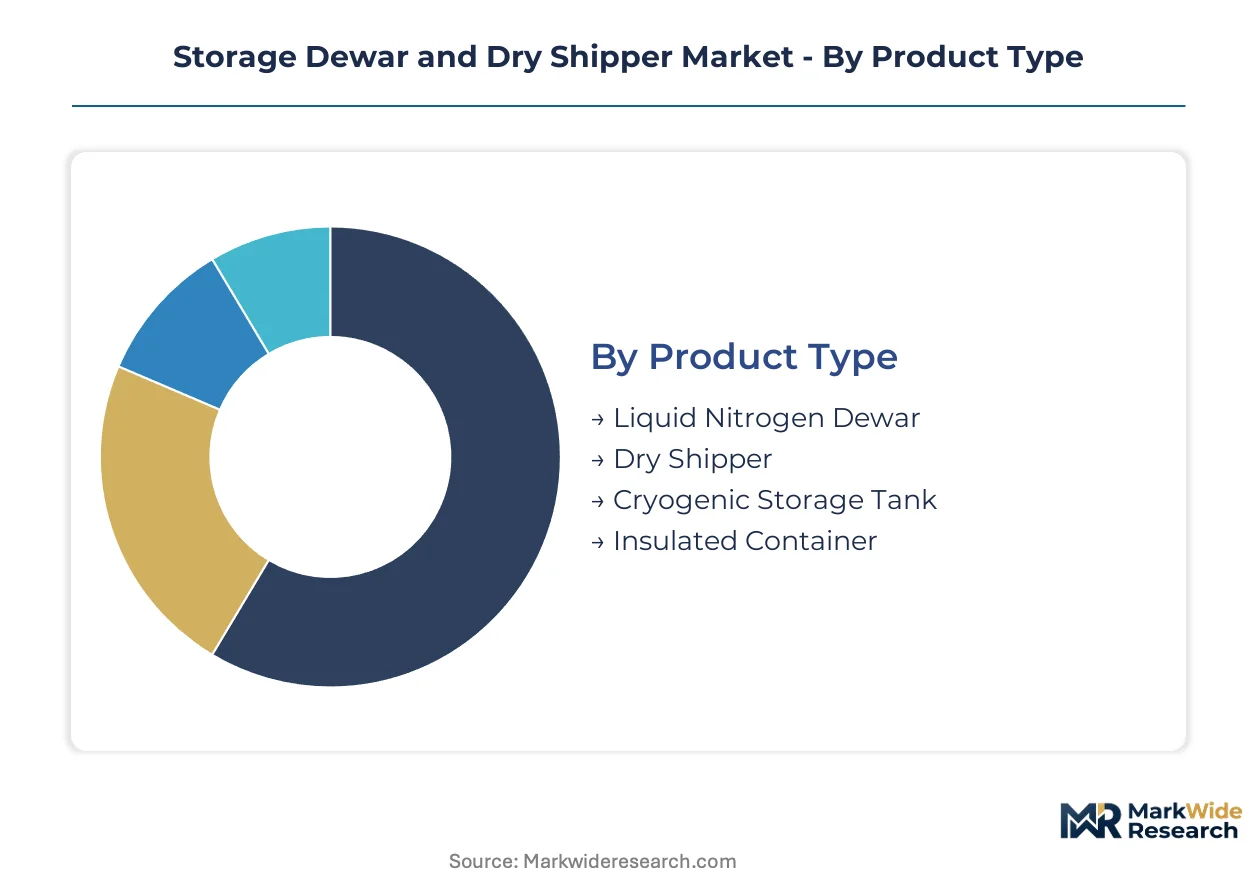
Cryogenic vessel segmentation reflects divergent performance requirements across passive storage versus active transport workflows. Product architecture, end-user compliance burdens, and application-specific hold-time demands create distinct margin profiles and competitive dynamics within each category.
Product Type:
Mature vacuum insulation platforms dominate installed base volumes while emerging aerogel-composite designs reshape transport economics.
- Liquid Nitrogen Dewar:Double-walled stainless steel vessels with multi-layer vacuum insulation achieve passive thermal retention measured in weeks. Universal laboratory dependency on cryogenic storage for cell line preservation sustains demand concentration across United States, Germany, and Chinese research clusters.
- Dry Shipper:Absorbent material-filled vessels maintain sub-zero temperatures without free liquid nitrogen, enabling hazardous materials-compliant air freight. IATA Dangerous Goods Regulations tightening around biological transport is accelerating replacement of traditional dewars in pharmaceutical logistics networks.
- Cryogenic Storage Tank:Stationary bulk vessels with capacities exceeding 1,000 liters serve manufacturing-scale liquid nitrogen supply. Industrial gas distributors anchor procurement in mature pharmaceutical manufacturing regions.
- Insulated Container:Non-vacuum insulated units for short-duration transport or non-critical temperature maintenance. Cost-engineered alternatives capture emerging market laboratory budgets where validation requirements remain less stringent.
Liquid Nitrogen Dewar retains volume leadership; Dry Shipper holds the steepest expansion curve.
End User:
Customer segmentation stratifies across compliance intensity, procurement scale, and technical specification authority.
- Research Laboratories:Academic and government facilities with fragmented procurement and stringent budget constraints. EMA Good Distribution Practice adoption across European research infrastructures is elevating validation documentation requirements even for basic storage equipment.
- Healthcare Facilities:Hospitals and clinical biorepositories managing patient-derived specimens under FDA 21 CFR Part 11 protocols. Cell and gene therapy manufacturing scale-up is transforming hospital-based apheresis collection sites into cryogenic logistics nodes requiring validated dry shippers.
- Biotechnology Companies:Commercial entities with consolidated vendor panels and full-service cold chain partnership preferences. Gene therapy developers in Boston and San Diego clusters favor operational expenditure structures over vessel ownership.
- Educational Institutions:Undergraduate teaching laboratories with minimal compliance burdens and price-sensitive procurement. Basic liquid nitrogen dewars for physics and chemistry demonstrations constitute the primary demand.
Biotechnology Companies command the deepest margin pools; Healthcare Facilities are gaining share fastest as CAR-T therapy networks expand.
Application:
Use-case segmentation separates biological preservation workflows from industrial and specialized aerospace requirements.
- Biological Sample Storage:Preservation of cell lines, tissues, and pharmaceutical materials under ISO 20387 biobanking standards. Quality management system mandates across European research infrastructures are triggering replacement cycles for non-validated legacy equipment.
- Cryopreservation:Controlled-rate freezing and long-term storage of gametes, embryos, and stem cells. Fertility clinic networks in United States and Spain are expanding cryogenic capacity to meet deferred demand from pandemic-era treatment delays.
- Industrial Manufacturing:Cryogenic treatment of metals, plastics, and electronic components. Semiconductor fabrication facilities in Taiwan and South Korea utilize bulk liquid nitrogen dewars for wafer processing temperature control.
- Aerospace:Propellant storage and ground support equipment for launch operations. SpaceX and Blue Origin launch cadence increases are elevating demand for large-capacity cryogenic vessels at Cape Canaveral and Vandenberg facilities.
Biological Sample Storage anchors revenue concentration; Cryopreservation is climbing the fastest as fertility tourism and stem cell banking expand.
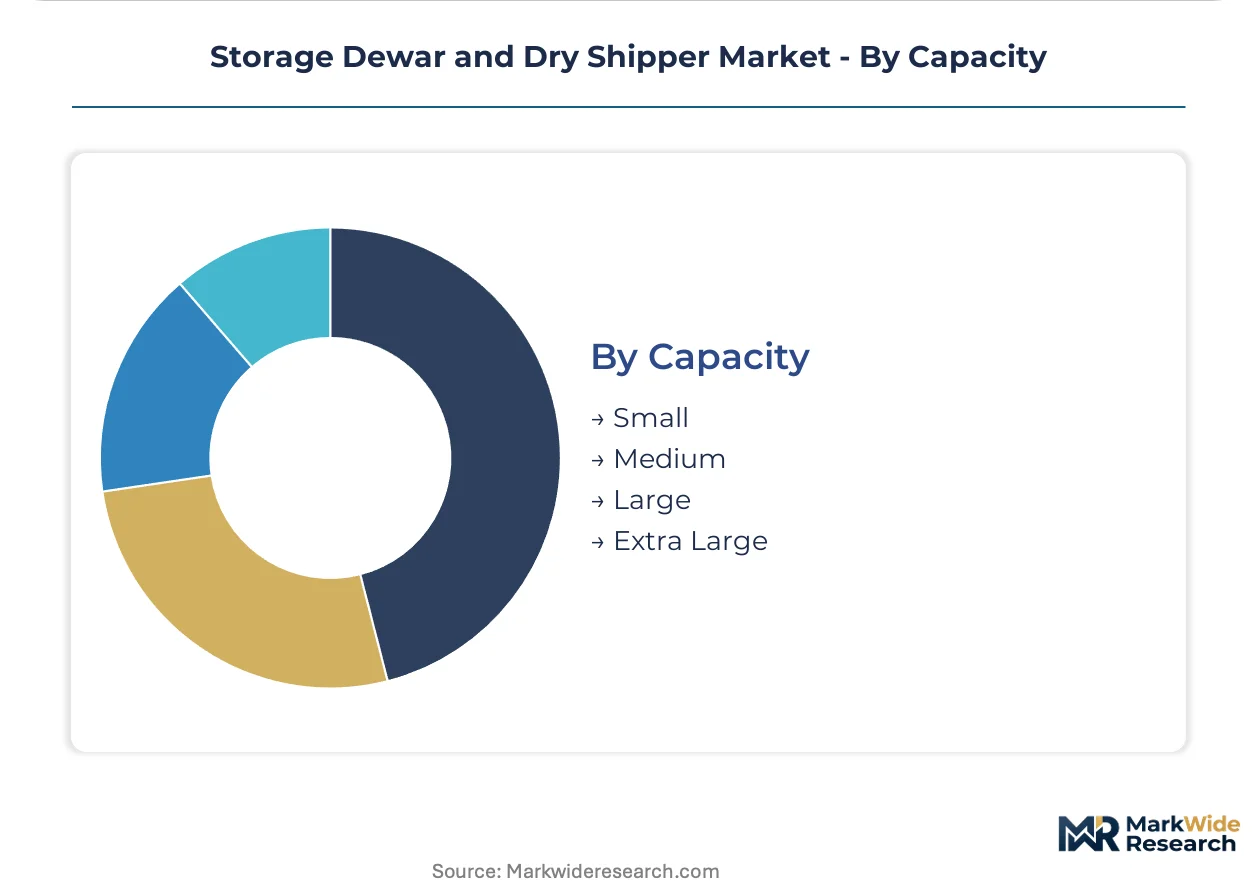
Capacity:
Size tier segmentation correlates with mobility requirements, hold-time specifications, and capital deployment intensity.
- Small:Portable vessels under 10 liters for benchtop use and short-duration transport. Research laboratories in India and Brazil are upgrading from non-validated units to ISO-compliant alternatives as biobanking infrastructure matures.
- Medium:10-50 liter units balancing mobility with extended hold times. Dry shippers in this range capture the majority of pharmaceutical air freight volumes between manufacturing and distribution sites.
- Large:50-200 liter stationary or semi-portable vessels for facility-scale storage. Biotechnology manufacturing suites specify large liquid nitrogen dewars as backup systems for mechanical freezer failures.
- Extra Large:Bulk systems exceeding 200 liters for manufacturing supply or specialized industrial applications. Helium liquefaction facilities and MRI magnet servicing operations in Qatar and United States anchor demand.
Medium capacity commands the steepest growth trajectory; Large vessels retain installed base dominance in established pharmaceutical clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German cryogenic vessel fabricators export validated dry shippers to United States biotechnology clusters and Chinese research infrastructures, establishing a trans-Atlantic and trans-Eurasian trade corridor that channels premium-grade equipment toward cell therapy manufacturing hubs.
United States
FDA 21 CFR Part 11 validation requirements and CAR-T therapy commercialization are driving procurement of documented cold chain equipment. The Boston and San Diego biotech clusters specify dry shippers with continuous monitoring capabilities for apheresis-to-manufacturing workflows. Massachusetts General Hospital and Dana-Farber Cancer Institute anchor demand concentration in Greater Boston.
Germany
EMA Good Distribution Practice mandates and ISO 20387 biobanking standards are triggering replacement cycles for legacy storage equipment. REACH amendments on perfluorinated compounds are accelerating sealant reformulation among Baden-Württemberg and Bavarian fabricators. Munich and Heidelberg research infrastructures lead European cryogenic vessel procurement.
China
NMPA tightening of biological transport documentation and national biobank network expansion are elevating demand for validated equipment. Yangtze River Delta pharmaceutical manufacturing zones in Shanghai and Suzhou are upgrading from non-validated units to ISO-compliant alternatives. Beijing-Tianjin-Hebei research clusters follow with similar procurement patterns.
India
CDSCO import regulation alignment with international cold chain standards and national cancer grid expansion are creating demand for cost-engineered dry shippers. Maharashtra and Gujarat biobanking infrastructure investments in Mumbai and Ahmedabad are driving medium-capacity vessel procurement. Telangana's Hyderabad life sciences corridor is emerging as a secondary demand node.
United Kingdom
UK MHRA post-Brexit alignment with EMA temperature validation protocols and fertility clinic network expansion are sustaining equipment demand. London and Southeast research councils are specifying ISO 20387-compliant storage for distributed biobank networks. Cambridge life sciences cluster anchors precision medicine specimen preservation requirements.
Storage Dewar and Dry Shipper Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that stratifies into three tiers. Consolidated procurement by biotechnology companies favors full-service cold chain partners capable of bundling vessels, monitoring hardware, and compliance documentation. The competitive arena separates scale-driven diversified industrials, validation-focused scientific equipment providers, and cost-engineered emerging market specialists. Dominant competitive moves include strategic partnerships with gene therapy contract manufacturers and geographic expansion through distributor networks in India and China.
Among diversified scientific equipment providers, Thermo Fisher Scientific and VWR International occupy positions exemplifying the full-service partnership model. Worthington Industries anchors the industrial fabrication tier with specialized stainless steel capabilities. Haier Biomedical represents the cost-engineered specialist archetype targeting emerging market laboratory budgets. Statebourne Cryogenics and Taylor-Wharton sit within the European precision fabrication tradition. Wessington Cryogenics exemplifies mid-tier positioning between premium validation documentation and accessible pricing.
| Leading Market Players |
|---|
| VWR International, LLC |
| Statebourne Cryogenics Ltd |
| Worthington Industries |
| Wessington Cryogenics |
| Taylor-Wharton |
| Thermo Fisher Scientific |
| Cole-Parmer Instrument Company, LLC |
| Haier Biomedical |
| Air Products and Chemicals, Inc. |
| Others |
Value Network & Pricing Analysis
Stainless steel fabrication concentration in Germany and the United States anchors premium vessel pricing, while Chinese metalworking capacity feeds cost-engineered tiers. Margin pools concentrate downstream with validation documentation bundling rather than raw thermal performance.
Pricing Analysis
Traditional perlite-insulated dewars, aerogel-composite next-generation vessels, and legacy non-validated units occupy distinct price bands. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling. Cost compression in the standard tier intensifies as aerogel technology eliminates hold-time premiums previously commanded by European fabricators. Educational institutions exhibit highest price sensitivity; gene therapy contract manufacturers show lowest sensitivity due to compliance failure costs.
Supply Chain Analysis
Extended payment terms from German and Swiss OEMs to stainless steel distributors stabilize working capital across fabrication cycles. Manufacturing concentrates in Germany, the United States, and China. Vacuum jacket assemblies draw from specialized glass-fiber reinforced epoxy suppliers and multi-layer insulation material providers. Single-source vulnerability persists in qualified sealant chemistries facing REACH authorization pressure. Distribution runs through industrial gas distributors for bulk tanks and direct OEM relationships for validated dry shippers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment creates durable defensive moats—FDA 21 CFR Part 11 validation protocols and EMA Good Distribution Practice mandates impose switching costs that freeze incumbent positions.
For Market Incumbents: Pre-empt mechanical refrigeration substitution by embedding IoT monitoring platforms into vessel contracts, locking in recurring service revenue. Accelerate aerogel-composite validation ahead of European competitors to compress pricing umbrellas. Prioritize backward integration into stainless steel fabrication capacity in Baden-Württemberg to defend margin position against Chinese cost-engineered entrants. For New Entrants and Emerging Players: India's national cancer grid expansion offers the most penetrable geographic entry point, with CDSCO import regulations creating compliance barriers that favor validated dry shipper specialists over commodity hardware vendors. Target medium-capacity vessels for biobanking infrastructure in Maharashtra and Telangana. Lead with ISO 20387 certification bundling to differentiate from legacy non-validated equipment. For Investors and Strategic Acquirers: Capital is best deployed toward full-service cold chain platform providers capable of integrating vessels, monitoring hardware, and compliance documentation through single contracts. Long-term viability hinges on gene therapy manufacturing scale-up sustaining demand across the next decade. Watch for IATA Dangerous Goods Regulation amendments tightening liquid nitrogen transport restrictions as the signal for dry shipper demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Aerogel-Composite Product Launch | Eliminates hold-time premiums commanded by specialized European fabricators. |
| REACH-Compliant Sealant Reformulation | European OEMs qualify hydrocarbon-based alternatives ahead of authorization sunset dates. |
| Full-Service Cold Chain Partnership | Boston and San Diego gene therapy clusters favor operational expenditure structures. |
| Drone-Enabled Last-Mile Delivery Pilot | Carbon composite vessels reduce weight by 40% for temperature-critical specimen transport. |
| ISO 20387 Biobank Certification Program | European research infrastructures trigger replacement cycles for non-validated legacy equipment. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with cryogenic vessel procurement managers, biobank quality directors, and cold chain logistics coordinators; and secondary validation through FDA 21 CFR guidance documents, EMA Good Distribution Practice guidelines, IATA Dangerous Goods Regulations, and ISO 20387 biobanking standards. Bottom-up triangulation across product type, capacity tier, and end-user segmentation reconciled with top-down market sizing.
Forecast inputs considered cell and gene therapy manufacturing expansion, biobanking infrastructure investment patterns, and regulatory validation protocol evolution across the projection horizon. Segmentation dimensions modeled include product architecture, end-user compliance intensity, application-specific hold-time requirements, and regional regulatory cluster. CAGRs derived from volume-demand elasticity analysis and replacement cycle timing for legacy equipment.
Macroeconomic conditions sit as an overlay; deviation in pharmaceutical R&D funding levels or air freight capacity pricing would shift the trajectory. Forecasts reflect assumptions about regulatory enforcement consistency and aerogel-composite manufacturing scale-up. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Handheld Mobile Computers Market
Others
Solar Animal Repellent Market
Others
Duckweed Market
Others
Workbench Tanks Market
Others
Android STB and TV Market
Others
Europe Smart Homes Market
Others
Rugged Devices Market
Others
France Automotive LED Lighting Market
Others
Europe Transportation Management Systems Market
Others
Global Computer Peripherals Market
Others
Japan Automotive LED Lighting Market
Others
Ultra Mobile Devices (UMD) Market
Others
Connected TV Market
Others
Global Optical Comparator Market
Others
Global Augmented Reality in Retail Market
Others
Wood Stoves Market