
 Rugged Devices Market | 2026-2036
Rugged Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Rugged Devices Market Outlook
The capability gap between vertically integrated manufacturers and assembly-reliant competitors is rotating competitive advantage toward firms with in-house component production. Samsung Electronics leverages captive semiconductor fabrication to control chipset supply for its rugged tablet lines. Caterpillar anchors its position through extreme-environment field testing protocols tied to heavy machinery operator workflows. Motorola Solutions differentiates via dedicated public-safety spectrum integration in its handheld portfolio.
Rugged devices are engineered computing and communication equipment built to withstand shock, vibration, temperature extremes, moisture ingress, and particulate contamination, typically validated against MIL-STD-810H or IP6X standards for operational continuity in hostile environments. Their primary purpose is to sustain data capture, voice communication, and situational awareness where consumer-grade electronics would fail within hours. Rugged smartphones currently occupy the largest revenue pool among product types, though wearable devices represent the fastest-expanding category as wrist-mounted biometric and location trackers penetrate field services and defense applications. Construction and manufacturing end users generate the steadiest replacement cycles, while defense procurement commands premium pricing tiers tied to encrypted communication requirements.
FCC equipment authorization and NHTSA distracted-driving guidelines in the United States shape voice-first interface requirements and hands-free operation standards for in-vehicle rugged deployments. ETSI radio spectrum coordination and CE marking under the EU Radio Equipment Directive govern market access across European member states, with REACH compliance adding material disclosure obligations for battery and enclosure chemistries. Stakeholders must monitor evolving encryption export controls and regional content mandates that threaten to fragment supply chains and force parallel product variants for different national certification regimes.
Market Dynamics
Defense procurement cycles and NATO battlefield modernization programs are compressing product development timelines while simultaneously elevating MIL-STD-810H validation requirements. Manufacturers must now engineer for mission-ready deployment rather than gradual commercial adoption.
Growth Catalysts
- PLI scheme incentives:India's production-linked incentive framework for electronics manufacturing is accelerating domestic assembly of rugged handheld units for construction and field services verticals.
- MIL-STD-810H procurement mandates:United States defense acquisition protocols now require shock, vibration, and temperature-extreme validation for all mission-critical communication hardware.
- Infrastructure build-outs:Large-scale civil engineering projects across India are generating replacement demand for dust-resistant and moisture-sealed data capture equipment.
Market Restraints
- Semiconductor supply concentration:Captive fabrication capacity remains concentrated among integrated device manufacturers, constraining chipset access for assembly-reliant competitors.
- IP68 validation costs:Ingress protection certification against particulate and liquid contamination requires specialized testing infrastructure that extends product qualification timelines.
- Consumer-grade substitution:Improved water resistance in standard smartphones creates pricing pressure at the lower-performance tier of the rugged spectrum.
Strategic Opportunities
- Wearable biometric integration:Wrist-mounted location and health monitoring devices represent an underdeveloped category within field services and defense applications.
- Public-safety spectrum allocation:Dedicated bandwidth for first responders creates hardware differentiation opportunities through specialized radio module integration.
- Domestic content thresholds:India's phased manufacturing program incentivizes local component sourcing for devices serving government and infrastructure contracts.
Industry Challenges
- MIL-STD-810H test cycle duration:Environmental stress validation protocols extend time-to-market for new product introductions.
- Encryption export control fragmentation:Divergent national security requirements force parallel firmware variants and complicate inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rugged Devices Market |
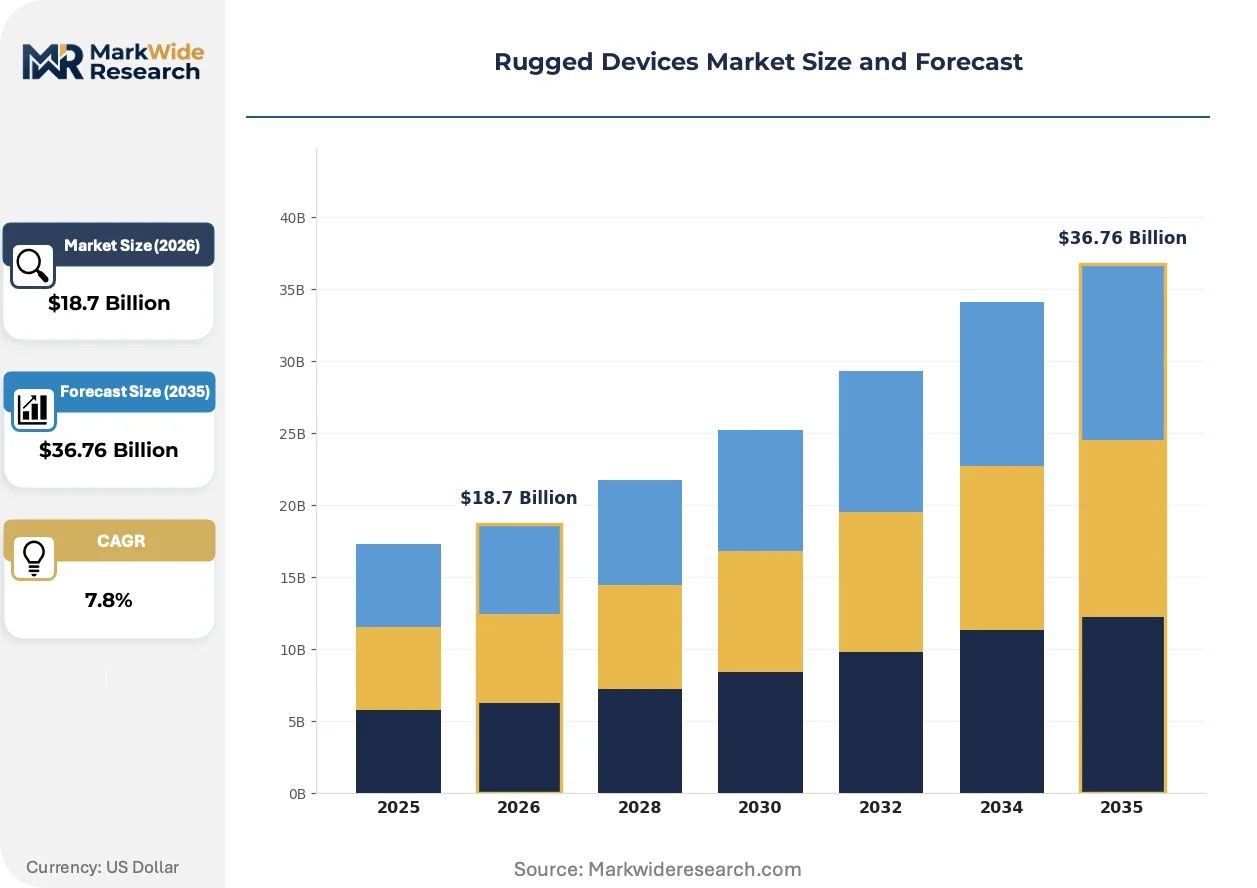
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $36.76 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rugged Smartphones, Rugged Tablets, Rugged Laptops, Wearable Devices End User: Defense, Construction, Manufacturing, Field Services Technology: GPS, RFID, NFC, Barcode Scanning Deployment: On-Premises, Cloud, Hybrid, Remote Management |
| Companies Covered | CROSSCALL, Blackview, Samsung Electronics, Ulefone, Doogee, Caterpillar, Kyocera Corporation, Motorola Solutions, Sonim Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rugged Devices Market Strategic Shifts
Hardware architectures are compressing while computational demands intensify, forcing trade-offs between thermal management and physical durability. Three developments are actively restructuring competitive positioning.
System-in-package (SiP) module integration is consolidating multiple semiconductor functions into single substrates. Defense and field services buyers are specifying these compact assemblies for space-constrained wearable and handheld form factors. This consolidation is miniaturizing device footprints without sacrificing MIL-STD-810H shock resistance.
ETSI radio spectrum coordination under the EU Radio Equipment Directive is mandating interoperability testing for cross-border public-safety communication. Equipment vendors must now engineer modular radio architectures that satisfy multiple national frequency allocations. Handheld units destined for European defense and emergency services procurement are most affected, with manufacturers responding through software-defined radio platforms.
Buyer organizations are consolidating vendor relationships and demanding integrated hardware-software-service bundles. System integrators and large construction firms are displacing transactional equipment purchasing with multi-year fleet management contracts. India and Germany exhibit the most pronounced concentration, where infrastructure contractors favor single-source suppliers for device provisioning, maintenance, and secure data management.
Rugged Devices Market Segmentation
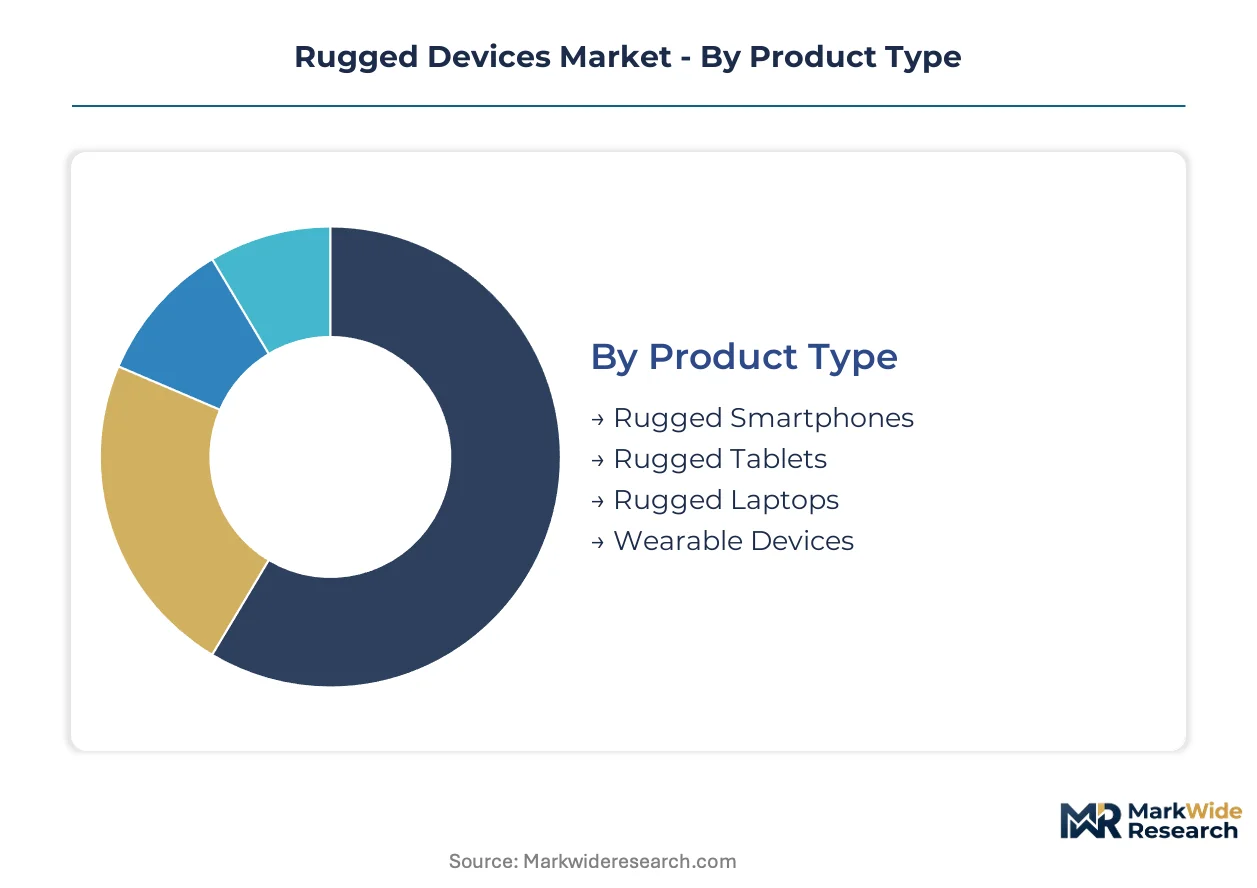
Rugged device procurement patterns diverge sharply across product architectures and operational environments. End-use requirements for MIL-STD-810H certification versus commercial IP68 validation create distinct sourcing channels that manufacturers must navigate simultaneously.
Product Type:
Rugged smartphones concentrate domestic demand in India's infrastructure vertical, while wearable devices drive export-led growth into NATO defense procurement.
- Rugged Smartphones:MIL-STD-810H validated handheld units with reinforced chassis and sealed ports sustain voice communication and data capture in construction and field services. India's PLI scheme incentives are accelerating domestic assembly for government and infrastructure contracts, compressing import dependency.
- Wearable Devices:Wrist-mounted biometric and location trackers integrate health monitoring with GPS positioning for defense and emergency responder applications. NATO battlefield modernization programs in Germany and France are specifying these compact form factors for situational awareness without hand-occupation.
- Rugged Tablets:Larger-screen field computers with sunlight-readable displays and stylus input serve heavy machinery operators and maintenance crews.
- Rugged Laptops:Full-keyboard portable workstations with solid-state storage and extended temperature tolerances support engineering and logistics functions.
Rugged smartphones command the established base. The steepest expansion runs through wearable devices.
End User:
Defense procurement operates on classified contract vehicles with encrypted communication mandates, while construction and manufacturing follow commercial tender processes with shorter decision cycles.
- Defense:Mission-ready communication hardware with NSA-approved encryption modules and anti-tamper enclosures. United States defense acquisition protocols now require MIL-STD-810H validation for all battlefield-deployable units, elevating qualification barriers for non-integrated suppliers.
- Construction:Dust-resistant and moisture-sealed data capture equipment for civil engineering projects. India's infrastructure build-outs across Maharashtra and Gujarat are generating replacement demand for IP68-certified handheld units.
- Manufacturing:Shock-resistant terminals for production floor inventory management and quality control workflows.
- Field Services:Multi-mode connectivity devices for utility maintenance, telecommunications repair, and agricultural monitoring operations.
Defense procurement commands premium pricing tiers. Manufacturing generates the steadiest replacement cycles.
Technology:
RFID and NFC adoption concentrates in European manufacturing traceability mandates, while GPS integration dominates defense and field services positioning requirements.
- GPS:Multi-constellation satellite positioning with GLONASS and Galileo augmentation for meter-level accuracy in remote terrain.
- RFID:Passive and active radio-frequency identification for asset tracking and inventory automation in industrial environments.
- NFC:Near-field communication modules for secure credential verification and contactless data exchange.
- Barcode Scanning:Imager-based and laser-based optical readers for 1D and 2D symbology capture in logistics operations.
Barcode scanning retains the largest installed base. RFID is climbing the fastest in manufacturing verticals.
Deployment:
Cloud and hybrid architectures are displacing purely on-premises management as fleet sizes scale and security frameworks mature.
- On-Premises:Local server infrastructure for air-gapped defense and critical infrastructure environments with classified data handling requirements.
- Cloud:Centralized device management platforms with over-the-air firmware updates and telemetry analytics.
- Hybrid:Split architectures keeping sensitive operations local while pushing non-critical analytics to cloud instances.
- Remote Management:Dedicated mobile device management consoles for geographically dispersed field fleets with intermittent connectivity.
On-premises deployment anchors defense and critical infrastructure. Hybrid configurations are gaining share fastest among multi-site construction operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement in the United States prioritizes encrypted battlefield communication, while India's infrastructure vertical drives volume demand for dust-resistant construction equipment. Germany's manufacturing base sustains premium-tier industrial automation deployments.
United States
NATO modernization programs and defense acquisition protocols sustain demand for MIL-STD-810H validated handheld units. FCC equipment authorization governs radio module certification for public-safety spectrum integration. Defense contractors in Virginia and Texas concentrate procurement of mission-ready communication hardware with NSA-approved encryption.
Germany
Industrial automation and heavy machinery operator workflows generate replacement cycles for IP68-certified field computers. ETSI radio spectrum coordination under the EU Radio Equipment Directive mandates cross-border interoperability testing. Manufacturing clusters in Bavaria and Baden-Württemberg specify rugged tablets for production floor quality control.
India
Civil engineering projects across Maharashtra and Gujarat accelerate adoption of moisture-sealed data capture equipment. PLI scheme incentives under the Ministry of Electronics and Information Technology accelerate domestic assembly of rugged smartphones. Infrastructure contractors in Delhi-NCR consolidate vendor relationships for fleet management contracts.
France
Emergency responder applications and defense procurement specify wrist-mounted biometric trackers for situational awareness. ANSM and CNIL frameworks govern health data processing in connected field devices. Aerospace and defense suppliers in the Provence-Alpes-Côte d'Azur region integrate compact wearable form factors into soldier modernization programs.
Japan
Precision manufacturing and logistics operations sustain demand for shock-resistant inventory management terminals. METI industrial standards and JIS certification protocols validate environmental stress resistance for production floor deployment. Automotive suppliers in the Chubu/Nagoya corridor specify rugged handheld units for supply chain traceability.
Rugged Devices Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with captive semiconductor fabrication separating premium-positioned players from assembly-reliant competitors. The market structure rewards backward integration into chipset supply and in-house environmental testing infrastructure. Three archetypes dominate: vertically integrated electronics conglomerates, heavy machinery-origin equipment specialists, and dedicated public-safety communication vendors. Competitive moves concentrate on strategic partnerships for radio module sourcing and geographic expansion through domestic content compliance.
Within the integrated electronics tier, Samsung Electronics exemplifies captive supply chain control, while Motorola Solutions occupies a position in public-safety spectrum integration. Among machinery-origin specialists, Caterpillar anchors the extreme-environment testing archetype through field validation protocols tied to operator workflows.
| Leading Market Players |
|---|
| CROSSCALL |
| Blackview |
| Samsung Electronics |
| Ulefone |
| Doogee |
| Caterpillar |
| Kyocera Corporation |
| Motorola Solutions |
| Sonim Technologies |
| Others |
Value Chain & Pricing Dynamics
System-in-package module substitution for discrete component assemblies is redrawing manufacturing geography toward Taiwan and South Korea while compressing margin structures for assembly-reliant competitors in India and Vietnam. This consolidation simultaneously elevates pricing power for integrated device manufacturers and squeezes transactional pricing tiers for brands dependent on external chipset sourcing.
Pricing Analysis
Long-term fleet management contracts now dominate procurement for infrastructure contractors in India and Germany, displacing spot-market equipment purchasing. Three-tier pricing structure across MIL-STD-810H premium, IP68-standard, and commercial-rugged economy levels separates defense-grade encrypted units from construction-tier sealed handhelds. Cost compression in the economy tier intensifies because consumer-grade water resistance narrows the performance gap. Construction buyers in India's PLI scheme zones exhibit the highest price sensitivity, while NATO defense procurement shows minimal elasticity for mission-ready validated units.
Supply Chain Analysis
Strategic stockpiling of MIL-STD-810H certified chipsets and reinforced display substrates is displacing just-in-time inventory norms among defense-focused suppliers facing extended validation timelines. Captive fabrication in South Korea and Taiwan feeds premium-tier production, while India and Vietnam anchor final assembly for standard-tier volume. Semiconductor supply draws from concentrated foundry capacity, reinforced chassis components hinge on specialty alloy mills in Germany and Japan, and battery cells rest on South Korean and Chinese chemistry suppliers. Single-source vulnerability in NSA-approved encryption module supply threatens fulfillment for classified contracts. Distribution runs through authorized defense contractors and construction fleet integrators rather than open-channel retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rugged devices sit at an early-cycle expansion story where wearable biometric penetration in field services and NATO soldier modernization programs is accelerating category development faster than smartphone replacement saturation.
For Market Incumbents: Consolidate backward integration into captive semiconductor fabrication and in-house MIL-STD-810H testing infrastructure to defend against emerging fabless competitors leveraging India's PLI assembly incentives. Prioritize certification investment for NSA-approved encryption modules to lock out non-integrated suppliers from defense contract vehicles. Channel control through exclusive fleet management partnerships with infrastructure contractors in Delhi-NCR and Maharashtra compresses pricing transparency. For New Entrants and Emerging Players: Aftermarket service-layer gaps in device lifecycle management and secure data wiping for decommissioned field units present white-space openings where integrated incumbents under-serve. India's domestic content thresholds for government contracts offer the most penetrable entry path, particularly through joint ventures with local electronics manufacturing service providers. A hardware-as-a-service go-to-market angle bypasses capital-intensive certification barriers while capturing recurring revenue streams. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated mid-caps with captive testing infrastructure and established defense contract relationships over pure-play assembly operators. Long-term viability across the five-to-ten year window rests on encryption export license portfolios and software-defined radio platform development. The signal to watch is India's phased manufacturing program domestic content threshold escalation, which will force acquisition targets to demonstrate local component sourcing depth or face contract disqualification.| Strategic Initiative | Industry Significance |
|---|---|
| System-in-Package Module Integration | Consolidates semiconductor functions for MIL-STD-810H wearable form factors without shock resistance trade-offs. |
| Software-Defined Radio Platform Development | Enables ETSI cross-border interoperability for European defense and emergency services procurement mandates. |
| Domestic Content Compliance Investment | Secures PLI scheme eligibility and government contract access in India's phased manufacturing program. |
| NSA Encryption Module Certification | Unlocks premium-tier defense procurement with anti-tamper hardware requirements and classified contract vehicles. |
| Fleet Management Service Bundling | Captures multi-year recurring revenue from infrastructure contractors consolidating vendor relationships in Germany and India. |
Study Parameters
Desk research of defense procurement databases, FCC equipment authorization filings, and PLI scheme disclosure documents preceded structured interviews with rugged device product managers, defense acquisition officers, infrastructure contractor procurement leads, and semiconductor supply chain directors. Primary fieldwork across the United States, Germany, and India validated secondary estimates of certification timeline impacts and domestic content threshold compliance costs. Bottom-up unit shipment modeling by product tier and end-use vertical was cross-checked against top-down defense budget allocation analysis.
Variance decomposition across product type, end-user segment, technology integration level, and deployment architecture informed analytical framework construction throughout the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by pricing tier concentration. Forecast inputs incorporated MIL-STD-810H validation queue durations, India's phased manufacturing program milestone schedules, and NATO battlefield modernization procurement cycle timing.
Forecasts assume regulatory continuity in FCC equipment authorization protocols, ETSI radio spectrum coordination frameworks, and India's PLI scheme incentive structures; material policy shifts would require re-modeling of domestic assembly economics and cross-border equipment certification reciprocity. Revision becomes warranted when encryption export control fragmentation exceeds current bilateral agreement coverage or when semiconductor foundry capacity allocation for defense-grade chipsets crosses critical shortage thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Asia-Pacific Battery E-Commerce Market
Others
Europe Astrology Market
Others
Global Platform Trolley Market
Others
Smart TV Platforms Market
Others
Augmented Reality in BFSI Market
Others
Medium-Voltage Switchgear Market
Others
Corn Fiber Market
Others
Air Purification Systems Market
Others
Thailand Travel Retail Market
Others
Global Sportswear Market
Others
North America Medical Simulation Market
Others
IoT Testing Market
Others
North America 3D Printing Construction Market
Others
Caster Wheels Market
Others
Cat Food and Snacks Market
Others
US Mobile MRI Services Market