
 Android STB and TV Market | 2026-2036
Android STB and TV Market Size, Share, and Industry Trends Forecast 2026-2036
Android STB and TV Market Outlook
Embedded Linux firmware engineering talent scarcity is unwinding as consumer electronics manufacturers retrain semiconductor validation teams for Android TV OS optimization. Google leverages its certification program to control platform fragmentation across OEM partners. Samsung Electronics anchors high-end smart TV production through in-house display and chipset integration. TCL Electronics competes aggressively on cost-engineered 4K UHD panels with integrated Android TV functionality.
Android STB and TV encompasses smart televisions, set-top boxes, streaming dongles, and gaming-integrated displays running the Android TV operating system, typically featuring ARM-based SoCs with hardware video decode pipelines supporting HEVC and AV1 codecs at 4K UHD resolution with HDR10 or Dolby Vision metadata. These devices serve primary commercial purposes of delivering over-the-top video streaming, interactive advertising, and cloud gaming services to residential and commercial display endpoints. Smart TVs capture the dominant margin pool as panel costs decline and software service revenue attach rates improve, while streaming devices face structural pressure from smart TV OS integration that eliminates dedicated hardware need. AI integration represents the fastest-expanding technology segment as on-device recommendation engines and voice assistant processing migrate from cloud dependency to local neural processing unit execution.
The FCC governs electromagnetic emissions and RF spectrum compliance for wireless-enabled Android TV devices sold in the United States, while the EU Green Deal's ecodesign requirements mandate standby power limits and repairability disclosures for televisions marketed across European member states. China's MIIT enforces network access licenses and content security module integration for Android-based set-top boxes deployed on mainland broadband infrastructure. Stakeholders must monitor how fragmented national content licensing regimes interact with platform-level digital rights management standardization across Android TV OEM ecosystems.
Market Dynamics
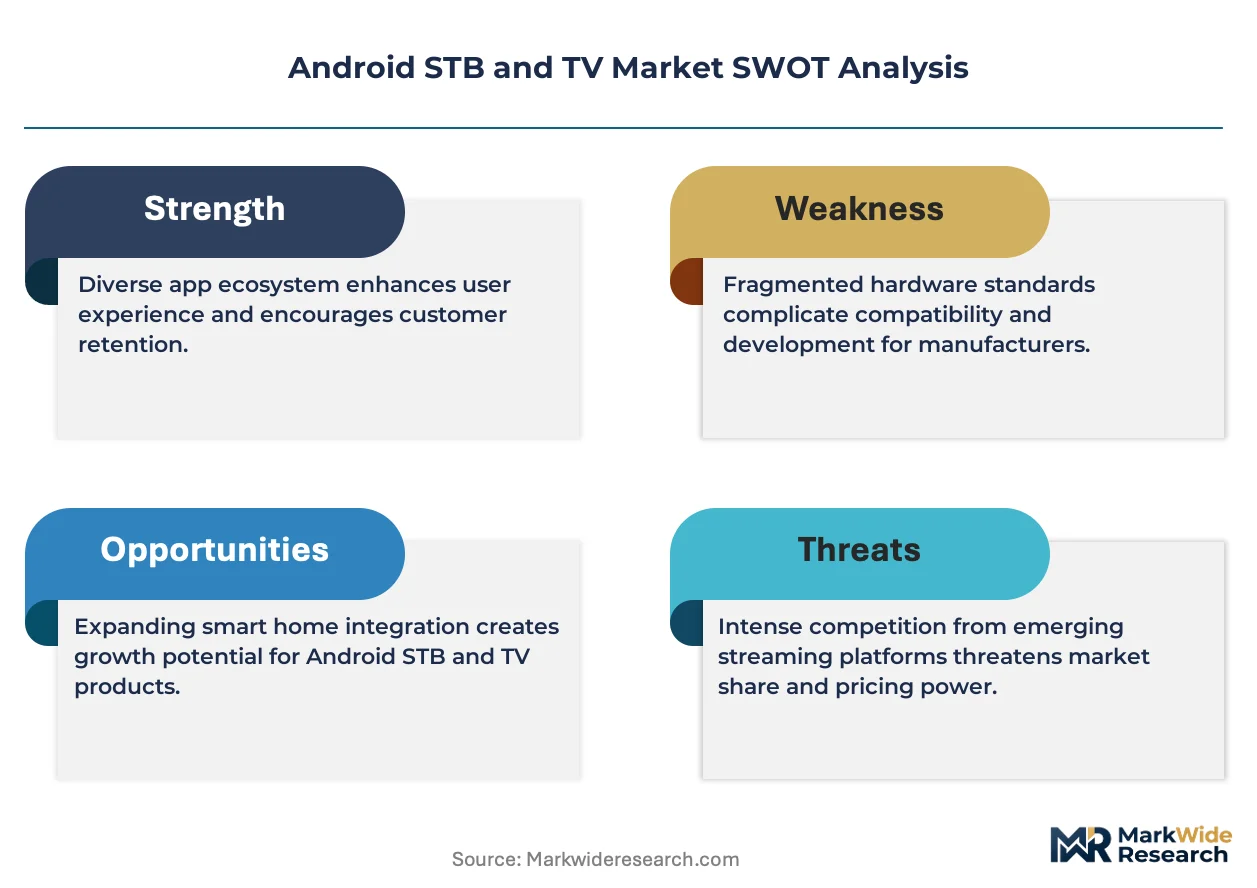
Google's certification gatekeeping through Android TV OS compliance requirements is compressing hardware vendor margins while consolidating platform control, forcing OEMs to reallocate engineering resources from differentiation toward compatibility validation.
Growth Catalysts
- India's PLI scheme for electronics manufacturing:Production-linked incentives for large-scale electronics manufacturing are attracting component assembly and finished goods production to Indian facilities, expanding local supply capacity for Android TV devices.
- AV1 codec hardware decode pipelines:Silicon vendors integrating AV1 decode blocks into ARM-based SoCs are reducing streaming bandwidth costs for OTT operators, accelerating replacement cycles for legacy HEVC-only hardware.
- Hospitality sector deployment mandates:Hotel chains and cruise operators are standardizing on Android-based entertainment systems to unify content management across property portfolios, creating recurring hardware refresh demand.
Market Restraints
- Panel cost volatility from LCD-OLED supply imbalances:Display panel pricing fluctuations compress margin predictability for smart TV assemblers, particularly in mid-tier product segments where cost engineering dominates positioning.
- Google certification timeline bottlenecks:Extended Android TV OS validation cycles delay product launches by 4-8 months, freezing inventory planning and marketing coordination for OEM partners.
- Streaming stick substitution by smart TV OS integration:Native Android TV functionality in entry-level television panels is eliminating the addressable market for dedicated streaming dongles and basic set-top boxes.
Strategic Opportunities
- Cloud gaming service bundling:Android TV hardware vendors can attach subscription revenue shares from NVIDIA GeForce NOW, Xbox Cloud Gaming, and Amazon Luna by optimizing SoC performance for low-latency game streaming.
- EU Green Deal ecodesign compliance premium:Manufacturers achieving standby power thresholds below mandated limits can access preferential retail placement and public procurement channels across European member states.
- AI recommendation engine localization:On-device neural processing unit deployment for content personalization reduces cloud inference costs and enables offline functionality, differentiating premium tier hardware in bandwidth-constrained markets.
Industry Challenges
- Firmware engineering talent scarcity:Consumer electronics manufacturers face recruitment gaps for Android TV OS optimization specialists, requiring retraining of embedded Linux validation teams.
- Content licensing fragmentation:Territory-specific digital rights management requirements force OEMs to maintain multiple firmware builds, complicating inventory management and software update distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Android STB and TV Market |
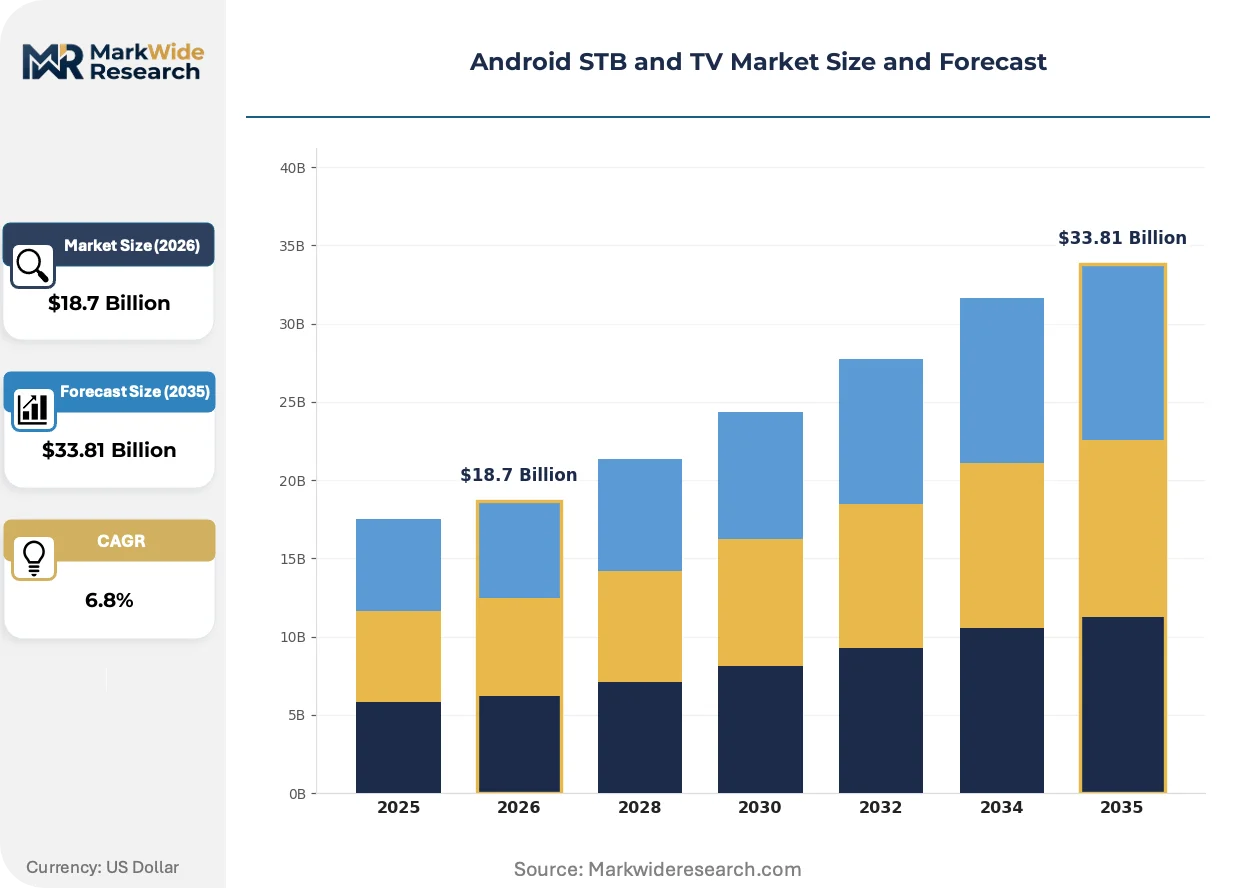
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart TVs, Set-Top Boxes, Streaming Devices, Gaming Consoles Technology: 4K UHD, HDR, AI Integration, Voice Control End User: Consumers, Hospitality, Education, Enterprises Distribution Channel: Online Retailers, Electronics Stores, Wholesale, Subscription Services |
| Companies Covered | Google, Samsung Electronics, Amazon, LG Electronics, TCL Electronics, Xiaomi Corporation, Sony Corporation, Nvidia Corporation, Roku, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Android STB and TV Market Strategic Shifts
Hardware-software decoupling is accelerating as Google tightens platform governance, compressing vendor differentiation space while opening service revenue attachment models.
On-device AI inference is decomposing cloud dependency for voice assistant processing and content recommendation engines. Hospitality operators and smart home integrators are deploying edge-based neural processing units to reduce latency and eliminate connectivity failure points. This architectural shift is decomposing the traditional SaaS revenue model for platform operators, forcing renegotiation of service fee structures.
EU Green Deal ecodesign requirements are mandating standby power limits and repairability disclosures for televisions marketed across European member states. Manufacturers must redesign power management subsystems and publish component-level repair documentation, increasing BOM complexity but unlocking preferential retail access. Premium tier vendors are responding fastest, using compliance as positioning leverage against cost-optimized imports.
Hotel procurement departments are consolidating vendor relationships around unified content management platforms, displacing fragmented legacy installations. Property technology integrators are replacing multiple single-purpose hardware categories with Android TV-based all-in-one endpoints. This concentration is most visible in luxury hospitality chains across Southeast Asian markets, where standardized guest experience specifications override local supplier preferences.
Android STB and TV Market Segmentation
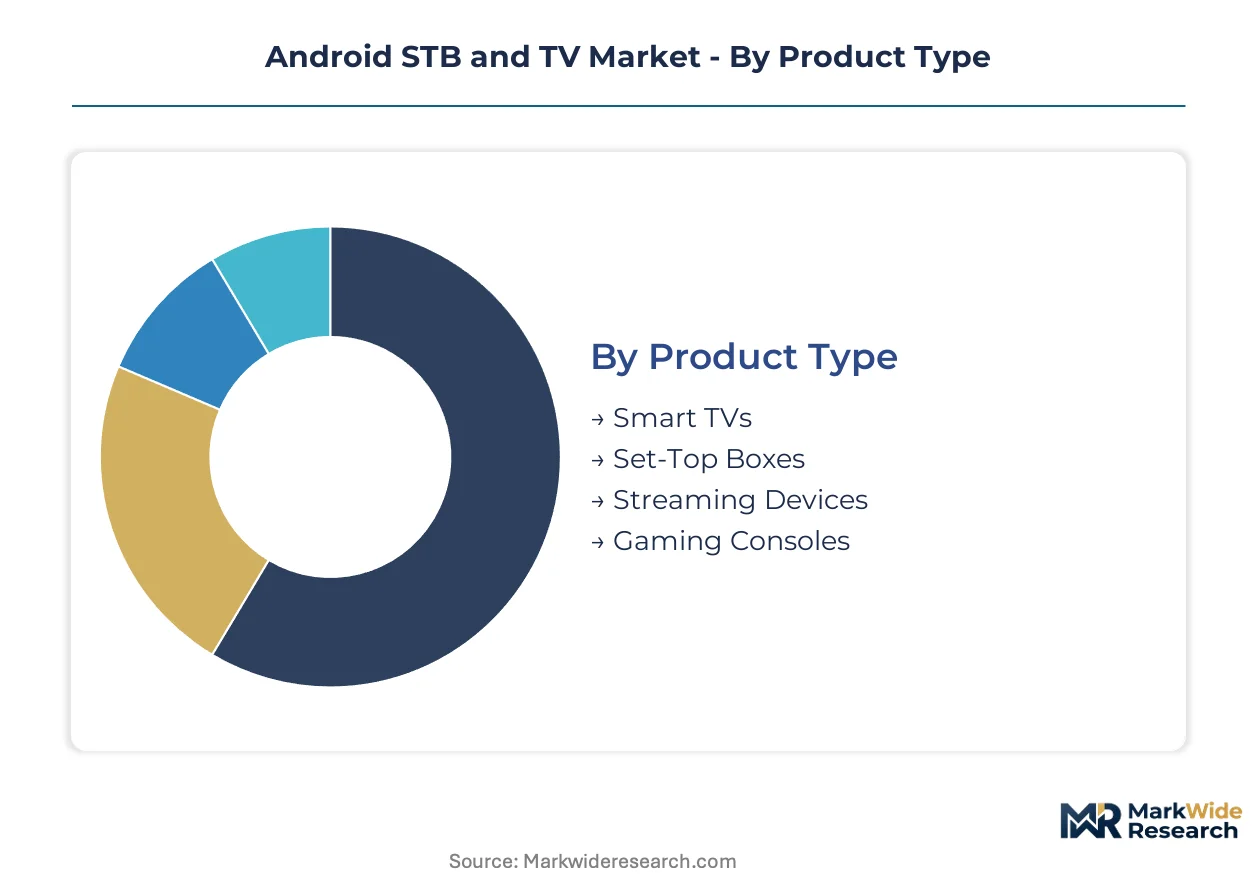
Android STB and TV market segmentation reveals how hardware form factors, display technologies, and commercial deployment models create distinct margin profiles and supply chain requirements. Understanding these divisions exposes where Google certification constraints bite hardest and where hospitality procurement patterns reshape volume allocation.
Product Type:
Smart TVs concentrate manufacturing in India and Vietnam for export to North American and European markets, while set-top boxes and streaming devices serve more localized deployment patterns tied to regional broadcaster infrastructure.
- Smart TVs:ARM-based SoC integration with direct panel bonding dominates BOM composition. India's PLI scheme has attracted TCL, Samsung, and Dixon Technologies to assemble 32-65 inch 4K UHD panels for export to US and EU retail channels, though Google certification bottlenecks delay launch windows by 4-8 months.
- Set-Top Boxes:Housed enclosures with tuner modules and conditional access hardware serve cable and satellite operator deployments. China's MIIT network access license requirements fragment firmware builds for mainland broadband infrastructure versus export variants.
- Streaming Devices:Compact HDMI dongles and puck form factors face structural pressure from smart TV OS integration. Amazon Fire TV and Google Chromecast hardware teams now prioritize software licensing over dedicated hardware volume.
- Gaming Consoles:Android TV-based gaming-integrated displays with low-latency streaming optimization target cloud gaming service bundling. NVIDIA GeForce NOW certification drives SoC selection toward higher GPU core counts.
Smart TVs hold the largest share; momentum sits with gaming consoles as cloud gaming service attach rates climb.
Technology:
Cost tier stratification separates premium HDR and AI-enabled hardware from baseline 4K UHD implementations, with voice control becoming table stakes across mid-tier and above.
- 4K UHD:Panel resolution standardization at 3840x2160 with 60Hz refresh rates anchors volume production. India and Vietnam assembly plants achieve lowest per-unit panel costs through scale concentration.
- HDR:Dolby Vision and HDR10+ metadata processing pipelines require dedicated tone-mapping hardware. Premium tier positioning in EU and US markets depends on HDR certification for streaming service content partnerships.
- AI Integration:On-device neural processing units for recommendation engines and voice assistant processing reduce cloud inference dependency. Hospitality operators in Singapore and Bangkok deploy edge-based AI to eliminate connectivity failure points.
- Voice Control:Far-field microphone arrays and natural language processing integration now standard across mid-tier hardware. Google Assistant and Amazon Alexa certification requirements add firmware validation cycles.
4K UHD captures baseline volume; AI Integration is expanding most quickly as hospitality and smart home integrators prioritize offline functionality.
End User:
Application-driven demand splits between residential consumer replacement cycles and commercial procurement mandates with unified content management requirements.
- Consumers:Residential replacement cycles tied to panel failure or streaming service feature requirements drive baseline demand. India's affordable smart TV penetration expands through government digital infrastructure programs.
- Hospitality:Hotel chains and cruise operators standardize on Android-based entertainment systems for unified content management. Marriott and Royal Caribbean procurement specifications override local supplier preferences in Southeast Asian markets.
- Education:Classroom and campus display deployments prioritize durability and centralized device management. K-12 and university IT departments in US and EU markets favor Chrome OS TV hybrids over pure Android TV.
- Enterprises:Corporate lobby and meeting room signage applications require MDM integration and scheduled content playback. Samsung and LG commercial display divisions compete with Android TV OEMs for corporate procurement.
Consumers represent the deepest volume base; hospitality is gaining share fastest as property technology consolidation accelerates.
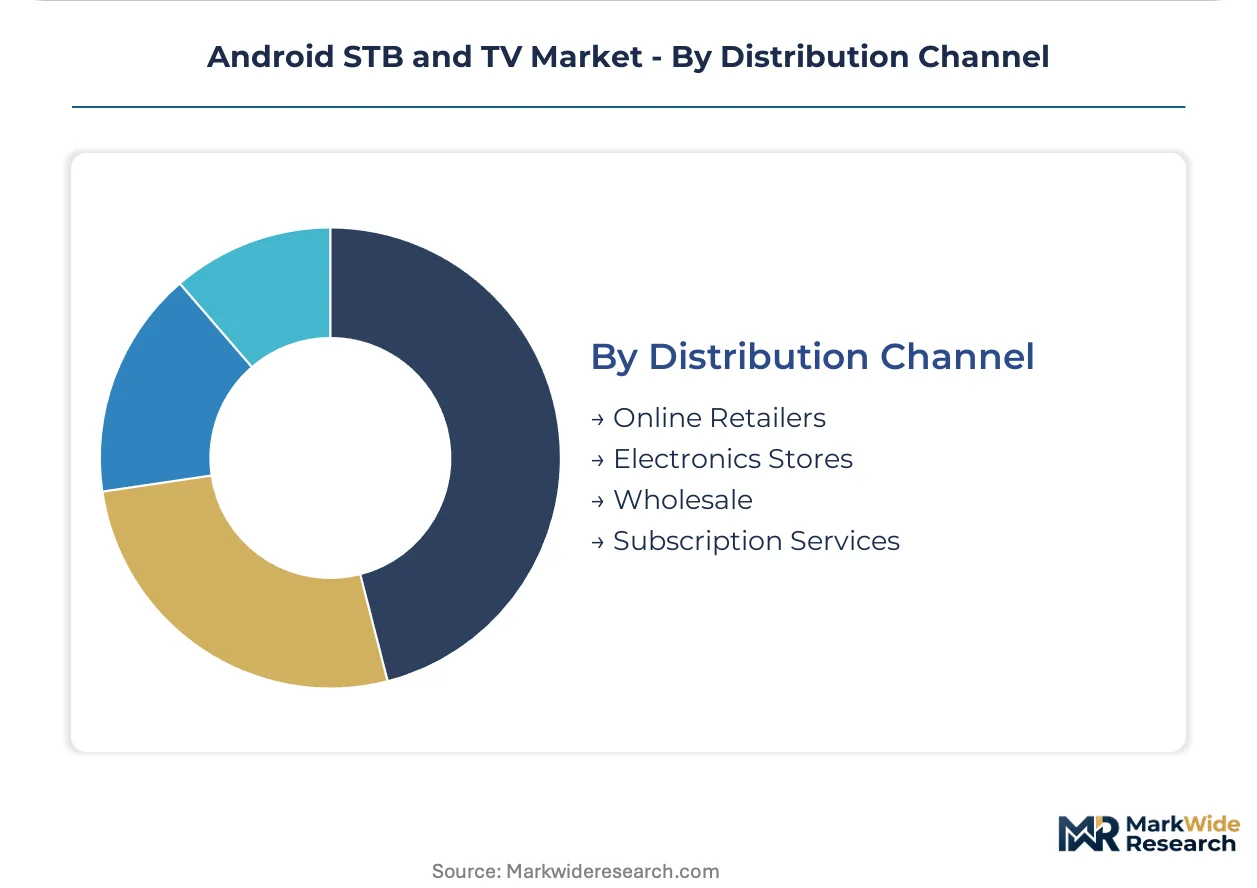
Distribution Channel:
Customer type and purchase behavior split between direct consumer acquisition and institutional procurement with extended payment terms and service bundling.
- Online Retailers:Amazon, Flipkart, and JD.com direct-to-consumer sales dominate price-transparent markets. India's e-commerce penetration for electronics has compressed traditional electronics store foot traffic.
- Electronics Stores:Best Buy, MediaMarkt, and regional chains provide hands-on evaluation for premium tier purchases. EU Green Deal ecodesign compliance unlocks preferential retail placement.
- Wholesale:B2B volume procurement for hospitality, education, and enterprise deployments runs through specialized AV integrators. Extended payment terms and installation service bundling characterize this channel.
- Subscription Services:Hardware subsidy models tied to multi-year streaming or cloud gaming commitments. Reliance Jio and Airtel in India bundle Android TV devices with broadband and content packages.
Online retailers hold the largest share; subscription services are climbing the fastest as telecom operators and streaming platforms pursue hardware-software integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC governs electromagnetic emissions and RF spectrum compliance for wireless-enabled Android TV devices in the United States, while the EU Green Deal's ecodesign requirements mandate standby power limits across European markets. India's PLI scheme for electronics manufacturing attracts component assembly and finished goods production, expanding local supply capacity.
United States
Residential replacement cycles tied to streaming service feature requirements drive baseline consumer demand. The FCC enforces electromagnetic emissions standards for WiFi-enabled devices. Best Buy and Amazon dominate retail distribution, with California and Texas housing the largest installed bases of smart TV households.
India
Affordable smart TV penetration expands through government digital infrastructure programs and telecom operator bundling. The PLI scheme for large-scale electronics manufacturing attracts TCL, Samsung, and Dixon Technologies to assemble panels for export. Noida and Chennai assembly plants achieve lowest per-unit costs through scale concentration.
Germany
EU Green Deal ecodesign requirements unlock preferential retail placement for manufacturers achieving standby power thresholds below mandated limits. The country's national electronics regulator enforces CE marking compliance. MediaMarkt and Saturn anchor premium-tier distribution in Berlin and Munich metropolitan areas.
China
MIIT network access license requirements fragment firmware builds for mainland broadband infrastructure versus export variants. The dual carbon goals pressure manufacturers to redesign power management subsystems. Shenzhen and Dongguan industrial clusters concentrate SoC integration and panel bonding operations.
Vietnam
Electronics manufacturing relocation from China accelerates Android TV assembly for North American and European export markets. The country's national trade ministry administers import tariff schedules for display components. Ho Chi Minh City and Bac Ninh Province host Samsung and LG display module facilities.
Android STB and TV Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Android STB and TV landscape. Platform operators with certification gatekeeping power extract margins through software licensing, while panel assemblers compete on cost engineering and scale efficiency. Three archetypes dominate: vertically integrated display manufacturers, platform licensors with hardware reference designs, and contract assemblers serving retail and hospitality channels. Strategic moves concentrate on M&A for display technology access and strategic partnerships for content service bundling.
Within the platform licensor tier, Google and Amazon occupy positions that reshape hardware vendor economics through certification requirements and service revenue attachment. Samsung Electronics anchors the vertically integrated archetype through in-house display and chipset integration. TCL Electronics exemplifies the cost-engineered panel assembler competing aggressively on 4K UHD positioning.
| Leading Market Players |
|---|
| Samsung Electronics |
| Amazon |
| LG Electronics |
| TCL Electronics |
| Xiaomi Corporation |
| Sony Corporation |
| Nvidia Corporation |
| Roku |
| Others |
Value Chain & Pricing Dynamics
Scale concentration at Indian and Vietnamese assembly plants compresses per-unit panel costs while establishing hard price floors for mid-tier smart TV positioning. Google's certification bottlenecks freeze inventory planning cycles, forcing OEMs to absorb working capital costs that transmit into retail pricing premiums across North American and European channels.
Pricing Analysis
Price spreads between India-assembled export units and China-mainland variants reflect differential tariff exposure and logistics cost structures rather than specification gaps. Three-tier pricing structure across premium HDR-certified, standard 4K UHD, and economy HD-ready levels separates Dolby Vision tiering from baseline hardware. Cost compression in mid-tier segments intensifies because panel oversupply from Chinese and Korean fabs erodes margin buffers. Hospitality procurement departments exhibit lowest price sensitivity due to unified content management requirements, while Indian residential consumers drive volume through telecom-bundled subsidy models.
Supply Chain Analysis
Just-in-time panel procurement dominates OEM planning, though Google certification timeline uncertainty forces strategic stockpiling of SoC inventory across 4-8 month validation windows. Component sourcing concentrates in China for ARM-based SoCs and display driver ICs, Vietnam for final assembly and bonding operations, and India for duty-advantaged export production. Raw material dependencies span LCD and OLED substrates from Korean and Chinese fabs, aluminum housing extrusions, and power management semiconductors. Single-source vulnerability sits with Google for Android TV OS certification authority. Distribution runs through Amazon and Flipkart direct-to-consumer channels in price-transparent markets, with Best Buy and MediaMart anchoring premium-tier retail placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware-software bundling economics now favor vendors capturing cloud gaming subscription revenue shares over pure device margins, as NVIDIA GeForce NOW and Xbox Cloud Gaming attach rates climb faster than replacement cycle hardware sales.
For Market Incumbents: Shield installed base relationships through backward integration into SoC validation capabilities that compress Google certification cycles. Prioritize hospitality channel lock-in via unified content management platform certification before property technology integrators consolidate vendor panels. Samsung Electronics and TCL Electronics must defend against streaming stick substitution by accelerating AI-enabled feature differentiation.
For New Entrants and Emerging Players: Google's Android TV OS certification fast-track for hospitality-optimized firmware builds offers the most penetrable entry vector. Target cruise line and boutique hotel segments where procurement specifications remain fragmented against Marriott and Royal Caribbean standardization. Lead with edge-based AI recommendation engines that eliminate cloud dependency for bandwidth-constrained maritime deployments.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors contract assemblers with captive Indian PLI scheme access and Google certification engineering depth over pure panel manufacturers. Long-term viability rests on service revenue attachment models rather than hardware shipment volumes. Watch cloud gaming platform certification announcements as inflection indicators for SoC vendor valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Google Certification Fast-Track Investment | Compresses 4-8 month validation cycles that currently freeze OEM inventory planning and marketing coordination. |
| Hospitality Content Management Platform Partnership | Locks in recurring hardware refresh demand from Marriott and Royal Caribbean standardization mandates. |
| Cloud Gaming Service Bundling Agreement | Attaches NVIDIA GeForce NOW or Xbox Cloud Gaming subscription revenue shares to hardware shipments. |
| EU Green Deal Ecodesign Compliance Program | Unlocks preferential retail placement at MediaMarkt and Saturn through standby power threshold certification. |
| On-Device AI NPU Integration | Differentiates premium tier hardware in Singapore and Bangkok hospitality markets through offline functionality. |
Study Parameters
A standing panel of Android TV OEM product managers, hospitality technology integrators, semiconductor validation engineers, and Indian PLI scheme facility operators provided ongoing calibration against shipment and certification timeline data. Primary interviews combined with secondary validation from FCC equipment authorization filings, EU Ecodesign directive compliance registries, MIIT network access license disclosures, and Indian DGFT electronics export statistics. Bottom-up triangulation across SoC vendor shipment disclosures and top-down reconciliation against panel fab utilization rates anchored volume estimates.
Consistency checks validated outputs against external benchmarks including hyperscaler Android TV device deployment disclosures and hospitality property technology procurement databases. The analytical framework modeled segmentation across product type, display technology tier, end-user application, and distribution channel throughout the forecast period. CAGRs derived from logistic adoption curve fitting to smart TV replacement cycle data and hospitality deployment mandate schedules. Industry-specific inputs included Google certification queue depth estimates and AV1 hardware decode penetration curves.
Underlying assumptions cover Google maintaining current Android TV OS certification timelines, Indian PLI scheme subsidy continuity, and panel cost normalization from LCD-OLED supply rebalancing, with deviation risk concentrated in regulatory fragmentation for content security modules and hospitality procurement consolidation velocity. Revision becomes warranted when cloud gaming platform certification standards cross hardware performance thresholds that trigger SoC vendor selection disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Latin America Video Conferencing Hardware Market
Others
Internet of Things Testing Market
Others
Disposable Non Woven Sponge Market
Others
Consumer Video Feedback Software Market
Others
Global Hardware Acceleration Market
Others
Language Translation Device Market
Others
Global Virtual Keyboard Market
Others
Lychee Market
Others
Brazil Cane Sugar Market
Others
Aircraft Cameras Market
Others
Cloud Broadcasting Solutions Market
Others
8K Technology Market
Others
Triathlon Clothing Market
Others
Couscous Market
Others
Biopharma Plastics Market
Others
Industrial Computers Market