
 Europe Transportation Management Systems Market | 2026-2036
Europe Transportation Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Transportation Management Systems Market Intelligence
Freight brokerage networks across the Rhine-Alpine corridor are reshaping how European shurers procure TMS platforms. SAP anchors its position through deep ERP integration with logistics modules that dominate German manufacturing supply chains. Oracle competes via cloud-native architecture that extends across multi-modal European networks. BluJay Solutions specializes in customs compliance layers that navigate post-Brexit trade complexity between the UK and EU member states.
Transportation Management Systems constitute software platforms that optimize freight movement through real-time visibility, carrier selection algorithms, and cost-minimization engines operating across road, rail, sea, and air modalities. These systems integrate with warehouse management and enterprise resource planning software to synchronize inventory positioning with transit schedules across complex supply chains. Cloud-based deployment leads adoption as European mid-market logistics service providers seek scalable infrastructure without capital-intensive on-premises installations. Artificial Intelligence and Machine Learning solutions within route optimization and predictive analytics are expanding fastest, driven by fuel cost volatility and customer demands for accurate delivery windows. On-premises installations retain share among pharmaceutical end users with stringent data residency requirements under GDPR and national health authority protocols.
The EU Green Deal's emissions reporting standards, enforced through national environmental agencies, compel manufacturers to deploy carrier management modules with carbon accounting capabilities. The CSRD mandates granular supply chain disclosures that drive demand for blockchain-enabled freight audit trails across European logistics service providers. EMA pharmaceutical distribution guidelines and GDPR data protection rules create dual compliance burdens that shape solution architecture for life science end users. Stakeholders must weigh cloud migration timelines against evolving EU AI Act risk classifications for automated routing decisions.
Market Dynamics
The EU Green Deal's emissions tracking mandates are forcing freight operators to rebuild their technology stacks around carbon accounting modules, compressing procurement timelines for integrated platforms that unify route optimization with regulatory reporting.
Growth Catalysts
- CSRD Supply Chain Disclosures:The Corporate Sustainability Reporting Directive mandates granular freight audit trails across European logistics service providers, accelerating demand for blockchain-enabled TMS architectures that capture carrier emissions data at the shipment level.
- Rhine-Alpine Manufacturing Clusters:Dense automotive and chemical production corridors spanning Germany, Switzerland, and northern Italy generate concentrated multi-modal freight volumes that reward real-time visibility investments.
- Cloud-Native Deployment Models:Mid-market third-party logistics providers across France and the Netherlands are abandoning on-premises infrastructure for scalable SaaS platforms that eliminate capital-intensive server maintenance.
Market Restraints
- GDPR Data Residency Requirements:Life science distributors face strict patient data localization rules that block cloud migration for temperature-controlled pharmaceutical shipments, preserving legacy on-premises installations.
- Legacy ERP Integration Debt:German manufacturing supply chains built on decades-old SAP R/3 instances confront expensive middleware development to connect modern TMS APIs with rigid core systems.
- Skilled Technical Labor Scarcity:Shortages of supply chain engineers with dual competencies in transportation optimization and EU regulatory compliance extend implementation timelines for complex multi-modal deployments.
Strategic Opportunities
- Post-Brexit Customs Automation:UK-EU trade friction creates urgent demand for TMS modules that automate customs documentation and duty calculations for cross-Channel freight flows.
- Predictive Analytics Convergence:Machine learning models for demand forecasting are merging with dynamic routing engines, enabling logistics providers to pre-position inventory before order spikes materialize.
- Eastern European Fleet Digitization:Polish and Romanian road haulage operators remain underpenetrated by TMS platforms, presenting expansion targets for vendors with localized language support and regional carrier networks.
Industry Challenges
- EU AI Act Risk Classification:Automated routing algorithms that optimize carrier selection face evolving regulatory scrutiny under emerging artificial intelligence governance frameworks, forcing vendors to build explainability features and human oversight protocols.
- Multi-Modal Data Fragmentation:Rail operators, barge networks, and short-sea shipping lines across the Benelux region maintain incompatible data standards that complicate end-to-end visibility for intermodal freight planners.
- Pharmaceutical Validation Protocols:EMA distribution guidelines require extensive software validation documentation that extends TMS deployment cycles for cold chain logistics providers by twelve to eighteen months.
Report Scope
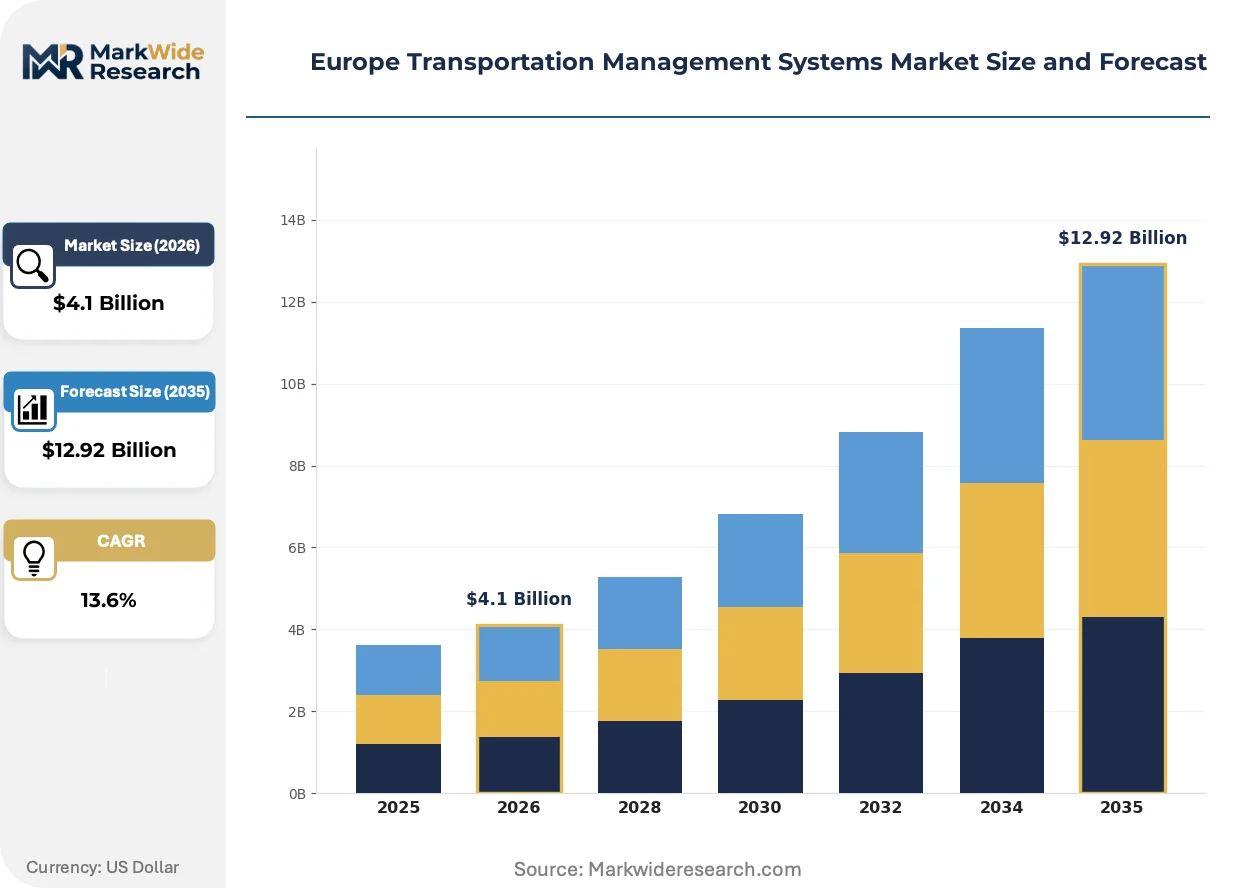
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Transportation Management Systems Market |
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $12.92 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premises, Hybrid, Multi-tenant End User: Retail, Logistics Service Providers, Manufacturing, Pharmaceutical Solution: Route Optimization, Freight Management, Carrier Management, Predictive Analytics Technology: IoT, Artificial Intelligence, Blockchain, Machine Learning |
| Companies Covered | Descartes Systems Group, MercuryGate, SAP, JDA Software, BluJay Solutions, Oracle, Trimble, Infor, Manhattan Associates, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Transportation Management Systems Market Strategic Shifts & Innovations
Artificial intelligence is embedding deeper into transportation execution layers, shifting competitive advantage from static optimization toward predictive systems that anticipate disruption before it cascades through multi-modal networks.
Digital twin technology is digitizing physical freight networks into virtual replicas that simulate lane congestion, port delays, and weather impacts before dispatch decisions finalize. Chemical manufacturers operating through Rotterdam-Antwerp port complexes deploy these simulations to stress-test routing alternatives against EU emissions budgets. The technology is digitizing how large shurers negotiate annual carrier contracts by replacing historical lane averages with dynamic scenario modeling.
The EU AI Act's risk-based classification framework is reclassifying automated dispatch systems as high-risk applications subject to conformity assessments and algorithmic transparency requirements. Logistics software vendors must now embed audit logging and human-in-the-loop checkpoints into routing engines that previously operated autonomously. German freight forwarders with significant contract logistics exposure are front-loading compliance investments to avoid operational shutdowns during enforcement phase-in.
Shipper procurement teams are consolidating vendor relationships around platforms that bundle TMS execution with freight payment and audit capabilities, displacing standalone point solutions. Retailers operating seasonal import programs through Mediterranean ports now prioritize integrated suites that close the loop between transportation spend and accrual accounting. This vendor consolidation is most visible among Dutch omnichannel distributors managing complex reverse logistics flows for e-commerce returns.
Europe Transportation Management Systems Market Segmentation
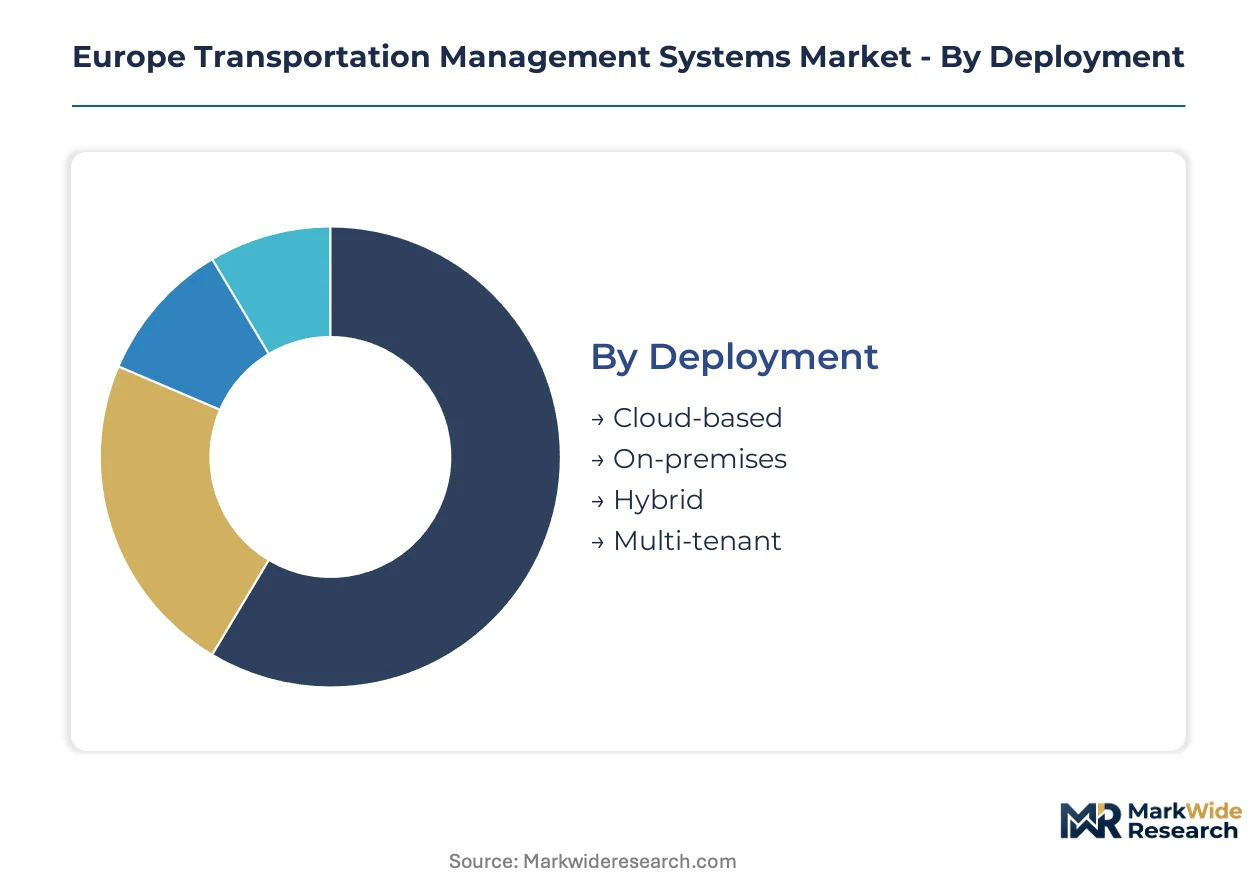
European TMS procurement patterns diverge sharply across deployment models, end-user industries, and technology layers. Procurement cycles for cloud-based solutions run 3-6 months versus 18-24 months for validated pharmaceutical installations. Understanding these structural differences shapes vendor pricing and implementation strategies.
Deployment:
Cloud-based deployments turn over fastest with 12-18 month contract renewals, while on-premises installations lock capital for 5-7 year depreciation cycles. Hybrid and multi-tenant models occupy intermediate positions with 2-3 year refresh timelines.
- Cloud-based:SaaS architectures eliminate server maintenance burdens for mid-market logistics providers across France and the Netherlands. Dutch third-party logistics operators are migrating entire carrier networks to cloud-native platforms to satisfy CSRD audit trail requirements without infrastructure capital.
- On-premises:Licensed software installed within client data centers serves pharmaceutical distributors bound by GDPR patient data localization and EMA validation protocols. German cold chain operators retain these installations for temperature-controlled shipments where cloud data residency triggers regulatory rejection.
- Hybrid:Split architectures maintain sensitive planning data on local servers while pushing execution layers to cloud infrastructure. This configuration appeals to automotive manufacturers in Stuttgart and Munich balancing IP protection with real-time carrier connectivity.
- Multi-tenant:Shared infrastructure models reduce per-seat costs for freight brokerages serving Rhine-Alpine corridor manufacturing clusters. Belgian logistics cooperatives deploy these platforms to pool TMS investments across member hauliers with overlapping lane coverage.
On-premises systems dominate installed base among life science distributors with validation requirements. Cloud-based deployment is where expansion concentrates as mid-market providers abandon capital-intensive infrastructure.
End User:
Cost tier segmentation reveals sharp procurement capability gaps. Retail and logistics service providers operate on thin margins demanding rapid ROI, while pharmaceutical and advanced manufacturing budgets accommodate 18-month implementation horizons.
- Retail:Omnichannel distributors managing seasonal import surges through Mediterranean ports require TMS platforms with reverse logistics modules for e-commerce returns. Spanish and Italian fashion retailers prioritize carrier selection algorithms that compress last-mile delivery windows during promotional peaks.
- Logistics Service Providers:Third-party freight operators serving multi-client networks need scalable platforms that segregate shipper data while pooling carrier relationships. Dutch and German contract logistics providers are consolidating around integrated suites bundling execution with freight audit capabilities.
- Manufacturing:Automotive and chemical producers along the Rhine-Alpine corridor generate concentrated multi-modal volumes rewarding real-time visibility investments. Swiss precision manufacturers demand TMS-ERP synchronization that aligns component deliveries with just-in-sequence production schedules.
- Pharmaceutical:EMA distribution guidelines mandate extensive software validation documentation extending deployment cycles. Temperature-controlled logistics providers serving Benelux distribution hubs face dual compliance burdens from GDPR data rules and pharmaceutical serialization requirements.
Manufacturing anchors current installed value given complex ERP integration requirements. Logistics service providers represent the steepest expansion trajectory as CSRD disclosure rules force technology stack rebuilds.
Solution:
Application maturity varies dramatically. Route optimization and freight management constitute established procurement categories with standardized RFP processes, while predictive analytics and advanced carrier management remain emerging investment priorities.
- Route Optimization:Algorithms calculating least-cost paths across road, rail, and short-sea combinations incorporate real-time traffic and port congestion data. German chemical shippers operating through Rotterdam-Antwerp complexes deploy these engines to stress-test alternatives against EU emissions budgets.
- Freight Management:Core execution modules handling shipment tendering, carrier communication, and delivery confirmation anchor most TMS installations. French retail distributors rely on these systems to manage peak season capacity allocation across competing carrier networks.
- Carrier Management:Performance scorecards and contract compliance tools are gaining priority as EU Green Deal emissions tracking mandates require granular carrier emissions data. Logistics providers are rebuilding procurement workflows around carbon-accounting-enabled selection criteria.
- Predictive Analytics:Machine learning models anticipating demand spikes and disruption cascades are merging with dynamic routing engines. Benelux omnichannel operators pre-position inventory based on algorithmic demand signals before order materialization.
Freight management holds dominant installed base across European logistics networks. Predictive analytics is where capability investments concentrate as fuel volatility and customer delivery precision demands intensify.
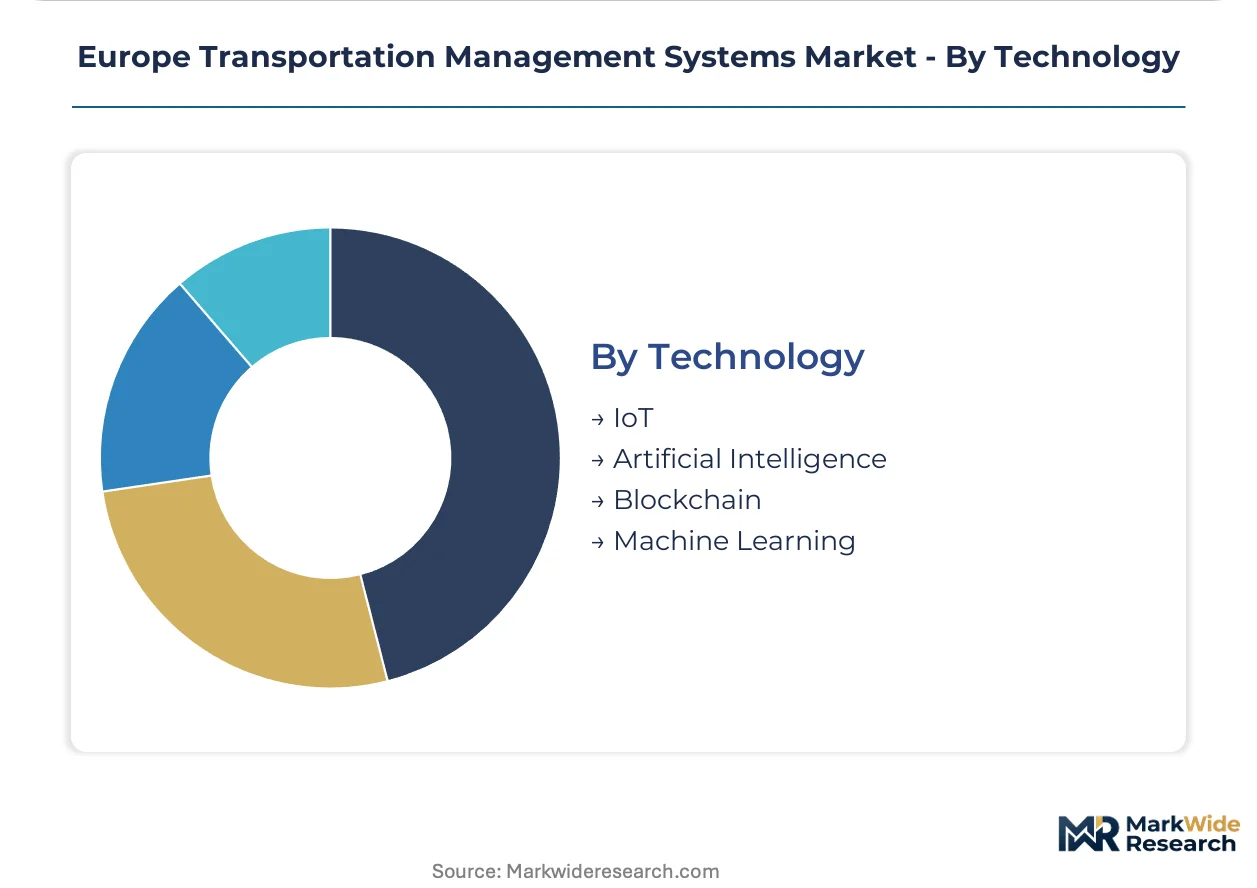
Technology:
Technology layer segmentation tracks vendor R&D allocation and implementation complexity. IoT and blockchain deployments require extensive hardware and integration investment, while AI and machine learning layers embed incrementally into existing platforms.
- IoT:Sensor networks providing real-time location, temperature, and shock monitoring for high-value shipments demand edge computing infrastructure. Pharmaceutical cold chain operators across Germany and Switzerland deploy these layers for EMA-compliant distribution documentation.
- Artificial Intelligence:Automated dispatch and carrier selection systems face emerging EU AI Act risk classifications requiring conformity assessments. German freight forwarders are front-loading explainability features and human-in-the-loop checkpoints to preempt operational shutdowns.
- Blockchain:Distributed ledger architectures creating immutable freight audit trails satisfy CSRD supply chain disclosure requirements. Logistics service providers serving UK-EU post-Brexit trade corridors use these layers for customs documentation verification.
- Machine Learning:Pattern recognition engines refining route algorithms through historical performance data represent the most penetrated advanced technology layer. Polish and Romanian fleet operators are adopting these capabilities through vendor-managed SaaS models without internal data science teams.
Machine learning dominates current technology deployment given its incremental integration path. Blockchain is where compliance-driven expansion concentrates as CSRD and post-Brexit customs requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German manufacturing corridors where ERP integration demands command premium deployment fees, while Polish and Romanian road haulage markets absorb standardized SaaS tiers at compressed margins.
Germany
Automotive and chemical clusters along the Rhine-Alpine corridor drive multi-modal TMS procurement with complex just-in-sequence synchronization requirements. The KBA enforces commercial vehicle telematics standards that shape fleet connectivity specifications. Stuttgart and Munich anchor demand for hybrid deployment models balancing IP protection with real-time carrier integration.
Netherlands
Rotterdam-Antwerp port complexes generate concentrated freight volumes demanding digital twin simulations for emissions budgeting. The EU Green Deal enforcement through national environmental agencies compels carbon accounting module adoption. Dutch third-party logistics operators in the Randstad are migrating entire carrier networks to cloud-native platforms for CSRD compliance.
France
Omnichannel retail distributors managing Mediterranean import surges prioritize reverse logistics modules for e-commerce returns. The CNIL interprets GDPR data localization rules that constrain pharmaceutical cloud migrations. Paris and Lyon fashion retailers deploy carrier selection algorithms compressing last-mile windows during promotional peaks.
United Kingdom
Post-Brexit customs friction creates urgent demand for TMS modules automating cross-Channel documentation and duty calculations. HMRC reporting requirements intersect with EU customs systems for hybrid trade flows. London freight forwarders rebuild technology stacks around blockchain-enabled audit trails for dual-jurisdiction compliance.
Switzerland
Swissmedic pharmaceutical distribution guidelines impose validation protocols extending TMS deployment cycles for cold chain operators. Precision manufacturers in Basel and Zurich demand TMS-ERP synchronization aligning component deliveries with production schedules. The country maintains stringent data residency requirements preserving on-premises installations for temperature-controlled shipments.
Europe Transportation Management Systems Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with narrower functional scope. The vendor base organizes around three tiers: ERP-native suites with deep manufacturing integration, cloud-native architectures serving multi-modal networks, and compliance-layer specialists navigating customs complexity. Consolidation pressure intensifies as shippers bundle freight payment and audit capabilities into single-vendor relationships. Strategic moves center on geographic expansion into Eastern European fleet digitization and AI explainability investments preempting EU Act enforcement.
Within the ERP-native tier, SAP and Oracle occupy positions defined by manufacturing supply chain anchoring and cloud architecture extensibility respectively. BluJay Solutions exemplifies the compliance-specialist archetype, sitting within the segment addressing post-Brexit trade friction through customs documentation automation.
| Leading Market Players |
|---|
| Descartes Systems Group |
| MercuryGate |
| SAP |
| JDA Software |
| BluJay Solutions |
| Oracle |
| Trimble |
| Infor |
| Manhattan Associates |
| Others |
Cost & Logistics Intelligence
Undercapacity in cloud-native TMS engineering talent across the Benelux and Rhine-Alpine corridor is compressing implementation timelines while inflating deployment premiums for configured solutions. German automotive manufacturers absorb these premiums to secure hybrid architectures that synchronize just-in-sequence production with real-time carrier networks.
Pricing Analysis
The customization-premium spread separates standard SaaS tiers from configured deployments integrating legacy SAP R/3 instances. Subscription-based SaaS pricing dominates mid-market logistics providers, while project-based licensing persists for pharmaceutical validations requiring EMA-compliant documentation. Price differentiation hinges on ERP integration depth and GDPR data residency certification. Pricing pressure stems from cloud-native entrants undercutting on-premises maintenance contracts. Retail distributors exhibit highest price sensitivity, while life science operators accept extended payback periods for validated installations.
Supply Chain Analysis
Contract manufacturing concentration in TMS hardware and edge-computing infrastructure rests on German industrial automation specialists, Taiwanese semiconductor foundries, and Dutch IoT sensor manufacturers. Software development draws from Indian engineering centers, Polish technical hubs, and Western European regulatory compliance boutiques. Supply chain risk centers on single-source vulnerability for specialized pharmaceutical validation documentation. Distribution runs through direct vendor-shipper relationships for enterprise deployments and channel partners for mid-market SaaS adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe TMS market is recovering from cyclical compression in logistics capital expenditure, with freight volume stabilization through Rotterdam-Antwerp and Hamburg port complexes signaling renewed procurement activity.
For Market Incumbents: Insulate core manufacturing relationships by deepening SAP ERP integration investments in Stuttgart and Munich automotive clusters. Prioritize explainability feature development to preempt EU AI Act enforcement against automated routing algorithms. Acquire specialized customs compliance capabilities to defend against post-Brexit trade friction specialists. For New Entrants and Emerging Players: Polish and Romanian road haulage underpenetration offers white-space expansion with localized language support and regional carrier network partnerships. Target freight brokerages serving Eastern European manufacturing corridors with multi-tenant SaaS platforms. Pursue vendor consolidation opportunities among Dutch omnichannel distributors seeking bundled freight audit capabilities. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native TMS providers serving logistics service providers with CSRD compliance mandates. Long-term viability favors platforms with embedded carbon accounting and blockchain audit trail architectures. Monitor EU AI Act implementation timelines as inflection indicators for explainability-focused R&D valuations.| Strategic Initiative | Industry Significance |
|---|---|
| AI Explainability Investment | Preempts EU AI Act enforcement against automated carrier selection algorithms. |
| Carbon Accounting Integration | Aligns TMS platforms with EU Green Deal emissions tracking mandates. |
| Post-Brexit Customs Automation | Captures UK-EU trade friction through automated duty calculation modules. |
| Eastern European Expansion | Addresses underpenetrated Polish and Romanian fleet digitization opportunities. |
| Blockchain Audit Trail Deployment | Satisfies CSRD supply chain disclosure requirements for logistics providers. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EU regulatory filings, customs trade databases, and vendor SEC disclosures. Interviews with logistics CTOs, supply chain directors at automotive OEMs, pharmaceutical distribution managers, and freight brokerage operators inform demand-side validation. Secondary sources include EMA distribution guidelines, CSRD implementation directives, and port authority throughput statistics. Bottom-up deployment counts triangulate against top-down software spending estimates across the analysis window.
Forecast inputs incorporate deployment model adoption curves, regulatory compliance deadline clustering, and ERP integration cycle durations. Segmentation dimensions span deployment architecture, end-user industry vertical, solution layer maturity, and technology stack penetration. CAGRs derive from logistic growth curve fitting against historical procurement patterns. Industry-specific inputs include EU Green Deal enforcement timelines and CSRD disclosure phase-in schedules.
Practitioners should monitor EU AI Act risk classification updates and CSRD audit standard finalization for early signals of demand inflection. Forecasts reflect assumptions regarding cloud migration velocity and pharmaceutical validation backlog clearance. Quarterly review of port throughput indices and logistics employment statistics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Senior Cat Food Market
Others
Water and Waste Water Treatment Chemicals Market
Others
Global Bio-Based Chemicals Market
Others
Europe Street Lighting Market
Others
Asia-Pacific Medium-Density Fiberboard Market
Others
Enterprise Video Market
Others
AI in Precision Medicine Market
Others
Manometers Market
Others
Composite Copper Foil Production Equipment Market
Others
Video Paas Market
Others
Construction Fabrics Market
Others
Griffin Beaker Market
Others
Video-As-A-Service (Vaas) Market
Others
Insoluble Sulfur Market
Others
Dried Egg Market
Others
Binoculars and Mounting Solutions Market