
 Global Computer Peripherals Market | 2026-2036
Global Computer Peripherals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Computer Peripherals Market Foresight
USB-IF certification is reorganizing competitive access in the Global Computer Peripherals Market, forcing manufacturers to validate power-delivery and data-transfer protocols before retail placement. Logitech International S.A. leverages its Swiss engineering heritage to dominate premium wireless input devices across European and North American channels. Razer Inc. specializes in high-refresh-rate gaming peripherals with proprietary optical switches. Kingston Technology Company Inc. sustains its position in enterprise storage peripherals through vertically controlled NAND supply chains.
Computer peripherals comprise external hardware components—keyboards, mice, monitors, external drives, network adapters, and power units—that extend host system functionality through standardized electrical interfaces, typically operating at 5V USB or 48V USB-C Power Delivery with data rates up to 40 Gbps over Thunderbolt 4. These devices enable human-machine interaction, data persistence, network connectivity, and power management across consumer, commercial, and industrial computing environments. Input Devices and Wireless technology segments anchor current revenue pools, while Virtual Reality application peripherals represent the fastest-expanding category as headset and haptic controller shipments accelerate. Gaming and Corporate Enterprises end-user segments concentrate margin capture, with the former commanding premium pricing for low-latency specifications and the latter driving volume through fleet refresh cycles.
FCC equipment authorization in the United States, CE marking under the EU Radio Equipment Directive, and China's MIIT compulsory certification collectively gate market access for wireless peripherals, with electromagnetic compatibility testing adding six to twelve months to product commercialization timelines. The EU's pending USB-C harmonization regulation will eliminate proprietary charging ports on small and medium devices, reshaping power-supply peripheral demand. India's BIS registration order for electronic products is tightening import compliance for foreign manufacturers. Stakeholders must monitor regulatory divergence between major economies as certification fragmentation threatens to segment supply chains and inflate compliance overhead.
Market Dynamics
USB-C interoperability mandates from the European Commission are compressing proprietary connector ecosystems and forcing power-delivery protocol standardization across peripheral categories. This regulatory pressure is redistributing competitive advantage toward manufacturers with certified USB-IF validation capabilities.
Growth Catalysts
- EU USB-C Harmonization:The European Commission's pending regulation eliminating proprietary charging ports on small and medium devices is accelerating power-supply peripheral refresh cycles across consumer electronics.
- Esports Professionalization:Tournament-grade gaming peripherals are commanding premium positioning as competitive gaming leagues standardize equipment specifications for broadcast integrity.
- Thunderbolt 4 Adoption:Intel's 40 Gbps interface specification is displacing legacy USB 3.2 connections in enterprise docking stations and external storage arrays.
Market Restraints
- NAND Flash Volatility:External storage peripheral margins compress when memory contract prices spike, squeezing Kingston Technology and similar vertically integrated suppliers.
- Shenzhen Supply Concentration:Mechanical keyboard switch and sensor module production clusters in Guangdong Province create single-point vulnerability for wireless input device supply chains.
- Electromagnetic Compatibility Testing:FCC equipment authorization and EU Radio Equipment Directive CE marking add six to twelve months to wireless peripheral commercialization timelines.
Strategic Opportunities
- India BIS Registration Gap:Foreign manufacturers facing tightened import compliance under India's Bureau of Indian Standards order can capture share through local certification partnerships and assembly investment.
- Haptic Controller Convergence:Virtual Reality application peripherals integrating force-feedback gloves with spatial tracking hardware represent untapped white space in industrial training simulation.
- Enterprise Fleet Refresh:Corporate procurement departments are consolidating vendor relationships for standardized wireless input device deployments across hybrid work environments.
Industry Challenges
- RF Engineering Talent Scarcity:Wireless peripheral development cycles stall when teams lack expertise in 2.4 GHz and 5 GHz antenna optimization for low-latency gaming specifications.
- Legacy Port Support:Peripheral manufacturers must maintain USB-A backward compatibility while transitioning form factors to USB-C, inflating BOM complexity and inventory SKU proliferation.
- MIIT Certification Backlogs:China's Ministry of Industry and Information Technology compulsory certification queues for wireless devices are extending time-to-revenue for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Computer Peripherals Market |
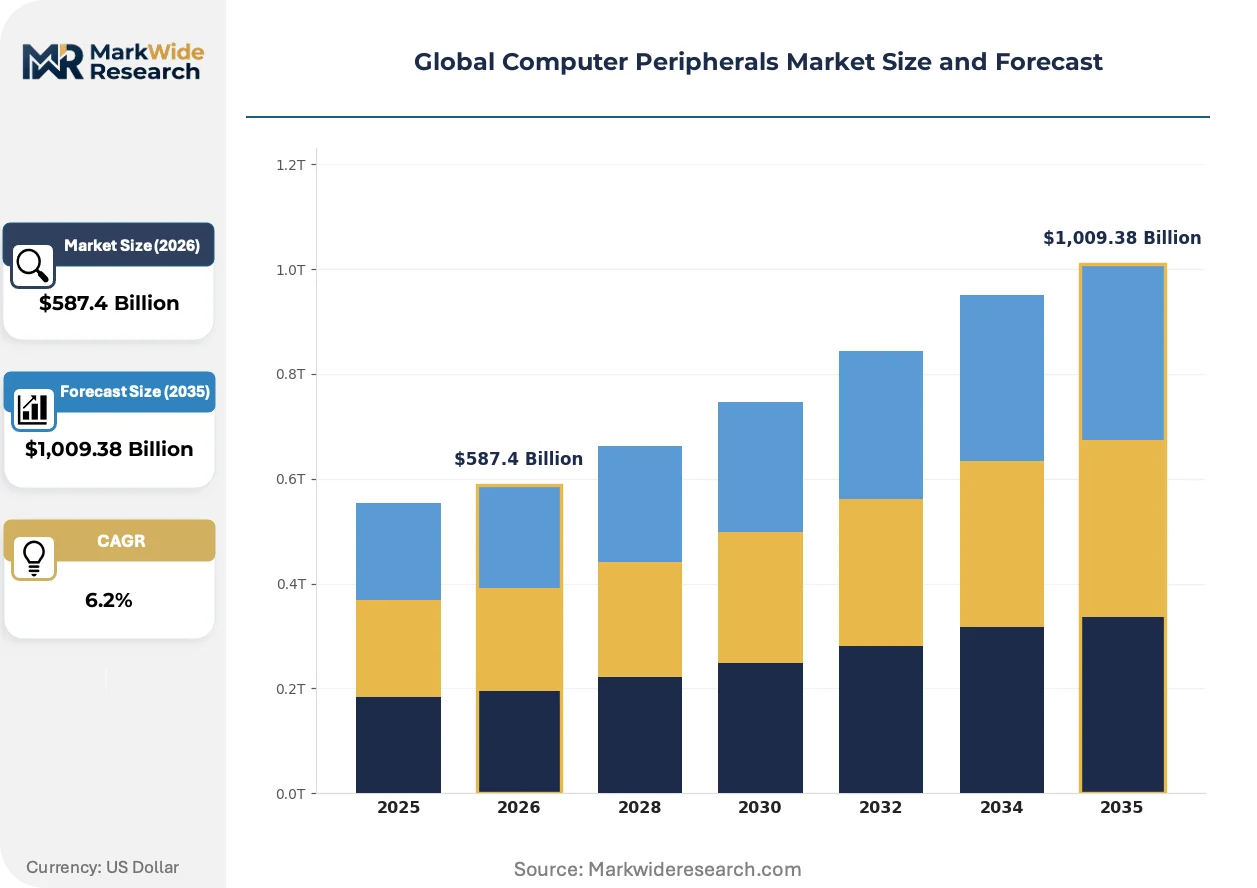
| Market Size in 2026 | $587.4 Billion |
| Market Size in 2035 | $1,009.38 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Input Devices, Output Devices, Storage Devices, Networking Devices, Power Supplies Technology: Wired, Wireless, Bluetooth, USB-C, Optical, Infrared Application: Gaming, Office Work, Graphic Design, Education, Data Center, Virtual Reality End User: Individual Consumers, Small Businesses, Corporate Enterprises, Educational Institutions, Government Agencies |
| Companies Covered | SteelSeries ApS, Cooler Master, Logitech International S.A., Mad Catz Global Limited, Turtle Beach Corporation, Razer Inc., ASUS Republic of Gamers, Kingston Technology Company Inc., Corsair Gaming Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Computer Peripherals Market Shifts & Advancements
Optical switch mechanisms and gallium nitride power delivery are compressing form factors while elevating performance thresholds across input and power peripheral categories. These material and architectural shifts are redistributing value toward semiconductor-integrated designs.
Gallium nitride (GaN) transistors in USB-C power adapters are achieving higher switching frequencies than silicon MOSFET predecessors. Enterprise procurement departments are specifying GaN-based power delivery units for reduced thermal footprint in dense workstation deployments. This semiconductor transition is miniaturizing wall-wart dimensions while maintaining 100W+ output capability.
The EU Radio Equipment Directive's electromagnetic compatibility requirements are tightening spurious emission limits for 2.4 GHz wireless peripherals. Manufacturers are redesigning antenna architectures and shielding enclosures to satisfy updated test protocols. Gaming-grade wireless mice and keyboards face the steepest compliance cost inflation due to their low-latency radio transmission profiles.
Corporate IT departments are unbundling peripheral procurement from OEM system purchases and establishing direct vendor relationships with Logitech and Razer for standardized fleet deployments. This disintermediation of traditional channel distribution is compressing reseller margins while accelerating refresh cycles in North American and German enterprise markets.
Global Computer Peripherals Market Segmentation
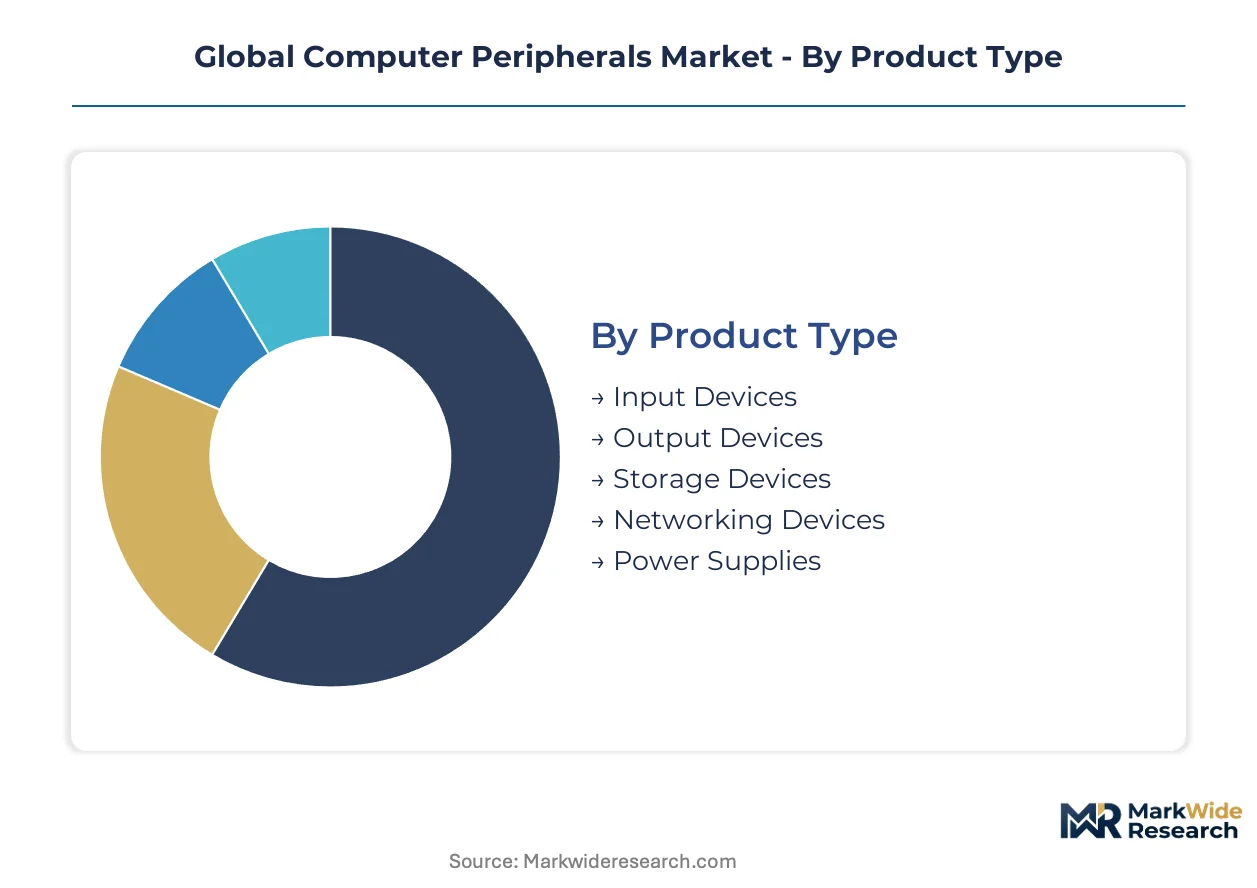
Peripheral manufacturers face diverging substitution pressures across product categories, with wireless technologies displacing wired interfaces and solid-state storage eroding mechanical alternatives. Segmentation clarity determines which R&D investments defend margin pools against functional convergence from adjacent device categories.
Product Type:
Input Devices face the most acute substitution threat from touchscreen and voice-interface technologies embedded directly into host systems, while Power Supplies benefit from connector standardization that extends their relevance across form-factor generations.
- Input Devices:Keyboards, mice, and trackpads translate human tactile action into digital signals through mechanical, membrane, or capacitive switch mechanisms. Corporate procurement departments in Germany and the United States are consolidating wireless input device specifications for hybrid work fleets, driving standardization around 2.4 GHz and Bluetooth protocols.
- Output Devices:Monitors, printers, and speakers render processed data into human-perceptible formats through LCD/OLED panels, inkjet/laser deposition, or electrodynamic transducers. Gaming and graphic design applications in China concentrate demand for high-refresh-rate displays with color-calibration capabilities.
- Storage Devices:External hard drives and solid-state drives provide non-volatile data persistence through magnetic platters or NAND flash arrays. NAND flash contract price volatility directly compresses margins for external SSD suppliers without captive semiconductor supply.
- Networking Devices:Network adapters, routers, and switches extend host connectivity through Ethernet, Wi-Fi, or cellular modems. Enterprise data center buildouts in India and Germany sustain demand for 10GbE and 25GbE peripheral connectivity.
- Power Supplies:USB-C power adapters and uninterruptible power units manage electrical delivery through AC-DC conversion and battery backup architectures. EU USB-C harmonization mandates are accelerating refresh cycles for proprietary connector elimination across consumer electronics.
Input Devices anchors the volume base while Power Supplies gains share at the steepest rate.
Technology:
Cost tier differentiation separates premium RF-engineered wireless implementations from commodity wired alternatives, with certification overhead creating margin stratification across the technology stack.
- Wired:USB-A and USB 2.0/3.2 connections deliver power and data through copper conductors with deterministic latency profiles. Budget-conscious educational institutions in India and government agencies in Germany continue specifying wired peripherals for TCO minimization.
- Wireless:2.4 GHz proprietary protocols enable sub-1ms latency for gaming-grade mice and keyboards through dedicated USB receivers. FCC equipment authorization and EU Radio Equipment Directive CE marking add six to twelve months to commercialization timelines.
- Bluetooth:Standardized 2.4 GHz ISM band protocol enables cross-device pairing without dedicated receivers. Office work applications dominate volume as corporate IT departments specify Bluetooth 5.0+ for multi-device roaming.
- USB-C:Reversible connector with USB-IF certified power delivery up to 240W and data rates to 40 Gbps via Thunderbolt 4. Intel's interface specification is displacing legacy USB 3.2 in enterprise docking stations.
- Optical:Infrared or laser-based sensing for mice and switches eliminates mechanical contact wear. Gaming peripheral specialists leverage optical switch mechanisms for 100-million-click durability ratings.
- Infrared:Line-of-sight wireless communication for remote controls and legacy input devices. Rapidly declining share as radio-frequency alternatives eliminate pointing constraints.
Wired technology maintains the highest shipment volumes while USB-C climbs the fastest as connector standardization accelerates.
Application:
Customer type concentration varies sharply, with Gaming commanding premium pricing for performance specifications and Office Work driving absolute volume through fleet refresh economics.
- Gaming:Tournament-grade peripherals with high-refresh-rate sensors, optical switches, and customizable RGB lighting. Esports professionalization in South Korea and the United States is standardizing equipment specifications for broadcast integrity.
- Office Work:Ergonomic keyboards, precision mice, and dual-monitor setups for productivity optimization. Corporate Enterprises across China and Germany are consolidating vendor relationships for standardized wireless deployments.
- Graphic Design:Color-accurate displays, pressure-sensitive tablets, and wide-gamut monitors for creative workflows. Small design studios in Japan and France drive demand for calibration-certified output devices.
- Education:Ruggedized keyboards, basic mice, and document cameras for classroom deployment. India's BIS registration tightening is filtering import compliance for foreign manufacturers serving this segment.
- Data Center:KVM switches, serial consoles, and remote management peripherals for server infrastructure. Enterprise procurement in the United States specifies IP-based KVM for lights-out facility management.
- Virtual Reality:Head-mounted displays, haptic controllers, and spatial tracking hardware for immersive simulation. Industrial training applications in Germany and Japan represent the steepest expansion trajectory for force-feedback glove integration.
Office Work dominates absolute volume while Virtual Reality expands most quickly as headset shipments accelerate.
End User:
Geography and volume scale differentiate procurement patterns, with Individual Consumers fragmenting across retail channels and Corporate Enterprises consolidating through direct vendor relationships.
- Individual Consumers:Retail-purchased peripherals for home computing, gaming, and personal productivity. E-commerce penetration in China and the United States concentrates demand during promotional calendar events.
- Small Businesses:Cost-optimized peripheral fleets with limited IT support infrastructure. Reseller channel dependence in India and Brazil creates price sensitivity for bundled system purchases.
- Corporate Enterprises:Standardized wireless input device deployments with centralized procurement and helpdesk support. Direct vendor relationships with Swiss and Taiwanese manufacturers are disintermediating traditional distribution in North America.
- Educational Institutions:Volume purchases of ruggedized peripherals with multi-year replacement cycles. India's BIS compulsory registration is tightening import compliance timelines for foreign suppliers.
- Government Agencies:Security-certified peripherals with supply chain provenance requirements and TAA compliance. Federal procurement in the United States specifies domestic assembly for sensitive installations.
Corporate Enterprises anchor procurement volume while Educational Institutions gain share fastest as digital literacy programs expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate procurement departments in Germany, the United States, and China anchor peripheral demand through enterprise fleet refresh cycles. Gaming peripheral consumption concentrates in South Korea and the United States where esports tournament infrastructure drives premium equipment specifications. Manufacturing gravity clusters in Guangdong Province, Shenzhen, and Dongguan supply mechanical switches and sensor modules to global brands.
United States
Enterprise IT departments in Austin, Texas and Seattle, Washington consolidate wireless input device specifications for hybrid work deployments. FCC equipment authorization mandates six to twelve month commercialization timelines for 2.4 GHz gaming peripherals. Silicon Valley engineering teams specialize in low-latency RF protocols for tournament-grade mice and keyboards.
Germany
Industrial training simulation centers in Bavaria and Baden-Württemberg drive haptic controller demand for VR-based workforce development. EU Radio Equipment Directive CE marking tightens electromagnetic compatibility limits on wireless peripheral spurious emissions. Stuttgart automotive suppliers integrate force-feedback peripherals into assembly line digital twin systems.
China
MIIT compulsory certification queues in Beijing extend time-to-revenue for new wireless device introductions. Shenzhen and Dongguan manufacturing clusters produce eighty percent of global mechanical keyboard switches and optical sensor modules. Shanghai enterprise procurement departments specify USB-C power delivery units for dense workstation deployments.
India
Bureau of Indian Standards registration tightening filters import compliance timelines for foreign peripheral manufacturers. Educational institutions in Maharashtra and Karnataka drive volume demand for ruggedized keyboards and basic mice. Delhi-NCR corporate campuses consolidate vendor relationships for standardized wireless fleet deployments.
South Korea
Esports tournament organizers in Seoul standardize equipment specifications for broadcast integrity across professional gaming leagues. METI-aligned technology standards influence peripheral interoperability requirements in adjacent markets. Busan manufacturing facilities supply high-refresh-rate display panels to global gaming monitor brands.
Global Computer Peripherals Market Competitive Landscape
Player mix skews toward specialized gaming peripheral houses with RF engineering capabilities and diversified electronics conglomerates with captive semiconductor supply. Market structure concentrates premium positioning around Swiss and Taiwanese engineering heritage while commodity tiers fragment across Shenzhen-based contract manufacturers. Two strategic archetypes dominate: vertically integrated semiconductor suppliers controlling NAND flash supply chains, and gaming-focused specialists leveraging proprietary optical switch IP. Competitive moves center on USB-IF certification pre-positioning ahead of EU harmonization deadlines and RF engineering talent acquisition for sub-1ms latency specifications.
Within the diversified technology tier, Logitech International S.A. and Kingston Technology Company Inc. exemplify scale-driven positioning across enterprise and consumer channels. Razer Inc. anchors the gaming-specialist archetype with tournament-grade peripheral focus. SteelSeries ApS occupies a position in the premium gaming peripheral segment. These three companies represent contrasting strategic postures: Swiss-engineered wireless input dominance, vertically integrated storage peripheral supply, and esports-native brand cultivation.
| Leading Market Players |
|---|
| SteelSeries ApS |
| Cooler Master |
| Logitech International S.A. |
| Mad Catz Global Limited |
| Turtle Beach Corporation |
| Razer Inc. |
| ASUS Republic of Gamers |
| Kingston Technology Company Inc. |
| Corsair Gaming Inc. |
| Others |
Supply & Pricing Matrix
Eighty percent mechanical switch production capacity utilization in Guangdong Province compresses margin floors for wireless input device manufacturers while concentrating bargaining power among Shenzhen-based sensor module suppliers. USB-IF certification costs and FCC electromagnetic compatibility testing create tiered entry barriers that stratify pricing power across premium RF-engineered and commodity wired peripheral tiers.
Pricing Analysis
NAND flash indexation in external storage contracts ties peripheral margins to memory spot price volatility, with Kingston Technology and similar suppliers absorbing cost spikes through captive semiconductor supply. Three-tier pricing structure across premium, standard, and economy levels separates USB-C Power Delivery certified adapters from legacy USB-A alternatives and unbranded Shenzhen imports. Cost compression in entry-level wireless mice intensifies as Bluetooth 5.0 module commoditization accelerates. Educational institutions in India exhibit highest price sensitivity for ruggedized keyboard fleets, while esports tournament organizers in South Korea accept premium positioning for sub-1ms latency specifications.
Supply Chain Analysis
China, Taiwan, and Vietnam anchor global peripheral manufacturing, with Dongguan mechanical switch foundries, Taoyuan RF semiconductor packaging, and Ho Chi Minh City cable assembly feeding finished goods to brand houses. GaN transistor and optical sensor IC supply draws from Taiwan Semiconductor and similar foundry capacity. Single-source vulnerability concentrates in Guangdong Province switch production clusters. Distribution runs through direct enterprise procurement relationships disintermediating traditional reseller channels in North America and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
USB-C harmonization mandates fragment competitive access by certification tier, creating niche opportunities for USB-IF validated specialists and regional compliance partners as procurement departments unbundle from OEM system purchases.
For Market Incumbents: Shield premium positioning by deepening USB-IF certification pre-positioning ahead of EU enforcement deadlines, while consolidating RF engineering talent pools against new entrant poaching in Taiwan and South Korea. Acquire haptic controller startups in Germany and Japan to defend margin pools against VR peripheral convergence from adjacent simulation hardware categories. For New Entrants and Emerging Players: Anchor in India's BIS registration gap through local assembly partnerships serving educational institutions in Maharashtra and Karnataka, where foreign manufacturer compliance tightening creates procurement friction. Target enterprise fleet refresh cycles in Austin and Seattle with white-label wireless input device specifications tailored to hybrid work security requirements. For Investors and Strategic Acquirers: GaN power delivery specialists with captive semiconductor relationships represent priority acquisition targets as enterprise procurement specifies thermal-efficient USB-C adapters for dense workstation deployments. Monitor EU Radio Equipment Directive spurious emission limit enforcement as inflection signal for wireless peripheral compliance cost inflation and RF engineering capability scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| USB-IF Certification Pre-Positioning | Validates power-delivery protocols ahead of EU harmonization deadlines, securing retail placement. |
| RF Engineering Talent Acquisition | Secures sub-1ms latency development capability for tournament-grade gaming peripheral specifications. |
| GaN Semiconductor Integration | Miniaturizes USB-C adapter form factors while maintaining 100W+ output for enterprise dense deployments. |
| India Local Assembly Investment | Accelerates BIS compliance timelines for educational institution and corporate fleet procurement. |
| Haptic Controller Convergence | Integrates force-feedback gloves with spatial tracking for industrial training simulation in Germany. |
Research Methodology
Initial hypotheses were tested against primary input from peripheral procurement managers, RF engineering directors, USB-IF certification leads, and esports tournament operators and refined through secondary validation. Primary fieldwork encompassed enterprise IT departments in Austin, Seattle, and Shanghai, gaming peripheral specialists in Seoul and Taipei, and Shenzhen contract manufacturers. Secondary sources included FCC equipment authorization databases, EU Radio Equipment Directive CE marking registries, MIIT compulsory certification filings, and trade flow records from India's DGFT. Bottom-up shipment modeling triangulated against top-down market sizing across technology and application segments.
Variance decomposition across the projection horizon isolates volume drivers by product type, technology protocol, end-user procurement pattern, and regional regulatory cluster. CAGRs derive from segment-level growth rate synthesis anchored to USB-C adoption curves, esports viewership expansion, and enterprise hybrid work fleet refresh economics. Forecast inputs incorporate NAND flash contract price trajectories, Thunderbolt 4 port penetration in enterprise docking stations, and BIS registration timeline assumptions for India market access.
Decision-makers should treat outputs as directional under assumptions of EU USB-C harmonization enforcement timing and sustained NAND flash supply elasticity; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
China Online Gambling Market
Others
Bio-Based Leather Market
Others
Latin America IT Device Market
Others
Embedded Computer Market
Others
Brazil Cane Sugar Market
Others
Ceramic Machinery Market
Others
Japan 3D Printing Construction Market
Others
Chip Card Scanners Market
Others
Global Bio-Based Chemicals Market
Others
Education and Learning Analytics Market
Others
Griffin Beaker Market
Others
Industrial Wearable Devices Market
Others
Communication Base Station Body Market
Others
Asia-Pacific Programmatic Display Advertising Market
Others
Rotary Evaporators Market
Others
Heat Treatment Furnace Market