
 Veterinary Disinfectant for Pets and Farms Market | 2026-2036
Veterinary Disinfectant for Pets and Farms Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Disinfectant for Pets and Farms Market Analytics
Intensive livestock farming is expanding as a share of disinfectant consumption, displacing traditional smallholder veterinary applications. Kersia Group leverages its dairy and poultry hygiene heritage to dominate European farm biosecurity programs. Neogen Corporation anchors North American supply through its food safety and animal health distribution network. Zoetis Inc. competes by extending its veterinary pharmaceutical channel into companion animal clinic disinfection protocols.
Veterinary disinfectant for pets and farms comprises antimicrobial formulations engineered to eliminate bacterial, viral, and fungal pathogens from animal housing, equipment, and clinical surfaces, typically containing quaternary ammonium compounds, chlorine derivatives, phenolics, or iodophors at concentrations between 0.5% and 5% active ingredient. These products serve to prevent zoonotic transmission, secure food chain safety, and maintain regulatory compliance in production animal facilities. Liquid formulations lead volume due to dilution flexibility and spray application compatibility, while quaternary ammonium compounds capture the fastest growth trajectory as producers seek lower-corrosion alternatives to chlorine. Surface disinfection generates the largest revenue pool, though water treatment applications in poultry and swine operations are deepening as recirculating systems expand.
The EPA regulates veterinary disinfectant efficacy claims and environmental toxicity profiles in the United States, while REACH governs chemical registration and biodegradability thresholds across European Union member states. Brazil's ANVISA and China's MEE impose parallel residue monitoring and import licensing requirements that shape product registration timelines and formulation choices. Stakeholders must monitor evolving biocide authorization timelines, as regulatory delays in major protein-producing jurisdictions directly compress commercialization windows and redistribute competitive advantage toward registrants with established dossier capabilities.
Market Dynamics
Biosecurity protocol intensification across commercial livestock operations is compressing purchasing cycles and consolidating procurement authority into vertically integrated protein producers, fundamentally altering how veterinary disinfectants flow from formulation to farm application.
Growth Catalysts
- African Swine Fever Containment Mandates:Outbreak-driven culling protocols across Southeast Asia and Eastern Europe are mandating perimeter disinfection infrastructure at all commercial swine facilities, creating baseline demand floors for virucidal formulations.
- REACH Biocide Authorization Timelines:The European Union's phased reauthorization of quaternary ammonium compounds under BPR is accelerating pre-registration investments by suppliers seeking grandfathered market access.
- Recirculating Aquaculture Systems:Water treatment applications in intensive salmon and shrimp farming are expanding disinfectant dosing points beyond surface cleaning into continuous flow systems.
Market Restraints
- Active Ingredient Supply Concentration:China controls approximately three-quarters of global quaternary ammonium compound intermediate production, exposing formulators to export license volatility and shipping corridor disruptions.
- Corrosion Limitations of Chlorine Derivatives:Sodium hypochlorite formulations degrade stainless steel drinking systems in poultry houses, restricting deployment in facilities with capital-intensive automated watering infrastructure.
- EPA Registration Timelines:New chemical entity approvals for veterinary disinfectant claims currently average thirty-six months, compressing commercialization windows for novel antimicrobial mechanisms.
Strategic Opportunities
- Brazil's Poultry Belt Expansion:Mato Grosso and Paraná states are adding integrated broiler capacity at rates exceeding domestic disinfectant supplier coverage, creating import substitution openings for registered foreign formulations.
- Peroxyacetic Acid-Chlorine Dioxide Convergence:Combined dosing systems for biofilm removal in swine farrowing crates are enabling premium pricing for dual-mechanism chemistries previously deployed separately.
- Veterinary E-Commerce Direct Channels:Farm supply cooperatives in the United States are bypassing traditional distributor markups through platform procurement, rewarding suppliers with digital dossier capabilities and same-fulfillment logistics.
Industry Challenges
- Field Efficacy Validation Talent Scarcity:Qualified microbiologists capable of designing GLP-compliant challenge studies for novel pathogen claims command compensation premiums that mid-tier formulators struggle to absorb.
- Legacy Equipment Compatibility Testing:Disinfectant suppliers must maintain testing protocols across three decades of housing infrastructure variations, from galvanized steel nipple drinkers to polymer-based slatted flooring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Disinfectant for Pets and Farms Market |
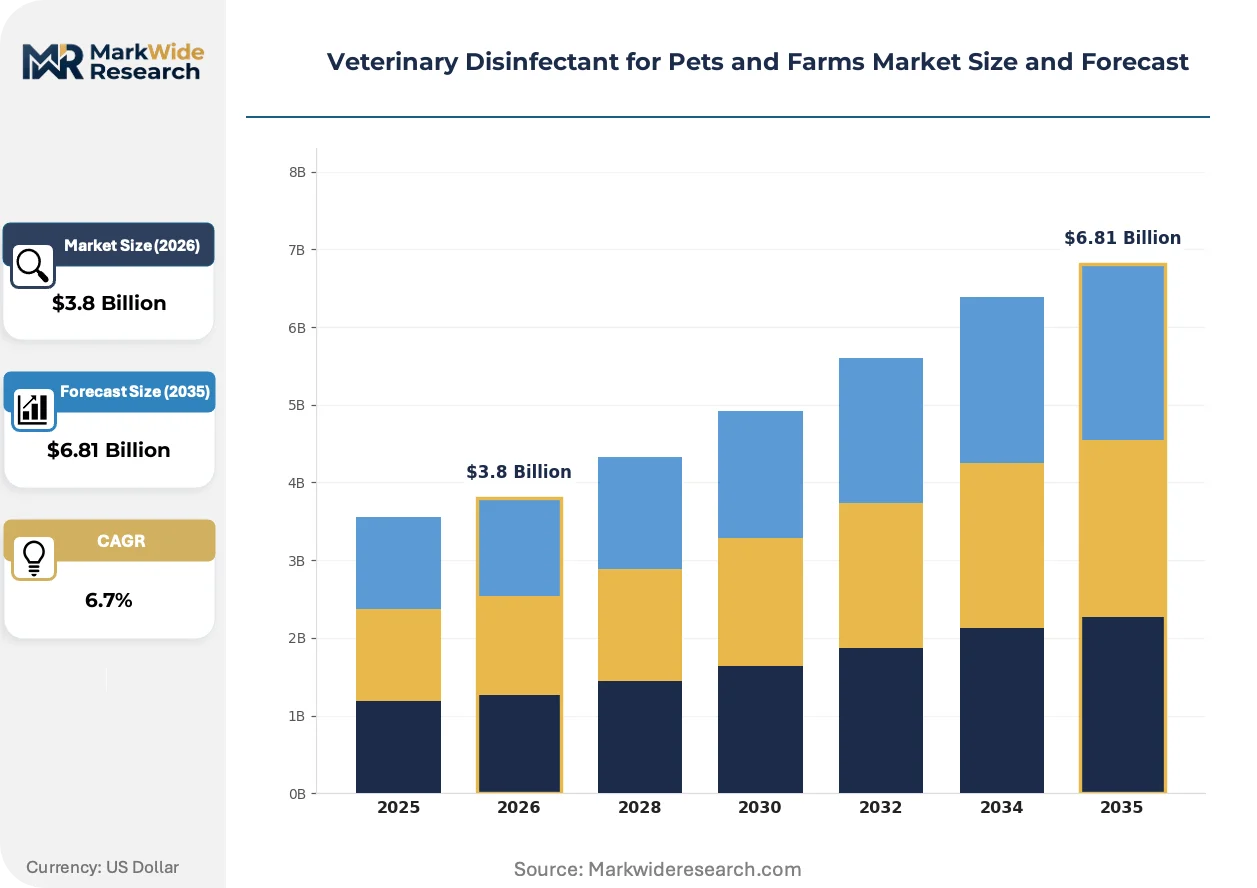
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Foam, Spray Application: Surface Disinfection, Equipment Cleaning, Water Treatment, Hygiene Maintenance End User: Veterinary Clinics, Animal Shelters, Livestock Farms, Pet Owners Active Ingredient: Quaternary Ammonium Compounds, Chlorine Compounds, Phenolics, Iodophors |
| Companies Covered | Kersia Group, Ceva Santé Animale, Neogen Corporation, Virbac SA, Vetoquinol SA, Zoetis Inc., Ecolab Inc., Bimeda Inc., Lanxess AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Disinfectant for Pets and Farms Market Evolving Landscape
Electrochemical generation technologies and residue monitoring protocols are compressing the distance between disinfectant production and point-of-use application, while buyer consolidation demands formulation transparency and batch-level traceability.
On-site electrolyzed water generators are decentralizing chlorine-based disinfectant supply chains by enabling farms to produce sodium hypochlorite from salt and electricity at concentrations tailored to specific housing systems. Large integrated poultry operators in the United States and Brazil are installing skid-mounted units in feed mill complexes, eliminating drum handling and dilution errors while reducing transport costs for remote facilities. This distributed production model is decentralizing procurement authority from central chemical buyers to individual site managers with capital expenditure approval.
REACH's 2026 biodegradability screening thresholds for quaternary ammonium compounds are forcing reformulation of legacy alkyl dimethyl benzyl ammonium chloride products toward esterquat and amphoteric alternatives with faster aquatic degradation profiles. German and Dutch formulators are investing in anaerobic biodegradation testing infrastructure to pre-validate dossier submissions ahead of sunset date deadlines. Surface disinfection applications in dairy parlors face the steepest compliance costs, as these high-frequency use cases accumulate the greatest environmental discharge volumes subject to monitoring.
Protein producers are consolidating disinfectant procurement into multi-year framework agreements with volume commitments and technical service bundling, displacing spot purchasing through agricultural supply retailers. This contract concentration favors suppliers with in-house veterinary technical support teams capable of training farm staff on application protocols and residue testing procedures. The shift is most visible in China's Yangtze River Delta pig farming clusters, where provincial agricultural conglomerates have centralized biosecurity purchasing for hundreds of contracted grower operations.
Veterinary Disinfectant for Pets and Farms Market Segmentation
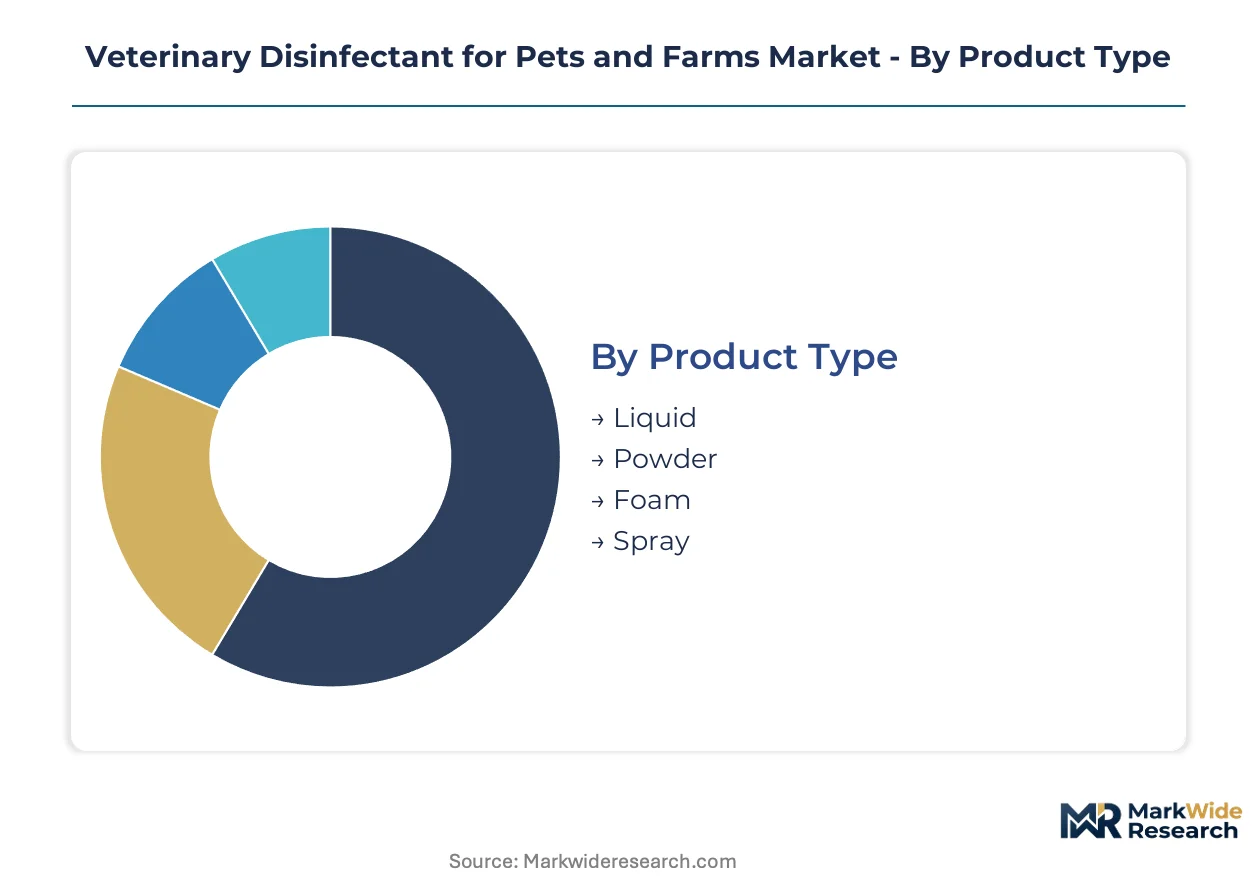
Veterinary disinfectant procurement patterns diverge sharply between mass-volume livestock operations and precision-driven companion animal settings. Understanding these segment boundaries clarifies where formulation investments generate returns versus where commoditization pressures dominate.
Product Type:
Standardization pressures intensify from liquid concentrates toward ready-to-use formats, with dilution control and application method driving the customization spectrum.
- Liquid:Concentrated formulations requiring on-site dilution between 0.5% and 5% active ingredient, compatible with backpack sprayers and pressure-wash systems. Demand concentrates in Brazil's integrated poultry houses and China's Yangtze River Delta pig farming clusters, where bulk tank storage and automated dosing systems favor volume-efficient supply. Most installed capacity flows through Liquid. Expansion is steepest in Foam.
- Foam:Thickened formulations extending contact time on vertical surfaces and porous materials in farrowing crates and calf hutches. German and Dutch dairy parlors are adopting foam generators for pre-milking teat disinfection, driven by REACH biodegradability mandates pushing replacement of legacy chlorine sprays.
- Powder:Granular calcium hypochlorite and peroxygen blends for footbaths and bedding treatment in high-organic-load environments. Australian feedlot operators favor powder formulations for road and yard disinfection during quarantine periods.
- Spray:Aerosol and trigger-spray packaging for spot treatment in companion animal clinics and small-scale kennel operations. Convenience positioning commands shelf space in US veterinary e-commerce channels despite higher per-liter cost.
Installed capacity concentrates in liquid bulk supply. Foam applications are climbing the fastest as contact-time engineering improves.
Application:
Frequency and regulatory intensity separate high-volume recurring protocols from episodic deep-cleaning requirements.
- Surface Disinfection:Floor, wall, and equipment coating protocols in housing systems between animal cycles. Southeast Asian swine facilities are mandating perimeter disinfection infrastructure under African swine fever containment protocols, establishing baseline demand floors for virucidal formulations.
- Water Treatment:Continuous or pulse dosing in recirculating aquaculture systems and automated poultry drinking lines. Norwegian salmon farming operations are expanding electrochemical generation systems for on-site chlorine dioxide production, bypassing chemical transport to remote coastal sites.
- Equipment Cleaning:CIP (clean-in-place) protocols for milking machines, hatchery incubators, and veterinary surgical suites. Stainless steel compatibility requirements restrict chlorine derivative deployment in capital-intensive automated infrastructure.
- Hygiene Maintenance:Footbaths, vehicle sprays, and personnel decontamination at facility entry points. China's provincial agricultural conglomerates are centralizing biosecurity purchasing across contracted grower networks, consolidating procurement authority for these perimeter protocols.
Surface disinfection generates the largest revenue pool. Water treatment applications are gaining share fastest as recirculating systems expand in intensive aquaculture.
End User:
Scale and purchasing sophistication fragment the buyer landscape from centralized framework agreements to discretionary retail selection.
- Livestock Farms:Integrated protein producers with multi-year volume commitments and technical service bundling requirements. Mato Grosso and Paraná broiler operations in Brazil are adding capacity faster than domestic supplier coverage, creating import substitution openings for registered foreign formulations.
- Veterinary Clinics:Companion animal hospitals requiring clinic-grade disinfection between surgical procedures and isolation ward management. Zoetis extends its pharmaceutical distribution channel into clinic disinfection protocols, leveraging existing veterinary relationships.
- Animal Shelters:High-turnover municipal and nonprofit facilities with constrained budgets and outbreak-driven episodic demand. These operations prioritize broad-spectrum efficacy over specialized pathogen claims.
- Pet Owners:Retail purchasers of household disinfectants for kennels, litter boxes, and accident cleanup. US farm supply cooperatives are bypassing distributor markups through platform procurement, capturing this fragmented demand directly.
Livestock farms command the dominant procurement volume. Veterinary clinics offer the steepest margin expansion trajectory through technical service bundling.
Active Ingredient:
Corrosion profiles and environmental persistence drive substitution patterns between established chemistries.
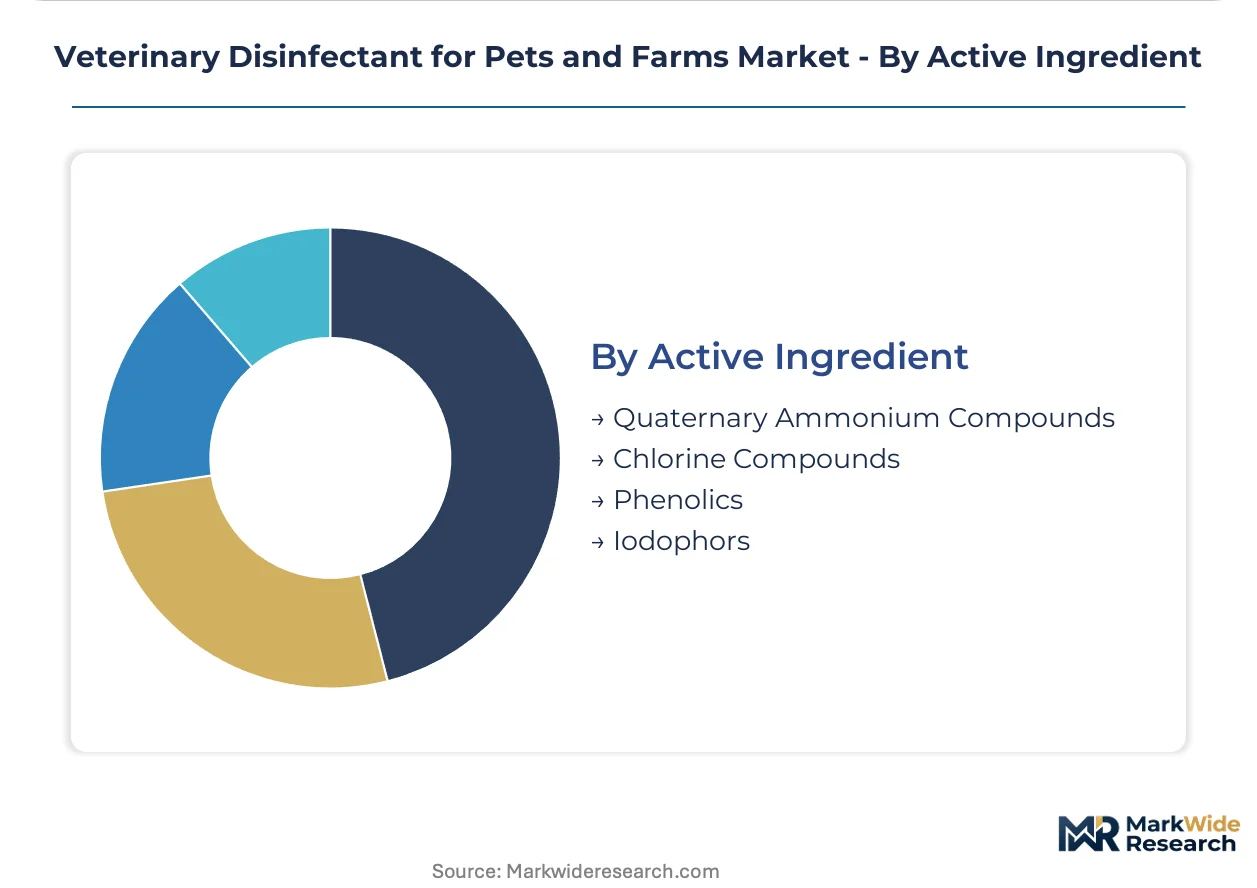
- Quaternary Ammonium Compounds:Lower-corrosion alternatives to chlorine with surfactant properties for organic soil penetration. REACH's phased reauthorization under BPR is accelerating pre-registration investments by suppliers seeking grandfathered European market access.
- Chlorine Compounds:Sodium hypochlorite and chlorine dioxide with rapid kill kinetics against enveloped viruses. Degradation of stainless steel drinking systems in poultry houses restricts deployment in facilities with automated watering infrastructure.
- Phenolics:Residual activity formulations for tuberculosis and fungal pathogen control in dairy housing. EPA registration timelines averaging thirty-six months compress commercialization windows for novel phenolic derivatives.
- Iodophors:Teat disinfection and wound care applications leveraging skin-compatible iodine complexes. New Zealand and Australian pasture-based dairy systems maintain iodophor preference for pre- and post-milking protocols.
Quaternary ammonium compounds dominate installed formulation capacity. Peroxyacetic acid-chlorine dioxide convergence products are expanding most quickly in dual-mechanism biofilm removal systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting veterinary disinfectant production toward jurisdictions with streamlined biocide authorization pathways, as REACH reauthorization costs in Europe widen cost-of-compliance gaps with faster-registration markets.
United States
Integrated poultry operators across Georgia and Arkansas are deploying electrochemical generation systems for on-site chlorine production, bypassing drum transport to remote facilities. EPA registration timelines averaging thirty-six months compress commercialization windows for novel antimicrobial mechanisms. The Delmarva Peninsula broiler corridor concentrates demand for virucidal formulations compliant with USDA biosecurity protocols.
Germany
Dairy parlors in Lower Saxony and Bavaria are replacing legacy chlorine sprays with foam-based quaternary ammonium applications ahead of REACH biodegradability deadlines. ECHA's phased BPR reauthorization is accelerating pre-registration investments by suppliers seeking grandfathered market access. The Münsterland milk production cluster is centralizing procurement through cooperative purchasing agreements.
China
Provincial agricultural conglomerates in the Yangtze River Delta are consolidating biosecurity purchasing across hundreds of contracted grower operations following African swine fever containment mandates. MEE residue monitoring and import licensing requirements shape product registration timelines and formulation choices. Sichuan-Chongqing pig farming regions are adding perimeter disinfection infrastructure at commercial facilities.
Brazil
Integrated broiler capacity expansion in Mato Grosso and Paraná is outpacing domestic disinfectant supplier coverage, creating import substitution openings for registered foreign formulations. ANVISA import licensing requirements govern product entry timelines. The western São Paulo poultry belt is mandating virucidal perimeter protocols under industry-wide biosecurity standards.
Australia
Pasture-based dairy systems in Victoria and New South Wales maintain iodophor preference for pre- and post-milking teat disinfection protocols. TGA parallel import pathways accelerate access to European-registered formulations. The Murray-Darling irrigation corridor is expanding powder-based footbath applications for feedlot quarantine management.
Veterinary Disinfectant for Pets and Farms Market Competitive Landscape
Capacity expansion dominates the current landscape as suppliers position bulk formulation assets near protein production clusters. The vendor base organizes into three tiers: multinational chemical conglomerates with biocide registration infrastructure, veterinary pharmaceutical companies leveraging distribution channel overlap, and regional formulators serving protected domestic markets. Strategic archetypes include registration-heavy dossier specialists, integrated hygiene service bundlers, and cost-optimized commodity suppliers. M&A activity and geographic expansion represent the dominant competitive moves, with acquisition targets concentrated in Latin American and Southeast Asian registration holders.
Among European veterinary hygiene specialists, Kersia Group exemplifies the integrated service bundler archetype, while Ceva Santé Animale occupies a position bridging pharmaceutical and disinfection protocols. Neogen Corporation anchors North American supply through food safety and animal health distribution infrastructure. These three entities represent distinct strategic postures: heritage dairy-poultry technical service depth, veterinary channel extension, and diagnostic-to-hygiene portfolio convergence.
| Leading Market Players |
|---|
| Kersia Group |
| Ceva Santé Animale |
| Neogen Corporation |
| Virbac SA |
| Vetoquinol SA |
| Zoetis Inc. |
| Ecolab Inc. |
| Bimeda Inc. |
| Lanxess AG |
| Others |
Value Network & Pricing Analysis
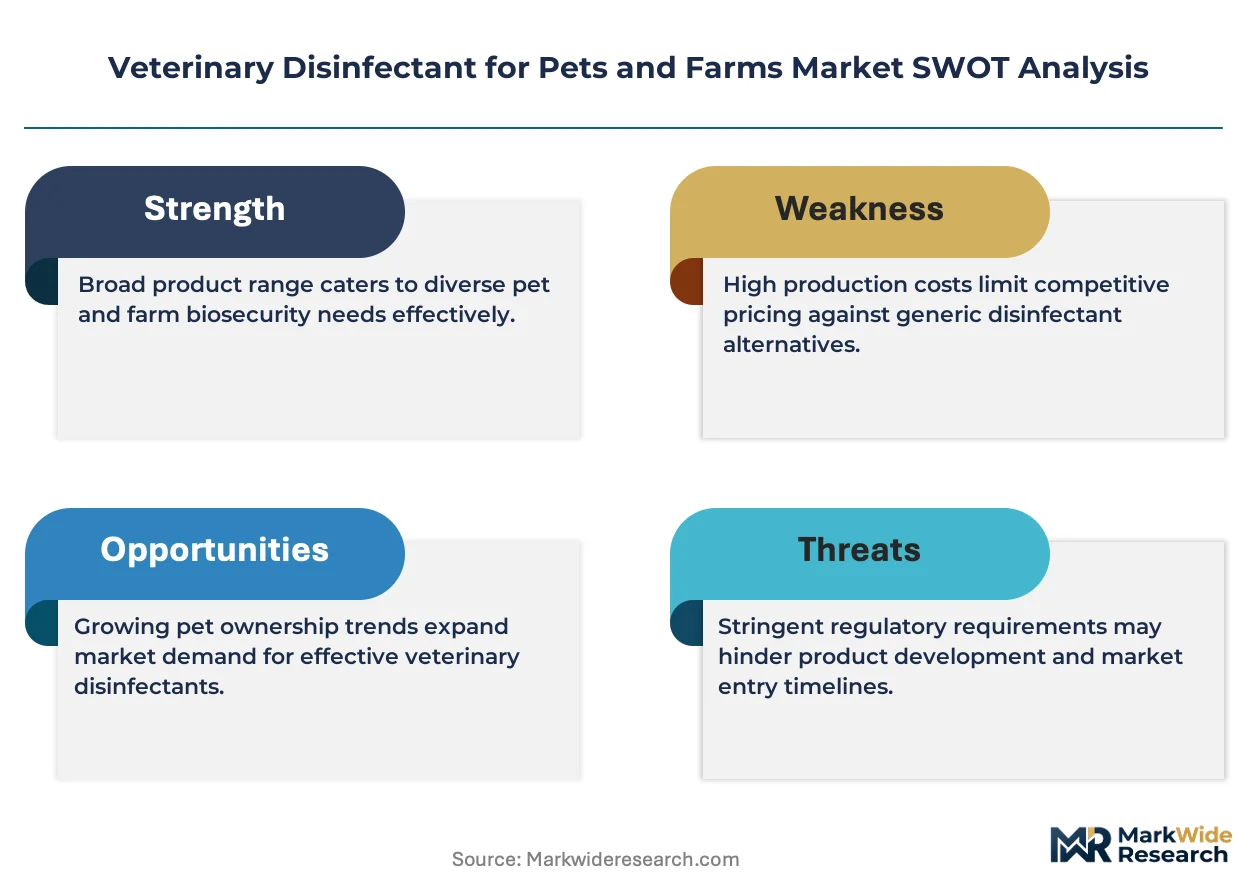
Vertically integrated protein producers in Brazil's Mato Grosso poultry belt and China's Yangtze River Delta pig farming clusters command three-year framework agreements with volume floors, compressing spot-market pricing power and forcing formulators toward cost-plus contract structures with technical service bundling.
Pricing Analysis
Distributor margins of 15-25 percent in traditional agricultural supply channels are collapsing as US farm supply cooperatives adopt platform procurement, bypassing markups through direct-to-farm digital ordering. Pricing stratifies across premium, standard, and economy tiers based on EPA registration tier and biodegradability certification under REACH. Cost compression in standard-grade quaternary ammonium formulations is intensifying because Chinese intermediate suppliers control three-quarters of global production. Smallholder livestock operations remain most price-sensitive, while integrated protein producers absorb premium pricing for bundled technical support and residue monitoring protocols.
Supply Chain Analysis
Empty drum returns and expired concentrate reclamation flows are negligible in veterinary disinfectant supply chains, as on-site electrochemical generation systems in Georgia and Arkansas poultry operations eliminate packaging waste entirely. Active ingredient production concentrates in China, Germany, and the United States, with formulators drawing from quaternary ammonium chloride intermediates, chlorine gas feedstocks, and peracetic acid precursors. Single-source vulnerability in Chinese intermediate supply exposes formulators to export license volatility and shipping corridor disruptions. Distribution runs through veterinary pharmaceutical wholesalers, agricultural supply cooperatives, and direct procurement platforms serving integrated livestock operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in veterinary disinfectants rests on substitution of high-cost chlorine-compatible equipment with lower-corrosion quaternary ammonium formulations, alongside premium pricing for REACH-compliant biodegradable alternatives in German and Dutch dairy markets.
For Market Incumbents: Acquire Latin American and Southeast Asian biocide registration holders to preempt competitor dossier filings under ANVISA and MEE frameworks. Consolidate backward integration into quaternary ammonium intermediate production to offset Chinese supply concentration. Expand technical service teams in Brazil's Paraná state to capture import substitution demand from domestic capacity shortfalls. For New Entrants and Emerging Players: Veterinary e-commerce direct channels offer the lowest barrier to entry for registered formulations seeking bypass of incumbent distributor networks. Target Australia's pasture-based dairy segment with iodophor alternatives priced below incumbent veterinary pharmaceutical channels. Pursue white-label supply agreements with US farm supply cooperatives lacking in-house formulation capabilities. For Investors and Strategic Acquirers: Veterinary pharmaceutical conglomerates are the most active acquirer in this space, seeking disinfection protocol extensions for companion animal clinic networks. Mid-tier formulators with established EPA and REACH dossiers represent the highest-probability acquisition targets over the next decade. Monitor ANVISA registration timeline compression as the inflection signal for Brazilian market entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| Biocide Registration Dossier Acquisition | Accelerates market access under EPA and REACH authorization timelines. |
| On-Site Electrochemical Generation Deployment | Eliminates drum logistics costs for remote Georgia and Arkansas poultry facilities. |
| REACH-Compliant Biodegradable Reformulation | Secures grandfathered European market access ahead of sunset deadlines. |
| Technical Service Team Expansion | Captures bundled procurement contracts from China's provincial agricultural conglomerates. |
| Direct-to-Farm E-Commerce Platform Launch | Bypasses traditional distributor markups in US cooperative procurement channels. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region combined with secondary validation. Interviews with veterinary pharmaceutical procurement directors, agricultural cooperative supply managers, EPA regulatory affairs specialists, and dairy parlour technical service teams informed demand-side assumptions. Secondary sources include EPA registration databases, ECHA biocide authorization filings, ANVISA import licensing records, and customs trade data on quaternary ammonium intermediate flows. Bottom-up volume estimates from individual livestock facility consumption rates were triangulated against top-down protein production forecasts.
Granularity extends to active ingredient chemistry, application method, end-user scale tier, and country-level regulatory cluster across the projection horizon. Segmentation dimensions encompass liquid, foam, powder, and spray formulations; surface disinfection, water treatment, equipment cleaning, and hygiene maintenance applications; livestock farms, veterinary clinics, animal shelters, and pet owners; and quaternary ammonium, chlorine, phenolic, and iodophor chemistries. CAGRs were derived from regression analysis of historical procurement volume against protein production capacity expansion. Forecast inputs include African swine fever containment protocol mandates and REACH biodegradability deadline compliance costs.
The model assumes a particular technology adoption path; alternative pathways for electrochemical on-site generation would alter the outlook if capital expenditure constraints delay poultry operator deployment. Forecasts reflect assumptions about regulatory authorization timelines, intermediate supply stability, and integrated producer procurement consolidation. Practitioners should monitor EPA registration backlog clearance rates, Chinese export license volatility, and Brazilian domestic supplier capacity additions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Germicidal UV Lamp Market
Infection Control
Community Acquired Pneumonia (CAP) Market
Infection Control
New Zealand Healthcare Surface Disinfectant Wipes Market
Infection Control
Medical Washer Disinfector Market
Infection Control
UV Sterilizer Pouch Market
Infection Control
Point of Care Infection Control Market
Infection Control
Infection Surveillance Solutions Market
Infection Control
Hospital Acquired Infections Market
Infection Control
Botulism Market
Infection Control
Global Sepsis Therapeutics Market
Infection Control
Air Sanitizer Market
Infection Control
Antimicrobial Catheters Market
Infection Control
Alcohol Wipes Market
Infection Control
Sterilization Technologies Market
Infection Control
Virus Filtration Market
Infection Control
Intra Abdominal Infection Market