
 Global Construction Tape Market | 2026-2036
Global Construction Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Global Construction Tape Market Intelligence
Commercial building renovation is expanding as the dominant demand vector for construction tapes, displacing new residential construction as the primary volume driver. 3M Company leverages its adhesive science portfolio to dominate high-performance segments where structural bonding specifications are stringent. tesa SE anchors its position through automotive-to-construction technology transfer, applying acrylic foam expertise to building envelope applications. Nitto Denko Corporation specializes in double-sided mounting tapes for prefabricated facade systems, a category gaining share in modular construction workflows.
Construction tape comprises pressure-sensitive adhesive tapes engineered for temporary or permanent bonding, sealing, masking, and reinforcement across building sites, with backing materials including PVC, polyethylene, cloth, and paper substrates rated for tensile strength, temperature resistance, and surface adhesion. Duct tape and masking tape represent mature volume pools where price competition compresses margins, while filament tape and specialty electrical tapes command premium positioning due to tensile reinforcement and code-compliant insulation properties. Material segmentation shows polyethylene backings gaining share in weatherproofing applications, whereas PVC retains dominance in electrical insulation where flame-retardant ratings matter.
REACH in Europe and RoHS restrict hazardous substance content in adhesive formulations, compelling reformulation investments that favor larger chemical suppliers with in-house toxicology testing. EPA regulations in the United States govern volatile organic compound emissions from tape manufacturing, shaping plant location decisions and coating technology choices. OSHA workplace exposure standards influence tape selection on job sites, particularly for asbestos abatement and lead paint remediation where certified barrier tapes are mandatory. Stakeholders must monitor evolving building energy codes that specify air barrier continuity, a technical requirement that expands demand for high-performance sealing tapes in envelope assemblies.
Market Dynamics
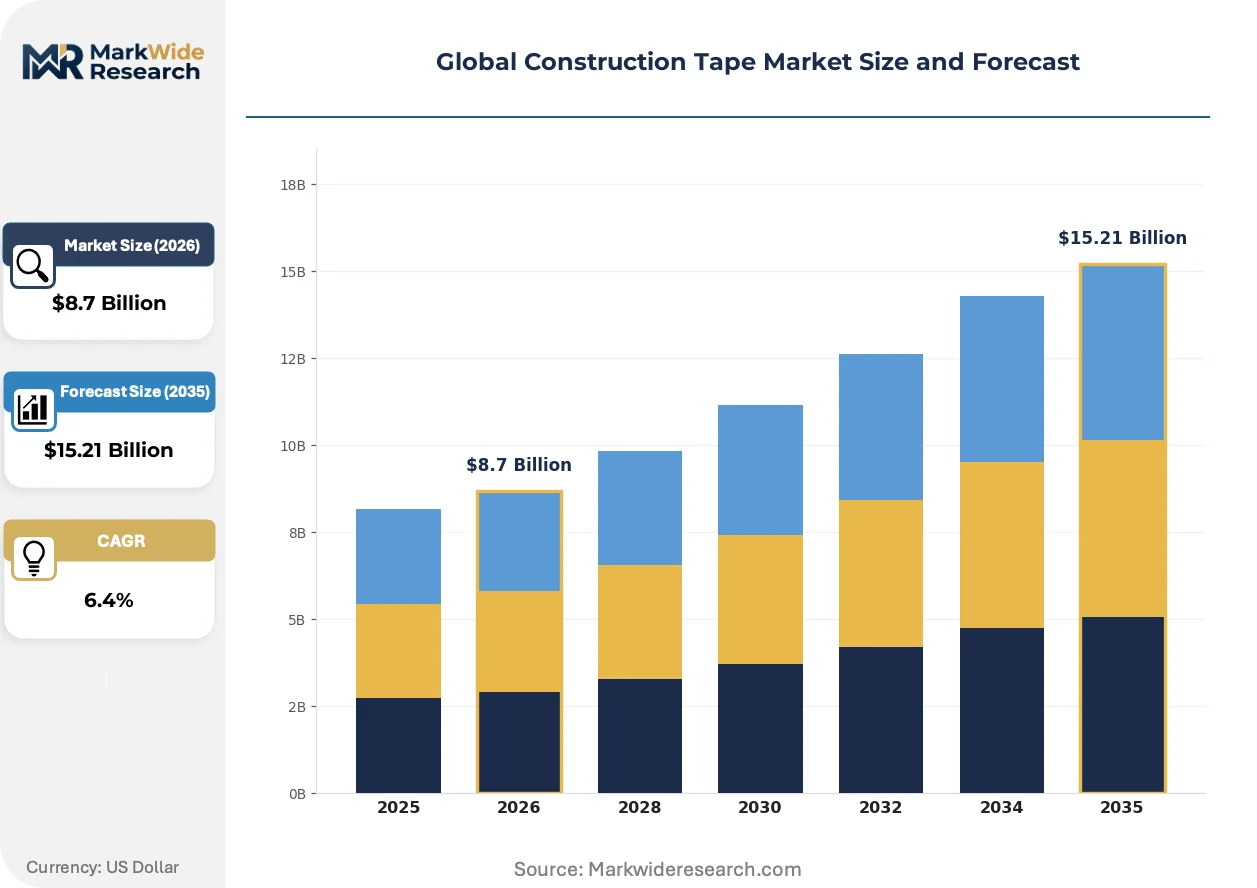
Commercial building renovation has displaced new residential construction as the primary volume driver, with air barrier continuity mandates in energy codes forcing specification upgrades toward high-performance sealing tapes across envelope assemblies.
Growth Catalysts
- REACH and RoHS in Europe:Solvent-free adhesive formulations are gaining regulatory preference, accelerating reformulation investments by chemical suppliers with in-house toxicology testing capabilities.
- Prefabricated facade systems:Modular construction workflows are absorbing double-sided mounting tapes for panel-to-frame bonding, creating dedicated demand pools outside traditional site-applied categories.
- Urban redevelopment in China:Infrastructure investment and building envelope upgrades are concentrating tape volumes in sealing and weatherproofing applications across coastal provinces.
Market Restraints
- Petrochemical input volatility:Polyethylene and PVC backing materials expose margin structures to crude oil derivative pricing swings without pass-through mechanisms in commoditized duct and masking tape segments.
- Supply concentration in Asia:Acrylic adhesive resin production clusters in East Asian chemical corridors, creating geographic single-source risk for European and North American tape coaters.
- Technical ceiling in high-temperature bonding:Silicone and acrylic chemistries face performance boundaries above 150°C in structural glazing applications, limiting tape substitution of mechanical fasteners.
Strategic Opportunities
- India building code enforcement:BIS standards for fire-rated electrical insulation tapes are tightening, creating certification-driven replacement cycles in commercial and industrial wiring.
- Biobased adhesive convergence:Tackified natural rubber and rosin ester formulations are intersecting with compostable film backings to serve green building certification schemes.
- Direct contractor procurement platforms:Digital distributor models are bypassing traditional two-step distribution, capturing specification influence through job-site delivery and inventory management tools.
Industry Challenges
- Adhesive formulation chemistry expertise:Solvent-free coating transitions require polymer science capabilities scarce outside major chemical conglomerates, constraining mid-tier tape manufacturers.
- Multi-jurisdiction certification timelines:UL, CE marking, and GB standard testing sequences extend product launch cycles by 18-24 months for tapes serving cross-border equipment OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Construction Tape Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Masking Tape, Duct Tape, Electrical Tape, Filament Tape Application: Painting, Electrical, HVAC, Packaging Material: PVC, Polyethylene, Cloth, Paper End User: Contractors, Retailers, Manufacturers, DIY Enthusiasts |
| Companies Covered | 3M Company, tesa SE, Nitto Denko Corporation, Intertape Polymer Group, Shurtape Technologies, LLC, Scapa Group plc, Avery Dennison Corporation, Berry Global Inc, Saint-Gobain Performance Plastic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Construction Tape Market Strategic Shifts & Innovations
Acrylic foam tape technology is migrating from automotive assembly into building envelope applications, while regulatory pressure on volatile organic compounds is reshaping coating plant investments and adhesive chemistry roadmaps.
Acrylic foam core tapes with viscoelastic properties are integrating structural bonding and sealing functions into single-layer solutions for curtain wall and window perimeter applications. Façade contractors in Germany and the Netherlands are specifying these tapes for dead-load glazing retention, displacing wet-applied structural silicones in unitized panel systems. The technology is integrating permanent adhesion with thermal movement accommodation, compressing installation labor hours and eliminating cure-time delays from project schedules.
EPA volatile organic compound emission standards for adhesive coating operations are forcing capital redeployment toward hot-melt and radiation-cured systems in U.S. manufacturing plants. Tape converters with legacy solvent-based lines face equipment replacement decisions or geographic relocation to jurisdictions with less stringent air quality enforcement. Electrical insulation tapes with flame-retardant PVC backings are most affected, as halogen-free alternatives require entirely different coating infrastructure and supply chain qualification.
Building envelope commissioning protocols are compressing contractor accountability for air leakage performance, shifting tape specification authority from purchasing departments to envelope consultants and commissioning agents. Performance-based contractor agreements with leakage-rate guarantees are displacing commodity procurement in commercial and institutional projects. This pattern is most visible in California and Washington state markets, where Title 24 and state energy codes mandate blower-door testing for commercial buildings.
Global Construction Tape Market Segmentation
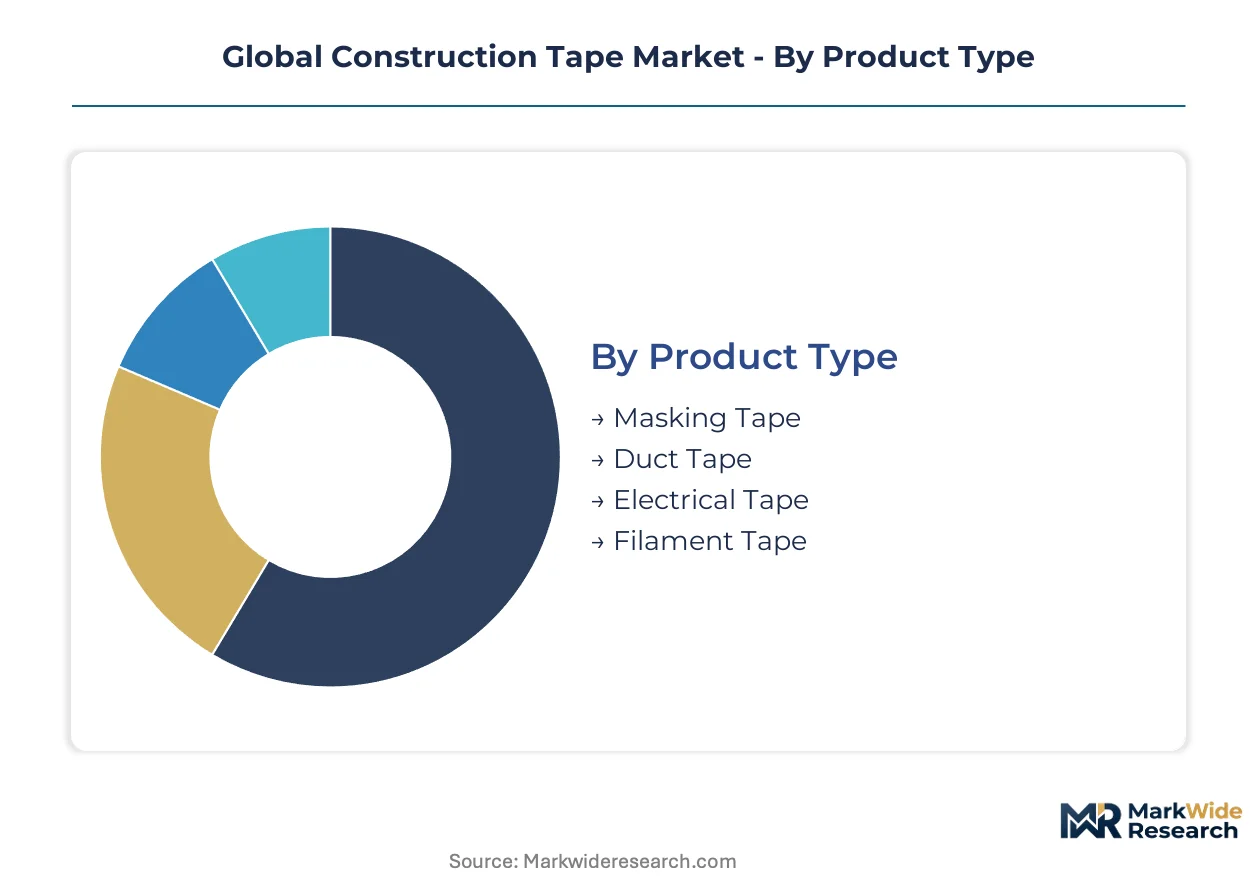
Construction tape segmentation reveals divergent margin structures across commodity and specialty categories. Product type and material chemistry determine pricing power, while application context dictates specification authority and channel access.
Product Type:
Volume concentrates in mature categories where price competition erodes returns, while premium positioning accrues to segments with technical certification requirements.
- Duct Tape:Reinforced polyethylene or cloth backing with natural rubber adhesive serves heavy-duty sealing and repair across job sites. Demand clusters in North American commercial renovation where temporary enclosure and surface protection absorb roll quantities, though petrochemical input volatility compresses converter margins without pricing power.
- Electrical Tape:PVC film backing with pressure-sensitive rubber or acrylic adhesive provides flame-retardant insulation rated for voltage stress and temperature cycling. Specification concentrates in India where BIS standards for fire-rated wiring insulation are tightening, creating mandatory replacement cycles in commercial electrical installations.
- Masking Tape:Crepe paper backing with synthetic rubber adhesive engineered for clean removal after paint curing cycles.
- Filament Tape:Fiberglass-reinforced backing delivers tensile strength for bundling and palletizing heavy construction materials.
Today's leader: Duct Tape. Tomorrow's challenger: Electrical Tape.
Application:
Specification authority shifts from procurement departments to technical consultants as building performance codes tighten envelope requirements.
- HVAC:Foil and reinforced tapes seal ductwork joints against pressure loss and thermal leakage. California Title 24 mandates and Washington state energy codes are forcing blower-door testing for commercial buildings, expanding specification of high-performance sealing tapes in mechanical assemblies.
- Electrical:Insulation and color-coding tapes for conductor protection and circuit identification in permanent wiring installations.
- Painting:Masking and surface protection tapes for finish work where adhesive residue control determines contractor callbacks.
- Packaging:Reinforced carton sealing and bundling tapes for material shipment and jobsite logistics.
Current procurement priority: HVAC. Specification momentum: Electrical.
Material:
Backing chemistry determines weathering performance and regulatory compliance trajectory across regional markets.
- Polyethylene:Moisture-resistant film backing dominates weatherproofing and temporary enclosure applications. Coastal provinces in China absorb significant volumes for building envelope upgrades in urban redevelopment projects.
- PVC:Flame-retardant film retains electrical insulation dominance where halogen-free alternatives require entirely different coating infrastructure and supply chain qualification.
- Cloth:Woven cotton or synthetic fabric backing provides tear resistance and conformability for irregular surfaces.
- Paper:Crepe and flat paper backings serve masking and temporary holding applications with controlled removability.
Established standard: PVC. Fastest material transition: Polyethylene.
End User:
Channel structure fragments between specification-driven commercial procurement and price-sensitive retail consumption.
- Contractors:Commercial and residential builders purchasing through distribution for specified applications. Digital procurement platforms are bypassing traditional two-step distribution, capturing specification influence through job-site delivery and inventory management tools.
- Retailers:Home improvement and hardware stores serving maintenance and small-project demand.
- Manufacturers:OEM tape consumption for prefabricated building component assembly.
- DIY Enthusiasts:Consumer segment driven by project-based purchasing with minimal brand loyalty.
Margin concentration: Contractors. Volume expansion: Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors construction tape demand through massive urban redevelopment and infrastructure renewal programs. Tape volumes concentrate in sealing and weatherproofing applications across coastal manufacturing zones. Regional regulatory divergence is fragmenting formulation strategies as jurisdictions impose distinct chemical compliance thresholds.
China
Urban redevelopment in Shanghai and Jiangsu province absorbs polyethylene-backed tapes for building envelope upgrades. GB standards for construction materials are tightening adhesive content requirements, forcing reformulation investments by domestic coaters. The Pearl River Delta manufacturing corridor hosts acrylic adhesive resin production clusters serving tape converters across East Asia.
United States
Commercial building renovation in California and Washington state drives specification of high-performance sealing tapes for HVAC and envelope assemblies. EPA volatile organic compound standards for adhesive coating operations are forcing capital redeployment toward hot-melt systems. The Southeast manufacturing belt contains legacy solvent-based tape lines facing equipment replacement decisions.
Germany
Façade contractors in the Netherlands and German border regions specify acrylic foam tapes for unitized panel systems in modular construction. REACH compliance mandates solvent-free adhesive formulations, accelerating toxicology testing investments by chemical suppliers. The Ruhr industrial corridor hosts coating plants transitioning from solvent-based to radiation-cured infrastructure.
India
BIS standards for fire-rated electrical insulation tapes are tightening certification requirements in Maharashtra and Gujarat commercial wiring markets. CDSCO-aligned building safety regulations are mandating replacement cycles in industrial electrical installations. The Delhi-NCR construction corridor concentrates demand for PVC-backed insulation tapes in high-rise commercial projects.
United Arab Emirates
Mega-project construction in Dubai and Abu Dhabi absorbs weatherproofing tapes for building envelope applications in extreme climate conditions. MOHAP-aligned building safety protocols are influencing adhesive specification for permanent bonding applications. The Jebel Ali industrial zone hosts tape distribution hubs serving Gulf Cooperation Council infrastructure markets.
Global Construction Tape Market Key Industry Players
Portfolio diversification dominates the current landscape as incumbents extend adhesive science capabilities across construction end-uses. The vendor base separates into three tiers: multinational chemical conglomerates with in-house polymer research, regional tape converters with coating and slitting operations, and specialized adhesive formulators serving niche specification segments. Two competitive vectors define current positioning: technology licensing agreements that transfer automotive adhesive expertise into building applications, and geographic expansion through distribution partnerships in high-growth construction corridors.
Within the multinational conglomerate tier, 3M Company, tesa SE, and Nitto Denko Corporation exemplify divergent strategic anchors. 3M represents the integrated materials science archetype with captive adhesive development. tesa SE occupies the technology-transfer position, migrating automotive foam expertise into construction specifications. Nitto Denko sits within the Asia-Pacific production gravity, specializing in double-sided mounting solutions for prefabricated systems. These three entities illustrate how geographic origin and legacy industry exposure shape competitive positioning without converging on identical capability bundles.
| Leading Market Players |
|---|
| 3M Company |
| tesa SE |
| Nitto Denko Corporation |
| Intertape Polymer Group |
| Shurtape Technologies, LLC |
| Scapa Group plc |
| Avery Dennison Corporation |
| Berry Global Inc |
| Saint-Gobain Performance Plastic Corporation |
| Others |
Cost & Logistics Intelligence
Hot-melt coating infrastructure transitions across U.S. and European plants are simultaneously elevating capital requirements for solvent-free adhesive production and compressing supplier tiers toward chemical conglomerates with captive polymer science capabilities. This technology migration reshapes cost economics by forcing equipment replacement cycles while concentrating supply relationships among integrated manufacturers.
Pricing Analysis
Petrochemical input pass-through mechanics dominate margin structures for polyethylene and PVC backing materials, with crude oil derivative volatility compressing converter returns in commoditized duct and masking tape categories. Three-tier pricing structure across premium, standard, and economy levels separates UL-certified electrical insulation from ungraded construction grades, with brand premiums accruing to 3M and tesa in specification-driven envelope applications. Price erosion runs through duct tape segments where Asian imports saturate North American distribution channels. Retail DIY buyers exhibit highest price sensitivity, while envelope consultants specifying air barrier tapes demonstrate lowest elasticity due to performance guarantees in contractor agreements.
Supply Chain Analysis
Dual-sourcing mandates from major façade contractors and OEM equipment builders require tape coaters to qualify multiple adhesive resin suppliers, extending procurement timelines but reducing geographic concentration risk. Acrylic adhesive resin production clusters in China, South Korea, and Japan feed converters across East Asia, with European and North American coaters drawing from these chemical corridors for specialty formulations. Supply chain vulnerability centers on single-source dependency for radiation-cured coating equipment. Distribution runs through two-step industrial distribution, though digital procurement platforms are capturing specification influence in commercial renovation segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where commercial building renovation demand is concentrating specification authority with envelope consultants and commissioning agents, displacing commodity procurement with performance-based sourcing.
For Market Incumbents: To counter Asian import price pressure in duct and masking tape categories, prioritize backward integration into acrylic adhesive resin production in the U.S. Southeast manufacturing belt, while accelerating UL and CE marking investments to defend specification position in electrical insulation segments where BIS standards are tightening certification requirements. For New Entrants and Emerging Players: Begin with biobased adhesive formulations for green building certification schemes, targeting Indian electrical tape replacement cycles where CDSCO-aligned regulations mandate fire-rated wiring insulation upgrades, and pursue direct contractor procurement platform partnerships to bypass entrenched two-step distribution channels. For Investors and Strategic Acquirers: Valuations sit cheapest among regional tape converters with solvent-based legacy lines facing EPA compliance-driven equipment replacement decisions. Five-to-ten year viability hinges on coating technology transition execution. Monitor acrylic foam tape specification rates in German and Dutch modular construction markets as the inflection signal for premium segment expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Hot-Melt Coating Transition | EPA VOC standards force capital redeployment toward solvent-free adhesive production systems. |
| Acrylic Foam Technology Transfer | Automotive bonding expertise migrates into building envelope applications for curtain wall systems. |
| Digital Procurement Platform Integration | Job-site delivery tools capture specification influence from traditional distribution channels. |
| Biobased Formulation Development | Tackified natural rubber adhesives align with LEED and BREEAM green building certification schemes. |
| Multi-Jurisdiction Certification Investment | UL, CE marking, and GB standard testing extends product launch cycles but locks in cross-border OEM supply. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining tape converter executives, adhesive formulator R&D directors, façade contractor procurement leads, and envelope consultant specification authorities. Secondary validation draws from EPA emission filings, ECHA REACH registration databases, SEC 10-K disclosures from listed tape manufacturers, and BIS certification records. Bottom-up volume modeling triangulates against top-down construction spending allocation analysis.
Granularity-level modeling disaggregates the market across product type, material chemistry, application context, and end-user channel, with regional regulatory cluster as an additional dimension. CAGRs derive from segment-level volume trajectories applied across the projection horizon, incorporating construction spending forecasts and energy code adoption curves as industry-specific demand drivers.
Caveats apply where petrochemical price volatility, REACH reformulation timelines, or modular construction adoption rates could materially shift the outlook. Deviation in Chinese infrastructure investment intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Tear Tape Dispenser Market
Tapes
Thermal Transfer Tapes Market
Tapes
Heat Release Tape Market
Tapes
Gaffers Tape Market
Tapes
Twist Tube Market
Tapes
Tape Unwinder Market
Tapes
Tape Applicator Machines Market
Tapes
UV Tapes Market
Tapes
Adhesive Transfer Tape Market
Tapes
Tape Dispenser Market
Tapes
Aerospace Tapes Market
Tapes
Tape Stretching Line Market
Tapes
Unidirectional Tapes Market
Tapes
Raffia Tape Stretching Line Market
Tapes
Masking Tape Market
Tapes
India Masking Tapes Market