
 Spirit-Based RTD Mixes Market | 2026-2036
Spirit-Based RTD Mixes Market Size, Share, and Industry Trends Forecast 2026-2036
Spirit-Based RTD Mixes Market Analysis
ISO 22000 certification is reorganizing competitive access in spirit-based RTD mixes, filtering out smaller co-packers who cannot maintain hazard-critical control points across liquid blending and canning lines. Diageo Plc leverages its captive distillery network to secure consistent base-spirit supply for canned cocktail programs. Cutwater Spirits LLC anchors its position through specialized production of whiskey-based RTD formats in California. Suntory Global Spirits Inc. competes by integrating Japanese whisky heritage into highball-centric product architecture for North American export channels.
Spirit-based RTD mixes comprise pre-formulated beverages blending distilled spirits with carbonated or still mixers, typically packaged in aluminum cans with alcohol-by-volume ranging from four to ten percent, designed for immediate consumption without bartender intervention. The primary commercial purpose centers on delivering consistent cocktail experiences through shelf-stable, single-serve formats that eliminate preparation complexity for off-premise and on-premise operators. Cocktail and highball categories within product type segmentation capture dominant volume, while premium alcohol tiers in the alcohol content dimension concentrate margin pools as consumers trade up from beer and seltzer alternatives. Cans within packaging type segmentation lead volume due to logistics efficiency and recycling infrastructure, though pouches represent an emerging format for festival and outdoor event channels.
FDA alcohol labeling rules and TTB formula approval requirements govern product entry in the United States, while EFSA additive standards and EU alcohol taxation frameworks shape European formulation and pricing architecture. These regulatory layers elevate compliance costs for new entrants and favor established players with dedicated regulatory affairs functions. Stakeholders must monitor evolving state-level distribution laws and sugar-tax proposals that could recalibrate channel economics for standard-strength and flavored variants.
Market Dynamics
ISO 22000 certification requirements are filtering out smaller co-packers from spirit-based RTD supply chains, concentrating production capacity among hazard-critical control point compliant facilities while reshaping competitive access for new entrants.
Growth Catalysts
- TTB Formula Approval Streamlining:The Alcohol and Tobacco Tax and Trade Bureau's accelerated review protocols for canned cocktail formulations are compressing time-to-market for compliant producers in the United States.
- Aluminum Can Recycling Infrastructure:Municipal recycling program expansions across Brazil and Japan are reducing packaging cost premiums for RTD brands versus glass-dependent competitors.
- Hospitality Labor Shortages:Hotels and casual dining chains are substituting pre-mixed cocktails for bartender-staffed bars to maintain beverage program margins.
Market Restraints
- Base Spirit Supply Concentration:Premium whisky and tequila agave sourcing depends on concentrated distillery capacity in Kentucky and Jalisco, creating input vulnerability.
- EFSA Additive Restrictions:European flavor compound approvals limit formulation flexibility for US-exporting RTD producers versus domestic European competitors.
- Glass Bottle Substitution:Premium on-premise accounts retain preference for bottled cocktails in certain Japanese and Brazilian metropolitan markets, constraining can-format penetration.
Strategic Opportunities
- Festival and Outdoor Event Channels:Pouch-format RTD cocktails are capturing share at music venues and sporting events where glass prohibition and can weight create friction.
- Japanese Whisky Highball Heritage:North American export channels present white space for heritage-positioned Japanese whisky-based RTD formats targeting premium convenience retail.
- State-Level Distribution Law Liberalization:Direct-to-retailer shipping permissions in select US states are opening bypass routes around traditional three-tier distribution.
Industry Challenges
- Liquid Blending Technician Scarcity:Hazard-critical control point certified operators capable of managing spirit-proof consistency across batch runs command wage premiums that compress co-packer margins.
- Canning Line Retrofit Capex:Existing beverage facilities require six-figure capital deployment to handle carbonated alcohol formulations without flavor degradation.
- Cross-Border Formula Registration:Divergent FDA and EFSA disclosure requirements force dual documentation workflows that extend compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spirit-Based RTD Mixes Market |
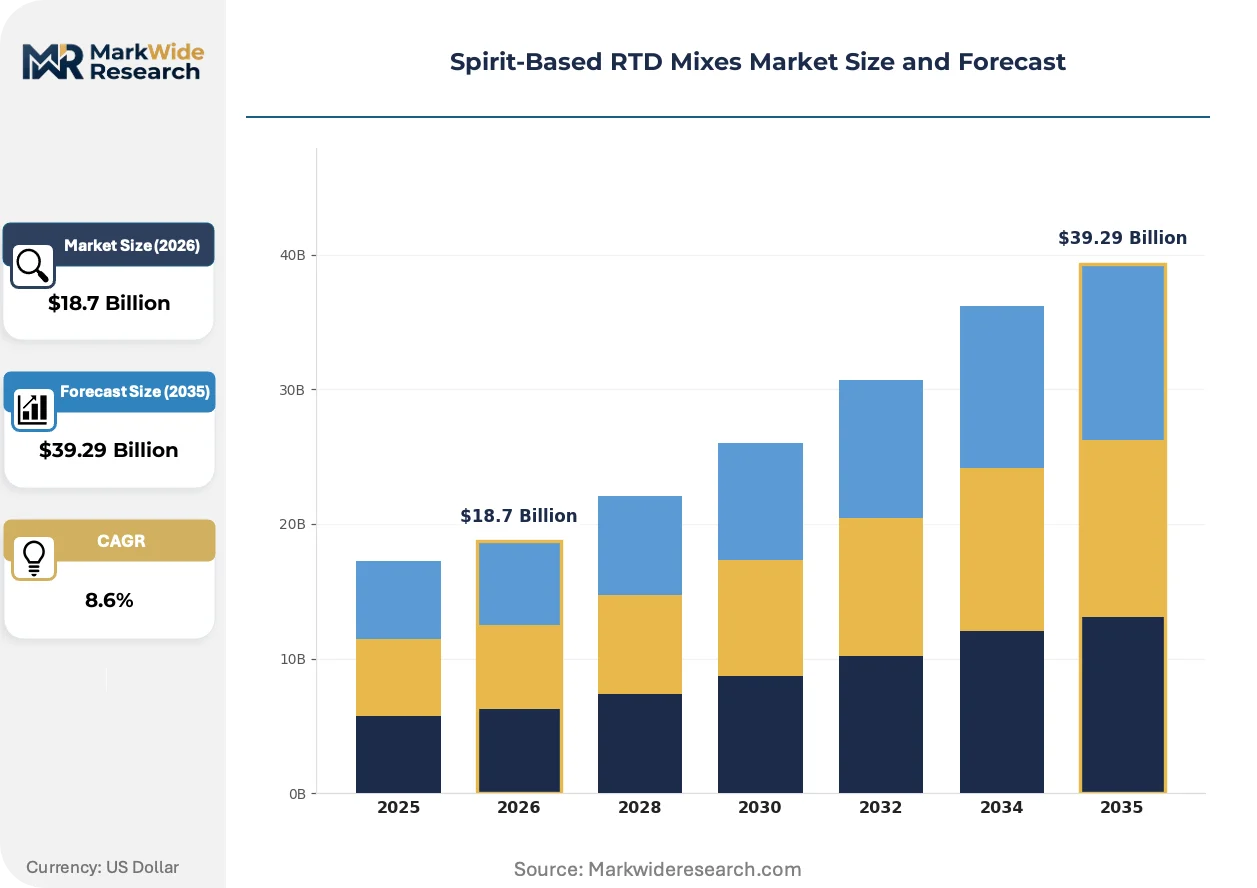
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cocktail, Highball, Sour Mix, Fizz Flavor Profile: Citrus, Berry, Spiced, Herbal Alcohol Content: Low Alcohol, Standard Strength, High Alcohol, Premium Alcohol Packaging Type: Cans, Bottles, Tetra Paks, Pouches |
| Companies Covered | Constellation Brands Inc., Suntory Global Spirits Inc., Anheuser-Busch InBev SA/NV, Campari Group, Brown-Forman Corp., Bacardi Ltd., Pernod Ricard SA, Cutwater Spirits LLC, Diageo Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spirit-Based RTD Mixes Market Emerging Trajectories
Active packaging technologies and formulation science are compressing the gap between canned convenience and craft cocktail quality, while regulatory transparency mandates reshape how producers communicate alcohol content and ingredient sourcing to consumers.
Nitrogen dosing systems in canning lines are supplanting traditional carbonation methods for still-spirit RTD formats. Premium whiskey-based producers in California and Kentucky are adopting this technology to preserve aromatic integrity without effervescence. The shift is enabling shelf-stable products that compete directly with freshly mixed bar cocktails.
FDA updated labeling requirements for alcohol content disclosure and ingredient transparency are mandating granular nutritional paneling that exceeds previous voluntary standards. Producers must now disclose added sugars and allergen cross-contamination risks on primary packaging. Large-format RTD portfolios are absorbing compliance costs through dedicated regulatory affairs functions while smaller entrants face documentation barriers.
Millennial and Gen-Z consumers in the hospitality sector are compressing their beverage switching cycles, rotating between canned cocktails, hard seltzers, and craft beer within single occasions. On-premise operators are responding with modular RTD programs that reduce inventory risk versus dedicated tap lines. This pattern concentrates in United States coastal metropolitan markets where convenience retail and bar channels overlap geographically.
Spirit-Based RTD Mixes Market Segmentation
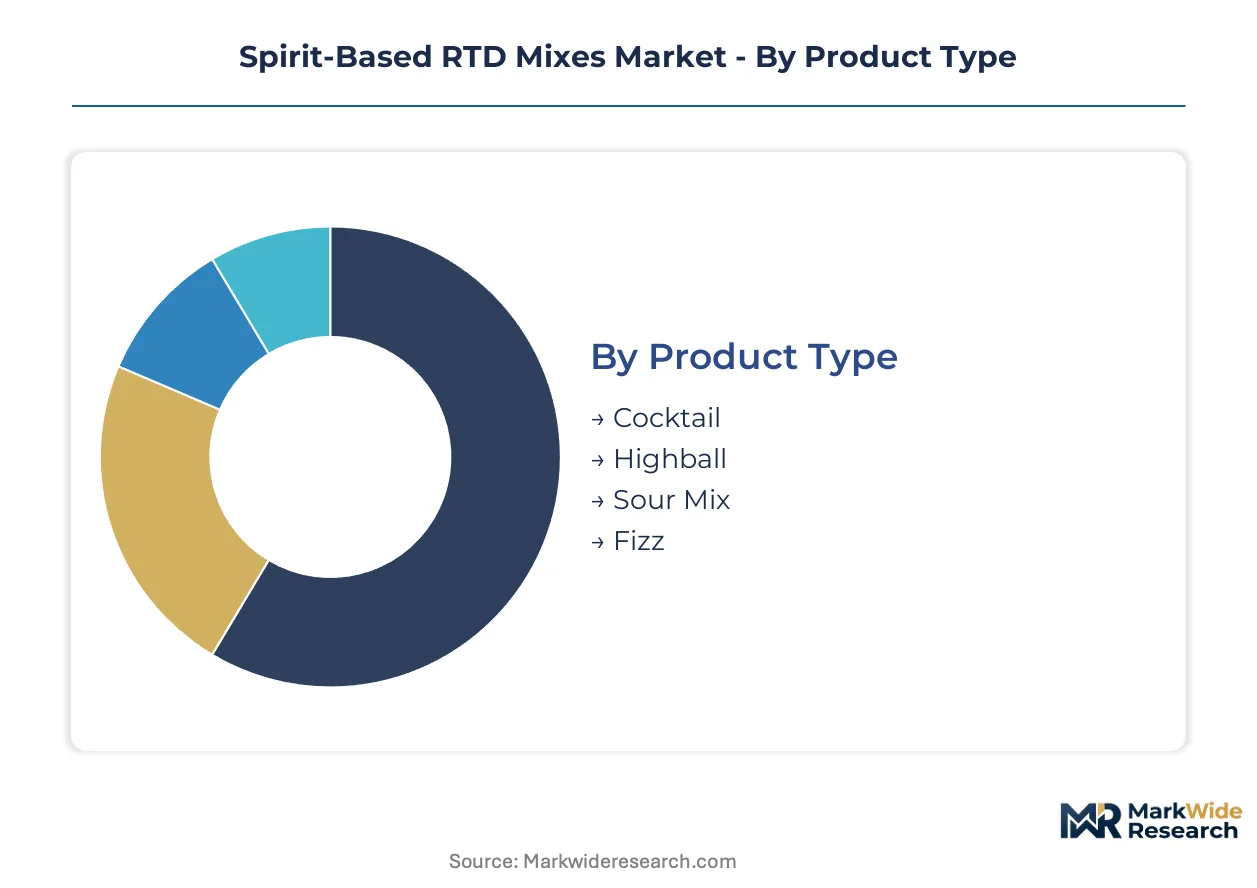
Segmentation in spirit-based RTD mixes determines channel economics and margin capture. Product architecture, alcohol tier, and packaging format each create distinct distribution pathways and consumer access points across retail and hospitality channels.
Product Type:
Cocktail formats flow through convenience retail and grocery channels, while highballs concentrate in on-premise hospitality accounts and specialty beverage retailers.
- Cocktail:Pre-mixed combinations of distilled spirits with multiple modifiers, typically vodka or rum-based, achieving alcohol-by-volume between five and ten percent. United States coastal metropolitan markets show concentrated demand as Millennial and Gen-Z consumers rotate between canned cocktails and craft beer within single occasions. FDA labeling requirements for ingredient transparency elevate compliance costs for multi-component formulations.
- Highball:Two-ingredient constructions pairing whisky, tequila, or gin with carbonated mixers, emphasizing simplicity and heritage positioning. Japanese whisky-based highballs gain traction in North American export channels through Suntory Global Spirits' heritage architecture. The format benefits from nitrogen dosing systems that preserve aromatic integrity without effervescence degradation.
- Sour Mix:Citrus-forward formulations incorporating acidulated components for margarita and whiskey sour analogues.
- Fizz:Effervescent variants combining spirits with carbonated water and minimal sweetening agents.
By volume, Cocktail leads. By growth pace, Highball is expanding most quickly.
Flavor Profile:
Flavor positioning stratifies across price tiers, with citrus commanding economy placement and spiced variants capturing premium shelf positioning.
- Citrus:Lemon, lime, and grapefruit-forward formulations dominating mass-market penetration. Brazil shows concentrated demand as municipal recycling infrastructure reduces packaging cost premiums for aluminum-can formats. EFSA additive restrictions limit synthetic flavor compound flexibility for US-exporting producers versus domestic European competitors.
- Berry:Raspberry, blackberry, and mixed berry constructions targeting female-skewing demographics in convenience retail.
- Spiced:Cinnamon, clove, and chili-infused variants anchoring autumn and winter seasonal programs. United States hospitality labor shortages drive hotel and casual dining substitution toward pre-mixed spiced formats that eliminate bartender intervention. TTB formula approval streamlining compresses time-to-market for these complex flavor systems.
- Herbal:Botanical and aromatic herb infusions including rosemary, basil, and lavender notes.
By volume, Citrus leads. By margin capture, Spiced is ahead.
Alcohol Content:
Alcohol tier determines taxation treatment, distribution licensing requirements, and permissible sales channels across state and national jurisdictions.
- Low Alcohol:Four to five percent ABV formulations competing directly with beer and hard seltzer alternatives. Japan concentrates demand as metropolitan consumers seek sessionable options for extended social occasions. State-level distribution law liberalization in select US states opens direct-to-retailer shipping routes that bypass traditional three-tier constraints for this tier.
- Standard Strength:Five to seven percent ABV positioning for mainstream cocktail replication.
- High Alcohol:Eight to ten percent ABV variants targeting value-conscious consumers seeking efficient intoxication per dollar spent.
- Premium Alcohol:Craft-distilled base spirits with ABV exceeding eight percent and ingredient transparency documentation. Kentucky and Jalisco base spirit supply concentration creates input vulnerability for this tier as premium whisky and tequila agave sourcing depends on concentrated distillery capacity. FDA updated labeling requirements mandate granular nutritional paneling exceeding previous voluntary standards.
By volume, Standard Strength leads. By value growth, Premium Alcohol is climbing the fastest.
Packaging Type:
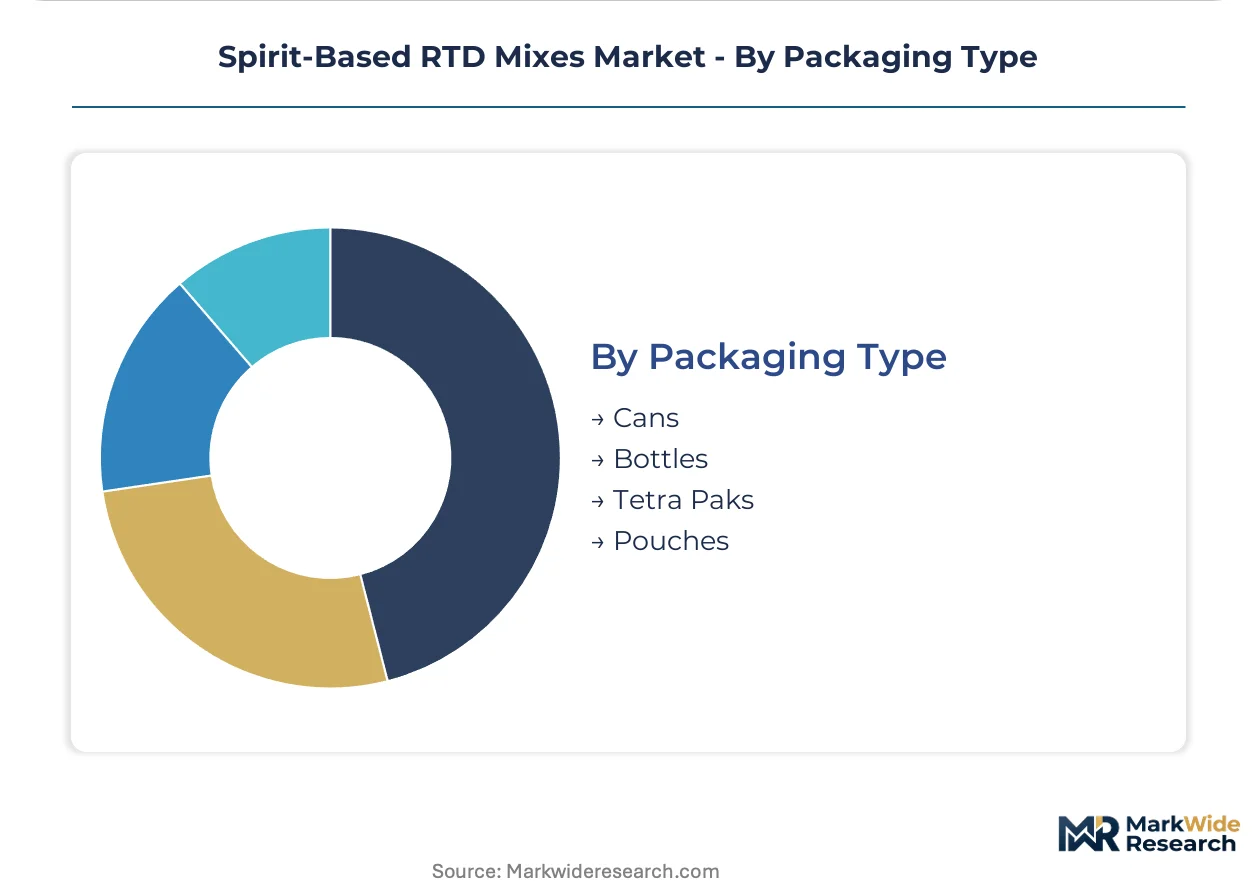
Packaging format dictates logistics efficiency, recycling economics, and occasion-based consumption access across retail and experiential channels.
- Cans:Aluminum single-serve formats dominating volume through logistics efficiency and established recycling infrastructure. Brazil and Japan municipal program expansions reduce packaging cost premiums versus glass-dependent competitors. Canning line retrofit capital requirements filter out smaller co-packers who cannot maintain hazard-critical control points across liquid blending operations.
- Bottles:Glass containers retaining preference in Japanese and Brazilian metropolitan on-premise markets where premium accounts reject can formats.
- Tetra Paks:Aseptic carton constructions for multi-serve and travel retail applications.
- Pouches:Flexible film formats capturing festival and outdoor event channels where glass prohibition and can weight create friction. Music venues and sporting events in United States coastal markets show concentrated adoption as operators seek reduced inventory risk versus dedicated tap lines. Pouch-format RTD cocktails bypass weight-based shipping cost penalties for remote event locations.
By volume, Cans lead. By channel expansion rate, Pouches are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA labeling mandates and TTB formula streamlining reshape United States market entry, while EFSA additive frameworks and Japan's METI efficiency standards create divergent compliance pathways across major producing jurisdictions.
United States
Millennial and Gen-Z consumers in coastal metropolitan markets compress beverage switching cycles between canned cocktails, hard seltzers, and craft beer. TTB accelerated review protocols compress time-to-market for compliant producers. California and Kentucky production clusters concentrate nitrogen dosing adoption and whiskey-based RTD formulation expertise.
Japan
Metropolitan consumers seek sessionable low-alcohol options for extended social occasions, driving highball format demand. METI efficiency standards govern canning line energy consumption and recycling infrastructure investments. Tokyo-Osaka corridor production facilities integrate Japanese whisky heritage into export-oriented RTD architecture.
Brazil
Municipal recycling program expansions reduce aluminum packaging cost premiums versus glass-dependent competitors. ANVISA beverage registration requirements shape import documentation workflows for foreign RTD entrants. São Paulo state manufacturing clusters scale citrus-forward formulation capacity for domestic and regional distribution.
Germany
EFSA additive restrictions limit synthetic flavor compound flexibility for US-exporting producers versus domestic European competitors. EU alcohol taxation frameworks elevate pricing architecture for standard-strength and flavored variants. Bavarian beverage technology suppliers retrofit canning lines for carbonated alcohol formulations.
United Kingdom
Hospitality labor shortages drive hotel and casual dining substitution toward pre-mixed formats that eliminate bartender intervention. HMRC alcohol duty structures differentiate tax treatment across ABV tiers. London metropolitan distribution networks concentrate premium-tier RTD import and specialty retail channels.
Spirit-Based RTD Mixes Market Vendor Landscape
Listed leaders compete with private specialists across production scale and heritage positioning, creating a tiered structure where consolidated multinational portfolios intersect with craft-distilled specialists. Publicly traded beverage conglomerates leverage captive distillery networks and regulatory affairs functions to absorb compliance cost escalations. Private specialists anchor regional production clusters through whiskey-based or highball-centric architectures. Dominant competitive moves include backward integration into base spirit supply and canning line capacity expansion to capture ISO 22000-certified production slots.
Within the heritage-positioning tier, Suntory Global Spirits Inc. and Cutwater Spirits LLC exemplify geographic specialization strategies, while Diageo Plc occupies a position representing consolidated multinational scale. Suntory Global Spirits Inc. anchors Japanese whisky highball export architecture. Cutwater Spirits LLC sits within California-focused whiskey-based production. Diageo Plc represents regulatory affairs depth and captive supply chain control.
| Leading Market Players |
|---|
| Constellation Brands Inc. |
| Suntory Global Spirits Inc. |
| Anheuser-Busch InBev SA/NV |
| Campari Group |
| Brown-Forman Corp. |
| Bacardi Ltd. |
| Pernod Ricard SA |
| Cutwater Spirits LLC |
| Diageo Plc |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between California and Kentucky distilleries and RTD co-packers lock in base-spirit supply visibility while stabilizing input costs across volatile agave and whiskey markets. These contracts concentrate pricing power among ISO 22000-certified facilities that can guarantee batch-to-batch proof consistency.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ISO 22000-compliant facilities commanding fifteen to twenty percent premiums over uncertified co-packers. Three-tier pricing structure across premium, standard, and economy levels stratifies by alcohol content and ingredient transparency documentation. Cost compression in economy tiers intensifies because aluminum can shortages and nitrogen dosing equipment scarcity elevate fixed costs. Hospitality buyers show highest price sensitivity, while specialty retailers absorb premium markups for heritage-positioned Japanese whisky formats.
Supply Chain Analysis
Kentucky and Jalisco anchor premium whiskey and tequila agave supply, with São Paulo state manufacturing clusters scaling citrus-forward formulation capacity for Latin American distribution. Raw material dependencies center on aluminum can sheet, liquid nitrogen for dosing systems, and natural flavor extracts subject to EFSA additive restrictions. Single-source vulnerability concentrates in Kentucky bourbon barrel stock, where aged inventory cycles create multi-year supply lags. Distribution runs through three-tier wholesale networks in the United States, with direct-to-retailer shipping emerging in select state-level liberalization corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where canning line capacity functions as the scarce resource layer, with interoperability between distillery base-spirit supply and co-packer blending infrastructure determining competitive access.
For Market Incumbents: Compound captive distillery control with ISO 22000-certified co-packer capacity reservations to defend against emerging craft-distilled entrants. Secure nitrogen dosing equipment slots through equipment financing partnerships. Prioritize backward integration into aluminum can manufacturing where municipal recycling infrastructure reduces packaging cost premiums. For New Entrants and Emerging Players: Festival and outdoor event channel service gaps where incumbents under-serve present the most penetrable white space, with pouch-format RTD cocktails bypassing weight-based shipping penalties. Target United States coastal metropolitan markets where hospitality labor shortages drive hotel and casual dining substitution toward pre-mixed formats. Deploy direct-to-retailer shipping permissions in select states as the primary go-to-market angle around traditional three-tier distribution constraints. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-cap specialists with captive Kentucky or Jalisco base-spirit supply and ISO 22000 certification already in place. Acquisition targets should demonstrate canning line retrofit completion and established TTB formula approval workflows. Watch for state-level distribution law liberalization as the inflection signal indicating channel bypass viability and margin expansion potential.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 22000 Certification Investment | Filters competitive access by eliminating uncertified co-packers from FDA and EFSA-compliant supply chains. |
| Nitrogen Dosing Line Retrofit | Preserves aromatic integrity in premium whiskey-based formats competing with freshly mixed bar cocktails. |
| Direct-to-Retailer Shipping Expansion | Bypasses three-tier distribution constraints in select US states with liberalized alcohol shipping permissions. |
| Japanese Whisky Heritage Positioning | Captures North American export channel white space through Suntory-style highball-centric product architecture. |
| Pouch-Format Festival Channel Launch | Reduces inventory risk at music venues and sporting events where glass prohibition and can weight create friction. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of TTB formula approval databases, FDA labeling guidance documents, and EFSA additive restriction registers. Primary interviews engaged regulatory affairs directors at multinational beverage conglomerates, co-packer operations managers at ISO 22000-certified facilities, and category buyers at United States coastal metropolitan specialty retailers. Secondary validation drew from customs trade data, SEC beverage segment filings, and municipal recycling program expansion records across Brazil and Japan. Bottom-up volume modeling triangulated against top-down value projections across the analysis window.
Segmentation dimensions modeled include product type architecture, alcohol content tier, packaging format, flavor profile positioning, and regional regulatory cluster. CAGRs were derived from trend-line extrapolation of volume and value outputs, cross-referenced against aluminum can supply forecasts and distillery capacity expansion announcements. Forecast inputs incorporated nitrogen dosing adoption rates, state-level distribution law liberalization timelines, and hospitality labor shortage persistence indicators throughout the projection horizon.
Underlying assumptions cover sustained FDA labeling enforcement, stable TTB formula approval timelines, and continued aluminum recycling infrastructure investment, with deviation risk concentrated in EFSA additive restriction tightening and Kentucky base-spirit supply disruption. Recalibration cycles align with material shifts in regulatory guidance, co-packer certification status changes, and channel economics from distribution law liberalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Cognac Brandy Market
Alcoholic Beverages
Global Brewery Filtration Market
Alcoholic Beverages
Canned Wine Market
Alcoholic Beverages
Smart Wine Cellar Market
Alcoholic Beverages
Global Wine Market
Alcoholic Beverages
Yorker Spouts Market
Alcoholic Beverages
Global Premium Gin Market
Alcoholic Beverages
Craft Rum Market
Alcoholic Beverages
South Africa Beverages Market
Alcoholic Beverages
Japanese Whisky Market
Alcoholic Beverages
Pre-Mixed/RTD Alcoholic Drinks Market
Alcoholic Beverages
Middle East and Africa Fermented Drinks Market
Alcoholic Beverages
Digital Shaker Market
Alcoholic Beverages
Balsam Bottle Market
Alcoholic Beverages
Beer Keg System Market
Alcoholic Beverages
Europe Beer Market