
 Europe Alcohol E-Commerce Market | 2026-2036
Europe Alcohol E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Alcohol E-Commerce Market Insights
Millennial and Gen Z consumers is reorganizing Europe's alcohol e-commerce landscape, displacing traditional older demographics as the primary online buyers. Heineken leverages its pan-European distribution infrastructure to dominate direct-to-consumer channels across multiple jurisdictions. Carlsberg Group anchors its digital strategy through proprietary online stores and third-party platform partnerships. Pernod Ricard differentiates via subscription services and mobile app investments targeting premium spirits buyers.
Europe alcohol e-commerce denotes the digital retailing of alcoholic beverages through internet-based platforms, requiring temperature-controlled last-mile logistics, age-verification protocols, and compliance with varying national excise duties. Wine and spirits command the highest margin pools within product type segments, while beer sustains volume leadership through repeat purchase frequency. Third-party platforms and mobile apps represent the fastest-growing sales channels, though online stores retain superior margin capture for producers controlling their own customer data and pricing architecture.
EU REACH, national excise frameworks, and country-specific alcohol marketing restrictions collectively shape product availability, cross-border fulfillment feasibility, and platform operating licenses across member states. EMA-aligned labeling standards and GDPR-mandated data handling further constrain how retailers personalize offers and manage customer identities. Stakeholders must monitor divergent national licensing regimes and delivery-time alcohol advertising bans as these determine which customer segments remain addressable through digital channels.
Market Dynamics
EU REACH and the Geoblocking Regulation are compressing cross-border fulfillment feasibility while national licensing divergences fragment platform operating rights across member states. Temperature-controlled last-mile logistics and age-verification protocols now determine which customer segments remain digitally addressable.
Growth Catalysts
- GDPR-compliant data architectures:Platforms investing in consent-first customer identity management unlock personalized subscription offerings without triggering EDPB enforcement actions.
- Same-day delivery networks:Mature urban logistics infrastructure in Germany, France, and the United Kingdom enables scheduled alcohol delivery windows that capture repeat purchase frequency.
- Urban millennial consumption patterns:Digital-native buyers in metropolitan clusters across the Netherlands and Spain are reorganizing purchase occasions toward app-based discovery and mobile checkout.
Market Restraints
- Refrigerated fleet capital intensity:Cold-chain compliance for wine and spirits fulfillment demands dedicated vehicle investment that squeezes unit economics for regional operators.
- National excise duty asymmetries:Divergent alcohol taxation frameworks between Sweden, Finland, and continental EU members create arbitrage enforcement risks that deter cross-border inventory positioning.
- Delivery-time advertising prohibitions:France and Ireland enforce strict bans on alcohol marketing during fulfillment windows that constrain customer acquisition tactics.
Strategic Opportunities
- Underpenetrated Eastern European markets:Poland and Romania exhibit low online alcohol penetration relative to Western benchmarks, offering first-mover platform expansion potential.
- EMA-aligned digital labeling:Automated compliance with evolving EU ingredient disclosure standards enables real-time product page updates without physical packaging redesign.
- Subscription-loyalty program convergence:Premium spirits buyers in Belgium and Austria respond to curated monthly selections that reduce customer acquisition cost through retention mechanics.
Industry Challenges
- Age-verification technology integration:Biometric identity checks at point-of-delivery require coordination with national ID systems that lack API standardization.
- Excise duty warehousing complexity:Bonded storage obligations for high-alcohol products fragment inventory positioning and complicate dynamic pricing algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Alcohol E-Commerce Market |
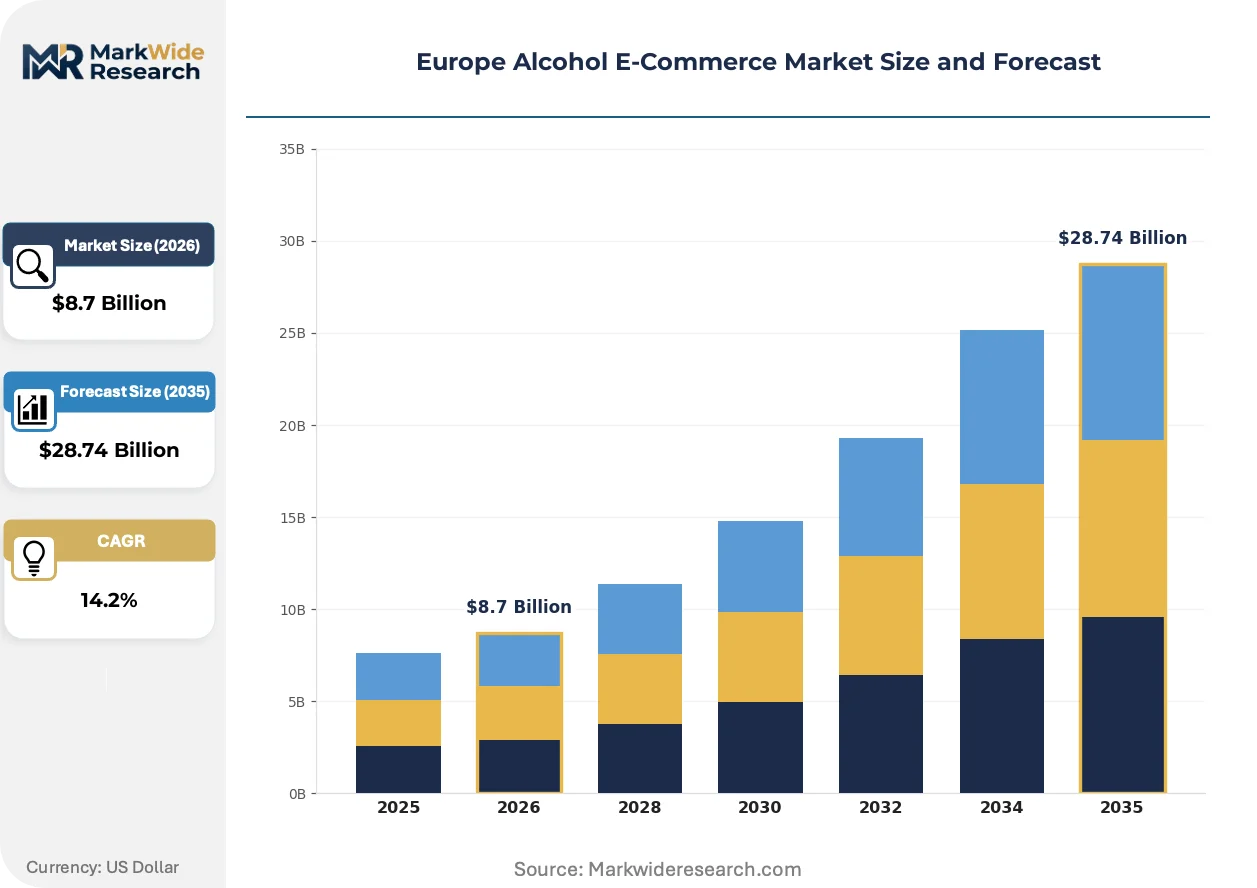
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beer, Wine, Spirits, Liqueurs Customer Type: Consumers, Retailers, Wholesalers, Bars Delivery Mode: Home Delivery, Click & Collect, Same-Day Delivery, Scheduled Delivery Sales Channel: Online Store, Mobile App, Third-Party Platform, Subscription Service |
| Companies Covered | Heineken, Carlsberg Group, Anheuser-Busch InBev, Constellation Brands, Campari Group, Diageo, Bacardi Limited, Brown-Forman, Pernod Ricard, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Alcohol E-Commerce Market Trends and Innovations
Digital retail infrastructure is reorganizing alcohol distribution through three interconnected shifts: biometric compliance tools, regulatory automation, and subscription-based customer relationships. These forces are compressing traditional wholesale margins while elevating data-capture capabilities.
Blockchain-enabled provenance tracking is supplanting paper-based certificate-of-origin documentation for premium wine and spirits shipments. Collectors and gift buyers in Scandinavia and the United Kingdom are demanding immutable vineyard-to-door chain-of-custody records. This technology is enabling direct authentication that bypasses traditional importer verification layers and compresses margin extraction by middle-tier distributors.
EU AI Act transparency requirements are reshaping how recommendation engines surface alcohol products to platform users. Automated decision-making systems must now disclose logic pathways for personalized offers, forcing retailers to rearchitect customer-facing algorithms. Premium spirits segments in Germany and France face the steepest compliance costs given their reliance on predictive taste-matching tools.
Subscription box curation is reorganizing discovery patterns among urban professionals who previously relied on retail sommelier guidance. Monthly spirits selections delivered to Amsterdam, Copenhagen, and Lisbon apartments are displacing impulse purchases at physical wine merchants. This behavioral pivot is most pronounced among millennial households where convenience scheduling overrides traditional shopping occasions.
Europe Alcohol E-Commerce Market Segmentation
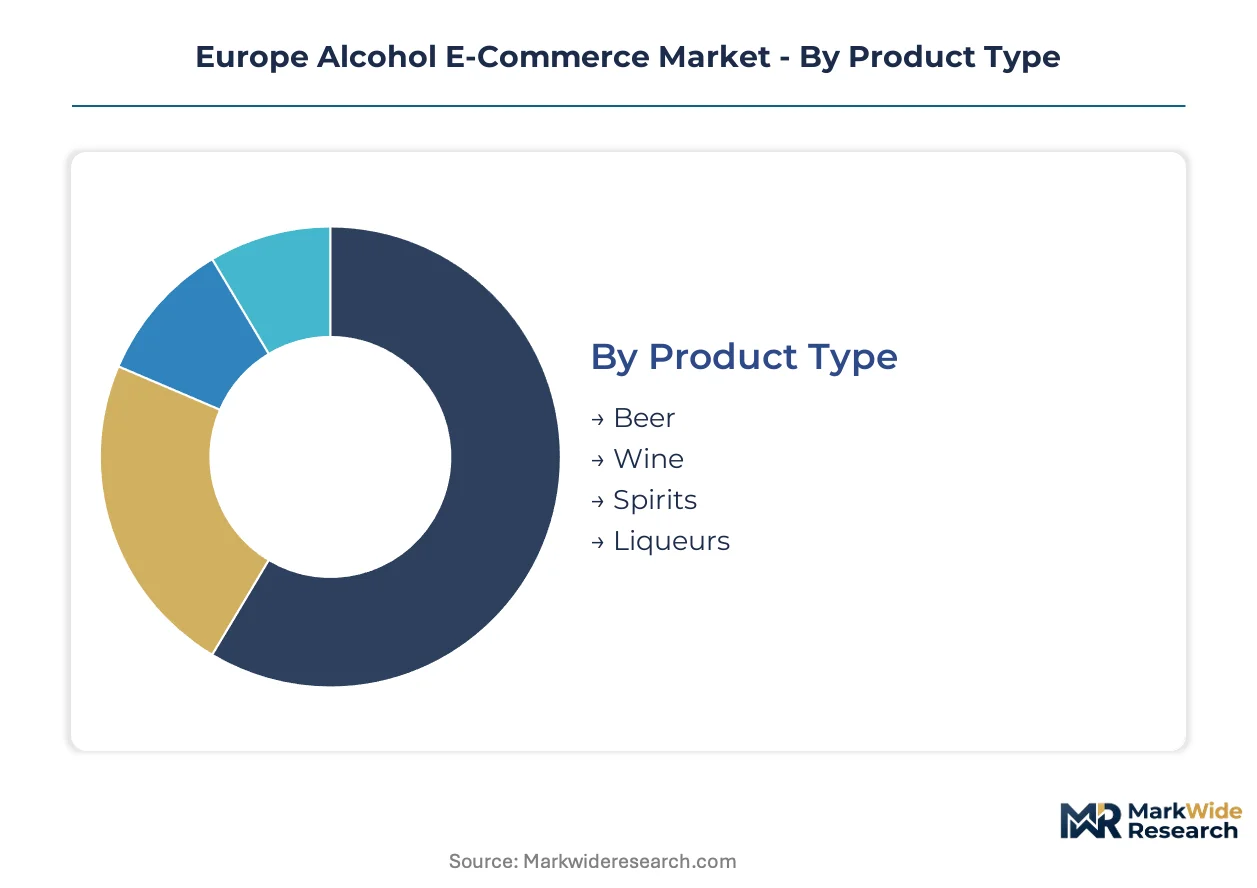
Segmentation in Europe alcohol e-commerce determines which logistics investments platforms prioritize and which regulatory burdens apply to specific fulfillment pathways. Wine and spirits require temperature-controlled infrastructure that beer does not, while B2B customer types trigger wholesale licensing distinct from consumer retail permissions.
Product Type:
Wine and spirits face intensifying substitution pressure from ready-to-drink cocktails and low-alcohol alternatives, while beer maintains habitual purchase frequency that resists displacement.
- Wine:Temperature-sensitive varietals demand cold-chain integrity from bonded warehouse to doorstep, with French and Italian origin labels commanding premium positioning in German and UK urban markets. Bordeaux and Champagne shipments concentrate in subscription channels where curated selections justify higher per-bottle margins.
- Spirits:High-proof products trigger stricter excise warehousing obligations across Sweden, Finland, and Ireland, fragmenting inventory positioning and complicating dynamic pricing algorithms. Whisky and gin purchases cluster in gift occasions where blockchain provenance verification increasingly influences buyer selection.
- Beer:Repeat purchase frequency sustains volume leadership through mobile app reordering and scheduled delivery subscriptions in Amsterdam and Copenhagen metropolitan clusters.
- Liqueurs:Seasonal demand spikes around holiday periods in Belgium and Austria drive inventory pre-positioning challenges for third-party platforms.
Beer anchors the volume base while spirits gains share at the steepest rate.
Customer Type:
Cost tier differentiation separates high-touch B2B relationships from automated consumer transactions, with wholesale accounts demanding credit terms and compliance documentation that retail channels bypass.
- Consumers:Digital-native millennials and Gen Z buyers in metropolitan Spain and the Netherlands drive mobile-first discovery patterns, with age-verification protocols at delivery determining addressable segment size. GDPR-compliant identity management unlocks personalized subscription offerings without triggering EDPB enforcement actions.
- Retailers:Independent wine merchants in France and Italy source through B2B platforms to supplement depleted inventory between traditional distributor shipments, requiring invoice-level excise documentation.
- Wholesalers:Cross-border arbitrage enforcement risks deter inventory positioning between high-tax Nordic markets and continental EU members.
- Bars:On-trade procurement through digital channels concentrates in London and Berlin where cocktail program experimentation demands rapid spirits replenishment.
Consumers dominate transaction volume while retailers expand their digital procurement most quickly.
Delivery Mode:
Application urgency separates immediate consumption occasions from planned inventory builds, with same-day services capturing impulse purchases that scheduled windows cannot address.
- Home Delivery:Standard fulfillment to residential addresses constitutes the baseline service tier, with France and Ireland enforcing delivery-time advertising bans that constrain customer acquisition tactics during fulfillment windows.
- Same-Day Delivery:Mature urban logistics infrastructure in Germany, France, and the United Kingdom enables scheduled alcohol delivery windows that capture repeat purchase frequency among convenience-oriented households.
- Click & Collect:Pickup points at retail partners reduce last-mile costs for platforms lacking proprietary fleet coverage in secondary Polish and Romanian cities.
- Scheduled Delivery:Subscription-aligned timing allows temperature-controlled batching that improves refrigerated fleet utilization for wine shipments.
Home Delivery anchors the volume base while same-day delivery gains share at the steepest rate.
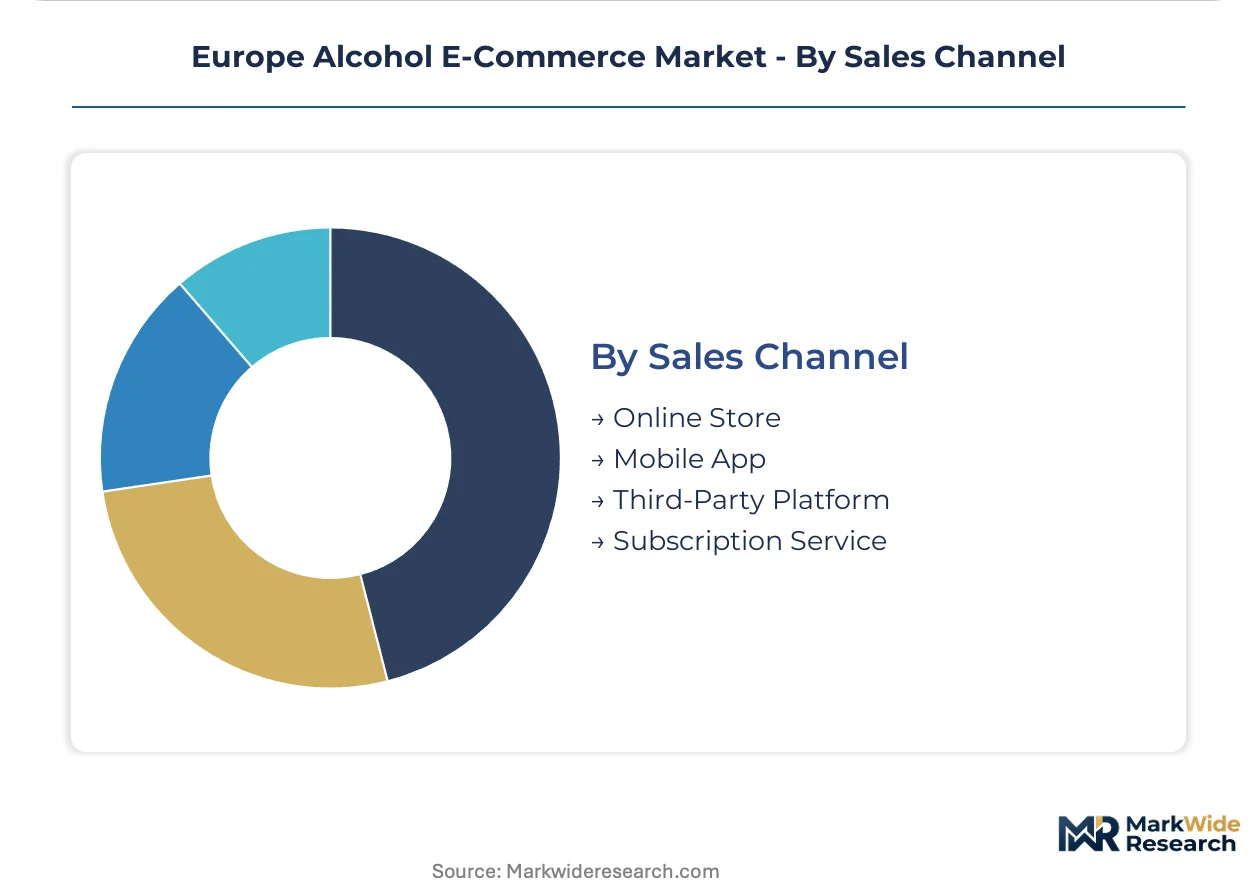
Sales Channel:
Margin capture separates owned-channel data control from platform-dependent customer relationships, with subscription mechanics reducing acquisition costs through retention programs.
- Online Store:Producer-controlled storefronts retain superior margin capture and pricing architecture autonomy, with Heineken and Carlsberg leveraging pan-European distribution infrastructure to dominate direct-to-consumer channels across multiple jurisdictions.
- Subscription Service:Curated monthly selections targeting premium spirits buyers in Belgium and Austria reduce customer acquisition cost through retention mechanics that displace impulse purchases at physical wine merchants.
- Mobile App:Discovery and checkout optimization captures urban millennial consumption patterns in Lisbon and Copenhagen where convenience scheduling overrides traditional shopping occasions.
- Third-Party Platform:Marketplace aggregation expands reach for regional operators lacking proprietary logistics, though margin compression and customer data loss constrain long-term positioning.
Third-party platforms anchor the volume base while subscription services gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dutch logistics hubs channel temperature-controlled wine shipments into German and UK metropolitan markets, while Nordic excise asymmetries redirect cross-border inventory positioning toward bonded warehouses in Denmark and Poland.
Germany
Urban millennial demand in Berlin and Hamburg drives same-day delivery subscriptions for craft beer and natural wine selections. The country's Federal Cartel Office monitors platform concentration under national competition law, constraining marketplace dominance by single operators. Bavarian logistics clusters around Munich anchor refrigerated fleet operations that serve Alpine corridor markets.
United Kingdom
London's cocktail culture sustains rapid spirits replenishment through app-based procurement for bar and restaurant accounts. HMRC excise warehousing rules fragment inventory positioning between England and Scotland, complicating unified pricing algorithms. Manchester and Birmingham distribution centers capture recurring subscription volume from convenience-oriented households.
France
Bordeaux and Champagne origin labels command premium positioning in Parisian subscription channels where curated selections justify higher per-bottle margins. The country's Loi Évin restrictions enforce strict delivery-time advertising bans that constrain customer acquisition tactics during fulfillment windows. Lyon logistics hubs coordinate temperature-controlled batching for Rhône Valley wine shipments.
Netherlands
Amsterdam metropolitan clusters exhibit the densest same-day delivery penetration for beer and ready-to-drink cocktails in Europe. Dutch bonded warehouse infrastructure under EU customs code enables cross-border fulfillment arbitrage into Belgian and German border regions. Rotterdam port logistics integrate maritime wine imports with last-mile cold-chain distribution.
Poland
Warsaw and Krakow urban markets show accelerating mobile app adoption for alcohol discovery among digitally-native younger demographics. The country's national excise framework maintains lower duty rates than Nordic neighbors, attracting cross-border inventory positioning from regional operators. Silesian logistics corridors develop refrigerated capacity to serve emerging subscription demand.
Europe Alcohol E-Commerce Market Competitive Landscape
Listed brewers compete with private distillers across platform access and direct-to-consumer data ownership. Market structure concentrates around pan-European distribution infrastructure controlled by beverage conglomerates, while specialist retailers fragment across national licensing boundaries. Two archetypes dominate: vertically integrated producers operating proprietary online stores, and aggregator platforms dependent on third-party logistics partnerships. Competitive moves center on subscription service launches and biometric age-verification technology licensing.
Among Dutch-British and Danish brewing groups, Heineken and Carlsberg exemplify the integrated-producer archetype through controlled direct-to-consumer channels. Pernod Ricard occupies a position within the premium-spirits specialist tier, anchoring subscription-based customer retention mechanics. These three entities represent contrasting strategic postures toward data ownership and margin capture architecture.
| Leading Market Players |
|---|
| Heineken |
| Carlsberg Group |
| Anheuser-Busch InBev |
| Constellation Brands |
| Campari Group |
| Diageo |
| Bacardi Limited |
| Brown-Forman |
| Pernod Ricard |
| Others |
Pricing and Supply Chain Analysis
Scheduled delivery subscriptions lock in refrigerated fleet capacity and price visibility for wine merchants across German and UK metropolitan markets, insulating platforms from spot-rate volatility in temperature-controlled logistics.
Pricing Analysis
Legacy age-verification technology versus next-generation biometric systems versus emerging AI-driven compliance tools creates a three-tier pricing structure across premium, standard, and economy levels in the European alcohol e-commerce landscape. Subscription services in Belgium and Austria command premium positioning through curated selections, while third-party platforms compete on per-unit transactional economics with compressed margins. Pricing pressure stems from refrigerated fleet capital intensity squeezing unit economics for regional operators. B2B wholesale accounts show lowest price sensitivity due to invoice-level excise documentation requirements, whereas urban millennial consumers exhibit highest sensitivity to delivery fees and subscription minimums.
Supply Chain Analysis
Rotterdam port congestion and container availability constraints on Atlantic trade lanes disrupt maritime wine imports destined for Dutch bonded warehouses and German distribution centers. Supply concentration centers on France, Italy, and Spain for wine provenance; Germany and the Netherlands for logistics infrastructure; and Poland for emerging cold-chain capacity. Raw material dependencies include temperature-controlled packaging materials, bonded warehouse space, and biometric verification hardware. Single-source vulnerability sits with pan-European distribution infrastructure controlled by beverage conglomerates. Distribution runs through vertically integrated producer channels and third-party platform partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across national licensing regimes creates white-space opportunities for platforms that master jurisdiction-specific compliance, as urban millennial demand shifts toward app-based discovery and mobile checkout.
For Market Incumbents: Secure proprietary customer data architectures through GDPR-compliant identity management systems that unlock personalized subscription offerings without EDPB enforcement exposure. Consolidate refrigerated fleet operations around Bavarian and Dutch logistics clusters to defend against margin compression from third-party logistics markups. Channel control through owned mobile apps represents the critical defensive lever against platform-dependent customer relationships.
For New Entrants and Emerging Players: Differentiate on biometric age-verification technology integration targeting markets with strict delivery-time advertising prohibitions like France and Ireland. White-space concentration sits in Poland and Romania where online alcohol penetration remains below Western benchmarks. A direct-to-consumer launch with subscription-loyalty program convergence offers the most penetrable go-to-market angle for premium spirits buyers in Belgium and Austria.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mid-cap specialists with captive refrigerated logistics and established GDPR-compliant data architectures. Long-term viability over the projection horizon hinges on platforms controlling both customer identity data and temperature-controlled fulfillment networks. The signal to watch is regulatory harmonization momentum around EU-wide alcohol marketing restrictions that would favor scaled compliance investments over fragmented national adaptations.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Age-Verification Deployment | GDPR-aligned identity checks at delivery unlock addressable segments in France and Ireland. |
| Subscription-Loyalty Program Convergence | Curated monthly selections reduce customer acquisition costs for premium spirits buyers. |
| Refrigerated Fleet Consolidation | Bavarian and Dutch logistics clusters improve cold-chain economics for wine shipments. |
| EMA-Aligned Digital Labeling Investment | Automated compliance enables real-time product page updates without packaging redesign. |
| Blockchain Provenance Tracking Integration | Immutable chain-of-custody records bypass traditional importer verification in Scandinavia. |
Research Methodology
A standing panel of platform operations directors, regulatory compliance officers, cold-chain logistics managers, and subscription service product leads provided ongoing calibration across the primary research phase. Primary interviews combined with secondary validation from EMA labeling guidance documents, EU customs bonded warehouse records, national excise duty frameworks, and GDPR enforcement case databases. Bottom-up platform transaction modeling and top-down beverage category sizing were triangulated for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type, customer type, delivery mode, and sales channel alongside jurisdiction-specific regulatory cluster variations. CAGRs were derived from cohort-based subscription retention curves and same-day delivery penetration trajectories. Industry-specific forecast inputs encompassed urban millennial consumption pattern shifts and refrigerated fleet capacity expansion timelines.
Material uncertainties — regulatory divergence in national alcohol marketing restrictions, excise duty asymmetry enforcement actions, and biometric identity system API standardization delays — sit outside the modeled envelope. Forecasts reflect assumptions around GDPR compliance cost trajectories and temperature-controlled logistics investment cycles. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
South America Fermented Drinks Market
Alcoholic Beverages
Sparkling Red Wine Market
Alcoholic Beverages
Fruit Beer Market
Alcoholic Beverages
Canada Tequila Market
Alcoholic Beverages
Pisco Market
Alcoholic Beverages
Vermouth Market
Alcoholic Beverages
Canned Wine Market
Alcoholic Beverages
Beer Adjuncts Market
Alcoholic Beverages
Middle East and Africa Beer Market
Alcoholic Beverages
Single Serve Wine Market
Alcoholic Beverages
Beer Keg System Market
Alcoholic Beverages
Yorker Spouts Market
Alcoholic Beverages
Automated Brewing System Market
Alcoholic Beverages
Beer Stabilizers Market
Alcoholic Beverages
Cocktail Market
Alcoholic Beverages
Wine Filling Machine Market