
 Europe Craft Beer Market | 2026-2036
Europe Craft Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Craft Beer Market Analysis
Subscription-based beer clubs and membership programs is expanding how European craft breweries monetize recurring consumer relationships. BrewDog leverages its direct-to-consumer subscription model to sustain repeat purchases across its UK and European taproom network. Duvel Moortgat Brewery anchors its portfolio through Belgian farmhouse ale specialization, competing against larger multinational portfolios. Mikkeller A/S differentiates through limited-edition collaborations and experimental hop profiles, occupying a premium niche in Scandinavian and German urban markets.
Europe craft beer denotes independently produced, small-batch fermented beverages typically brewed with traditional malted barley, proprietary yeast strains, and aroma-forward hops at volumes below regional mass-production thresholds, serving both experiential consumption occasions and connoisseur-led palate exploration. Barrel-aged releases command the highest margin pools due to extended aging cycles and scarcity positioning, while IPA formulations lead volume growth across urban on-premise channels in Berlin and Amsterdam. Traditional brewing methods retain dominance in Bavaria and Bohemia, though hybrid techniques combining wild fermentation with controlled temperature profiling are gaining traction among younger demographics.
EU Green Deal carbon benchmarks and REACH chemical safety standards shape brewery equipment procurement and ingredient sourcing across member states, with EFSA labeling requirements further dicturing nutritional transparency claims. Germany's BfR and France's DGCCRF enforce strict purity and contaminant thresholds that filter market access for non-compliant imports. Stakeholders must monitor evolving packaging-waste directives and energy-efficiency mandates that will determine capital allocation priorities for brewhouse upgrades and supply chain restructuring.
Market Dynamics
The EU Green Deal's carbon-reduction mandates are forcing brewhouse capital reallocation toward energy-efficient kettles and water-recovery systems, compressing operating margins for smaller independents while advantaging scaled operators with retrofit capital.
Growth Catalysts
- EU Green Deal mandates:Carbon benchmarks push breweries toward renewable thermal systems and closed-loop water infrastructure, creating equipment upgrade cycles across Germany, France, and Belgium.
- Gastropub channel expansion:Premium on-premise consumption in independent bars accelerates keg-format demand and experimental small-batch rotations in urban UK and Dutch markets.
- Wild fermentation hybridization:Controlled temperature profiling combined with spontaneous inoculation attracts younger demographics seeking terroir-linked authenticity in Scandinavian craft segments.
Market Restraints
- Barrel-aging capital intensity:Extended aging cycles tie up working capital for 12-36 months, constraining cash flow for breweries under ten thousand hectoliters annual output.
- Hop supply concentration:Aroma-forward varietal production concentrates in Pacific Northwest US and select German growing regions, exposing European brewers to currency and climate volatility.
- REACH chemical compliance:ECHA registration requirements for cleaning agents and process chemicals add fixed compliance costs that scale disproportionately for microbreweries.
Strategic Opportunities
- Subscription direct-to-consumer:Recurring revenue models bypass wholesale margin compression and build proprietary customer data assets in fragmented UK and Irish markets.
- EFSA nutritional transparency:Voluntary labeling ahead of mandatory disclosure deadlines commands shelf-space premiums in French and Italian retail channels.
- Packaging-waste directive alignment:Reusable bottle pooling systems and aluminum can circularity investments qualify for green financing instruments in Benelux and Nordic regions.
Industry Challenges
- Master brewer talent scarcity:Traditional apprenticeship pipelines fail to supply sufficient wild fermentation and barrel-aging specialists for experimental program expansion.
- BfR purity threshold navigation:Germany's contaminant and additive restrictions filter import access and require reformulation for cross-border distribution within the region.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Craft Beer Market |
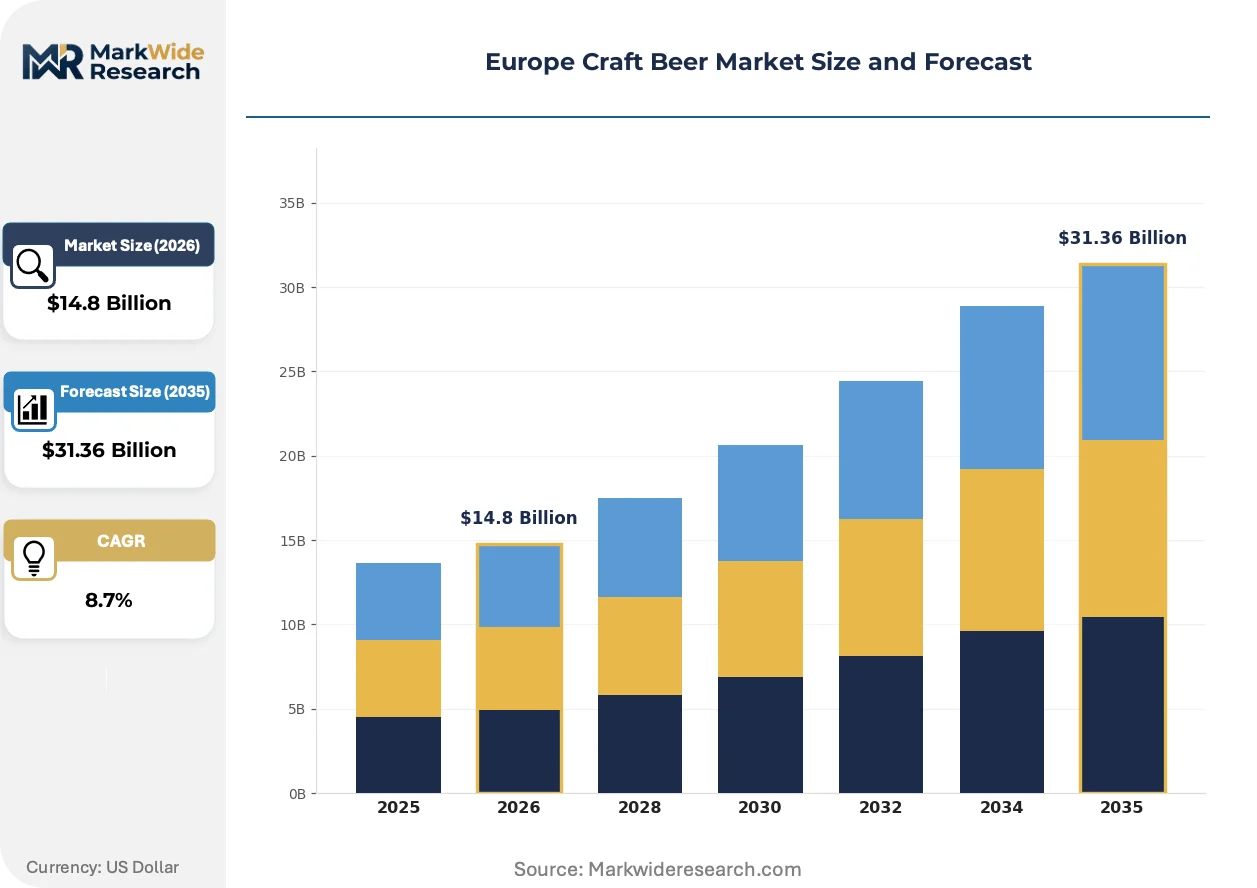
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IPA, Stout, Lager, Wheat Beer Brewing Method: Traditional, Innovative, Hybrid, Barrel-Aged Distribution Channel: On-Premise, Off-Premise, E-commerce, Wholesale Customer Type: Retail Consumers, Bars, Restaurants, Events |
| Companies Covered | Anheuser-Busch InBev, Molson Coors Beverage Company, BrewDog, Erdinger Brewery, Duvel Moortgat Brewery, Carlsberg Group, Mikkeller A/S, Radeberger Brewery, Heineken N.V., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Craft Beer Market Emerging Trajectories
Electrification of brewhouse thermal systems intersects with regulatory pressure and consumer preference for provenance transparency, compressing legacy equipment replacement cycles while opening premium positioning for carbon-neutral certified production.
Heat pump technology is electrifying traditional kettle boiling and wort heating processes previously dependent on natural gas combustion. Mid-scale breweries in Denmark and the Netherlands adopt these systems fastest due to favorable grid carbon intensity and green tariff structures. This electrification is compressing Scope 1 emissions reporting timelines and qualifying early adopters for EU Green Deal transition financing.
REACH chemical safety standards now extend to brewing adjuncts and flavoring compounds, requiring full supply chain substance registration. ECHA enforcement actions against non-compliant imports tighten ingredient sourcing options for experimental programs. Belgian and Czech traditionalists face particular friction where heritage recipes incorporate botanicals lacking full dossier documentation.
Urban consumers rotate toward membership-based access models that trade volume discounts for exclusivity and co-creation input. Independent UK taprooms and Scandinavian bottle shops displace supermarket distribution for limited releases. Berlin and Amsterdam demonstrate the strongest concentration of this behavior, where digital-native demographics prioritize experiential consumption over price efficiency.
Europe Craft Beer Market Segmentation
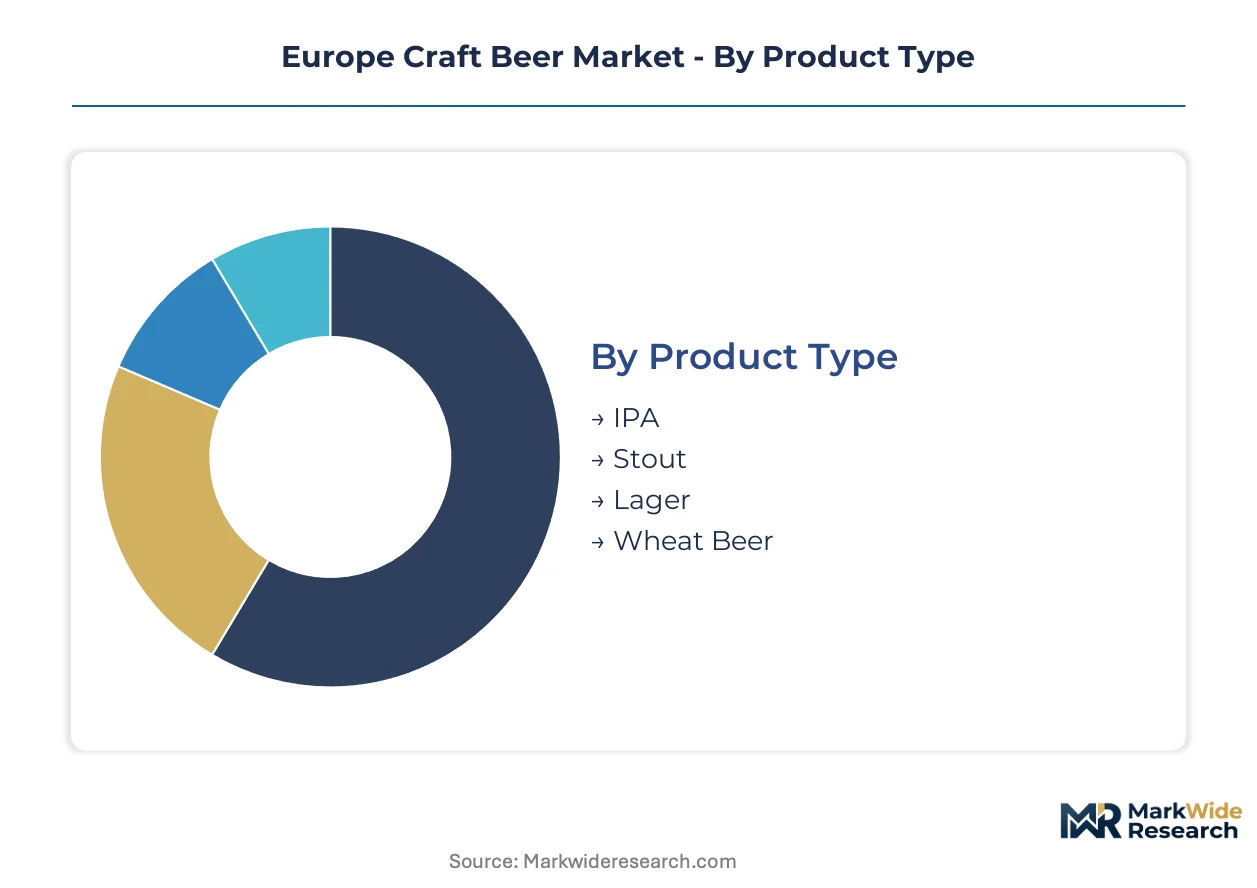
Craft beer segmentation in Europe reflects divergent capital intensity across production methods and channel access economics. Distinct margin profiles emerge between barrel-aged specialty releases and high-volume keg formats distributed through gastropub networks.
Product Type:
Supply concentration tilts toward hop-forward formulations where ingredient sourcing networks and brewing expertise cluster in Germany, the United Kingdom, and Belgium.
- IPA:Aroma-forward hop profiles define this category, with dry-hopping techniques requiring specialized cold-chain logistics. Demand concentrates in Berlin and Amsterdam urban on-premise channels where experimental small-batch rotations drive repeat visitation. German Hallertau and US Pacific Northwest hop contracts expose brewers to currency volatility.
- Stout:Dark roasted malt character with chocolate and coffee notes, traditionally associated with Irish and British brewing heritage. Barrel-aging programs in Ireland and Scotland tie up working capital for extended maturation cycles. UK independent bars anchor volume through winter seasonal releases.
- Lager:Bottom-fermented clarity standards dominate Bavarian production heritage. Czech Bohemia maintains traditional decoction mashing for authenticity positioning.
- Wheat Beer:Hefeweizen and witbier traditions persist in Belgian and German regional specialties. Banana-clove ester profiles from specialized yeast strains limit production flexibility.
IPA absorbs the bulk of installed capacity; Stout is expanding most quickly through premium barrel-aged positioning.
Brewing Method:
Capital deployment intensity varies dramatically across methods, with extended aging cycles creating divergent cash flow profiles for European independents.
- Traditional:Reinheitsgebot-compliant purity protocols restrict ingredient palettes to malted barley, hops, water, and yeast. Bavarian breweries leverage this heritage for export authenticity certification. BfR contaminant thresholds enforce strict quality gates for cross-border distribution within Germany.
- Innovative:Experimental hop varieties, fruit adjuncts, and non-traditional fermentation substrates attract younger demographics in Scandinavian urban markets. REACH chemical registration requirements for novel flavoring compounds constrain recipe development timelines.
- Hybrid:Controlled temperature profiling combined with spontaneous inoculation merges wild fermentation terroir with reproducible quality. Danish and Dutch mid-scale operators pioneer this approach for differentiation.
- Barrel-Aged:Extended 12-36 month maturation in ex-spirit casks commands scarcity premiums. Working capital intensity filters participation to scaled operators with balance sheet capacity.
Traditional methods retain the largest production base; Barrel-Aged commands the steepest expansion trajectory in revenue per hectoliter.
Distribution Channel:
Channel economics determine margin capture, with direct access models bypassing wholesale compression in fragmented UK and Irish markets.
- On-Premise:Gastropub and independent bar consumption drives keg-format demand with highest per-liter margins. UK and Dutch urban clusters show strongest concentration of premium experimental rotations.
- Off-Premise:Supermarket and specialty retail shelf space competition intensifies with EFSA nutritional transparency requirements. French and Italian channels reward early voluntary labeling compliance.
- E-commerce:Subscription direct-to-consumer models build proprietary customer data assets. BrewDog's UK and European taproom network demonstrates recurring revenue scalability.
- Wholesale:Third-party distributor relationships compress margins but enable geographic expansion for sub-scale producers.
On-Premise captures the majority of value creation; E-commerce is gaining share fastest through membership-based access models.
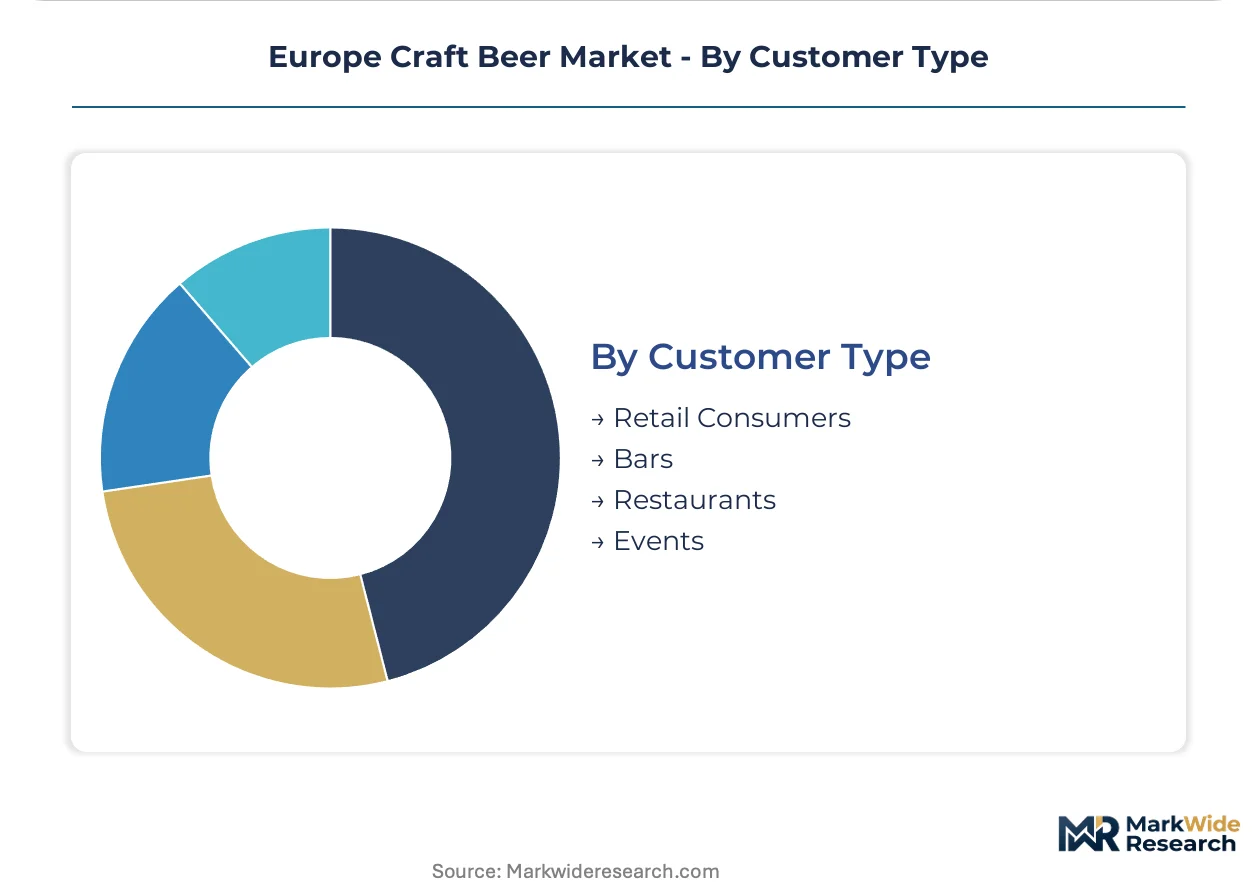
Customer Type:
End-use concentration shapes product format and pricing architecture across experiential versus convenience-oriented occasions.
- Retail Consumers:Bottle shop and supermarket purchasers prioritize provenance transparency and packaging sustainability credentials. Nordic and Benelux markets show strongest reusable bottle pooling system adoption.
- Bars:Independent on-premise accounts drive experimental small-batch demand with rotating tap programs. Berlin and Amsterdam demonstrate highest concentration of digital-native experiential consumption.
- Restaurants:Food-pairing focused selections emphasize lower-ABV session formats and Belgian farmhouse ale traditions.
- Events:Festival and temporary activation formats require mobile dispensing infrastructure and limited-release exclusivity positioning.
Bars account for the dominant share of premium volume; Events are climbing the fastest as experiential marketing investments intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production heritage concentrates in Bavaria and Bohemia while consumption accelerates in urban UK and Dutch clusters. This geographic split shapes capital allocation toward export capacity versus taproom experience infrastructure. Regulatory divergence across member states filters market access for cross-border operators.
Germany
Bavaria's Reinheitsgebot tradition anchors premium lager exports while Berlin's experimental microbreweries drive IPA innovation. BfR purity thresholds enforce strict contaminant limits that complicate ingredient sourcing for wild fermentation programs. The Hallertau hop-growing region supplies aroma-forward varietals to domestic and neighboring brewers.
United Kingdom
Gastropub channel expansion in London and Manchester sustains keg-format demand for rotating small-batch releases. REACH chemical registration requirements for cleaning agents add fixed compliance burdens to microbrewery operations. Scottish barrel-aging specialists in Edinburgh and Glasgow command scarcity premiums for extended-maturation releases.
Belgium
Farmhouse ale heritage in Flemish Brabant competes with multinational portfolio consolidation in Leuven. EFSA nutritional transparency mandates shape labeling investments ahead of mandatory disclosure deadlines. Brussels and Antwerp urban consumers drive membership-based access models for limited-edition releases.
Netherlands
Amsterdam's digital-native demographics prioritize experiential consumption over price efficiency in independent bar channels. EU Green Deal carbon benchmarks accelerate heat pump adoption in mid-scale brewhouse thermal systems. Rotterdam port logistics enable efficient import distribution for US Pacific Northwest hop contracts.
France
DGCCRF enforcement actions tighten purity and additive restrictions for craft imports entering Paris and Lyon retail channels. Voluntary EFSA nutritional labeling ahead of deadlines commands shelf-space premiums in French hypermarkets. Alsatian brewing traditions near Strasbourg blend German heritage with experimental French hop cultivation.
Europe Craft Beer Market Vendor Landscape
Capital-heavy producers with captive brewing infrastructure compete with asset-light brand architects outsourcing production to third-party facilities. The market structure fragments across multinational portfolio divisions, mid-scale regional independents, and microbrewery taproom operators. Three archetypes dominate: heritage-anchored traditionalists, subscription-scaled direct-to-consumer platforms, and experimental collaboration specialists. Competitive moves concentrate on vertical integration into ingredient sourcing and geographic expansion through taproom network replication.
Among UK-based operators, BrewDog exemplifies subscription-scaled direct-to-consumer architecture. Duvel Moortgat Brewery occupies a position within Belgian heritage-anchored traditionalists. Mikkeller A/S represents the experimental collaboration specialist archetype in Scandinavian urban markets.
| Leading Market Players |
|---|
| Anheuser-Busch InBev |
| Molson Coors Beverage Company |
| BrewDog |
| Erdinger Brewery |
| Duvel Moortgat Brewery |
| Carlsberg Group |
| Mikkeller A/S |
| Radeberger Brewery |
| Heineken N.V. |
| Others |
Supply Flow & Price Mechanics
Master brewer scarcity in Bavaria and Bohemia widens labor-cost spreads between heritage traditionalists and experimental independents, compressing mid-tier margins while premium barrel-aged releases capture scarcity premiums through extended aging cycles.
Pricing Analysis
Margin tightening in keg-format standard releases reflects wholesale distributor compression and gastropub buyer consolidation in UK and Dutch urban clusters. Three-tier pricing structure across premium barrel-aged, standard draft, and economy packaged formats separates scarcity-positioned releases from volume-driven core lines. Price differentiation hinges on certification tier—Reinheitsgebot-compliant Bavarian exports command heritage premiums—and vertical integration into captive taproom networks. Cost-down pressure on standard-format packaged beer accelerates because supermarket private-label expansion in France and Germany erodes branded shelf space. Independent bars demonstrate lowest price sensitivity for rotating experimental small-batches; retail hypermarket buyers in Southern Europe exhibit highest sensitivity to per-liter differentials.
Supply Chain Analysis
Aroma-forward hop supply rests on Pacific Northwest US growing regions and Germany's Hallertau belt, exposing European brewers to currency volatility and climate-driven yield variability. Raw material dependencies concentrate on specialty malted barley from France and UK, proprietary yeast strain cultivation in Belgium and Denmark, and ex-spirit cask sourcing from Scottish and Irish distilleries. Single-source vulnerability concentrates in US hop varietals where European acreage remains insufficient for aromatic substitution. Distribution runs through third-party wholesale networks for sub-scale independents, while scaled operators with captive taproom infrastructure bypass margin compression through direct-to-consumer subscription models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive advantage in European craft beer is consolidating around upstream control over ingredient sourcing and downstream captive channel access, forcing capital allocation toward vertical integration or asset-light brand architecture.
For Market Incumbents: Cement Reinheitsgebot-certified export positioning through BfR purity threshold compliance investments that filter import competition in German-speaking markets. Defend against subscription-scaled direct-to-consumer entrants by acquiring or building proprietary taproom density in London and Amsterdam urban clusters. Prioritize barrel-aging capacity expansion to capture scarcity-premium revenue pools that experimental independents cannot fund. For New Entrants and Emerging Players: Heat pump electrification of brewhouse thermal systems offers technology-first wedge into EU Green Deal transition financing eligibility in Denmark and Netherlands markets. Target hybrid wild fermentation segments in Scandinavian urban demographics where master brewer talent scarcity among heritage players creates formulation white space. Deploy membership-based access models with co-creation input rights to bypass wholesale margin compression in fragmented UK and Irish markets. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale regional independents possessing captive brewing infrastructure and proven taproom replication capability given subscription revenue scalability and green financing access. Long-term viability favors operators with balance sheet capacity for barrel-aging working capital intensity and cross-border regulatory navigation expertise. Watch EFSA mandatory nutritional disclosure deadlines as inflection indicator for early voluntary labeling adopters commanding French and Italian retail shelf-space premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hop Cultivation | Direct control over Hallertau acreage reduces Pacific Northwest currency exposure for German brewers. |
| Heat Pump Electrification Deployment | EU Green Deal transition financing eligibility accelerates Scope 1 emissions reduction in Danish operations. |
| Subscription Direct-to-Consumer Launch | Recurring revenue models bypass wholesale compression and build proprietary customer data in UK markets. |
| Barrel-Aging Capacity Expansion | Extended maturation cycles capture scarcity premiums that filter participation to balance-sheet-capable operators. |
| EFSA Nutritional Labeling Pre-Compliance | Voluntary disclosure ahead of deadlines commands shelf-space premiums in French hypermarket channels. |
Methodological Framework
Document review covered EU regulatory filings, ECHA substance registrations, and national brewing association production statistics, complemented by interviews with master brewers, gastropub procurement managers, specialty retail buyers, and equipment manufacturers. Secondary validation drew from BfR contaminant threshold documentation, EFSA labeling guidance, and trade flow data across member states. Bottom-up volume modeling triangulated against top-down category spend estimates from distribution channel partners.
Cross-referencing historical production trajectories against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, brewing method, distribution channel, and regional regulatory cluster. CAGRs were derived through growth driver weighting and constraint factor discounting. Industry-specific forecast inputs incorporated EU Green Deal compliance timelines and REACH chemical registration enforcement patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under hop supply disruption or accelerated EFSA mandatory disclosure deadlines. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and consumer subscription adoption curves. Hop yield volatility, master brewer labor market tightness, and packaging-waste directive implementation pace warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Ouzo Market
Alcoholic Beverages
Crystal Malt Market
Alcoholic Beverages
Tea Beer Market
Alcoholic Beverages
Distillers Malt Market
Alcoholic Beverages
Drinkware, Beverageware, and Barware Market
Alcoholic Beverages
White Wine Market
Alcoholic Beverages
Gluten-Free Beer Market
Alcoholic Beverages
Low-Alcohol Beer Market
Alcoholic Beverages
Craft Wine Market
Alcoholic Beverages
Light-Flavor Liquor Market
Alcoholic Beverages
Alcohol-Free Pineapple Beer Market
Alcoholic Beverages
Tequila Market
Alcoholic Beverages
GCC Beer Market
Alcoholic Beverages
Arak Market
Alcoholic Beverages
Hard Tea Market
Alcoholic Beverages
Global Spiced/Flavored Rum Market