
 Wine Aerator Market | 2026-2036
Wine Aerator Market Size, Share, and Industry Trends Forecast 2026-2036
Wine Aerator Market Outlook
Aftermarket service revenue and accessory replacement cycles is narrowing as manufacturers bundle aerators with preservation systems and pourer sets. Coravin anchors its position through integrated wine access and aeration ecosystems. Vinturi competes on handheld simplicity and point-of-sale visibility across specialty retailers. Aervana differentiates through battery-powered dispensing technology that commands shelf space in premium kitchen channels.
A wine aerator is a device that accelerates the interaction between wine and atmospheric oxygen through engineered air channels, typically achieving the equivalent of 30-60 minutes of traditional decanting in seconds of pour time. The device serves commercial and residential users seeking to soften tannins, release aromatic compounds, and improve perceived wine quality without extended wait periods. Electric aerators occupy the fastest-expanding margin pool as rechargeable designs attract tech-forward household buyers seeking countertop convenience. Manual pourer aerators sustain volume leadership through low price points and universal bottle fit that drives impulse purchases. Stainless steel construction commands preference in the premium tier due to durability perceptions and dishwasher-safe maintenance.
FDA food-contact substance regulations govern plastic and silicone components in aerators sold to US consumers, while EU REACH restrictions on phthalates and heavy metals shape material selection for European imports. BIS certification requirements affect stainless steel grades in products entering India, where import scrutiny on kitchenware intensifies. Stakeholders must monitor evolving chemical disclosure mandates across multiple jurisdictions and calibrate material sourcing strategies before compliance deadlines tighten.
Market Dynamics
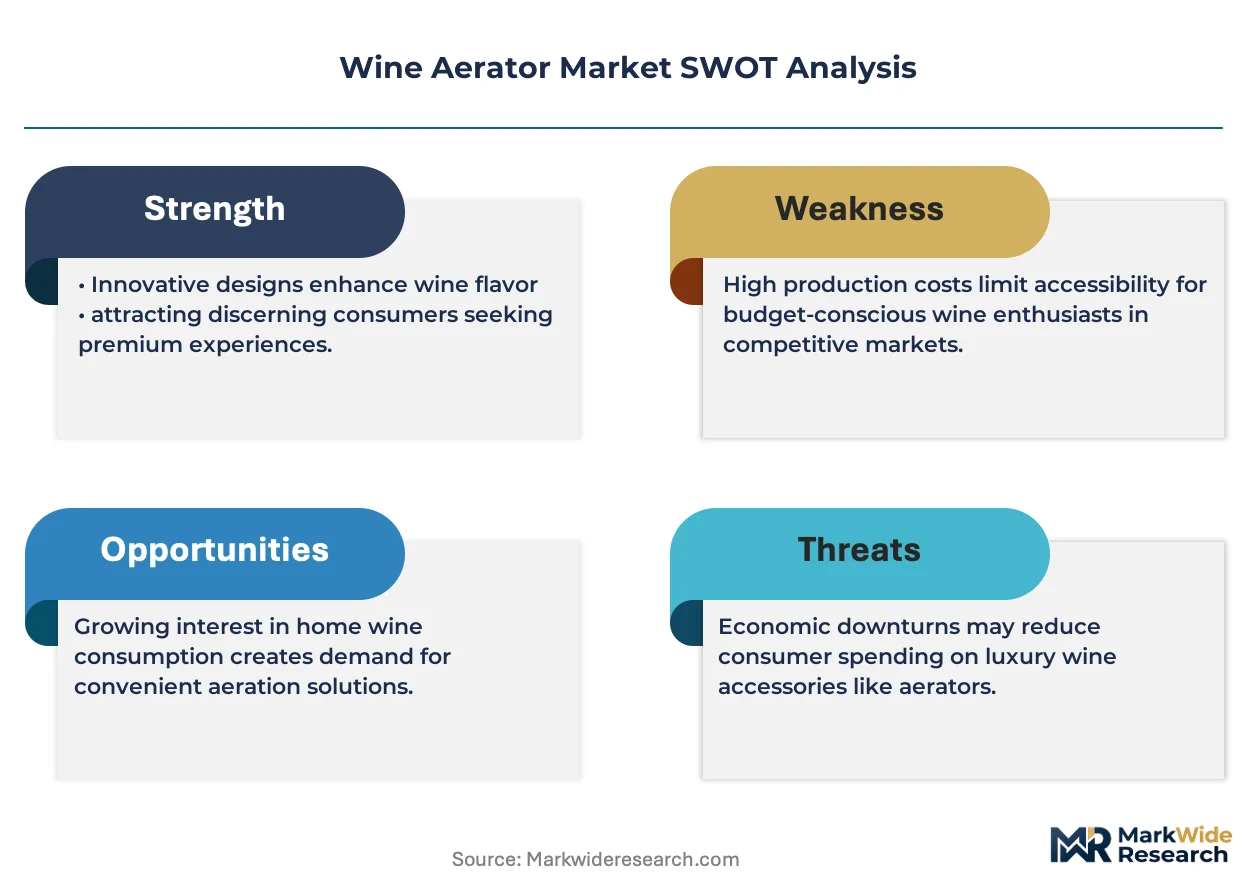
Electric aeration technology is compressing replacement cycles and bundling aerators with preservation ecosystems, forcing manual incumbents to defend shelf space through price repositioning and material upgrades.
Growth Catalysts
- EU REACH compliance on silicone components:Manufacturers reformulating food-contact materials gain preferential access to German and French specialty retailers, accelerating premium tier turnover.
- Rechargeable lithium-ion designs:Battery-powered dispensing systems attract tech-forward household buyers seeking countertop convenience without manual pour mechanics.
- Japan's established wine culture:Replacement demand from aging decanter owners drives adoption of speed-aeration devices in Tokyo and Osaka metropolitan markets.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316 price swings compress margin pools for premium construction tiers, forcing material substitution to lower-grade alloys.
- FDA food-contact substance scrutiny:Extended notification timelines for new polymer formulations delay product launches by 12-18 months for US-bound inventories.
- Traditional decanting ritual:Sommelier-trained consumers in established wine markets resist mechanized aeration, limiting penetration in fine-dining channels.
Strategic Opportunities
- India's import certification gap:BIS kitchenware scrutiny creates first-mover advantage for compliant stainless steel suppliers in Mumbai and Delhi distribution corridors.
- Smart home integration:Bluetooth-enabled pour tracking and app-connected dispensing converge with connected kitchen ecosystems in US and German households.
- Direct-to-consumer wine club bundling:Subscription channels bypass specialty retail markup, attaching aerators to recurring shipment models in California and Texas markets.
Industry Challenges
- Cross-jurisdiction chemical disclosure:Divergent FDA, ECHA, and BIS material standards force parallel testing protocols, inflating compliance overhead for multi-market portfolios.
- Legacy decanter inventory:Long-lived glassware replacement cycles stretch payback periods for aerator marketing spend in mature wine-consuming households.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wine Aerator Market |
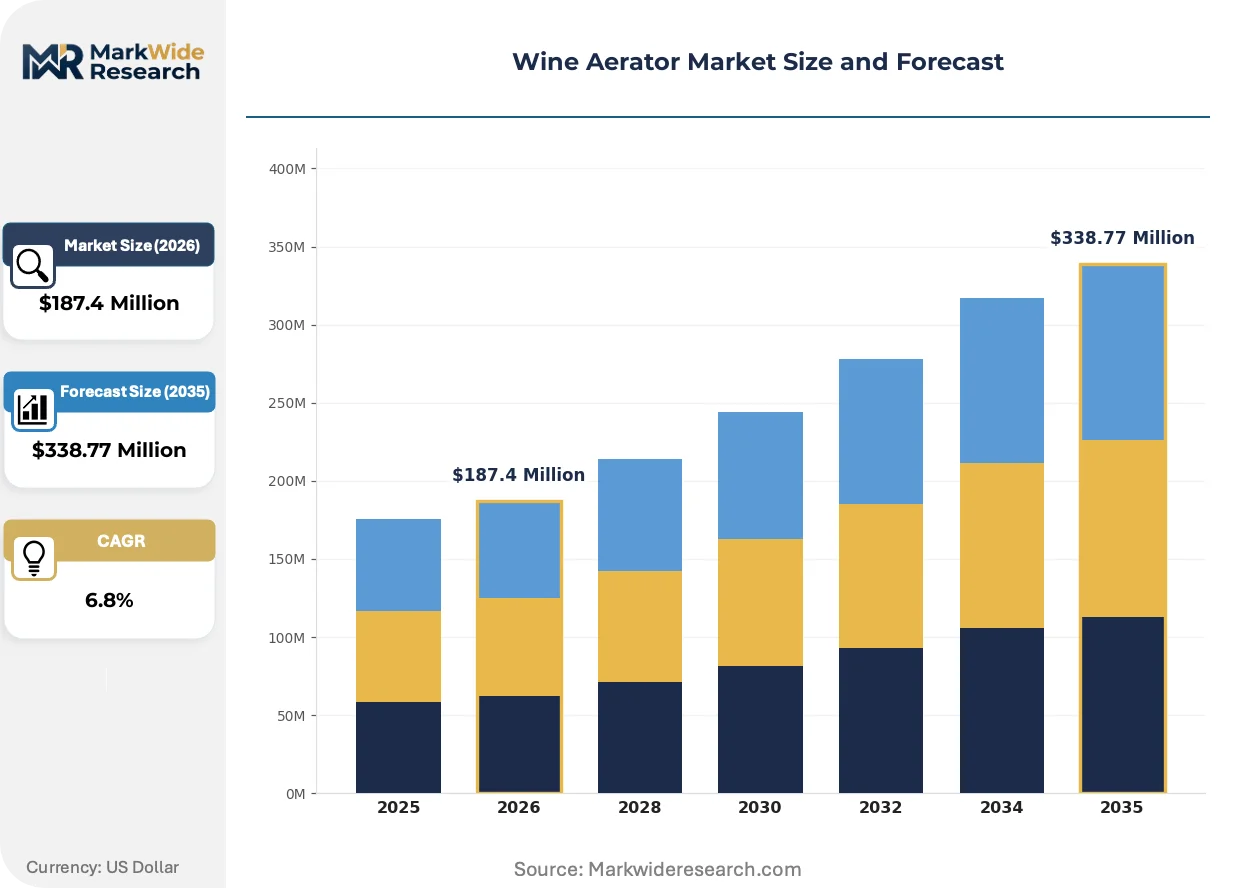
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Aerators, Electric Aerators, Pourer Aerators, Travel Aerators End User: Households, Restaurants, Wineries, Retailers Material: Plastic, Glass, Stainless Steel, Silicone Price Range: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Vinturi, Aervana, Coravin, Rabbit, Soireehome, Trudeau Corporation, Vintorio, Vacu Vin, Zazzol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wine Aerator Market Strategic Shifts
Product architecture is splitting between disposable impulse formats and durable connected systems, with material science and power electronics driving divergent innovation paths.
Rechargeable dispensing mechanisms are migrating from novelty positioning to core household expectations. Tech-forward buyers in US and German markets now treat battery-powered aeration as standard countertop equipment. This migration from manual to electric formats compresses price-to-performance ratios and forces incumbent pourer manufacturers into material differentiation or channel retreat.
EU REACH restrictions on phthalates and heavy metals are reshaping silicone sourcing strategies for European imports. Manufacturers must now document full supply chain chemical composition before customs clearance. German specialty retailers and French kitchenware distributors are most affected, responding by consolidating supplier bases around pre-certified polymer compounders.
Gifting occasion concentration is shifting procurement toward bundled presentation sets. Specialty retail channels in Japan and the United States are losing share to direct wine club and e-commerce platforms that attach aerators to subscription shipments. California and Texas demonstrate the fastest channel rotation, where vineyard-direct sales teams now specify aerator inclusion in tasting room fulfillment.
Wine Aerator Market Segmentation
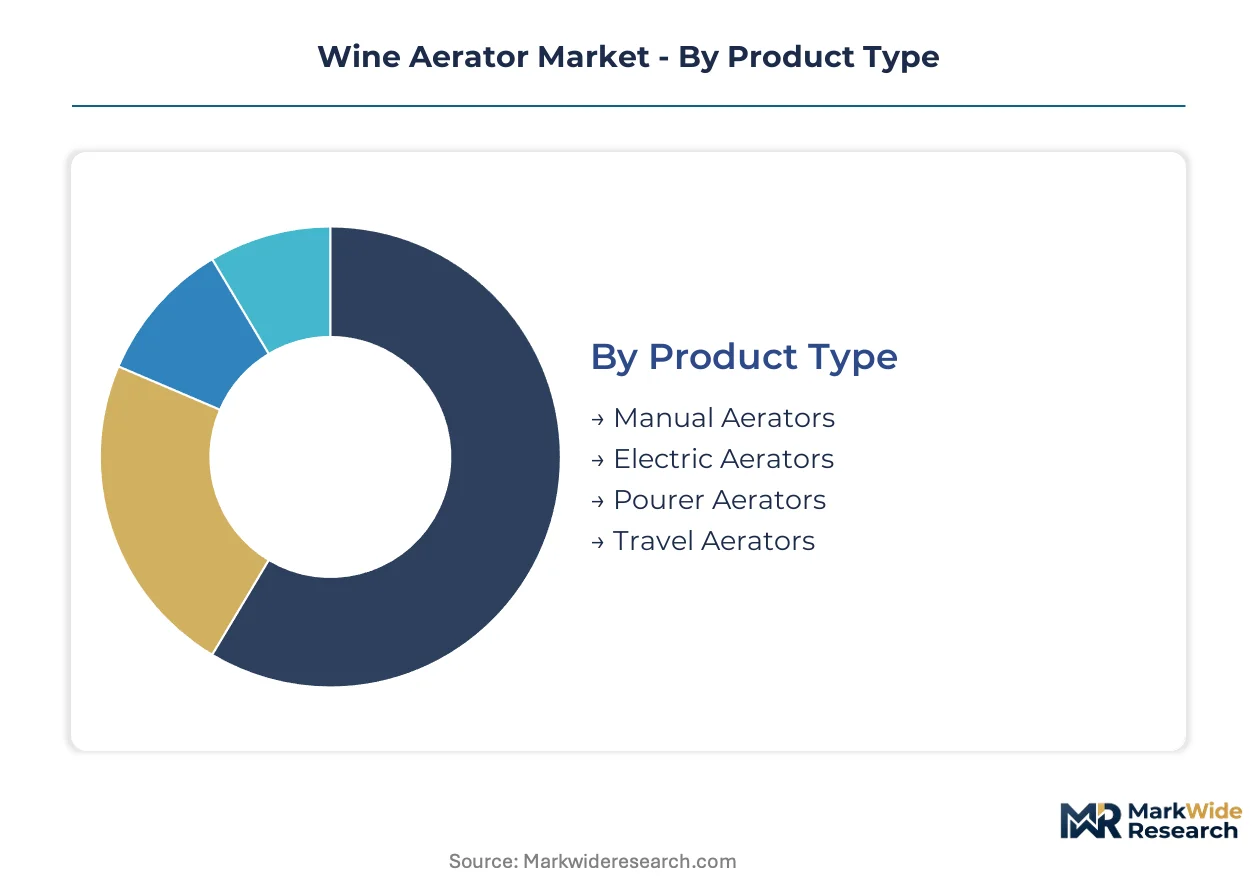
Wine aerator segmentation reveals divergent engineering priorities across use cases, from countertop electric systems to pocket-sized travel formats. Material selection and power source drive margin stratification, while end-user context determines channel access and replacement velocity.
Product Type:
Manual pour-through designs dominate impulse retail, while powered dispensing systems capture premium kitchen renovation spending.
- Manual Aerators:Chambered acrylic or stainless steel bodies force wine through narrow air-mixing channels using gravity alone. Mass-market penetration concentrates in US specialty grocers and German department stores where sub-$20 price points drive basket attachment.
- Electric Aerators:Rechargeable lithium-ion pumps draw wine through pressurized oxygen injection nozzles. Tech-forward households in California and Texas metropolitan markets treat countertop electric units as standard entertaining equipment, compressing replacement cycles versus manual alternatives.
- Pourer Aerators:Spout-mounted designs integrate air intake vents into bottle-neck inserts. Restaurant procurement in Japan favors dishwasher-safe pourers for by-the-glass service speed.
- Travel Aerators:Collapsible silicone and plastic formats prioritize packability over aeration efficiency. Airline retail and duty-free channels in Frankfurt and Dubai move travel formats as wine tourism accessories.
The dominant share belongs to Manual Aerators, while Electric Aerators is closing the gap fastest.
End User:
Procurement authority splits between individual gifting decisions and institutional beverage program specifications.
- Households:Direct-to-consumer wine club bundling in California and subscription kitchenware platforms in Germany accelerate household acquisition. Countertop electric systems now anchor premium home entertaining setups.
- Restaurants:By-the-glass program economics in Tokyo and Osaka drive pourer aerator standardization. Sommelier resistance to mechanized formats limits penetration in Michelin-tier dining rooms.
- Wineries:Tasting room fulfillment in Napa and Sonoma counties specifies aerator inclusion for bottle purchases. Vineyard-direct channels bypass specialty retail markup.
- Retailers:Point-of-sale placement in US specialty grocers and French kitchenware distributors sustains impulse velocity for manual formats.
Households command the volume base, though Restaurants generate the steadiest replacement demand.
Material:
Regulatory compliance costs and durability perceptions stratify material selection across price tiers.
- Plastic:FDA food-contact substance notification requirements delay US-bound polymer launches. BPA-free formulations gain preferential placement in mass-market channels.
- Glass:Hand-blown decanter-style chambers target gifting occasions in Japan. Fragility limits commercial adoption despite aesthetic premium.
- Stainless Steel:Grade 304 and 316 constructions satisfy BIS kitchenware certification for Indian import clearance. German and US buyers prioritize dishwasher-safe maintenance.
- Silicone:EU REACH phthalate restrictions force supply chain documentation for European imports. Travel format manufacturers consolidate around pre-certified compounders.
Stainless Steel anchors premium positioning, while Silicone faces the steepest compliance cost inflation.
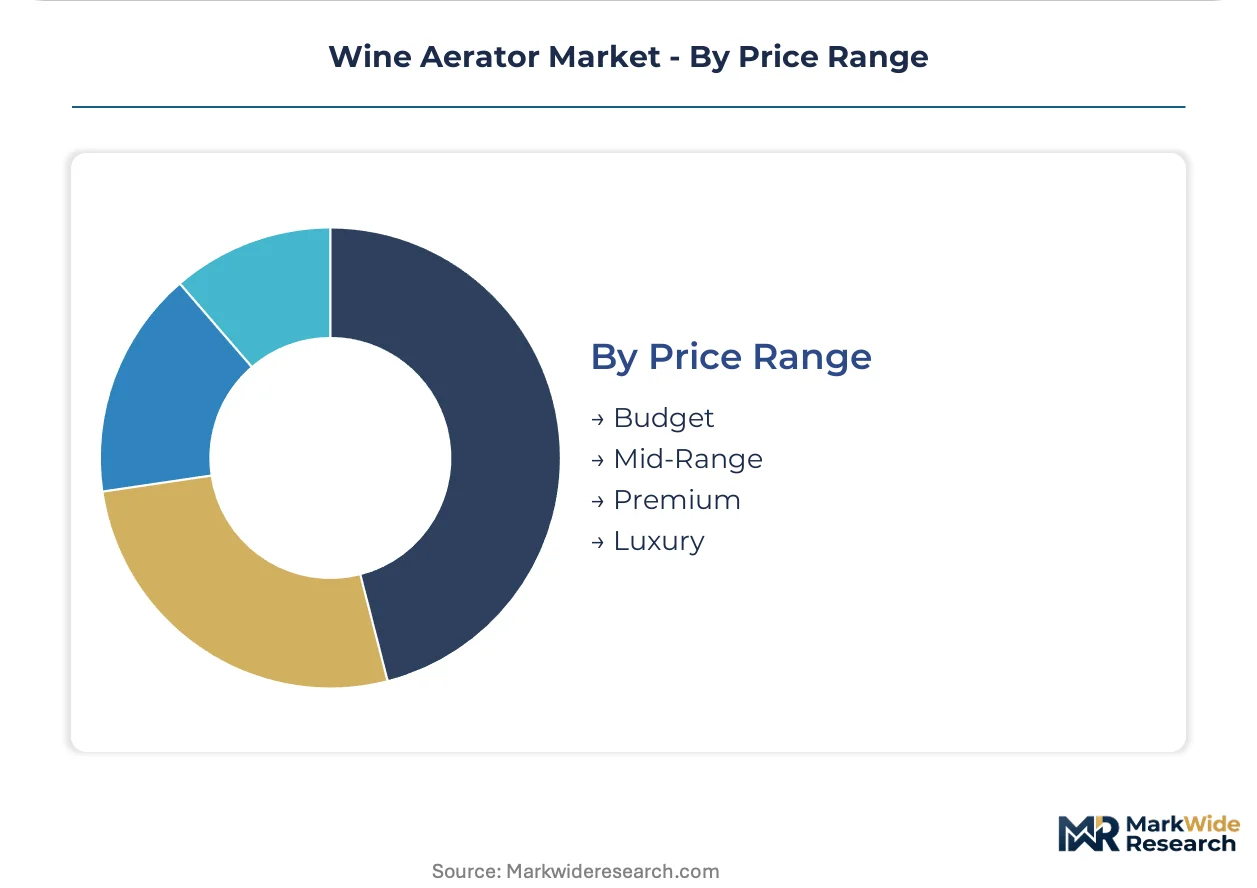
Price Range:
Three-tier pricing structure separates impulse accessibility from connected-system premiums.
- Budget:Sub-$15 plastic pourers dominate US big-box and supermarket wine accessory aisles. Margin compression forces material substitution to lower-grade polymers.
- Mid-Range:$25-$60 stainless steel manual units balance durability perception with gift-appropriate packaging. German specialty retailers concentrate mid-range assortment depth.
- Premium:$75-$150 electric countertop systems with rechargeable batteries. Tech-forward buyers in US and German markets treat premium electric as standard equipment.
- Luxury:$200+ connected systems with app integration and pour tracking. Limited distribution through sommelier supply houses and high-end kitchen boutiques.
Budget captures unit volume leadership, though Premium is expanding most quickly as electric formats normalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Households in Germany and Japan show low price elasticity for premium electric formats, while budget plastic pourers dominate impulse purchases in United States mass-market channels.
United States
Direct-to-consumer wine club bundling in California and Texas accelerates countertop electric adoption. FDA food-contact substance notifications delay polymer formulation launches by 12-18 months. Napa and Sonoma tasting rooms specify aerator inclusion for vineyard-direct bottle sales.
Germany
Specialty retailers in Munich and Hamburg consolidate supplier bases around pre-certified silicone compounders to satisfy EU REACH documentation requirements. German households treat rechargeable countertop systems as standard entertaining equipment. North Rhine-Westphalia kitchenware distributors favor dishwasher-safe stainless steel constructions.
Japan
Aging decanter owners in Tokyo and Osaka metropolitan markets drive replacement demand for speed-aeration devices. METI product safety standards govern electrical appliance imports. Kansai region restaurants standardize pourer aerators for by-the-glass service speed.
India
BIS kitchenware certification creates first-mover advantage for Grade 304 stainless steel suppliers in Mumbai and Delhi distribution corridors. Import scrutiny intensifies on food-contact polymers. Maharashtra-based hospitality procurement favors manual pourers for cost-sensitive banquet operations.
France
French kitchenware distributors respond to EU REACH phthalate restrictions by consolidating around documented silicone supply chains. Sommelier-trained consumers in Paris and Lyon resist mechanized formats, limiting fine-dining penetration. Île-de-France specialty retailers emphasize gift-appropriate presentation sets.
Wine Aerator Market Competitive Environment
Integrated-system specialists and handheld-pourer manufacturers split the market between preservation ecosystems and impulse-accessible formats. The vendor base concentrates around three strategic archetypes: wine-access technology integrators, battery-powered dispensing innovators, and manual-pourer volume leaders. Competitive moves center on bundling aerators with preservation systems and securing point-of-sale visibility across specialty retail channels.
Within the wine-access technology tier, Coravin anchors integrated ecosystem positioning, while Aervana exemplifies battery-powered dispensing innovation. Vinturi occupies the handheld-simplicity archetype. These three companies represent divergent engineering priorities: pressurized wine access systems, rechargeable countertop convenience, and gravity-fed pour-through mechanics.
| Leading Market Players |
|---|
| Vinturi |
| Aervana |
| Coravin |
| Rabbit |
| Soireehome |
| Trudeau Corporation |
| Vintorio |
| Vacu Vin |
| Zazzol |
| Others |
Value Chain & Pricing Dynamics
Shanghai-to-Long Beach freight corridors transmit container cost volatility directly into landed cost structures for electric aerator assemblies, compressing margin pools for mid-tier manufacturers while amplifying price differentiation between battery-powered premium units and manual pour-through alternatives. This logistics chokepoint concentrates supply-side leverage with contract manufacturers holding multi-country certification portfolios.
Pricing Analysis
Aftermarket accessory replacement and bundled preservation system attach rates now drive lifetime value capture more than hardware margins alone. Three-tier pricing structure across premium, standard, and economy levels stratifies the market: sub-$15 plastic pourers anchor impulse channels, $25-$60 stainless steel manual units balance durability perception with gift positioning, and $75-$150 electric countertop systems command tech-forward household spending. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in the budget tier intensifies as Grade 304 stainless steel input volatility forces material substitution to lower-grade alloys. Household buyers in Germany and Japan show lowest price sensitivity for premium electric formats, while US mass-market channels exhibit acute elasticity.
Supply Chain Analysis
Export-control documentation requirements for lithium-ion battery cells constrain cross-border flows of rechargeable aerator assemblies into EU and US customs territories. Manufacturing concentration centers on China for injection-molded polymer housings, Taiwan for precision pump motor assemblies, and Germany for stainless steel fabrication. Raw material dependencies include food-grade silicone compounds, Grade 304/316 stainless steel billets, and lithium-ion battery cells. Single-source vulnerability in certified polymer compounders serving EU REACH compliance creates procurement risk. Distribution runs through specialty kitchenware retailers in Germany and Japan, direct-to-consumer wine club channels in California, and hospitality procurement networks in Tokyo.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wine aerator market economics increasingly resemble service-attach models where preservation ecosystem bundling and replacement accessory subscriptions expand recurring revenue faster than standalone hardware turnover.
For Market Incumbents: Pre-empt channel erosion by securing exclusive pourer aerator placement in Japanese restaurant procurement networks before battery-powered entrants capture by-the-glass service specifications. Consolidate supplier relationships around pre-certified silicone compounders to satisfy EU REACH documentation requirements without parallel testing overhead. Vertical integration into stainless steel fabrication buffers Grade 304 price volatility.
For New Entrants and Emerging Players: Build out direct-to-consumer wine club partnerships in Texas and California metropolitan markets where subscription bundling bypasses specialty retail markup. Target India's BIS-compliant stainless steel tier where import certification gaps create first-mover advantage in Mumbai and Delhi distribution corridors. Pursue smart home integration as the primary go-to-market angle.
For Investors and Strategic Acquirers: Connected-system specialists with Bluetooth-enabled pour tracking and app ecosystems represent the most defensible acquisition profile. Long-term viability hinges on recurring revenue attachment rates exceeding hardware replacement cycles. Watch for inflection when FDA food-contact substance notification timelines compress, signaling regulatory pathway maturation for new polymer entrants.
| Strategic Initiative | Industry Significance |
|---|---|
| Preservation Ecosystem Bundling | Coravin's integrated wine access systems demonstrate attach-rate economics that manual pourer manufacturers cannot replicate. |
| EU REACH Pre-Certification Investment | German specialty retailers now require full supply chain chemical documentation before customs clearance. |
| Direct-to-Consumer Wine Club Partnership | California vineyard-direct channels bypass traditional kitchenware distributor markups entirely. |
| Smart Home Platform Integration | Bluetooth-enabled pour tracking converges with connected kitchen ecosystems in US and German households. |
| BIS Certification-First Market Entry | Grade 304 stainless steel suppliers gain preferential access to Mumbai and Delhi hospitality procurement. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with product development leads at electric aerator manufacturers, procurement managers at German and Japanese specialty retailers, and regulatory affairs specialists navigating FDA and ECHA compliance pathways; and secondary validation against customs import records, EU REACH substance databases, and BIS kitchenware certification registries. Bottom-up unit economics modeling triangulated against top-down category spending estimates derived from wine club shipment data and hospitality equipment procurement disclosures.
Forecast inputs considered product type segmentation across manual, electric, pourer, and travel formats; material tier stratification by regulatory compliance burden; end-user channel dynamics spanning households, restaurants, wineries, and retailers; and regional adoption patterns across the analysis window. CAGRs were derived from installed base replacement velocity and premium tier penetration curves. Industry-specific inputs included lithium-ion battery cost decline trajectories and EU REACH substance restriction implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive ecosystem bundling moves by wine-access technology integrators would shift outcomes materially. Forecasts assume stable FDA notification timelines and unchanged EU REACH substance restriction scopes. Material shifts in BIS kitchenware enforcement intensity or lithium-ion battery export control classifications would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Honey Wine Market
Alcoholic Beverages
South America Wine Market
Alcoholic Beverages
Pineapple Beer Market
Alcoholic Beverages
Stemware Market
Alcoholic Beverages
Ready to Drink Cocktails Market
Alcoholic Beverages
Instant Wine Chillers and Refreshers Market
Alcoholic Beverages
UAE Alcohol E-Commerce Market
Alcoholic Beverages
Italy Alcohol E-Commerce Market
Alcoholic Beverages
Organic Beer Market
Alcoholic Beverages
Japan Tequila Market
Alcoholic Beverages
Rum Market
Alcoholic Beverages
Global Spiced/Flavored Rum Market
Alcoholic Beverages
France Tequila Market
Alcoholic Beverages
Spain Alcohol E-Commerce Market
Alcoholic Beverages
Chocolate Liqueur Market
Alcoholic Beverages
Asia-Pacific Alcoholic Beverage Market