
 Alcohol Gummies Market | 2026-2036
Alcohol Gummies Market Size, Share, and Industry Trends Forecast 2026-2036
Alcohol Gummies Market Outlook
Capital-intensity divergence between boutique confectioners and scaled spirits conglomerates is reorganizing competitive boundaries in alcohol-infused edibles. Sugarfina leverages its premium retail footprint and licensed brand collaborations to sustain pricing power in specialty channels. Smith & Sinclair anchors its position through patented alcohol-delivery formulations that differentiate texture stability across temperature ranges. Boozy Bears competes on seasonal limited-release velocity, controlling direct-to-consumer engagement cycles that larger players struggle to replicate.
Alcohol gummies are gelatin or pectin-based confectionery matrices incorporating distilled spirits, wine, or beer at concentrations typically ranging from five to fifteen percent alcohol by volume, formulated for controlled-release consumption in social and gifting contexts. The manufacturing process demands precise ethanol binding to prevent syneresis while maintaining shelf stability over twelve to twenty-four months. CBD Infused and Functional Gummies segments command expanding margin pools as wellness-positioned consumers cross-shop between recreational and adaptogenic formats. Fruit Flavors dominate current volume, though Sour and Herbal profiles are capturing fastest-growing demand among experimental adult palates seeking complexity beyond traditional candy profiles.
The FDA governs alcohol gummies as overlapping food and alcohol products, requiring dual compliance with TTB labeling standards for alcohol content disclosure and FDA food safety mandates for ingredient transparency. State-level three-tier distribution laws in the United States create fragmented market access, with some jurisdictions classifying these products as spirits subject to wholesale monopoly controls. Stakeholders must monitor evolving state legislative frameworks and TTB guidance on serving-size standardization as classification ambiguity threatens channel expansion timelines.
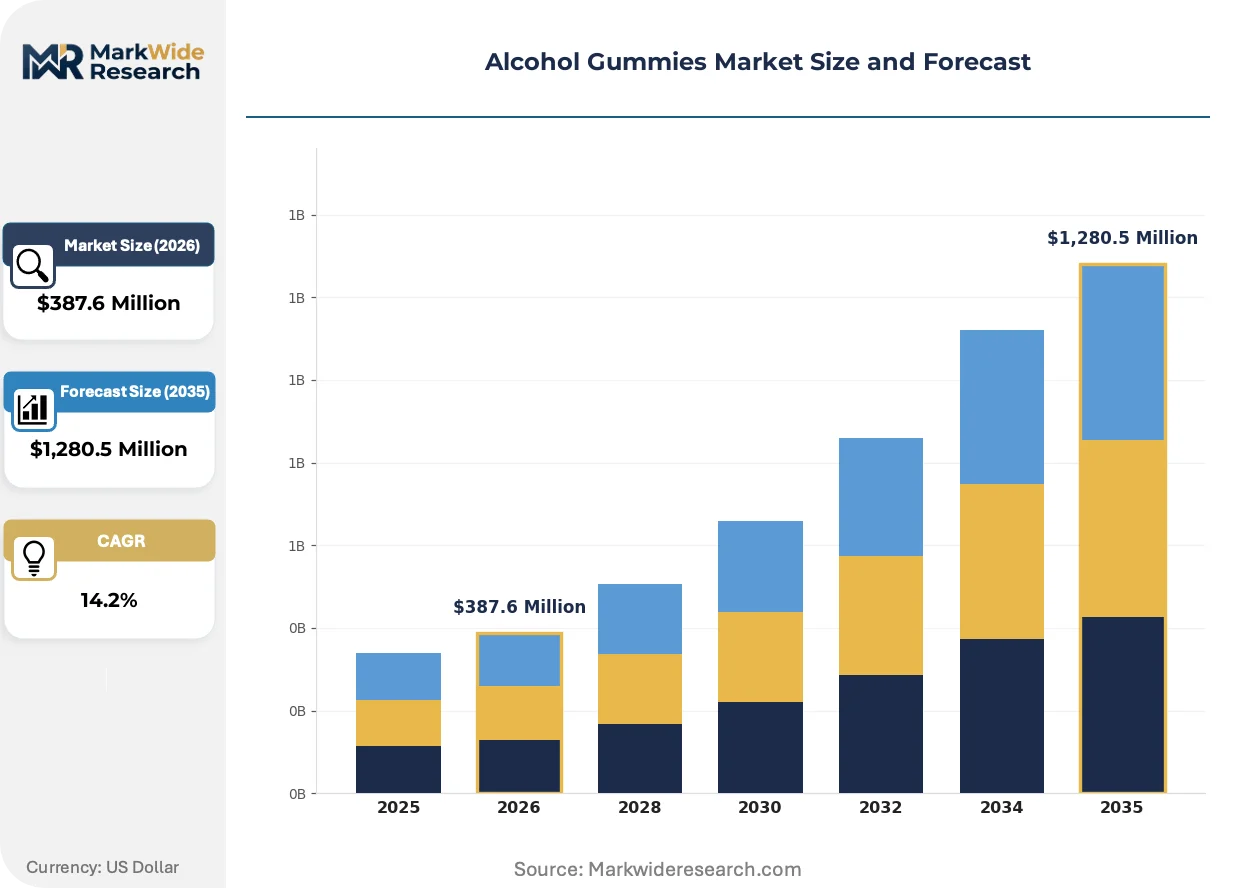
Market Dynamics
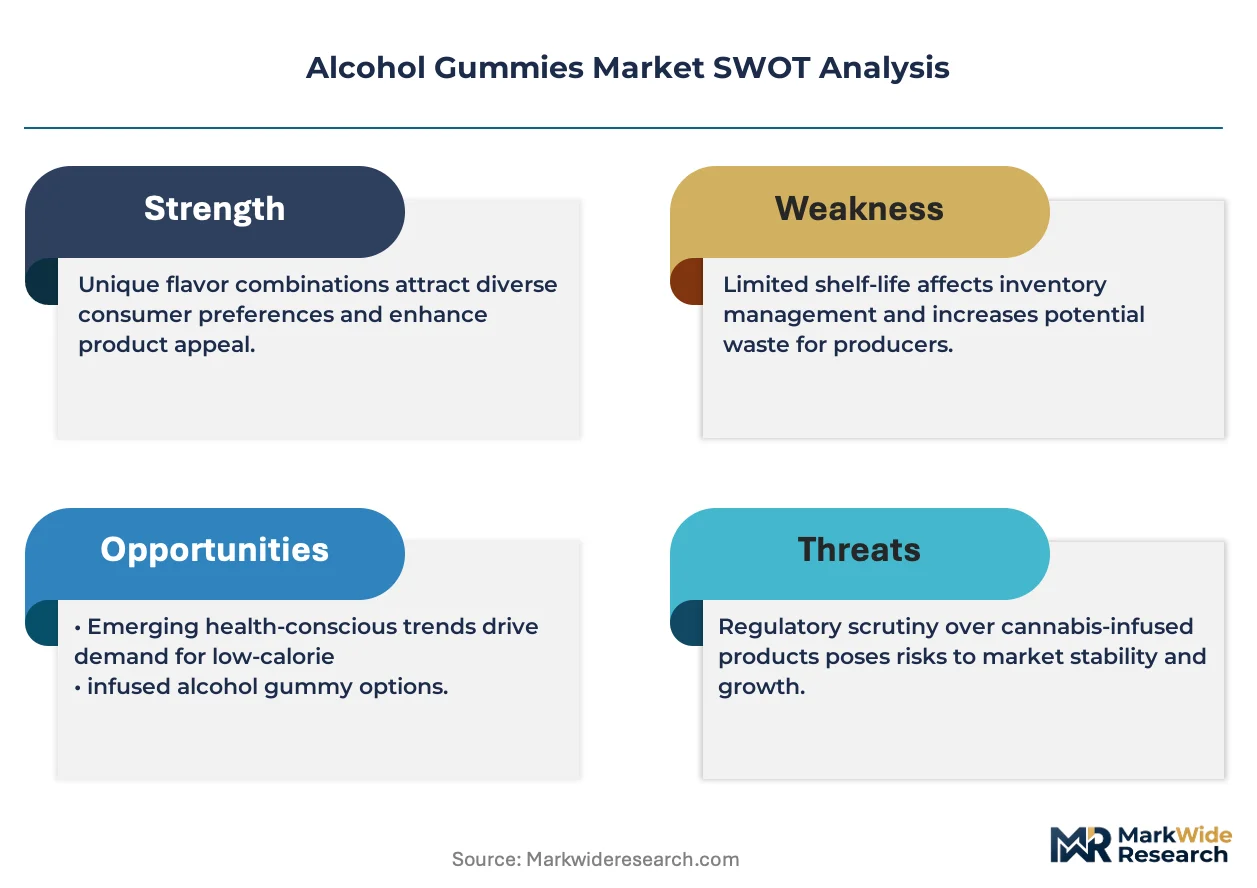
Dual FDA-TTB jurisdiction is forcing alcohol gummy manufacturers to maintain parallel compliance systems for food safety and alcohol labeling, elevating fixed costs and favoring scaled producers with dedicated regulatory infrastructure over boutique entrants.
Growth Catalysts
- Social consumption normalization:Adult gifting occasions and party-centric use cases are expanding addressable demand beyond traditional spirits channels into specialty retail and direct-to-consumer platforms.
- REACH compliance harmonization:European ingredient disclosure standards are creating transferable formulation protocols that reduce re-certification burdens for cross-border market entry.
- Pectin stabilization technology:Plant-based gelling agents are enabling vegan-positioned product lines that capture dietary-restricted consumer segments previously excluded from gelatin-based offerings.
Market Restraints
- Ethanol input volatility:Distilled spirits supply concentration among contracted bulk suppliers exposes margin compression when grain alcohol prices fluctuate.
- Three-tier distribution lock-in:State-level wholesale monopoly controls in multiple US jurisdictions force channel dependence on licensed spirits distributors with limited confectionery expertise.
- Shelf-life technical ceiling:Current ethanol-binding formulations face 24-month stability limits that constrain inventory management flexibility for seasonal product cycles.
Strategic Opportunities
- Functional ingredient convergence:Adaptogen and nootropic co-formulations are opening wellness-positioned segments that command premium pricing beyond recreational use cases.
- Direct-to-consumer regulatory arbitrage:E-commerce shipping frameworks in certain state jurisdictions bypass three-tier wholesale requirements, enabling margin capture currently absorbed by distributor markups.
- CSRD sustainability disclosure:European corporate reporting mandates are creating first-mover advantage for carbon-labeled supply chains that preempt procurement requirements from multinational retail buyers.
Industry Challenges
- Cross-functional talent scarcity:Formulation chemistry expertise spanning both food science and alcohol stability remains concentrated among a limited pool of specialists with spirits industry backgrounds.
- Dual certification timeline compression:Simultaneous FDA food facility registration and TTB formula approval processes extend product launch cycles beyond confectionery norms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alcohol Gummies Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CBD Infused, THC Infused, Non-Alcoholic, Functional Gummies Flavor Profile: Fruit Flavors, Sour, Herbal, Spicy Distribution Channel: Online Retail, Convenience Stores, Specialty Shops, Supermarkets Consumer Segment: Young Adults, Health-Conscious Consumers, Party Goers, Tourists |
| Companies Covered | Sugarfina, Smith & Sinclair, Inebriated Baker, Kate & Belle, Lolli & Pops, Maggie Lyon Chocolatiers, Project 7, Boozy Bears, Tipsy Elves, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alcohol Gummies Market Strategic Shifts
Active reformulation around clean-label positioning and bioactive ingredients is compressing traditional confectionery R&D cycles, with alcohol gummy developers now integrating pharmaceutical-grade encapsulation methods previously reserved for supplement applications.
Microencapsulation via spray-dried ethanol complexes is displacing conventional surface-coating methods for alcohol integration, enabling higher ABV thresholds without compromising texture integrity. Premium spirits brands are adopting this technology fastest, using it to launch cocktail-replica gummies that justify 40-60% price premiums over wine-based alternatives. The structural consequence is a bifurcation between technology-enabled premium tiers and commodity-positioned wine-gummy segments.
TTB serving-size standardization guidance is tightening alcohol content disclosure requirements, forcing reformulation of products previously marketed with ambiguous per-piece dosing. Manufacturers are responding by adopting pharmaceutical-style blister packaging with individual unit labeling. The craft confectionery segment faces disproportionate compliance burden relative to scaled spirits conglomerates with existing regulatory infrastructure.
Subscription-based replenishment models are capturing repeat purchase behavior previously dependent on impulse retail exposure. Direct-to-consumer platforms are displacing specialty food boutiques as the primary discovery channel for experimental flavor profiles. This shift concentrates most visibly in urban coastal markets where delivery logistics infrastructure supports cold-chain requirements for temperature-sensitive formulations.
Alcohol Gummies Market Segmentation
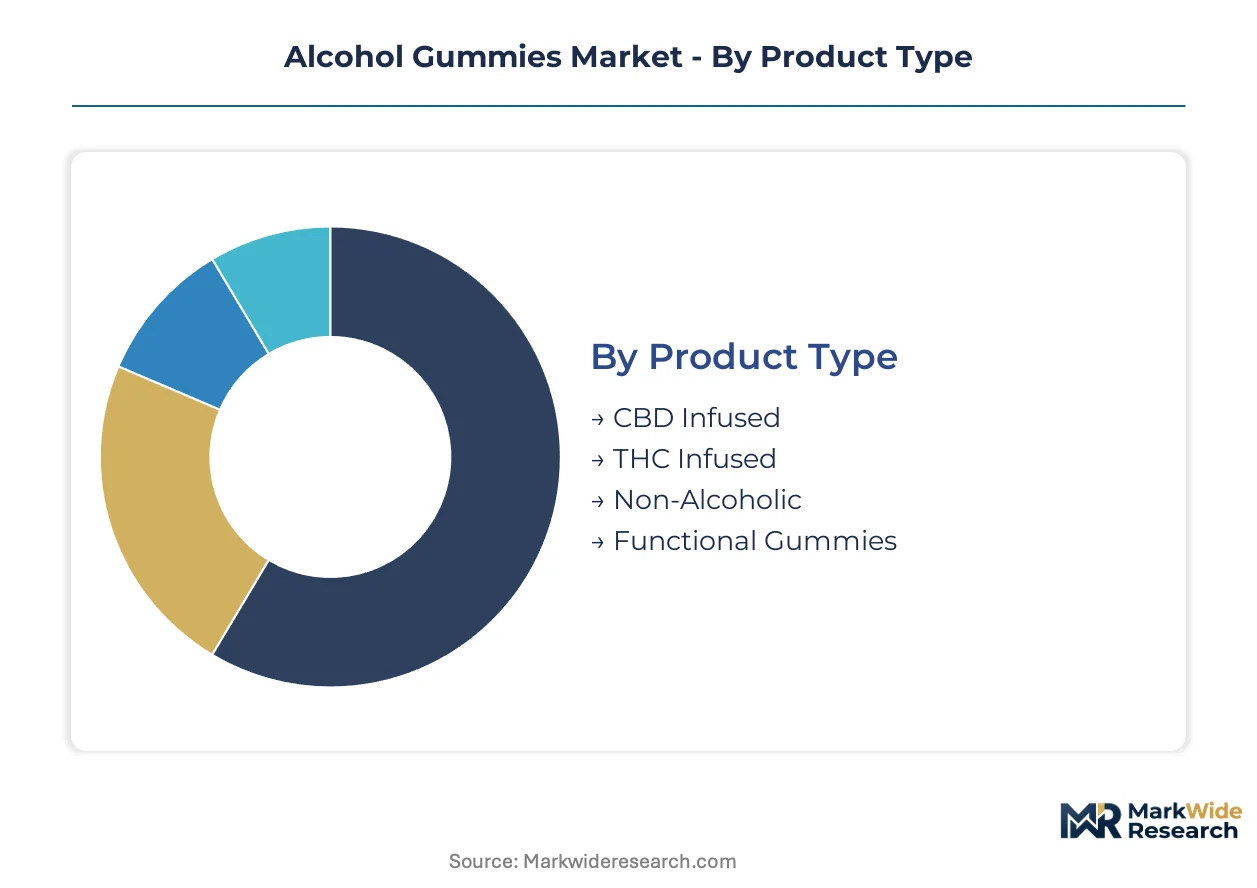
Segmentation in alcohol gummies determines regulatory pathway complexity and shelf placement strategy. Product type dictates whether FDA, TTB, or state cannabis agency oversight applies, while flavor profile and channel selection shape margin architecture and consumer acquisition costs.
Product Type:
CBD Infused and Functional Gummies concentrate in domestic US direct-to-consumer channels, while THC Infused formats face export restrictions that limit cross-border shipment viability.
- CBD Infused:Cannabidiol co-formulations bind ethanol within lipid-based carriers, enabling wellness-positioned marketing that commands 25-40% price premiums over recreational alternatives. Demand clusters in California, Colorado, and Oregon where state hemp regulations permit interstate commerce.
- Functional Gummies:Adaptogen and nootropic additives target stress-relief and cognitive enhancement use cases, attracting health-conscious millennials through subscription replenishment models. Procurement concentrates among biotech ingredient suppliers with GRAS certification for alcohol-matrix stability.
- THC Infused:Delta-9 tetrahydrocannabinol formulations require state-licensed dispensary distribution, constraining addressable market to jurisdictions with adult-use cannabis frameworks.
- Non-Alcoholic:Zero-ABV cocktail-flavored gummies bypass TTB jurisdiction entirely, enabling grocery and mass retail placement previously inaccessible to ethanol-containing products.
Non-Alcoholic holds the largest share; momentum sits with Functional Gummies.
Flavor Profile:
Cost tier stratification runs from commodity fruit bases through premium botanical extractions, with sour and spicy variants capturing the steepest expansion trajectory among experimental adult palates.
- Fruit Flavors:Strawberry, raspberry, and citrus formulations dominate volume through familiar taste profiles that reduce trial barriers for first-time purchasers. Manufacturing scales efficiently using concentrated juice powders with 18-24 month shelf stability.
- Herbal:Lavender, rosemary, and elderflower infusions target cocktail-replica positioning, requiring cold-press extraction methods that elevate COGS by 30-50% versus synthetic flavoring. Adoption concentrates in urban coastal markets with established craft cocktail culture.
- Sour:Citric acid coating layers create tactile contrast that differentiates shelf presence in specialty retail environments.
- Spicy:Capsaicin and ginger heat profiles appeal to heat-seeking demographics crossing over from craft hot sauce and spicy snack categories.
Fruit Flavors anchor volume; Herbal gains share fastest among premium-positioned entrants.
Distribution Channel:
Customer type and purchase occasion split sharply between impulse-driven convenience formats and planned subscription replenishment through digital platforms.
- Online Retail:Direct-to-consumer platforms bypass three-tier wholesale markups, capturing 15-25 percentage points of additional margin while enabling flavor customization and limited-release velocity. Cold-chain logistics requirements constrain participation to carriers with temperature-controlled last-mile capabilities.
- Specialty Shops:Curated confectionery boutiques and spirits-focused retailers provide discovery context that justifies premium pricing through staff education and sampling programs. Foot traffic concentrates in metropolitan areas with disposable income thresholds above national medians.
- Convenience Stores:Grab-and-go placement targets unplanned social occasions with single-serve packaging formats.
- Supermarkets:Mass retail access requires Non-Alcoholic classification or state-specific spirits licensing agreements that fragment rollout timelines.
Specialty Shops retain the highest per-unit economics; Online Retail scales most rapidly.
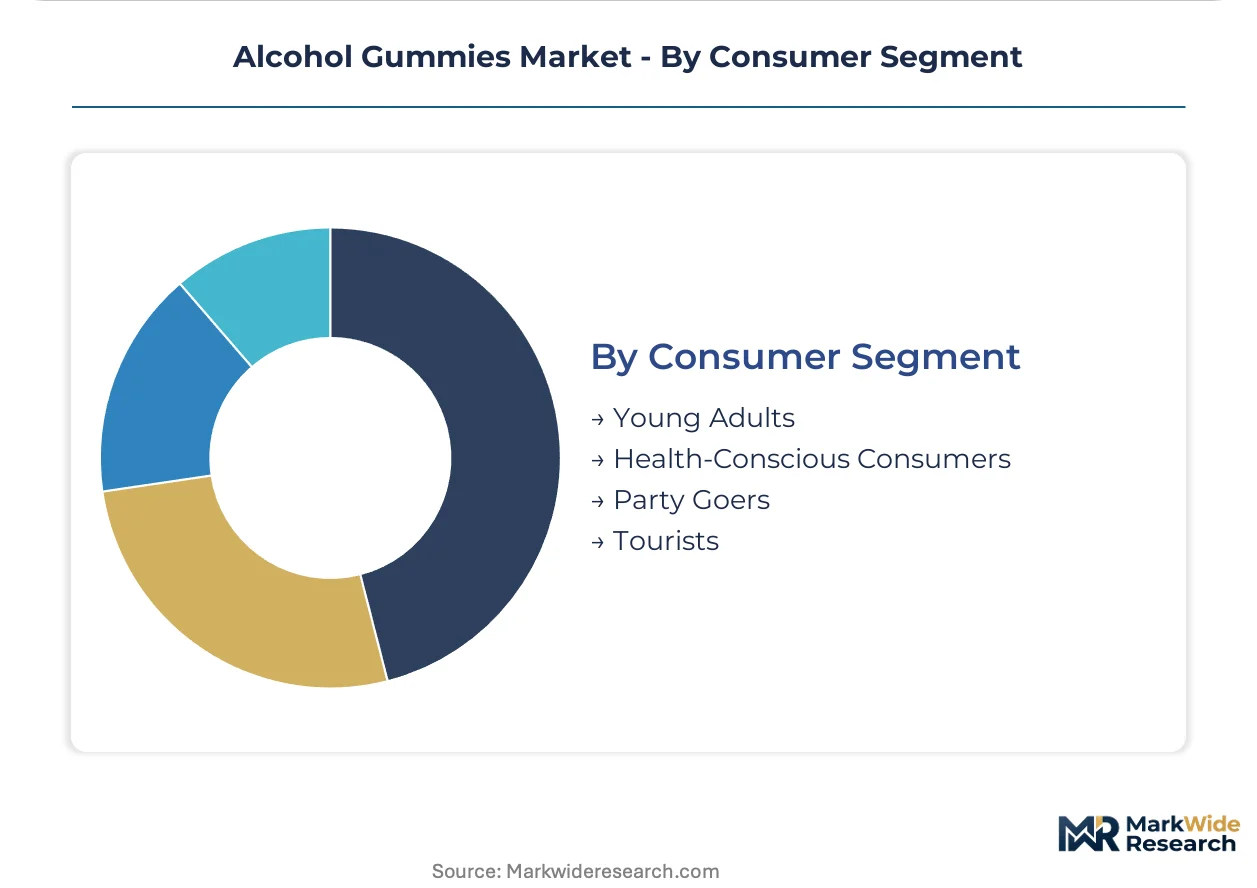
Consumer Segment:
Maturity and occasion-based usage patterns separate recreational social consumption from wellness-motivated integration into daily routines.
- Young Adults:Millennial and Gen Z demographics aged 25-34 drive trial velocity through social media discovery and gifting exchange occasions. Frequency concentrates around holidays, bachelorette events, and music festival seasons.
- Health-Conscious Consumers:Functional ingredient seekers prioritize clean-label positioning and sugar-reduced formulations, accepting 50-70% price premiums for organic certification and adaptogenic claims.
- Party Goers:Occasion-based purchasers respond to novelty packaging and limited-edition collaborations with spirits brands or entertainment properties.
- Tourists:Airport and destination retail exposure captures impulse purchases from travelers seeking localized souvenir formats with regional spirit infusions.
Young Adults represent the largest addressable base; Health-Conscious Consumers deliver the highest lifetime value per cohort.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in coastal United States markets, while European demand clusters around regulatory-compliant formulations that trade at 15-20% discounts to American equivalents. This asymmetry reflects divergent compliance burdens and distribution channel economics across jurisdictions.
United States
Millennial gifting occasions and bachelorette-party tourism drive volume in California, Florida, and New York. FDA-TTB dual jurisdiction forces parallel compliance systems that elevate fixed costs above boutique-producer viability thresholds. Los Angeles and Miami anchor craft confectionery clusters where direct-to-consumer platforms bypass three-tier wholesale markups.
Germany
REACH-compliant ingredient disclosure standards enable transferable formulation protocols that reduce re-certification burdens for cross-border expansion. EFSA alcohol-in-food guidance shapes serving-size standardization that constrains per-piece ABV thresholds. Berlin and Munich host specialist retailers curating premium imported gummy assortments for experiential adult consumers.
United Kingdom
Cocktail-culture crossover demand concentrates in London and Edinburgh where craft spirits brand collaborations command shelf space in department store food halls. HMRC excise classification treats alcohol gummies as spirits for duty purposes, compressing margins relative to non-alcoholic confectionery. Manchester and Bristol emerge as direct-to-consumer fulfillment hubs serving subscription replenishment models.
Canada
Provincial liquor board monopolies in Ontario, British Columbia, and Alberta restrict retail placement to government-controlled channels with limited confectionery expertise. Health Canada novel food ingredient assessments delay product registration timelines relative to American market entry. Toronto and Vancouver concentrate specialist importers navigating federal-provincial regulatory fragmentation.
Australia
Food Standards Australia New Zealand alcohol-in-food thresholds cap ABV at lower levels than American formulations, forcing recipe adaptation for market entry. TGA complementary medicine classifications create pathway ambiguity for functional ingredient co-formulations. Sydney and Melbourne direct-to-consumer platforms exploit interstate shipping frameworks that bypass retail distribution constraints.
Alcohol Gummies Market Competitive Environment
Concentration sits with spirits-conglomerate licensing arms and boutique confectionery specialists operating at opposite ends of the capability spectrum. Mid-scale regional players face margin compression from dual regulatory compliance costs and ethanol input volatility. Three strategic archetypes dominate: premium retail-curators with licensed brand portfolios, patented-technology formulators controlling texture stability, and seasonal-velocity direct-to-consumer operators. Competitive moves center on microencapsulation technology licensing and exclusive spirits-brand collaboration agreements that lock up limited-release positioning.
Within the premium retail-curator archetype, Sugarfina leverages its specialty boutique footprint and licensed spirits partnerships to sustain pricing power in discovery-driven channels. Smith & Sinclair anchors the technology-formulator tier through patented alcohol-delivery systems that differentiate shelf-stable texture profiles. Boozy Bears exemplifies the seasonal-velocity model, controlling direct-to-consumer engagement cycles through limited-release calendars that larger players struggle to replicate. These three occupy distinct competitive spaces rather than direct confrontation, with each archetype capturing margin through non-overlapping capability investments.
| Leading Market Players |
|---|
| Sugarfina |
| Smith & Sinclair |
| Inebriated Baker |
| Kate & Belle |
| Lolli & Pops |
| Maggie Lyon Chocolatiers |
| Project 7 |
| Boozy Bears |
| Tipsy Elves |
| Others |
Value Chain & Pricing Dynamics
FDA-TTB dual jurisdiction gates both supplier qualification and price differentiation simultaneously, forcing manufacturers to absorb parallel compliance costs that stratify market access between scaled spirits conglomerates and boutique confectioners. This regulatory overlay compresses margins at the mid-market tier while enabling premium pricing for players with dedicated regulatory infrastructure.
Pricing Analysis
Configured-to-order pricing commands 40-60% premiums over standard cocktail-replica formats, with microencapsulation-enabled ABV thresholds driving the spread. Three-tier pricing structure across premium, standard, and economy levels anchors the dominant model, with differentiation resting on spirits brand licensing tiers and cold-chain delivery guarantees. Cost compression in wine-based commodity segments is intensifying because bulk ethanol contracts face grain price volatility. Health-conscious consumers show lowest price sensitivity, absorbing 50-70% premiums for organic certification, while convenience-store impulse purchasers drive volume at entry price points.
Supply Chain Analysis
Inventory lead times stretch 18-24 months for ethanol-binding formulations facing stability ceilings, constraining seasonal product cycle flexibility. Manufacturing concentrates in the United States, Germany, and the United Kingdom, with pectin and gelatin feedstocks drawing from Southeast Asian processing hubs. Bulk spirits supply rests on contracted relationships with grain alcohol distillers, creating single-source vulnerability when input prices fluctuate. Distribution runs through licensed spirits wholesalers in three-tier jurisdictions, though direct-to-consumer platforms bypass these markups in permissive state frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Alcohol gummies trace a cyclical recovery pattern anchored to social consumption occasion normalization post-regulatory clarification, with millennial gifting velocity serving as the lead cyclical indicator.
For Market Incumbents: Compound defensive moats through exclusive spirits-brand collaboration agreements that lock up limited-release positioning, and deepen backward integration into pectin stabilization technology to control texture integrity across temperature ranges. Boutique confectioners threaten share through velocity-driven direct-to-consumer calendars that larger players struggle to replicate. For New Entrants and Emerging Players: Anchor in functional ingredient convergence as the most penetrable white space, targeting adaptogen and nootropic co-formulations that command wellness-positioned premiums. European REACH-compliant markets offer lower re-certification barriers for cross-border expansion. Launch through subscription replenishment models that capture repeat purchase behavior without retail slotting fee exposure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed craft confectionery specialists carrying seasonal-velocity direct-to-consumer platforms and patented alcohol-delivery formulations. Long-term viability over the five-to-ten year window hinges on regulatory arbitrage sustainability as state-level three-tier frameworks evolve. Watch TTB serving-size standardization guidance as the inflection signal that would compress margins for non-compliant product portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Enables higher ABV thresholds without texture degradation, justifying 40-60% price premiums over wine-based alternatives. |
| Direct-to-Consumer Platform Launch | Bypasses three-tier wholesale markups in permissive state jurisdictions, capturing 15-25 percentage points of additional margin. |
| Exclusive Spirits-Brand Collaboration | Locks up limited-release positioning that seasonal-velocity competitors cannot replicate through standard procurement channels. |
| Functional Ingredient Co-Formulation | Opens wellness-positioned segments commanding 25-40% price premiums through adaptogen and nootropic claims. |
| CSRD Sustainability Disclosure Program | Creates first-mover advantage for carbon-labeled supply chains that preempt multinational retail buyer procurement requirements. |
Study Parameters
Operator-level perspectives from brand managers at spirits conglomerates, category buyers at specialty retailers, formulation chemists with dual food-alcohol expertise, and regulatory affairs leads anchored the qualitative base. These primary insights combined with secondary validation from FDA formula approval databases, TTB labeling guidance documents, state liquor control board filings, and customs import records. Bottom-up demand modeling across consumer segments triangulated against top-down market sizing from production capacity assessments.
Sensitivity analysis tested forecast robustness across ethanol price volatility scenarios and regulatory timeline compression assumptions over the projection horizon. Segmentation dimensions modeled include product type, flavor profile, distribution channel, and consumer occasion-based usage patterns. CAGRs derived from historical volume trajectories adjusted for penetration ceiling effects and cross-category substitution elasticities. Forecast inputs incorporated spirits industry bulk ethanol contract pricing trends and e-commerce logistics cost curves.
Decision-makers should treat outputs as directional under base assumptions of sustained FDA-TTB jurisdictional stability and continued three-tier distribution fragmentation; material deviation in federal-state regulatory alignment would warrant model refresh. Specific risk factors include state-level reclassification of alcohol gummies as spirits subject to wholesale monopoly controls, and TTB serving-size standardization enforcement that forces reformulation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Cannabis Beverages Market
Alcoholic Beverages
American Oak Barrels Market
Alcoholic Beverages
Global Malt Market
Alcoholic Beverages
Yorker Spouts Market
Alcoholic Beverages
South Korea Tequila Market
Alcoholic Beverages
North America Craft Beer Market
Alcoholic Beverages
Mini Brew Fermenter Market
Alcoholic Beverages
Ouzo Market
Alcoholic Beverages
Alcoholic Beverages Market
Alcoholic Beverages
F-Style Jugs Market
Alcoholic Beverages
Cigar Market
Alcoholic Beverages
Vermouth Market
Alcoholic Beverages
Europe Beer Market
Alcoholic Beverages
Global Brewery Filtration Market
Alcoholic Beverages
Chocolate Beer Market
Alcoholic Beverages
Global Wine Coolers Market