
 Stem Cell Panel Market | 2026-2036
Stem Cell Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Stem Cell Panel Market Analytics
Aftermarket panel customization revenue is narrowing as vendors bundle characterization services with initial product sales. Thermo Fisher Scientific leverages its cell culture media portfolio to anchor downstream panel contracts in North American research markets. Lonza Group sustains competitive positioning through specialized induced pluripotent stem cell lines with documented differentiation protocols. Merck KGaA dominates European supply channels via its Sigma-Aldrich distribution network for characterized stem cell panels.
A stem cell panel comprises a curated collection of characterized stem cell populations, typically including defined markers for pluripotency (OCT4, SOX2, NANOG expression) and lineage-specific differentiation potential, used for comparative research, drug screening, and regenerative medicine development. Human stem cells command premium positioning due to stringent donor consent and ethical sourcing requirements, while stem cell-derived products represent the fastest-expanding margin pool as researchers shift toward ready-to-use differentiated cell types rather than raw propagation material. Animal stem cells retain stable demand in preclinical toxicology workflows where human equivalents face regulatory complexity.
FDA oversight through its Human Cells, Tissues, and Cellular and Tissue-Based Products regulations constrains market entry for uncertified panel suppliers, while EMA's Advanced Therapy Medicinal Products framework shapes European commercialization pathways. ISO 20399 standards for ancillary materials in cell processing establish baseline quality thresholds that differentiate premium panel vendors from commodity suppliers. Stakeholders must monitor evolving reimbursement codes for cell-based therapies, as payer acceptance directly determines the addressable market for clinically validated stem cell panels.
Market Dynamics
FDA tightening of Human Cells, Tissues, and Cellular and Tissue-Based Products qualification requirements is compressing the supplier base, while academic research institutions accelerate procurement of human pluripotent stem cell panels for disease modeling applications.
Growth Catalysts
- Advanced Therapy Medicinal Products framework:EMA's regulatory pathway accelerates commercialization of clinically validated stem cell panels across European research markets.
- Induced pluripotent stem cell line specialization:Documented differentiation protocols enable researchers to bypass raw propagation material and adopt ready-to-use differentiated cell types.
- California biomedical corridor concentration:Stanford and UCSF drive panel customization volumes through expanded procurement of disease modeling applications.
Market Restraints
- Donor consent and ethical sourcing requirements:Human stem cells face premium positioning constraints due to stringent procurement protocols that limit scalable supply expansion.
- ISO 20399 quality threshold differentiation:Ancillary materials standards create structural barriers for uncertified panel suppliers attempting market entry.
- Animal stem cell regulatory complexity:Preclinical toxicology workflows retain stable demand for animal equivalents where human stem cells face approval friction.
Strategic Opportunities
- Stem cell-derived product margin expansion:Researchers shifting toward differentiated cell types creates the fastest-expanding revenue pool for ready-to-use panel formats.
- Reimbursement code evolution:Payer acceptance for cell-based therapies directly determines addressable market expansion for clinically validated panels.
- Aftermarket service bundling:Vendors integrating characterization services with initial product sales capture revenue streams previously lost to third-party customization providers.
Industry Challenges
- Pluripotency marker standardization:OCT4, SOX2, NANOG expression documentation lacks uniform protocols across commercial suppliers, complicating comparative research reproducibility.
- Cell culture media portfolio integration:Downstream panel contract anchoring requires technical coordination between media formulation and stem cell characterization workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stem Cell Panel Market |
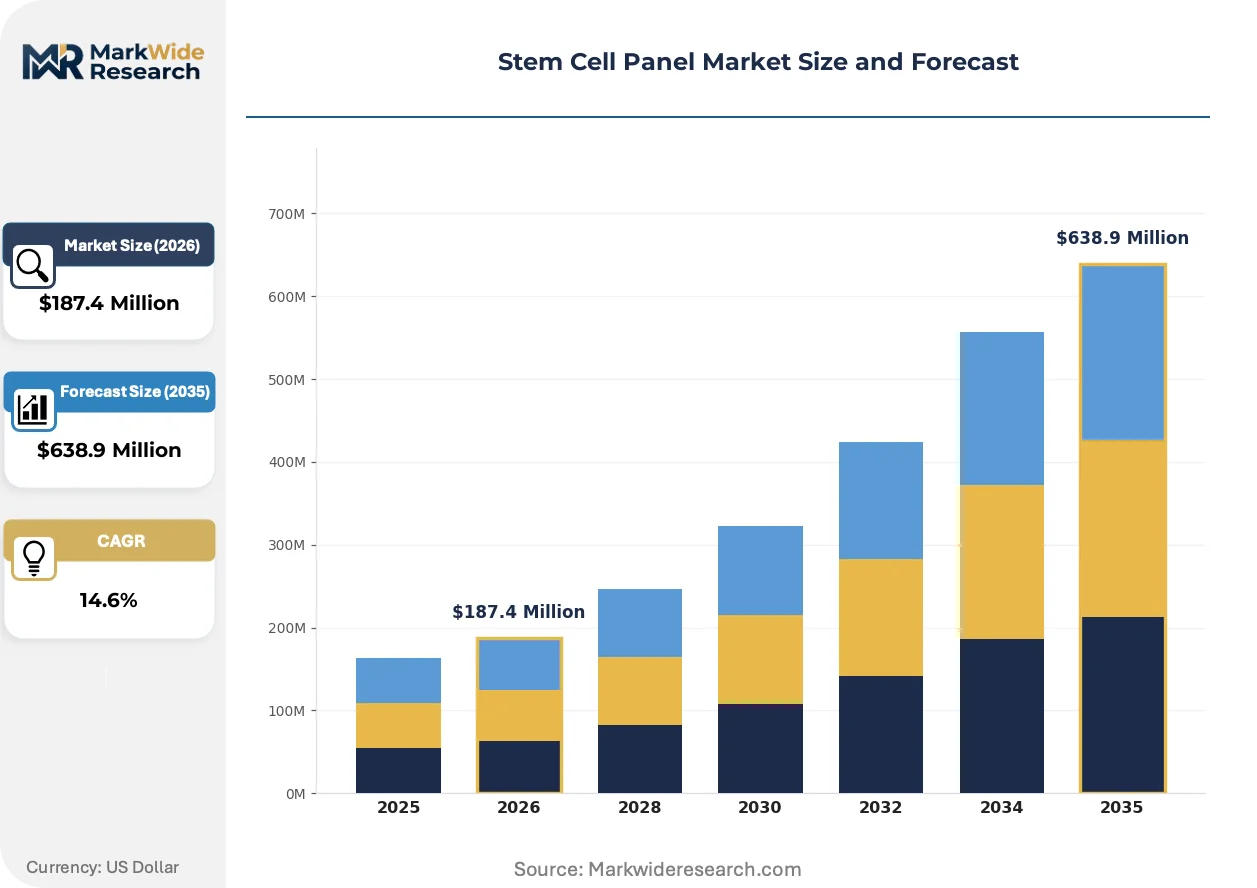
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Human Stem Cells, Animal Stem Cells, Stem Cell Lines, Stem Cell-Derived Products Therapy Area: Regenerative Medicine, Oncology, Neurology, Cardiology End User: Research Institutions, Pharmaceutical Companies, Biotechnology Firms, Clinical Laboratories Delivery Mode: Injectable, Infusable, Transplantable, Topical |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Lonza Group, STEMCELL Technologies, Bio-Techne, Miltenyi Biotec, Corning Incorporated, Takara Bio Inc., PromoCell GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stem Cell Panel Market Evolving Landscape
Characterization workflows are digitizing at the point of quality verification, while regulatory frameworks on both sides of the Atlantic tighten documentation requirements for human-derived biological materials.
High-content imaging platforms are digitizing stem cell panel quality assessment by automating pluripotency marker detection and lineage trajectory prediction. Academic core facilities and contract research organizations are adopting these systems at accelerated replacement cycles for manual microscopy protocols. The technology is digitizing supplier differentiation criteria, compressing competitive advantage to algorithmic consistency rather than manual expertise.
EMA's Advanced Therapy Medicinal Products framework is reshaping European commercialization pathways for stem cell panels intended for clinical translation. Manufacturers must now document manufacturing processes and quality controls to medicinal product standards rather than research-grade specifications. Cell therapy developers in Germany and Switzerland are responding by qualifying dual-use panel inventories that satisfy both research and clinical precursor requirements.
Consolidated procurement through institutional core facilities is displacing individual laboratory purchasing authority for stem cell panels. Stanford, UCSF, and comparable research institutions are centralizing vendor qualification and volume contracting decisions. This concentration is most visible in California's biomedical corridor, where customization volumes now flow through single points of institutional negotiation rather than distributed principal investigator discretion.
Stem Cell Panel Market Segmentation
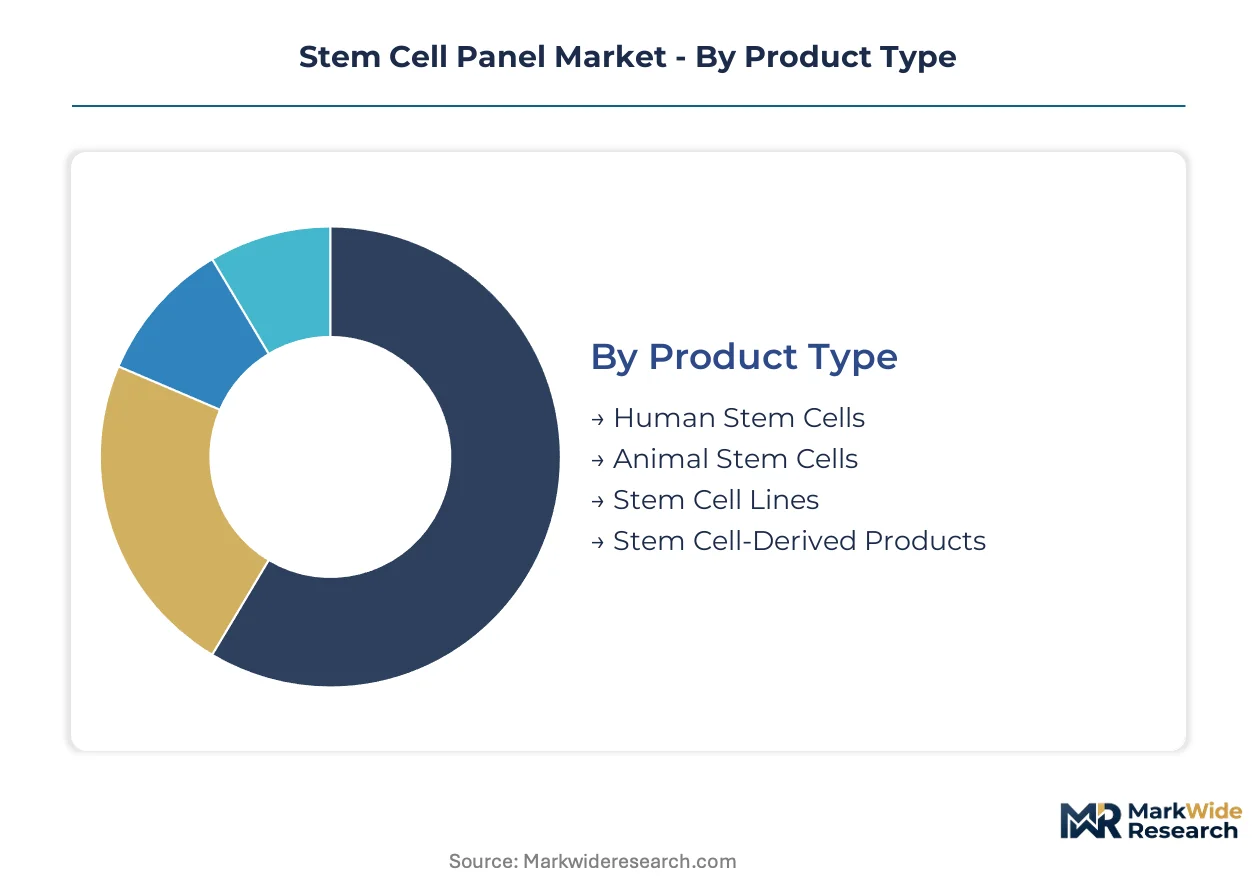
Stem cell panel segmentation reflects divergent maturity levels across biological source materials, therapeutic applications, and institutional procurement patterns. Product type stratification separates established human stem cell offerings from emerging ready-to-use differentiated formats, while end-user concentration determines customization depth and regulatory documentation requirements.
Product Type:
Mature propagation formats coexist with emerging ready-to-use derivatives across the product spectrum.
- Human Stem Cells:Primary pluripotent populations requiring documented donor consent and ethical sourcing verification. Academic research institutions in California concentrate procurement for disease modeling applications, constrained by FDA qualification requirements that compress the certified supplier base.
- Stem Cell-Derived Products:Pre-differentiated cell types bypassing raw propagation workflows. Stanford and UCSF drive adoption of documented differentiation protocols, creating the fastest-expanding margin pool as researchers shift away from manual lineage induction.
- Animal Stem Cells:Retain stable demand in preclinical toxicology where human equivalents face regulatory friction.
- Stem Cell Lines:Characterized populations with pluripotency marker documentation (OCT4, SOX2, NANOG).
Human Stem Cells retains volume leadership; Stem Cell-Derived Products holds the steepest expansion curve.
Therapy Area:
Application focus shifts from experimental oncology toward clinically validated regenerative pathways.
- Regenerative Medicine:Cell replacement therapies and tissue engineering applications requiring GMP-compliant panel characterization. EMA's Advanced Therapy Medicinal Products framework accelerates European commercialization, while reimbursement code evolution determines addressable market scale.
- Oncology:Tumor modeling and immuno-oncology screening platforms. Pharmaceutical companies concentrate demand for patient-derived xenograft applications, though differentiation protocol standardization lags behind regenerative applications.
- Neurology:Disease modeling for neurodegenerative conditions using induced pluripotent stem cell-derived neurons.
- Cardiology:Cardiomyocyte differentiation for arrhythmia screening and heart failure modeling.
Regenerative Medicine commands the premium pricing tier; Oncology maintains the broadest installed base.
End User:
Procurement authority is concentrating through institutional core facilities rather than distributed laboratory purchasing.
- Research Institutions:Academic core facilities consolidating vendor qualification and volume contracting. Stanford, UCSF, and comparable institutions now centralize panel customization decisions, displacing individual principal investigator discretion in California's biomedical corridor.
- Pharmaceutical Companies:Integrated drug discovery workflows requiring scalable, reproducible panel supply. ISO 20399 compliance differentiates premium vendors from commodity suppliers in high-throughput screening applications.
- Biotechnology Firms:Cell therapy developers qualifying dual-use inventories satisfying research and clinical precursor requirements.
- Clinical Laboratories:Diagnostic applications requiring documented manufacturing processes to medicinal product standards.
Research Institutions dominate customization volumes; Biotechnology Firms are gaining share fastest through cell therapy pipeline expansion.
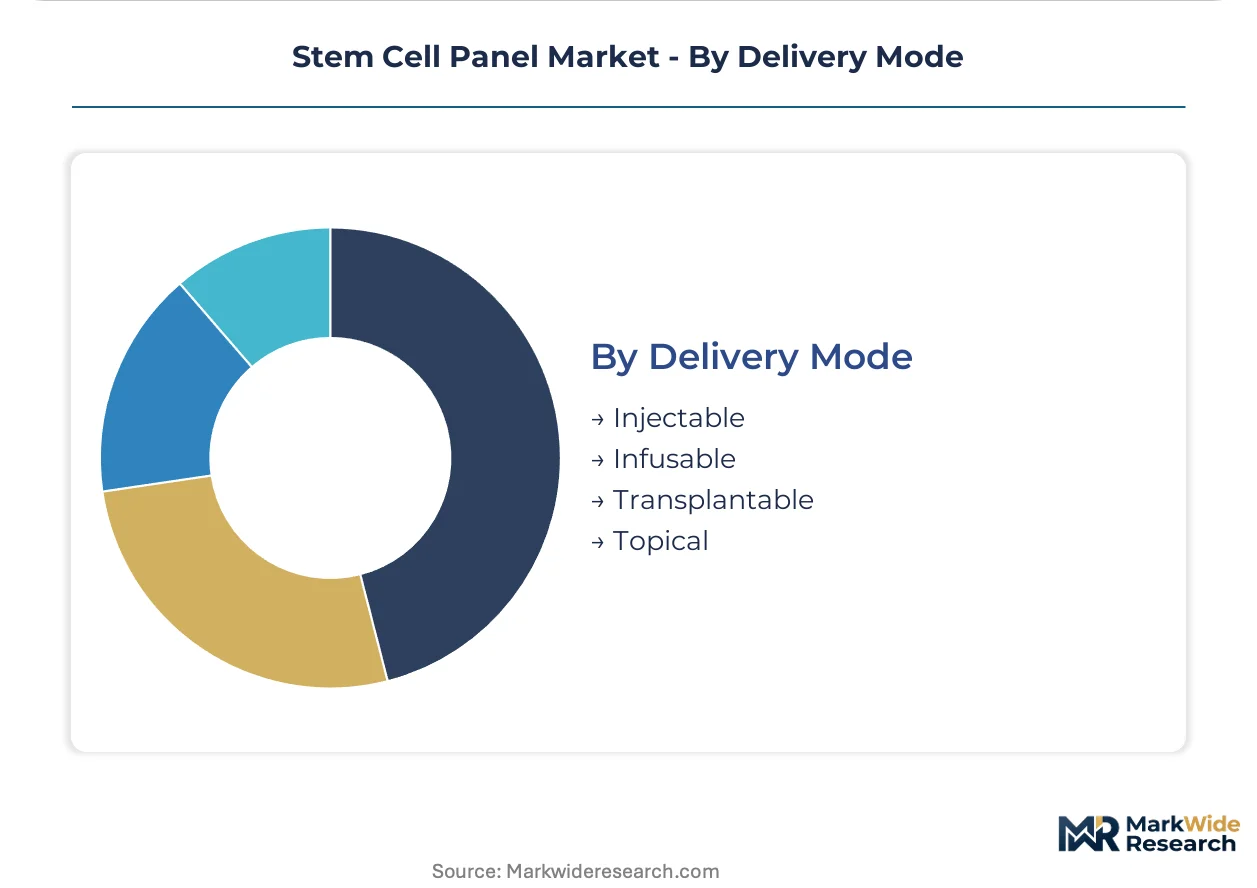
Delivery Mode:
Physical format selection determines regulatory pathway complexity and shelf-life economics.
- Injectable:Suspension formulations for localized tissue delivery. Clinical laboratories concentrate demand as cell-based therapies advance toward commercial reimbursement, with cryopreservation protocols establishing quality thresholds.
- Transplantable:Three-dimensional constructs and organoid formats. Regenerative medicine applications in Germany and Switzerland drive qualification of implantable panel derivatives to EMA medicinal product standards.
- Infusable:Systemic circulation delivery for hematopoietic applications.
- Topical:Surface applications in dermatology and wound healing.
Injectable formats retain procedural familiarity; Transplantable configurations are climbing the fastest through organoid technology maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement contexts. Academic core facilities negotiate volume discounts aggressively, while cell therapy developers absorb premium pricing for clinically validated panels. Demand elasticity tightens where reimbursement pathways remain undefined.
United States
Stanford and UCSF anchor procurement concentration in California's biomedical corridor, driving panel customization volumes for disease modeling applications. FDA's Human Cells, Tissues, and Cellular and Tissue-Based Products regulations compress the certified supplier base through tightened qualification requirements. Greater Boston's cell therapy cluster qualifies dual-use inventories satisfying research and clinical precursor standards.
Germany
Cell therapy developers in Baden-Württemberg and Bavaria accelerate adoption of EMA-aligned panel inventories. The country's national pharmaceutical regulator enforces Advanced Therapy Medicinal Products documentation standards for manufacturing processes and quality controls. Heidelberg and Munich research consortia centralize vendor qualification decisions through institutional core facilities.
Switzerland
Basel-based pharmaceutical operations concentrate demand for GMP-compliant stem cell panels in regenerative medicine applications. Swissmedic requirements shape commercialization pathways for clinically validated inventories intended for therapeutic translation. The Zurich-Genève corridor hosts specialized induced pluripotent stem cell line providers with documented differentiation protocols.
Japan
PMDA's regenerative medicine framework accelerates procurement of characterized stem cell populations for clinical precursor applications. METI-funded initiatives support domestic panel standardization efforts. The Kansai region's biomedical cluster concentrates high-content imaging platform adoption for automated pluripotency marker detection.
United Kingdom
London and Cambridge research institutions expand procurement of human pluripotent stem cell panels for comparative research workflows. The MHRA's alignment with EMA standards shapes documentation requirements for clinically oriented inventories. Oxford's cell therapy pipeline drives demand for ISO 20399-compliant ancillary materials in processing workflows.
Stem Cell Panel Market Competitive Landscape
Capability concentration sits with specialized cell line developers; scale advantage sits with diversified life science conglomerates. The supplier base stratifies across three tiers: integrated conglomerates anchoring downstream contracts through media portfolio bundling; mid-scale specialists commanding premium positioning through documented differentiation protocols; and regional distributors serving price-sensitive academic segments. Dominant competitive moves include aftermarket service integration and dual-use inventory qualification for research-to-clinical transition pathways.
Within the integrated conglomerate tier, Thermo Fisher Scientific and Merck KGaA occupy positions shaped by distribution network reach and ancillary product portfolio breadth. Lonza Group exemplifies the specialization archetype, with documented protocol libraries supporting premium panel positioning. These three entities represent contrasting strategic anchors: one through cell culture media integration, another through European supply channel dominance, and the third through induced pluripotent stem cell line specialization.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Lonza Group |
| STEMCELL Technologies |
| Bio-Techne |
| Miltenyi Biotec |
| Corning Incorporated |
| Takara Bio Inc. |
| PromoCell GmbH |
| Others |
Value Network & Pricing Analysis
Cold-chain logistics corridors connecting California's biomedical corridor to European cell therapy clusters impose freight premiums that compress margins for uncertified suppliers while amplifying price differentiation between GMP-compliant and research-grade panel tiers. FDA qualification requirements and EMA Advanced Therapy Medicinal Products documentation standards create supply base bifurcation, with certified vendors capturing pricing power through dual-use inventory positioning.
Pricing Analysis
Aftermarket characterization service contracts now drive lifetime value as vendors bundle quality verification with initial panel sales. Three-tier pricing structure across premium GMP-compliant, standard research-grade, and economy uncharacterized tiers reflects ISO 20399 certification status and documented differentiation protocol depth. Cost compression in the research-grade tier intensifies as institutional core facilities consolidate procurement and negotiate volume discounts aggressively. Academic core facilities exhibit highest price sensitivity, while cell therapy developers absorb premium pricing for clinically validated inventories.
Supply Chain Analysis
Export-control regimes on human-derived biological materials restrict cross-border flows of characterized stem cell populations, particularly affecting shipments between United States and European research institutions. Supply concentrates in United States, Germany, and Switzerland, with panel manufacturing anchored in FDA-regulated and EMA-aligned facilities. Raw material dependencies include donor consent documentation systems, cryopreservation media formulations, and high-content imaging platforms for quality verification. Single-source vulnerability runs through specialized induced pluripotent stem cell line repositories. Distribution runs through institutional core facilities and qualified contract research organizations rather than traditional laboratory supply distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from characterization and differentiation protocol licensing expands faster than hardware panel sales, creating recurring income pools that justify premium valuations for integrated vendors.
For Market Incumbents: Build protocol-documentation moats by investing in proprietary induced pluripotent stem cell line libraries with validated lineage trajectories. Deepen backward integration into cell culture media formulation to anchor downstream panel contracts against Thermo Fisher Scientific's bundling strategy. Expand capacity in Baden-Württemberg and Bavaria to capture EMA-aligned demand from German cell therapy developers consolidating procurement through Heidelberg and Munich core facilities. For New Entrants and Emerging Players: Pursue white-space opportunities in animal stem cell panels for preclinical toxicology workflows, where regulatory friction limits human-equivalent competition and pricing remains less compressed. Target biotechnology firms in the Zurich-Genève corridor seeking dual-use inventories that satisfy both research and clinical precursor requirements. Differentiate through automated pluripotency marker detection services bundled with panel sales, displacing third-party high-content imaging providers. For Investors and Strategic Acquirers: Specialized cell line developers with documented differentiation protocols and GMP-ready manufacturing infrastructure represent the most defensible acquisition targets in a consolidating supplier base. Long-term viability hinges on reimbursement code evolution for cell-based therapies, which will determine addressable market scale for clinically validated panels. Watch for FDA qualification requirement expansions that would accelerate supplier base compression and reward early movers in dual-use inventory positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Use Inventory Qualification | EMA's Advanced Therapy Medicinal Products framework rewards manufacturers satisfying both research and clinical precursor standards. |
| Characterization Service Bundling | Automated pluripotency marker detection displaces manual microscopy and captures aftermarket revenue from third-party providers. |
| Core Facility Partnership | Stanford and UCSF procurement consolidation creates single-point negotiation leverage for volume panel customization contracts. |
| Backward Integration into Media | In-house cell culture formulation anchors downstream panel contracts against diversified life science conglomerates. |
| Regional Manufacturing Footprint | Baden-Württemberg and Bavaria capacity expansion captures EMA-aligned demand from German cell therapy developers. |
Research Methodology
A standing panel of cell therapy development executives, academic core facility directors, regulatory affairs specialists, and GMP manufacturing quality officers provided ongoing calibration across the primary research phase. This study combined structured interviews with these stakeholders against secondary validation from FDA Human Cells, Tissues, and Cellular and Tissue-Based Products guidance documents, EMA Advanced Therapy Medicinal Products framework publications, ISO 20399 ancillary materials standards, and institutional procurement records from Stanford, UCSF, and comparable research consortia. Bottom-up panel demand modeling and top-down life science reagent market sizing were triangulated to converge on segment-level estimates.
Scenario-bracketing around reimbursement code evolution for cell-based therapies and FDA qualification requirement tightening framed the analytical approach across the projection horizon. Segmentation dimensions modeled include biological source material, therapeutic application focus, end-user institutional type, and delivery mode format. CAGRs were derived from fitted growth curves calibrated to documented procurement volumes and vendor-reported customization trends. Forecast inputs incorporated high-content imaging platform adoption cycles and institutional core facility consolidation patterns.
Macroeconomic conditions sit as an overlay; deviation in NIH funding allocations, pharmaceutical R&D budgets, or cell therapy venture financing would shift the trajectory. Forecasts reflect assumptions regarding regulatory pathway stability and payer acceptance timelines for regenerative medicine applications. Material shifts in FDA qualification requirements or EMA Advanced Therapy Medicinal Products documentation standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Diagnostics
Global Complete Blood Count Device Market
Medical Diagnostics
North America Circulating Tumor Cells (CTC) Liquid Biopsy Market
Medical Diagnostics
Global Hydrophobic Interaction Chromatography Market
Medical Diagnostics
Carrier Screening Market
Medical Diagnostics
Fluid Biopsy Market
Medical Diagnostics
Medical Isotope Market
Medical Diagnostics
Artificial Intelligence (AI) in Medical Diagnostics Market
Medical Diagnostics
Global ECG Stress Test Market
Medical Diagnostics
Blood Platelet Market
Medical Diagnostics
North America Flow Cytometry Market
Medical Diagnostics
Liver Biopsy Market
Medical Diagnostics
Telepathology Market
Medical Diagnostics
Magnetic Resonance Analyzer Market
Medical Diagnostics
Flow Cytometry Market
Medical Diagnostics
Asia-Pacific Flow Cytometry Market
Medical Diagnostics
Circulating Tumor Cells (Ctcs) Prognostic Technologies Market