
 Automotive Emission Sensors Market | 2026-2036
Automotive Emission Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Emission Sensors Market Analysis
Fleet operators and regulatory compliance buyers is collapsing as the dominant demand archetype, while individual consumer aftermarket purchasing loses relative share. Robert Bosch GmbH leverages its vertically integrated sensor manufacturing to dominate OEM supply chains for passenger and commercial vehicles. Denso Corporation anchors its position through R&D intensity in wideband oxygen sensing technology. Continental AG competes by controlling distribution channels across European and North American vehicle assembly plants.
Automotive emission sensors are electrochemical or optical transducers that detect exhaust gas concentrations of oxygen, nitrogen oxides, and particulate matter, typically operating at temperatures exceeding 600°C to ensure catalytic converter efficiency and regulatory compliance. Their primary commercial purpose is real-time exhaust monitoring that enables engine control units to optimize combustion and trigger fault conditions when emissions exceed calibrated thresholds. NOx sensors command premium positioning due to diesel aftertreatment complexity and Euro 7 implementation timelines, while particulate matter sensors gain share from gasoline particulate filter adoption in direct-injection engines. Electrochemical technology leads volume shipments, though optical sensors attract development investment for multi-species detection capability.
The United States EPA and California Air Resources Board enforce tailpipe standards that mandate sensor redundancy and onboard diagnostic verification, directly shaping product specifications and warranty obligations for suppliers. Europe's Euro 7 framework and REACH chemical restrictions further tighten material compliance and durability requirements across the sensor value chain. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether modular sensor architectures or region-specific product lines offer superior capital efficiency.
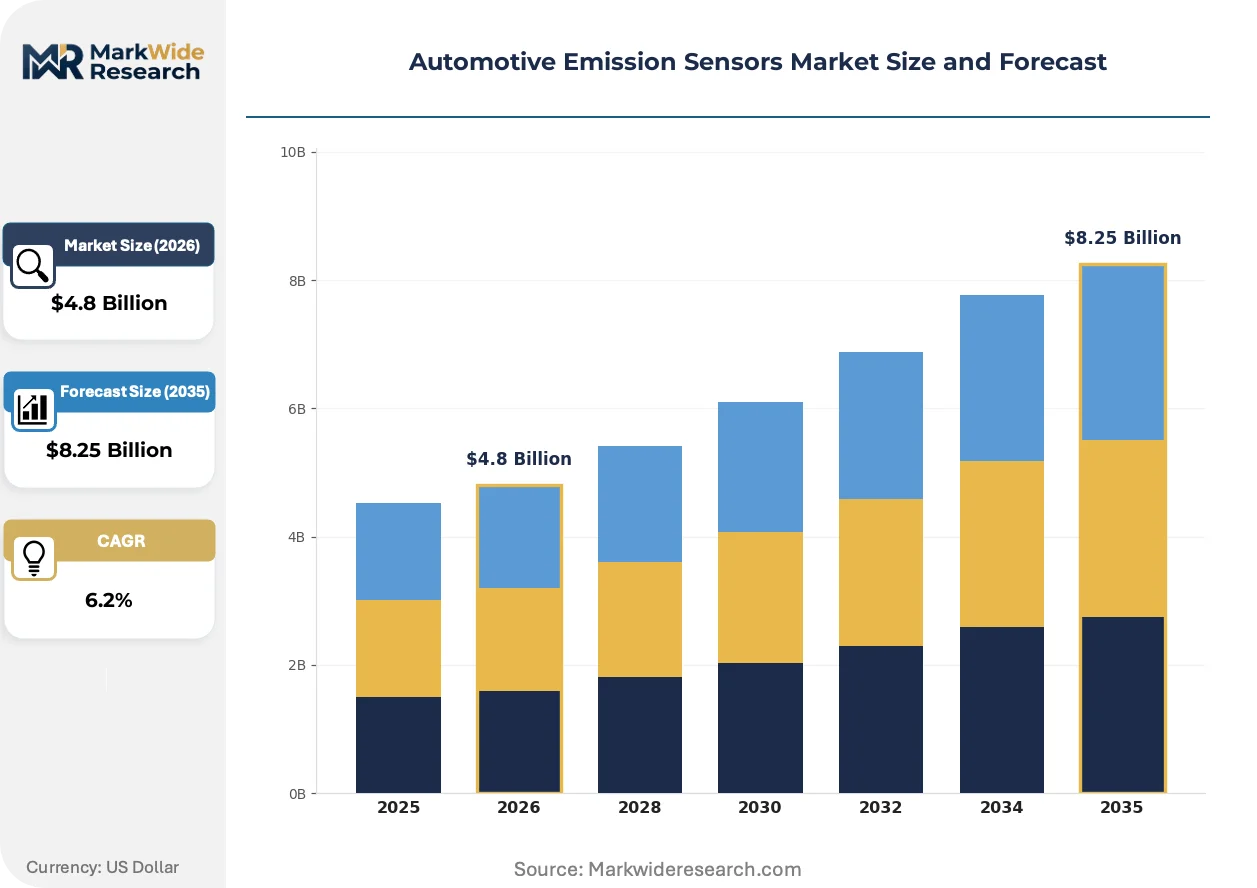
Market Dynamics
Regulatory calibration timelines are compressing development cycles as Euro 7 and EPA Tier 3 force simultaneous compliance across multiple pollutant categories, requiring sensor architectures that adapt to diverging certification thresholds without full platform redesigns.
Growth Catalysts
- Diesel aftertreatment complexity:Heavy-duty commercial fleets in Germany and the United States face expanded NOx monitoring mandates under Euro 7 and EPA rules, multiplying sensor count per vehicle.
- Gasoline particulate filter adoption:Direct-injection gasoline engines require particulate matter sensors previously unnecessary in spark-ignition architectures.
- Onboard diagnostic verification:California Air Resources Board mandates for redundant sensor arrays create pull-through demand for backup electrochemical transducers.
Market Restraints
- Platinum group metal cost volatility:Electrochemical NOx sensors depend on rhodium and palladium electrodes, exposing manufacturers to commodity price swings.
- Thermal cycling durability limits:Sensors operating above 600°C face material degradation that compresses warranty exposure windows.
- REACH chemical restrictions:ECHA substance limitations constrain ceramic substrate formulations and electrode coatings.
Strategic Opportunities
- India commercial vehicle phase-in:BS VI Stage II implementation creates first-mover positioning for suppliers establishing local calibration facilities.
- Optical multi-species detection:Non-dispersive infrared and laser absorption spectroscopy converge to enable single-sensor nitrogen oxides and ammonia measurement.
- Remanufactured sensor channels:Independent aftermarket distributors in Poland and Mexico capture value from out-of-warranty fleet refurbishment demand.
Industry Challenges
- Cross-functional calibration expertise scarcity:Engineers must simultaneously master exhaust chemistry, control algorithm integration, and regulatory interpretation.
- Dual certification timeline compression:Suppliers face overlapping EPA and KBA homologation deadlines with incompatible test protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Emission Sensors Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: O2 Sensors, NOx Sensors, Particulate Matter Sensors, Wideband Sensors Technology: Chemical Sensors, Electrochemical Sensors, Optical Sensors, Thermal Sensors End User: Vehicle Manufacturers, Aftermarket Suppliers, Research Institutions, Regulatory Bodies Installation Type: OEM Integration, Aftermarket Installation, Retrofit Solutions, R&D Prototypes |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, Faurecia, Fujikura Ltd., Walker Products, Inc., Friedrichshafen AG, Valeo S.A., Infineon Technologies AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Emission Sensors Market Emerging Trajectories
Sensor modality diversification is fragmenting technology roadmaps as electrochemical dominance faces optical encroachment, while regulatory divergence between jurisdictions forces modular platform strategies over unified global designs.
Wideband oxygen sensing is supplanting narrowband architectures in gasoline engine control modules. Tier-one suppliers are accelerating adoption to meet Euro 7 lambda control precision requirements. This transition is compressing margins for legacy sensor producers while rewarding R&D-intensive manufacturers with captive semiconductor fabrication.
REACH substance restrictions are tightening material compliance across the European sensor value chain. ECHA candidate list updates are forcing reformulation of electrode pastes and ceramic substrates. German OEMs are responding by consolidating supplier qualification programs to reduce testing redundancy.
Fleet procurement consolidation is reshaping contract structures for commercial vehicle sensor supply. Large logistics operators in the United States are bypassing traditional distribution tiers to negotiate direct volume agreements with manufacturers. This channel compression is most visible in long-haul trucking segments where total cost of ownership calculations dominate specification decisions.
Automotive Emission Sensors Market Segmentation
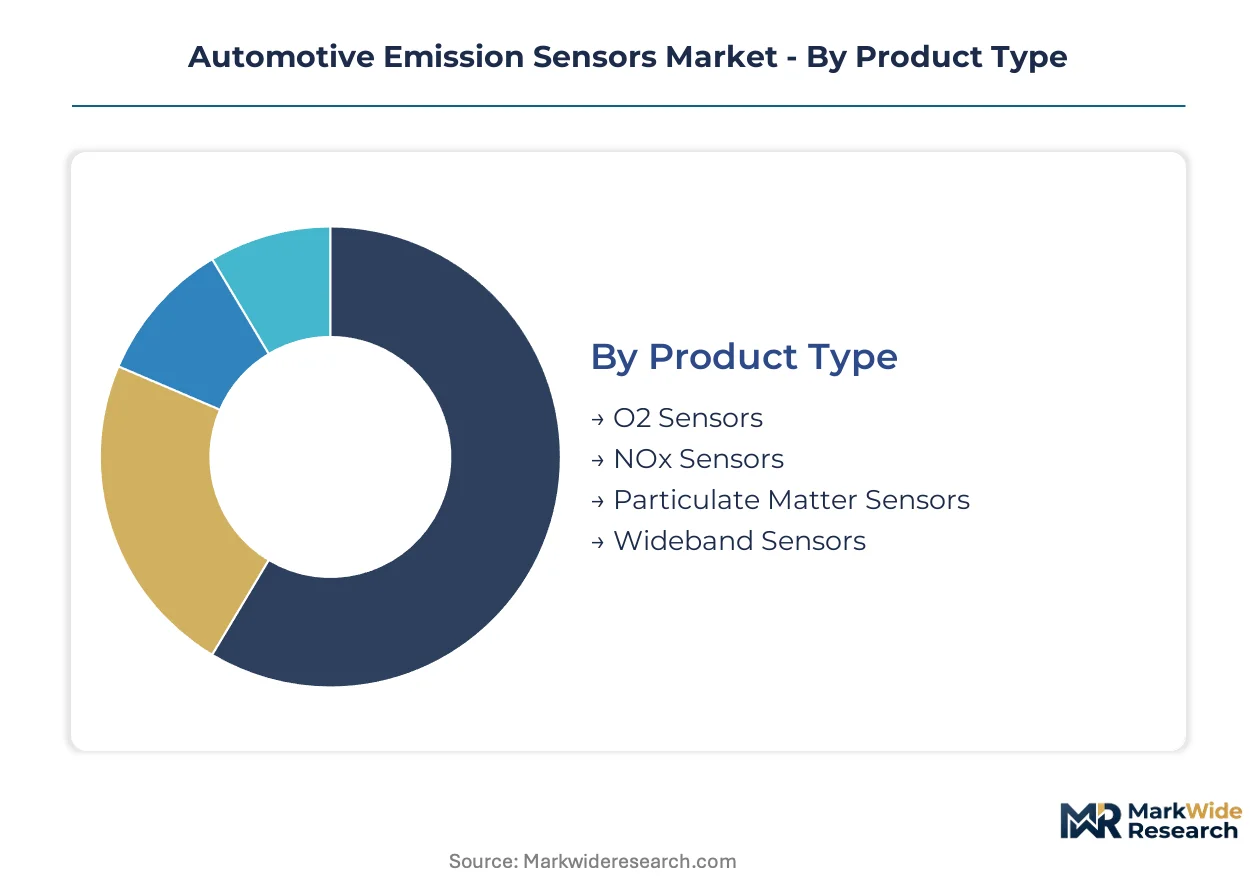
Emission sensor procurement splits sharply between OEM calibration requirements and aftermarket replacement cycles, with technology choices increasingly dictated by Euro 7 and EPA Tier 3 compliance timelines rather than pure cost optimization.
Product Type:
Wideband architectures face substitution pressure from next-generation optical systems, while legacy narrowband designs confront accelerated phase-out.
- O2 Sensors:Narrowband zirconia-based transducers measure oxygen concentration through voltage differential across a heated ceramic element. German passenger vehicle OEMs still specify these for cost-sensitive engine control modules despite precision limitations.
- NOx Sensors:Electrochemical cells with rhodium-palladium electrodes detect nitrogen oxide concentrations in diesel exhaust streams. Heavy-duty fleet operators in the United States multiply sensor counts per vehicle to satisfy CARB redundant monitoring mandates.
- Particulate Matter Sensors:Piezoelectric accumulation devices measure soot loading in gasoline particulate filters.
- Wideband Sensors:Pump-cell architectures deliver continuous lambda measurement across lean-to-rich combustion regimes.
O2 sensors anchor the volume base while wideband sensors gain share at the steepest rate.
Technology:
Cost tier stratification separates premium optical R&D investments from commoditized electrochemical volume production.
- Chemical Sensors:Solid-state metal oxide semiconductors react with target gas species to produce measurable resistance changes. Aftermarket distributors in Poland favor these for out-of-warranty fleet refurbishment due to lower unit economics.
- Electrochemical Sensors:Amperometric cells with liquid or polymer electrolytes dominate current production volumes. Robert Bosch GmbH and Denso Corporation control captive manufacturing of ceramic substrates and electrode pastes.
- Optical Sensors:Non-dispersive infrared and laser absorption spectroscopy enable multi-species detection without consumable electrodes.
- Thermal Sensors:Calorimetric devices measure combustion efficiency through exhaust gas temperature differentials.
Electrochemical technology anchors the volume base while optical sensors expand most quickly.
End User:
Customer type concentration favors direct procurement by large fleet operators, compressing traditional distribution tier margins.
- Vehicle Manufacturers:OEMs specify sensor architectures during powertrain development cycles with 5-7 year lock-in periods. Tier-one suppliers in Germany coordinate calibration with KBA homologation timelines.
- Aftermarket Suppliers:Independent distributors serve replacement demand from aging commercial vehicle fleets. Mexican refurbishment specialists capture value from cross-border parts arbitrage.
- Research Institutions:Universities and national laboratories validate next-generation sensing modalities.
- Regulatory Bodies:EPA and CARB contract sensor manufacturers for reference-grade measurement equipment.
Vehicle manufacturers anchor the volume base while aftermarket suppliers climb the fastest.
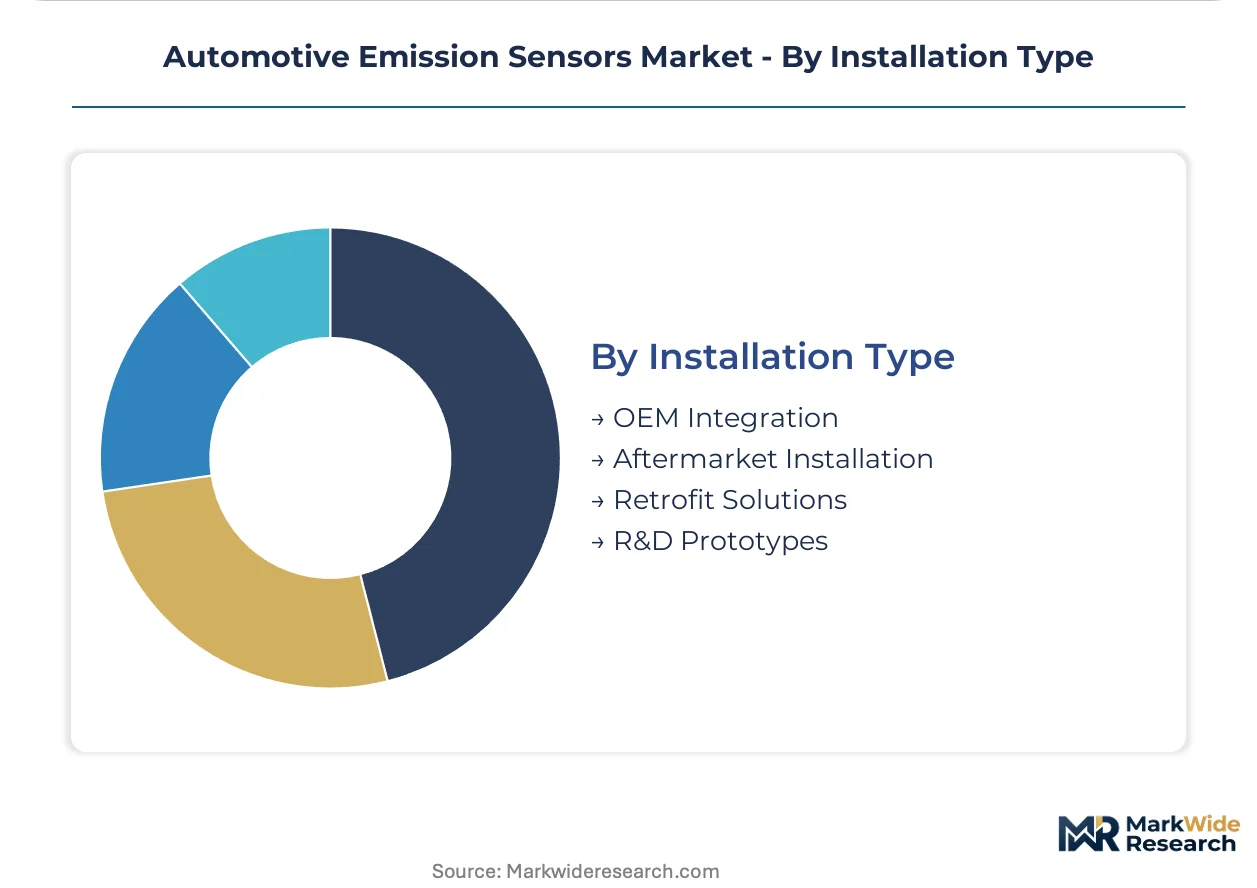
Installation Type:
Application maturity diverges between factory-integrated architectures and emerging retrofit channels.
- OEM Integration:Sensors ship as pre-calibrated modules embedded within exhaust aftertreatment systems. Continental AG controls distribution channels across European and North American vehicle assembly plants.
- Aftermarket Installation:Replacement units require diagnostic tool recalibration for specific engine control module protocols. United States long-haul trucking operators negotiate direct volume agreements to bypass distribution tiers.
- Retrofit Solutions:Add-on systems upgrade pre-compliance vehicles to meet current emission thresholds.
- R&D Prototypes:Pre-production units support regulatory pre-homologation testing.
OEM integration anchors the volume base while aftermarket installation shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sensor manufacturing concentrates in Germany where tier-one suppliers coordinate KBA homologation timelines with OEM powertrain development cycles. Calibration expertise clusters around Stuttgart and Munich, creating a supply-side anchor that shapes procurement patterns across adjacent European markets.
United States
Heavy-duty commercial fleets multiply sensor counts per vehicle to satisfy CARB redundant monitoring mandates. EPA Tier 3 rules compress development cycles for suppliers serving Detroit-based OEMs. Long-haul trucking operators in Texas and California negotiate direct volume agreements that bypass traditional distribution tiers.
Germany
Automotive OEMs and tier-one suppliers coordinate regulatory calibration for Euro 7 implementation. KBA homologation timelines force simultaneous compliance across nitrogen oxides and particulate matter thresholds. Stuttgart anchors captive manufacturing of ceramic substrates and electrode pastes for electrochemical transducers.
China
Domestic OEMs accelerate sensor deployment to meet Stage VI emission standards for commercial vehicles. MIIT mandates onboard diagnostic verification that mirrors EPA technical requirements. Yangtze River Delta clusters host calibration facilities serving both local manufacturers and export-oriented joint ventures.
India
BS VI Stage II implementation creates first-mover positioning for suppliers establishing local calibration infrastructure. Commercial vehicle phase-in timelines concentrate demand around Pune and Chennai manufacturing corridors. The country's national automotive regulator tightens permissible emission thresholds for heavy-duty diesel fleets.
Mexico
Cross-border parts arbitrage supports aftermarket refurbishment demand from aging United States commercial vehicle fleets. Northern border states capture value from independent distributors serving out-of-warranty operators. Local assembly plants integrate pre-calibrated sensor modules for export to North American OEMs.
Automotive Emission Sensors Market Vendor Landscape
Concentration sits with diversified automotive suppliers that control captive manufacturing of ceramic substrates and electrode formulations. Three to five integrated players anchor OEM supply chains through long-term calibration lock-in periods. Strategic archetypes include vertically integrated sensor specialists, diversified tier-one automotive suppliers, and semiconductor-anchored technology providers. Competitive moves center on backward integration into ceramic substrate production and geographic expansion of calibration facilities to match regional homologation timelines.
Among Germany-based diversified suppliers, Robert Bosch GmbH and Continental AG exemplify the vertically integrated archetype that dominates OEM supply chains for passenger and commercial vehicles. Denso Corporation represents the Asia-Pacific anchored tier-one supplier with R&D intensity in wideband oxygen sensing technology. These three companies occupy positions that reflect the market's structural division between electrochemical volume production and optical technology development investment.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| Faurecia |
| Fujikura Ltd. |
| Walker Products, Inc. |
| Friedrichshafen AG |
| Valeo S.A. |
| Infineon Technologies AG |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day ceramic substrate lead times from Stuttgart suppliers concentrate pricing power among German tier-one manufacturers, compressing margin flexibility for downstream distributors while amplifying volume leverage for OEM direct procurement.
Pricing Analysis
Euro 7 dictates the pricing tier structure across electrochemical and optical sensor categories, stratifying premium wideband architectures against commoditized narrowband alternatives. Price differentiation hinges on KBA certification grade and rhodium-palladium electrode content, with heavy-duty fleet operators showing lowest sensitivity due to total-cost-of-ownership procurement models. Cost compression in aftermarket channels is intensifying because REACH compliance expenses force reformulation investments. Independent distributors in Poland and Mexico face the steepest price sensitivity as refurbishment demand competes on unit economics.
Supply Chain Analysis
Just-in-time inventory strategies dominate OEM sensor procurement, though platinum group metal price volatility pushes select manufacturers toward strategic electrode paste stockpiles. Manufacturing concentrates in Germany, China, and Mexico, with ceramic substrate production anchored in Stuttgart and Yangtze River Delta clusters. The chain draws from rhodium, palladium, and zirconium feedstocks, exposing producers to commodity swings. Single-source vulnerability in noble metal refining creates structural risk. Distribution runs through tier-one supplier direct channels to vehicle assembly plants, bypassing traditional wholesale tiers for large fleet accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect as sensor architectures modularize to accommodate diverging EPA and KBA homologation timelines, with interoperability between electrochemical and optical systems becoming the critical ecosystem battleground.
For Market Incumbents: Consolidate backward integration into ceramic substrate production to defend against optical technology substitution and captive semiconductor fabrication advantages. Lock in five-to-seven-year calibration lock-in periods with Stuttgart OEMs before Euro 7 implementation compresses development cycles. Channel control through direct fleet agreements represents the priority defensive lever against margin erosion in aftermarket tiers.
For New Entrants and Emerging Players: Anchor in India's BS VI Stage II commercial vehicle phase-in, where local calibration infrastructure scarcity creates first-mover positioning before incumbent facilities achieve regional coverage. Target optical multi-species detection R&D partnerships with Yangtze River Delta joint ventures as the most penetrable technology entry point. A go-to-market angle through remanufactured sensor channels in Mexico captures cross-border parts arbitrage value from aging United States fleets.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across optical sensor development programs as non-dispersive infrared and laser absorption spectroscopy converge. Long-term viability favors semiconductor-anchored technology providers with captive fabrication over pure-play electrochemical specialists. Acquisition targets should display calibration expertise spanning exhaust chemistry and control algorithm integration. The signal to watch is EPA-KBA regulatory divergence acceleration, which rewards modular platform strategies over unified global designs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrates | Captive supply of zirconia elements insulates Robert Bosch GmbH from REACH reformulation costs. |
| Optical Multi-Species Detection Development | Laser absorption spectroscopy convergence enables single-sensor NOx and ammonia measurement for Euro 7. |
| Local Calibration Facility Expansion | Pune and Chennai infrastructure captures BS VI Stage II commercial vehicle demand before incumbent arrival. |
| Direct Fleet Procurement Channel | Texas and California long-haul operators bypass distribution tiers, compressing aftermarket margins. |
| Remanufactured Sensor Channel Development | Polish and Mexican refurbishment specialists capture value from out-of-warranty United States fleet demand. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EPA regulatory filings, KBA homologation databases, vehicle production registries, and tier-one supplier procurement disclosures. Interviews with OEM platform engineers, aftermarket distribution heads, and ceramic substrate procurement leads combined with exhaust aftertreatment system technical documentation. Bottom-up sensor shipment estimates triangulate against top-down automotive production forecasts.
Segmentation dimensions modeled span sensor modality, vehicle propulsion architecture, content per vehicle by emissions aftertreatment complexity, OEM supply tier, and regional regulatory cluster. CAGRs derive from regression against historical adoption curves for comparable compliance-driven automotive electronics. Industry-specific inputs include platinum group metal price trajectory assumptions and Euro 7-EPA Tier 3 implementation timeline convergence scenarios.
Material uncertainties — platinum group metal supply disruptions, REACH substance list expansions, and cross-jurisdictional homologation protocol divergence — sit outside the modeled envelope. Forecasts reflect assumptions about calibration expertise scarcity resolution and optical technology cost curves. Revision becomes warranted when regulatory timeline compression exceeds concurrent development cycle adaptation capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Global Automotive Projector Headlamps Market
Automotive Electrical & Electronics
Automotive Temperature and Humidity Sensors Market
Automotive Electrical & Electronics
Europe Automotive EPS Market
Automotive Electrical & Electronics
Automotive Esim Market
Automotive Electrical & Electronics
Automotive Ultracapacitor Market
Automotive Electrical & Electronics
Automotive Camera Market
Automotive Electrical & Electronics
Automotive Engine Management Sensors Market
Automotive Electrical & Electronics
Automotive Lighting Actuators Market
Automotive Electrical & Electronics
Automotive Electronics Control Unit Management (ECU/ECM) Market
Automotive Electrical & Electronics
Automotive Digital Market
Automotive Electrical & Electronics
Bicycle Electronic Drivetrain Market
Automotive Electrical & Electronics
Africa and Middle East Automotive Tpms Market
Automotive Electrical & Electronics
US Automotive E-Axle Market
Automotive Electrical & Electronics
Automotive Speed Sensor Market
Automotive Electrical & Electronics
India Automotive Sensors Market
Automotive Electrical & Electronics
Global Automotive Starter and Alternator Market