
 Steering Roll Connector Market | 2026-2036
Steering Roll Connector Market Size, Share, and Industry Trends Forecast 2026-2036
Steering Roll Connector Market Analysis
Integration of active steering feedback systems into electric and steer-by-wire architectures is tilting development priorities toward high-cycle-life contact assemblies. Sumitomo Electric leverages its conductor materials expertise to anchor supply relationships with Japanese OEMs advancing steer-by-wire roadmaps. ZF Friedrichshafen sustains vertical integration from connector design through steering system assembly, competing on module-level validation rather than component sales alone. TE Connectivity dominates the specification process at North American OEMs, extending its influence through early-stage platform engineering partnerships.
A steering roll connector is a rotary electrical interface that maintains continuous signal and power transmission between a fixed vehicle harness and a rotating steering column, typically incorporating gold-plated slip rings, self-cleaning contact blocks, and environmental sealing rated for temperature extremes and vibration loads. Its primary purpose is to preserve uninterrupted connectivity for airbag deployment circuits, steering angle sensors, and multifunction controls throughout full wheel rotation cycles. Active roll connectors command margin pools in the product type dimension as automakers specify real-time torque feedback and lane-keeping assist interfaces. The application landscape tilts toward automotive systems, where steer-by-wire proliferation and advanced driver-assistance integration are expanding unit content per vehicle, while aerospace controls represent a specialized niche with elongated certification horizons and concentrated supplier rosters.
NHTSA Federal Motor Vehicle Safety Standards and ECE R79 type-approval requirements govern steering system integrity and fail-safe performance, compelling connector manufacturers to validate contact resistance stability across millions of rotation cycles. China's GB standards for automotive electrical components, administered by MIIT and SAMR, mandate localized testing protocols that shape market access timelines for foreign suppliers. Stakeholders must monitor the divergence between regional electromagnetic compatibility and functional safety regimes as steer-by-wire adoption accelerates, since connector architectures that satisfy one jurisdiction's validation framework may require fundamental redesign for another.
Market Dynamics
The transition from hydraulic to electric power steering architectures is compressing connector cycle-life requirements while multiplying signal channel counts per vehicle platform.
Growth Catalysts
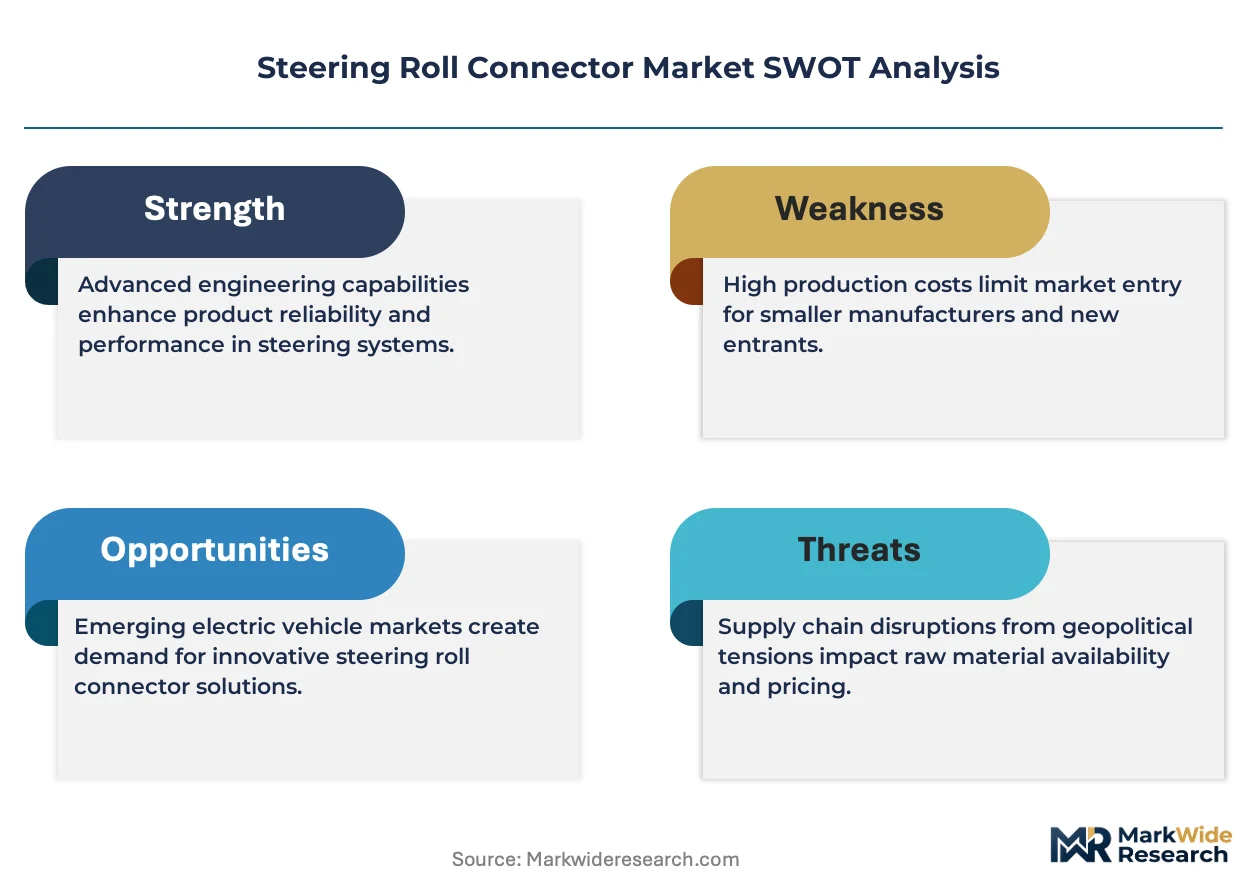
- Steer-by-wire mandates:ECE R79 type-approval pathways for fully electric steering systems are forcing OEM validation of high-rotation-cycle connectors before platform launch.
- China's EV production concentration:Yangtze River Delta automotive clusters are localizing steering system supply chains, creating captive demand for qualified roll connector suppliers.
- Copper alloy material science:High-flex conductor formulations are extending contact life beyond ten million rotation cycles, satisfying NHTSA durability benchmarks for autonomous steering redundancy.
Market Restraints
- Precious metal input volatility:Gold plating thickness specifications for contact surfaces expose manufacturers to commodity price swings in precious metals markets.
- Supplier concentration risk:Japanese conductor material specialists control proprietary high-flex alloy formulations, creating single-source dependencies for Western connector assemblers.
- Steering column integration:Tier-1 system suppliers are internalizing connector design within steering module contracts, compressing standalone component market access.
Strategic Opportunities
- India automotive electrification:PLI scheme incentives for EV component manufacturing are opening qualification pathways for connector suppliers establishing local test facilities.
- Sealed contact geometry patents:Intellectual property around self-cleaning contact block designs is creating licensing revenue streams from second-tier Asian manufacturers.
- ISO 26262 functional safety convergence:ASIL-D certification requirements for steer-by-wire systems are elevating technical barriers that favor established validation-capable suppliers.
Industry Challenges
- Rotation cycle validation capacity:Million-cycle durability testing requires specialized equipment that extends R&D timelines and capital deployment for new product qualification.
- Regional EMC divergence:China's GB standards for electromagnetic compatibility mandate test protocols that differ from ECE R10 frameworks, forcing dual validation tracks for export-bound production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steering Roll Connector Market |
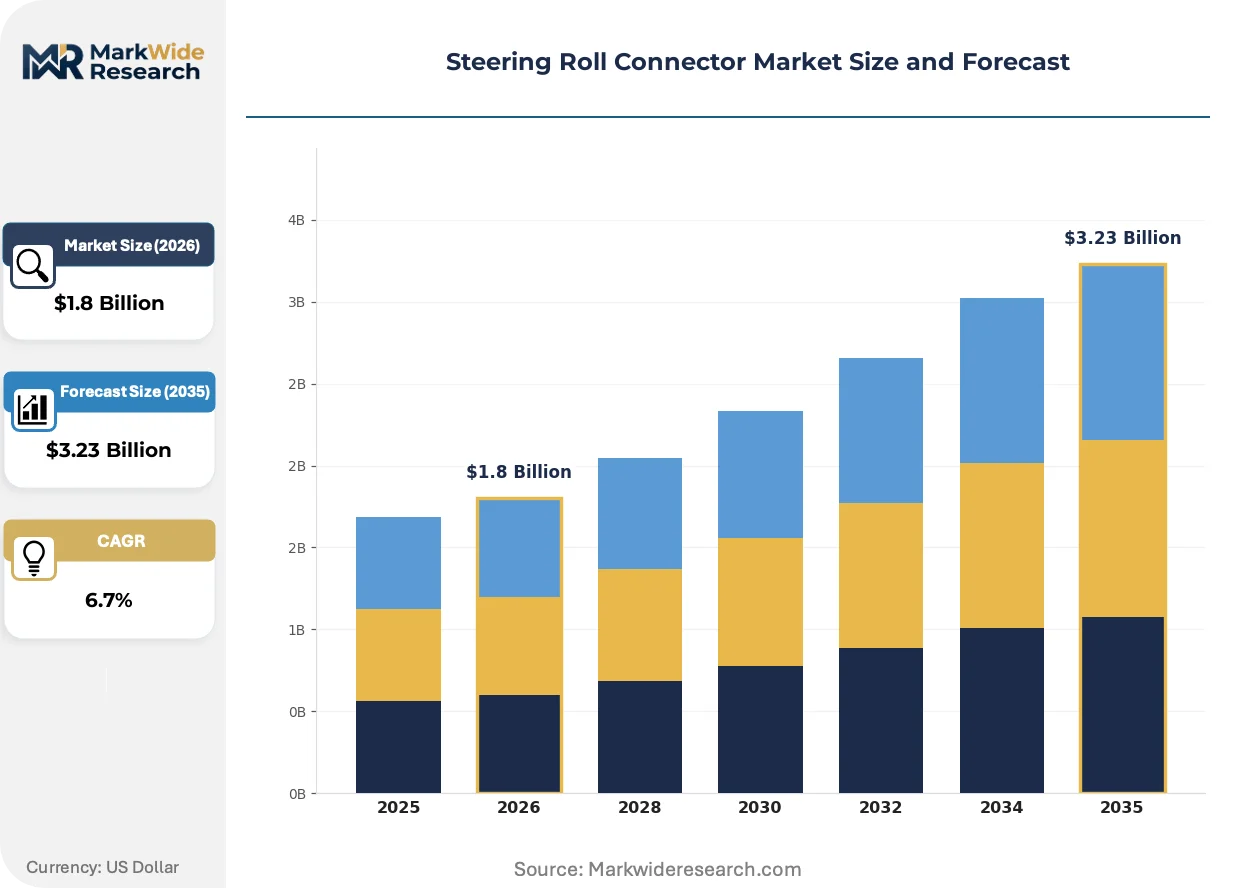
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Roll Connectors, Active Roll Connectors, High-Speed Roll Connectors, Low-Speed Roll Connectors Application: Automotive Systems, Aerospace Controls, Heavy Machinery, Robotics End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Component Manufacturers Installation: Onboard Installations, Standalone Systems, Retrofit Solutions, Integrated Systems |
| Companies Covered | Sumitomo Electric, ZF Friedrichshafen, Furukawa Electric, LEONI, Motherson Group, TE Connectivity, Autoliv, Amphenol Corporation, Yazaki Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steering Roll Connector Market Emerging Trajectories
Contact interface architectures are bifurcating between legacy slip-ring designs and solid-state rotary transformer approaches as steering system electrification accelerates.
Capacitive rotary coupler technology is virtualizing the physical contact interface in next-generation steering columns. German OEMs pursuing steer-by-wire roadmaps are qualifying transformer-based signal transmission for high-bandwidth sensor data. This shift is virtualizing the wear-prone friction surfaces that historically defined roll connector replacement intervals and service-life calculations.
ECE R79 revisions governing steering system fail-safe performance are tightening validation requirements for signal continuity during fault conditions. Connector manufacturers must now demonstrate contact resistance stability across temperature extremes and vibration profiles before platform approval. Asian suppliers are responding by establishing European homologation testing partnerships to accelerate market access timelines.
Fleet procurement of steering systems is consolidating specification authority at platform engineering teams rather than commodity purchasing functions. North American OEMs are embedding connector suppliers into early-stage vehicle architecture definition, displacing late-stage component selection. This concentration is most visible in full-size truck platforms where steering column content per vehicle has tripled with advanced driver-assistance integration.
Steering Roll Connector Market Segmentation
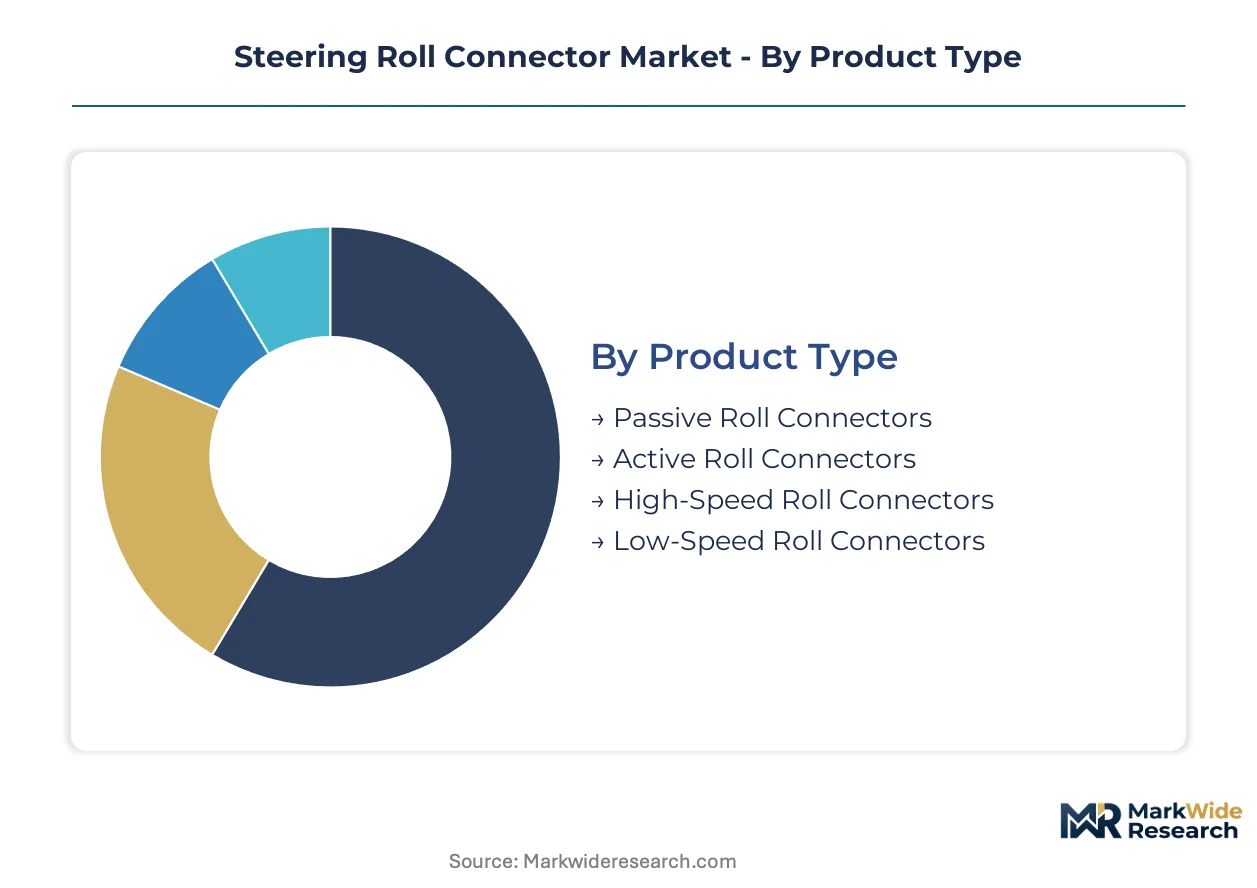
Segmentation in the steering roll connector market reveals how electrification pressures and application-specific durability requirements reshape procurement patterns across automotive, aerospace, and industrial verticals. Understanding these divides clarifies where margin pools concentrate and which technical specifications dominate supplier qualification processes.
Product Type:
Mature passive designs coexist with emerging active architectures as steer-by-wire roadmaps accelerate validation demands for real-time feedback interfaces.
- Passive Roll Connectors:These assemblies transmit power and basic signals through gold-plated slip-ring contacts without integrated feedback circuitry. Demand concentrates in legacy hydraulic steering platforms across India's commercial vehicle sector, where cost sensitivity preserves specification continuity.
- Active Roll Connectors:Torque feedback sensors and lane-keeping assist interfaces are embedded within the rotary contact assembly. German OEMs expanding electric power steering procurement anchor demand for these units, driven by ECE R79 type-approval requirements for fail-safe signal continuity.
- High-Speed Roll Connectors:Optimized for rapid rotation cycles exceeding 10 million operational events in steer-by-wire validation protocols.
- Low-Speed Roll Connectors:Deployed in heavy machinery and material handling equipment where rotation frequency remains below 100,000 cycles annually.
Passive Roll Connectors handle the majority of throughput; Active Roll Connectors are climbing the fastest as steer-by-wire adoption accelerates.
Application:
Volume concentration tilts toward automotive platforms while margin structures favor aerospace certification premiums.
- Automotive Systems:Electric power steering architectures and advanced driver-assistance integration multiply channel counts per vehicle. China's Yangtze River Delta automotive cluster localizes supply chain procurement, compressing qualification timelines for domestic EV programs.
- Aerospace Controls:Elongated certification horizons and MIL-STD environmental requirements define this niche. Concentrated supplier rosters in France and Germany capture value through proprietary sealed contact geometries rated for altitude and temperature extremes.
- Heavy Machinery:Construction and mining equipment specify connectors for hydraulic steering retrofits and joystick control interfaces.
- Robotics:Collaborative robot arms and automated guided vehicles demand compact rotary interfaces for continuous 360-degree joint rotation.
Automotive Systems dominates absolute unit volume; Aerospace Controls commands the steepest premium expansion trajectory.
End User:
Customer type determines specification authority location and contract structure complexity.
- OEMs:Platform engineering teams embed connector requirements into early-stage vehicle architecture definition. North American full-size truck programs triple steering column content through advanced driver-assistance integration, concentrating procurement at vehicle manufacturer technical centers.
- Tier-1 Suppliers:Steering system integrators internalize connector design within module contracts. ZF Friedrichshafen and similar suppliers compete on validation-capable module assembly rather than standalone component sales.
- Aftermarket Providers:Service replacement demand tracks vehicle fleet age and warranty expiration curves.
- Component Manufacturers:Specialized connector assemblers supply subassemblies to Tier-1 system houses under captive sourcing arrangements.
OEMs retain specification authority for new platforms; Tier-1 Suppliers are expanding fastest through module-level integration strategies.
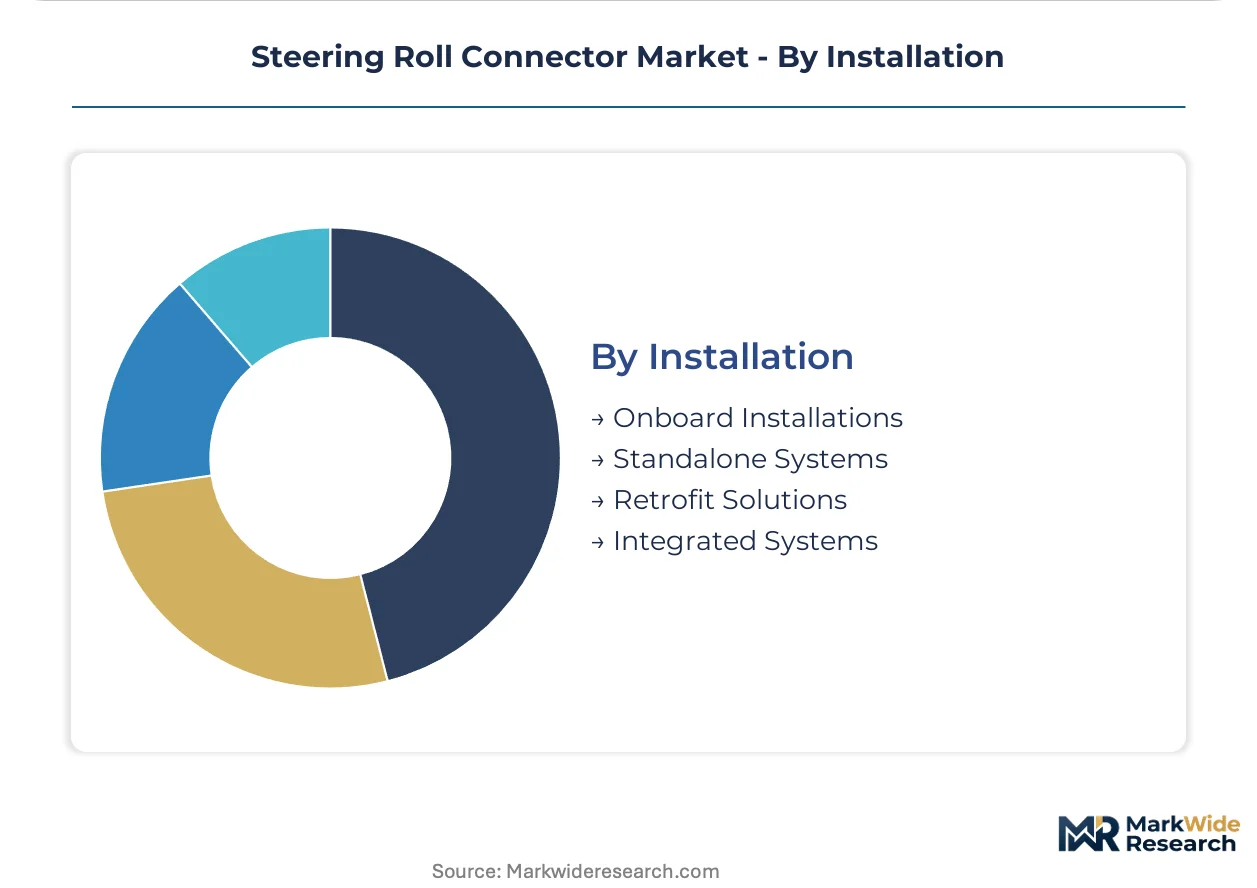
Installation:
Integration depth shapes validation responsibility allocation and field service economics.
- Integrated Systems:Connector assemblies ship pre-validated within steering column modules. Japanese OEMs advancing steer-by-wire roadmaps specify these configurations to compress homologation timelines and consolidate supplier accountability.
- Onboard Installations:Vehicle assembly plants perform connector mating during final trim operations. German automotive manufacturing clusters favor this approach for production flexibility across mixed powertrain platforms.
- Standalone Systems:Discrete connector units for repair and replacement applications.
- Retrofit Solutions:Aftermarket kits for upgrading legacy steering systems with multifunction control capabilities.
Integrated Systems absorb the majority of new vehicle content; Retrofit Solutions are expanding most quickly in aging fleet electrification programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in steering roll connectors tilt toward net importing positions in Western automotive markets, while East Asian manufacturing clusters generate surplus capacity serving regional OEM assembly networks. Trade balances reflect concentrated conductor materials specialization and localized Tier-1 integration strategies.
China
Yangtze River Delta automotive clusters anchor domestic EV program procurement, with Shanghai and Suzhou hosting localized steering system supply chains. MIIT-administered GB standards for automotive electrical components mandate in-country testing protocols that compress foreign supplier market access timelines. Tier-1 suppliers in Jiangsu province are internalizing connector production for captive consumption by domestic OEMs.
Germany
Stuttgart and Munich engineering centers specify active roll connectors for steer-by-wire platform validation, driving procurement from conductor material specialists. KBA oversight of ECE R79 type-approval pathways enforces fail-safe performance benchmarks that shape supplier qualification requirements. Baden-Württemberg's vertical integration from connector design through steering module assembly concentrates specification authority at ZF Friedrichshafen and similar system houses.
United States
Detroit-area full-size truck programs triple steering column content per vehicle through advanced driver-assistance integration, embedding connector requirements into early platform architecture. NHTSA Federal Motor Vehicle Safety Standards govern steering system integrity and contact resistance stability across rotation cycles. Michigan-based Tier-1 suppliers are consolidating module-level contracts that internalize connector sourcing decisions.
Japan
Nagoya and Tokyo OEM technical centers advance steer-by-wire roadmaps with active roll connector specifications for real-time torque feedback interfaces. METI industrial policy supports domestic conductor materials science development, preserving proprietary high-flex alloy formulations. Sumitomo Electric and Furukawa Electric anchor supply relationships through captive materials expertise and early-stage engineering partnerships.
India
Maharashtra and Tamil Nadu automotive corridors are opening qualification pathways for connector suppliers establishing local test facilities under PLI scheme incentives for EV component manufacturing. BIS standards for automotive electrical components create dual-track validation requirements for export-bound versus domestic production. Chennai-based steering system assemblers are expanding procurement from regional connector specialists to satisfy domestic content thresholds.
Steering Roll Connector Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic tiers: integrated system houses with captive connector design, specialized conductor materials firms with proprietary alloy formulations, and component assemblers competing on validation capacity and regional market access. Tier-1 steering system suppliers internalize connector production to compress homologation timelines and consolidate supplier accountability. Dominant competitive moves include backward integration into conductor materials production and strategic partnerships with OEM platform engineering teams for early-stage specification embedding.
Within the integrated system house tier, ZF Friedrichshafen exemplifies module-level validation strategies that displace standalone component sales. Among conductor materials specialists, Sumitomo Electric and Furukawa Electric occupy positions anchored by proprietary high-flex alloy expertise and Japanese OEM supply relationships. TE Connectivity represents the specification-influence archetype at North American OEMs through early-stage platform engineering partnerships.
| Leading Market Players |
|---|
| Sumitomo Electric |
| ZF Friedrichshafen |
| Furukawa Electric |
| LEONI |
| Motherson Group |
| TE Connectivity |
| Autoliv |
| Amphenol Corporation |
| Yazaki Corporation |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's Yangtze River Delta connector fabrication facilities is compressing supplier margins while amplifying price competition for export-bound contracts, forcing Western assemblers to absorb precious metal volatility through inventory hedging rather than pass-through pricing.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with three-tier pricing stratification across ASIL-D certified, standard automotive-grade, and economy aftermarket tiers. Price differentiation hinges on gold plating thickness specifications and ECE R79 validation documentation depth. Cost compression in the economy tier is intensifying because Indian PLI scheme incentives are attracting second-tier Asian manufacturers with lower labor cost bases. Tier-1 steering system integrators exhibit lowest price sensitivity due to consolidated module-level procurement, while independent aftermarket distributors face acute margin pressure from commoditized passive connector imports.
Supply Chain Analysis
Extended payment terms from Japanese OEM technical centers are squeezing working capital for conductor material specialists, who in turn are pushing supply-chain finance facilities onto sub-tier copper alloy processors. Manufacturing concentration rests on Japan, Germany, and China, with proprietary high-flex alloy formulations drawing from Sumitomo Electric and Furukawa Electric captive smelters. Raw material dependencies center on high-purity copper cathodes, gold bullion for contact plating, and specialized polymer compounds for environmental sealing. Single-source vulnerability in Japanese conductor materials creates structural risk for Western connector assemblers lacking backward integration. Distribution runs through Tier-1 steering system suppliers who internalize connector sourcing within module contracts, displacing standalone component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capacitive rotary transformer technology threatens to virtualize the physical contact interfaces that define incumbent roll connector replacement economics, forcing established suppliers to defend their installed base against solid-state substitution architectures.
For Market Incumbents: Entrench proprietary high-flex alloy expertise through captive materials production and early-stage OEM platform engineering partnerships that embed specification authority before steer-by-wire architecture freeze points. Secure ASIL-D certification capacity ahead of ECE R79 revision enforcement to create validation barriers against transformer-based entrants. Deepen backward integration into conductor materials to insulate margin pools from precious metal price volatility and Japanese supplier concentration risk. For New Entrants and Emerging Players: India's Maharashtra and Tamil Nadu automotive corridors offer the most penetrable geographic entry point, where PLI scheme incentives and nascent domestic EV program procurement create qualification windows before incumbent supply relationships solidify. Target aftermarket retrofit solutions for aging commercial vehicle fleets in Southeast Asia, where cost sensitivity preserves specification continuity for passive connector architectures. Establish local test facilities under BIS standards to compress dual-track validation timelines for export-bound versus domestic production. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because module-level integration strategies are compressing standalone component market access and concentrating specification authority at validation-capable system houses. Target acquisition candidates with established European homologation testing partnerships and proprietary sealed contact geometry intellectual property. Monitor ECE R79 revision implementation timelines as the critical inflection signal for steer-by-wire platform validation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductor Materials | Captive copper alloy production insulates margin pools from Japanese supplier concentration and precious metal volatility. |
| ASIL-D Functional Safety Certification Investment | Elevated technical barriers from ISO 26262 requirements favor established validation-capable suppliers over emerging entrants. |
| European Homologation Testing Partnership Establishment | Accelerated ECE R79 market access timelines differentiate qualified suppliers in German steer-by-wire platform procurement. |
| Early-Stage OEM Platform Engineering Embedding | Specification authority concentration at vehicle architecture definition phases displaces late-stage component selection. |
| Local Test Facility Deployment in India | PLI scheme qualification pathways open captive demand from domestic EV programs in Maharashtra and Tamil Nadu corridors. |
Methodological Framework
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 steering system procurement leads, aftermarket distributor operations heads, and conductor materials R&D directors, and refined through secondary validation against vehicle production databases, IHS Markit registration data, customs trade records for copper alloy imports, and NHTSA FMVSS documentation. Bottom-up unit volume estimates across propulsion architectures and content-per-vehicle assumptions were triangulated with top-down market value reconstruction from supplier revenue disclosures and module-level contract values.
Demand-supply balance modeling across the analysis window integrated electric power steering adoption curves, steer-by-wire platform launch timelines, and regional EV production concentration shifts. Segmentation dimensions included product type (passive versus active architectures), vehicle class (passenger versus commercial), propulsion architecture (internal combustion versus battery electric), and regional regulatory cluster (NHTSA, ECE R79, GB standards). CAGRs were derived from fitted adoption curves rather than linear extrapolation, with industry-specific inputs including million-cycle durability testing capacity constraints and precious metal price trajectory assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by conductor material specialists or accelerated solid-state rotary transformer commercialization would shift outcomes beyond modeled ranges. Macroeconomic deviation in automotive production volumes, regulatory divergence in electromagnetic compatibility standards, or technological breakthroughs in contactless signal transmission architectures would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
In-Car Gaming System Market
Automotive Electronics & Wiring
Automotive Smart Key Market
Automotive Electronics & Wiring
Automotive Console Box Market
Automotive Electronics & Wiring
Automotive Head-Up Display (HUD) and Instrument Cluster Market
Automotive Electronics & Wiring
USA Automotive Smart Keys Market
Automotive Electronics & Wiring
Virtual Reality in Automotive Market
Automotive Electronics & Wiring
Automotive Connectivity Market
Automotive Electronics & Wiring
Steer-By-Wire and Brake-By-Wire HMI Controller Systems Market
Automotive Electronics & Wiring
Russia Automotive Reed Sensors Switches Market
Automotive Electronics & Wiring
Automotive Wire Harness Tape Market
Automotive Electronics & Wiring
Automotive Fuse Market
Automotive Electronics & Wiring
UAE Automotive Sensors Market
Automotive Electronics & Wiring
Automotive HMI Market
Automotive Electronics & Wiring
Automotive Connectivity Control Unit Market
Automotive Electronics & Wiring
Automotive Auxiliary Lamps Market
Automotive Electronics & Wiring
Zonal Wiring Harness Platforms for Software-Defined Vehicles Market