
 North America Facade Market | 2026-2036
North America Facade Market Size, Share, and Industry Trends Forecast 2026-2036
North America Facade Market Analytics
The capital-intensity divergence between custom-engineered curtain wall specialists and volume-oriented cladding producers is bifurcating competitive dynamics in the North America facade sector. Enclos Corp. leverages its vertical integration into specialized glazing and structural silicone systems to command premium positions on signature commercial towers. Kingspan Group anchors its position through controlled manufacturing scale across insulated panel architectures serving industrial and cold-chain end users. ROCKWOOL International A/S differentiates via mineral wool core technology leadership that addresses stringent fire-resistance specifications in high-rise construction.
A facade constitutes the external envelope system of a building, integrating structural support, weatherproofing, thermal insulation, and aesthetic functions through assemblies of aluminum framing, glass lites, composite panels, or masonry units with engineered cavity drainage and pressure-equalized seals. Its primary commercial purpose is to mediate between interior conditioned environments and exterior climatic loads while enabling daylight harvesting and occupant comfort. Curtain wall systems dominate value capture in commercial high-rise applications where unitized fabrication and field-installation speed concentrate margins. Ventilated facade technology represents the fastest-growing segment as rainscreen configurations with continuous exterior insulation address escalating thermal bridging restrictions. Aluminum product types retain volume leadership though composite panels are displacing traditional materials in renovation applications where reduced dead load and simplified attachment matter.
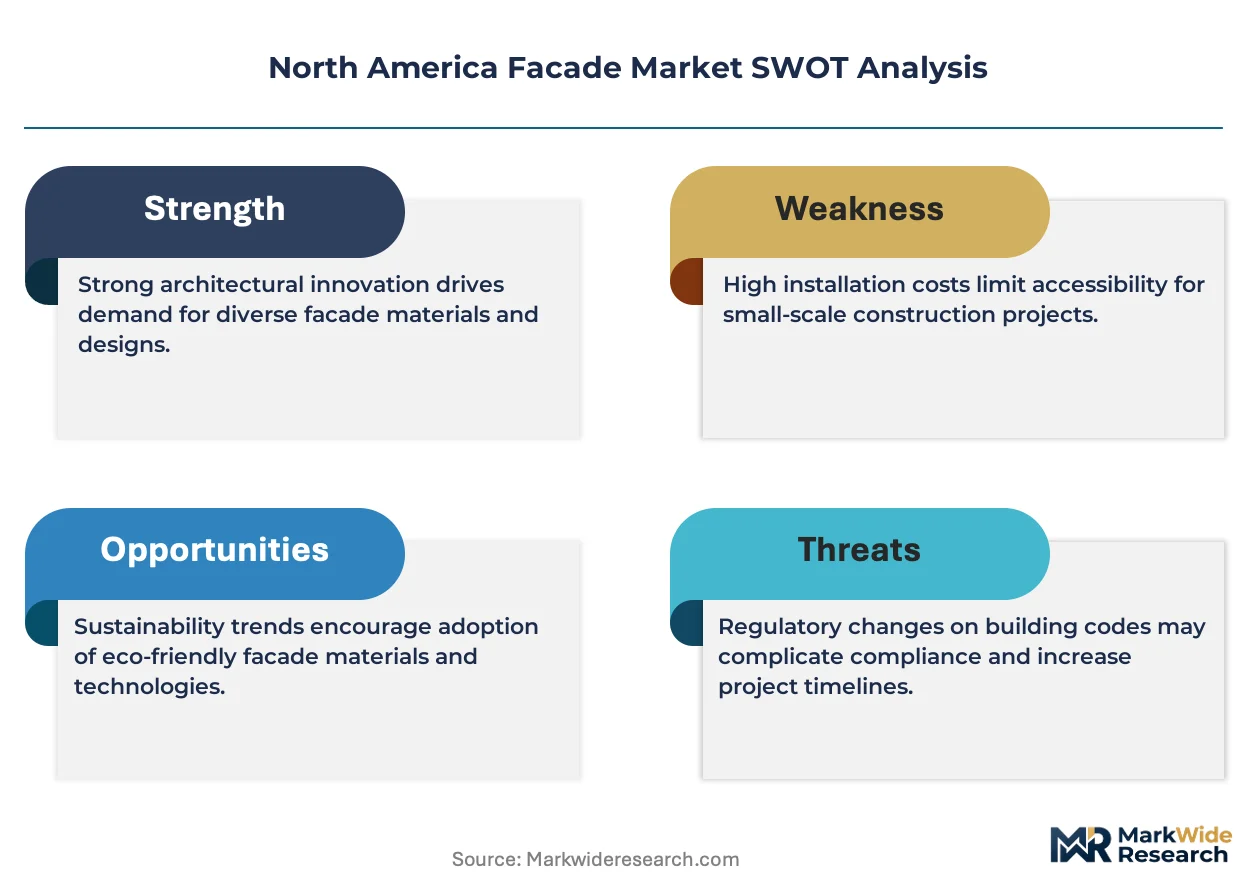
The U.S. Department of Energy building energy codes, ASHRAE Standard 90.1, and California Title 24 collectively shape product specifications by mandating continuous insulation and air-barrier performance that obsolete legacy facade assemblies. OSHA fall-protection standards and provincial codes across Canadian provinces further constrain installation methodologies and contractor qualification requirements. Stakeholders must monitor evolving electrification of heating systems and embodied-carbon disclosure rules that will reweight material selection criteria and supplier qualification frameworks.
Market Dynamics
The U.S. Department of Energy's escalating thermal performance mandates are compressing replacement cycles across legacy commercial building stock, forcing asset owners to treat facade upgrades as energy compliance instruments rather than discretionary capital projects.
Growth Catalysts
- California Title 24 net-zero mandates:The state's building energy standards are accelerating facade retrofit timelines in commercial properties across Los Angeles and San Francisco metropolitan clusters.
- Ventilated rainscreen technology:Continuous exterior insulation configurations are capturing specification share as thermal bridging restrictions tighten across Pacific Northwest jurisdictions.
- Electrification of heating systems:Building owners in New York and Massachusetts are upgrading envelope performance to reduce heat pump operating loads and peak demand charges.
Market Restraints
- Aluminum price volatility:Primary metal input costs swing with LME trading patterns, compressing fabrication margins for curtain wall specialists serving speculative office development.
- Canadian provincial code fragmentation:Ontario, British Columbia, and Quebec maintain divergent fall-protection and energy efficiency standards that complicate cross-border contractor qualification.
- Structural silicone supply concentration:Specialty glazing adhesion chemistry relies on limited domestic formulation capacity, creating procurement bottlenecks for unitized system fabricators.
Strategic Opportunities
- Industrial cold-chain expansion:Insulated metal panel demand is accelerating across Texas and Arizona distribution center construction where thermal performance directly reduces refrigeration energy intensity.
- Embodied-carbon disclosure rules:Emerging Environmental Product Declaration requirements in California and Washington are creating first-mover advantage for mineral wool and recycled aluminum suppliers.
- Utility demand-response integration:Smart facade systems with dynamic glazing and automated shading are qualifying for grid-interactive building incentives in Colorado and Illinois utility territories.
Industry Challenges
- Glazing installation craft shortage:OSHA-compliant fall-protection certification requirements are constraining qualified labor pools in high-rise construction markets including Chicago and Toronto.
- Air-barrier commissioning complexity:Whole-building pressure testing protocols under ASHRAE Standard 90.1 are extending project closeout timelines and creating warranty exposure for envelope contractors.
- Legacy masonry facade assessment:Condition evaluation of pre-1980 cavity wall systems requires specialized diagnostic expertise that remains scarce in secondary Midwest and Southeast markets.
Report Scope
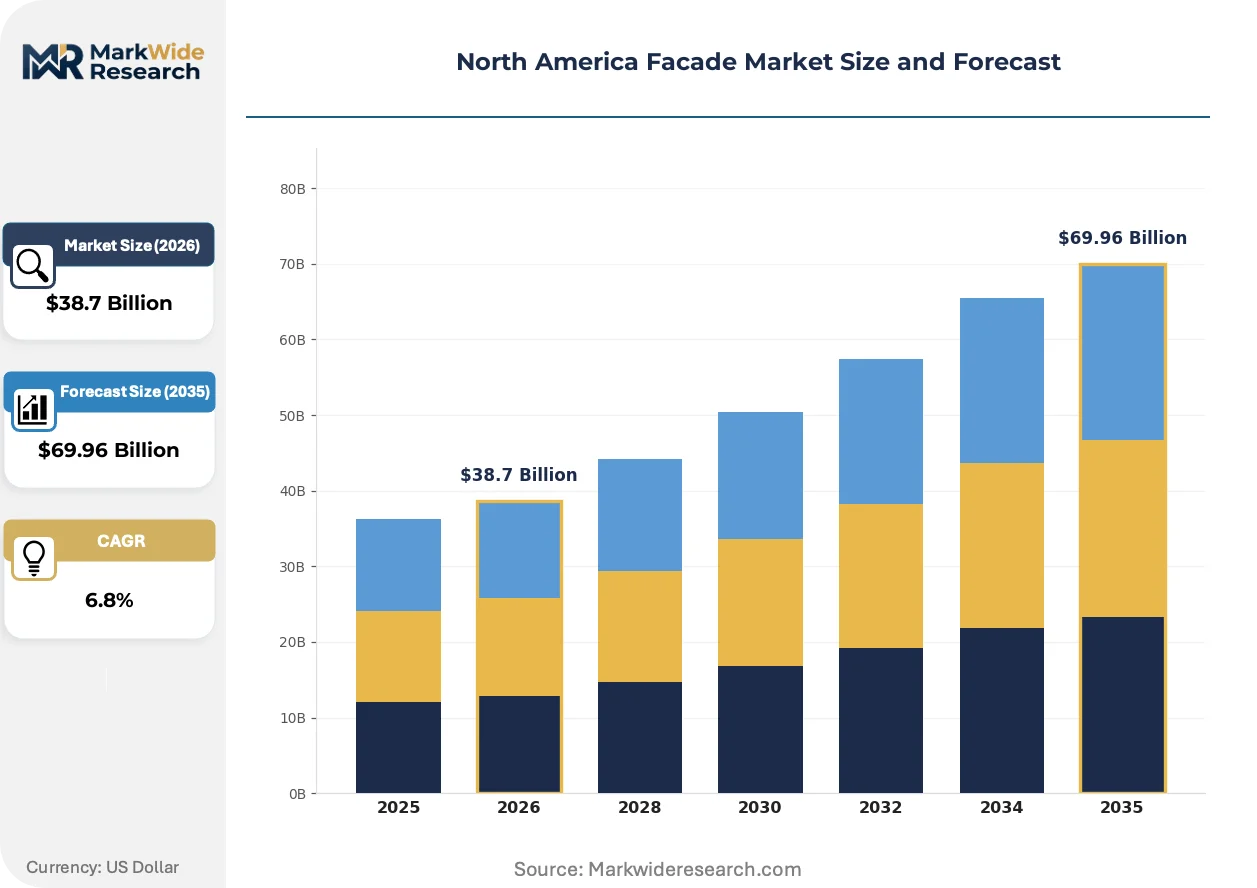
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Facade Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Glass, Composite, Brick End User: Commercial Buildings, Residential Properties, Industrial Facilities, Institutional Structures Installation Type: New Construction, Renovation, Retrofitting, Maintenance Technology: Ventilated Facades, Curtain Wall Systems, Integrated Facade Systems, Energy-Efficient Designs |
| Companies Covered | Enclos Corp., Permasteelisa S.p.A, Apogee Enterprises, Inc, Benson Curtain Wall & Glass (MiTek Industries Inc), Seele verwaltungs GmbH, Kingspan Group, Lindner Group, ROCKWOOL International A/S, Ramboll Group A/S, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Facade Market Evolving Landscape
Active materials research and digital fabrication methods are compressing the traditional separation between structural performance and aesthetic customization in envelope specification. These developments are reshaping how architects, contractors, and building owners evaluate system trade-offs.
Photovoltaic-integrated glazing is fragmenting the conventional division between power generation and weather protection functions. Commercial developers in California and Arizona are specifying building-integrated PV curtain wall units to meet on-site renewable mandates. This convergence is compressing the addressable market for standalone rooftop solar installations on mid-rise commercial structures.
ASHRAE Standard 90.1-2022 appendices are mandating continuous insulation and air-barrier performance verification through thermal imaging and blower-door testing. The industrial consequence is disqualification of traditional cavity wall assemblies without exterior insulation layers. High-rise residential towers in Vancouver and Seattle are responding with ventilated rainscreen configurations that satisfy both energy code and seismic drift requirements.
Building owners are consolidating envelope specification authority within dedicated asset management teams rather than delegating to general contractors. This centralization is displacing traditional design-bid-build procurement in favor of design-assist and performance-based contracting models. The shift is most visible in institutional portfolios across university and healthcare systems in the Northeast and Pacific Northwest.
North America Facade Market Segmentation
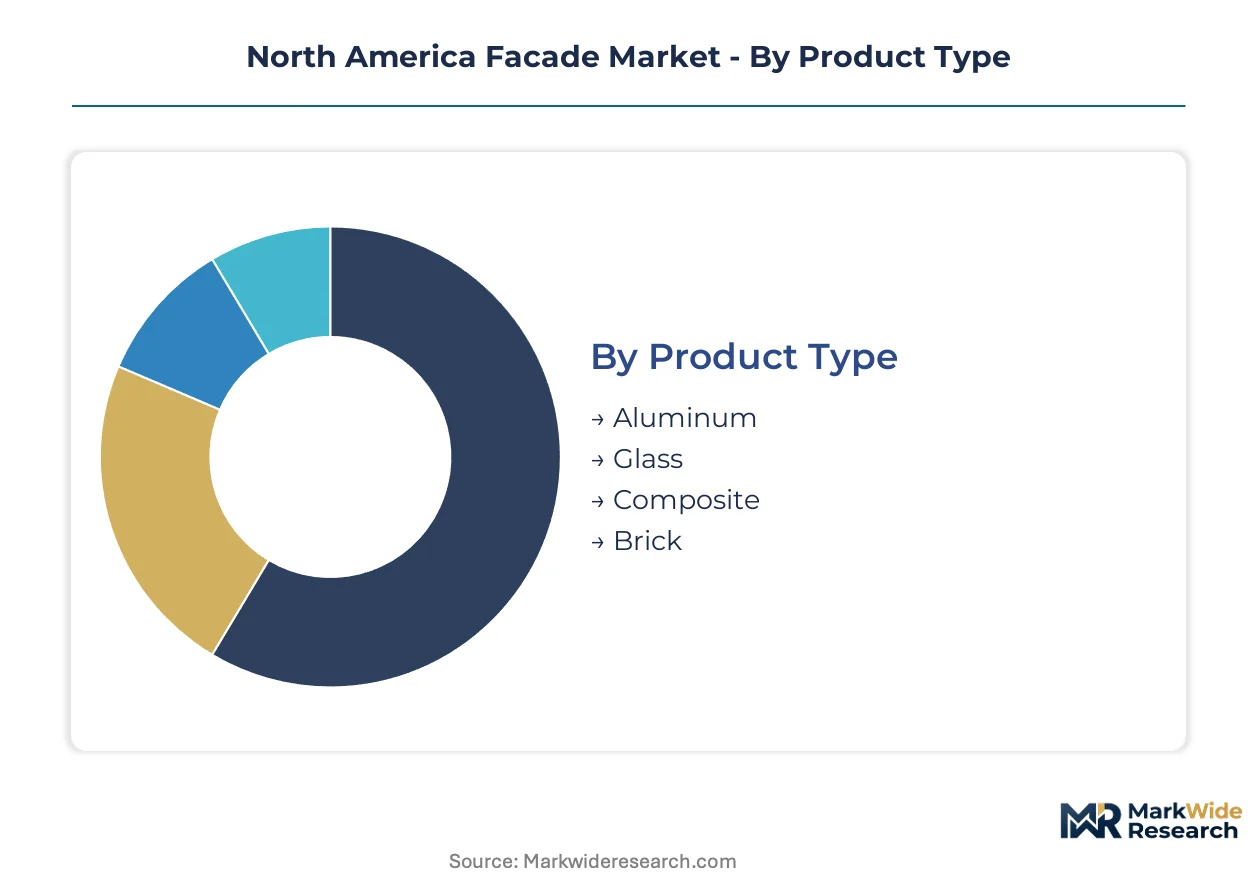
Facade specification patterns across North America diverge sharply by building typology and regulatory pressure, with product selection driven by thermal code compliance timelines rather than aesthetic preference alone. Understanding segment boundaries reveals where capital deployment concentrates and which technology transitions are accelerating.
Product Type:
Domestic fabrication capacity dominates aluminum and glass processing, while composite panel supply relies partly on cross-border manufacturing integration with Canadian producers.
- Aluminum:Extruded and formed into mullions, transoms, and panel skins with anodized or fluoropolymer finishes. Demand concentrates in speculative office towers across Texas and Florida where unitized curtain wall fabrication speed compresses construction schedules.
- Glass:Low-iron, low-e coated, and laminated safety lites specified in thicknesses from 6mm to 25mm. California and Pacific Northwest commercial retrofits are driving specification of triple-glazed units as Title 24 and Stretch Code thermal requirements tighten.
- Composite:Aluminum-faced panels with polyethylene or mineral core, valued for reduced dead load in renovation applications.
- Brick:Traditional masonry with engineered cavity drainage, retaining specification in institutional and heritage-sensitive projects.
Aluminum holds the largest share; momentum sits with composite as renovation volumes climb.
End User:
Cost tier stratification separates signature commercial towers with performance-based procurement from volume-driven residential and industrial segments.
- Commercial Buildings:High-rise offices, mixed-use developments, and retail complexes specifying unitized curtain wall and ventilated rainscreen systems. Class-A assets in Manhattan, Chicago, and downtown Toronto are treating facade upgrades as energy compliance instruments under ASHRAE 90.1-2022.
- Residential Properties:Mid-rise and high-rise multifamily structures employing window wall and precast panel systems. Seattle and Vancouver towers are adopting continuous insulation configurations to satisfy seismic drift and thermal bridging restrictions simultaneously.
- Industrial Facilities:Warehouses, distribution centers, and cold-chain infrastructure specifying insulated metal panels.
- Institutional Structures:University, healthcare, and government buildings with extended asset horizons and dedicated envelope management teams.
Commercial Buildings command the dominant revenue position; Industrial Facilities are expanding most quickly on cold-chain construction.
Installation Type:
Volume distribution tilts toward renovation and retrofitting as energy code compliance deadlines compress replacement cycles across legacy building stock.
- New Construction:Ground-up development with integrated design-assist procurement and performance-based specifications. Sun Belt metropolitan clusters including Phoenix, Dallas, and Atlanta are driving new installation volumes on speculative office and residential tower completions.
- Renovation:Partial facade replacement addressing envelope failure or aesthetic obsolescence. Boston and Philadelphia commercial assets are executing phased curtain wall replacements to maintain occupancy during construction.
- Retrofitting:Over-cladding and rainscreen additions to improve thermal performance without full demolition.
- Maintenance:Sealant replacement, glazing repair, and pressure-equalized drainage restoration.
New Construction retains volume leadership; Retrofitting shows the steepest expansion trajectory on code-driven thermal upgrades.
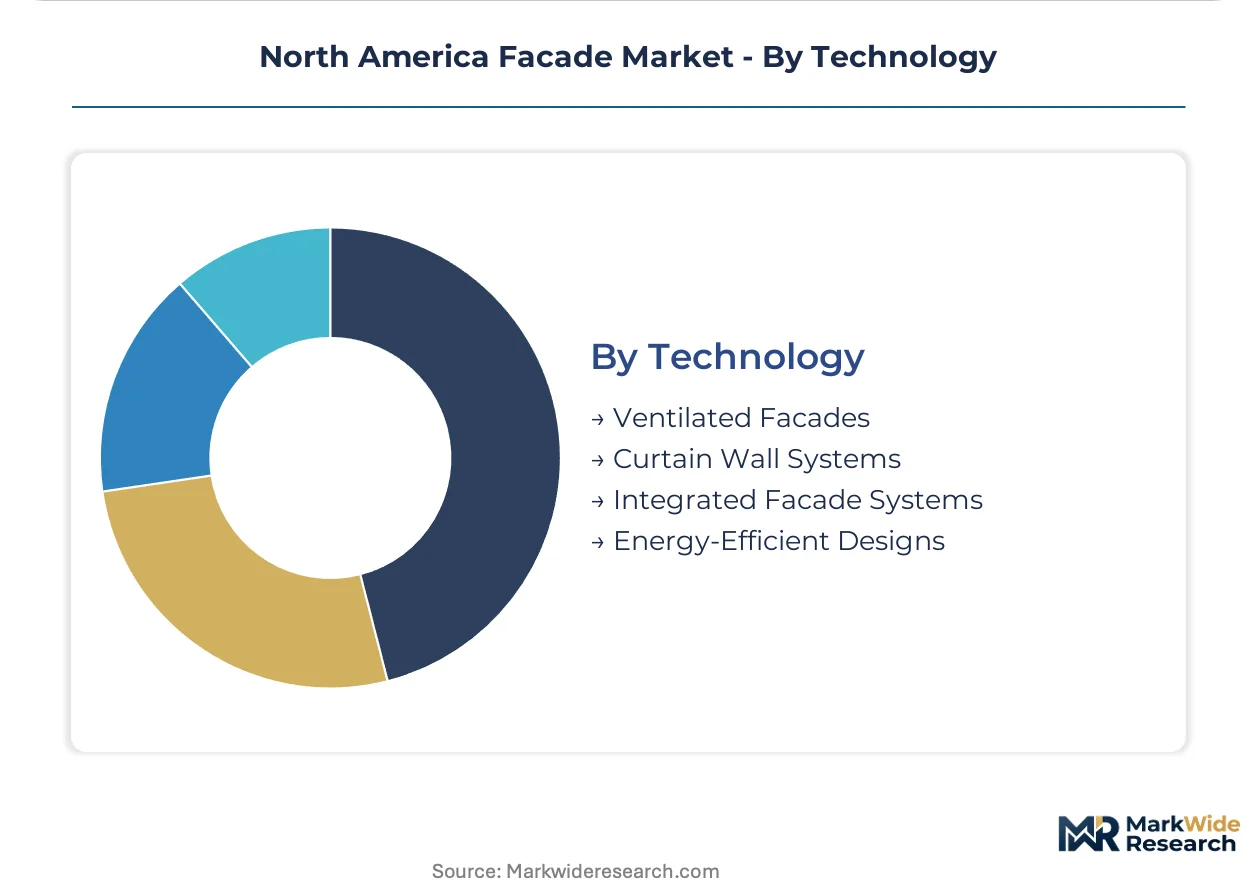
Technology:
Customer type differentiation separates architect-led specification of integrated systems from contractor-driven procurement of standardized curtain wall units.
- Ventilated Facades:Rainscreen configurations with continuous exterior insulation, pressure-equalized cavities, and drained backing walls. Pacific Northwest jurisdictions including Oregon and British Columbia are mandating these assemblies to eliminate thermal bridging in high-rise residential construction.
- Curtain Wall Systems:Unitized or stick-built aluminum framing with infill glazing and opaque panels. Chicago and Toronto high-rise markets remain concentrated demand centers despite labor certification constraints.
- Integrated Facade Systems:Pre-engineered assemblies combining structure, insulation, and weatherproofing in factory-controlled conditions.
- Energy-Efficient Designs:Dynamic glazing, automated shading, and building-integrated photovoltaics.
Curtain Wall Systems anchor current revenue; Ventilated Facades are gaining share fastest on regulatory thermal mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in facade specification concentrates in California and Pacific Northwest metros, while cost-competitive fabrication clusters dominate Texas and Southeast markets. This asymmetry shapes procurement patterns across the continent.
United States
California Title 24 net-zero mandates and ASHRAE 90.1-2022 thermal requirements are accelerating facade retrofit cycles in Los Angeles and San Francisco commercial corridors. The U.S. Department of Energy's building energy codes are tightening continuously, forcing asset owners to treat envelope upgrades as compliance instruments. New York and Boston institutional portfolios are consolidating specification authority within dedicated asset management teams.
Canada
Ontario, British Columbia, and Quebec maintain divergent fall-protection and energy efficiency standards that complicate cross-border contractor qualification. Vancouver high-rise residential towers are adopting ventilated rainscreen configurations to satisfy both seismic drift requirements and thermal bridging restrictions. Health Canada and provincial regulators are aligning embodied-carbon disclosure frameworks with emerging Environmental Product Declaration requirements.
Mexico
Industrial cold-chain expansion across Nuevo León and Jalisco is driving insulated metal panel demand for distribution center construction. Mexico City commercial development is specifying unitized curtain wall systems for speculative office towers. The country's national building code authorities are gradually adopting thermal performance standards that mirror U.S. ASHRAE benchmarks for cross-border project consistency.
Pacific Northwest
Oregon and Washington jurisdictions are mandating ventilated facade assemblies to eliminate thermal bridging in high-rise residential construction. Seattle and Portland metropolitan clusters are experiencing accelerated replacement cycles as net-zero building mandates compress project timelines. Utility demand-response integration incentives in Colorado and Illinois utility territories are qualifying smart facade systems with dynamic glazing.
Southeast United States
Florida and Georgia speculative office and residential tower completions are driving new installation volumes with compressed construction schedules. Atlanta and Miami commercial developers are specifying aluminum curtain wall systems where fabrication speed dominates procurement criteria. OSHA fall-protection certification requirements are constraining qualified labor pools in high-rise construction markets.
North America Facade Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America facade sector. Custom-engineered curtain wall specialists command premium positions on signature commercial towers through specialized glazing and structural silicone capabilities. Volume-oriented cladding producers anchor industrial and cold-chain segments through controlled manufacturing scale. The competitive landscape exhibits tiered consolidation with strategic moves centering on design-assist procurement partnerships and backward integration into core material supply.
Among European-origin fabricators with North American operations, Enclos Corp., Permasteelisa S.p.A, and Seele verwaltungs GmbH exemplify the technology-led archetype serving high-performance commercial envelope specifications. Kingspan Group and ROCKWOOL International A/S represent scale-driven specialists with captive manufacturing positions in insulated panel and mineral wool core technologies respectively. These five entities occupy distinct competitive positions without overlapping segment focus, reducing direct confrontation while maintaining pricing discipline within their respective tiers.
| Leading Market Players |
|---|
| Enclos Corp. |
| Permasteelisa S.p.A |
| Apogee Enterprises, Inc |
| Benson Curtain Wall & Glass (MiTek Industries Inc) |
| Seele verwaltungs GmbH |
| Kingspan Group |
| Lindner Group |
| ROCKWOOL International A/S |
| Ramboll Group A/S |
| Others |
Value Network & Pricing Analysis
Sixteen-week structural silicone lead times from domestic formulators concentrate pricing power among unitized curtain wall specialists serving California and Pacific Northwest commercial towers, while spot aluminum pricing on the LME compresses margins for volume-oriented fabricators in Texas and Florida speculative development markets.
Pricing Analysis
Configured-to-order premium spreads of 35-50 percent over standard insulated metal panel pricing separate signature commercial tower procurement from industrial cold-chain volume contracts. Project-based pricing dominates high-performance envelope specifications where thermal bridging compliance and seismic drift engineering drive customization intensity. Price differentiation hinges on OSHA fall-protection certification tier and in-house glazing formulation capability. Cost compression in standard aluminum curtain wall tiers intensifies as speculative office development slows in Sun Belt metros. Industrial facility buyers exhibit highest price sensitivity; institutional asset managers with dedicated envelope teams show lowest.
Supply Chain Analysis
Strait of Hormuz transit exposure for float glass raw materials concentrates supply risk assessment among Pacific Northwest and California project developers. Primary aluminum smelting in Canada, Mexico, and the United States feeds North American extrusion capacity with tariff-adjusted cost structures. Structural silicone chemistry and low-iron glass substrates draw from limited domestic formulation and melting capacity. Single-source vulnerability in specialty glazing adhesion creates procurement bottlenecks for unitized system fabricators. Distribution runs through design-assist procurement partnerships that displace traditional design-bid-build channels in institutional and Class-A commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified glazing installation labor capable of OSHA-compliant high-rise work remains scarce across Chicago, Toronto, and Seattle markets, constraining envelope contractor expansion and consolidating project execution authority among incumbent specialists with captive certification pipelines.
For Market Incumbents: Shield premium positioning by deepening backward integration into structural silicone formulation and specialized glazing supply. Expand design-assist procurement partnerships with institutional asset managers in Northeast and Pacific Northwest healthcare and university systems. Counter aluminum price volatility through long-term offtake agreements with Canadian smelters. Prioritize OSHA fall-protection certification pipeline investment to defend against emerging regional contractors. For New Entrants and Emerging Players: Lead with industrial cold-chain insulated metal panel specifications in Texas and Arizona distribution center construction where thermal performance requirements are codified but engineering complexity remains moderate. Target secondary Midwest and Southeast markets where legacy masonry facade assessment expertise is scarce and energy code compliance deadlines create retrofit urgency. Pursue utility demand-response integration partnerships in Colorado and Illinois territories to differentiate smart facade offerings. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified building materials conglomerates with underoptimized facade divisions lacking design-assist capabilities or Pacific Northwest regulatory expertise. Long-term viability favors specialists with captive mineral wool or recycled aluminum supply positions as California and Washington embodied-carbon disclosure frameworks mature. Monitor ASHRAE Standard 90.1 adoption velocity across Canadian provinces as inflection indicator for cross-border consolidation opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Structural Silicone | Captive formulation capacity insulates margin from supply bottlenecks affecting unitized system competitors. |
| Design-Assist Procurement Partnership | Direct relationships with institutional asset managers in Boston and Seattle displace traditional general contractor channels. |
| OSHA Certification Pipeline Investment | Qualified high-rise glazing labor scarcity in Chicago and Toronto creates defensive moat against regional entrants. |
| Utility Demand-Response Integration | Smart facade qualification for Colorado and Illinois grid-interactive incentives opens premium specification tier. |
| Embodied-Carbon Disclosure Compliance | Environmental Product Declaration positioning in California and Washington creates first-mover specification advantage. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of U.S. Department of Energy building code filings, ASHRAE Standard 90.1 technical appendices, California Title 24 compliance documentation, and provincial energy efficiency regulations across Ontario, British Columbia, and Quebec. Primary interviews engaged facade contractors, envelope engineering consultants, commercial asset managers, glazing installation specialists, and insulated metal panel procurement leads at cold-chain developers. Secondary validation drew from OSHA fall-protection certification records, LME aluminum price series, and Environmental Product Declaration databases. Bottom-up project pipeline assessment triangulated against top-down construction spending forecasts across commercial, residential, and industrial building typologies.
Segmentation dimensions modeled include product type, end user category, installation type, and technology configuration across the projection horizon. The analytical framework incorporates thermal code compliance timelines, electrification of heating system adoption curves, and net-zero building mandate implementation schedules. CAGRs derive from replacement cycle compression analysis and new construction volume projections by metropolitan cluster. Industry-specific forecast inputs include structural silicone supply capacity utilization and qualified glazing installation labor availability by OSHA certification tier.
The analysis sits within stated boundaries; outcomes outside sustained regulatory tightening on thermal bridging and embodied-carbon disclosure would require recalibration. Forecasts reflect assumptions regarding aluminum price volatility moderation and cross-border contractor qualification harmonization between U.S. and Canadian jurisdictions. Practitioners should keep alternative scenarios live as ASHRAE Standard 90.1 adoption velocity and utility incentive program continuity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Philippines Roofing Market
Structural Engineering
Civil Engineering Market
Structural Engineering
Concrete Wind Tower Market
Structural Engineering
Self-Healing Concrete Market
Structural Engineering
Americas Structural Insulated Panel Market
Structural Engineering
Fabricated Structural Steel Market
Structural Engineering
Asia-Pacific Structural Health Monitoring Market
Structural Engineering
Self-Compacting Concrete Market
Structural Engineering
North America Anchors and Grouts Market
Structural Engineering
Offshore Structural Analysis Software Market
Structural Engineering
Steel Structure Anchor Bolt Market
Structural Engineering
Bridge Bearing Pad Market
Structural Engineering
Fluid Viscous Dampers Market
Structural Engineering
Southeast Asia Anchors and Grouts Market
Structural Engineering
Europe Bridge Bearings Market
Structural Engineering
High Strength Concrete Market