
 Automotive Wheel Cap Market | 2026-2036
Automotive Wheel Cap Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Wheel Cap Market Analysis
Software-defined customization services for wheel caps is decoupling hardware sales from static SKU models, enabling automakers to offer downloadable badge geometries and seasonal color profiles. CIE AUTOMOTIVE S.A. leverages captive forging capacity across Iberian plants to anchor alloy cap supply for European OEM platforms. Zanini Auto Grup SA sustains dominant share in snap-on plastic assemblies through vertical control over injection molding lines. Lacks Enterprises, Inc differentiates via chroming expertise that commands premium positioning with Detroit-based vehicle assemblers.
An automotive wheel cap is a protective and decorative closure component fitted over the central hub of a vehicle wheel, typically manufactured from stamped steel, cast aluminum alloy, or injection-molded ABS polymer with diameters ranging from 50mm to 75mm to conceal lug nuts and bearing assemblies while enhancing aerodynamic efficiency. Alloy caps dominate value pools due to their strength-to-weight ratio and compatibility with premium wheel architectures, whereas carbon fiber variants occupy niche performance segments where rotational mass reduction justifies material cost premiums. OEMs constitute the most concentrated demand channel, with vehicle assemblers specifying caps at platform design stage and locking suppliers into multi-year tooling contracts.
NHTSA wheel retention standards and EPA corporate average fuel economy benchmarks jointly shape material selection and fastener geometry decisions for suppliers selling into the United States market. ECE R124 regulations in Europe mandate retention force testing that favors screw-on and plug-in installation types over snap-on alternatives for highway-speed applications. China MIIT publishes GB standards covering plastic component flammability that constrain raw material sourcing for wheel caps destined for domestic vehicle assembly. Stakeholders must monitor divergence between regional fastener mandates and lightweighting targets when allocating R&D budgets across product architectures.
Market Dynamics
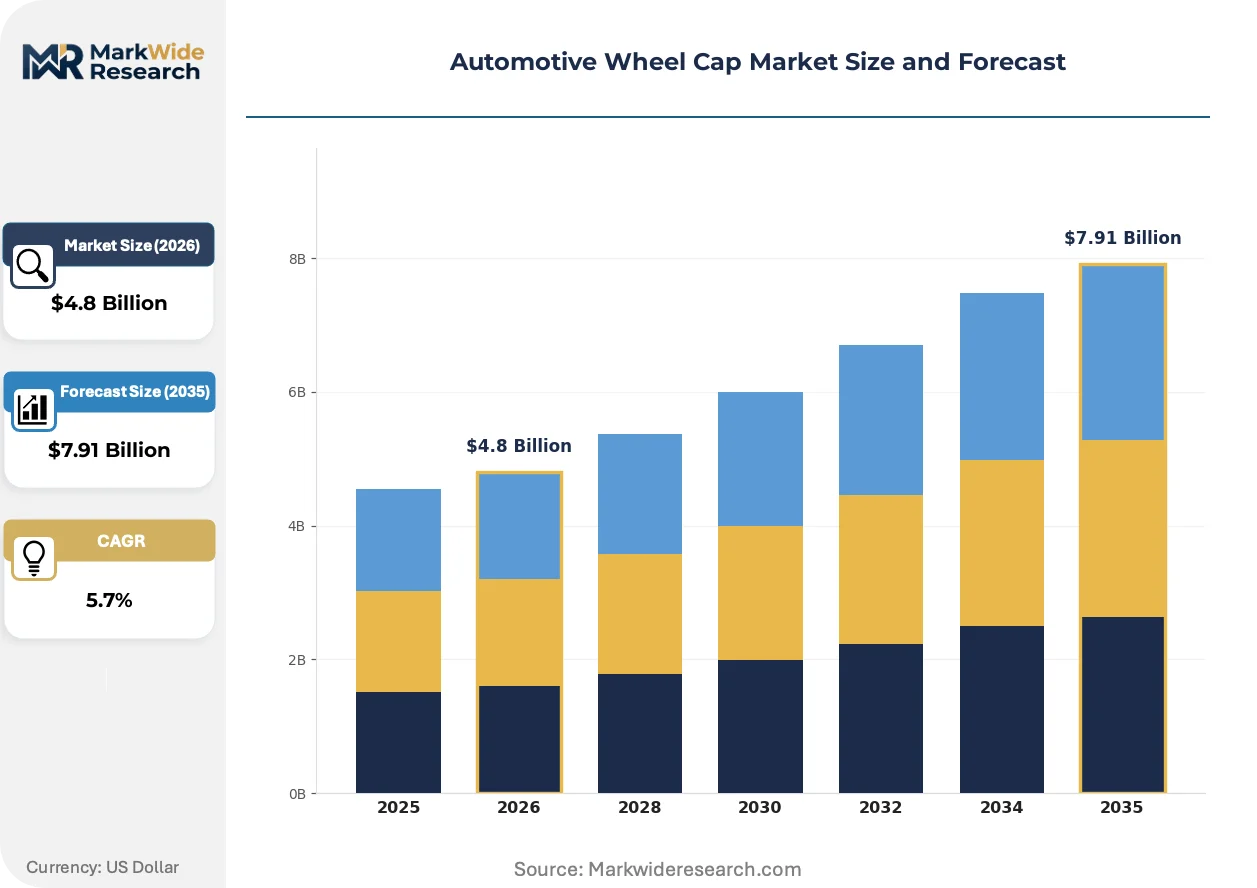
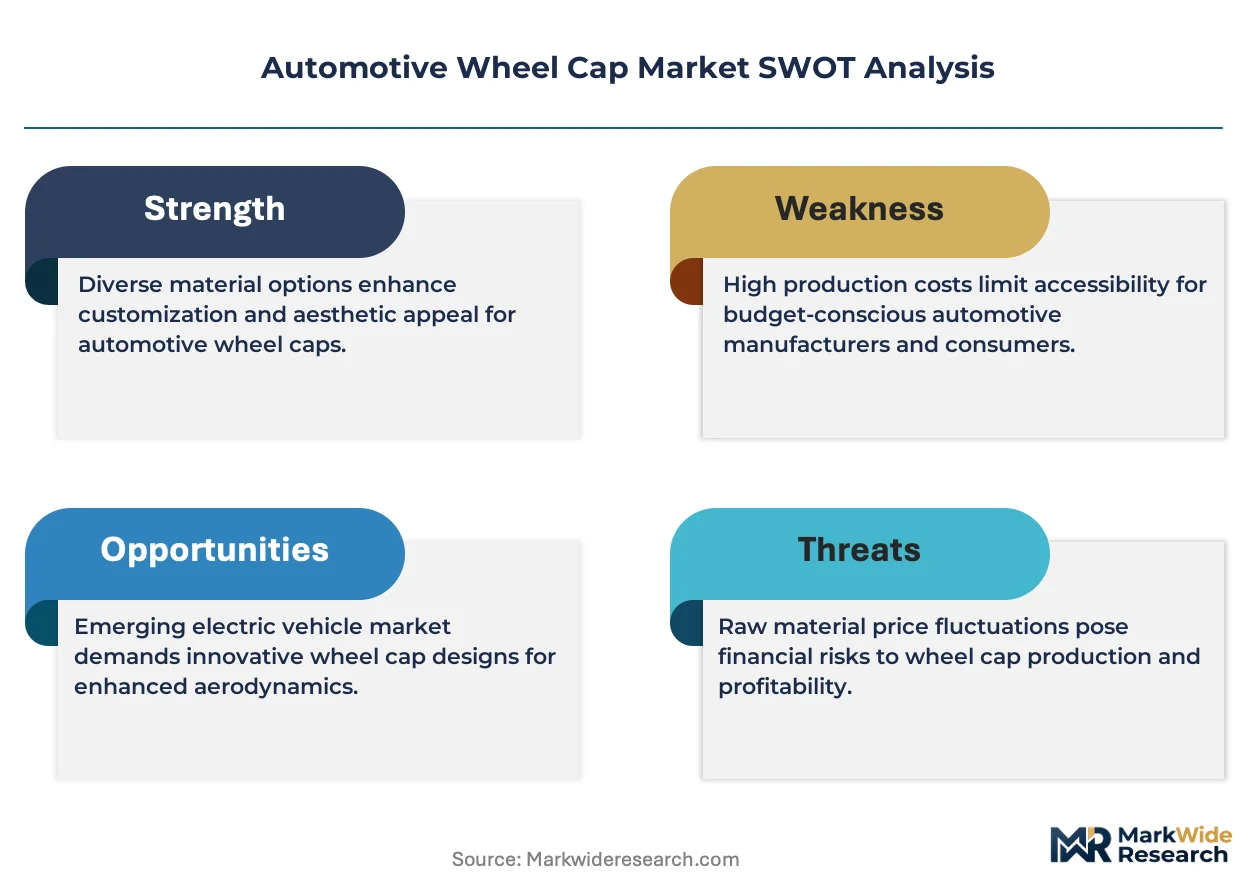
OEM platform standardization is compressing supplier margins while software-defined customization creates parallel revenue streams through downloadable geometries and seasonal color profiles. The tension between lightweighting mandates and retention-force regulations is forcing material selection trade-offs across every major supply contract.
Growth Catalysts
- EPA CAFE benchmarks:Corporate average fuel economy standards in the United States are accelerating alloy cap adoption as automakers pursue gram-level weight reductions across wheel assemblies.
- CIE AUTOMOTIVE S.A.'s Iberian forging network:Captive alloy production capacity anchors supply security for European OEM platforms facing just-in-sequence delivery requirements.
- ABS polymer flammability protocols:China MIIT GB standards are tightening raw material specifications, favoring suppliers with certified compound formulations and laboratory testing partnerships.
Market Restraints
- Aluminum ingot price volatility:Alloy cap margins compress when London Metal Exchange aluminum futures spike, exposing mid-tier suppliers without long-term smelter contracts.
- ECE R124 retention testing:European highway-speed mandates favor screw-on and plug-in fastener geometries, structurally disadvantaging snap-on plastic assembly specialists.
- Carbon fiber substitution ceiling:Rotational mass benefits fail to justify material cost premiums beyond niche motorsport and ultra-premium vehicle segments.
Strategic Opportunities
- Software-defined badge geometries:Over-the-air customization services decouple hardware from static SKUs, enabling recurring revenue through downloadable seasonal profiles.
- Indian domestic assembly growth:Local vehicle production expansion creates demand for wheel cap suppliers establishing captive molding or forging operations near Chennai and Pune clusters.
- NHTSA safety standard harmonization:Convergence between United States and Canadian wheel retention protocols reduces certification duplication costs for cross-border suppliers.
Industry Challenges
- Multi-year tooling contract lock-in:OEM platform commitments freeze design flexibility, delaying supplier response to fast-evolving aesthetic preferences and material innovations.
- Chroming process wastewater compliance:Hexavalent chromium restrictions in Germany and California require capital-intensive effluent treatment system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Wheel Cap Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Caps, Alloy Caps, Plastic Caps, Carbon Fiber Caps End User: OEMs, Aftermarket Retailers, Tire Shops, Vehicle Assemblers Installation Type: Snap-On, Screw-On, Push Fit, Plug-In Feature: Custom Designs, Reflective Elements, Weather Resistance, Lightweight |
| Companies Covered | CIE AUTOMOTIVE S.A., Zanini Auto Grup SA, Versaco s.r.o., Swell Marui Automobile Parts Co., LTD, Auto Pearl Automotives, Lacks Enterprises, Inc, Wheel Pros LLC, Prigan India Private Limited, Prim X Auto Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Wheel Cap Market Emerging Trajectories
Digital manufacturing workflows and regulatory material bans are converging to reshape how wheel caps are designed, produced, and certified across automotive supply chains.
Additive manufacturing for prototype validation is converging with production-scale forging to compress development cycles from eighteen months to under eight weeks. Tier 1 suppliers serving German and United States OEMs are adopting hybrid workflows where printed geometries inform final die designs. This convergence is collapsing traditional tooling cost barriers for low-volume premium variants.
ECHA REACH substance restrictions on hexavalent chromium are eliminating conventional decorative plating across European-sourced components. Suppliers with trivalent chromium or physical vapor deposition alternatives capture platform specifications previously held by legacy chroming houses. The regulatory shift most acutely affects Detroit-based vehicle assemblers with cross-Atlantic platform sharing agreements.
Automaker direct sourcing of downloadable customization profiles is displacing traditional aftermarket accessory channels. Vehicle owners in China and the United States now purchase seasonal color schemes and badge geometries through manufacturer-hosted digital storefronts. This behavioral pivot concentrates margin capture with OEMs while fragmenting aftermarket supplier revenue pools.
Automotive Wheel Cap Market Segmentation
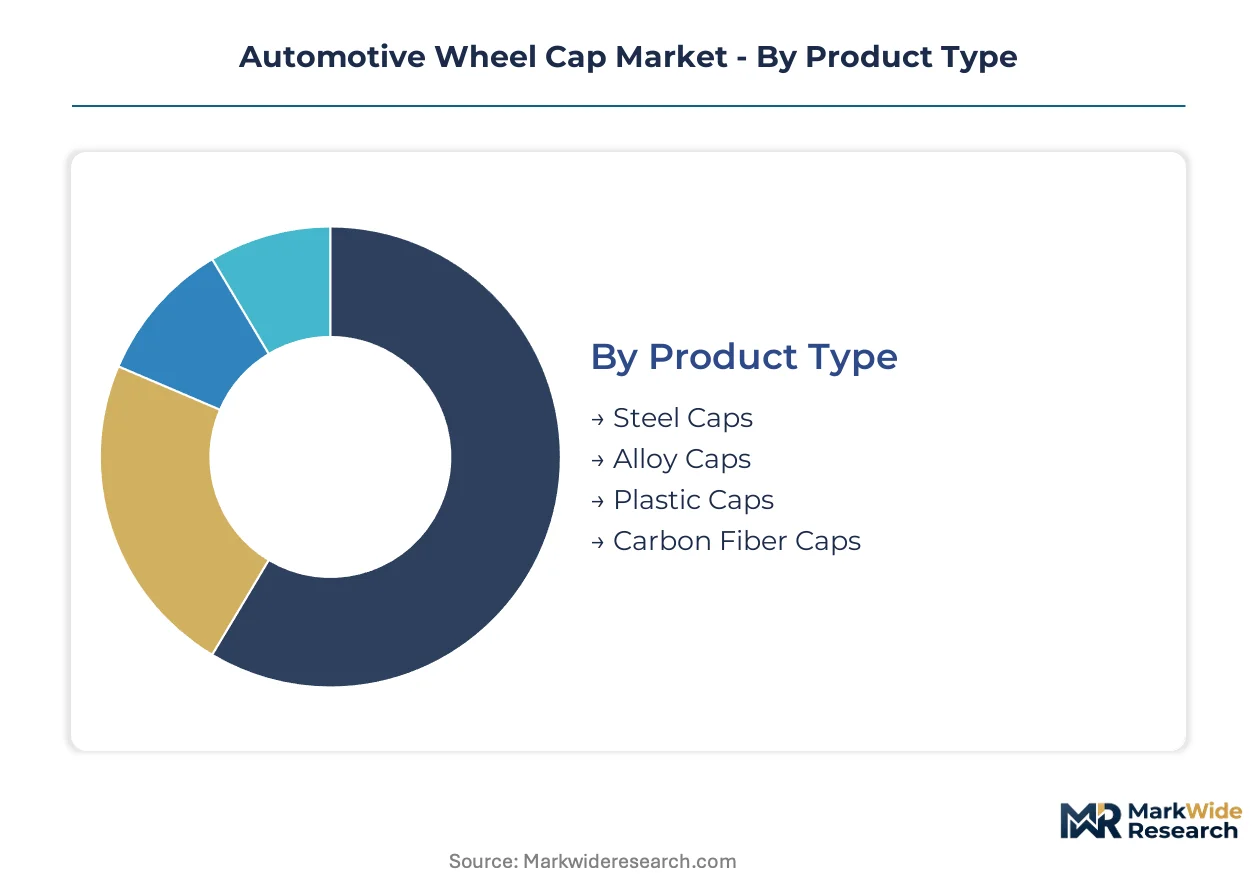
Wheel cap procurement splits across material specifications, channel relationships, and functional requirements. Each dimension carries distinct margin profiles and regulatory exposure that reshape supplier positioning across vehicle platforms.
Product Type:
Upgrade cycles accelerate when fuel-economy targets force gram-level weight scrutiny across wheel assemblies.
- Alloy Caps:Cast aluminum construction delivers optimal strength-to-weight ratios for premium wheel architectures. OEM procurement concentrates in Germany and the United States where EPA CAFE benchmarks and NHTSA safety standards jointly favor retention-force compliance with lightweighting mandates.
- Steel Caps:Stamped steel remains dominant in high-volume economy platforms where unit cost compression outweighs rotational mass concerns. Demand clusters with vehicle assemblers in China serving domestic mass-market segments.
- Plastic Caps:Injection-molded ABS polymers serve snap-on applications with lower speed ratings. China MIIT GB flammability standards constrain raw material sourcing for domestic assembly.
- Carbon Fiber Caps:Niche motorsport and ultra-premium segments justify material cost premiums through rotational mass reduction benefits.
Volume placements concentrate in steel and alloy variants; the faster expansion belongs to alloy caps as lightweighting mandates intensify.
End User:
Channel concentration determines pricing power and contract structure durability across the supply base.
- OEMs:Vehicle assemblers specify caps at platform design stage, locking suppliers into multi-year tooling contracts with just-in-sequence delivery requirements. Procurement authority sits with platform engineering teams in Detroit, Stuttgart, and Shanghai clusters.
- Vehicle Assemblers:Contract manufacturers and badge-engineering operations source caps through consolidated purchasing agreements. Volume concentrates with assemblers serving domestic Chinese brands and Indian expansion clusters near Chennai.
- Aftermarket Retailers:Digital storefronts and physical accessory chains serve owner-driven replacement and aesthetic upgrade demand. Revenue fragmentation accelerates as automaker direct sourcing of downloadable customization profiles displaces traditional channels.
- Tire Shops:Service bay replacement demand for damaged or lost caps generates episodic volume with minimal brand loyalty.
Revenue concentration favors OEM direct relationships; aftermarket channels face margin compression from digital displacement.
Installation Type:
Fastener geometry selection hinges on regional highway-speed regulations and assembly-line automation compatibility.
- Screw-On:Threaded metal-to-metal retention delivers maximum security for high-speed applications. ECE R124 retention testing in Europe structurally favors this geometry over snap alternatives.
- Plug-In:Bayonet-style engagement balances retention force with rapid assembly-line installation. German OEM platforms specify plug-in designs for premium wheel architectures.
- Snap-On:Plastic tab engagement enables lowest-cost production but faces regulatory headwinds. ECE R124 highway-speed mandates disadvantage snap-on specialists in European markets.
- Push Fit:Friction-based retention serves low-speed urban vehicles and temporary spare applications.
Regulatory compliance drives specification toward screw-on and plug-in variants; snap-on retains cost advantage in price-sensitive segments.
Feature:
Value-added attributes differentiate commodity hardware and unlock recurring revenue streams.
- Custom Designs:Software-defined badge geometries enable downloadable seasonal profiles and over-the-air personalization. Automaker-hosted digital storefronts in China and the United States concentrate margin capture with OEMs.
- Lightweight:Gram-level mass reduction supports fuel-economy certification strategies. Alloy and carbon fiber material selections dominate this feature category.
- Weather Resistance:UV-stable coatings and corrosion-resistant substrates extend service life in extreme climate exposure. ECHA REACH substance restrictions eliminate hexavalent chromium plating across European-sourced components.
- Reflective Elements:Retroreflective inserts enhance nighttime visibility for safety-critical applications.
Feature development investment clusters in custom design capabilities; lightweight attributes gain specification share fastest as efficiency targets tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in China and Germany while consumption concentrates in the United States and domestic Chinese vehicle markets. Regional regulatory divergence around fastener retention standards and material specifications fragments supplier certification requirements. Industrial policy in India and Mexico is drawing assembly investment away from traditional manufacturing centers.
United States
EPA CAFE benchmarks drive gram-level weight scrutiny across wheel assemblies, favoring alloy cap specifications from Detroit-based vehicle assemblers. NHTSA wheel retention standards mandate screw-on and plug-in geometries for highway-speed compliance. Manufacturing concentration in Michigan and Ohio sustains just-in-sequence supply relationships with domestic OEM platforms.
Germany
Premium vehicle export demand anchors alloy cap procurement from Stuttgart and Munich engineering centers. ECE R124 retention testing structurally favors metal fastener geometries over plastic alternatives. Supplier forging networks in Bavaria and Baden-Württemberg deliver captive capacity for European OEM just-in-time requirements.
China
Domestic vehicle assembly expansion creates the world's largest wheel cap consumption base. MIIT GB standards constrain plastic component flammability specifications for raw material sourcing. Yangtze River Delta and Pearl River Delta clusters concentrate injection molding and alloy casting capacity near Shanghai and Guangzhou assembly plants.
India
Local vehicle production growth generates demand for wheel cap suppliers establishing captive operations. BIS certification requirements for automotive components create entry barriers for uncertified imports. Chennai and Pune industrial corridors attract Tier 1 suppliers seeking proximity to expanding domestic OEM assembly.
Mexico
Nearshoring of North American vehicle assembly draws wheel cap supply chain investment southward. NHTSA-equivalent safety standards apply to production destined for US export markets. Nuevo León and Bajío Region manufacturing parks host supplier facilities serving cross-border OEM platforms.
Automotive Wheel Cap Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the wheel cap supply base. The market structure concentrates around multi-year OEM tooling contracts that freeze supplier design flexibility for platform durations. Three archetypes dominate: Iberian forging specialists with captive alloy capacity, injection molding houses with vertical control over plastic assemblies, and chroming experts commanding premium positioning with Detroit assemblers. Competitive dynamics center on backward integration into raw material supply and geographic expansion toward emerging assembly clusters.
Within the forging-specialist tier, CIE AUTOMOTIVE S.A. and Zanini Auto Grup SA exemplify divergent material strategies—one anchored in Iberian alloy production, the other in plastic assembly verticalization. Lacks Enterprises, Inc occupies a position representing decorative surface treatment expertise. These three entities illustrate how regional regulatory exposure and material certification capabilities determine platform access across distinct OEM procurement channels.
| Leading Market Players |
|---|
| CIE AUTOMOTIVE S.A. |
| Zanini Auto Grup SA |
| Versaco s.r.o. |
| Swell Marui Automobile Parts Co., LTD |
| Auto Pearl Automotives |
| Lacks Enterprises, Inc |
| Wheel Pros LLC |
| Prigan India Private Limited |
| Prim X Auto Industries |
| Others |
Supply Flow & Price Mechanics
Captive forging capacity across Iberian plants anchors CIE AUTOMOTIVE S.A.'s supply security while simultaneously propping pricing power against mid-tier competitors exposed to London Metal Exchange aluminum volatility. This backward integration into alloy production insulates platform pricing from raw material spikes that compress margins for stamping houses and injection molders lacking smelter partnerships.
Pricing Analysis
Cost-down pressure on economy-tier steel caps accelerates because Chinese domestic assemblers prioritize unit cost compression over rotational mass reduction in high-volume platforms. Three-tier pricing structure across premium, standard, and economy levels separates screw-on alloy specifications for German OEMs from snap-on plastic assemblies serving price-sensitive segments. Certification grade under ECE R124 and NHTSA retention standards drives price differentiation between highway-speed compliant metal fasteners and lower-speed plastic alternatives. Vehicle assemblers in China exhibit highest price sensitivity, while Stuttgart and Munich engineering centers absorb premiums for forged alloy architectures.
Supply Chain Analysis
Freight cost escalation from Yangtze River Delta injection molding clusters to European assembly plants favors regional forging networks in Bavaria and Baden-Württemberg. Supply concentrates in China, Germany, and Mexico, with raw material dependencies spanning aluminum ingots, ABS polymer compounds, and trivalent chromium plating chemicals. Single-source vulnerability around certified alloy formulations under China MIIT GB flammability standards threatens just-in-sequence delivery commitments. Distribution runs through Tier 1 supplier direct relationships with OEM platform engineering teams, bypassing traditional aftermarket channels increasingly displaced by automaker digital storefronts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Alloy cap supply constraints from captive forging capacity limitations prop pricing power for integrated producers while stranding mid-tier competitors on volatile spot markets for aluminum inputs.
For Market Incumbents: To counter margin compression from OEM platform standardization, defend position through captive forging capacity expansion near Chennai and Pune clusters, while accelerating trivalent chromium certification to capture platform specifications vacated by hexavalent chromium plating houses under ECHA REACH restrictions. For New Entrants and Emerging Players: NHTSA safety standard harmonization with Canadian protocols opens a window for cross-border certification arbitrage serving Detroit-based vehicle assemblers with unified retention testing documentation. Target Indian domestic assembly growth near emerging industrial corridors, leveraging BIS certification partnerships as a go-to-market wedge against uncertified import competition. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by OEMs seeking captive alloy supply security, particularly Iberian forging assets with proven just-in-sequence delivery track records. Long-term viability favors vertically integrated producers with backward control over smelter relationships and certified compound formulations; monitor aluminum futures volatility as an inflection signal for margin compression among non-integrated competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Customization Investment | Over-the-air badge geometries enable recurring revenue through seasonal profile downloads from OEM digital storefronts. |
| Captive Forging Capacity Expansion | Iberian and Indian alloy production assets insulate platform pricing from London Metal Exchange aluminum volatility. |
| Trivalent Chromium Certification | ECHA REACH compliance captures decorative plating specifications previously held by legacy hexavalent chromium houses. |
| Geographic Manufacturing Footprint | Nuevo León and Bajío Region facilities serve cross-border OEM platforms under NHTSA-equivalent safety standards. |
| Long-term OEM Tooling Contracts | Multi-year platform commitments lock in volume visibility despite freezing design flexibility for contract durations. |
Methodological Framework
Multi-period observation of vehicle production volumes, alloy pricing spreads, and regulatory filing trajectories anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers. Primary fieldwork combined with secondary validation against IHS Markit registration data, vehicle production databases, SEC 10-K filings from automotive component suppliers, and customs records tracking aluminum ingot and ABS polymer trade flows. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Segment-weighting across material specifications, installation types, and regional production clusters informed the analytical framework. Modeled dimensions included alloy versus steel versus plastic construction, screw-on versus plug-in versus snap-on fastener geometries, and OEM direct versus aftermarket channel relationships. CAGRs were derived from regression analysis against historical production correlations and forward-projected platform standardization timelines, incorporating EPA CAFE benchmark stringency and ECE R124 retention testing adoption as industry-specific forecast inputs.
The model assumes a particular technology adoption path for software-defined customization services; alternative pathways for additive manufacturing production scaling would alter the outlook for traditional forging and injection molding capacity investments. Forecasts reflect assumptions about aluminum price stability, regulatory harmonization progress, and OEM platform consolidation trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Rechargeable Tires Market
Tires and Wheels
Automotive Wheel Spindle Market
Tires and Wheels
Low Rolling Resistance Tire Market
Tires and Wheels
North America 2-Wheeler Tire Market
Tires and Wheels
Global Automotive Tire Socks Market
Tires and Wheels
Asia-Pacific Automotive Tire Pressure Management System Market
Tires and Wheels
Run Flat Tire Inserts Market
Tires and Wheels
Automotive Smart Tire Market
Tires and Wheels
Global Ultra High Performance Tire Market
Tires and Wheels
Global Electric Vehicle Tire Market
Tires and Wheels
Asia-Pacific Alloy Wheels Market
Tires and Wheels
Global Winter Tires Market
Tires and Wheels
Automotive Tubeless Tire Market
Tires and Wheels
Tire Protection Chains Market
Tires and Wheels
Wheel Cover Market
Tires and Wheels
Global Automotive Tire Inflator Market