
 Southeast Asian Tire Market | 2026-2036
Southeast Asian Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asian Tire Market Insights
REACH compliance is rebalancing the cost-of-entry calculus for European-branded tire imports into Southeast Asia, forcing manufacturers to reformulate compound recipes or absorb certification overhead. Continental AG leverages its in-house testing infrastructure in the region to pre-validate compound batches before shipment. Bridgestone Corporation anchors its competitive position through backward integration into natural rubber sourcing across Indonesian and Thai plantations. Michelin differentiates via sustained R&D spending on low-rolling-resistance compounds tailored to tropical humidity cycles.
A tire is an elastomer-composite toroidal structure comprising steel-belted radial plies, synthetic rubber compounds, and carbon-black reinforcement, manufactured through calendering, extrusion, and vulcanization processes to provide load-bearing, shock-absorption, and traction functions for wheeled vehicles. Radial construction dominates OEM fitment across passenger car and commercial vehicle channels due to superior heat dissipation and tread life under sustained highway speeds. Two-wheeler demand in Indonesia and Vietnam sustains bias-ply and tube-type configurations where cost sensitivity and repair infrastructure favor simpler construction. Distribution through authorized dealers captures the replacement premium, while online sales channels are gaining traction among urban fleet managers seeking consolidated procurement.
Thailand's Industrial Standards Institute (TISI) enforces SNI-aligned tire labeling and safety testing, while Indonesia's Badan Standardisasi Nasional mandates homologation for both domestic production and imports, creating a dual-compliance burden for regional suppliers. Vietnam's Ministry of Science and Technology is phasing in parallel GB-standard harmonization for cross-border truck tire certification, complicating multi-country distribution strategies. Stakeholders must monitor divergent national certification timelines and pre-position testing capacity in each major market to avoid customs detention and margin erosion.
Market Dynamics
Indonesia's SNI mandatory certification regime is compressing import windows and forcing regional suppliers to pre-position domestic testing capacity, redrawing competitive entry costs across the entire market.
Growth Catalysts
- Thailand's Eastern Economic Corridor manufacturing cluster:Commercial vehicle fleets are extending replacement purchase cycles as highway freight volumes expand through this industrial zone.
- REACH compliance spillover:European compound reformulation standards are elevating quality baselines for premium tire imports into Vietnam and Indonesia.
- Radial construction technology:Heat dissipation advantages under sustained tropical highway speeds are displacing bias-ply configurations in passenger car OEM channels.
Market Restraints
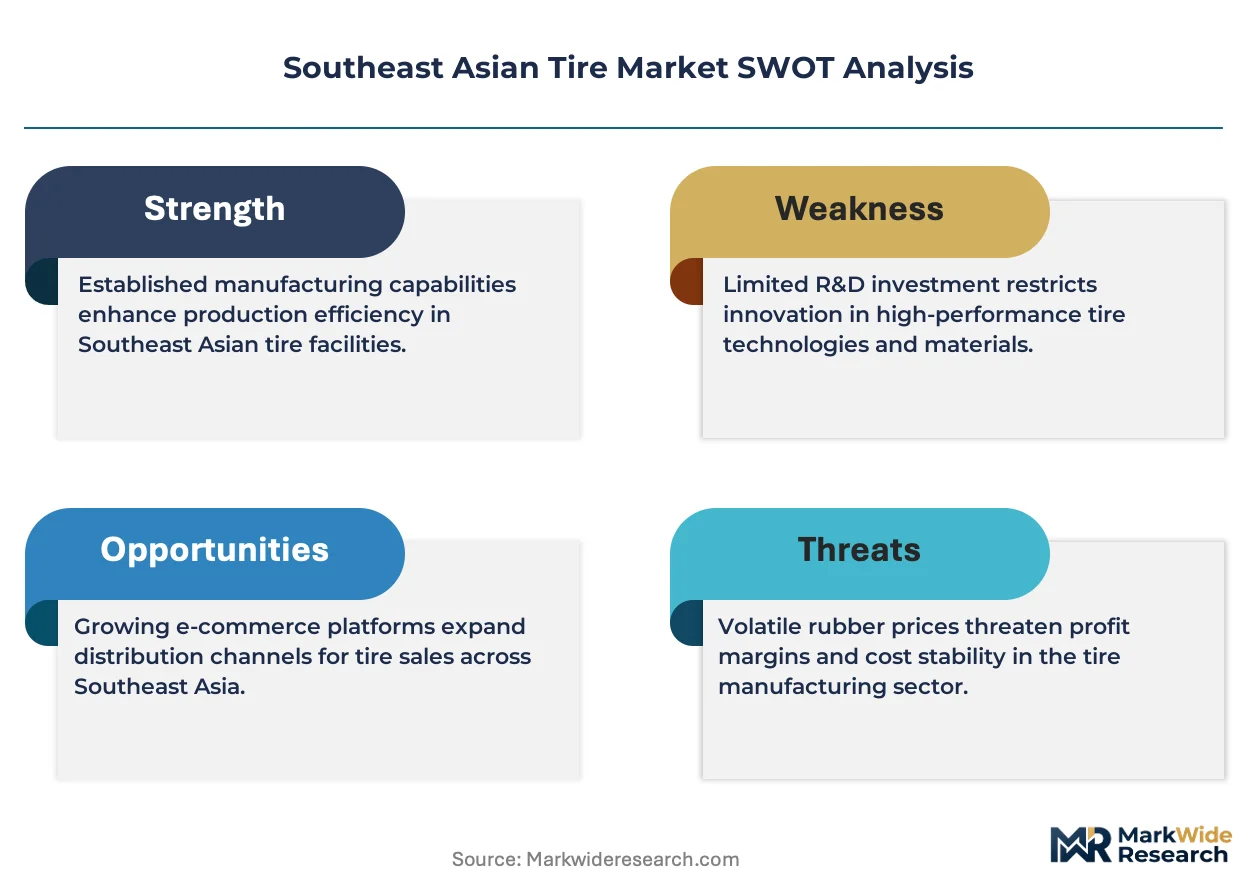
- Natural rubber price volatility:Input cost swings from Indonesian and Thai plantation supply disruptions compress margin predictability for compounders lacking backward integration into upstream sourcing.
- Dual-certification burden:Indonesia's Badan Standardisasi Nasional homologation requirements layered against Thailand's TISI labeling rules fragment testing budgets for multi-country distributors.
- Tube-type repair infrastructure:Two-wheeler bias-ply configurations retain cost advantages where roadside service networks remain underdeveloped in rural Vietnamese provinces.
Strategic Opportunities
- Vietnam's GB-standard harmonization:Cross-border truck tire certification alignment with Chinese technical regulations opens consolidated procurement for fleet operators spanning both markets.
- Online fleet procurement platforms:Urban commercial vehicle managers in Bangkok and Jakarta are consolidating replacement orders through digital channels, bypassing traditional dealer networks.
- Low-rolling-resistance compounds:Tropical humidity cycle optimization creates white space for R&D-focused manufacturers to capture fuel-efficiency premiums from logistics operators.
Industry Challenges
- Vulcanization technician scarcity:Calendering and extrusion process expertise concentrates in Thailand's established manufacturing bases, constrating capacity expansion in emerging Vietnamese production zones.
- Customs detention risk:Divergent national certification timelines between Indonesia, Thailand, and Vietnam create working capital strain from pre-positioned inventory awaiting homologation clearance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asian Tire Market |
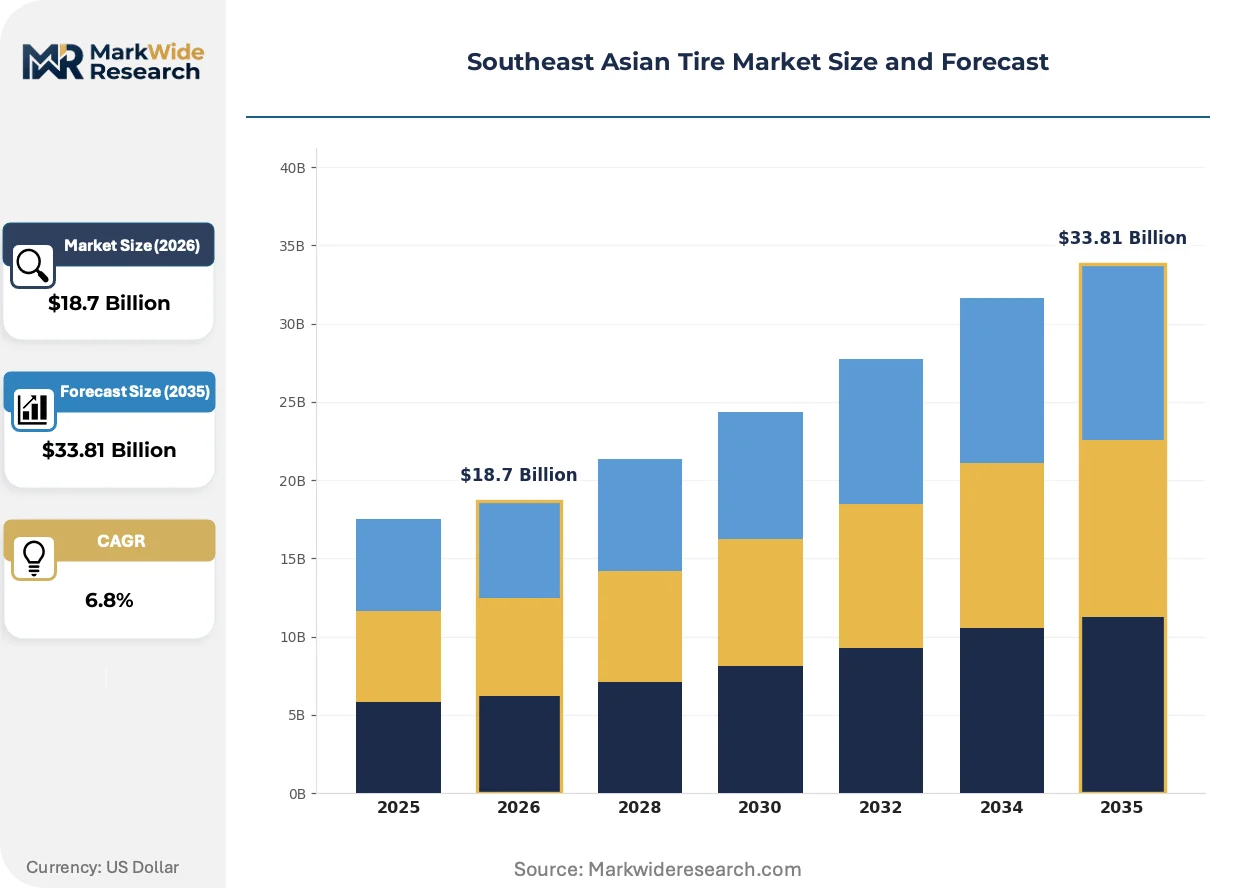
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial, Bias, Tubeless, Tube-Type End User: Passenger Cars, Commercial Vehicles, Off-Road Vehicles, Two-Wheelers Size: 15 Inch, 16 Inch, 17 Inch, 18 Inch Distribution Channel: Online Sales, Retail Outlets, Wholesale, Authorized Dealers |
| Companies Covered | Continental AG, PT Suryaraya Rubberindo Industries, Bridgestone Corporation, The Yokohama Rubber Co., Ltd., Sumitomo Rubber Industries, Ltd., Michelin, Goodyear Tire & Rubber Company, Hankook Tire & Technology Co., Ltd., PT Gajah Tunggal Tbk, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asian Tire Market Trends and Innovations
Compound formulation advances and procurement digitization are compressing traditional channel structures while regulatory layering across ASEAN member states forces testing infrastructure decentralization.
Silica-reinforced tread compounds are integrating nanoscale dispersion techniques to reduce rolling resistance without sacrificing wet-grip performance under monsoon humidity cycles. Premium passenger car OEMs in Thailand are specifying these formulations for factory fitment at accelerating rates. The technology is integrating carbon-black hybrid architectures that previously required separate production lines, collapsing compound development timelines for mid-tier suppliers.
Indonesia's Badan Standardisasi Nasional is expanding SNI scope to cover imported commercial vehicle tires previously exempt from domestic homologation. Thai manufacturers with pre-existing TISI-certified laboratories are capturing first-mover advantage by cross-approving batches for dual-market entry. Vietnamese regulators are observing this divergence, signaling potential GB-standard alignment rather than independent regime development.
Fleet procurement managers across Jakarta and Bangkok are consolidating replacement tire purchasing through centralized online platforms that aggregate volume across multiple vehicle classes. Authorized dealer networks are responding by unbundling installation services from product margins to retain commercial relationships. This channel compression is most visible among logistics operators with standardized vehicle configurations and predictable annual mileage thresholds.
Southeast Asian Tire Market Segmentation
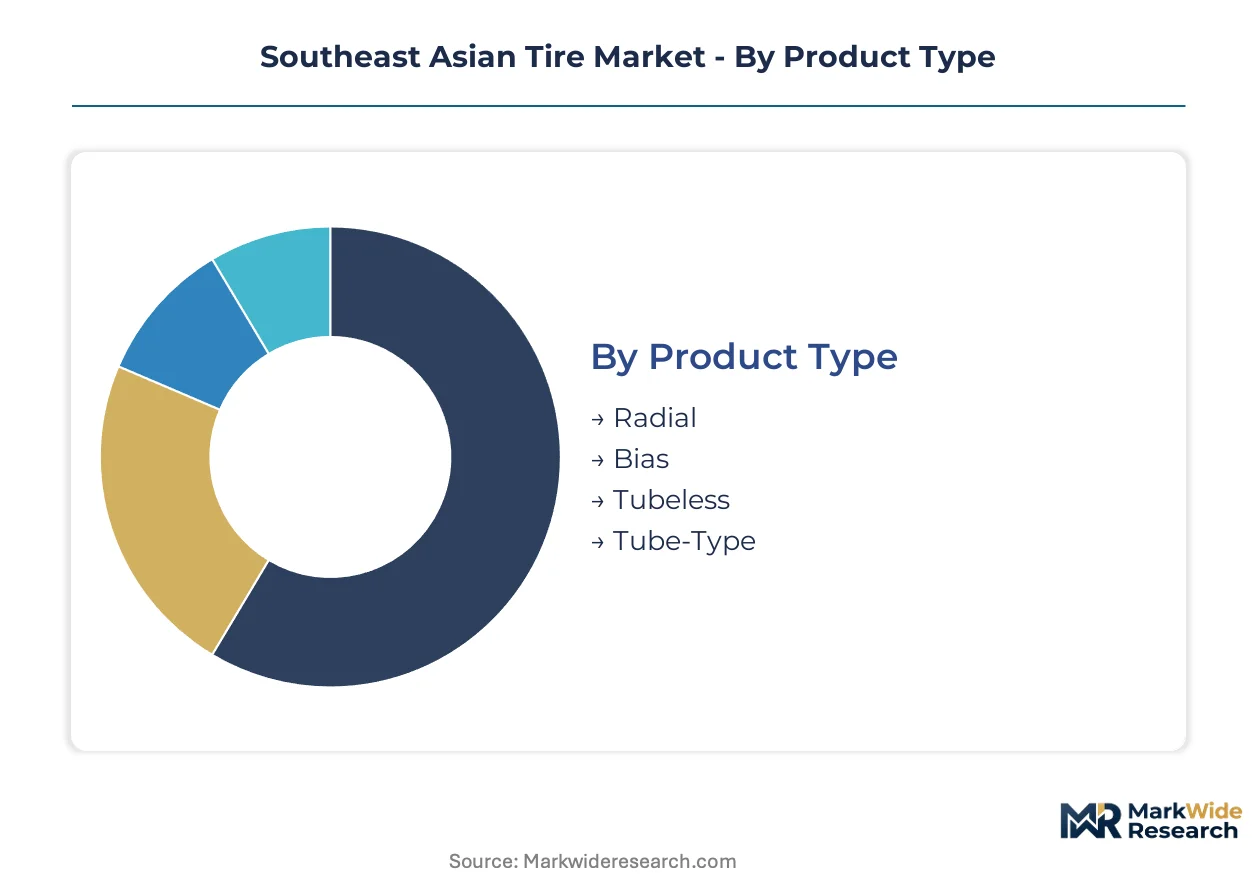
Tire purchasing patterns across Southeast Asia diverge sharply by vehicle class and operating environment, with fleet managers prioritizing durability metrics while two-wheeler owners emphasize roadside serviceability. Technical specifications and certification requirements fragment procurement strategies across Indonesia, Thailand, and Vietnam.
Product Type:
Construction method determines heat management capability and repair complexity under tropical operating conditions.
- Radial:Steel-belted cord plies arranged perpendicular to the direction of travel deliver superior heat dissipation during sustained highway operation. Thailand's Eastern Economic Corridor freight corridors are displacing bias configurations as fleet operators prioritize tread life and fuel efficiency.
- Tubeless:Elimination of inner tubes through airtight bead-seal construction reduces rotational mass and puncture-related downtime. Urban passenger car OEM channels in Jakarta and Bangkok are specifying tubeless fitments at accelerating rates as expressway infrastructure expands.
- Bias:Diagonal ply construction retains cost advantages for low-speed applications where repair simplicity outweighs highway performance requirements.
- Tube-Type:Conventional inner tube configurations persist in rural Vietnamese and Indonesian two-wheeler markets where roadside vulcanization services remain the dominant repair modality.
Volume sits with radial construction; growth tilts toward tubeless configurations.
End User:
Operating intensity and duty cycles separate replacement frequency and specification rigor across buyer categories.
- Commercial Vehicles:Heavy-duty truck and bus fleets subject tires to sustained load-bearing stress across Thailand's industrial freight corridors. Indonesia's SNI certification expansion to imported commercial tires is compressing supplier qualification timelines for regional fleet procurement managers.
- Two-Wheelers:Motorcycles and scooters dominate unit volume across Indonesian and Vietnamese urban mobility, with bias-ply tube-type configurations retaining preference where repair infrastructure concentrates in informal roadside service networks.
- Passenger Cars:Private vehicle owners prioritize ride comfort and wet-grip performance during monsoon conditions, driving silica-compound adoption in replacement channels.
- Off-Road Vehicles:Agricultural and construction equipment tires face abrasive terrain and irregular load distribution, requiring reinforced sidewall construction and specialized tread patterns for plantation and mining applications.
Two-wheelers dominate unit shipments; commercial vehicles command the steepest expansion trajectory as logistics infrastructure modernizes.
Size:
Rim diameter correlates with vehicle class positioning and replacement cost tiering across Southeast Asian markets.
- 16 Inch:Mid-size passenger car fitment balances ride quality and fuel efficiency for the dominant vehicle class in Thailand's domestic market. Replacement demand concentrates in Bangkok's suburban commuter corridors where highway speeds necessitate heat-dissipating radial construction.
- 15 Inch:Compact vehicle specification retains volume leadership in Indonesian and Vietnamese entry-level segments where cost sensitivity shapes procurement decisions. Fleet operators in these markets prioritize unit economics over performance premiums.
- 17 Inch:Premium passenger car and crossover fitments are gaining traction among urban professionals in Jakarta and Bangkok seeking aesthetic differentiation alongside handling improvements.
- 18 Inch:Performance and luxury vehicle applications remain niche, concentrated in Thailand's high-end import channels and Indonesian premium dealership networks.
15-inch and 16-inch specifications anchor current volume; 17-inch fitments are climbing the fastest as vehicle fleets upgrade.
Distribution Channel:
Buyer sophistication and order scale determine channel preference, with digital platforms eroding traditional dealer margins in consolidated fleet procurement.
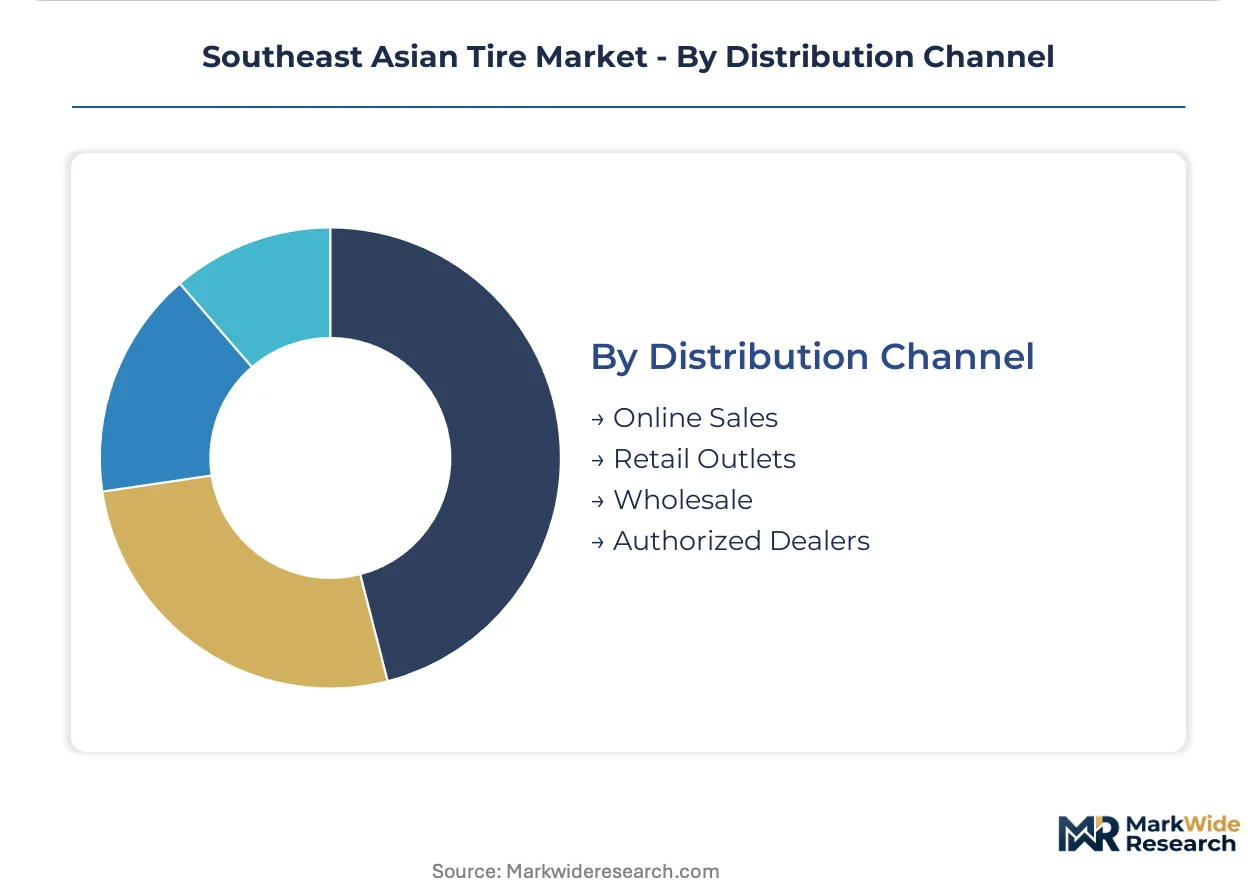
- Authorized Dealers:Branded retail networks capture replacement premiums through warranty-backed installation services and technical consultation. Indonesia's SNI compliance verification requirements reinforce dealer channel importance for import validation.
- Online Sales:Digital procurement platforms aggregate volume across vehicle classes for urban fleet managers in Bangkok and Jakarta, compressing traditional distribution markups. These channels prioritize standardized specifications and predictable delivery timelines.
- Retail Outlets:Independent tire shops serve price-sensitive consumers and rural markets where brand loyalty yields to immediate availability and negotiated installation pricing.
- Wholesale:Bulk distribution to secondary retailers and fleet maintenance depots concentrates in Thailand's manufacturing zones, leveraging proximity to production facilities for margin preservation.
Authorized dealers retain the largest revenue share; online sales are gaining share fastest among commercial vehicle segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial vehicle fleet expansion and manufacturing cluster development concentrate demand across Thailand's Eastern Economic Corridor, Indonesia's industrial zones, and Vietnam's logistics corridors. Regulatory layering between national certification regimes fragments procurement strategies for multi-country suppliers.
Thailand
Heavy-duty truck fleets serving the Eastern Economic Corridor generate sustained replacement demand for radial construction tires rated for tropical highway heat. Thailand's Industrial Standards Institute enforces TISI-aligned labeling and safety testing that overlaps with Indonesian requirements. Manufacturing facilities cluster in Rayong and Chonburi provinces where calendering and extrusion expertise supports regional export capacity.
Indonesia
Motorcycle and scooter dominance in urban mobility sustains bias-ply tube-type volume despite radial penetration in passenger channels. Badan Standardisasi Nasional mandates SNI homologation for both domestic production and imports, compressing supplier qualification timelines. Industrial zones in Bekasi and Karawang host domestic tire plants seeking to bypass import certification delays through localized testing capacity.
Vietnam
Cross-border freight growth with China drives truck tire demand along the Hanoi-Hai Phong logistics corridor. The Ministry of Science and Technology is phasing GB-standard harmonization for truck tire certification, creating alignment pressure with Chinese technical regulations. Manufacturing investment concentrates in Hai Phong and Quang Ninh provinces where producers target export markets and domestic fleet replacement.
Malaysia
Port logistics and palm oil plantation vehicle fleets generate specialized off-road tire demand in Peninsular Malaysia. The Department of Standards Malaysia enforces MS standards that generally align with broader ASEAN technical regulations. Industrial zones in Shah Alam and Kulim host assembly and distribution operations serving both domestic replacement and re-export channels.
Philippines
Jeepney fleet modernization and logistics truck expansion drive commercial tire replacement in Metro Manila and Cebu. The Bureau of Philippine Standards administers mandatory certification through the Philippine Standard Quality and Safety Certification Mark scheme. Manufacturing presence concentrates in Laguna and Cavite provinces where producers leverage tariff preferences under regional trade agreements.
Southeast Asian Tire Market Competitive Landscape
Japanese and European producers anchor the premium tier; Indonesian and Thai specialists hold mid-market positions through plantation-sourced natural rubber integration. The vendor base spans consolidated multinational operations and regional compounders with backward integration into upstream sourcing. Three archetypes dominate: integrated natural rubber processors, R&D-focused premium compounders, and scale-driven mass-market suppliers. Competitive moves concentrate on dual-certification laboratory pre-positioning and silica-compound technology licensing.
Within the integrated processor tier, PT Gajah Tunggal Tbk and PT Suryaraya Rubberindo Industries represent Indonesian natural rubber-anchored fabrication. Continental AG and Bridgestone Corporation exemplify premium-tier positioning through sustained compound development investment. Michelin occupies a position emphasizing low-rolling-resistance formulation specialization for tropical operating conditions.
| Leading Market Players |
|---|
| Continental AG |
| PT Suryaraya Rubberindo Industries |
| Bridgestone Corporation |
| The Yokohama Rubber Co., Ltd. |
| Sumitomo Rubber Industries, Ltd. |
| Michelin |
| Goodyear Tire & Rubber Company |
| Hankook Tire & Technology Co., Ltd. |
| PT Gajah Tunggal Tbk |
| Others |
Pricing and Supply Chain Analysis
Indonesia's SNI mandatory certification expansion is forcing importers to pre-position domestic testing capacity, which compresses supplier margins and fragments pricing power across certification tiers. Supply chain configuration must absorb these compliance costs or cede volume to localized producers with captive laboratory infrastructure.
Pricing Analysis
Volume concentrates in mass-market radial and bias-ply segments where plantation-sourced natural rubber integration anchors margin preservation, while premium silica-compound tiers capture fuel-efficiency premiums from logistics operators. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and backward integration depth. Price erosion runs through import-dependent suppliers lacking TISI or SNI pre-certification, as customs detention risk forces working capital absorption. Fleet procurement managers in Bangkok and Jakarta exhibit lowest price sensitivity due to consolidated volume aggregation, while rural two-wheeler owners in Vietnamese provinces prioritize unit economics over performance specifications.
Supply Chain Analysis
Regional distribution centers in Thailand's Rayong and Chonburi provinces anchor hub-and-spoke patterns serving Indonesia, Vietnam, and Malaysia through cross-border freight corridors. Manufacturing gravity draws from Indonesian and Thai natural rubber plantations, Chinese synthetic rubber feedstocks, and Japanese carbon-black reinforcement technologies. Supply chain risk centers on single-source vulnerability for SNI-certified testing capacity, where Indonesia's Badan Standardisasi Nasional homologation delays create inventory detention exposure. Distribution runs through authorized dealer networks for warranty-backed installation, with digital platforms eroding markups among urban fleet managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vulcanization technician scarcity in emerging Vietnamese production zones constrains capacity expansion, propping pricing for established Thai manufacturers with calendering and extrusion expertise.
For Market Incumbents: Hedge against Indonesian SNI compliance fragmentation by cross-approving batches through TISI-certified laboratories for dual-market entry. Deepen backward integration into Thai and Indonesian plantation sourcing to buffer natural rubber price volatility. Prioritize silica-compound R&D licensing to mid-tier suppliers seeking tropical humidity-optimized formulations. For New Entrants and Emerging Players: Vietnam's GB-standard harmonization with Chinese technical regulations opens a window for cross-border truck tire certification consolidation targeting fleet operators spanning both markets. Target online fleet procurement platforms in Jakarta and Bangkok with standardized specifications and predictable delivery timelines. Penetrate through installation-service unbundling to bypass entrenched authorized dealer networks. For Investors and Strategic Acquirers: The window for entry favors integrated natural rubber processors with captive laboratory infrastructure and plantation supply control. Long-term viability rests on certification pre-positioning across multiple ASEAN regimes rather than single-market dominance. Monitor GB-standard implementation timelines in Vietnam as inflection indicator for cross-border procurement consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Laboratory Pre-Positioning | TISI-SNI cross-approval capability captures first-mover advantage in Indonesian import windows. |
| Silica-Compound Technology Licensing | Tropical humidity-optimized formulations command fuel-efficiency premiums from logistics operators. |
| Online Fleet Procurement Platform Integration | Direct channel access bypasses traditional dealer markups among Bangkok and Jakarta fleet managers. |
| Backward Integration into Plantation Sourcing | Captive natural rubber supply buffers margin compression from Indonesian and Thai plantation disruptions. |
| GB-Standard Harmonization Alignment | Vietnamese truck tire certification convergence with Chinese regulations opens consolidated procurement volumes. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with tire plant managers, fleet procurement directors, authorized dealer network heads, and Badan Standardisasi Nasional compliance officers. Bottom-up triangulation combined shipment volume analysis with top-down validation against TISI and SNI certification databases. SEC filings from listed tire manufacturers, ASEAN customs trade statistics, and Eastern Economic Corridor industrial zone development reports provided cross-referenced demand indicators.
Data-stream reconciliation across production volume, import clearance timelines, and replacement cycle surveys enabled segmentation modeling by construction method, vehicle class, rim diameter, and distribution channel. CAGRs were derived from trend extrapolation of highway freight expansion, fleet modernization rates, and regulatory implementation schedules across the analysis window. Forecast inputs incorporated silica-compound adoption curves, online procurement penetration rates, and cross-border certification alignment probabilities.
The model assumes a particular technology adoption path; alternative pathways for tubeless radial penetration in two-wheeler segments would alter the outlook. Forecasts reflect stated assumptions regarding SNI scope expansion timing and GB-standard harmonization completion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
All Weather Tire Market
Tires and Wheels
Global Tire Curing Press Market
Tires and Wheels
Re-Tread Tires Market
Tires and Wheels
EV Tire Market
Tires and Wheels
Self-Sealing Tire Market
Tires and Wheels
Automotive Smart Tire Market
Tires and Wheels
Wheel and Tire Service Equipment Market
Tires and Wheels
Heavy Duty Tire Market
Tires and Wheels
Smart Tire Market
Tires and Wheels
Automotive Wheel Cap Market
Tires and Wheels
Tire Carousel Market
Tires and Wheels
Wheel Market
Tires and Wheels
Global Automotive Tires Market
Tires and Wheels
Tire Bead Wire Market
Tires and Wheels
Solid Tire Market
Tires and Wheels
Global Aircraft Tire Market