
 Automotive Tubeless Tire Market | 2026-2036
Automotive Tubeless Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Tubeless Tire Market Analysis
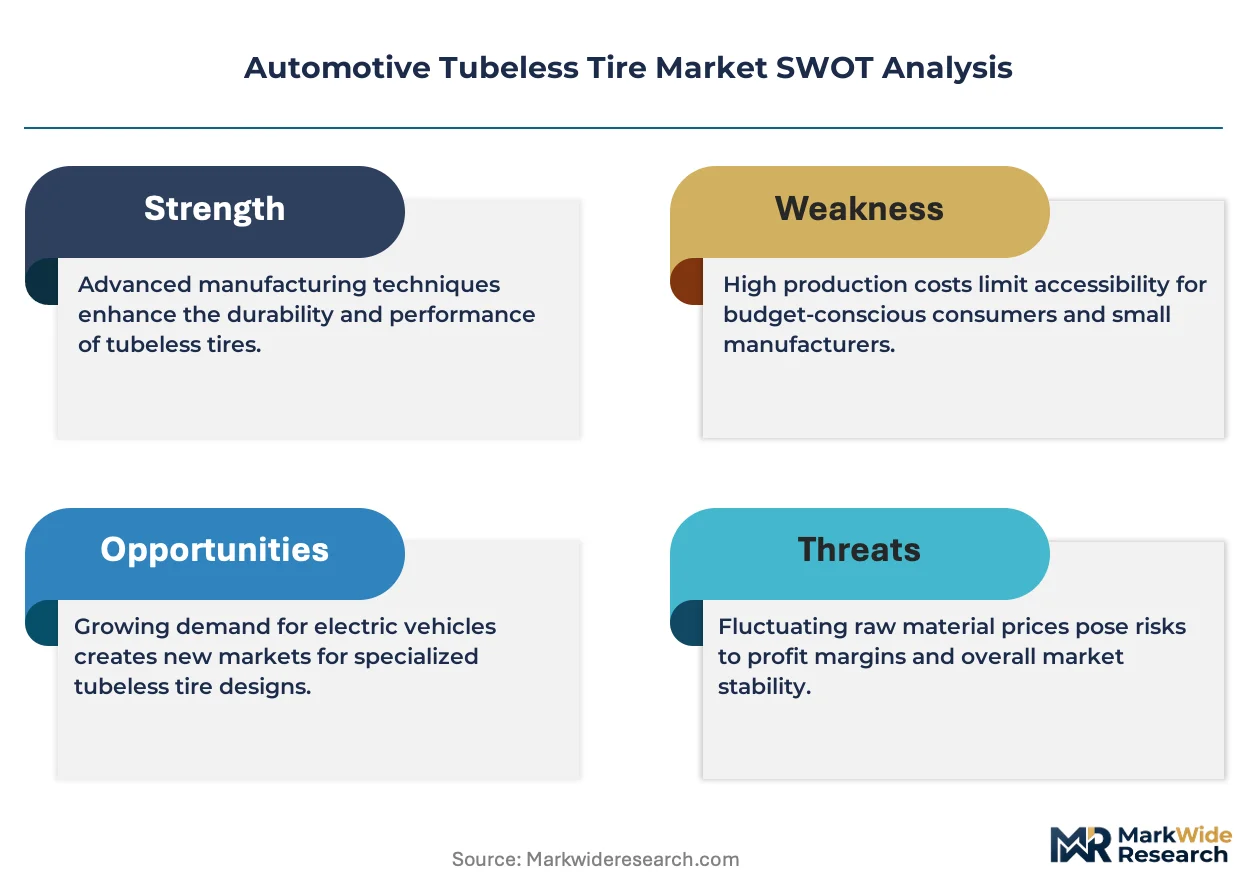
The premium-commodity divide in automotive tubeless tires is rebalancing around wet-grip ratings, rolling-resistance bands, and warranty terms rather than raw price points. Continental AG leverages its in-house silica-silane research to command position in the original equipment channel. Bridgestone Corporation anchors volume through captive supply relationships with Japanese automakers. Michelin SCA differentiates via sustained investment in airless architecture and sustainable natural rubber sourcing.
An automotive tubeless tire seals air through an integrated chlorobutyl or halobutyl rubber liner bonded to the inner carcass, eliminating the separate inner tube while maintaining inflation pressure via airtight contact with the wheel rim; this design reduces unsprung mass and dissipates heat more efficiently than tubed alternatives. Passenger car tires occupy the dominant value share, though light truck segments carry thicker margin pools due to replacement-cycle premiums and load-rating specialization. Directional tread patterns are gaining preference in wet-climate markets, while asymmetrical designs dominate the performance tier where highway and track use overlap.
The US NHTSA maintains Federal Motor Vehicle Safety Standard 109 for tire performance, while the EU ECE R30 and R54 regulations govern passenger and commercial tire homologation; REACH restrictions on aromatic oils and the EU Green Deal's embedded carbon requirements are forcing compound reformulation across the supply base. China's GB standards and MIIT energy-efficiency labeling add compliance layers for import access. Stakeholders must monitor how battery-electric vehicle weight distribution shifts are altering load-index specifications and wear-pattern expectations.
Market Dynamics
Electric vehicle weight distribution is rewriting load-index specifications across the supply base, forcing compound reformulation and bead-structure reinforcement at the design stage.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of fluorinated greenhouse gases is accelerating halobutyl liner adoption as manufacturers seek lower-global-warming-potential sealing solutions.
- China's Jiangsu-Shandong corridor:Concentrated tire production clusters feed both domestic EV assembly plants and export channels, creating procurement efficiencies.
- Silica-silane coupling:Advanced filler systems are reducing rolling resistance while maintaining wet-grip performance, meeting dual-labeling requirements.
Market Restraints
- Natural rubber price volatility:Hevea brasiliensis supply sensitivity to climate patterns in Southeast Asia compresses margin predictability for compounders.
- REACH aromatic oil restrictions:Reformulation mandates for extender oils are increasing R&D cycle times and certification costs.
- Airless tire prototypes:Michelin's Tweel architecture and similar non-pneumatic designs threaten replacement-cycle revenue models.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for advanced automotive components are drawing greenfield tire capacity to Tamil Nadu and Gujarat.
- Sensor-embedded intelligent tires:Convergence of RFID tags and pressure-monitoring systems is opening fleet-management data services.
- EU Green Deal embedded carbon requirements:First-mover certification under incoming carbon-border adjustments commands premium positioning.
Industry Challenges
- Compounder talent scarcity:Formulation chemistry expertise for silica-silane systems and bio-based alternatives is concentrated among retiring specialists.
- Homologation timeline compression:Parallel ECE R30, R54, and GB standard testing is extending product-launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Tubeless Tire Market |
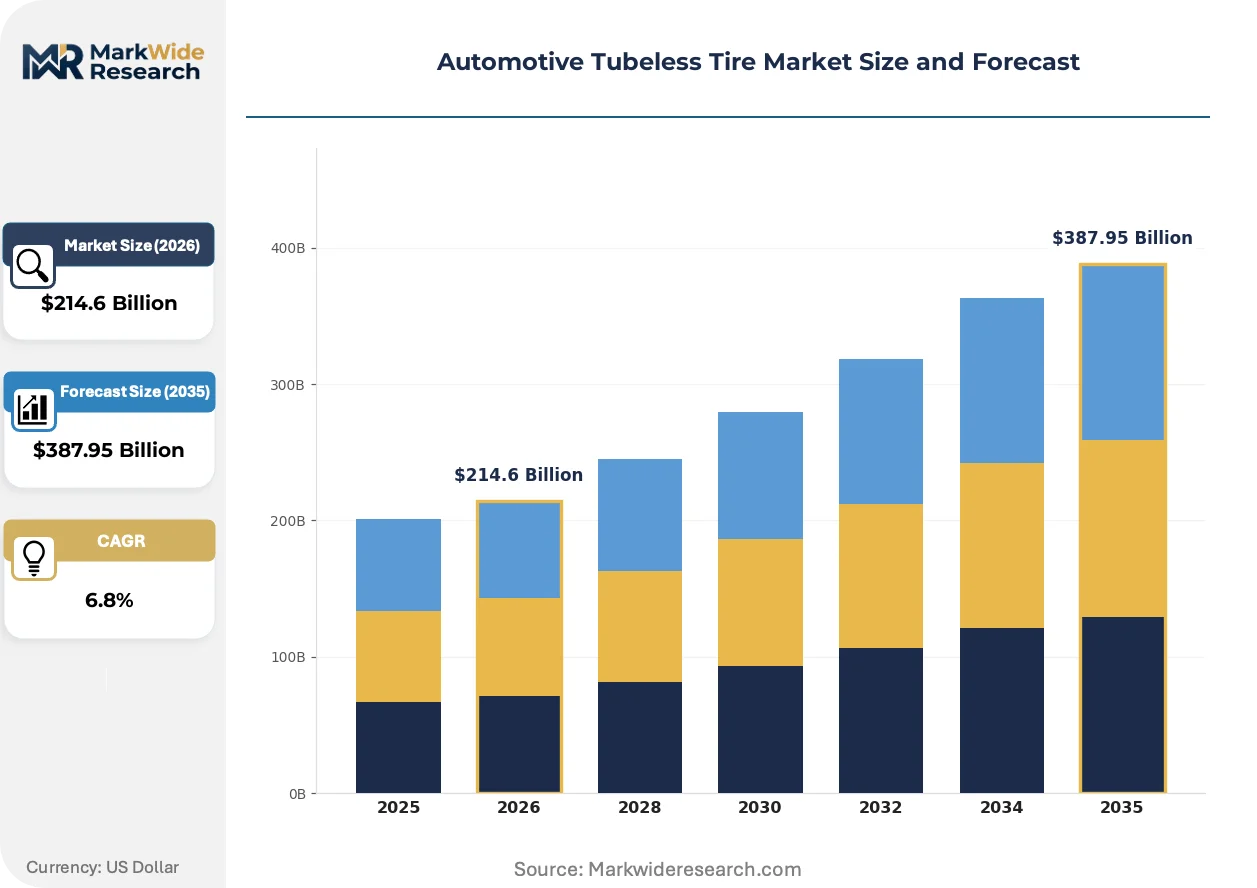
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $387.95 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Car, Light Truck, Motorcycle, Bus Tread Pattern: Symmetrical, Asymmetrical, Directional, Hybrid Size: 15 Inch, 16 Inch, 17 Inch, 18 Inch Distribution Channel: Online Retail, Tire Shops, Dealerships, Wholesalers |
| Companies Covered | Continental AG, Sumitomo Rubber Industries Ltd., Bridgestone Corporation, Yokohama Rubber Co., Ltd., Hankook Tire & Technology Co., Ltd., Michelin SCA, Pirelli & C. S.p.A., Cheng Shin Rubber Industry Co., The Goodyear Tire & Rubber Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Tubeless Tire Market Emerging Trajectories
Material science breakthroughs and regulatory carbon accounting are converging to redefine performance benchmarks and sourcing transparency across the tire value chain.
Airless architecture is expanding into commercial fleet trials after proving durability in off-highway applications. Heavy-duty pickup and last-mile delivery operators in North America are piloting non-pneumatic designs to eliminate downtime from punctures. This shift is compressing traditional replacement revenue cycles while opening subscription-based mobility service models.
REACH restrictions on polycyclic aromatic hydrocarbons in extender oils are forcing compound reformulation across European manufacturing. Suppliers are pivoting to naphthenic and bio-based alternatives, with passenger tire lines facing the steepest compliance deadlines. German and French testing houses are reporting extended homologation queues as manufacturers resubmit legacy formulations.
Fleet procurement departments are consolidating supplier relationships around total-cost-of-ownership metrics rather than unit pricing. Large logistics operators in China are negotiating direct contracts with Shandong manufacturers, bypassing traditional distribution layers. This disintermediation is most pronounced in the light truck segment where warranty terms and predictive maintenance integration determine contract awards.
Automotive Tubeless Tire Market Segmentation
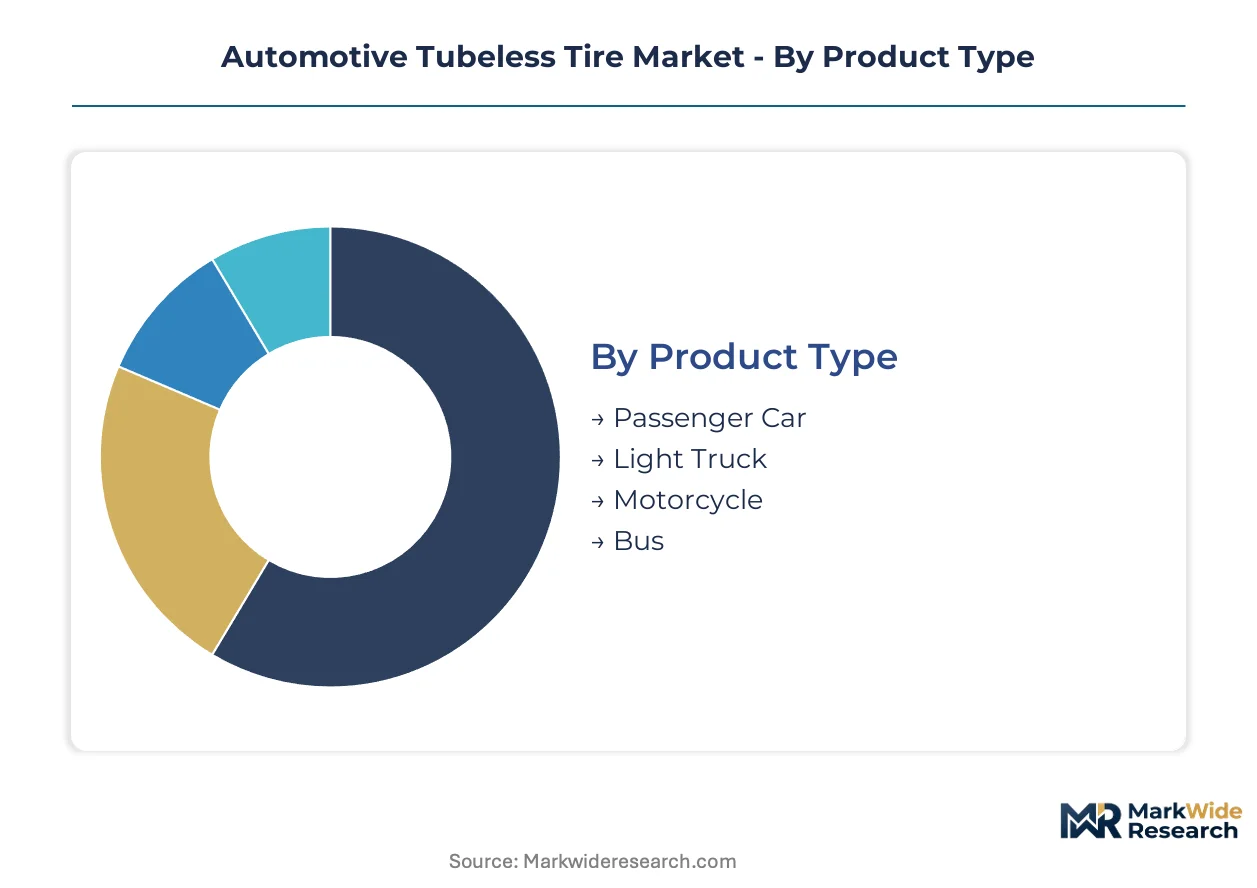
Tubeless tire procurement patterns diverge sharply across vehicle duty cycles, tread performance requirements, and fleet procurement sophistication. Segment boundaries are hardening around regulatory compliance tiers and total-cost-of-ownership metrics rather than legacy dimensional classifications.
Product Type:
Standardization dominates high-volume categories while specialty engineering commands premium positioning in load-rated and speed-rated variants.
- Passenger Car:Halobutyl liners and silica-silane tread compounds define the specification baseline for OEM fitment. China's Jiangsu corridor feeds assembly plants for domestic EV producers and European export channels, with wet-grip labeling under ECE R30 driving compound selection.
- Light Truck:Reinforced bead structures and higher load-index ratings accommodate battery-electric vehicle weight distribution shifts. North American fleet operators prioritize puncture resistance and extended warranty terms over unit pricing in direct procurement negotiations with manufacturers.
- Motorcycle:Bias-ply and radial constructions split by displacement class, with sport-touring segments demanding multi-compound tread zones.
- Bus:Retreadability and sidewall durability dominate specification sheets for municipal and intercity operators.
Most installed capacity flows through Passenger Car. Expansion is steepest in Light Truck.
Tread Pattern:
Climate exposure and driving duty determine pattern selection, with wet-market geographies imposing stricter performance verification protocols.
- Symmetrical:Uniform block design permits rotation in all four positions, extending tread life for cost-sensitive fleet operators. Volume concentrates in economy-tier replacement channels across price-sensitive markets.
- Asymmetrical:Distinct inner and outer shoulder compounds optimize dry cornering and wet evacuation simultaneously. Performance-tier OEM fitments for German and Japanese sport sedans specify these patterns exclusively.
- Directional:V-shaped grooves channel water at high speeds, dominating Nordic and Southeast Asian markets with pronounced monsoon exposure.
- Hybrid:Combines directional water evacuation with asymmetrical dry-grip zones for crossover vehicles.
Symmetrical patterns carry the highest unit volumes. Asymmetrical designs capture the widest margin spreads.
Size:
Rim diameter correlates with vehicle electrification status and unsprung mass sensitivity in chassis engineering.
- 15 Inch:Economy compact and subcompact vehicle fitments, with highest replacement frequency in emerging market parc structures.
- 16 Inch:Mid-size sedan and small crossover standard fitment, balancing ride comfort and rolling resistance optimization.
- 17 Inch:Premium compact and electric vehicle primary specification, where aerodynamic wheel covers integrate with tire sidewall geometry.
- 18 Inch:Performance and luxury segment entry point, with run-flat and self-sealing variants commanding substantial premiums.
16 Inch maintains the broadest vehicle coverage. 18 Inch is climbing the fastest on EV platform proliferation.
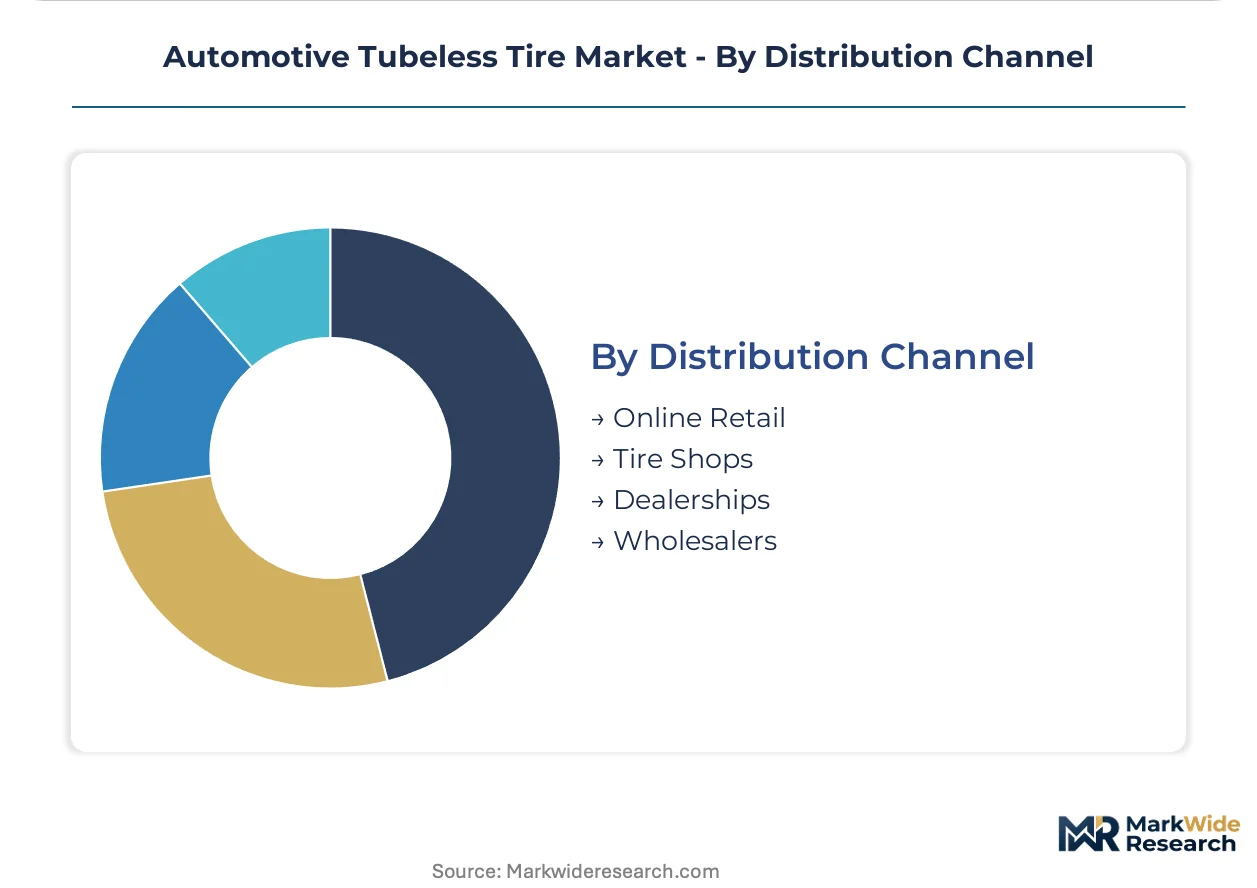
Distribution Channel:
Channel power is shifting from fragmented retail toward direct fleet contracting and integrated service platforms.
- Online Retail:Price transparency and fitment verification tools are capturing DIY replacement demand, though mounting complexity limits pure-play growth.
- Tire Shops:Independent and chain operators retain loyalty through speed of service and alignment capabilities, particularly in North American suburban corridors.
- Dealerships:OEM-captive distribution dominates warranty-period replacement and brand-loyal upgrade cycles.
- Wholesalers:Volume aggregation for independent repair networks and regional distributors maintains relevance in fragmented aftermarket structures.
Tire Shops process the highest transaction velocity. Online Retail is expanding most quickly on mobile fitment-assurance technology deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compound formulation chemists and tire design engineers concentrate in Germany's industrial belt, China's eastern manufacturing corridors, and the US Midwest automotive triangle. These talent pools anchor regional competitive advantages in silica-silane research, halobutyl liner production, and EV-specific load-index engineering.
China
MIIT energy-efficiency labeling and GB standard compliance requirements are tightening import access protocols for foreign manufacturers. The Jiangsu-Shandong corridor hosts concentrated tire production clusters feeding domestic EV assembly plants and European export channels. Shandong manufacturers negotiate direct procurement contracts with logistics operators, bypassing traditional distribution layers.
Germany
KBA homologation queues are extending as manufacturers resubmit legacy formulations under REACH polycyclic aromatic hydrocarbon restrictions. Continental AG anchors silica-silane research capabilities in Hanover. The ECE R30 and R54 regulatory framework governs passenger and commercial tire certification across EU member states.
United States
NHTSA Federal Motor Vehicle Safety Standard 109 maintains performance benchmarks for tire construction and endurance. Heavy-duty pickup and last-mile delivery operators pilot non-pneumatic designs to eliminate puncture-related downtime. The US Midwest retains deep engineering talent in bead-structure reinforcement and load-index specification development.
India
PLI scheme production-linked incentives for advanced automotive components are drawing greenfield tire capacity to Tamil Nadu and Gujarat. BIS certification requirements add compliance layers for domestic market access. Fleet procurement departments consolidate supplier relationships around total-cost-of-ownership metrics rather than unit pricing.
Japan
METI industrial policy supports next-generation mobility material research including airless architecture development. Yokohama and Osaka house specialized compound formulation expertise for multi-compound tread zones. JIS standards alignment with ECE regulations facilitates export market access for domestic manufacturers.
Automotive Tubeless Tire Market Vendor Landscape
Top-tier vendors anchor premium OEM fitment channels, while mid-scale compounders and regional wholesalers occupy volume replacement segments. The vendor base stratifies across three archetypes: integrated rubber-chemical conglomerates with captive silica research, tire-specialist manufacturers with captive automaker relationships, and contract compounders serving private-label distributors. Capacity expansion and strategic technology licensing represent the dominant competitive moves as stakeholders address homologation timeline compression.
Among European-anchored conglomerates, Continental AG and Michelin SCA exemplify integrated research-to-manufacture positioning, while Bridgestone Corporation represents the Japanese tire-specialist archetype with deep automaker supply relationships. These three entities occupy positions across the premium-tier vector where wet-grip ratings, rolling-resistance certification, and warranty terms determine contract awards rather than raw price positioning. Their collective presence shapes compound formulation standards and airless architecture development timelines across the supply base.
| Leading Market Players |
|---|
| Continental AG |
| Sumitomo Rubber Industries Ltd. |
| Bridgestone Corporation |
| Yokohama Rubber Co., Ltd. |
| Hankook Tire & Technology Co., Ltd. |
| Michelin SCA |
| Pirelli & C. S.p.A. |
| Cheng Shin Rubber Industry Co. |
| The Goodyear Tire & Rubber Company |
| Others |
Supply Flow & Price Mechanics
Electric vehicle OEM procurement departments concentrate purchasing power around total-cost-of-ownership metrics, compressing traditional spot-market pricing and favoring long-term contract structures with embedded service bundles. This buyer concentration shifts margin capture toward manufacturers with captive silica-silane research and direct fleet relationships.
Pricing Analysis
The bundled-versus-unbundled service split separates contract structures in this market. Premium tiers wrap installation, alignment, and predictive maintenance into per-kilometer subscription models, while economy channels transact on unit price alone. Price differentiation rests on wet-grip certification grades and warranty term length. Cost compression in the standard tier intensifies as Shandong manufacturers bypass distribution layers. Fleet operators show lowest price sensitivity; DIY replacement buyers exhibit highest.
Supply Chain Analysis
India's PLI scheme local-content thresholds are reshaping sourcing patterns for manufacturers serving that market. Raw material supply concentrates in Thailand, Indonesia, and Vietnam for natural rubber, with China and Germany for synthetic polymers and silica fillers. The chain draws from petroleum-derived feedstocks and agricultural latex, exposing margins to commodity volatility. Tariff exposure on Chinese finished tires into Europe and North America looms as the dominant structural risk. Distribution runs through captive OEM supply agreements and direct fleet contracting, with independent wholesale layers losing share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by irreversible fleet electrification and replacement-cycle predictability. OEM procurement consolidation and regulatory compliance layering create durable barriers for entrenched positions.
For Market Incumbents: To counter airless architecture disruption from Michelin's Tweel and similar non-pneumatic designs, prioritize backward integration into halobutyl liner production and silica-silane coupling research. Lock in direct supply relationships with battery-electric vehicle platform engineers before load-index specifications crystallize. Certify compounds early under EU Green Deal embedded carbon requirements to capture premium positioning ahead of carbon-border adjustments. For New Entrants and Emerging Players: Fleet management data services represent the most penetrable white-space target, with sensor-embedded intelligent tires opening subscription revenue streams. India's Tamil Nadu and Gujarat greenfield corridors offer geographic entry points under PLI scheme incentives. Partner with last-mile delivery operators on puncture-resistance pilot programs to establish reference accounts before scaling manufacturing footprint. For Investors and Strategic Acquirers: Integrated tire-chemical conglomerates are the most active acquirer in this space, seeking captive silica research and OEM supply relationships. The long-term viability window favors compound formulation specialists with REACH-compliant bio-based alternatives in their pipelines. Watch for homologation timeline compression as the inflection signal—extended ECE R30 and GB standard testing queues indicate regulatory friction that favors scaled players with dedicated certification resources.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Halobutyl Production | Captive liner supply secures margin control against raw material volatility. |
| Silica-Silane Coupling R&D Expansion | Continental AG's Hanover research complex demonstrates premium positioning through formulation leadership. |
| Direct Fleet Contracting Bypass | Shandong manufacturers negotiating with Chinese logistics operators disintermediate traditional wholesale layers. |
| EU Green Deal Carbon Certification | First-mover status under incoming carbon-border adjustments commands OEM procurement preference. |
| Sensor-Embedded Intelligent Tire Launch | RFID and pressure-monitoring convergence opens data-service revenue beyond commodity tire sales. |
Methodological Framework
Multiple input streams — procurement director interviews at fleet operators, compound formulation chemist consultations, and regulatory affairs specialist dialogues — were reconciled with secondary validation from MIIT energy-efficiency labeling databases, ECE R30 and R54 homologation records, and customs trade flows through the Jiangsu-Shandong corridor. Bottom-up tire production capacity tallies and top-down vehicle parc replacement-cycle modeling were cross-checked for triangulation.
Data-stream reconciliation across vehicle class, propulsion architecture, tread pattern specification, and regional production cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume builds and value-per-unit trends. Forecast inputs incorporated EV platform weight distribution shifts and REACH aromatic oil reformulation timelines.
Revisions become necessary when battery-electric vehicle load-index specifications diverge from current projections, natural rubber supply disruptions from Southeast Asian climate events materialize, or airless architecture commercialization accelerates beyond pilot phases. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Automotive Automatic Tire Inflation System (ATIS) Market
Tires and Wheels
Kuwait Tyres Market
Tires and Wheels
Re-Tread Tires Market
Tires and Wheels
Asia Pacific Two Wheeler Tire Market
Tires and Wheels
Automotive Summer Tire Market
Tires and Wheels
Performance Tires Market
Tires and Wheels
Wheel Cover Market
Tires and Wheels
Automotive Wheel Coating Market
Tires and Wheels
Cargo Bike Tire Market
Tires and Wheels
Truck and Bus Radial (TBR) Tire Market
Tires and Wheels
All Weather Tire Market
Tires and Wheels
Southeast Asian Tire Market
Tires and Wheels
Automotive Wheel Alignment System Market
Tires and Wheels
Steel Tire Cord Market
Tires and Wheels
Magnesium Wheel Market
Tires and Wheels
Automotive Green Tires Market