
 Spectral Sensor Market | 2026-2036
Spectral Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Spectral Sensor Market Insights
The spectral sensor landscape is recalibrating around a widening capability gap between research-grade hyperspectral instruments and cost-optimized multispectral modules for commercial drones. Hamamatsu Photonics leverages its photonics foundry depth to sustain dominance in high-sensitivity detector arrays for laboratory and medical applications. Headwall Photonics anchors its position in airborne and satellite remote sensing through diffractive optical designs that compete on spectral purity in defense and environmental monitoring contracts.
A spectral sensor captures electromagnetic radiation across discrete wavelength bands to identify material composition through characteristic absorption or reflectance signatures, with modern devices achieving spectral resolutions below 10 nanometers using compact grating or filter-on-chip architectures. These instruments enable non-destructive chemical analysis in industrial process control, agricultural yield optimization, and clinical diagnostics where real-time molecular identification replaces slower wet chemistry methods. Hyperspectral sensors command premium positioning in defense and satellite payloads where full contiguous spectrum coverage justifies unit costs above commercial multispectral alternatives. RGB and near-infrared sensors dominate volume shipment in precision agriculture drones where simpler band combinations satisfy normalized difference vegetation index calculations at mass-market price points. Imaging spectroscopy technology leads R&D investment as semiconductor integration pushes detector arrays toward wafer-scale manufacturing cost structures.
FDA 510(k) clearance requirements shape healthcare spectral sensor development timelines by mandating clinical validation against predicate devices for tissue oximetry and wound assessment applications. EPA water quality monitoring protocols and EU Green Deal agricultural sustainability targets are expanding multispectral sensor procurement in environmental compliance and carbon sequestration verification programs. ISO 9001 and IEC 60825 laser safety standards govern manufacturing consistency and optical hazard classification for photonics-integrated spectral systems across aerospace and industrial end markets. Stakeholders must monitor how REACH substance restrictions on rare-earth dopants in detector materials reshape supply chain sourcing for high-performance near-infrared arrays.
Market Dynamics
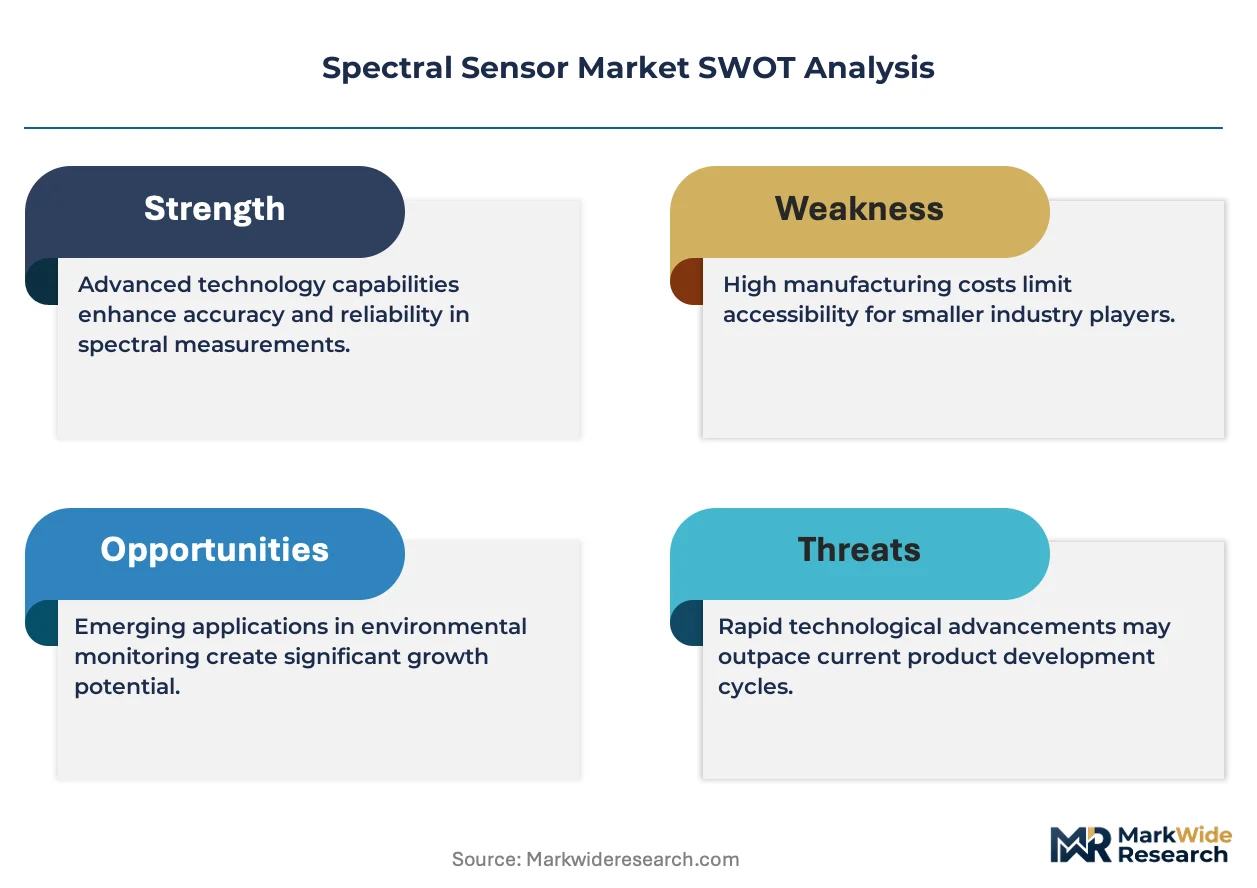
Semiconductor integration is compressing detector array costs while fragmenting the vendor landscape between photonics foundries and modular system integrators, forcing specialization decisions across the value chain.
Growth Catalysts
- EU Green Deal agricultural mandates:Carbon sequestration verification protocols in member states are mandating multispectral deployment for soil health monitoring, expanding procurement beyond traditional yield optimization.
- Inline food inspection:Germany's industrial automation corridor is absorbing high-speed near-infrared sensors for real-time contamination detection, replacing batch laboratory testing.
- Filter-on-chip architectures:Wafer-scale manufacturing of compact grating designs is enabling drone-integrable hyperspectral modules previously restricted to satellite payloads.
Market Restraints
- Rare-earth dopant concentration:REACH substance restrictions on europium and ytterbium sourcing are constraining near-infrared array production, with limited qualified suppliers outside China.
- Clinical validation timelines:FDA 510(k) clearance pathways for tissue oximetry devices impose 18-24 month development cycles that deter mid-cap entrants from healthcare applications.
- Grating-based hyperspectral cost floors:Diffractive optical designs require precision diamond-turned substrates that resist economies of scale below aerospace and defense order volumes.
Strategic Opportunities
- Brazil precision agriculture expansion:Cerrado and Mato Grosso farming cooperatives are deploying multispectral-enabled variable-rate input systems with limited incumbent vendor presence.
- Wound assessment diagnostics:Hyperspectral tissue oxygenation mapping is penetrating outpatient care centers as Medicare reimbursement codes expand for chronic wound management.
- AI-integrated edge processing:On-chip neural network accelerators combined with CMOS spectral detectors are enabling real-time material classification without cloud connectivity.
Industry Challenges
- Photonics assembly skill scarcity:Precision alignment of detector arrays to micro-optics requires technicians trained in semiconductor cleanroom protocols, with limited vocational pipeline outside East Asian manufacturing hubs.
- Interoperability with legacy SCADA:Food processing plants running 1990s-era process control systems face integration complexity when retrofitting inline spectral quality stations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spectral Sensor Market |
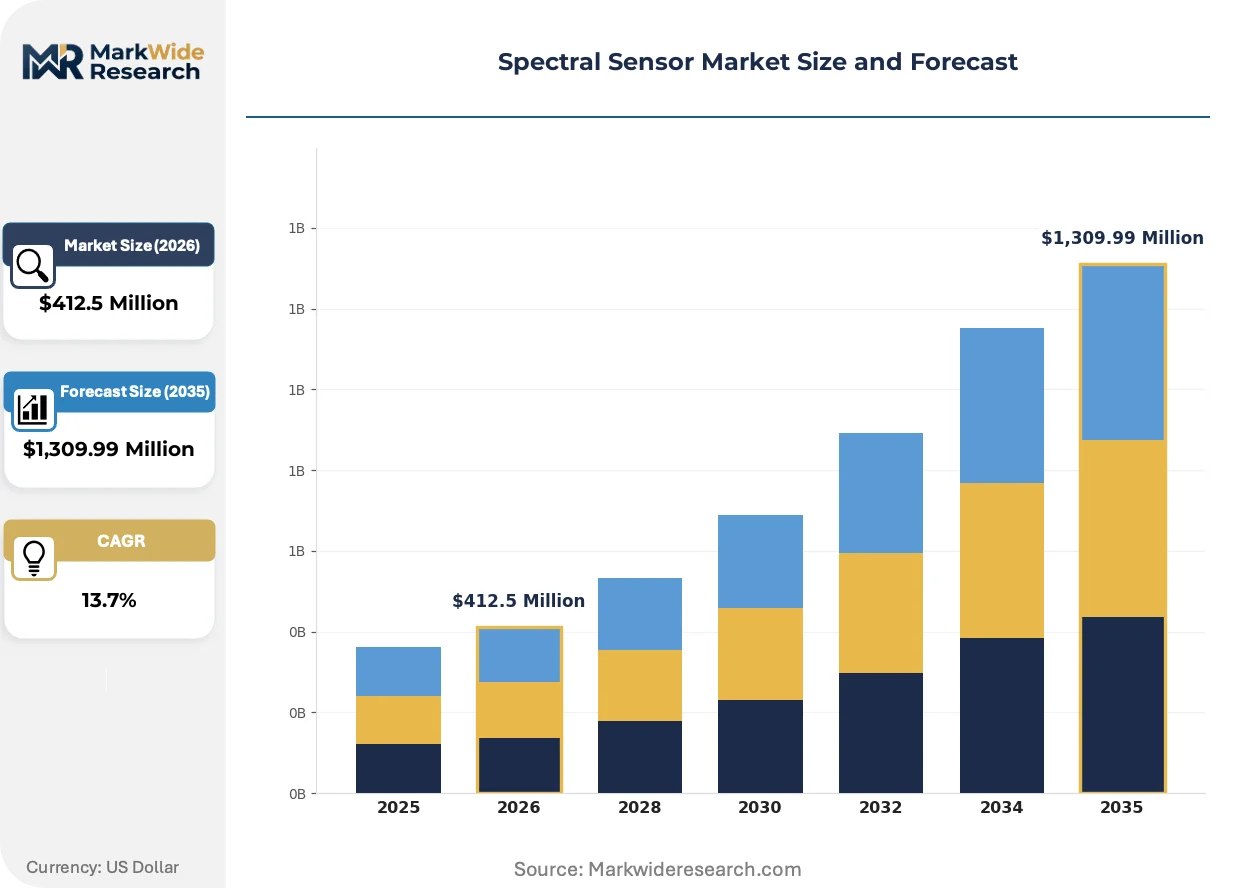
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,309.99 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hyperspectral Sensors, Multispectral Sensors, RGB Sensors, Near-Infrared Sensors Application: Agriculture, Environmental Monitoring, Food Quality Analysis, Healthcare End User: Aerospace, Defense, Manufacturing, Research Institutions Technology: Optical Detection, Remote Sensing, Imaging Spectroscopy, Photonics |
| Companies Covered | Teledyne Technologies, Headwall Photonics, Hamamatsu Photonics, Ocean Insight, BaySpec, Corning Incorporated, FLIR Systems, Imec, Specim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spectral Sensor Market Trends and Innovations
Computational spectroscopy and edge AI are collapsing the traditional trade-off between spectral resolution and real-time processing, enabling deployment scenarios that previously demanded laboratory infrastructure.
Filter-on-chip CMOS architectures are unifying photodetection and wavelength discrimination in single-die designs. Agricultural drone OEMs in the United States and Brazil are adopting these integrated modules for sub-10-nanometer resolution at mass-market price points. This unification is compressing the addressable market for discrete optical component suppliers while expanding total deployable unit volumes.
EU MDR classification rules are tightening performance documentation requirements for healthcare spectral devices. Manufacturers must now submit clinical evidence against predicate devices for tissue characterization claims, extending regulatory timelines. Wound assessment and surgical guidance applications in Germany and France are experiencing the steepest compliance cost increases.
Equipment-as-a-service contracts are displacing capital purchase models in food quality inspection. German meat processing cooperatives are subscribing to per-tonne pricing for inline near-infrared fat analysis, transferring obsolescence risk to sensor vendors. This shift is most visible in Bavaria's dairy and protein processing clusters, where capex constraints favor operational expenditure structures.
Spectral Sensor Market Segmentation
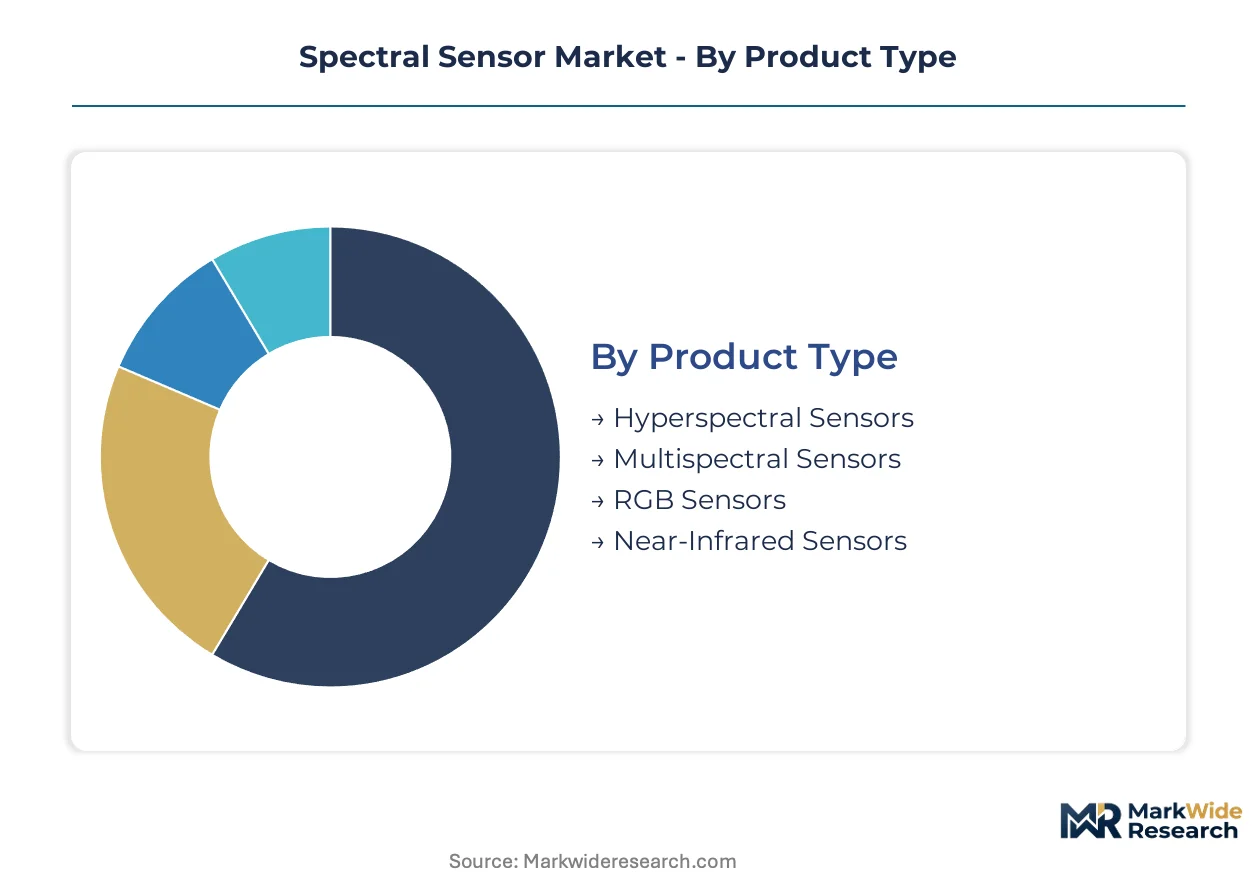
Spectral sensor procurement patterns diverge sharply across application contexts, with precision agriculture demanding volume-optimized modules while defense and satellite programs absorb premium hyperspectral instruments. Understanding these segment boundaries clarifies where semiconductor integration compresses costs versus where optical purity sustains pricing power.
Product Type:
Supply concentration in photonics foundries shapes competitive dynamics across detector architectures, with wafer-scale CMOS integration favoring certain spectral configurations over legacy designs.
- Hyperspectral Sensors:Full contiguous spectrum coverage below 10-nanometer resolution enables material fingerprinting for defense reconnaissance and satellite-based mineral mapping. Demand concentrates in classified aerospace programs and environmental monitoring contracts where spectral purity justifies unit costs exceeding commercial alternatives by an order of magnitude. Grating-based diffractive designs from specialized optical houses dominate this tier.
- Multispectral Sensors:Discrete band filtering—typically 4-12 channels—balances diagnostic capability with manufacturability for agricultural drones and inline process control. Filter-on-chip architectures are collapsing costs for Brazil's Cerrado farming cooperatives and US Midwest precision agriculture operators deploying normalized difference vegetation index calculations across thousands of hectares.
- RGB Sensors:Three-channel visible spectrum modules serve as entry-level crop health indicators for cost-constrained drone fleets. Mass-market Chinese OEMs supply these units to Brazilian and US agricultural service providers.
- Near-Infrared Sensors:Single-band or limited multi-band devices target moisture and protein analysis in Germany's dairy processing corridor. REACH restrictions on europium and ytterbium dopants constrain high-sensitivity array production.
Multispectral sensors absorb the bulk of installed capacity; near-infrared sensors are expanding most quickly in food quality applications.
Application:
Cost tier stratification separates laboratory-validated healthcare deployments from field-hardened agricultural systems, with regulatory burden as the primary dividing mechanism.
- Agriculture:Variable-rate input systems across Brazil's Mato Grosso and US Corn Belt rely on drone-mounted multispectral units for nitrogen stress detection and irrigation scheduling. Equipment-as-a-service pricing models are displacing capital purchases among mid-size farming cooperatives.
- Environmental Monitoring:EPA water quality protocols and EU Green Deal carbon sequestration verification mandate standardized spectral measurement for soil organic carbon quantification. Satellite and fixed-wing platforms dominate deployment.
- Food Quality Analysis:Real-time fat, protein, and contamination detection in German meat processing plants demands high-speed near-infrared throughput. Inline installations replace batch laboratory testing in Bavaria's protein processing clusters.
- Healthcare:Tissue oximetry and chronic wound assessment require FDA 510(k) clearance or EU MDR conformity, extending development cycles. Medicare reimbursement code expansion for outpatient wound centers is stimulating hyperspectral oxygenation mapping adoption.
Agriculture commands the greatest unit volumes; healthcare represents the steepest margin tier after regulatory compliance costs.
End User:
Customer procurement sophistication varies from defense acquisition offices with decade-long qualification horizons to research institutions with grant-driven replacement cycles.
- Aerospace:Satellite payload integrators specify radiation-hardened detector arrays with thermal stability across orbital temperature swings. Long qualification timelines favor incumbent photonics suppliers with heritage flight programs.
- Defense:Hyperspectral reconnaissance systems for airborne and unmanned platforms require ITAR-controlled component sourcing. Diffractive optical designs from specialized vendors compete on spectral purity in classified procurement.
- Manufacturing:German automotive and food processing plants integrate inline spectral quality stations, facing interoperability challenges with 1990s-era SCADA infrastructure.
- Research Institutions:University laboratories and national research centers drive early adoption of computational spectroscopy and AI-integrated edge processing architectures.
Defense absorbs the highest per-unit expenditure; manufacturing is climbing the fastest as Industry 4.0 retrofit programs accelerate.
Technology:
Maturity gradients separate established optical detection methods from emerging semiconductor-integrated approaches reshaping cost structures.
- Optical Detection:Discrete grating and filter architectures persist in high-performance applications where spectral resolution cannot be compromised. Diamond-turned substrate requirements resist economies of scale.
- Remote Sensing:Airborne and satellite platforms leverage atmospheric correction algorithms and georeferencing capabilities for agricultural and mineral survey contracts.
- Imaging Spectroscopy:Spatial-spectral data cubes enable pixel-level material classification for defense intelligence and precision agriculture. CMOS integration trends are pushing this capability toward mass-market price points.
- Photonics:Foundry-based III-V semiconductor fabrication and silicon photonics integration enable wafer-scale manufacturing of detector arrays. Cleanroom assembly skill scarcity constrains capacity expansion outside East Asian manufacturing hubs.
Optical detection retains the largest installed base; photonics integration is gaining share fastest as semiconductor economics transform sensor economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich's industrial automation corridor anchors near-infrared sensor demand for inline food quality inspection, while regulatory pressure across multiple jurisdictions reshapes procurement patterns for spectral instrumentation.
United States
Midwest precision agriculture operators in Iowa and Illinois deploy multispectral drones for nitrogen stress detection across corn and soybean acreage. EPA water quality monitoring protocols mandate standardized spectral measurement for nutrient runoff verification. FDA 510(k) clearance timelines in Massachusetts and California medical device clusters extend development cycles for tissue oximetry applications.
Germany
Bavarian meat processing cooperatives subscribe to equipment-as-a-service contracts for real-time fat analysis, transferring obsolescence risk to vendors. EU MDR classification rules tighten performance documentation for healthcare spectral devices in Berlin-Brandenburg medical technology hubs. Baden-Württemberg automotive suppliers integrate inline quality stations facing SCADA interoperability challenges.
Brazil
Cerrado and Mato Grosso farming cooperatives deploy variable-rate input systems with multispectral-enabled irrigation scheduling across soybean and cotton operations. ANVISA regulatory pathways for imported medical devices create compliance complexity for tissue characterization equipment. São Paulo's agribusiness service providers absorb volume-optimized RGB and multispectral modules from mass-market OEMs.
China
Yangtze River Delta photonics foundries manufacture CMOS-integrated detector arrays for export-oriented drone OEMs. MIIT standards for semiconductor equipment govern wafer-scale production protocols in Shanghai and Suzhou manufacturing parks. Pearl River Delta assembly hubs face cleanroom technician scarcity as production scales toward consumer electronics volumes.
Japan
Kanto region research institutions drive early adoption of computational spectroscopy and AI-integrated edge processing architectures. METI funding programs for photonics manufacturing sustain domestic detector array production against cost-optimized Chinese alternatives. Osaka-based industrial automation suppliers export inline inspection systems to ASEAN food processing markets.
Spectral Sensor Market Competitive Landscape
Premium-margin players sit above commodity-margin players across spectral resolution and regulatory certification tiers, with photonics foundries commanding pricing power in high-sensitivity arrays while modular integrators compete on unit cost. The vendor landscape fragments between semiconductor-integrated CMOS specialists and legacy optical houses maintaining diffractive grating expertise. Three archetypes dominate: photonics foundries with captive wafer-scale manufacturing, specialized optical designers serving aerospace and defense qualification timelines, and system integrators assembling commodity multispectral modules for agricultural drone OEMs. Capacity expansion in East Asian detector fabrication and strategic partnerships between sensor vendors and drone platform manufacturers represent the dominant competitive moves.
Within the photonics foundry tier, Hamamatsu Photonics and Teledyne Technologies exemplify scale-driven players with heritage in high-sensitivity detector arrays for laboratory and medical applications. Headwall Photonics occupies a position among specialized optical designers anchored in diffractive architectures for airborne and satellite remote sensing contracts. These three companies represent the spectrum from semiconductor-integrated volume manufacturing to precision optical engineering for qualification-intensive aerospace programs.
| Leading Market Players |
|---|
| Teledyne Technologies |
| Headwall Photonics |
| Hamamatsu Photonics |
| Ocean Insight |
| BaySpec |
| Corning Incorporated |
| FLIR Systems |
| Imec |
| Specim |
| Others |
Pricing and Supply Chain Analysis
Captive wafer-scale manufacturing in East Asian photonics foundries anchors both supply security and pricing power for high-sensitivity detector arrays, while modular system integrators compete on unit cost without upstream control over europium and ytterbium dopant sourcing.
Pricing Analysis
Outcome-based equipment-as-a-service contracts now anchor pricing for German meat processing cooperatives subscribing to per-tonne fat analysis rather than capital purchase. Pricing stratifies across FDA-cleared medical tiers, ITAR-controlled defense tiers, and uncertified agricultural tiers, with certification level commanding the widest spreads. Cost compression in multispectral drone modules intensifies as filter-on-chip CMOS architectures collapse grating-based cost floors. Agricultural service providers in Brazil exhibit the highest price sensitivity; satellite payload integrators the lowest.
Supply Chain Analysis
Europium and ytterbium supply for near-infrared detector arrays rests on Chinese rare-earth processing concentration, with limited qualified alternatives under REACH substance restrictions. Photoresist and specialty gases for III-V semiconductor fabrication draw from Japanese and South Korean chemical producers. Single-source vulnerability in rare-earth dopant sourcing constrains near-infrared array expansion outside defense order volumes. Distribution runs through photonics foundry direct sales for premium tiers and drone OEM channel partnerships for volume tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over detector wafer fabrication determines margin capture across healthcare and defense tiers.
For Market Incumbents: Cement foundry capacity advantages by expanding cleanroom technician training pipelines outside East Asian hubs to address photonics assembly skill scarcity. Deepen backward integration into rare-earth dopant recycling to offset REACH sourcing constraints on europium and ytterbium. Lock in long-term ITAR-controlled component supply agreements before defense qualification timelines extend further. For New Entrants and Emerging Players: Capture white-space in Brazil's Cerrado farming cooperatives where variable-rate input systems lack established vendor relationships. Penetrate outpatient wound assessment centers as Medicare reimbursement codes expand for hyperspectral tissue oxygenation mapping. Lead with AI-integrated edge processing architectures that eliminate cloud dependency for real-time material classification. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by photonics foundries seeking diffractive optical design capabilities for defense and satellite contracts. Long-term viability favors targets with heritage flight program qualifications and ITAR-compliant supply chains. Watch for FDA 510(k) clearance backlog resolution as an inflection signal for healthcare spectral device deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Filter-on-Chip CMOS Integration | Enables drone-mountable hyperspectral modules previously restricted to satellite payloads. |
| Equipment-as-a-Service Transition | Transfers obsolescence risk to vendors in Bavarian meat processing cooperatives. |
| Rare-Earth Dopant Recycling Investment | Offsets REACH restrictions on europium and ytterbium sourcing for near-infrared arrays. |
| AI-Integrated Edge Processing Development | Combines on-chip neural accelerators with CMOS detectors for cloud-independent classification. |
| Cleanroom Technician Training Expansion | Addresses photonics assembly skill scarcity outside East Asian manufacturing hubs. |
Research Methodology
Independent corroboration across photonics foundry executives, agricultural drone OEM procurement leads, and FDA regulatory affairs specialists underwrites the qualitative findings. Secondary validation drew from EPA water quality monitoring protocols, EU MDR classification guidance documents, and customs trade data for rare-earth dopant flows. Bottom-up unit economics for detector array production were triangulated against top-down market sizing from satellite payload and precision agriculture procurement databases.
The forecast window anchored historical reference periods to established semiconductor manufacturing cost curves and regulatory clearance timeline distributions. Segmentation modeling spanned product architecture, application vertical, end-user procurement sophistication, and technology maturity tier across the projection horizon. CAGR derivation incorporated filter-on-chip adoption rates, REACH restriction enforcement patterns, and equipment-as-a-service contract penetration in German food processing clusters.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare-earth supply chain reconfiguration and FDA 510(k) backlog resolution. Forecasts reflect documented assumptions on CMOS integration timelines and agricultural drone OEM consolidation. A small set of triggers—REACH enforcement intensity, Medicare reimbursement code expansion, and ITAR qualification timeline shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Multi Touch Sensing Market
Sensors and Controls
China Sensors Market
Sensors and Controls
US Temperature Sensors Market
Sensors and Controls
Micropump Market
Sensors and Controls
Echo Sounder Market
Sensors and Controls
MEMS Accelerometer and Gyroscope Market
Sensors and Controls
Ingestible Sensor Market
Sensors and Controls
Doppler Wind Lidar System Market
Sensors and Controls
Body Worn Temperature Sensors Market
Sensors and Controls
Embedded Biometric Sensor Market
Sensors and Controls
DCT Mechatronic Control Unit Market
Sensors and Controls
Piezoelectric MEMS Resonators Market
Sensors and Controls
Laser Sensor Market
Sensors and Controls
Temperature Controller Market
Sensors and Controls
SCR Dosing Control Modules Market
Sensors and Controls
Global Radar Sensor Market