
 Asia-Pacific Industrial Control System Market | 2026-2036
Asia-Pacific Industrial Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Industrial Control System Market Outlook
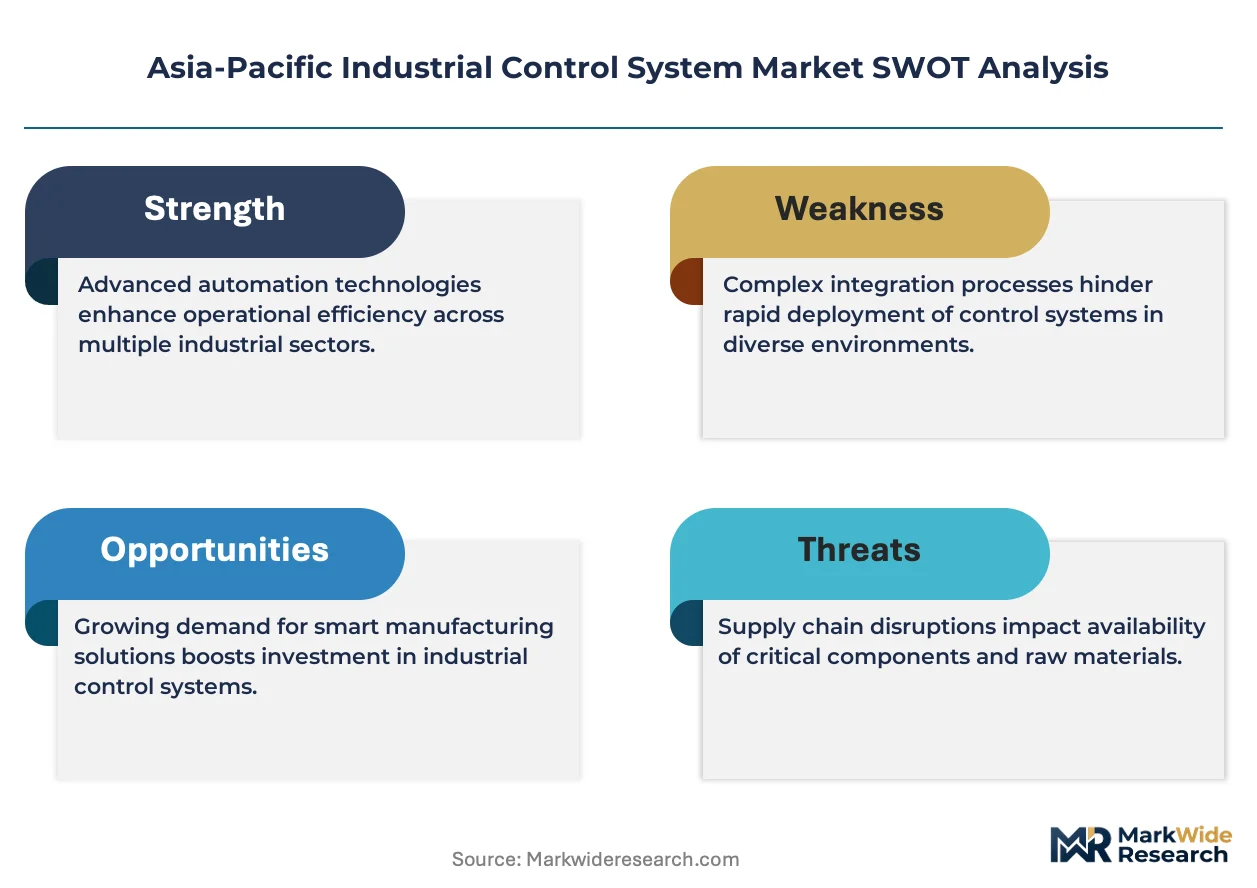
High-availability redundant controller specifications is unwinding legacy procurement patterns across the Asia-Pacific Industrial Control System Market. Siemens AG leverages its TIA Portal ecosystem to anchor automation projects across Chinese automotive plants. ABB Ltd competes through its Ability platform, which sustains deep integration between robotics and process control. Mitsubishi Electric Corporation dominates Japanese precision manufacturing with its MELSEC controller line, occupying niche segments where nanosecond response times matter.
An industrial control system comprises networked hardware and software components that monitor, regulate, and automate industrial processes through real-time data acquisition with millisecond-level response requirements. These systems execute closed-loop control across temperature, pressure, flow, and motion parameters to maintain operational continuity in continuous and batch manufacturing environments. PLC technology leads capital deployment in discrete manufacturing across the region, while DCS architectures command premium pricing in petrochemical complexes where cascade control strategies govern multi-variable processes. Cloud-hosted deployment is expanding fastest among mid-tier manufacturers in Vietnam and Indonesia seeking to bypass heavy on-premises infrastructure investments.
Japan's METI enforces JIS standards for functional safety in programmable controllers, while China's MIIT mandates cybersecurity classification reviews for critical information infrastructure operators deploying foreign-origin systems. India's CEA issues grid connectivity regulations that shape controller specifications for power sector deployments. Stakeholders must weigh localization requirements against technology access when configuring regional supply strategies.
Market Dynamics
China's MIIT cybersecurity classification reviews for critical information infrastructure operators are forcing foreign-origin system suppliers to reconfigure hardware architectures and data residency protocols across their Asia-Pacific deployments.
Growth Catalysts
- Automotive assembly automation:Southeast Asian manufacturing corridors are expanding robotic welding and paint-shop controller installations to serve electric vehicle battery pack production lines.
- MIIT cybersecurity mandates:China's tightening compliance requirements for foreign suppliers are accelerating domestic controller certification programs and joint-venture localization partnerships.
- Pharmaceutical corridor concentration:Demand is concentrating in India's manufacturing zones near Hyderabad and Mumbai, where batch process automation and sterile environment controls require validated DCS architectures.
Market Restraints
- Semiconductor component volatility:Industrial-grade FPGA and ASIC sourcing faces allocation constraints from Taiwan-based foundry concentration, extending PLC lead times.
- Legacy protocol fragmentation:Proprietary fieldbus standards from Japanese and European vendors create interoperability friction in brownfield integration projects.
- Skill scarcity in industrial cybersecurity:Certified ICS security practitioners remain concentrated in Singapore and Japan, constraining deployment velocity in Vietnam and Indonesia.
Strategic Opportunities
- Cloud-hosted deployment bypass:Mid-tier Vietnamese and Indonesian manufacturers are adopting subscription-based SCADA to circumvent heavy on-premises capital requirements.
- Dual-carbon policy alignment:China's MEE emissions monitoring mandates are creating demand for energy-optimized controller configurations in steel and cement plants.
- Edge-AI convergence:Machine vision and predictive maintenance algorithms are migrating onto hardened edge controllers, reducing latency for Japanese precision machining applications.
Industry Challenges
- Certification timeline compression:India's CEA grid connectivity regulations require extended type-testing for power sector controllers, delaying project commissioning.
- Brownfield integration complexity:Decades-old MELSEC and S7-300 installations in Japanese and Korean automotive plants resist seamless migration to Ethernet-based architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Industrial Control System Market |
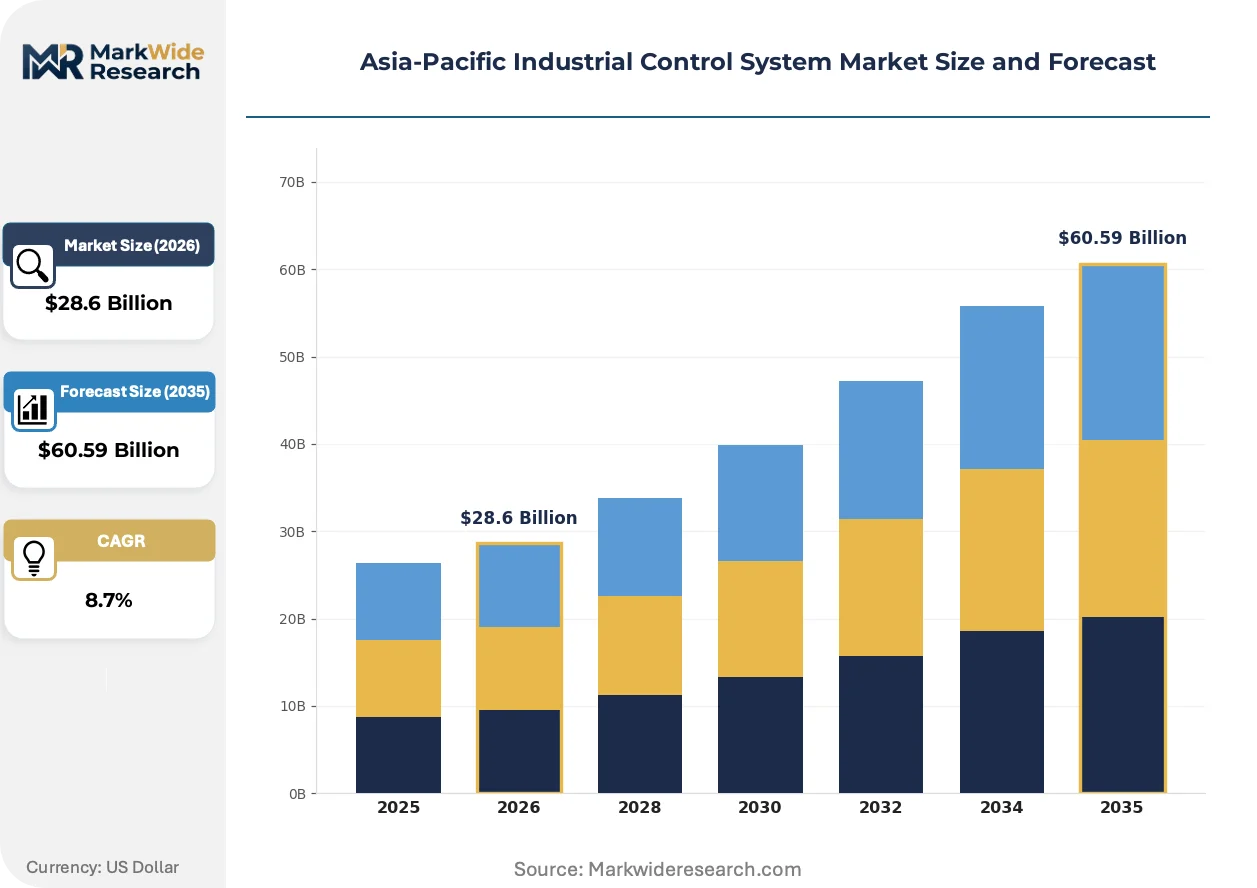
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: SCADA, DCS, PLC, HMI End User: Manufacturing, Energy, Transportation, Chemical Deployment: On-Premises, Cloud-Hosted, Hybrid, Remote Component: Sensors, Controllers, Actuators, Software |
| Companies Covered | Siemens AG, ABB Ltd, Honeywell International Inc, OMRON Corporation, Schneider Electric, Mitsubishi Electric Corporation, Rockwell Automation Inc, Yokogawa Electric Corporation, Emerson Electric Co, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Industrial Control System Market Strategic Shifts
Real-time deterministic networking is displacing legacy fieldbus hierarchies across Asia-Pacific factory floors, while regulatory pressure on data sovereignty accelerates edge computing localization.
Time-sensitive networking (TSN) over standard Ethernet is miniaturizing the physical layer of industrial communication, collapsing separate motion-control and process-control networks into unified infrastructures. Automotive plants in Thailand and China are adopting TSN-enabled remote I/O modules to synchronize robotic cells with sub-millisecond precision. This convergence is compressing switch hardware counts and simplifying cabling topologies in greenfield assembly facilities.
Japan's METI enforcement of updated JIS functional safety standards for programmable controllers is mandating redundant processor architectures in automotive and semiconductor fabrication deployments. Manufacturers must now document fault-tolerant design evidence through third-party certification bodies before operational approval. Korean battery cell production lines are accelerating safety PLC upgrades to meet export market requirements for European automotive OEMs.
Pharmaceutical manufacturers near Mumbai and Hyderabad are unbundling after-sales service contracts from hardware procurement, selecting specialized system integrators for validation documentation and periodic requalification. This disintermediation shifts margin capture from controller vendors to local engineering firms with FDA and CDSCO audit experience. The pattern is most visible in sterile injectable facilities where 21 CFR Part 11 compliance drives recurring validation expenditure.
Asia-Pacific Industrial Control System Market Segmentation
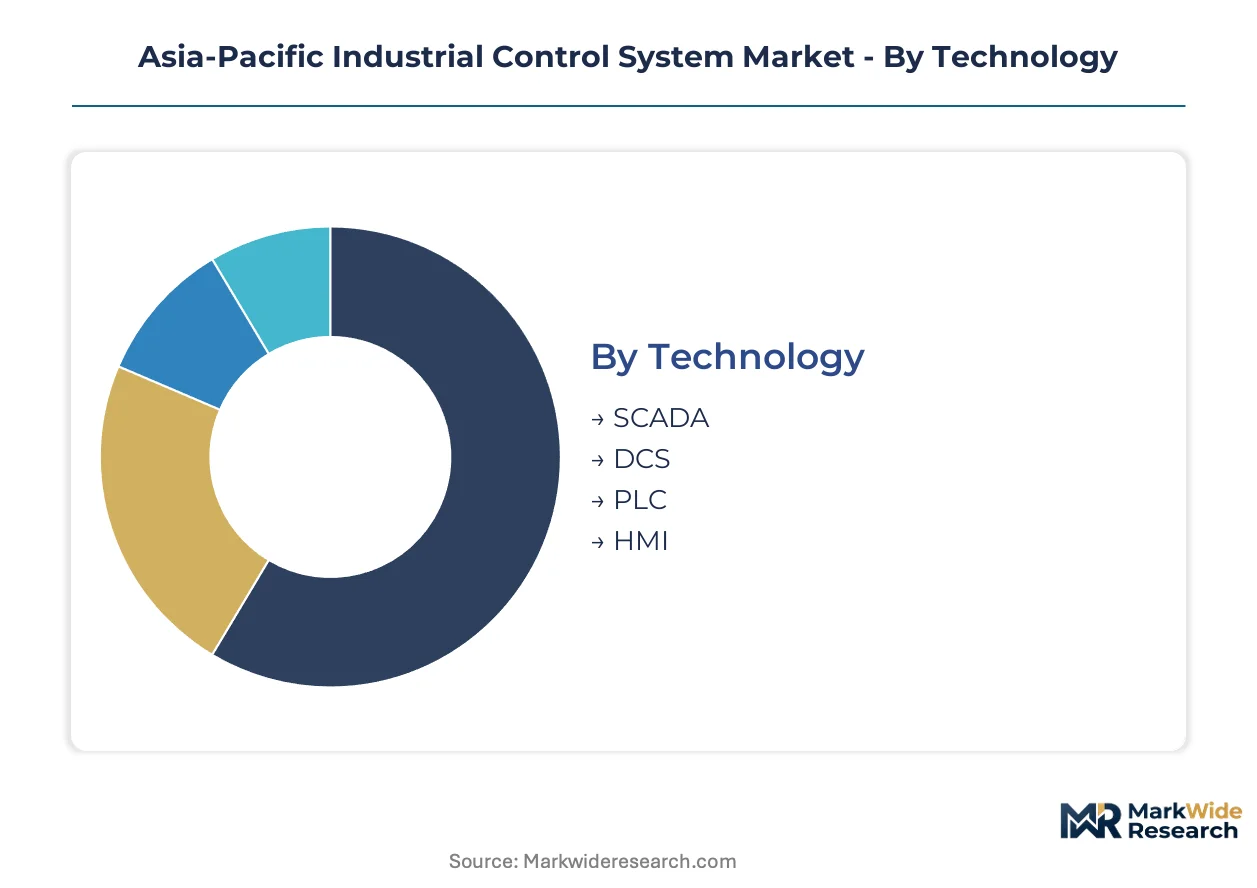
Technology selection in the Asia-Pacific Industrial Control System Market follows distinct geographic patterns. Japanese precision manufacturers demand nanosecond-response controllers, while Southeast Asian mid-tier producers prioritize cost-optimized cloud architectures. End-use concentration in automotive corridors and pharmaceutical clusters shapes component specifications across the region.
Technology:
Domestic demand in China and Japan drives PLC and DCS procurement, while export-oriented manufacturing in Vietnam and Thailand accelerates SCADA adoption for remote monitoring of overseas buyer facilities.
- PLC:Programmable logic controllers execute discrete control sequences with deterministic scan cycles. Manufacturing corridors in Vietnam and Indonesia deploy compact PLCs for automated assembly lines serving export markets. Lead times extend due to Taiwan foundry allocation constraints for industrial-grade processors.
- DCS:Distributed control systems orchestrate continuous processes through redundant controller architectures. Petrochemical complexes along China's eastern seaboard and India's western coast command premium configurations for cascade control strategies. MIIT cybersecurity reviews force foreign-origin DCS suppliers to localize data residency protocols.
- SCADA:Supervisory control and data acquisition systems aggregate field-level telemetry for centralized visualization. Cloud-hosted SCADA is expanding fastest among Indonesian and Vietnamese manufacturers bypassing heavy infrastructure investment.
- HMI:Human-machine interfaces provide operator interaction layers through industrial-grade touch panels and mobile visualization clients.
PLC holds the largest share; momentum sits with cloud-hosted SCADA configurations.
End User:
Application requirements diverge sharply between process industries needing validated batch records and discrete manufacturers prioritizing cycle-time optimization.
- Manufacturing:Automotive assembly plants in Thailand and China deploy robotic welding controllers with sub-millisecond synchronization. Electric vehicle battery pack production lines across Southeast Asia are expanding automated paint-shop and assembly controller installations. JIS functional safety mandates from Japan's METI compel redundant processor architectures in semiconductor fabrication.
- Energy:Power sector deployments face India's CEA grid connectivity regulations requiring extended type-testing for controller commissioning. Thermal and renewable generation facilities specify hardened controllers for substation automation and distributed energy resource management.
- Chemical:Process control architectures manage hazardous material handling through safety-instrumented systems with SIL-rated redundancy.
- Transportation:Rail signaling and port automation systems demand high-availability controllers with fault-tolerant failover capabilities.
Manufacturing commands the dominant position; energy sector specifications are tightening fastest under regulatory pressure.
Deployment:
Capital availability and data sovereignty requirements create a three-tier structure across the region's manufacturing base.
- Cloud-Hosted:Subscription-based SCADA and controller management platforms eliminate upfront infrastructure expenditure. Mid-tier Vietnamese and Indonesian manufacturers adopt these configurations to accelerate digital transformation without balance-sheet strain. Data residency concerns limit adoption in China's critical information infrastructure sectors.
- On-Premises:Traditional air-gapped installations dominate Japanese precision manufacturing and Chinese critical infrastructure where cybersecurity classification reviews apply. Pharmaceutical facilities near Hyderabad and Mumbai maintain on-premises DCS for FDA and CDSCO audit trail compliance.
- Hybrid:Edge-cloud architectures partition real-time control from analytics workloads. Korean battery cell producers deploy hybrid models to satisfy European automotive OEM data governance requirements while maintaining local loop performance.
- Remote:Satellite-linked and cellular-connected controllers enable offshore platform and pipeline monitoring across Australian and Southeast Asian extractive operations.
On-premises retains the largest installed base; cloud-hosted configurations are climbing the fastest among capital-constrained entrants.
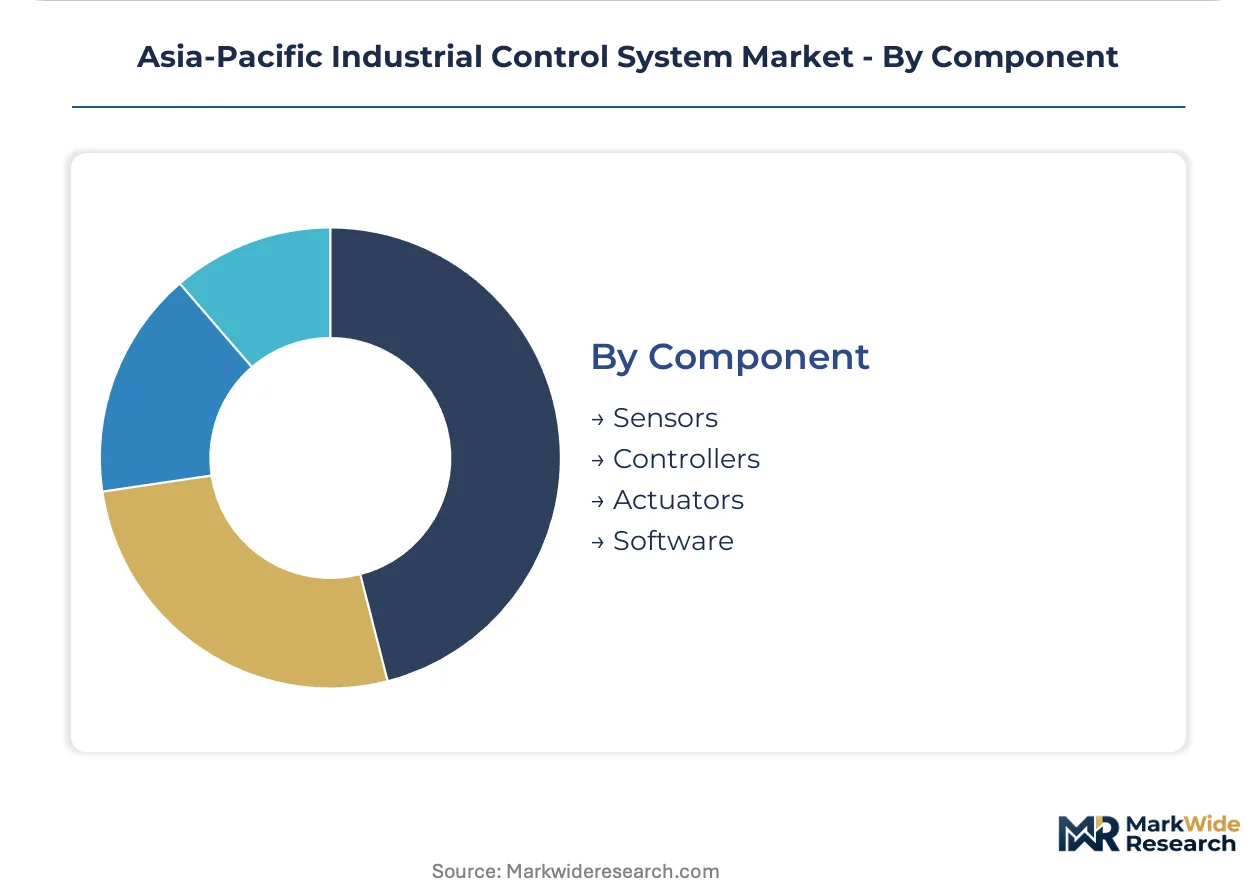
Component:
Supply chain concentration in Taiwanese semiconductor foundries shapes hardware availability across all controller tiers.
- Controllers:Industrial-grade CPUs, safety PLCs, and redundant processor modules form the computational core. FPGA and ASIC sourcing from Taiwan-based foundries faces allocation volatility extending procurement lead times. Japanese automotive plants specify MELSEC and S7-300 replacements with Ethernet-based architectures.
- Sensors:Temperature, pressure, flow, and vibration transducers provide analog and digital signal inputs. Smart sensor deployments with embedded edge-AI capabilities are accelerating in Japanese precision machining for predictive maintenance.
- Actuators:Motor drives, pneumatic valves, and robotic servo systems execute physical control actions. Electric vehicle battery production lines in Thailand and China integrate high-precision servo controllers for cell stacking and welding operations.
- Software:Engineering workstations, historian databases, and advanced process control algorithms complete the technology stack. TIA Portal and Ability platform ecosystems anchor automation projects through integrated development environments.
Controllers represent the highest-value segment; software is gaining share fastest through recurring license and subscription models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturing across Southeast Asia runs parallel to import-dependent technology sourcing from Japan and Germany. The region's industrial control system demand splits between domestic infrastructure buildouts and foreign-invested production facilities serving global supply chains.
China
Electric vehicle battery production lines in Guangdong and Jiangsu provinces are expanding robotic welding controller installations. MIIT cybersecurity classification reviews for critical information infrastructure operators mandate data residency protocols for foreign-origin DCS deployments. Yangtze River Delta petrochemical complexes command premium redundant controller configurations for cascade control strategies.
Japan
Semiconductor fabrication facilities in Kansai and Chubu regions require nanosecond-response MELSEC controllers for precision manufacturing. METI enforcement of updated JIS functional safety standards compels redundant processor architectures in automotive plants. Nagoya-area automotive suppliers are accelerating safety PLC upgrades to meet European OEM export requirements.
India
Pharmaceutical manufacturing corridors near Hyderabad and Mumbai are unbundling after-sales service contracts from hardware procurement. CEA grid connectivity regulations require extended type-testing for power sector controller commissioning. Sterile injectable facilities in these clusters demand validated DCS architectures for FDA and CDSCO audit compliance.
South Korea
Battery cell production lines for European automotive OEMs are accelerating safety PLC upgrades to satisfy export market requirements. MFDS pharmaceutical manufacturing standards shape controller specifications in biologics facilities. Busan-Ulsan industrial belt deploys hybrid edge-cloud architectures to balance data governance requirements with local loop performance.
Vietnam
Mid-tier manufacturers in Ho Chi Minh City and Hanoi industrial parks are adopting subscription-based SCADA to bypass heavy on-premises capital requirements. Foreign-invested electronics assembly plants source compact PLCs for automated export production lines. Domestic food processing facilities face capability scarcity in certified ICS security practitioners, constraining deployment velocity.
Asia-Pacific Industrial Control System Market Competitive Environment
Concentration sits with diversified industrial conglomerates anchoring automation projects through integrated platform ecosystems. European and Japanese vendors occupy distinct tier positions based on functional safety certification depth and deterministic control performance. Strategic moves center on joint-venture localization partnerships to satisfy data residency mandates and ecosystem lock-in through engineering workstation software. Geographic expansion into Vietnamese and Indonesian manufacturing corridors represents the second competitive vector.
Among diversified European industrial groups, Siemens AG and ABB Ltd exemplify platform-centric archetypes, while Honeywell International Inc occupies a position within the process control specialization tier. Japanese precision manufacturing demand anchors Mitsubishi Electric Corporation and OMRON Corporation as representatives of nanosecond-response controller capabilities. These five entities collectively illustrate the market's bifurcation between integrated ecosystem providers and performance-optimized specialists.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd |
| Honeywell International Inc |
| OMRON Corporation |
| Schneider Electric |
| Mitsubishi Electric Corporation |
| Rockwell Automation Inc |
| Yokogawa Electric Corporation |
| Emerson Electric Co |
| Others |
Value Chain & Pricing Dynamics
Twenty-six-week lead times for industrial-grade FPGAs and ASICs concentrate procurement power with Taiwanese foundry partners, compressing margins for controller vendors while amplifying price premiums on safety-certified redundant architectures. This inventory constraint reshapes how Japanese automotive plants and Chinese petrochemical complexes negotiate volume contracts against spot-market component volatility.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with safety PLC certifications from Japan's METI and China's MIIT commanding substantial premiums over compact PLCs for discrete manufacturing. Price differentiation rests on functional safety grade and after-sales validation documentation, particularly in India's pharmaceutical corridors where FDA and CDSCO compliance drives recurring service expenditure. Pricing pressure stems from semiconductor allocation volatility extending hardware delivery windows. Mid-tier Vietnamese and Indonesian manufacturers exhibit highest price sensitivity, preferring subscription-based SCADA to preserve capital, while Japanese precision fabricators prioritize deterministic performance over cost.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for industrial-grade processors and safety PLCs, with Japan and Germany supplying precision motion controllers and engineered software platforms. The regional controller supply chain draws from Taiwanese FPGA foundries, Korean memory semiconductor output, and Japanese precision electromechanical components. Single-source vulnerability concentrates in Taiwan-based foundry allocation for industrial ASICs, exposing lead-time extension risks across Southeast Asian assembly automation projects. Distribution runs through authorized system integrators and OEM direct channels, with cloud-hosted deployments increasingly bypassing traditional hardware distribution layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from validation documentation and cybersecurity compliance is expanding faster than hardware procurement across Asia-Pacific industrial control deployments, creating durable recurring income streams for vendors with local engineering capabilities.
For Market Incumbents: Fortify ecosystem lock-in through TIA Portal and Ability platform engineering workstation penetration, while accelerating joint-venture localization partnerships to satisfy MIIT data residency mandates. Add certified cybersecurity practitioner capacity in Vietnam and Indonesia to capture service-attach revenue from mid-tier manufacturers facing skill scarcity. Defend against emerging cloud-native SCADA entrants by bundling edge-AI predictive maintenance modules with controller hardware. For New Entrants and Emerging Players: CDSCO and FDA validation fast-tracks for pharmaceutical manufacturing corridors near Hyderabad and Mumbai offer the most penetrable entry point, as incumbent vendors unbundle after-sales service contracts. Target sterile injectable facilities requiring 21 CFR Part 11 compliance documentation, where specialized system integrators capture margin migration from hardware vendors. Establish partnerships with local engineering firms possessing audit experience to accelerate credential acquisition. For Investors and Strategic Acquirers: Long-term, this sits as a localization-mandate play because cybersecurity classification reviews for critical infrastructure are hardening data residency requirements across China, India, and Southeast Asia. Acquisition targets should display certified practitioner density in underserved geographies and established validation documentation capabilities for pharmaceutical and energy sector deployments. Watch for MIIT enforcement actions against foreign-origin systems as the signal indicating acceleration of domestic certification program adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Joint-Venture Localization Partnership | MIIT cybersecurity mandates force foreign DCS suppliers to establish domestic data residency protocols. |
| Cloud-Hosted SCADA Platform Launch | Vietnamese and Indonesian mid-tier manufacturers bypass heavy infrastructure through subscription models. |
| Edge-AI Controller Integration | Japanese precision machining demands sub-millisecond predictive maintenance algorithm deployment. |
| Safety PLC Certification Investment | METI JIS standards compel redundant architectures in Kansai semiconductor fabrication facilities. |
| Validation Documentation Service Expansion | Hyderabad pharmaceutical corridors unbundle hardware procurement from FDA and CDSCO compliance services. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of MIIT cybersecurity directives, METI JIS functional safety standards, and CEA grid connectivity regulations, with input from plant engineers, OEM procurement teams, aftermarket service heads, and system integration specialists. Trade data from regional customs authorities, SEC filings from diversified industrial conglomerates, and project commissioning records from petrochemical and automotive facilities provided validation anchors. Bottom-up controller shipment analysis triangulates against top-down manufacturing capital expenditure tracking across the region.
Segmentation dimensions modeled span technology type, end-user industry, deployment architecture, and component category, with additional granularity on cybersecurity classification tier and functional safety certification level across the projection horizon. CAGRs derive from installed base growth, replacement cycle compression, and greenfield automation intensity indices. Forecast inputs incorporate Taiwan foundry allocation constraints, MIIT enforcement trajectory, and pharmaceutical corridor validation expenditure patterns.
Decision-makers should treat outputs as directional under assumptions of sustained semiconductor supply volatility and progressive cybersecurity regulatory tightening; material deviation in foundry allocation or enforcement intensity would warrant model refresh. Recalibration cycles align with material shifts in MIIT classification review schedules, JIS standard revision timelines, and CEA grid code amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Echo Sounder Market
Sensors and Controls
Global Acceleration and Yaw Rate Sensors Market
Sensors and Controls
Automotive MEMS Sensor Market
Sensors and Controls
Biopotential Sensor Market
Sensors and Controls
Europe Smart Glove Market
Sensors and Controls
Middle-East and Africa Nanosensors Market
Sensors and Controls
Absolute Encoders Market
Sensors and Controls
Area Sensor Market
Sensors and Controls
Fiber Optic Pressure Sensors Market
Sensors and Controls
Sound Sensor Market
Sensors and Controls
Conveyor Belt Tracking Devices Market
Sensors and Controls
Global E-Compass Market
Sensors and Controls
Embedded Biometric Sensor Market
Sensors and Controls
Latin America Wearable Sensors Market
Sensors and Controls
Global Sonar Systems and Technology Market
Sensors and Controls
Latin America Gas Sensors Market