
 Predictive Touch Market | 2026-2036
Predictive Touch Market Size, Share, and Industry Trends Forecast 2026-2036
Predictive Touch Market Analytics
Automotive manufacturing is expanding as the dominant vertical for predictive touch deployment. NVIDIA Corp. leverages its GPU-accelerated AI platforms to power gesture-recognition pipelines for in-vehicle interfaces. Intel Corp. sustains R&D intensity around edge-computing silicon optimized for low-latency touch prediction. Microsoft Corp. competes through cloud-based AI services that enable over-the-air model updates for connected vehicle touch systems.
Predictive touch encompasses sensor-fusion systems that anticipate user intent through proximity detection, gesture trajectory analysis, and machine-learning inference before physical contact occurs. These systems typically operate at sub-100-millisecond latency thresholds and integrate capacitive, optical, or ultrasonic sensing layers to enable hygienic, non-contact interaction in high-throughput environments. Software solutions are capturing expanding margin pools as OEMs prioritize AI model licensing over hardware procurement. Capacitive technology dominates current installations, while ultrasonic sensing is gaining traction in medical device applications where sterility protocols demand contactless operation. Integrated modules are maturing as automotive Tier-1 suppliers standardize predictive touch into cockpit domain controllers.
The EU AI Act classifies predictive touch systems in safety-critical automotive and medical contexts as high-risk AI, mandating conformity assessments and traceability documentation. The FDA's human factors engineering guidance for medical devices requires validation of touchless control accuracy in sterile surgical environments. Germany's KBA enforces electromagnetic compatibility standards for automotive HMI components that affect predictive touch sensor certification. Stakeholders must monitor evolving interoperability mandates between AI inference engines and legacy vehicle bus architectures.
Market Dynamics
Automotive OEM procurement of predictive touch modules is concentrating purchasing power among cockpit domain controller suppliers, compressing margins for standalone sensor vendors while elevating software licensing economics.
Growth Catalysts
- EU AI Act high-risk classification:Mandatory conformity assessments for automotive and medical predictive touch systems are creating certified-supplier moats that favor established module integrators over component-only vendors.
- Capacitive-to-ultrasonic technology migration:Sterility protocols in surgical environments are accelerating ultrasonic sensing adoption, opening medical device revenue streams beyond automotive saturation.
- Germany automotive cluster concentration:KBA electromagnetic compatibility enforcement is standardizing predictive touch architectures across Tier-1 supplier portfolios, reducing fragmentation.
Market Restraints
- GPU silicon supply concentration:Inference acceleration for sub-100-millisecond latency depends on concentrated advanced semiconductor foundry capacity, creating input cost volatility.
- Sensor fusion calibration complexity:Multi-modal integration of capacitive, optical, and ultrasonic layers requires specialized firmware talent pools that remain geographically thin.
- Legacy vehicle bus architecture incompatibility:Predictive touch inference engines face friction integrating with CAN and LIN networks in existing automotive fleets, limiting retrofit markets.
Strategic Opportunities
- India medical device manufacturing:CDSCO regulatory harmonization with IEC standards is enabling export-oriented production of ultrasonic predictive touch surgical interfaces.
- Edge-AI model compression:Convergence of neural architecture search with automotive-grade silicon is enabling on-device inference without cloud dependency, reducing latency further.
- Over-the-air update channel maturation:Cloud-based AI service delivery is creating recurring revenue models that displace one-time hardware procurement in connected vehicle programs.
Industry Challenges
- Human factors engineering validation:FDA guidance on touchless control accuracy in sterile environments demands extensive usability testing that extends product development timelines.
- Cross-domain talent scarcity:Firmware engineering for sensor fusion requires simultaneous expertise in signal processing, machine learning, and automotive safety standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Predictive Touch Market |
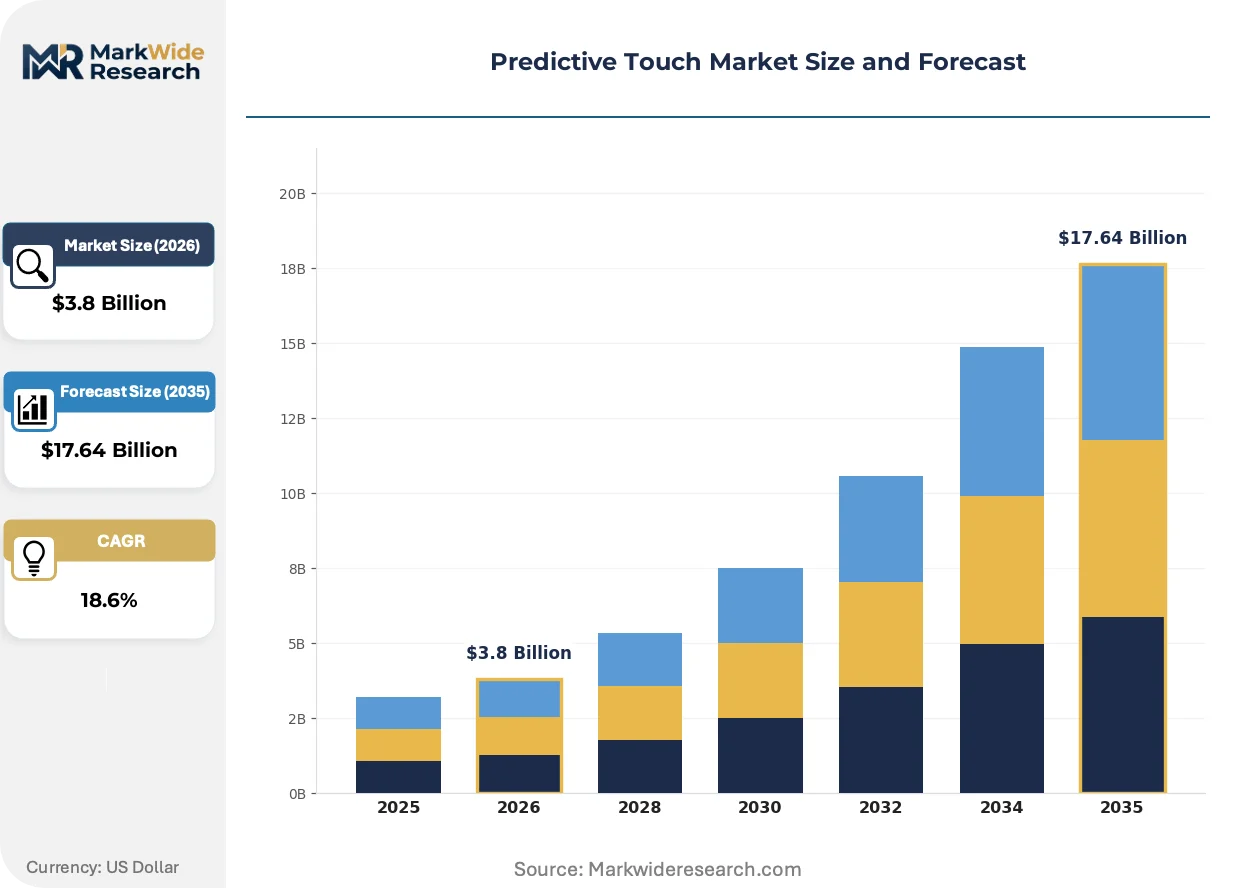
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Systems, Integrated Modules, Software Solutions, Custom Solutions Technology: Capacitive, Resistive, Optical, Ultrasonic End User: Healthcare Providers, Retailers, Automotive Manufacturers, Hospitality Application: Interactive Displays, Gaming Interfaces, Medical Devices, Smart Appliances |
| Companies Covered | Amazon.com Inc., Google LLC, Microsoft Corp., International Business Machines Corp., Intel Corp., NVIDIA Corp., Salesforce Inc., SAP SE, Oracle Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Predictive Touch Market Evolving Landscape
Three forces are restructuring predictive touch competitive economics: inference migration toward edge silicon, regulatory certification becoming a purchase prerequisite, and software licensing displacing hardware ownership models.
Ultrasonic sensing arrays for non-contact gesture recognition are electrifying medical device human-machine interfaces. Surgical equipment manufacturers in Germany and Switzerland are integrating these modules into sterile field controls. This technology is electrifying the shift from capacitive dominance toward multi-modal sensor fusion that reduces cross-contamination risk.
The EU AI Act's high-risk AI classification for automotive and medical predictive touch systems is mandating traceability documentation and conformity assessments across the European Economic Area. OEMs must now maintain model lineage records and bias testing protocols. German automotive suppliers are responding by embedding compliance engineering teams within product development organizations.
Automotive OEM procurement of predictive touch capabilities is consolidating around AI model licensing rather than discrete hardware procurement. Tier-1 suppliers are capturing margin by offering inference-as-a-service contracts with over-the-air update entitlements. This pattern is most visible in Germany, where Volkswagen, BMW, and Mercedes-Benz cockpit programs prioritize software-defined feature roadmaps over fixed hardware specifications.
Predictive Touch Market Segmentation
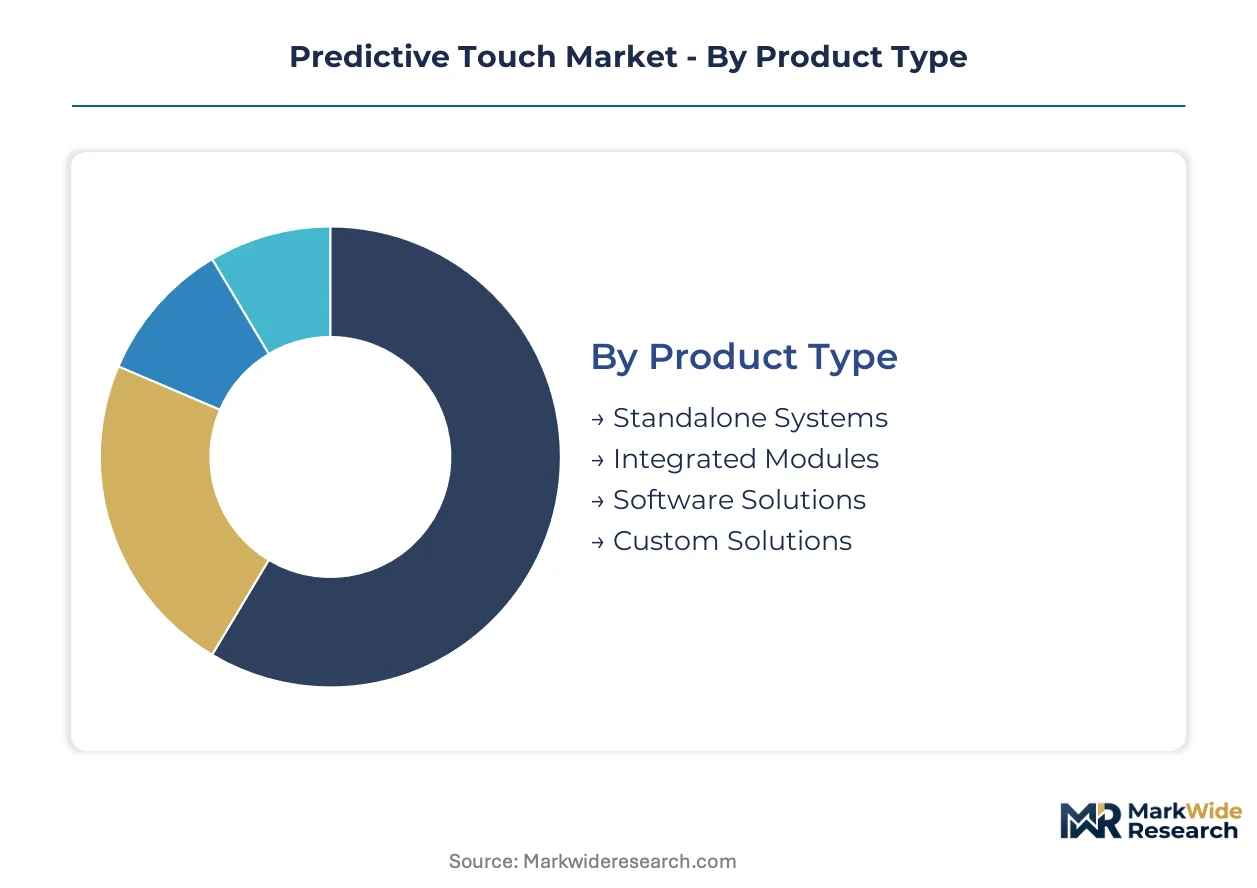
Predictive touch segmentation reveals divergent margin economics across hardware-software boundaries. Product architecture choices determine whether vendors capture one-time module revenue or recurring licensing income. Technology selection drives regulatory pathway complexity, particularly for medical and automotive certifications.
Product Type:
Volume deployment favors integrated modules, while premium economics concentrate in software licensing arrangements.
- Integrated Modules:Cockpit domain controllers from German Tier-1 suppliers standardize predictive touch as a bundled subsystem. Volkswagen, BMW, and Mercedes-Benz procurement contracts prioritize fixed hardware specifications with multi-year supply agreements.
- Software Solutions:AI model licensing generates recurring revenue through over-the-air update entitlements. Tier-1 suppliers capture expanding margin pools as OEMs shift from discrete hardware procurement to inference-as-a-service contracts.
- Standalone Systems:Retrofit installations for legacy vehicle fleets face CAN and LIN network incompatibility constraints.
- Custom Solutions:Surgical equipment manufacturers in Switzerland specify sterile-field ultrasonic arrays with proprietary calibration protocols.
Mature deployment sits with Integrated Modules. Newer deployment is concentrated in Software Solutions.
Technology:
Capacitive dominance yields to ultrasonic expansion in sterility-critical environments.
- Capacitive:Current automotive installations rely on proximity detection layers with sub-100-millisecond latency thresholds. German KBA electromagnetic compatibility enforcement standardizes these architectures across supplier portfolios.
- Ultrasonic:Non-contact gesture recognition arrays electrify medical device human-machine interfaces. Surgical equipment manufacturers in Germany and Switzerland integrate these modules into sterile field controls to reduce cross-contamination risk.
- Optical:Gaming interface applications leverage camera-based trajectory analysis with ambient light compensation.
- Resistive:Legacy industrial panels retain niche presence in cost-constrained appliance interfaces.
Certification-heavy deployment sits with Ultrasonic. Volume scaling is concentrated in Capacitive.
End User:
Automotive procurement concentrates purchasing power, while healthcare demands specialized compliance engineering.
- Automotive Manufacturers:Cockpit domain controller suppliers compress margins for standalone sensor vendors while elevating software licensing economics. EU AI Act high-risk classification mandates conformity assessments and traceability documentation.
- Healthcare Providers:FDA human factors engineering guidance requires validation of touchless control accuracy in sterile surgical environments, extending product development timelines.
- Retailers:Interactive kiosk deployments prioritize hygienic non-contact interaction in high-throughput environments.
- Hospitality:Smart room interfaces adopt proximity-activated controls for guest experience differentiation.
Regulatory complexity sits with Healthcare Providers. Procurement scale is concentrated in Automotive Manufacturers.
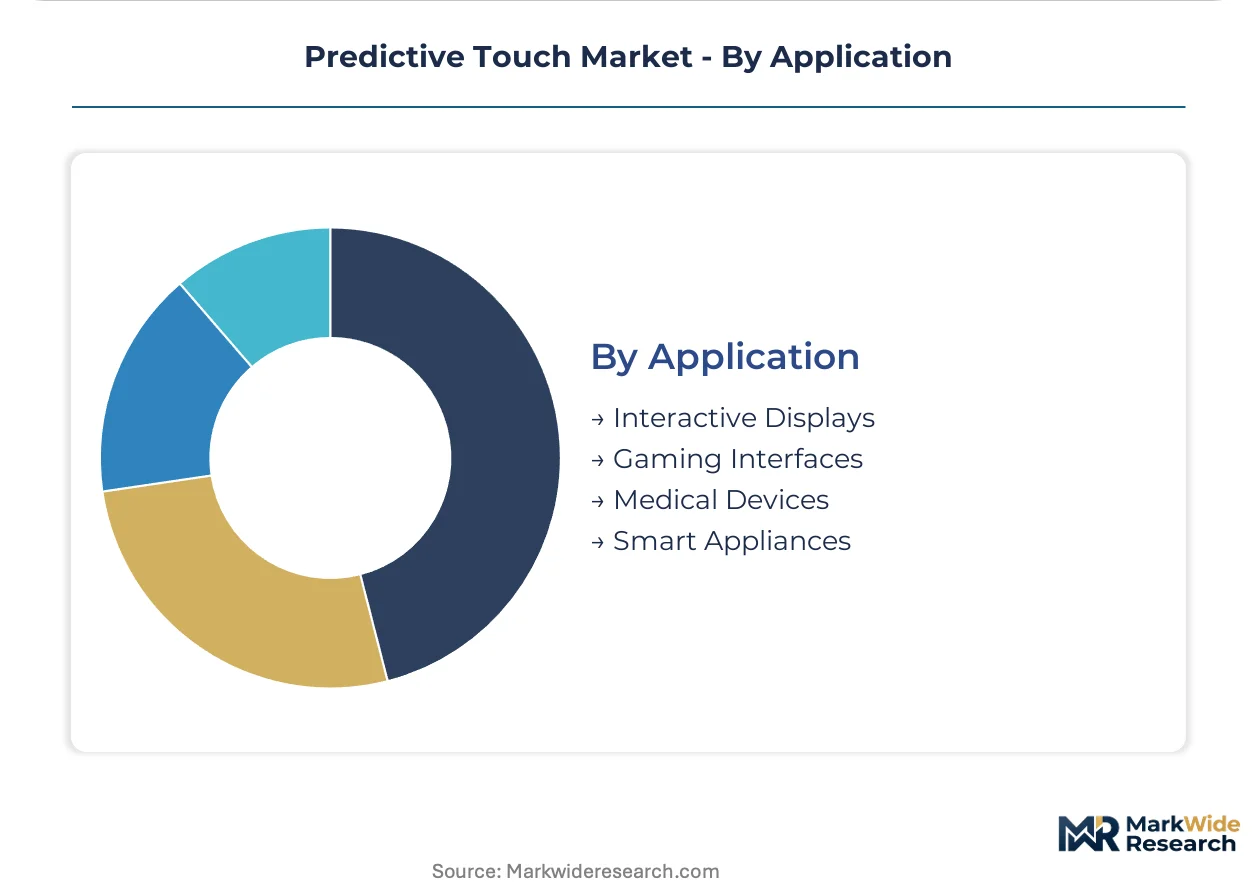
Application:
Medical device applications command premium pricing through sterility protocols, while smart appliances compete on cost optimization.
- Medical Devices:Sterile surgical environments demand ultrasonic sensing with specialized firmware for multi-modal sensor fusion. FDA guidance and EU AI Act high-risk classification create certified-supplier moats.
- Interactive Displays:Retail and hospitality deployments emphasize hygienic operation through capacitive proximity layers with gesture trajectory analysis.
- Gaming Interfaces:Optical sensing with camera-based recognition enables immersive controller-free interaction.
- Smart Appliances:Cost-driven resistive and capacitive implementations target mass-market kitchen and laundry segments.
Compliance engineering intensity sits with Medical Devices. Volume manufacturing is concentrated in Smart Appliances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates predictive touch module production through its automotive Tier-1 supplier cluster, while the United States and China drive divergent consumption patterns across medical and consumer electronics verticals.
Germany
Automotive OEM procurement from Volkswagen, BMW, and Mercedes-Benz anchors domestic demand for cockpit domain controllers. KBA electromagnetic compatibility enforcement standardizes predictive touch architectures across supplier portfolios. Stuttgart and Munich host concentrated R&D facilities where Tier-1 suppliers integrate ultrasonic sensing into next-generation vehicle interfaces.
United States
FDA human factors engineering guidance shapes medical device validation requirements for touchless surgical controls. NVIDIA Corp. leverages GPU-accelerated AI platforms from its California base to power gesture-recognition pipelines. Detroit automotive engineering centers and Boston medical device clusters drive divergent application development.
China
MIIT standards for intelligent vehicle human-machine interfaces accelerate domestic predictive touch adoption in electric vehicle programs. Yangtze River Delta manufacturing hubs produce capacitive sensing layers for export-oriented automotive suppliers. Shenzhen electronics clusters specialize in optical gesture-recognition modules for gaming and retail applications.
Switzerland
Swissmedic certification requirements for sterile surgical equipment create premium positioning for ultrasonic predictive touch arrays. Precision manufacturing traditions in Basel and Zurich support medical device OEMs integrating contactless controls into operating theater environments. German cross-border supply relationships extend module distribution into broader European markets.
India
CDSCO regulatory harmonization with IEC standards enables export-oriented production of ultrasonic surgical interfaces. Karnataka and Tamil Nadu medical device manufacturing parks attract predictive touch component assembly for North American and European customers. Domestic automotive programs in Maharashtra pilot capacitive proximity systems for mass-market vehicle segments.
Predictive Touch Market Competitive Landscape
Top-tier vendors anchor cloud-based AI service delivery, while specialized sensor fabricators and semiconductor specialists occupy differentiated tiers. Market structure reflects consolidation around inference-as-a-service licensing models alongside persistent fragmentation in hardware component supply. Three archetypes dominate: hyperscale cloud providers with over-the-air update capabilities, automotive Tier-1 module integrators, and edge-AI silicon specialists. Competitive dynamics center on strategic partnerships between software licensors and domain controller manufacturers, plus geographic expansion into medical device certification-heavy markets.
Within the hyperscale tier, Microsoft Corp. and Amazon.com Inc. exemplify cloud-native AI service architectures that enable recurring revenue through model update entitlements. Intel Corp. occupies a position among edge-computing silicon specialists optimizing for sub-100-millisecond latency thresholds. NVIDIA Corp. anchors GPU-accelerated inference acceleration, representing the convergence of automotive and medical device application pipelines through unified hardware platforms.
| Leading Market Players |
|---|
| Amazon.com Inc. |
| Google LLC |
| Microsoft Corp. |
| International Business Machines Corp. |
| Intel Corp. |
| NVIDIA Corp. |
| Salesforce Inc. |
| SAP SE |
| Oracle Corp. |
| Others |
Value Network & Pricing Analysis
Ultrasonic sensing migration from capacitive dominance simultaneously compresses hardware margins and concentrates procurement leverage among German Tier-1 suppliers with in-house calibration capabilities. This technology transition elevates software licensing economics while fragmenting component vendor pricing power across automotive and medical certification tiers.
Pricing Analysis
Short lead-time premiums for KBA-certified automotive modules run 15-25% above standard contract terms, while spot inventory of GPU-accelerated inference silicon commands scarcity markups. Pricing stratifies across automotive-grade certification, medical device FDA validation tiers, and uncertified consumer electronics implementations. Cost compression in standalone sensor hardware intensifies as cockpit domain controller bundling displaces discrete procurement. Tier-1 automotive suppliers exhibit lowest price sensitivity due to long-term platform commitments, whereas retail kiosk deployers demand economy-tier capacitive solutions.
Supply Chain Analysis
Freight cost volatility for precision ultrasonic transducers from Switzerland and Germany has prompted regional buffer stock strategies among surgical equipment OEMs. Manufacturing concentrates in Germany for automotive integration modules, China for capacitive sensing layer production, and Switzerland for sterile-field ultrasonic arrays. Raw material dependencies include advanced semiconductor foundry capacity for inference acceleration, specialized piezoelectric ceramics for medical-grade transducers, and optical-grade substrates for camera-based gesture systems. Single-source vulnerability sits with TSMC-class foundry allocation for sub-100-millisecond latency silicon. Distribution runs through Tier-1 automotive domain controller suppliers and medical device OEM direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The predictive touch market constitutes a vertical-integration race where control over sensor-fusion firmware and edge-AI silicon determines margin capture. Players are pursuing backward integration into specialized calibration protocols to escape commodity hardware pricing.
For Market Incumbents: Lock in long-term foundry allocation for automotive-grade inference silicon to secure sub-100-millisecond latency supply. Embed compliance engineering teams within R&D organizations to accelerate EU AI Act conformity assessments and create certified-supplier moats against emerging entrants. Prioritize acquisition of ultrasonic calibration specialists to capture medical device premium pricing.
For New Entrants and Emerging Players: Cloud-based AI service providers represent the most penetrable channel partner type for software licensing entry. Target India's CDSCO-harmonized manufacturing parks for export-oriented ultrasonic surgical interface production. Pursue white-label firmware licensing to automotive Tier-2 suppliers seeking domain controller independence from German incumbents.
For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscale cloud provider acquisition of edge-AI inference specialists. Long-term viability hinges on regulatory certification asset accumulation rather than hardware volume scale. Monitor KBA electromagnetic compatibility standard revisions as inflection indicators for supplier consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Model Compression Investment | Enables on-device inference without cloud dependency, reducing latency below KBA thresholds. |
| EU AI Act Conformity Certification | Creates defensible supplier positioning for high-risk automotive and medical deployments. |
| Ultrasonic Sensing Module Acquisition | Captures sterile surgical environment pricing premiums through Swissmedic-validated arrays. |
| Over-the-Air Update Infrastructure | Transforms hardware procurement into recurring inference-as-a-service revenue streams. |
| India Manufacturing Footprint Expansion | Leverages CDSCO-IEC harmonization for export-oriented medical device component supply. |
Research Methodology
Trade databases, SEC filings from semiconductor and automotive Tier-1 suppliers, and EU regulatory disclosure repositories formed the secondary backbone of this analysis. Primary interviews with cockpit domain controller procurement leads, FDA regulatory affairs specialists, ultrasonic sensor calibration engineers, and Tier-1 supplier platform architects combined with secondary validation through KBA certification records and CDSCO harmonization documentation. Bottom-up and top-down triangulation cross-referenced module shipment data against OEM production schedules and medical device installation records.
Bottom-up modeling aggregated individual product category trajectories while top-down validation checked aggregate market alignment with automotive electronics spending patterns and medical device HMI investment trends across the projection horizon. Segmentation dimensions included product architecture, sensing technology, end-user vertical, and application environment. CAGRs derived from fitted growth curves applied to technology adoption S-cycles and regulatory implementation timelines. Forecast inputs incorporated EU AI Act enforcement phasing and MIIT intelligent vehicle interface standard evolution.
Several conditions sit outside the modeled scope, including geopolitical disruption to Taiwan-foundry supply, unanticipated FDA guidance revisions on surgical touchless controls, and automotive OEM insolvency cascades affecting platform commitments. Forecasts reflect documented assumptions about regulatory implementation cadence and technology cost reduction curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Steam Trap Monitor Market
Sensors and Controls
Digestible Sensors Market
Sensors and Controls
MEMS Combo Sensors Market
Sensors and Controls
United States Pressure Transmitter Market
Sensors and Controls
North America Sensor Market
Sensors and Controls
Biopotential Sensor Market
Sensors and Controls
Electric Vehicle (EV) Sensor Market
Sensors and Controls
China Pressure Sensors Market
Sensors and Controls
Industrial Transmitters Market
Sensors and Controls
Global Collision Avoidance Sensors Market
Sensors and Controls
Body Worn Antenna Market
Sensors and Controls
Variable Reluctance Sensor Market
Sensors and Controls
Smart Level Probe Market
Sensors and Controls
Electrochemical Gas Sensor Market
Sensors and Controls
Pressure Transducer Market
Sensors and Controls
Timing Device Market