
 Aerospace and Defense Materials Market | 2026-2036
Aerospace and Defense Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace and Defense Materials Market Intelligence
Predictive maintenance subscriptions tied to material performance data is decoupling the initial material sale from its long-term value proposition. Hexcel Corporation specializes in advanced composite materials, which are critical for next-generation airframes. Spirit AeroSystems Holdings, Inc. leverages these materials in large-scale aerostructure manufacturing. 3M provides a diverse portfolio of adhesives and coatings, essential for component assembly and protection.
Aerospace and defense materials are specialized substances engineered for high-stress environments, characterized by superior strength-to-weight ratios and extreme temperature resistance. Their primary purpose is to ensure structural integrity and operational performance in aircraft, spacecraft, and weapon systems. Composite materials, including carbon fiber reinforced plastics, command a significant share due to lightweighting initiatives. The adoption of Additive Manufacturing technology is enabling complex geometries and on-demand production of engine components.
Material qualification and market access are governed by stringent regulatory bodies such as the US Federal Aviation Administration (FAA) and European Union regulations like REACH. Global standards, including ISO 9001 and AS9100, enforce quality management systems across the supply chain. Navigating the evolving requirements for material traceability and sustainability reporting is a critical task for all supply chain participants.
Market Dynamics
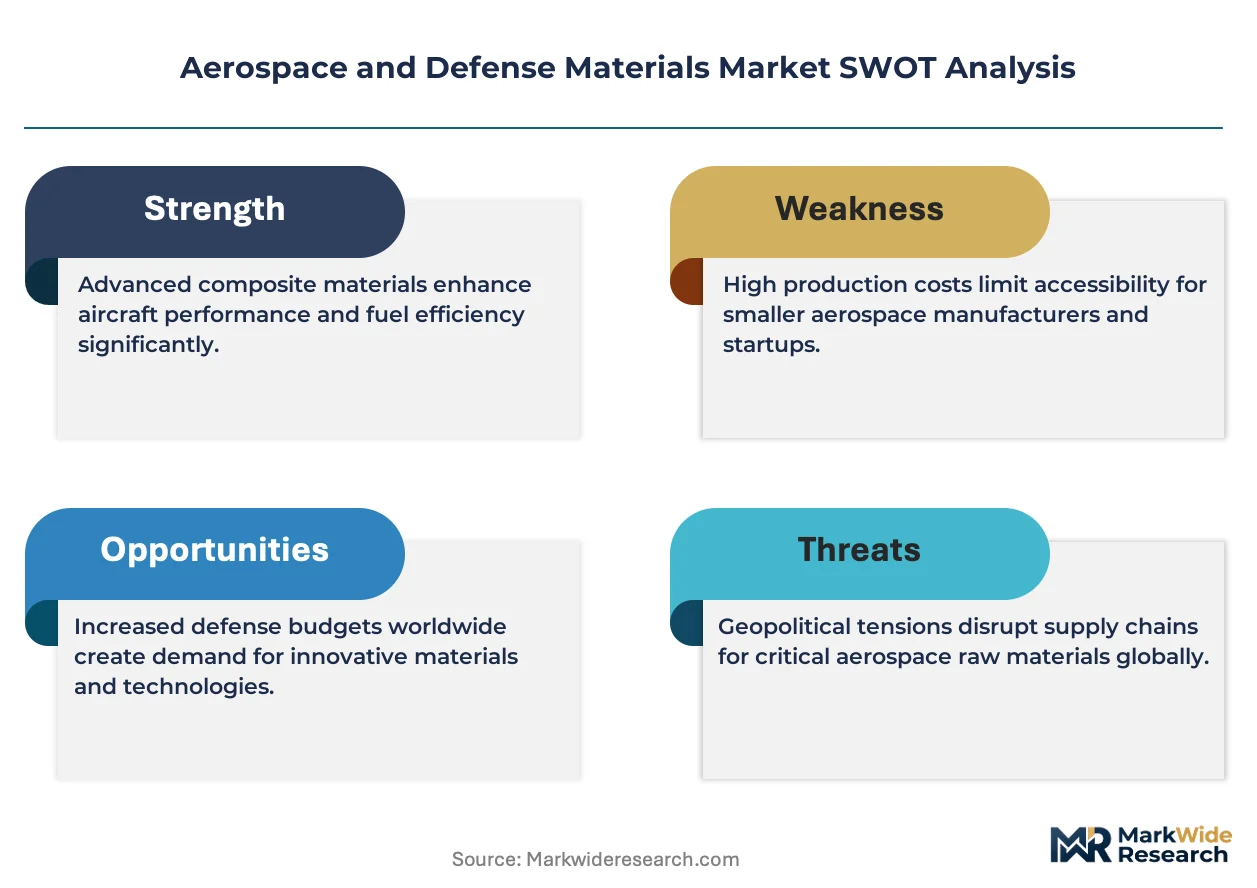
The central dynamic shaping the market is the tension between accelerating performance demands for next-generation platforms and the intensifying pressure of regulatory compliance and cost containment. This forces a trade-off between deploying novel, high-performance materials and relying on established, fully qualified substances with extensive service histories.
Growth Catalysts
- Next-Generation Platforms:The development of unmanned aerial vehicles (UAVs), urban air mobility (UAM) aircraft, and new satellite constellations creates dedicated demand for lightweight composites and specialized alloys to meet unique performance, endurance, and payload requirements.
- Defense Modernization Programs:Increased government defense spending, particularly in the United States and allied nations, supports long-term procurement of advanced materials for new fighter jets, naval vessels, and missile systems, ensuring a stable demand base.
- Additive Manufacturing Adoption:The maturation of additive manufacturing processes enables the production of complex, topology-optimized components from materials like titanium aluminide and nickel superalloys, reducing waste and lead times for critical engine and structural parts.
Market Restraints
- Stringent Qualification Cycles:The extensive and costly process of material qualification and certification by bodies such as the US Federal Aviation Administration (FAA) creates high barriers to entry and slows the adoption of new material innovations.
- Raw Material Price Volatility:Supply chains are exposed to price fluctuations and geopolitical supply risks for critical raw materials, including titanium sponge, cobalt, and carbon fiber precursors, impacting production costs and margin stability.
- Substitution from Incumbent Materials:The high cost and complex processing requirements of advanced composites can limit their application, with designers sometimes opting for improved grades of aluminum and steel alloys that offer a more favorable cost-performance balance.
Strategic Opportunities
- Sustainable Aviation Materials:European Union regulations like the EU Green Deal create opportunities for developing recyclable thermoplastic composites, bio-based resins, and materials compatible with sustainable aviation fuel (SAF) systems, addressing industry environmental mandates.
- Hypersonic and Space Applications:The burgeoning field of hypersonic vehicles and increased commercial space launches present a significant white-space opportunity for developing ultra-high temperature ceramics, ceramic matrix composites (CMCs), and advanced metallic alloys.
- Digital Material Passporting:The development of digital platforms for material traceability offers a chance to provide value-added services, helping customers manage compliance with regulations like REACH and streamline their own quality assurance processes.
Industry Challenges
- Specialized Workforce Scarcity:A persistent shortage of materials scientists, manufacturing engineers, and technicians with expertise in advanced composite fabrication, additive manufacturing, and non-destructive testing hinders production scale-up and innovation efforts.
- Supply Chain Traceability:Implementing robust, end-to-end traceability for materials to comply with standards like AS9100 and evolving sustainability reporting requirements is a complex operational challenge, particularly for globally distributed supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace and Defense Materials Market |
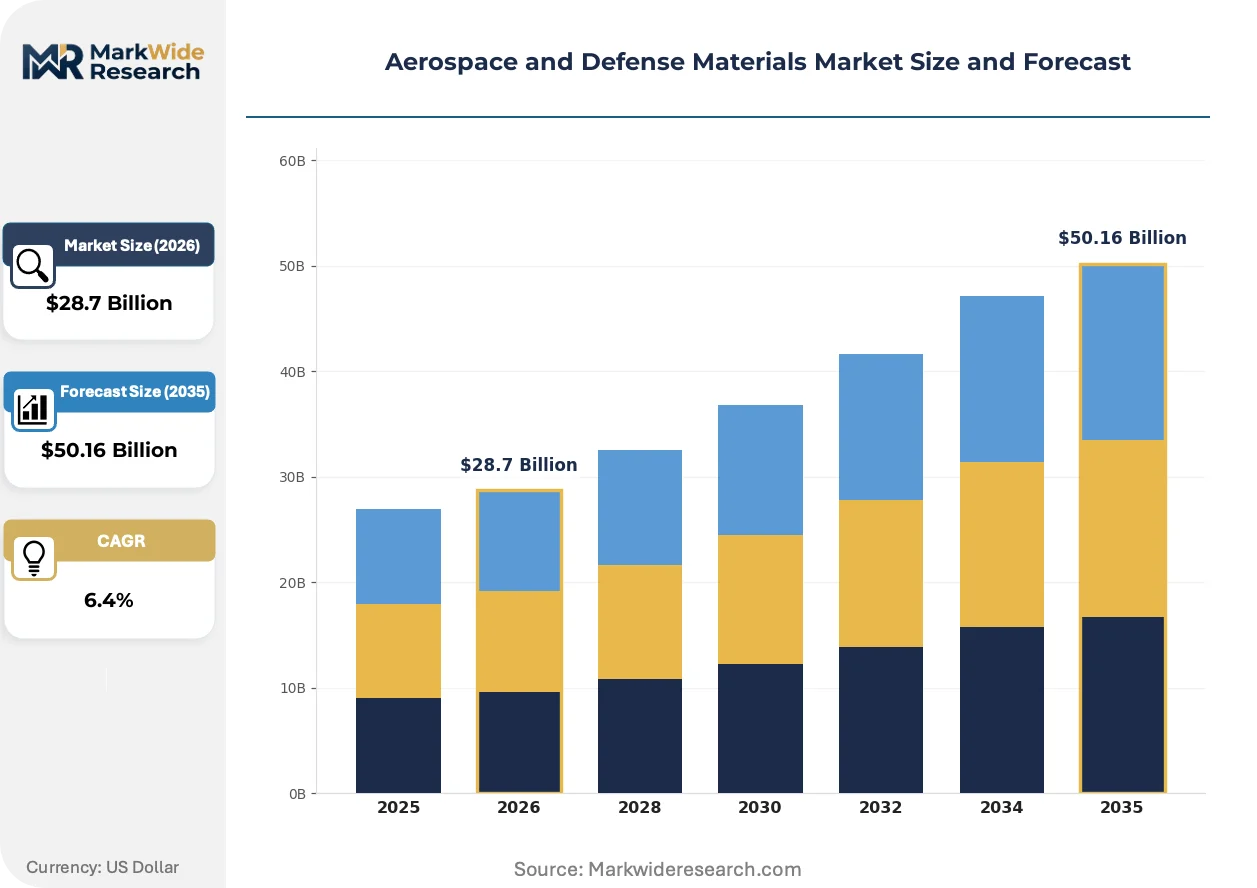
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum Alloys, Titanium Alloys, Composite Materials, Steel Alloys, Nickel Alloys, Ceramics Technology: Heat Treatment, Surface Coating, Additive Manufacturing, Metal Injection Molding, Cryogenic Processing, Forging Application: Airframe Structures, Engine Components, Avionics Housing, Missile Systems, Satellite Components, Spacecraft Frames End User: Military Aircraft Manufacturers, Defense Contractors, Space Agencies, UAV Developers, Satellite Operators, Weapon System Integrators |
| Companies Covered | Park Aerospace Corp., GRACO Inc., Hexcel Corporation, ANEST IWATA Corporation, SATA GmbH & Co. KG, 3M, Ducommun Incorporated, Wagner Group, Spirit AeroSystems Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace and Defense Materials Market Strategic Shifts & Innovations
Digitalization is transforming the material lifecycle from initial design and simulation to in-service health monitoring. This shift connects material science with data science, creating new models for predicting performance, managing maintenance, and ensuring regulatory compliance across the entire value chain.
Digital Twins for Material Performance
Digital twin technology creates a virtual replica of a physical material or component, allowing for the simulation of its behavior under operational stress. Airframe and engine OEMs are adopting this approach to predict fatigue, corrosion, and damage progression, optimizing maintenance schedules. This predictive capability is absorbing the high costs and long timelines associated with traditional, physical testing regimes.
Sustainability and Lifecycle Reporting Mandates
European Union directives, particularly the Corporate Sustainability Reporting Directive (CSRD), are compelling material producers to provide transparent, verifiable data on their products' environmental lifecycle. This regulatory push requires comprehensive tracking of carbon footprint, resource consumption, and end-of-life recyclability. The composites segment is most affected, driving investment in life-cycle assessment (LCA) software and circular economy business models to meet compliance demands.
Performance-Linked Service Models
A notable shift is occurring away from purely transactional material sales toward integrated, performance-based contracts. Under these models, material suppliers are compensated based on the in-service reliability and longevity of their products, such as engine fan blades or fuselage panels. This trend is most visible in the commercial aviation sector in North America, linking material science innovation directly to operational outcomes.
Aerospace and Defense Materials Market Segmentation
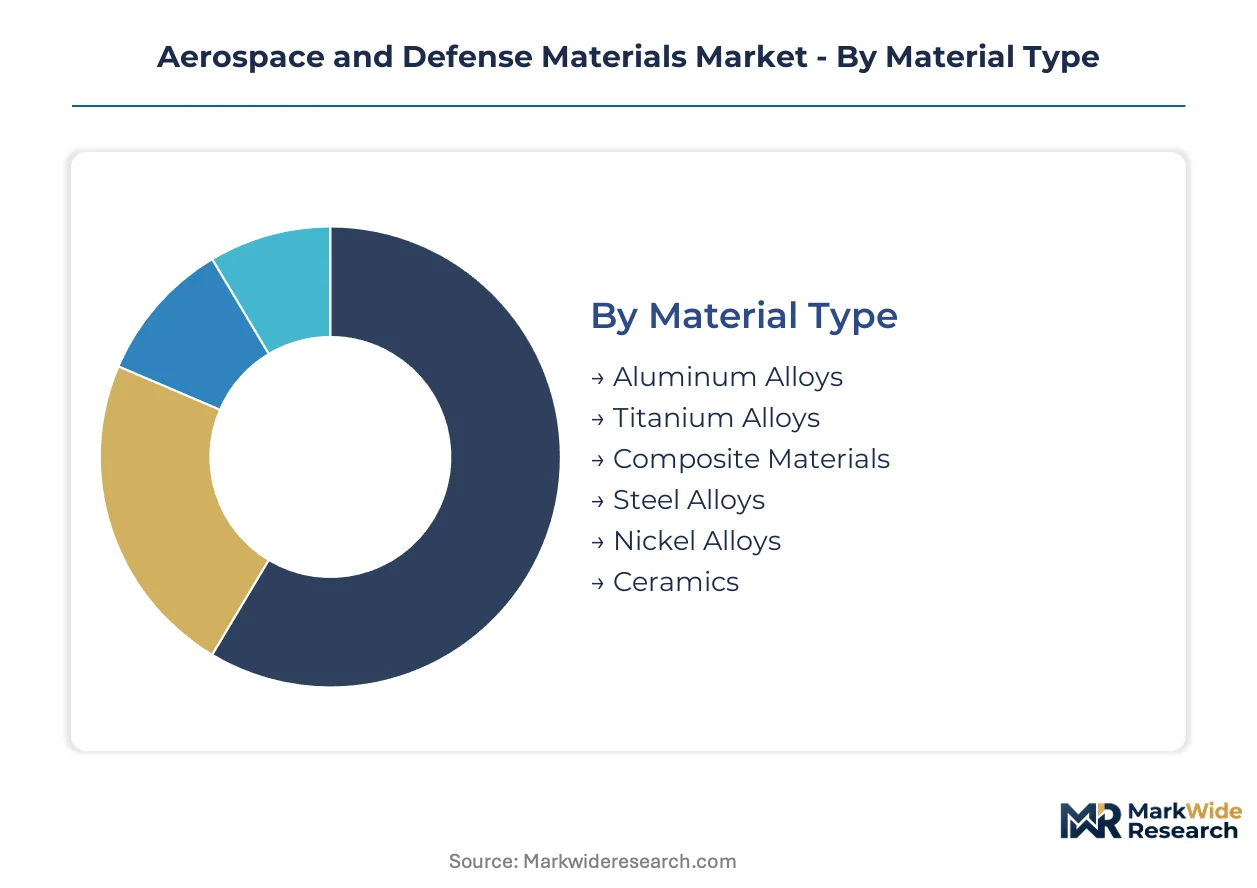
Market segmentation provides a granular understanding of the diverse material requirements and technological demands across the aerospace and defense sectors. This analysis identifies distinct categories crucial for strategic planning and product development. Each segment reflects unique performance criteria, regulatory pathways, and end-user procurement cycles within the industry.
Material Type:
Material specifications define performance envelopes for aerospace and defense applications.
- Composite Materials:These advanced materials, primarily carbon fiber reinforced plastics, offer exceptional strength-to-weight ratios and design flexibility. Demand concentrates in next-generation airframe structures and UAVs, driven by lightweighting initiatives and fuel efficiency mandates.
- Titanium Alloys:Known for their high strength, corrosion resistance, and ability to withstand extreme temperatures, titanium alloys are critical for engine components and high-stress structural parts. Procurement is significant in military aircraft manufacturing and commercial aviation, supporting long operational lifespans.
- Aluminum Alloys:These light, corrosion-resistant metals remain foundational for many airframe and structural components due to their cost-effectiveness and well-established manufacturing processes.
- Steel Alloys:High-strength steel alloys provide robust solutions for landing gear, fasteners, and other components requiring superior fatigue resistance and durability.
- Nickel Alloys:Superalloys based on nickel offer excellent high-temperature strength and creep resistance, essential for hot sections of jet engines and exhaust systems.
- Ceramics:Advanced ceramics and ceramic matrix composites (CMCs) are emerging for ultra-high temperature applications in hypersonic vehicles and missile systems, pushing thermal limits.
Aluminum Alloys lead on scale; Composite Materials lead on momentum.
Technology:
Manufacturing technologies enable the precise shaping and enhancement of specialized materials for their intended use.
- Additive Manufacturing:This technology builds complex, topology-optimized components layer by layer, reducing material waste and enabling rapid prototyping for engine and structural parts. Adoption is accelerating for nickel superalloys and titanium aluminide in commercial and military platforms.
- Heat Treatment:Controlled heating and cooling processes modify the microstructure of metals, enhancing properties such as strength, hardness, and ductility. This technology is fundamental for nearly all metallic components in aircraft and weapon systems, ensuring structural integrity.
- Surface Coating:Application of thin layers to material surfaces improves wear resistance, corrosion protection, and thermal insulation for components exposed to harsh environments.
- Metal Injection Molding:This process combines powdered metals with a binder to create complex shapes with high precision, suitable for small, intricate parts.
- Cryogenic Processing:Ultra-cold treatment of materials can improve their wear resistance and fatigue life, particularly for tools and high-performance components.
- Forging:Mechanical deformation of metals under high pressure produces parts with superior strength and grain structure, commonly used for critical structural elements.
Additive Manufacturing drives innovation; Heat Treatment ensures material integrity.
Application:
Specific application areas impose distinct performance requirements on aerospace and defense materials.
- Airframe Structures:This segment encompasses the primary load-bearing elements of aircraft, including wings, fuselage, and empennage, demanding materials with high strength-to-weight ratios and fatigue resistance. Lightweight composites and advanced aluminum alloys dominate this application, particularly in commercial aviation.
- Engine Components:Materials for engine components must withstand extreme temperatures, high rotational speeds, and corrosive environments, requiring superalloys, titanium, and increasingly, ceramic matrix composites. Demand is constant from both military and commercial engine manufacturers for performance and durability.
- Avionics Housing:Enclosures for electronic systems require materials that offer EMI shielding, thermal management, and lightweight properties, often utilizing specialized aluminum alloys and plastics.
- Missile Systems:Materials for missile bodies, control surfaces, and propulsion systems must endure high speeds, thermal stress, and G-forces, often employing high-strength steels, titanium, and composites.
- Satellite Components:Space-grade materials for satellites must exhibit ultra-lightweight characteristics, thermal stability, and radiation resistance for long-duration orbital missions.
- Spacecraft Frames:Structural elements for rockets and spacecraft demand materials capable of extreme strength, low mass, and resilience to launch stresses and vacuum conditions.
Airframe Structures command significant material demand; Engine Components require extreme material complexity.
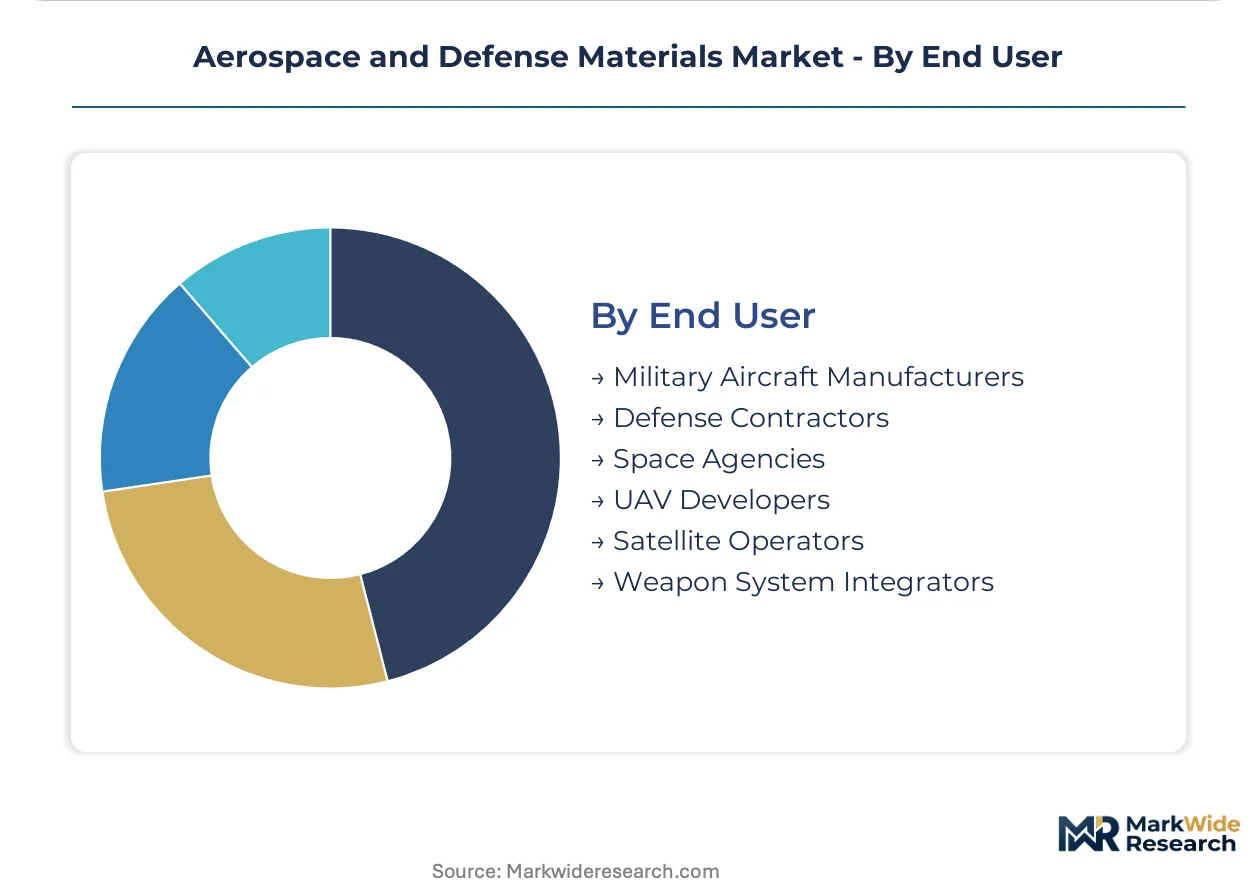
End User:
End-user segments dictate procurement patterns and material qualification pathways within the market.
- Military Aircraft Manufacturers:These entities require materials that meet stringent defense specifications, often involving long qualification cycles and secure supply chains for fighter jets, bombers, and transport aircraft. Procurement is characterized by long-term contracts and high-performance requirements.
- UAV Developers:The expanding UAV market demands lightweight, durable, and cost-effective materials for drones of various sizes and missions. Innovation in composite materials and rapid prototyping technologies supports this segment's agile development cycles.
- Defense Contractors:These companies integrate materials into a wide array of weapon systems, naval vessels, and ground vehicles, focusing on ruggedness, survivability, and regulatory compliance.
- Space Agencies:Government and commercial space agencies procure highly specialized materials for rockets, satellites, and manned spacecraft, prioritizing reliability and performance in extreme environments.
- Satellite Operators:Companies managing satellite constellations require materials that ensure longevity and performance of their in-orbit assets, focusing on radiation resistance and thermal stability.
- Weapon System Integrators:These firms assemble complex weapon systems, sourcing materials for components ranging from projectile casings to guidance system housings, emphasizing precision and durability.
Military Aircraft Manufacturers exert significant market influence; UAV Developers represent a rapidly expanding segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States drives significant demand for aerospace and defense materials through its extensive defense modernization programs, while France leads European material innovation for commercial aviation. Each nation approaches material procurement with distinct regulatory frameworks and industrial concentrations, reflecting their strategic priorities. These regional dynamics shape investment in advanced manufacturing capabilities and specialized material development.
United States
Defense modernization programs and next-generation aircraft development fuel substantial demand for advanced materials in the United States. The US Federal Aviation Administration (FAA) enforces rigorous certification processes for new aerospace materials, ensuring high safety standards. Seattle, Washington, remains a critical hub for commercial aircraft manufacturing, where composite and aluminum alloys are extensively utilized.
France
European defense initiatives and robust commercial aerospace production, particularly by Airbus, necessitate high-performance materials in France. European Union regulations like the EU Green Deal mandate sustainable aviation materials, influencing research and development. Toulouse serves as a major center for aerospace research, development, and manufacturing, concentrating demand for advanced composites and specialized alloys.
Germany
Germany's strong industrial base supports demand for advanced materials across its aerospace and specialized engine component sectors. European Union REACH regulations govern the chemical substances used in these materials, impacting supply chain compliance. The Munich region hosts numerous aerospace suppliers and research institutes, focusing on high-temperature alloys and ceramic matrix composites.
Japan
Domestic defense procurement and the development of satellite components drive demand for high-performance aerospace materials in Japan. The Ministry of Economy, Trade and Industry (METI) actively supports advanced manufacturing initiatives within the aerospace sector. Nagoya is a significant center for aircraft assembly and component production, utilizing titanium and carbon fiber materials.
United Kingdom
Military aircraft upgrades and emerging research into hypersonic applications create demand for specialized materials within the United Kingdom. UK regulatory frameworks ensure aviation safety and environmental compliance for material suppliers. Bristol is home to significant aerospace engineering and manufacturing activities, focusing on advanced composite structures and high-strength alloys.
Aerospace and Defense Materials Market Key Industry Players
Top-tier vendors anchor the premium segment, while specialized material producers and component manufacturers operate within various niche markets. The market structure exhibits a tiered consolidation, with large diversified companies alongside highly specialized material science firms. Strategic archetypes include integrated material suppliers, aerostructure component manufacturers, and adhesive/coating specialists. Strategic partnerships and technology licensing are dominant competitive moves, alongside targeted capacity expansion in advanced composite manufacturing.
Specialists in advanced composite materials like Hexcel Corporation exemplify the innovation-driven segment, providing critical components for next-generation airframes. Spirit AeroSystems Holdings, Inc. occupies a position as a major aerostructure manufacturer, integrating these advanced materials into large-scale assemblies. Diversified material science companies such as 3M offer a broad portfolio of adhesives and coatings, essential for component assembly and protection across the aerospace and defense sectors.
| Leading Market Players |
|---|
| Park Aerospace Corp. |
| GRACO Inc. |
| Hexcel Corporation |
| ANEST IWATA Corporation |
| SATA GmbH & Co. KG |
| 3M |
| Ducommun Incorporated |
| Wagner Group |
| Spirit AeroSystems Holdings, Inc. |
| Others |
Cost & Logistics Intelligence
Additive Manufacturing adoption simultaneously reshapes cost economics and supply concentration within the Aerospace and Defense Materials market. This technology reduces waste and lead times for complex components, influencing material procurement strategies.
Pricing Analysis
Capacity additions in Europe are reshaping price floors for advanced composite materials. The dominant pricing model incorporates long-term contract-based off-take agreements, often supplemented by performance-linked service models. Price differentiation stems from FAA certification levels and customization requirements for specialized components. Raw material price volatility and stringent qualification cycles intensify pricing pressure, making UAV developers the most price-sensitive segment compared to military aircraft manufacturers.
Supply Chain Analysis
Dual-sourcing requirements often mandated by prime contractors mitigate risk across the aerospace and defense supply chain. Geographic supply concentration for critical raw materials like titanium sponge and carbon fiber precursors is notable in the United States and Japan. The supply chain relies on these specific inputs, exposing it to geopolitical supply risks. Distribution predominantly runs through direct sales channels to large OEMs and specialized Tier 1 aerostructure manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Aerospace and Defense Materials market presents a geographic-arbitrage opportunity, driven by differing regulatory burdens. European Union directives like CSRD impose higher compliance costs for sustainable materials compared to current US standards.
For Market Incumbents: Cement long-term supplier relationships with prime contractors to secure positions for next-generation platforms. Invest heavily in R&D for advanced composites and digital material passporting to counter stringent qualification cycles and raw material price volatility. Expand manufacturing capacity in strategic geographies like the US and France to optimize logistics and reduce lead times for critical components.
For New Entrants and Emerging Players: Urban Air Mobility (UAM) aircraft developers represent an underserved buyer archetype seeking agile, rapidly qualifiable material solutions. Target the burgeoning hypersonic and space applications with ultra-high temperature ceramics and advanced metallic alloys. A specific go-to-market angle involves offering performance-validated, on-demand additive manufacturing services for complex engine and structural components.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized material science firms with proprietary IP in advanced composites or additive manufacturing. The market maintains long-term viability, essential for defense modernization and sustainable aviation over the next decade. Acquire companies demonstrating strong capabilities in digital twin technology for accelerated material qualification. The acceleration of digital twin adoption for material qualification serves as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Advanced composite manufacturing capacity expansion in the US supports growing airframe demand. |
| Technology Licensing | Licensing ultra-high temperature ceramic IP accelerates market entry into hypersonic applications. |
| Strategic Partnership | Partnering with UAV developers ensures early integration of lightweight material innovations. |
| R&D Investment | Increased R&D in bio-based resins addresses EU Green Deal sustainability mandates. |
| Digital Platform Development | Developing digital material passporting platforms streamlines regulatory compliance for customers. |
Research Approach
Direct dialogue with aerospace engineers, procurement managers, regulatory compliance officers, and material scientists formed the primary data collection. This primary research was triangulated with extensive secondary validation from FAA certification documents, EU REACH reports, ISO standards, and public company 10-K filings. Both bottom-up and top-down approaches ensured comprehensive market sizing and segmentation.
Quantitative projections were generated using a robust analytical framework, modeling market dynamics across the analysis window. The framework segmented the market by material type, technology, application, end-user, and key geographic regions. Compound annual growth rates were derived from historical trends, coupled with future demand projections based on defense spending budgets and new aircraft program announcements.
Underlying measurement precision varies by segment; established material types and commercial aviation applications carry tighter precision than emerging space and hypersonic segments. Forecasts reflect documented assumptions regarding technological advancements and regulatory stability. Deviation in geopolitical events or raw material supply disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerospace Fiber Optics Market
Aerospace and Aircraft Materials
Global Military Aerospace Coatings Market
Aerospace and Aircraft Materials
Aerospace Composites Market
Aerospace and Aircraft Materials
Global High Strength Aluminum Alloys Market
Aerospace and Aircraft Materials
Aerospace Raw Materials Market
Aerospace and Aircraft Materials
Out-of-Autoclave Composite Skin Panels for Regional and Business Jets Market
Aerospace and Aircraft Materials
Aerospace and Defense Metal Stamping Market
Aerospace and Aircraft Materials
Aerogel Blanket Market
Aerospace and Aircraft Materials
Aerospace Radome Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives and Sealants Market
Aerospace and Aircraft Materials
Aerospace and Defense Composites Market
Aerospace and Aircraft Materials
Stealth Coating Market
Aerospace and Aircraft Materials
Aerospace Composite Ducting Market
Aerospace and Aircraft Materials
Electromagnetic and Radio Frequency Interference Coating Market
Aerospace and Aircraft Materials
Aerospace Foam Market
Aerospace and Aircraft Materials
Commercial Aerospace Carbon Brakes Market