
 Campus Switches Market | 2026-2036
Campus Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Campus Switches Market Outlook
The capability gap between merchant-silicon-dependent vendors and custom-ASIC developers is reorganizing competitive tiers in campus switching. Cisco Systems leverages its proprietary silicon program to sustain pricing power across enterprise deployments. Huawei Technologies anchors its position through integrated supply chains spanning chip design to switch assembly. Arista Networks differentiates via cloud-native operating systems that appeal to hyperscale-influenced campus architects.
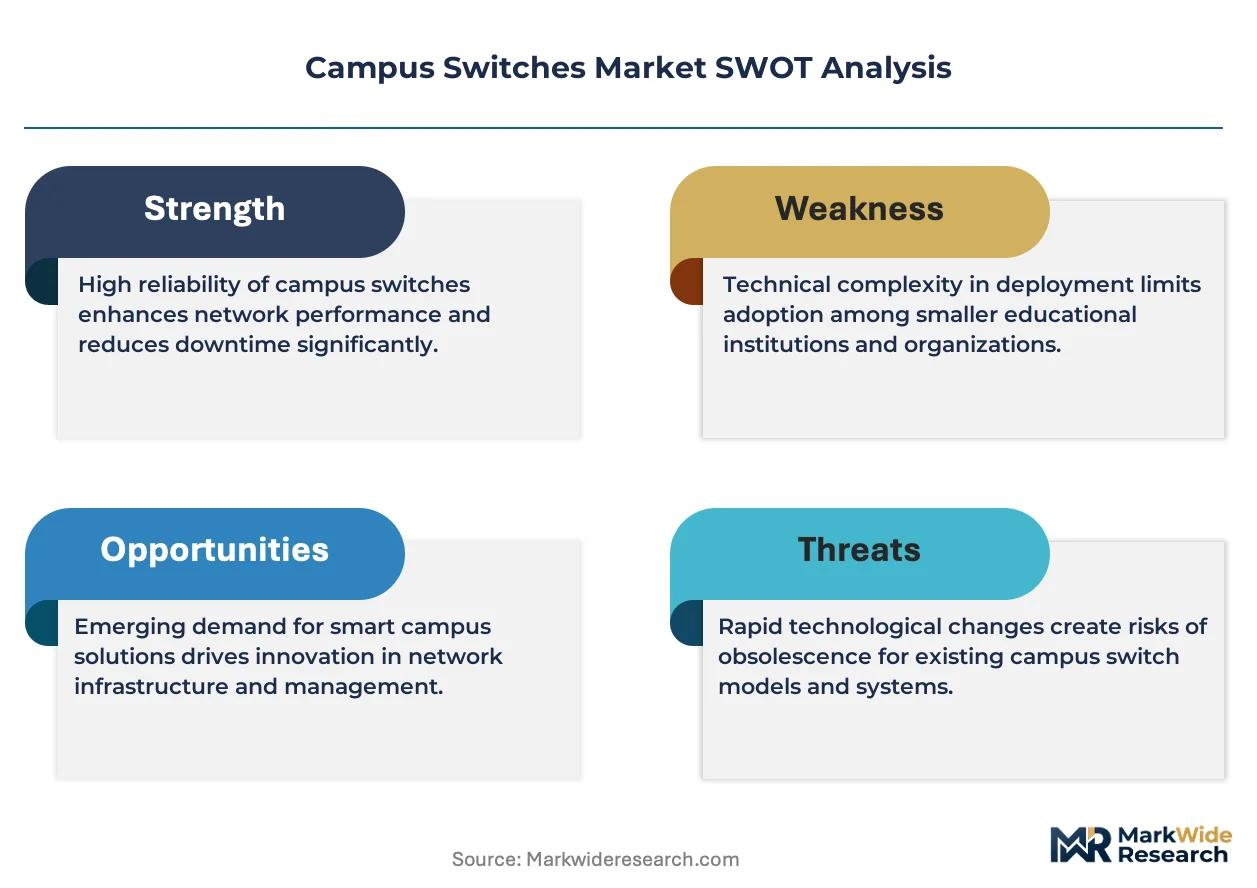
Campus switches are Layer 2/Layer 3 network devices that interconnect endpoints within educational, corporate, and institutional environments, typically supporting port densities from 24 to 96 and power budgets up to 90W per port under IEEE 802.3bt for PoE++ applications. These devices form the aggregation backbone for wireless access points, IoT sensors, and user devices, with management platforms enabling zero-touch provisioning and policy enforcement. Managed switches and PoE switches command the deepest margin pools as organizations prioritize centralized visibility and power delivery for access infrastructure. Cloud-managed deployment models represent the fastest-expanding configuration, though on-premise retains dominance in regulated sectors requiring localized control planes.
The Federal Communications Commission's E-Rate program shapes procurement timelines for U.S. educational institutions, while the EU Cybersecurity Act and CE marking requirements govern product access across European member states. China's GB standards and MIIT network equipment certification create distinct compliance pathways for domestic and imported switch platforms. Stakeholders must weigh ASIC development roadmaps against software subscription attach rates when calibrating long-term positioning in this hardware-software convergence.
Market Dynamics
The campus switches market is experiencing structural pressure from Wi-Fi 7 deployment timelines, which compress refresh cycles and force simultaneous upgrades to multi-gigabit switching infrastructure across educational and corporate environments.
Growth Catalysts
- Federal broadband funding:The FCC's E-Rate program channels capital directly into K-12 and university network infrastructure, accelerating procurement timelines for PoE++ capable switches.
- IoT sensor proliferation:Smart building deployments in higher education require dense PoE port configurations to power environmental monitors, security cameras, and access control systems.
- Hybrid learning permanence:Universities have institutionalized blended instruction models, necessitating resilient campus networks with sub-50ms failover capabilities.
Market Restraints
- ASIC supply concentration:Advanced switching silicon fabrication concentrates among Taiwan-based foundries, exposing lead times to geopolitical friction and capacity constraints.
- Copper commodity volatility:Ethernet cable and PoE magnetics depend on copper pricing, which fluctuates with mining output and speculative trading.
- Technical debt accumulation:Legacy VLAN architectures resist migration to intent-based networking, forcing parallel infrastructure maintenance.
Strategic Opportunities
- Cloud-managed channel expansion:MSPs and value-added resellers are capturing switch deployment contracts previously held by direct enterprise sales teams.
- EU Cybersecurity Act compliance:Mandatory EN 303 645 certification for network equipment creates premium positioning for vendors with pre-certified product lines.
- AI-driven network operations:Convergence of machine learning telemetry with switch fabric management enables predictive fault detection in large campus deployments.
Industry Challenges
- Intent-based networking expertise scarcity:Campus IT departments lack personnel trained in API-driven policy automation and Python-based orchestration.
- Multi-vendor integration complexity:Heterogeneous environments combining incumbent switches with cloud-native alternatives demand specialized professional services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Campus Switches Market |
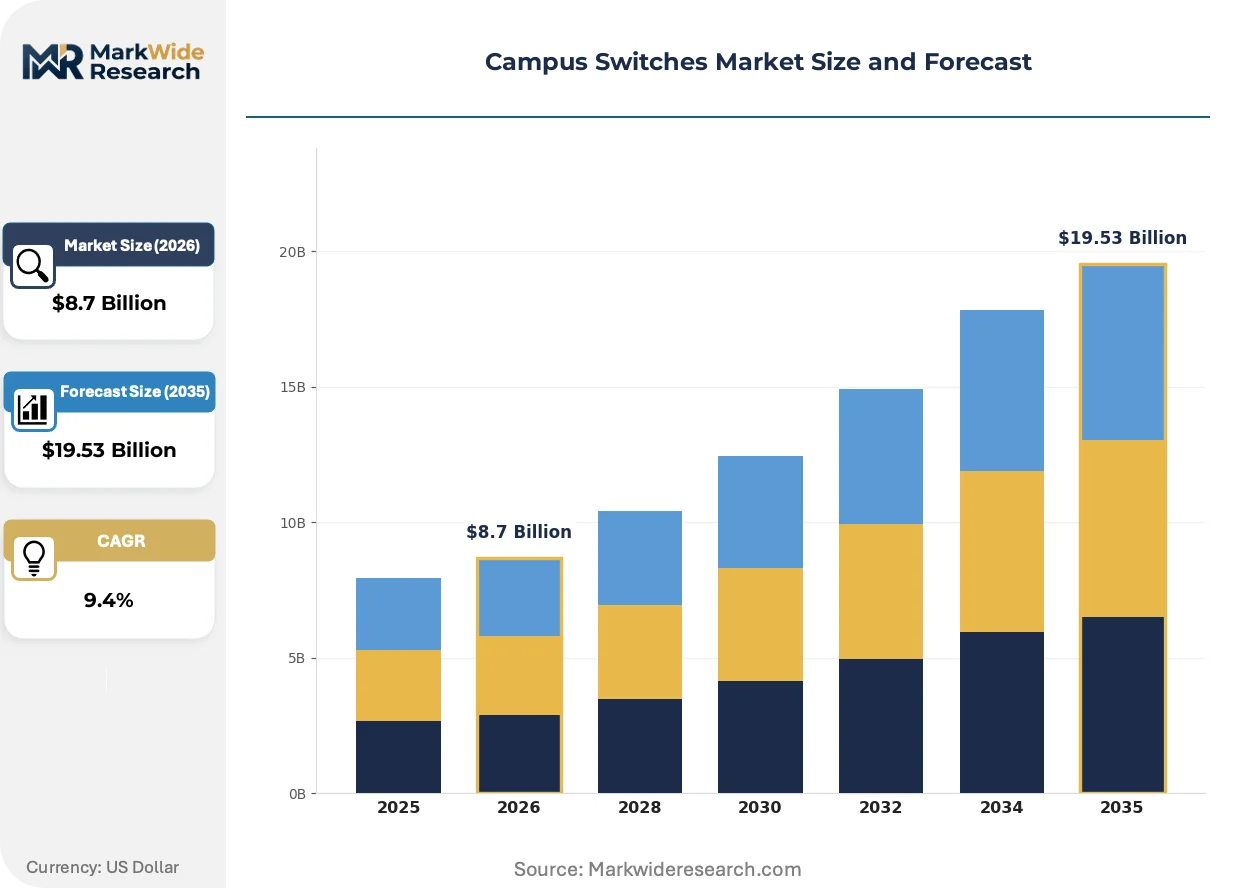
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Managed Switches, Unmanaged Switches, PoE Switches, Stackable Switches End User: Educational Institutions, Corporate Offices, Healthcare Facilities, Government Agencies Deployment: On-Premise, Cloud-Managed, Hybrid, Virtualized Technology: Ethernet, Fast Ethernet, Gigabit Ethernet, Multi-Gigabit Ethernet |
| Companies Covered | Cisco Systems, Huawei Technologies, Hewlett Packard Enterprise, Juniper Networks, Dell Technologies, Extreme Networks, Arista Networks, Allied Telesis, NETGEAR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Campus Switches Market Strategic Shifts
Silicon program differentiation and management plane abstraction are restructuring how campus infrastructure is procured, deployed, and operated across institutional environments.
Merchant silicon is supplanting proprietary ASICs in mid-market switch lines, enabling cost compression without sacrificing baseline performance. Regional universities and community colleges are adopting these platforms fastest, trading marginal feature depth for 40% capital savings. This substitution is compressing gross margins for custom-silicon vendors while expanding addressable volume.
REACH substance restrictions and RoHS recast directives are forcing redesigns of switch chassis and PCB assemblies across European deployments. Manufacturers must eliminate restricted flame retardants and heavy metals from power supply units. Vendors with pre-validated green material libraries are capturing tenders from German and French public universities ahead of compliance deadlines.
Subscription-based network management is displacing perpetual license purchases in North American higher education. CIOs favor operational expenditure models that bundle hardware refreshes with software support, particularly at research universities with constrained capital budgets. This preference is visible most acutely in California and Texas public university systems negotiating multi-campus framework agreements.
Campus Switches Market Segmentation
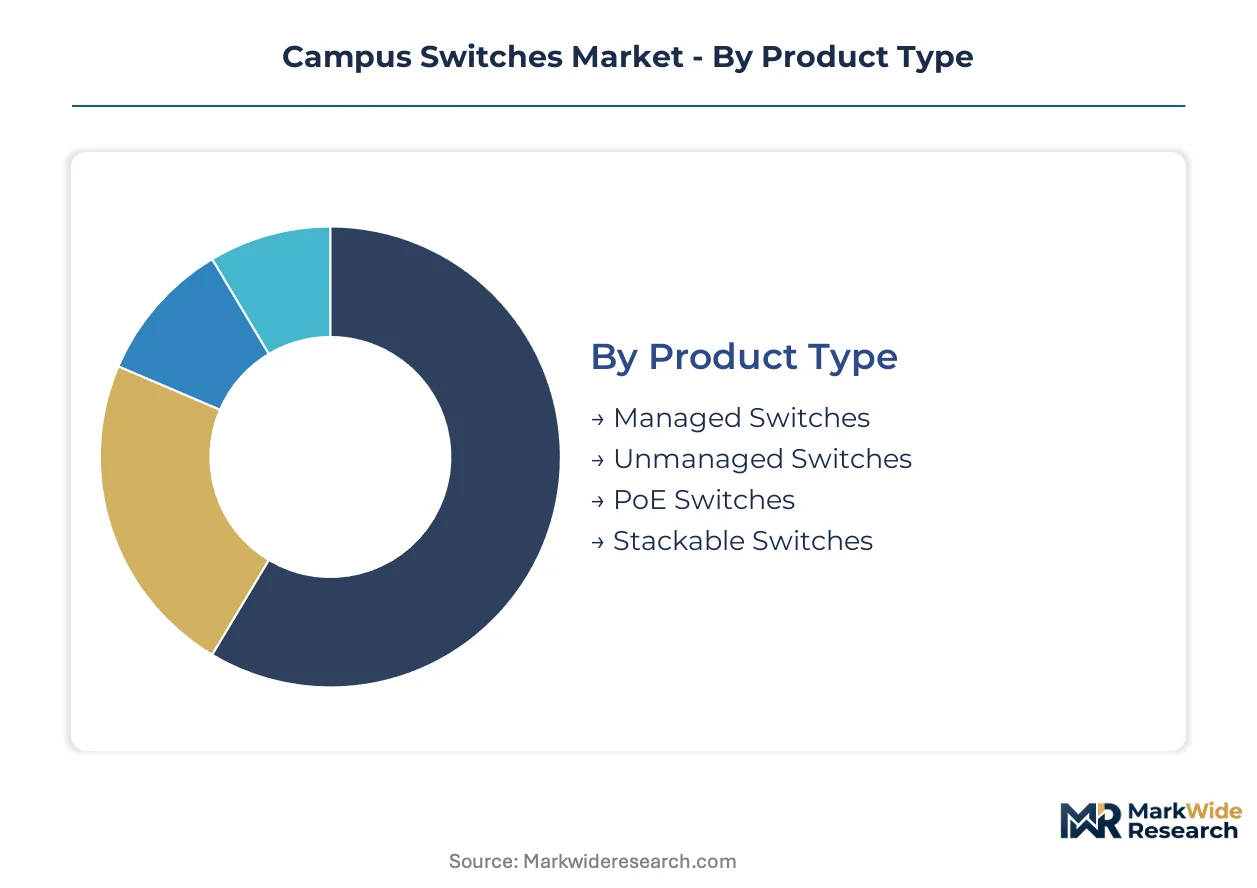
Campus switch procurement decisions cluster around four orthogonal axes: hardware capability, institutional buyer type, operational control plane, and physical layer speed. Each axis carries distinct regulatory, budgetary, and technical constraints that reshape vendor positioning.
Product Type:
FCC E-Rate certification requirements and EU Cybersecurity Act EN 303 645 compliance create divergent margin structures across switch categories, with certified managed platforms commanding premium positioning in institutional tenders.
- Managed Switches:These platforms embed centralized configuration engines, SNMP monitoring stacks, and role-based access control. Demand concentrates in United States K-12 districts leveraging E-Rate subsidies for PoE++ aggregation backbones. Compliance documentation burdens favor incumbent vendors with pre-certified product lines.
- PoE Switches:IEEE 802.3bt power delivery up to 90W per port enables single-cable deployment of Wi-Fi 7 access points and pan-tilt-zoom cameras. German technical universities and Texas public university systems are standardizing on these configurations for smart building retrofits. Thermal design and magnetics quality separate premium from commodity tiers.
- Unmanaged Switches:Plug-and-play Layer 2 forwarding without configuration interfaces. Small California community colleges and French regional vocational institutes deploy these for cost-constrained edge extensions.
- Stackable Switches:Physical interconnection via proprietary backplane cables creates single management domains across multiple chassis. Corporate campuses in Illinois and Bavaria favor these for modular growth without controller forklift upgrades.
Established volume favors managed platforms; emerging adoption favors PoE switches.
End User:
Buyer procurement authority and capital cycle timing separate segments more sharply than technical requirements, with educational institutions operating on E-Rate-driven refresh calendars distinct from corporate CapEx windows.
- Educational Institutions:K-12 districts and universities dominate PoE++ port demand for wireless density and IoT sensor grids. United States federal broadband funding flows disproportionately into this segment, compressing vendor sales cycles.
- Corporate Offices:Hybrid work permanence has shifted priority from density to segmentation, with micro-branch switches requiring SD-WAN integration. German Mittelstand manufacturers and Illinois healthcare conglomerates drive multi-gigabit refresh timelines.
- Healthcare Facilities:HIPAA-compliant isolation VLANs and medical device power requirements shape specifications. Texas hospital systems and Bavarian Klinikum networks prioritize deterministic latency for imaging workflows.
- Government Agencies:FedRAMP and EU classified network accreditation create vendor pre-qualification barriers. California state facilities and French prefecture deployments favor domestic supply chain provenance.
Procurement concentration sits with educational buyers; margin expansion favors healthcare deployments.
Deployment:
Control plane location determines operational staffing models, with cloud-managed alternatives displacing on-premise dominance in budget-constrained environments while regulated sectors retain localized management.
- Cloud-Managed:Subscription-based dashboards enable zero-touch provisioning without dedicated network engineering staff. California State University system and French Grandes Écoles are expanding multi-campus framework agreements around these platforms.
- On-Premise:Localized controllers satisfy air-gapped requirements and sub-50ms failover mandates. Texas research universities and Bavarian defense contractors maintain these configurations for sensitive workloads.
- Hybrid:Policy orchestration splits between cloud analytics and on-device enforcement. Illinois healthcare networks and German automotive corporate campuses pilot these for regulatory flexibility.
- Virtualized:Switch control planes running as containerized workloads on standard compute. Emerging in United States federal testbeds and French cloud-first government modernization programs.
Cloud-managed configurations are climbing the fastest; on-premise retains regulated sector anchoring.
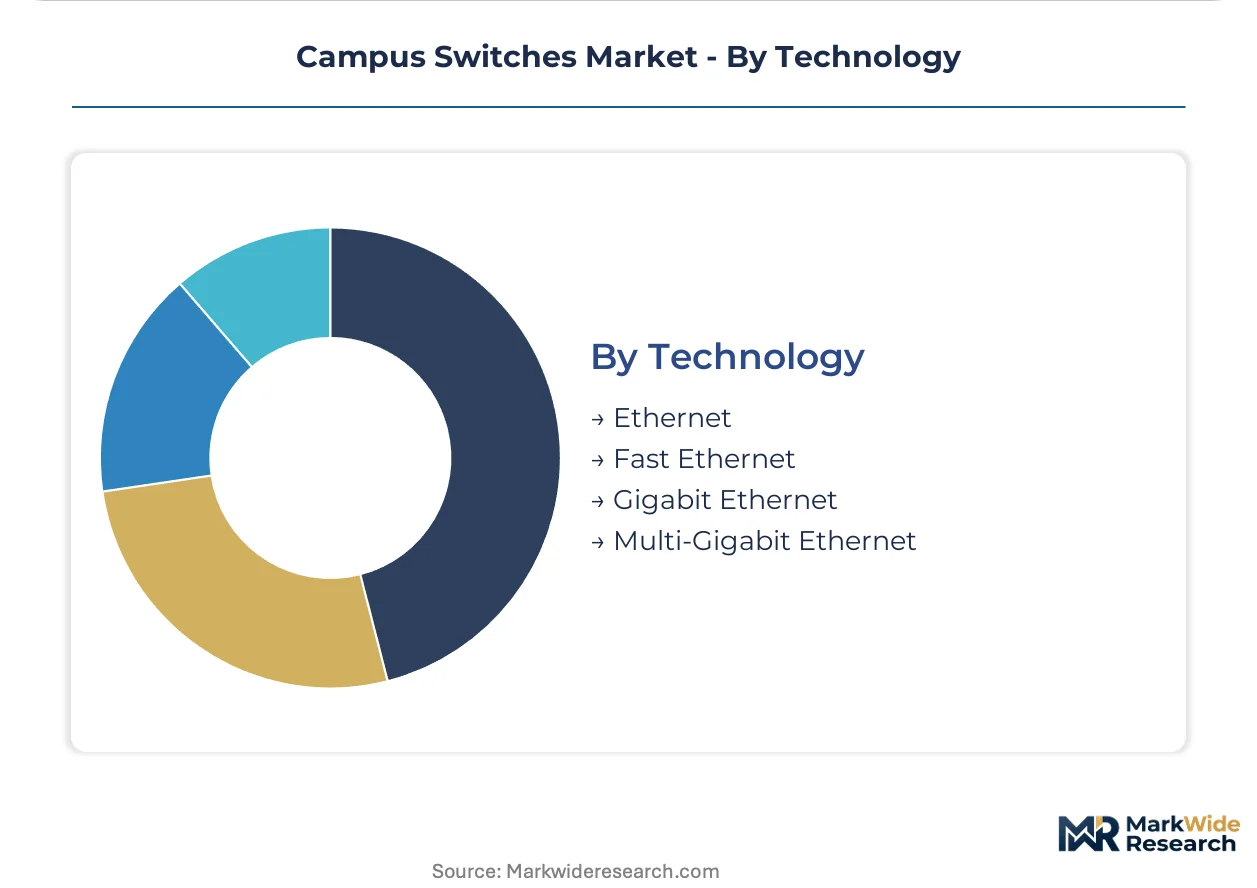
Technology:
Physical layer speed tiers map directly to Wi-Fi generation support requirements, with multi-gigabit adoption accelerating where Wi-Fi 7 access point density justifies cable infrastructure replacement.
- Multi-Gigabit Ethernet:NBASE-T standards enable 2.5G/5G/10G over existing Cat5e/Cat6 cabling. United States higher education and German technical universities lead deployment for 802.11be access point backhaul.
- Gigabit Ethernet:IEEE 802.3ab remains the default for desktop and standard wireless access. California K-12 districts and French regional university hospitals standardize here for cost-controlled refreshes.
- Fast Ethernet:100 Mbps ports persist in legacy building automation and environmental sensor aggregation. Bavarian municipal facilities and Illinois school districts maintain these for non-critical IoT.
- Ethernet:10 Mbps legacy connectivity for obsolete equipment support. Minimal new procurement; replacement demand only in Texas industrial campuses with vintage control systems.
Gigabit Ethernet holds installed base dominance; multi-gigabit Ethernet shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a structural trade surplus in advanced campus switching equipment, exporting proprietary-ASIC platforms while importing merchant-silicon alternatives from Asian contract manufacturers. German and Chinese markets exhibit near-balanced trade profiles, with domestic production serving regional demand clusters.
United States
Federal E-Rate program disbursements drive K-12 procurement cycles, with the FCC channeling infrastructure subsidies into PoE++ capable aggregation backbones. California State University system negotiates multi-campus framework agreements for cloud-managed deployments. Research Triangle Park in North Carolina hosts testing facilities for Wi-Fi 7 readiness validation.
Germany
REACH substance restrictions and RoHS recast directives force chassis redesigns for European market access. Bavarian technical universities standardize on multi-gigabit NBASE-T configurations for smart building retrofits. Stuttgart's industrial automation corridor pilots deterministic latency switches for manufacturing-IT convergence.
China
MIIT network equipment certification and GB standards create distinct compliance pathways for domestic versus imported platforms. Yangtze River Delta manufacturing clusters produce merchant-silicon switch platforms for cost-sensitive education verticals. Shenzhen's enterprise networking hub concentrates firmware development for cloud-native operating systems.
Japan
METI industrial standards and JIS certification requirements shape product specifications for institutional buyers. Tokyo metropolitan universities prioritize sub-50ms failover capabilities for hybrid learning resilience. Osaka-Kobe manufacturing belt supplies precision magnetics for high-wattage PoE++ power delivery systems.
United Kingdom
CE marking and post-Brexit UKCA conformity assessment govern network equipment market access. London's higher education consortiums negotiate centralized procurement for SD-WAN integrated campus architectures. Cambridge technology cluster hosts validation labs for intent-based networking policy automation.
Campus Switches Market Competitive Environment
Concentration sits with custom-ASIC developers and cloud-native operating system specialists, creating a tiered structure where proprietary silicon programs command premium positioning. Merchant-silicon vendors occupy mid-market volume segments through cost compression. Strategic moves center on subscription-based management attach rates and vertical integration into chip design-to-assembly supply chains.
Within the custom-ASIC tier, Cisco Systems and Huawei Technologies exemplify divergent supply chain architectures, with the former leveraging captive silicon foundry relationships and the latter integrating from semiconductor design through finished switch assembly. Arista Networks occupies a position representing cloud-native management plane abstraction, appealing to hyperscale-influenced campus architects. Hewlett Packard Enterprise and Juniper Networks sit within the hybrid archetype, balancing proprietary hardware elements with merchant-silicon cost structures.
| Leading Market Players |
|---|
| Cisco Systems |
| Huawei Technologies |
| Hewlett Packard Enterprise |
| Juniper Networks |
| Dell Technologies |
| Extreme Networks |
| Arista Networks |
| Allied Telesis |
| NETGEAR |
| Others |
Value Chain & Pricing Dynamics
Twenty-six-week ASIC foundry lead times concentrate pricing power with Taiwan-based wafer fabricators, compressing margins for merchant-silicon campus switch vendors while amplifying premiums for custom-ASIC developers with captive supply arrangements. This inventory-to-pricing nexus forces procurement officers at United States universities and German technical institutes into long-term offtake commitments to secure allocation.
Pricing Analysis
Configured-to-order pricing for PoE++ switches with 90W port budgets commands a 35-50% premium over standard SKUs, reflecting thermal engineering and magnetics customization. Three-tier pricing structure across premium, standard, and economy levels stratifies by ASIC program depth and FCC E-Rate certification status. Cost compression in mid-market merchant-silicon tiers is intensifying because Taiwanese foundry capacity constraints favor high-volume commitments. California community colleges exhibit acute price sensitivity, while Texas research universities prioritize deterministic latency over unit economics.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for advanced switching silicon, while China's Yangtze River Delta concentrates PCB assembly and chassis manufacturing. Copper magnetics for PoE++ power delivery draw from Japanese suppliers in the Osaka-Kobe belt. Single-source vulnerability in 7nm ASIC foundry capacity exposes lead times to geopolitical friction. Distribution runs through authorized value-added resellers and MSPs for cloud-managed deployments, with direct OEM relationships dominating on-premise regulated sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: FCC E-Rate certification creates multi-year vendor lock-in for United States educational procurement.
For Market Incumbents: Compound switching cost advantages by embedding subscription-based network management into multi-campus framework agreements, neutralizing cloud-native challengers. Deepen backward integration into custom silicon design to defend margin position against merchant-silicon price erosion. Prioritize EN 303 645 pre-certification for European tender access. For New Entrants and Emerging Players: Anchor in French regional vocational institutes and California community college systems where E-Rate documentation burdens favor agile certification specialists over incumbents. Target unmanaged switch edge extensions as the most penetrable volume tier. Pursue MSP channel partnerships to bypass direct enterprise sales team incumbency. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because subscription attach rates for cloud-managed campus networks generate predictable cash flows decoupled from hardware refresh volatility. Acquisition targets should exhibit vertical integration into firmware development and established Grandes Écoles framework relationships. Monitor Wi-Fi 7 access point shipment trajectories as the inflection signal for multi-gigabit switch demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ASIC Supply Agreement | Captive foundry allocation from TSMC insulates Cisco and Huawei from Taiwan Strait disruption. |
| Cloud-Native OS Launch | Arista's EOS-derivative platforms attract hyperscale-influenced campus architects in Research Triangle Park. |
| E-Rate Certification Investment | FCC pre-approval unlocks $4.7 billion annual subsidy flow into K-12 and university infrastructure. |
| PoE++ Thermal Design Patent | Proprietary magnetics architectures enable 90W port density without chassis redesign for Wi-Fi 7 backhaul. |
| MSP Channel Partnership | Cloud-managed deployment contracts shift procurement authority from CIOs to service provider aggregators. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, encompassing campus network architects at California State University and Texas A&M systems, procurement officers in Bavarian technical universities, value-added resellers specializing in E-Rate compliance, and semiconductor supply planners at Taiwanese foundries. Secondary validation drew from FCC E-Rate disbursement databases, MIIT network equipment certification registries, EU Cybersecurity Act EN 303 645 documentation, and SEC filings of publicly traded networking vendors. Bottom-up port shipment estimates triangulated against top-down infrastructure spending forecasts.
Across the analysis window, the quantitative framework modeled campus switch demand through four segmentation dimensions: product type hierarchy, end-user procurement authority, deployment control plane location, and physical layer speed tier. CAGRs were derived from slope-intercept modeling of historical refresh cycles against Wi-Fi 7 rollout timelines. Industry-specific inputs included E-Rate funding authorization trajectories, copper commodity price volatility bands, and REACH substance restriction compliance deadlines.
Decision-makers should treat outputs as directional under sustained federal broadband funding and stable Taiwan Strait logistics; material deviation in either would warrant model refresh. Specific risk factors encompass ASIC foundry capacity reallocation toward AI accelerators, abrupt E-Rate program restructuring, and RoHS recast directive scope expansion. Recalibration cycles align with material shifts in Wi-Fi 7 access point penetration rates and hyperscaler capex disclosure patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Asia-Pacific High Voltage Switchgear Market
Switches
Panel Mounted Disconnect Switch Market
Switches
Europe Push Buttons and Signaling Devices Market
Switches
Differential Pressure Switches Market
Switches
Rotary Limit Switches Market
Switches
Safety Limit Switches Market
Switches
DC Switchgear Market
Switches
Global Switchgear Market
Switches
Asia Pacific Safety Switches Market
Switches
DC Circuit Breaker Market
Switches
Navigation Switches Market
Switches
Canada Switch Gear Market
Switches
Power Load Switches Market
Switches
ASEAN Switchgear Market
Switches
Japan Reed Sensors Switches Market
Switches
Disconnect Switch Market