
 Asia Pacific Transfer Switches Market | 2026-2036
Asia Pacific Transfer Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Transfer Switches Market Outlook
Japan's METI carbon neutrality roadmap is decoupling industrial power backup requirements from conventional diesel-dependent architectures. Schneider Electric SE leverages its regional manufacturing footprint to supply automatic switchgear for hyperscale facilities. Cummins Inc anchors the generator-integrated transfer switch segment through its longstanding dealer network across Australia and India. Kohler Power differentiates via specialized healthcare-grade switching systems that sustain hospital operations during grid instability.
Asia Pacific transfer switches are electromechanical or solid-state devices engineered to shift electrical load between independent power sources, typically operating within 16 milliseconds for static variants to prevent data loss or equipment damage. Their primary purpose is ensuring uninterrupted power for mission-critical operations across healthcare, telecommunications, and industrial process control. Automatic switches command the dominant share as facility managers prioritize remote operability and reduced human intervention in unmanned substations. Static transfer switches represent the fastest-expanding category, driven by semiconductor-grade tolerances demanded by data center operators. Double-throw switches retain relevance in legacy industrial settings where cost sensitivity outweighs speed requirements.
Japan's PMDA and METI enforce medical-grade electrical reliability standards that mandate dual-source redundancy for hospital surgical suites and imaging departments. India's CEA and BIS jointly regulate low and medium voltage switchgear certification, creating compliance barriers for uncertified imports while accelerating domestic assembly partnerships. China's GB standards and SAMR quality supervision framework shape product testing protocols for grid-connected infrastructure. Stakeholders must weigh the trade-off between static switch speed premiums and automatic switch total cost of ownership as edge computing diffuses beyond established metropolitan data hubs.
Market Dynamics
State grid modernization programs across China and India's tightening electrical safety mandates are forcing rapid replacement of manual switchgear with automatic transfer systems, compressing procurement cycles for industrial and data center operators.
Growth Catalysts
- Hyperscale data center expansion:Cloud computing demand across Southeast Asia is mandating sub-16-millisecond failover capability, accelerating static transfer switch procurement for facilities in Singapore and Indonesia.
- India's BIS certification tightening:The Bureau of Indian Standards now mandates third-party testing for critical infrastructure switchgear, creating replacement demand for uncertified legacy installations in manufacturing corridors.
- Semiconductor-grade power tolerance:Wafer fabrication facilities in Taiwan and South Korea require microsecond-level transfer precision, pulling solid-state switch technology from adjacent industrial applications.
Market Restraints
- Copper and silicon carbide cost volatility:Raw material price swings for static switch semiconductor substrates are compressing margins for mid-tier switchgear assemblers.
- Domestic supply concentration in China:GB standards compliance requires in-country testing facilities, creating barriers for foreign manufacturers without established Chinese assembly partnerships.
- Technical speed-ceiling for electromechanical variants:Automatic transfer switches face hard physical limits below 100 milliseconds, disqualifying them from hyperscale data center specifications.
Strategic Opportunities
- Vietnam's emerging industrial zones:Northern provinces near Hanoi lack established backup power infrastructure, creating first-mover advantage for automatic switchgear providers.
- Healthcare-grade switching systems:Japan's PMDA surgical suite redundancy mandates are opening specialized procurement channels for dual-source hospital installations.
- Edge computing facility proliferation:Distributed data nodes beyond metropolitan hubs require compact, remotely operable transfer switches with cellular monitoring integration.
Industry Challenges
- Power electronics engineering scarcity:Static switch design requires semiconductor physics expertise that outpaces regional vocational training output.
- Multi-standard certification timelines:Manufacturers targeting China, India, and Japan simultaneously face non-harmonized testing protocols from SAMR, BIS, and METI respectively.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Transfer Switches Market |
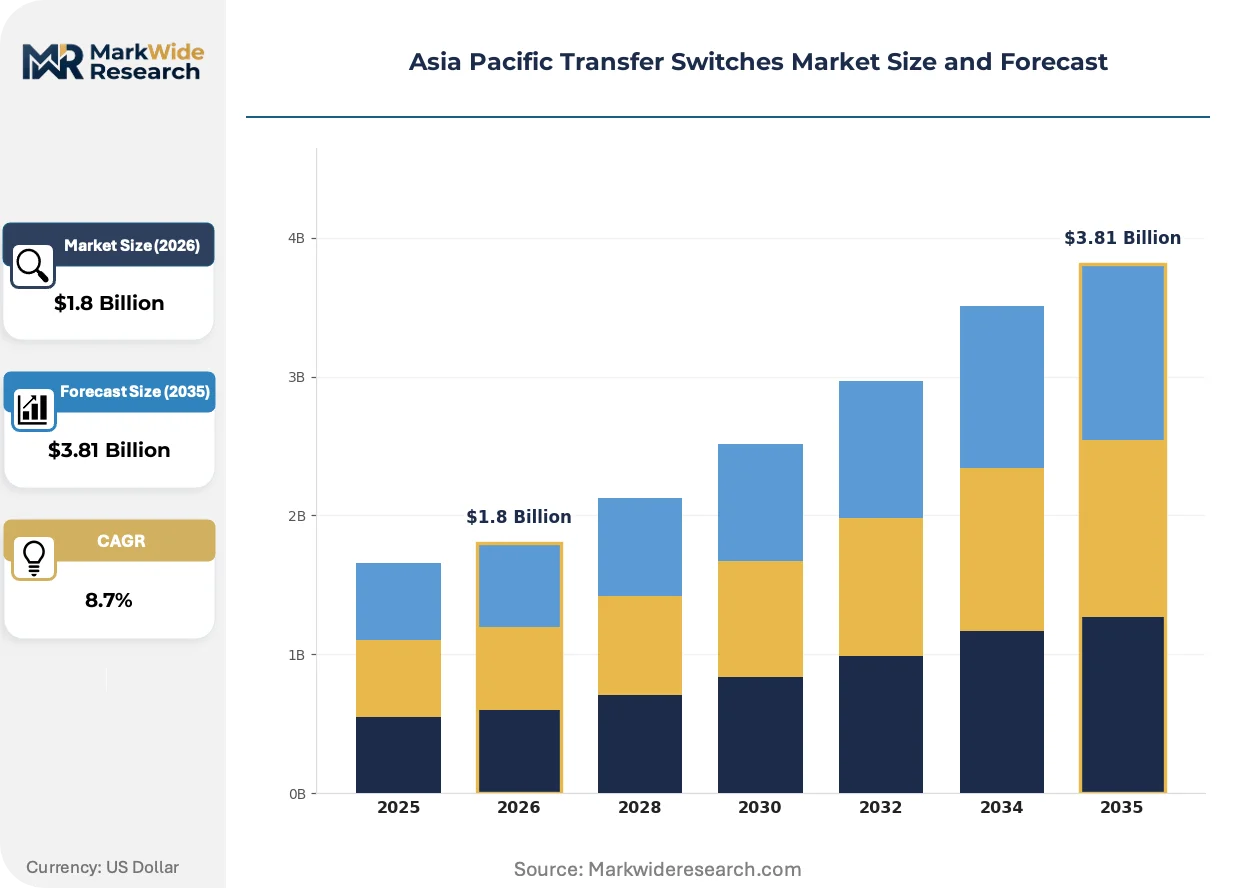
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Switches, Automatic Switches, Static Switches, Double-throw Switches Installation Type: Indoor, Outdoor, Wall-mounted, Rack-mounted End User: Commercial, Industrial, Healthcare, Data Centers Power Rating: Low Voltage, Medium Voltage, High Voltage, Ultra High Voltage |
| Companies Covered | Siemens AG, Cummins Inc, Schneider Electric SE, General Electric, Kohler Power, ABB Ltd, Generac Power Systems Inc, Emerson Electric Company, Eaton Corporation PLC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Transfer Switches Market Strategic Shifts
Solid-state semiconductor switching is compressing failover windows below electromechanical limits while regulatory pressure on carbon-intensive backup architectures is reshaping procurement specifications across the region.
Silicon carbide MOSFET arrays are integrating into static transfer switch designs to achieve sub-cycle interruption times. Data center operators in Singapore and Sydney are specifying these variants for hyperscale facilities despite 40-60% cost premiums over thyristor-based alternatives. The technology is integrating predictive thermal monitoring that prevents cascading failures during repeated rapid transfers.
Japan's METI carbon neutrality roadmap is decoupling industrial backup requirements from diesel-dependent architectures. The policy mandates renewable-source readiness for new installations above 500kVA, forcing switchgear manufacturers to engineer multi-source input capability. Hospital and semiconductor fabrication buyers are responding by specifying dual-compatible automatic switches that accept both grid and battery storage feeds.
Facility managers are consolidating vendor relationships around full-stack power continuity providers. Standalone transfer switch procurement is contracting as buyers prefer integrated generator-switchgear packages with unified service contracts. This pattern is most visible in Australia's mining and India's pharmaceutical manufacturing sectors, where single-source accountability reduces downtime dispute friction.
Asia Pacific Transfer Switches Market Segmentation
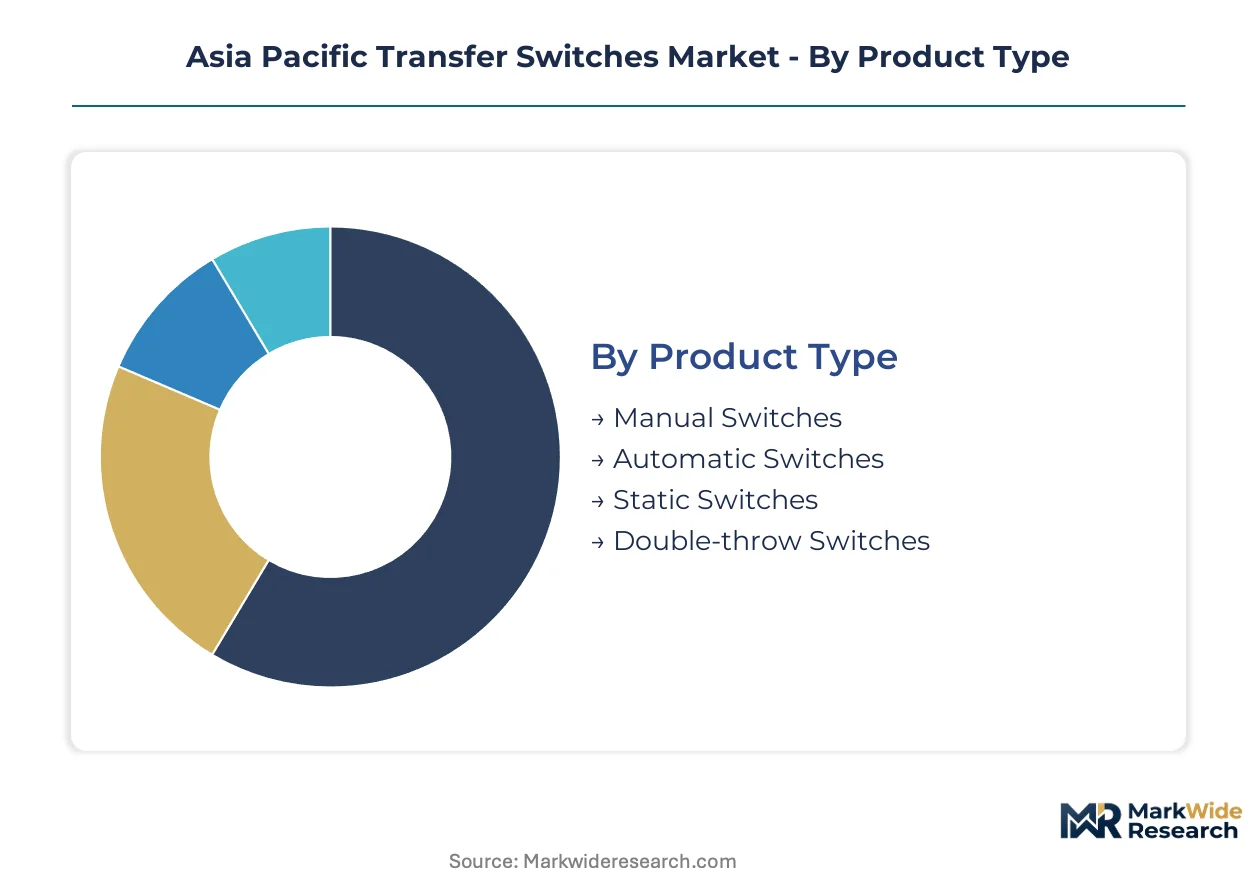
Transfer switch procurement patterns diverge sharply across installation environments and operational criticality. Facility engineers prioritize failover speed thresholds, environmental resilience ratings, and regulatory compliance tiers when specifying equipment for Asia Pacific deployments.
Product Type:
Supply concentration tilts toward electromechanical manufacturers with established foundry partnerships across China and India.
- Automatic Switches:Microprocessor-controlled mechanisms execute load transfers within 50-100 milliseconds using motorized contactors. Industrial corridors in China's Yangtze River Delta and India's Maharashtra state absorb the majority of procurement volume as state grid modernization programs mandate remote operability.
- Static Switches:Silicon-controlled rectifier and IGBT arrays achieve sub-16-millisecond transfers without mechanical wear. Singapore and Sydney hyperscale data centers specify these variants exclusively, accepting 40-60% cost premiums for semiconductor-grade power continuity.
- Manual Switches:Operator-actuated rotary or toggle mechanisms serve cost-sensitive legacy installations in Vietnam's emerging industrial zones.
- Double-throw Switches:Mechanical interlock designs prevent simultaneous grid connection in rural electrification projects across Indonesia and the Philippines.
Automatic switches absorb the bulk of installed capacity; static switches are expanding most quickly.
Installation Type:
Cost tier separation runs deepest between weather-hardened outdoor enclosures and standardized indoor cabinet formats.
- Indoor:Climate-controlled switchgear rooms in Taiwan semiconductor fabs and Japanese hospitals demand sealed NEMA 12 enclosures with particulate filtration. METI electrical reliability standards mandate redundant cooling integration for installations above 500kVA.
- Rack-mounted:19-inch chassis designs slide into standard server cabinets at edge computing nodes. Australian telecommunications providers specify these for cellular base station upgrades requiring sub-10kVA footprints.
- Outdoor:IP65-rated housings with tropicalized coatings withstand monsoon humidity in Thailand manufacturing estates and Malaysian palm oil processing facilities.
- Wall-mounted:Compact surface installations serve retail banking branches and clinic networks across South Korea's secondary cities.
Indoor configurations retain the largest revenue base; rack-mounted formats are climbing the fastest.
End User:
Application-specific certification requirements fragment procurement workflows across sectoral boundaries.
- Data Centers:Hyperscale operators in Singapore, Jakarta, and Sydney specify static switches with predictive thermal monitoring. Sub-16-millisecond failover prevents server memory corruption during repeated grid disturbances.
- Healthcare:Japan's PMDA mandates dual-source redundancy for surgical suites and MRI suites. Kohler Power and Schneider Electric compete for hospital-grade installations requiring IEC 60364-7-710 compliance.
- Industrial:Process control facilities in Taiwan and South Korea prioritize electromechanical automatic switches for motor load compatibility. Wafer fabrication cleanrooms demand semiconductor-grade power tolerance.
- Commercial:Office towers and retail complexes across India's Bangalore and Hyderabad favor cost-optimized automatic switches with basic remote monitoring.
Data center deployments command the steepest expansion trajectory; industrial installations maintain the deepest installed base.
Power Rating:
Volume concentration sits at low voltage tiers where manufacturing scale and component standardization compress unit economics.
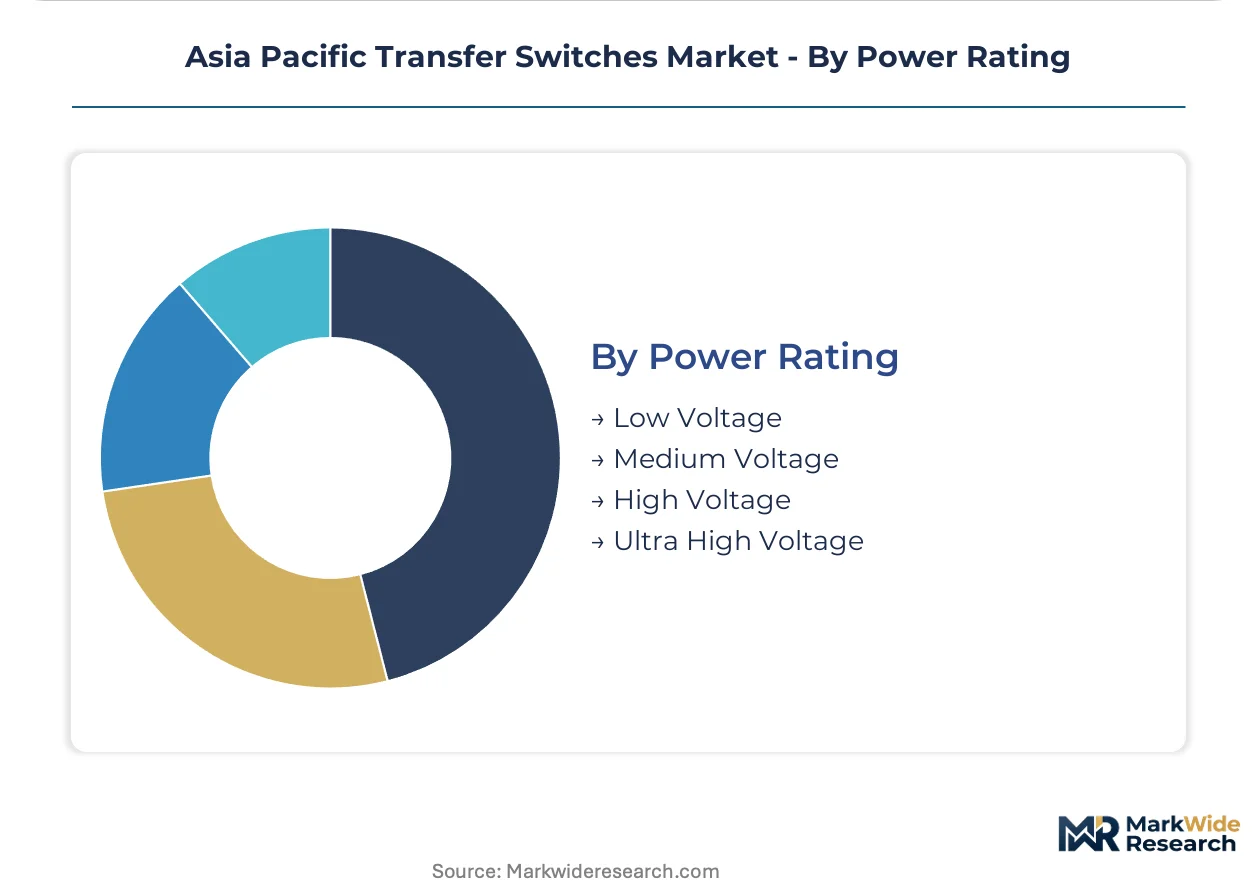
- Low Voltage:Up to 1kV ratings dominate commercial and light industrial procurement. Chinese GB standards and Indian BIS certification frameworks shape testing protocols for this mass-market tier.
- Medium Voltage:1kV-36kV switches serve heavy manufacturing and district cooling plants. Thailand's Eastern Economic Corridor and Vietnam's northern industrial zones drive replacement demand as grid infrastructure upgrades.
- High Voltage:36kV-150kV applications concentrate in utility-scale substations and aluminum smelters. Procurement cycles extend 18-24 months due to custom engineering requirements.
- Ultra High Voltage:Above 150kV ratings remain confined to state grid backbone projects in China and interconnector stations in Australia.
Low voltage equipment captures the greatest shipment volumes; medium voltage systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Tuas industrial corridor concentrates hyperscale data center construction, driving procurement of sub-16-millisecond static transfer switches for cloud computing infrastructure across Southeast Asia.
China
State Grid modernization programs in the Yangtze River Delta prioritize automatic transfer switch deployment for industrial corridor reliability. SAMR quality supervision frameworks mandate in-country testing facilities, compressing procurement cycles for foreign manufacturers seeking GB standards compliance. Manufacturing clusters in Jiangsu and Zhejiang provinces absorb the dominant share of medium-voltage switchgear volume.
India
Bureau of Indian Standards tightened certification mandates for critical infrastructure equipment, creating replacement demand across Maharashtra and Karnataka manufacturing belts. CEA grid reliability directives accelerate automatic switchgear adoption in unmanned substations. Pharmaceutical and automotive corridors near Pune and Chennai drive low-voltage procurement concentration.
Japan
METI carbon neutrality roadmaps decouple industrial backup from diesel-dependent architectures, mandating renewable-source readiness above 500kVA. PMDA surgical suite redundancy standards enforce dual-source automatic switch specifications for hospital installations. Kanto and Kansai metropolitan areas concentrate healthcare-grade demand.
Australia
Mining operations in Western Australia and Queensland specify integrated generator-switchgear packages for remote site power continuity. Telecommunications infrastructure upgrades across New South Wales drive rack-mounted transfer switch procurement for cellular base stations. National electricity market reliability standards accelerate replacement of legacy manual switchgear.
Vietnam
Northern industrial zones near Hanoi lack established backup power infrastructure, creating first-mover positioning for automatic switchgear providers. Foreign direct investment in electronics manufacturing drives demand for semiconductor-grade power tolerance. Provincial grid instability accelerates procurement timelines for facilities in Bac Ninh and Hai Duong provinces.
Asia Pacific Transfer Switches Market Competitive Environment
The competitive structure tilts toward diversified electrical equipment conglomerates with integrated power continuity portfolios. Mid-tier specialists face margin compression from raw material volatility and certification compliance costs. Two strategic archetypes dominate: full-stack power infrastructure providers bundling switchgear with generation assets, and semiconductor-grade switching specialists serving hyperscale data center specifications. Capacity expansion in Southeast Asian assembly facilities and technology licensing partnerships for silicon carbide MOSFET arrays represent the dominant competitive vectors.
Among diversified industrial conglomerates, Siemens AG and ABB Ltd occupy positions spanning electromechanical and solid-state switch architectures. Schneider Electric SE exemplifies the integrated power continuity archetype through regional manufacturing footprints serving automatic switchgear demand. Kohler Power anchors specialized healthcare-grade positioning for hospital and medical facility installations. These three companies represent distinct strategic postures: broad portfolio diversification, regional supply chain integration, and application-specific certification focus.
| Leading Market Players |
|---|
| Siemens AG |
| Cummins Inc |
| Schneider Electric SE |
| General Electric |
| Kohler Power |
| ABB Ltd |
| Generac Power Systems Inc |
| Emerson Electric Company |
| Eaton Corporation PLC |
| Others |
Value Chain & Pricing Dynamics
Silicon carbide MOSFET adoption in static transfer switches is simultaneously compressing manufacturing cost curves and concentrating production capability among semiconductor-integrated foundries. This technology transition rewards suppliers with captive wafer fabrication access while squeezing margins for electromechanical assemblers dependent on commodity copper and silicon carbide spot markets.
Pricing Analysis
Uptime-guarantee contracts anchor pricing structures for hyperscale data center operators who specify sub-16-millisecond failover. Three-tier pricing stratifies across semiconductor-grade static switches, electromechanical automatic variants, and manual legacy installations. Cost compression in mid-tier automatic switchgear intensifies as copper contactor prices fluctuate and Indian BIS certification adds compliance overhead. Pharmaceutical manufacturers in Pune and Chennai exhibit highest price sensitivity, prioritizing total cost of ownership over speed premiums.
Supply Chain Analysis
China's GB standards compliance requirements are reshaping sourcing patterns by mandating in-country testing facilities for grid-connected infrastructure. Manufacturing concentrates in Jiangsu and Zhejiang provinces for electromechanical assemblies, with Taiwan and South Korea supplying silicon carbide substrates and IGBT arrays. Single-source vulnerability runs through semiconductor-grade component streams, particularly for static switch MOSFET arrays. Distribution runs through integrated power continuity providers bundling switchgear with generator assets, compressing standalone procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific transfer switches market sits in a technology-transition phase where solid-state semiconductor switching displaces electromechanical architectures in mission-critical applications. Static transfer switches with silicon carbide MOSFET arrays are capturing specification share from automatic variants in hyperscale data centers and semiconductor fabrication facilities.
For Market Incumbents: Anchor defensive positioning through backward integration into silicon carbide semiconductor sourcing and certification pre-positioning for India's tightening BIS mandates. Incumbents must consolidate around full-stack power continuity offerings that bundle switchgear with generator assets, as standalone procurement contracts in Australia's mining sector and India's pharmaceutical corridors shift toward unified service accountability. Electromechanical specialists face margin compression from raw material volatility and speed-ceiling limitations below 100 milliseconds. For New Entrants and Emerging Players: Systems integrators with existing hospital relationships represent the most accessible channel pathway for specialized healthcare-grade switchgear penetration. Northern Vietnam's electronics manufacturing zones near Hanoi and Bac Ninh offer white-space positioning where backup power infrastructure remains underdeveloped and provincial grid instability accelerates procurement timelines. New entrants should target rack-mounted compact formats for edge computing nodes requiring cellular monitoring integration and sub-10kVA footprints. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified electrical equipment conglomerates seeking semiconductor-grade switching capability. Long-term viability favors targets with established SAMR testing partnerships for China GB compliance and METI-recognized quality frameworks for Japan healthcare installations. Watch hyperscale data center capex announcements in Singapore and Jakarta as inflection indicators for static switch demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Technology Licensing | Enables sub-16-millisecond failover for Singapore hyperscale facilities. |
| Domestic Assembly Partnership Formation | Secures SAMR testing access for China state grid modernization programs. |
| Healthcare-Grade Certification Investment | Opens PMDA-mandated procurement channels for Japan surgical suite installations. |
| Integrated Generator-Switchgear Packaging | Captures Australia's mining sector preference for single-source accountability. |
| Edge Computing Rack-Mounted Format Development | Targets distributed data nodes beyond metropolitan hubs requiring remote operability. |
Study Parameters
Document review covered regulatory filings from BIS, SAMR, and METI, complemented by interviews with data center infrastructure directors, hospital biomedical engineers, and industrial plant maintenance managers. Secondary validation drew from customs trade data, SEC filings of diversified electrical equipment manufacturers, and state grid procurement disclosures. Primary fieldwork with generator-set distributors and switchgear OEM procurement teams supported bottom-up volume estimates, while top-down triangulation against national electrification investment programs anchored value projections.
Segmentation-level outputs across product type, installation format, end-user vertical, and power rating tier were generated through the projection horizon. CAGRs were derived from installed base turnover analysis and greenfield capacity announcements across Southeast Asian data center corridors. Forecast inputs incorporated semiconductor fabrication capex cycles, hospital infrastructure investment pipelines, and industrial zone electrification timelines.
Several conditions sit outside the modeled scope, including abrupt commodity price spikes in copper and silicon carbide, unilateral tariff impositions on electrical equipment imports, and technological disruption from battery-backed UPS architectures that bypass transfer switching entirely. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and grid reliability improvement trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Reed Switches Sensors Market
Switches
Europe Switchgear Market
Switches
India Switchgear Market
Switches
Drive Mode Selector Switch and Controller Systems Market
Switches
Ethernet Switch Market
Switches
Smart Home Switches Market
Switches
APAC Push Buttons and Signaling Devices Market
Switches
Pad-Mounted Switchgear Market
Switches
Global Disconnector Switch Market
Switches
Argentina Automotive Reed Sensors Switches Market
Switches
Global Push Buttons and Signalling Devices Market
Switches
Australia Switchgear Market
Switches
UK Reed Sensors Switches Market
Switches
Zero Speed Switch Market
Switches
Smart Plugs and Switches Market
Switches
Membrane Switch Market