
 Optical Cross Connect (OXC) Switches Market | 2026-2036
Optical Cross Connect (OXC) Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Cross Connect (OXC) Switches Market Analytics
China is rewriting capacity dynamics in optical switching through state-backed investments in domestic photonics manufacturing corridors. Huawei Technologies Co. Ltd. leverages captive silicon photonics foundries to control component costs across its OXC portfolio. Ciena Corporation sustains R&D intensity in liquid crystal on silicon architectures for programmable wavelength routing. Nokia Corporation anchors European supply security through its Bell Labs heritage in wavelength-selective switch design.
Optical Cross Connect (OXC) Switches are fiber-optic network elements that reconfigure light paths without optical-to-electrical conversion, typically supporting port counts from 32x32 to 576x576 with switching speeds under 50 milliseconds for circuit restoration. These systems enable transparent wavelength routing across metro, regional, and long-haul transport layers. MEMS Switches occupy the premium tier for high-port-count reconfigurable optical add-drop multiplexers, while Photonic Switches compete on nanosecond-scale switching for packet-optical convergence. Wavelength Routing technology dominates telecom backbone deployments, whereas Circuit Switching retains entrenched positions in legacy SONET/SDH migration scenarios.
FCC open-access rules and the EU AI Act's data infrastructure transparency mandates are reshaping how carriers qualify OXC vendors for interconnection points. China's GB standards on optical transport network equipment and the US NIST cybersecurity framework for critical infrastructure collectively elevate compliance burdens for cross-border deployments. Stakeholders must monitor divergence between national spectrum allocation regimes and optical layer encryption requirements as procurement criteria harden.
Market Dynamics
Hyperscale data center operators are forcing wavelength-selective switching architectures into metro networks to handle explosive east-west traffic volumes, compressing deployment cycles from years to quarters.
Growth Catalysts
- MIIT next-generation optical guidelines:China's domestic procurement standards are accelerating state-backed fiber infrastructure builds across provincial transport corridors.
- Hyperscale data center expansion:Cloud operators are retrofitting metro rings with 576x576 port-count OXC systems to support machine-learning cluster interconnects.
- Liquid crystal on silicon maturation:Programmable wavelength routing is reducing reconfiguration latency below 50 milliseconds for circuit restoration scenarios.
Market Restraints
- Silicon photonics foundry concentration:Captive production capacity in China creates supply security risks for Western equipment vendors.
- MEMS actuator cost structure:Precision micro-electromechanical components require specialized fabrication that limits economies of scale below 256x256 port configurations.
- FCC open-access rule friction:Interconnection point qualification timelines are extending vendor certification cycles for cross-border deployments.
Strategic Opportunities
- SONET/SDH migration whitespace:Circuit switching legacy infrastructure in North American incumbent networks represents a 15-year replacement backlog.
- EU AI Act data infrastructure mandates:Transparency requirements for high-performance computing networks are creating compliance-driven upgrade cycles.
- Photonic switch convergence:Nanosecond-scale packet-optical integration is opening data center interconnect applications beyond traditional telecom boundaries.
Industry Challenges
- Multi-physics simulation expertise gap:Thermal-optical co-design for high-density wavelength routing requires specialized talent pools concentrated in Bell Labs heritage institutions.
- GB standards compliance timelines:China's optical transport equipment certification processes create 18-24 month product validation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Cross Connect (OXC) Switches Market |
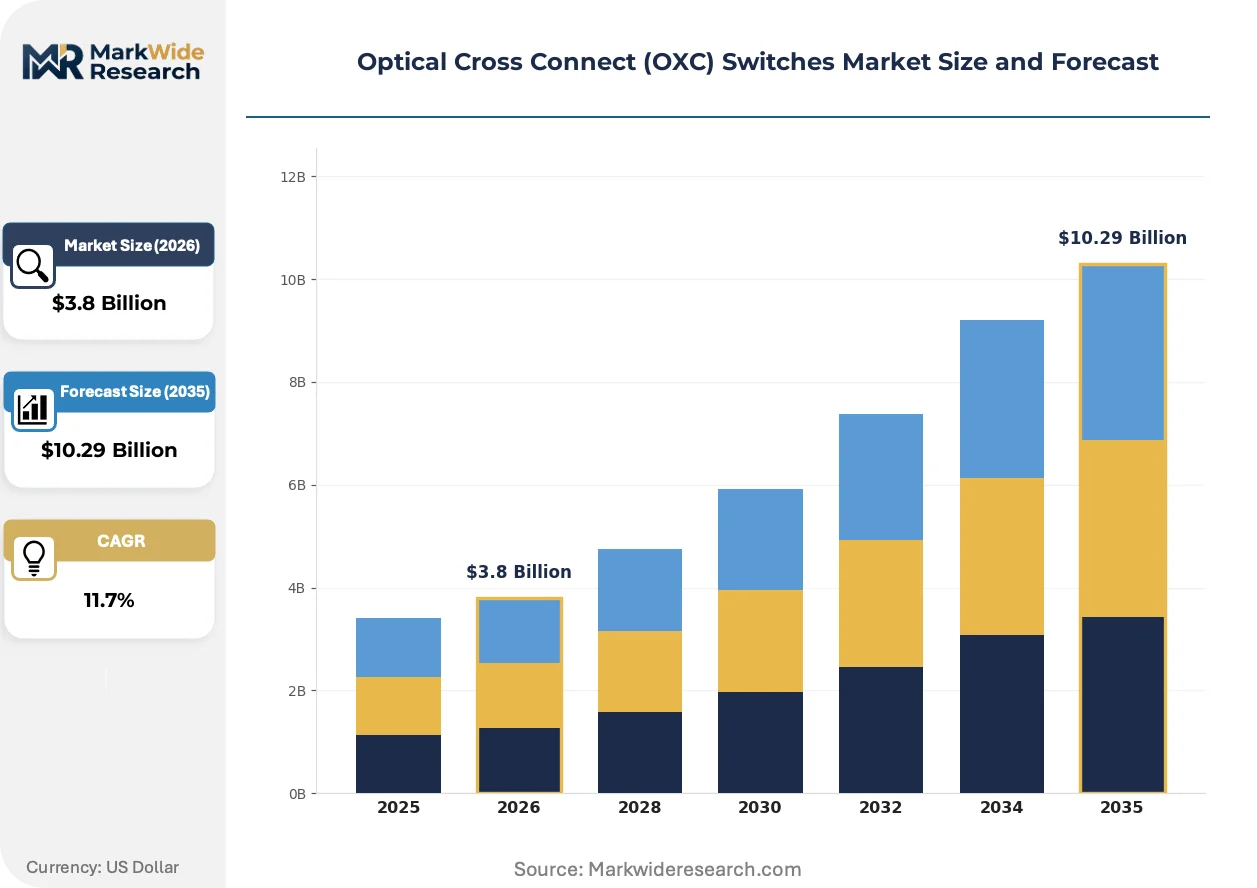
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical Switches, MEMS Switches, Photonic Switches, Hybrid Switches Application: Telecommunications, Data Centers, Network Infrastructure, Cloud Services End User: Telecom Operators, Enterprises, Cloud Providers, Managed Service Providers Technology: Wavelength Routing, Circuit Switching, Packet Switching, Optical Routing |
| Companies Covered | Fujitsu Ltd., Ciena Corporation, Huawei Technologies Co. Ltd., Infinera Corporation, Nokia Corporation, Cisco Systems Inc., Juniper Networks Inc., Lumentum Holdings Inc., Broadcom Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Cross Connect (OXC) Switches Market Evolving Landscape
Wavelength-selective switching architectures are undergoing rapid functional expansion as port densities scale and control plane integration deepens across transport layers.
Silicon photonics-based optical engines are migrating from discrete component assemblies to co-packaged photonic-electronic chiplets. Hyperscale operators in the United States are adopting these integrated platforms for 400G and 800G line-side interfaces. The technology is migrating from telecom backbone applications into data center interconnects, compressing traditional transponder-agnostic switching margins.
The EU AI Act's infrastructure transparency mandates are forcing carriers to document optical layer encryption and wavelength path provenance. Equipment vendors must now embed audit-grade logging in wavelength-selective switch control planes. European operators are responding by pre-qualifying vendors against CSRD-aligned supply chain disclosure requirements before procurement.
Cloud providers are consolidating optical transport procurement under direct equipment sourcing, bypassing traditional systems integrators. This disintermediation concentrates buying power among five to seven hyperscale architects who specify custom port-count and software-defined networking integration. The pattern is most visible in United States metro network builds where Amazon, Microsoft, and Google account for the majority of new 576x576 OXC port deployments.
Optical Cross Connect (OXC) Switches Market Segmentation
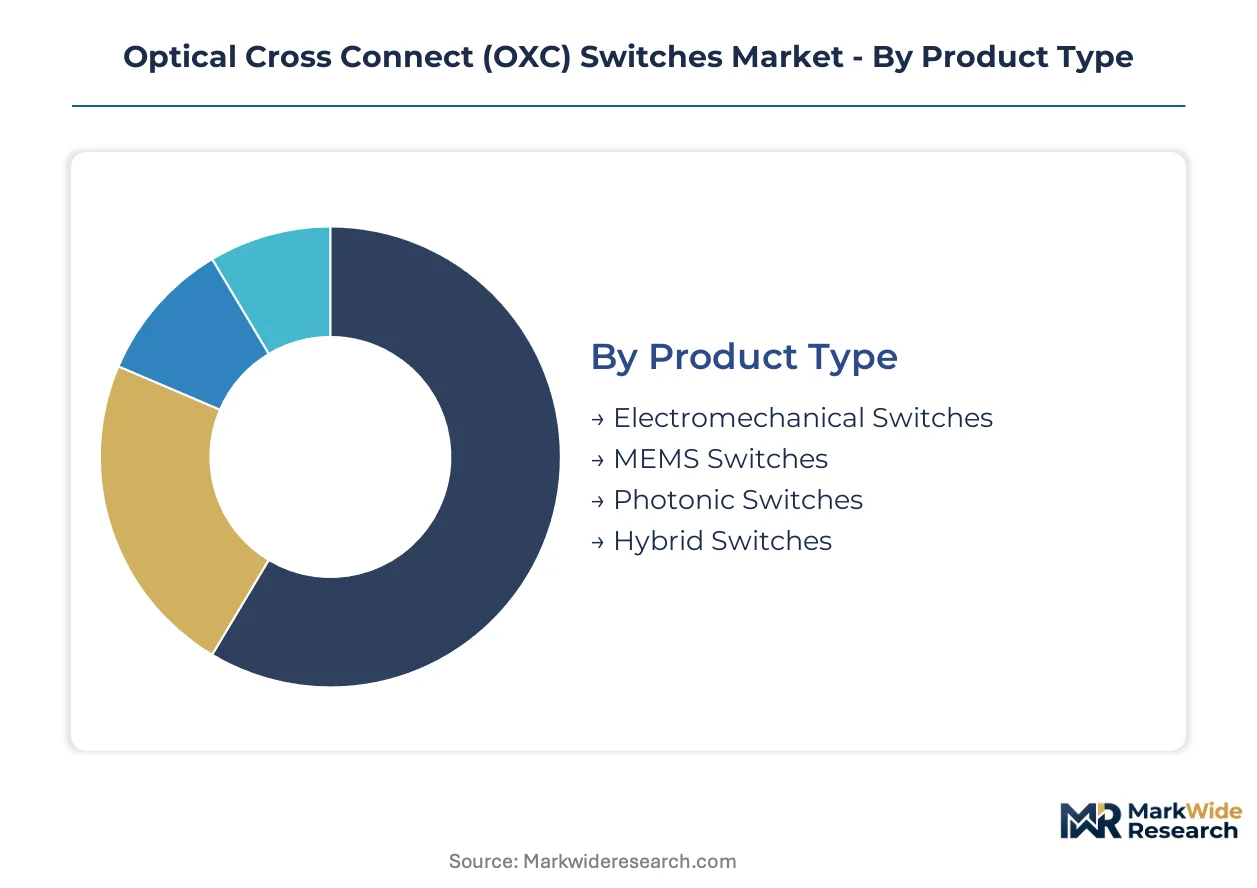
OXC switch architectures fragment across four distinct dimensions. Product type determines switching speed and port density ceilings. Application context dictates whether wavelength transparency or packet convergence takes priority in procurement specifications.
Product Type:
Mature electromechanical designs anchor legacy deployments while emerging photonic architectures target nanosecond-scale reconfiguration requirements.
- Electromechanical Switches:Relay-based architectures achieve port counts up to 32x32 with millisecond-scale switching latencies. Demand concentrates in North American incumbent carrier networks where SONET/SDH migration timelines extend replacement cycles over legacy infrastructure.
- MEMS Switches:Micro-electromechanical mirror arrays deliver 256x256 to 576x576 port configurations with sub-50-millisecond restoration speeds. Cloud providers in the United States specify these systems for metro ring builds handling machine-learning cluster interconnects.
- Photonic Switches:All-optical architectures eliminate opto-electronic conversion for nanosecond-scale packet-optical convergence.
- Hybrid Switches:Integrated platforms combine MEMS port density with photonic switching modules for flexible service provisioning.
MEMS Switches handle the majority of throughput; Photonic Switches are expanding most quickly on share in data center interconnect applications.
Application:
Volume concentration follows traffic gravity centers rather than traditional geographic demand patterns.
- Telecommunications:Backbone wavelength routing across metro, regional, and long-haul transport layers. Carriers in China deploy 576x576 systems under MIIT next-generation optical guidelines for provincial corridor builds.
- Data Centers:East-west traffic management for hyperscale compute clusters. United States cloud operators retrofit metro rings with wavelength-selective switching to support 400G and 800G line-side interfaces.
- Network Infrastructure:Multi-tenant exchange points and carrier-neutral facilities.
- Cloud Services:Direct optical layer connectivity bypassing traditional transport aggregation.
Telecommunications absorbs the largest equipment volume; Data Centers are climbing the fastest as procurement cycles compress from years to quarters.
End User:
Buying power consolidation is reshaping vendor qualification requirements across customer categories.
- Telecom Operators:Incumbent carriers with legacy SONET/SDH infrastructure and greenfield 5G transport builds. European operators pre-qualify vendors against CSRD-aligned supply chain disclosure requirements under EU AI Act mandates.
- Cloud Providers:Hyperscale architects specifying custom port counts and software-defined networking integration. Amazon, Microsoft, and Google account for the majority of new 576x576 OXC port deployments in United States metro networks.
- Enterprises:Financial services and healthcare verticals with private wavelength requirements.
- Managed Service Providers:Multi-tenant optical layer services for mid-market customers.
Telecom Operators maintain the installed base; Cloud Providers are gaining share fastest through direct equipment sourcing that bypasses systems integrators.
Technology:
Control plane integration depth separates incumbent approaches from emerging programmable architectures.
- Wavelength Routing:Transparent optical path switching without electrical regeneration. Dominates telecom backbone deployments where signal integrity across 1000+ kilometer spans determines equipment selection.
- Circuit Switching:Legacy SONET/SDH-compatible architectures with established operational procedures. Retains entrenched positions in North American incumbent networks facing 15-year replacement backlogs.
- Packet Switching:MPLS-TP and segment routing integration for statistical multiplexing gains.
- Optical Routing:Software-defined control plane automation with real-time wavelength path computation.
Wavelength Routing carries the highest deployment volume; Optical Routing is gaining share fastest as programmable control planes mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon photonics foundry capacity concentrates in China and the United States, creating asymmetric supply security dynamics across procurement corridors. Carrier procurement patterns diverge sharply between state-backed infrastructure builds in Asia-Pacific and hyperscale-driven metro retrofits in North America.
United States
Hyperscale cloud operators in Ashburn, Virginia and Hillsboro, Oregon drive 576x576 port-count OXC deployments for machine-learning cluster interconnects. FCC open-access rules extend vendor certification cycles for cross-border equipment qualification. The Dallas-Fort Worth metroplex anchors multi-tenant exchange point builds where Amazon, Microsoft, and Google consolidate optical layer procurement under direct sourcing agreements.
China
Provincial transport corridors under MIIT next-generation optical guidelines absorb high-port-count wavelength-selective switching systems for state-backed fiber infrastructure. GB standards on optical transport network equipment impose 18-24 month product validation windows on domestic and foreign vendors. The Yangtze River Delta manufacturing corridor hosts captive silicon photonics foundries that control component costs across integrated OXC portfolios.
Germany
Deutsche Telekom and incumbent carriers face 15-year SONET/SDH circuit switching replacement backlogs across legacy infrastructure. EU AI Act data infrastructure transparency mandates force carriers to document optical layer encryption and wavelength path provenance. The Munich-Stuttgart industrial corridor concentrates Bell Labs heritage institutions with specialized thermal-optical co-design expertise for high-density wavelength routing.
Japan
METI-backed photonics initiatives accelerate domestic R&D in liquid crystal on silicon architectures for programmable wavelength routing. NTT and regional carriers deploy wavelength routing systems across metro and regional transport layers with signal integrity requirements spanning 1000+ kilometer spans. The Kanto region around Tokyo anchors precision MEMS actuator fabrication for micro-electromechanical mirror arrays.
United Kingdom
BT and Virgin Media O2 retrofit core networks with software-defined control plane automation for real-time wavelength path computation. CSRD-aligned supply chain disclosure requirements shape vendor pre-qualification criteria under EU AI Act infrastructure mandates. The London-Southeast corridor concentrates carrier-neutral data center builds where photonic switch convergence targets nanosecond-scale packet-optical integration.
Optical Cross Connect (OXC) Switches Market Competitive Landscape
Vertically integrated telecom equipment conglomerates and specialized optical component suppliers split the market along control plane integration depth. Vendor concentration intensifies at the high-port-count tier where 576x576 configurations require captive silicon photonics foundries or exclusive MEMS fabrication partnerships. Two strategic archetypes dominate: heritage Bell Labs institutions with multi-physics simulation expertise, and Asian conglomerates with backward integration into photonic-electronic chiplet production. Competitive moves concentrate on strategic partnerships for co-packaged optical engine development and geographic expansion through state-backed procurement corridors.
Among heritage telecom equipment manufacturers, Nokia Corporation and Ciena Corporation occupy positions within the wavelength-selective switch design tier. Huawei Technologies Co. Ltd. exemplifies the vertically integrated archetype with captive silicon photonics foundry control. Fujitsu Ltd. anchors Japanese supply security through METI-aligned domestic photonics manufacturing. These three entities represent distinct strategic postures: European heritage R&D intensity, Chinese state-backed vertical integration, and Japanese precision MEMS fabrication.
| Leading Market Players |
|---|
| Fujitsu Ltd. |
| Ciena Corporation |
| Huawei Technologies Co. Ltd. |
| Infinera Corporation |
| Nokia Corporation |
| Cisco Systems Inc. |
| Juniper Networks Inc. |
| Lumentum Holdings Inc. |
| Broadcom Inc. |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese silicon photonics foundries compresses component pricing across OXC portfolios while simultaneously incentivizing suppliers to extend financing terms and lock in long-term procurement relationships with Western equipment vendors seeking supply security.
Pricing Analysis
FCC open-access rules dictate the pricing tier structure for cross-border OXC deployments, separating premium-certified systems from standard domestic configurations. Three-tier pricing structure across premium, standard, and economy levels reflects GB standards compliance depth, port density scale, and software-defined networking integration complexity. Cost compression in the standard tier intensifies because Chinese captive foundries flood the component market with excess silicon photonics capacity. Cloud providers exhibit the lowest price sensitivity due to direct equipment sourcing power, while managed service providers face margin pressure from systems integrator disintermediation.
Supply Chain Analysis
Extended payment terms from Chinese silicon photonics foundries now anchor supply-chain finance facilities for Western equipment vendors managing working capital across 18-24 month GB standards certification windows. Manufacturing gravity centers on China, the United States, and Japan, with the Yangtze River Delta hosting captive foundries, Ashburn-Hillsboro corridors driving hyperscale procurement, and Kanto region precision MEMS fabrication. Component sourcing draws from lithium niobate modulators, indium phosphide lasers, and liquid crystal on silicon substrates. Single-source vulnerability concentrates in Chinese silicon photonics wafer supply. Distribution runs through direct hyperscale procurement agreements bypassing traditional systems integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
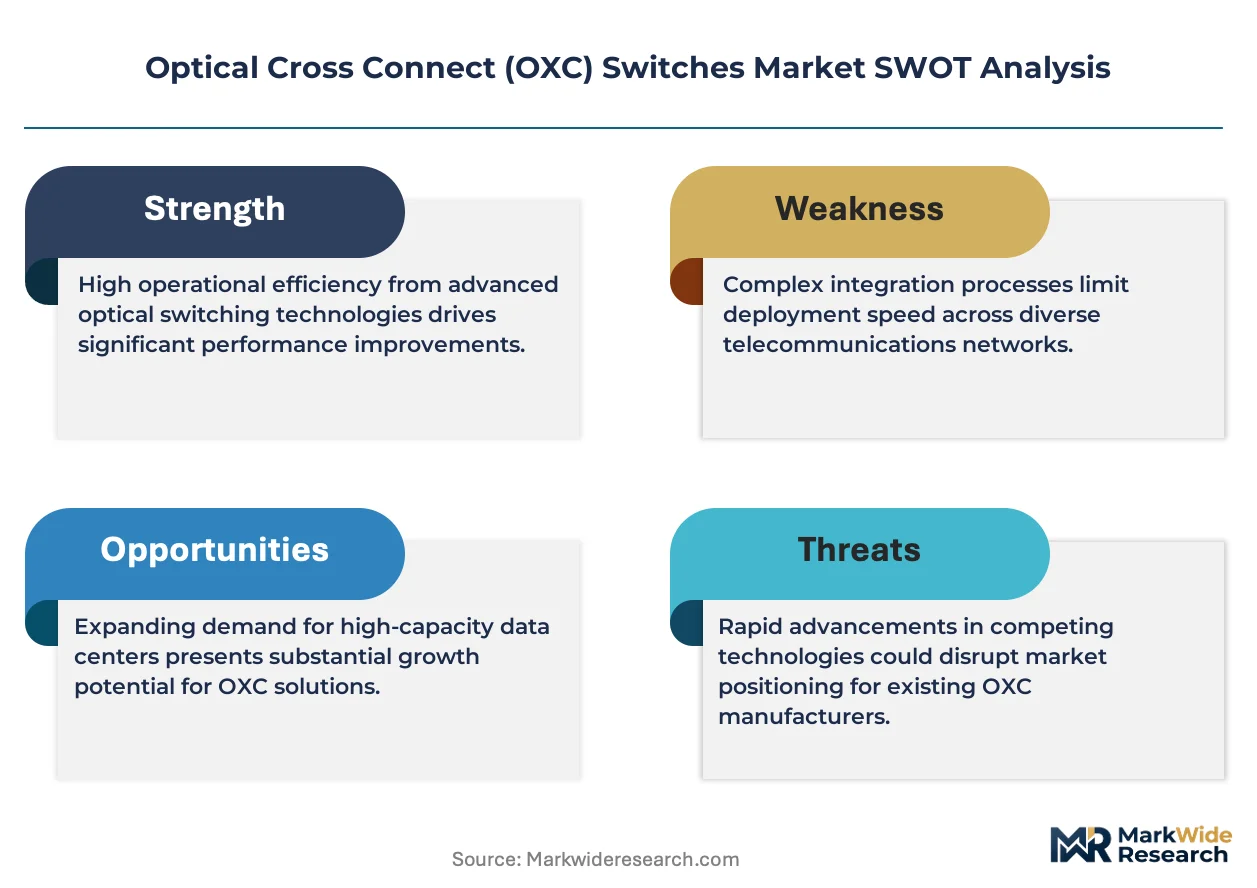
OXC switching architectures are approaching a platform-economics inflection where software-defined control plane interoperability determines vendor lock-in intensity, with the EU AI Act's audit-grade logging mandates accelerating ecosystem standardization around wavelength path provenance APIs.
For Market Incumbents: Pre-empt photonic switch convergence threats by accelerating liquid crystal on silicon R&D partnerships with METI-backed Japanese institutions before nanosecond-scale packet-optical integration commoditizes wavelength-selective switching margins. Secure captive MEMS actuator supply through exclusive fabrication agreements with Kanto-region precision manufacturers to defend against Chinese backward integration into mirror array production.
For New Entrants and Emerging Players: German SONET/SDH migration whitespace offers the most penetrable entry point, where Deutsche Telekom's 15-year circuit switching replacement backlog creates procurement windows for programmable wavelength routing solutions. Target EU AI Act compliance-driven upgrade cycles by embedding CSRD-aligned supply chain disclosure capabilities into control plane software before incumbent qualification cycles conclude.
For Investors and Strategic Acquirers: Capital is best deployed toward Bell Labs heritage institutions with concentrated multi-physics simulation expertise for thermal-optical co-design, as capability scarcity in high-density wavelength routing sustains premium valuation multiples across the analysis window. Monitor MIIT procurement guideline revisions as the inflection signal indicating state-backed Chinese vendor consolidation or accelerated foreign equipment qualification pathways.
| Strategic Initiative | Industry Significance |
|---|---|
| Co-packaged Optical Engine Development | Integrates silicon photonics chiplets with electronic ASICs for 800G line-side interfaces at hyperscale data centers. |
| Software-Defined Control Plane Integration | Enables real-time wavelength path computation compliant with EU AI Act audit-grade logging mandates. |
| MEMS Actuator Supply Security Partnership | Secures exclusive access to Kanto-region precision fabrication for 576x576 port-count mirror arrays. |
| GB Standards Pre-certification Investment | Compresses 18-24 month product validation windows for MIIT-aligned provincial transport corridor deployments. |
| Photonic Switch Convergence R&D | Targets nanosecond-scale packet-optical integration for data center interconnect applications beyond telecom boundaries. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, MIIT procurement bulletins, and EU regulatory databases to validate OXC deployment trajectories across metro and regional transport layers. Primary interviews incorporated network planning executives at cloud providers, optical transport procurement leads at incumbent carriers, photonics R&D directors at equipment vendors, and regulatory affairs specialists navigating FCC open-access and GB standards compliance. Bottom-up port-deployment tallies triangulated against top-down wavelength-selective switching revenue estimates.
Forecast inputs span switching architecture type, port density tier, application context, and end-user procurement pattern across the projection horizon. Segmentation modeling incorporated product type, deployment geography, control plane integration depth, and compliance regime cluster. CAGRs derived from fitted growth curves calibrated to observed hyperscale metro retrofit acceleration and MIIT guideline implementation timelines, with silicon photonics foundry utilization rates and MEMS actuator yield improvements as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed Chinese vendors or accelerated photonic switch convergence by Bell Labs heritage institutions would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Reed Switches Sensors Market
Switches
Solid State Relay Market
Switches
Asia Pacific Safety Switches Market
Switches
Miniature-Circuit Breaker Market
Switches
Europe Switchgear Market
Switches
Zero Speed Switch Market
Switches
Analog Switches Market
Switches
Transfer Switch Market
Switches
Static Transfer Switches Market
Switches
Fixed Switch Cabinet Market
Switches
Asia-Pacific Low Voltage Switchgear Market
Switches
Rocker Switch Market
Switches
Global Disconnector Switch Market
Switches
Antenna Switch Module Market
Switches
Reed Switch Market
Switches
Italy Reed Sensors Switches Market