
 Low Calorie Oil Market | 2026-2036
Low Calorie Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Oil Market Analytics
Specialized lipid formulation expertise is redrawing competitive boundaries in the low calorie oil sector. Cargill Incorporated leverages its integrated oilseed processing network to secure cost-advantaged feedstocks for reduced-calorie product lines. Archer Daniels Midland sustains R&D intensity in enzymatic interesterification, a process that restructures triglycerides to lower caloric content while preserving functional properties. Wilmar International Ltd dominates Southeast Asian palm oil derivatives, converting plantation proximity into specialized low-calorie fractionation capacity.
Low calorie oil comprises triglyceride-based fats engineered through fractionation, interesterification, or blending to deliver reduced energy density, typically achieving caloric values below the standard nine kilocalories per gram through modified fatty acid profiles or structured lipid architectures. These oils serve commercial food production where thermal stability, mouthfeel retention, and label-friendly positioning must coexist with energy reduction targets. Olive oil and avocado oil command premium positioning in health food shops and specialty stores, where consumers trade up for perceived nutritional density and monounsaturated fat profiles. Sunflower oil occupies volume-driven segments in supermarkets and mainstream food manufacturing, competing on price-accessible reformulation for restaurants and catering services seeking partial fat replacement without operational disruption.
The FDA enforces nutrition labeling standards that mandate calorie and fat disclosure, directly shaping reformulation procurement decisions by restaurants and food manufacturers subject to menu labeling rules. EFSA evaluates novel food applications and health claims across Europe, creating divergent approval pathways for structured lipids and modified oils that fragment market access timelines. FSSAI in India monitors edible oil quality parameters and fortification mandates, influencing import specifications for international suppliers targeting food service and household segments. Stakeholders must monitor regulatory divergence in calorie measurement methodologies and novel food classifications, as these definitions determine which reformulation technologies qualify for clean-label positioning in each jurisdiction.
Market Dynamics
Enzymatic interesterification technology is compressing the cost-performance tradeoff in reduced-calorie lipid production, allowing food manufacturers to hit calorie targets without sacrificing frying stability or shelf life. This process reconfiguration is forcing capital redeployment across oilseed processing networks.
Growth Catalysts
- FDA menu labeling mandates:Chain restaurants with twenty or more locations must disclose calorie counts, accelerating bulk procurement of reformulated frying oils and baking fats that reduce per-serving energy density without altering operational equipment.
- Clean-label positioning:Consumer packaged goods manufacturers in the United States are removing partially hydrogenated oils from ingredient decks, creating immediate substitution demand for structured lipids that replicate functional properties without trans fat content.
- Avocado oil fractionation:Cold-pressed and refined avocado oil variants are capturing shelf space in health food retail channels, where premium positioning justifies higher input costs for salad dressing and specialty cooking applications.
Market Restraints
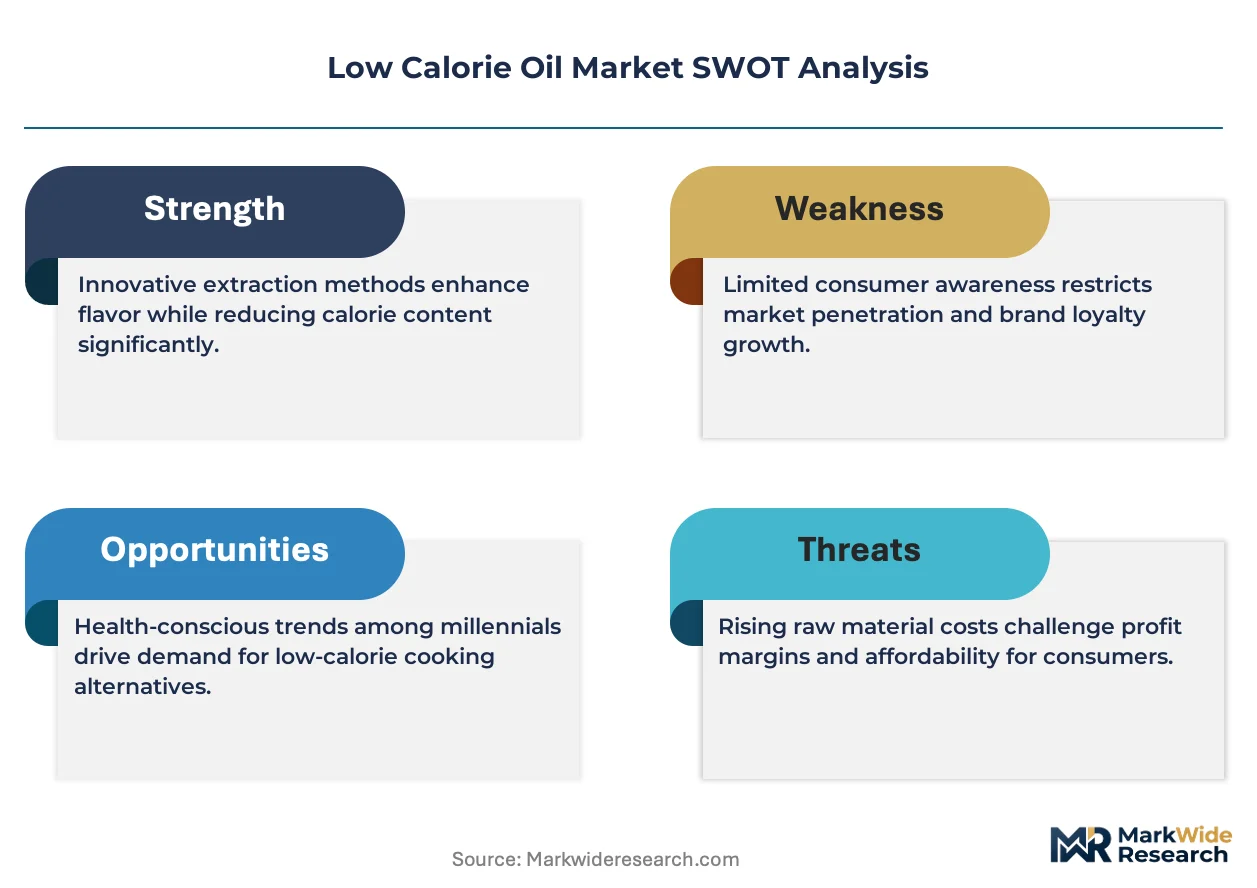
- Palm oil feedstock concentration:Southeast Asian plantation proximity creates supply vulnerability for fractionated low-calorie derivatives, with Wilmar International and regional processors controlling upstream access.
- Enzyme cost volatility:Lipase biocatalysts required for interesterification face price instability tied to microbial fermentation capacity constraints, compressing margins for mid-scale oil processors.
- Sensory performance ceilings:Structured triglycerides with reduced caloric density often fail to replicate the mouthfeel and flavor carry of conventional fats in deep-fried applications, limiting penetration in quick-service restaurant chains.
Strategic Opportunities
- Indian food service expansion:FSSAI fortification mandates and quality parameter enforcement are creating import specifications that favor international suppliers with certified low-calorie oil portfolios targeting household and institutional segments.
- Plant-based meat binders:Extruded protein formulations require lipid systems that deliver juiciness at reduced energy density, opening formulation partnerships between oil processors and alternative protein manufacturers.
- Carbon accounting integration:EU Green Deal sustainability reporting requirements are rewarding processors with verified supply chain traceability, creating differentiation premiums for plantation-to-bottle documentation.
Industry Challenges
- Specialized lipid technologist scarcity:Formulation chemistry expertise spanning enzymology, crystallography, and food rheology commands premium compensation, constraining R&D team scaling for mid-cap processors.
- Interesterification asset intensity:Continuous enzymatic reactor systems require seven-figure capital deployment with extended commissioning timelines, delaying payback periods for capacity expansion decisions.
- Novel food authorization delays:EFSA evaluation timelines for structured lipids with modified fatty acid architectures extend market access windows by eighteen to thirty-six months, fragmenting European launch synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Oil Market |
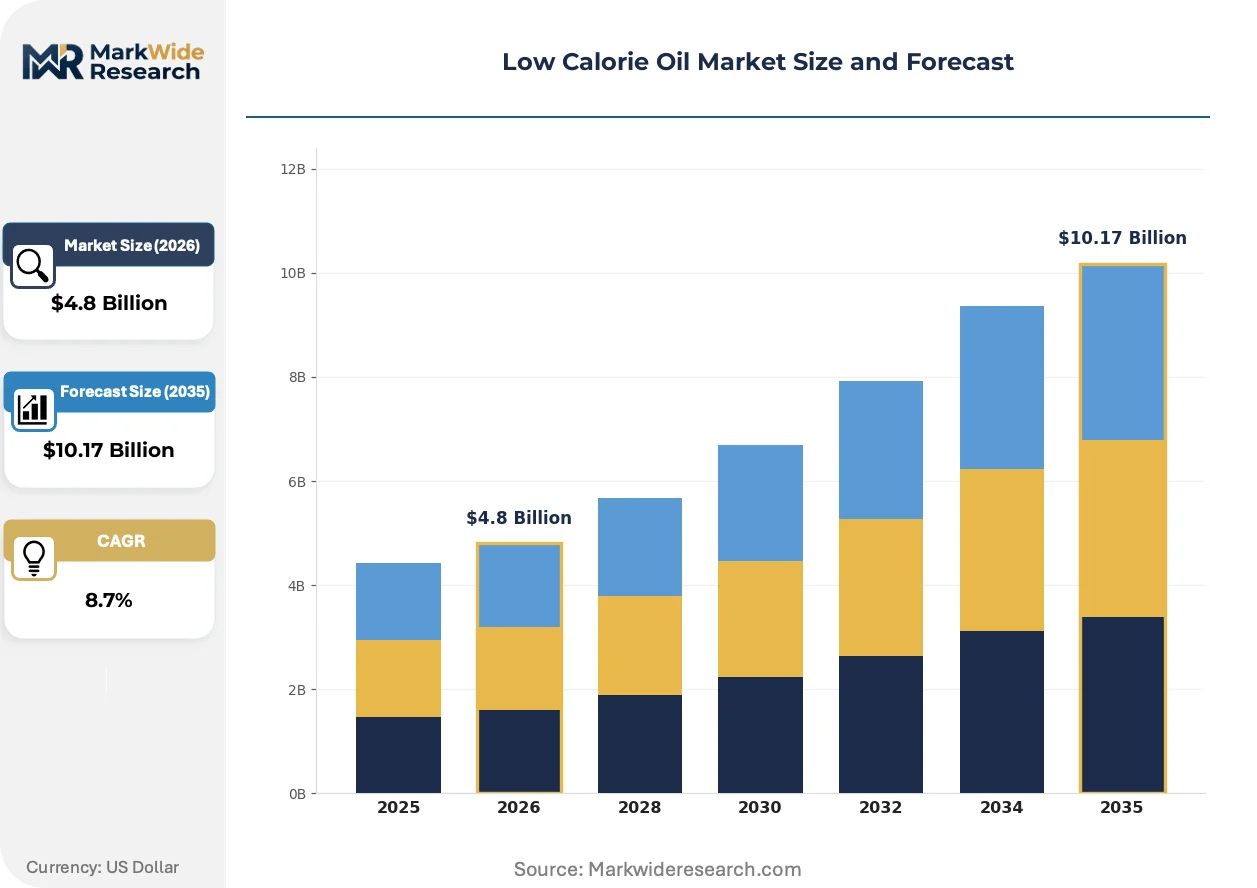
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Olive Oil, Coconut Oil, Avocado Oil, Sunflower Oil Application: Cooking, Baking, Salad Dressings, Marinades Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Health Food Shops End User: Households, Restaurants, Catering Services, Food Manufacturers |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland, Wilmar International Ltd, Bunge Limited, Louis Dreyfus Company, Conagra Brands, Fuji Oil Holdings Inc., Olam Agri Holdings Pte Ltd, Kuala Lumpur Kepong Berhad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Oil Market Evolving Landscape
Process intensification and regulatory disclosure requirements are jointly reconfiguring how reduced-calorie lipids move from refinery to finished food. Technology adoption curves are compressing as ingredient suppliers integrate formulation services directly into customer technical support.
Enzymatic interesterification is supplanting chemical transesterification in premium oil processing. Food manufacturers seeking clean-label positioning are adopting lipase-catalyzed restructuring at accelerated rates, particularly for bakery and confectionery applications. This technology shift is supplanting legacy sodium methoxide processes that require downstream refining to remove residual catalysts, shortening production cycles and reducing wastewater treatment burdens.
EFSA novel food classification protocols are tightening evidentiary requirements for structured lipids with non-conventional triglyceride architectures. Manufacturers must now submit comprehensive toxicology and nutritional equivalence dossiers before market authorization, extending development timelines. European reformulation programs are responding by prioritizing fractionation-based approaches that qualify as conventional foods rather than novel ingredients, redirecting R&D investment toward physical separation technologies.
Chain restaurant procurement teams are consolidating supplier relationships around integrated formulation partners who deliver application-specific lipid systems rather than commodity oils. Technical service contracts now bundle oil supply with sensory testing and operational troubleshooting, displacing transactional spot purchasing. This bundling trend is most visible in United States quick-service restaurant networks, where menu reformulation timelines demand rapid iteration support that commodity traders cannot provide.
Low Calorie Oil Market Segmentation
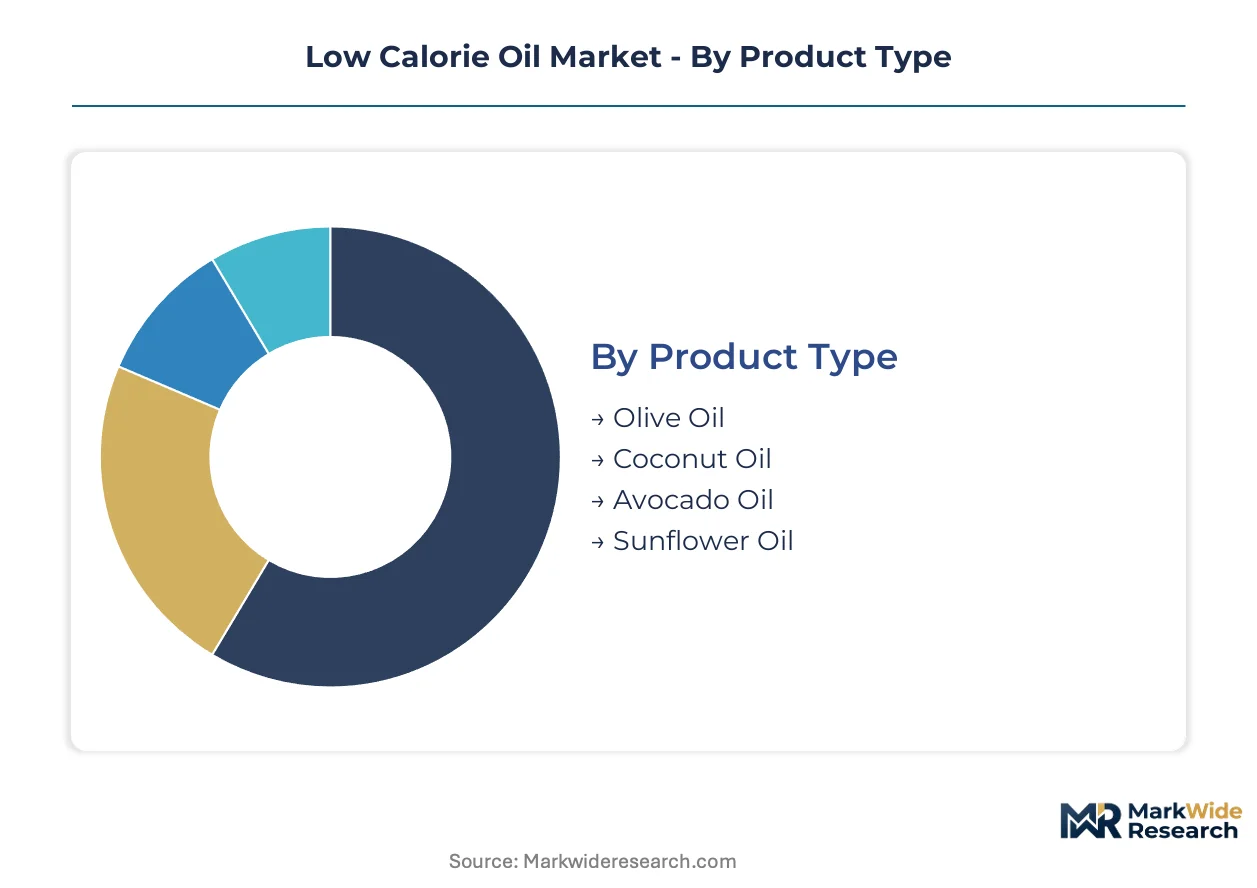
Low calorie oil procurement decisions diverge sharply across use cases, with FDA disclosure rules pushing restaurants toward reformulated frying oils while clean-label retail demand favors cold-pressed specialty grades. Segment boundaries are hardening as enzymatic processing capabilities concentrate among integrated processors.
Product Type:
EFSA novel food classifications and FDA GRAS determinations create divergent approval timelines for modified lipid architectures across these four oil categories.
- Olive Oil:Extra-virgin and refined grades achieve reduced caloric density through early-harvest pressing and selective fatty acid fractionation. Italian and Spanish bottlers dominate retail shelf space in United States specialty channels where monounsaturated positioning commands premium placement.
- Avocado Oil:Cold-pressed variants retain heat-sensitive phytonutrients while refined lines deliver neutral flavor for high-temperature applications. California processors and Mexican exporters are expanding fractionation capacity to serve United States health food retail where salad dressing manufacturers specify low-calorie lipid systems.
- Coconut Oil:Medium-chain triglyceride concentrates fractionated from copra deliver rapid energy metabolism claims. Southeast Asian processors control upstream supply.
- Sunflower Oil:High-oleic hybrids dominate volume-driven reformulation for quick-service restaurant chains seeking trans fat replacement without equipment modification.
Sunflower oil handles the majority of throughput; avocado oil is climbing the fastest on share.
Application:
Operational temperature requirements and finished-product sensory targets sort demand across these four use cases.
- Cooking:Frying and sautéing applications demand thermal stability above 180°C without polymerization or off-flavor development. United States quick-service restaurant chains specify interesterified low-calorie blends for deep-fryer consistency across thousands of locations.
- Baking:Creaming properties and shelf-life extension require structured triglycerides that replicate solid fat functionality without hydrogenation. Commercial bakeries in Germany and France are adopting enzymatically modified palm fractions to meet EU Green Deal sustainability reporting while reducing per-serving energy density.
- Salad Dressings:Emulsion stability and cold-temperature clarity favor high-oleic oils with minimal wax content. Premium positioning in United States specialty retail justifies avocado and olive oil input costs.
- Marinades:Flavor carry and meat penetration rates determine oil selection for prepared protein applications. Food service distributors specify cost-optimized sunflower blends.
Cooking absorbs the largest volume commitment; salad dressings show the steepest expansion trajectory as refrigerated premium lines multiply.
Distribution Channel:
Customer technical support requirements and procurement scale separate these four channel structures.
- Supermarkets:High-velocity shelf turnover demands standardized pack sizes and national distribution logistics. United States retail chains are consolidating supplier lists around processors who deliver private-label low-calorie oils with guaranteed trans fat compliance.
- Online Retail:Direct-to-consumer subscription models favor premium positioning with detailed fatty acid profile disclosure. Cold-pressed avocado and olive oil variants from California and Mediterranean producers dominate this channel.
- Specialty Stores:Curated assortments and staff expertise support higher price points for estate-bottled and single-origin oils. Italian and Greek exporters maintain strongest presence.
- Health Food Shops:Certification requirements for organic and non-GMO positioning filter supplier eligibility. This channel concentrates demand for minimally processed oils with intact antioxidant content.
Supermarkets move the greatest absolute volume; online retail is gaining share fastest as subscription models lock in recurring purchase patterns.
End User:
Scale economies and formulation expertise availability differentiate procurement behavior across these four customer types.
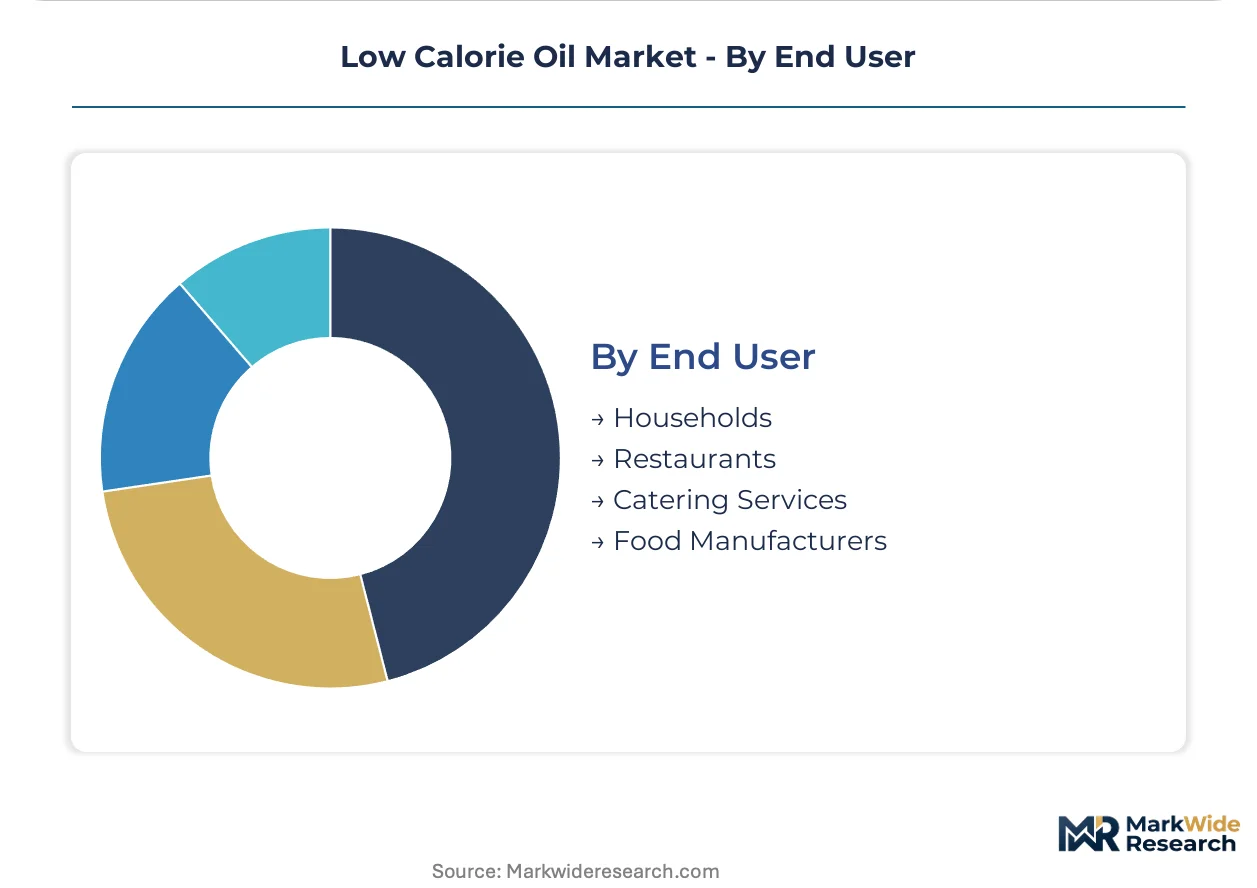
- Households:Individual purchase decisions prioritize label claims and price accessibility over technical specifications. United States consumers respond to FDA-mandated calorie disclosure by switching to high-oleic sunflower oil for everyday cooking.
- Restaurants:Chain operations with twenty or more locations face mandatory menu labeling that accelerates bulk procurement of reformulated frying oils. Technical service contracts now bundle oil supply with sensory validation.
- Catering Services:Volume flexibility and consistent performance across batch sizes drive supplier selection. Regional distributors in Germany and France specify interesterified blends for event-scale food preparation.
- Food Manufacturers:Ingredient integration into packaged goods requires customized lipid systems with specified crystallization behavior and oxidative stability. Cargill and Archer Daniels Midland capture largest formulation partnerships.
Food manufacturers represent the deepest volume commitment; restaurants are expanding most quickly as menu reformulation deadlines compress procurement timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States quick-service restaurants deploy low-calorie oils primarily for frying consistency across thousands of locations, while German commercial bakeries prioritize enzymatically modified palm fractions for sustainability reporting compliance. This consumption-mix differential shapes divergent procurement specifications and supplier relationship structures across major markets.
United States
Chain restaurant menu reformulations and clean-label retail launches drive bulk procurement of interesterified frying oils. FDA menu labeling mandates for operations with twenty or more locations accelerate substitution timelines. Chicago and Dallas processing clusters concentrate formulation partnerships between oil processors and national restaurant networks.
Germany
Commercial bakeries adopt enzymatically modified palm fractions to meet EU Green Deal sustainability documentation requirements. EFSA novel food classifications redirect R&D investment toward physical fractionation technologies. Hamburg and Frankfurt house technical service centers bundling oil supply with sensory validation for industrial bakery customers.
India
FSSAI fortification mandates and edible oil quality parameter enforcement create import specifications favoring certified low-calorie portfolios. Household and institutional segments expand simultaneously. Mumbai and Delhi-NCR distribution hubs concentrate procurement activity for food service and retail channels.
China
Food manufacturers integrate reduced-calorie lipids into packaged goods reformulations for domestic health-conscious consumers. SAMR nutrition labeling standards shape ingredient disclosure practices. Yangtze River Delta processing facilities expand fractionation capacity for both domestic consumption and export markets.
Brazil
Soybean processing networks pivot toward structured lipid production for regional food manufacturing customers. ANVISA food additive regulations govern interesterification process approvals. São Paulo state houses the primary concentration of oilseed crushing and specialty fat formulation capabilities.
Low Calorie Oil Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the low-calorie oil sector. The upper tier comprises agribusiness conglomerates with captive oilseed processing networks and in-house enzymatic modification capabilities. Mid-scale processors occupy specialist positions in fractionation or regional distribution. Strategic moves concentrate on backward integration into plantation assets and forward integration into formulation services that bundle technical support with commodity supply.
Among integrated agribusiness conglomerates, Cargill Incorporated and Archer Daniels Midland exemplify the scale-driven archetype with extensive oilseed processing footprints. Wilmar International Ltd occupies a distinct position leveraging Southeast Asian plantation proximity for upstream feedstock control. These three entities anchor the competitive structure through integrated supply chain positioning that spans crushing, refining, and specialty lipid modification.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland |
| Wilmar International Ltd |
| Bunge Limited |
| Louis Dreyfus Company |
| Conagra Brands |
| Fuji Oil Holdings Inc. |
| Olam Agri Holdings Pte Ltd |
| Kuala Lumpur Kepong Berhad |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day inventory cycles among United States quick-service restaurant chains concentrate purchasing power in the hands of integrated processors with enzymatic modification capabilities, compressing margin capture for mid-scale refiners while rewarding backward-integrated suppliers with captive oilseed supply.
Pricing Analysis
Long-term offtake contracts dominate procurement between national restaurant chains and integrated oil processors, displacing spot-market transactions as FDA menu labeling mandates synchronize reformulation timelines across thousands of locations. Price differentiation hinges on enzymatic processing certification and guaranteed trans fat compliance tiers, with premium structured lipids commanding spreads over commodity high-oleic sunflower oil. Cost compression in standard-grade frying oils is intensifying because lipase biocatalyst supply constraints limit mid-scale processor participation. Quick-service restaurant procurement teams exhibit highest price sensitivity, while specialty retail channels absorb premium positioning for cold-pressed avocado and olive variants.
Supply Chain Analysis
Strategic stockpiling of palm oil fractions prevails among Southeast Asian processors anticipating El Niño-related harvest volatility, contrasting with just-in-time enzyme procurement that exposes interesterification facilities to fermentation-capacity bottlenecks. Upstream supply concentrates in Indonesia, Malaysia, and Argentina, with crushing capacity tethered to plantation proximity and soybean harvest cycles. Raw material dependencies span crude palm oil, high-oleic sunflower seeds, and microbial lipase biocatalysts. Single-source vulnerability in Southeast Asian plantation networks creates disruption exposure for fractionated low-calorie derivatives. Distribution runs through technical service partnerships bundling oil supply with sensory validation rather than commodity spot trading.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic interesterification technology is disrupting competitive boundaries in the low calorie oil sector, with FDA calorie disclosure mandates compressing procurement timelines and favoring integrated suppliers with in-house formulation capabilities.
For Market Incumbents: Fortify enzymatic processing capacity through captive fermentation infrastructure investment, defending against emerging biotech entrants with novel biocatalyst platforms. Deepen backward integration into high-oleic oilseed genetics programs to secure differentiated feedstock supply. Prioritize technical service contract penetration among quick-service restaurant chains facing synchronized menu reformulation deadlines. For New Entrants and Emerging Players: Differentiate on carbon-accounting transparency and plantation-to-bottle traceability documentation, targeting EU Green Deal compliance premiums that incumbent commodity processors underweight. Penetrate the plant-based meat binder formulation segment, where lipid system partnerships with alternative protein manufacturers remain undersupplied. Pursue direct-to-health-food-retail distribution with subscription-model fatty acid profile disclosure. For Investors and Strategic Acquirers: Long-term, this sits as a specialty-ingredient consolidation play because enzymatic interesterification asset intensity and lipid technologist scarcity create durable moats for scaled processors. Target acquisition candidates with certified low-calorie portfolios and established FSSAI import specifications for Indian market access. Watch lipase biocatalyst cost curves as the inflection signal determining mid-scale processor viability.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Processing Capacity Expansion | Captures FDA-mandated reformulation demand from quick-service restaurant chains. |
| Backward Integration into Oilseed Genetics | Secures proprietary high-oleic feedstock supply for differentiated low-calorie fractions. |
| Carbon Accounting Certification Program | Unlocks EU Green Deal sustainability premiums through verified supply chain traceability. |
| Technical Service Partnership Bundling | Displaces commodity spot purchasing with integrated formulation support contracts. |
| Plant-Based Meat Lipid System Development | Addresses formulation gaps in extruded protein juiciness at reduced energy density. |
Research Methodology
Desk research of FDA GRAS determinations, EFSA novel food classifications, and FSSAI fortification mandates preceded structured interviews with oilseed processing plant managers, quick-service restaurant procurement directors, enzymatic technology R&D leads, and specialty retail category buyers. Secondary validation drew from customs trade data, SEC 10-K filings of integrated agribusiness conglomerates, and industry association technical publications. Bottom-up volume modeling triangulated against top-down market sizing across enzymatic interesterification capacity disclosures.
Variance decomposition across product type, application temperature requirement, distribution channel technical support intensity, and end-user procurement scale anchored the analytical framework throughout the forecast period. CAGRs derived from segment-level volume trajectories weighted by reformulation pipeline visibility and regulatory deadline synchronization. Industry-specific inputs incorporated lipase biocatalyst cost curve projections and palm oil fractionation capacity expansion announcements.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement of menu labeling rules or accelerated EFSA novel food authorization timelines would require recalibration. Forecasts reflect assumptions regarding enzymatic technology adoption curves and plantation supply stability. Revision becomes warranted when lipase fermentation capacity constraints cross thresholds that structurally exclude mid-scale processor participation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Black Cumin Seed Oil Market
Ingredients
Carica Papaya Seed Oil Market
Ingredients
Middle East & Africa Prebiotic Ingredients Market
Ingredients
Microbial Food Ingredients Market
Ingredients
Custom Dry Ingredients Blends Market
Ingredients
Dried Fruit Ingredients Market
Ingredients
Egg Replacement Ingredients Market
Ingredients
Asia-Pacific Prebiotic Ingredients Market
Ingredients
Carob Protein Market
Ingredients
United States Corn Glucose Market
Ingredients
Oat Fiber Market
Ingredients
Dill Seed Oil Market
Ingredients
Durian Powder Market
Ingredients
Rapid-Set Gelatin Market
Ingredients
Functional Flours Market
Ingredients
Savory Ingredients Market