
 Decongestants Market | 2026-2036
Decongestants Market Size, Share, and Industry Trends Forecast 2026-2036
Decongestants Market Outlook
The FDA's advisory committee review of oral phenylephrine effectiveness is recalibrating formulation priorities across the decongestants category. Johnson & Johnson leverages its consumer health infrastructure to sustain retail distribution breadth for multi-symptom cold products. Pfizer Inc. anchors its position through Rx-to-OTC switch expertise and legacy brand equity in sinus therapeutics. GSK plc differentiates via respiratory-specialist positioning and pediatric formulation development.
Decongestants are sympathomimetic agents that induce vasoconstriction in nasal mucosal blood vessels, typically formulated with pseudoephedrine, phenylephrine, or oxymetazoline at concentrations ranging from 0.05% to 10% depending on route and indication. These compounds restore nasal patency by reducing tissue edema, serving primary commercial purposes in cold relief, allergic rhinitis management, and acute sinusitis symptom control. Nasal sprays capture premium positioning due to rapid onset and targeted delivery, while oral tablets maintain volume leadership through convenience and travel-friendly dosing. The over-the-counter delivery mode dominates transaction frequency, though prescription pathways retain importance for combination therapies and pediatric indications where dosing supervision matters.
FDA monograph standards, DEA pseudoephedrine tracking requirements under the Combat Methamphetamine Epidemic Act, and USP dissolution specifications collectively shape product development timelines, channel access rules, and manufacturing compliance costs for domestic suppliers. State-level pharmacy placement restrictions on pseudoephedrine-containing products create a fragmented regulatory patchwork that influences regional distribution economics and inventory management. Stakeholders must monitor emerging FDA guidance on phenylephrine-containing products and assess reformulation investments against the timeline for any monograph revision that would redefine acceptable active ingredients.
Market Dynamics
Reformulation pressure from FDA phenylephrine efficacy scrutiny is compressing development timelines and forcing manufacturers to revalidate active ingredient portfolios across oral and topical delivery systems.
Growth Catalysts
- Seasonal allergy prevalence:Rising diagnostic rates for allergic rhinitis in the United States sustain baseline demand for nasal spray and tablet formulations through predictable annual purchase cycles.
- Combat Methamphetamine Epidemic Act tracking infrastructure:DEA pseudoephedrine purchase monitoring has stabilized channel access rules, reducing diversion risks and preserving retail pharmacy distribution for controlled decongestant variants.
- Nasal spray bioavailability advantages:Direct mucosal delivery technology enables rapid onset of action, capturing consumer preference for immediate symptom relief in acute congestion episodes.
Market Restraints
- API supply concentration:Pseudoephedrine precursor sourcing depends on concentrated Asian manufacturing clusters, exposing formulators to import tariff volatility and geopolitical disruption.
- Formulation switching costs:FDA monograph compliance timelines extend 18-36 months for new active ingredient substitutions, locking manufacturers into suboptimal phenylephrine portfolios pending regulatory clarity.
- Rebound congestion liability:Topical oxymetazoline use beyond three days induces rhinitis medicamentosa, limiting repeat purchase frequency and inviting substitution by oral alternatives.
Strategic Opportunities
- Pediatric indication expansion:Unmet need for age-appropriate dosing formulations in children under six years presents white space for concentration-calibrated nasal drops and taste-masked oral solutions.
- Telehealth-integrated prescribing:Virtual consultation platforms enable prescription-strength combination decongestant-antihistamine distribution without physical clinic visits, expanding addressable patient populations.
- Combination therapy convergence:Fixed-dose pairing of decongestants with intranasal corticosteroids addresses both immediate and sustained symptom control, differentiating portfolios in allergic rhinitis management.
Industry Challenges
- Clinical trial recruitment:Seasonal constraint windows compress enrollment for efficacy studies, requiring multi-site coordination across disparate geographic pollen zones to achieve statistical power.
- Legacy manufacturing retooling:Transitioning from phenylephrine-dominant tableting lines to pseudoephedrine or novel vasoconstrictor production demands capital expenditure for containment and DEA-compliant storage infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decongestants Market |
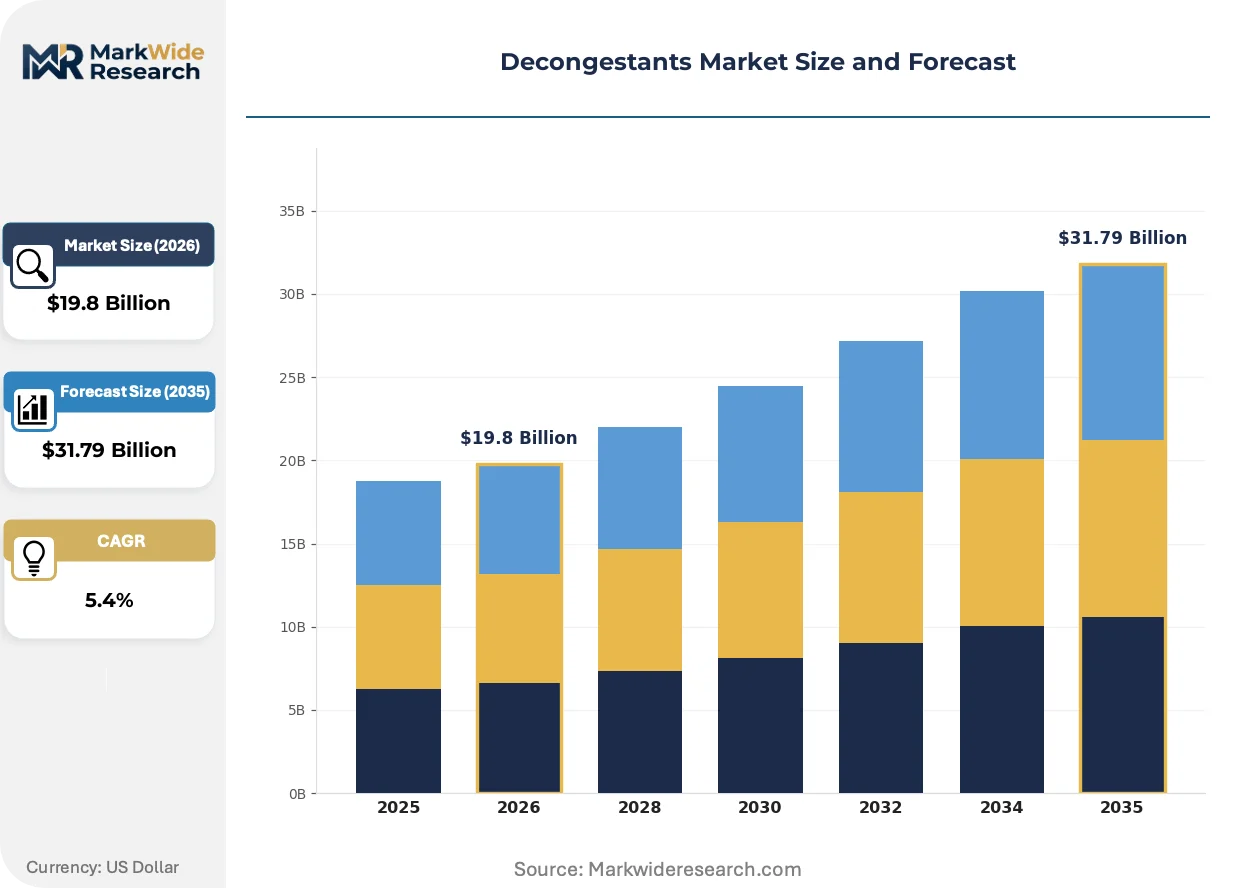
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $31.79 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Tablets, Nasal Sprays, Liquid Solutions, Granules Delivery Mode: Prescription, Over-the-Counter, Homeopathic, Herbal End User: Adults, Children, Hospitals, Clinics Application: Cold Relief, Allergies, Sinusitis, Flu Symptoms |
| Companies Covered | Johnson & Johnson, Bayer AG, Pfizer Inc., Sanofi S.A., Viatris Inc., GSK plc, Teva Pharmaceutical Industries Ltd., Perrigo Company plc, Haleon plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decongestants Market Strategic Shifts
Delivery system miniaturization and bioadhesive polymer science are compressing the efficacy gap between prescription and over-the-counter congestion relief, while regulatory scrutiny of established actives accelerates portfolio diversification.
Micronized particle engineering is rewriting absorption kinetics for intranasal corticosteroid-decongestant combinations. Allergic rhinitis sufferers in Germany and the United Kingdom are adopting these formulations at twice the rate of conventional sprays. The technology is compressing the time-to-onset differential that previously separated Rx and OTC categories.
EMA reflection papers on pediatric extrapolation for nasal decongestants are forcing adult-to-child dose bridging studies. Formulators must now generate juvenile pharmacokinetic data before label expansion. Combination product developers in France and Italy are front-loading these trials to secure first-mover positioning in the under-six segment.
Self-diagnostic smartphone applications are fragmenting the traditional pharmacy consultation pathway. United States consumers increasingly initiate decongestant selection through symptom-checker algorithms rather than pharmacist interaction. This channel shift concentrates volume in direct-to-consumer platforms and subscription replenishment models, bypassing retail shelf competition.
Decongestants Market Segmentation
Decongestant purchasing patterns diverge sharply between acute symptom management and chronic condition maintenance, with formulation choice driven by onset speed requirements, regulatory access constraints, and age-appropriate safety profiles. Manufacturers calibrate portfolio depth across these axes to capture both pharmacy counter traffic and prescription channel value.
Product Type:
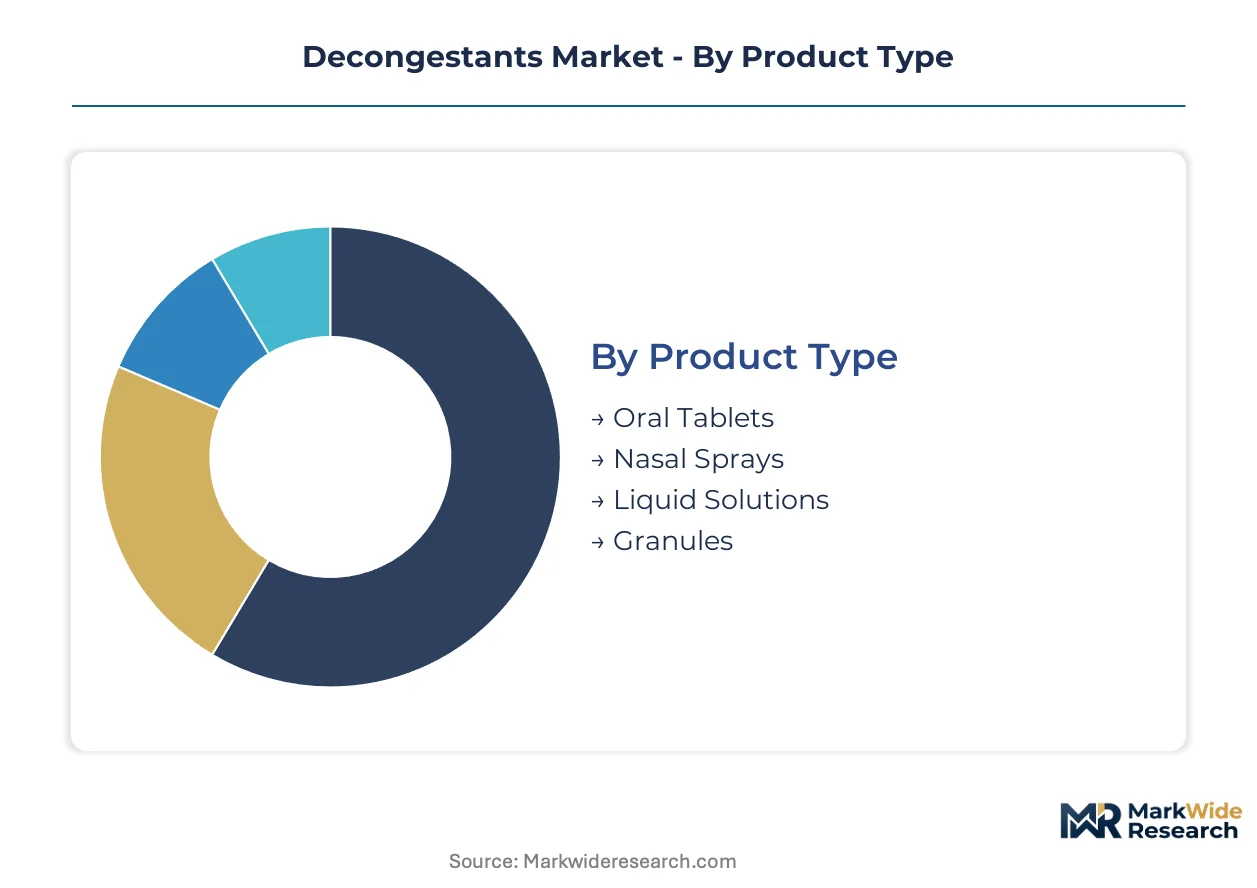
Volume concentration sits in oral tablets, while premium capture gravitates toward nasal spray delivery systems with bioavailability advantages.
- Oral Tablets:Pseudoephedrine and phenylephrine formulations dominate unit sales through retail pharmacy chains and convenience store distribution. United States consumers favor this format for travel-friendly dosing and discreet consumption during work hours, though FDA efficacy scrutiny on phenylephrine is compressing formulation stability.
- Nasal Sprays:Oxymetazoline and xylometazoline solutions command shelf space expansion at CVS, Walgreens, and Rite Aid locations due to sub-30-second onset kinetics. Direct mucosal vasoconstriction delivers superior patency restoration for allergic rhinitis sufferers in high-pollen states like Texas and Florida, offsetting rebound congestion liability through repeat purchase cycles.
- Liquid Solutions:Pediatric-calibrated concentrations with taste-masking excipients serve caregivers seeking precise dose titration for children under twelve.
- Granules:Effervescent and dry powder formats target Asian markets with traditional medicine consumption habits and hot beverage integration.
Today's leader: Oral Tablets. Tomorrow's challenger: Nasal Sprays.
Delivery Mode:
Regulatory classification determines margin structure, with DEA-controlled pathways demanding compliance infrastructure that excludes marginal competitors.
- Over-the-Counter:Phenylephrine tablets and oxymetazoline sprays generate the highest transaction frequency through self-selection at retail. United States pharmacy chains allocate prime shelf positioning to these SKUs, though FDA advisory committee proceedings threaten active ingredient legitimacy and force parallel pseudoephedrine portfolio maintenance.
- Prescription:Combination decongestant-antihistamine products and pediatric formulations require physician oversight and pharmacy benefit manager negotiation. This channel captures chronic rhinitis patients in integrated delivery networks like Kaiser Permanente and CVS Health, where formulary placement drives sustained prescribing loyalty.
- Homeopathic:Diluted natural preparations occupy specialty retail and direct-to-consumer channels with minimal regulatory burden.
- Herbal:Ephedra-free botanical formulations serve complementary medicine adherents through natural products retailers and online subscription models.
Regulatory gatekeeping favors Prescription for chronic conditions, while acute episodes sustain OTC dominance.
End User:
Adult self-medication sustains volume, but pediatric indication expansion offers the steepest expansion trajectory as formulation safety data accumulates.
- Adults:Working-age consumers between 18 and 64 drive baseline demand through seasonal cold and allergy episodes. Occupational requirements for alertness favor non-sedating decongestant selection, with United States office workers in urban corridors showing preference for nasal spray formats that avoid systemic absorption.
- Children:Formulation gaps for ages 2-6 create unmet need as caregivers seek alternatives to off-label adult dosing. EMA reflection papers on pediatric extrapolation are forcing juvenile pharmacokinetic studies that, once completed, will unlock label expansion and premium pricing for concentration-calibrated drops.
- Hospitals:Inpatient formulary committees prioritize combination therapies for post-surgical sinus procedures and intensive care nasal intubation support.
- Clinics:Urgent care and allergy specialist practices prescribe prescription-strength variants with diagnostic confirmation of underlying rhinitis or sinusitis.
Adult segments anchor current revenue; pediatric data generation determines next-decade growth.
Application:
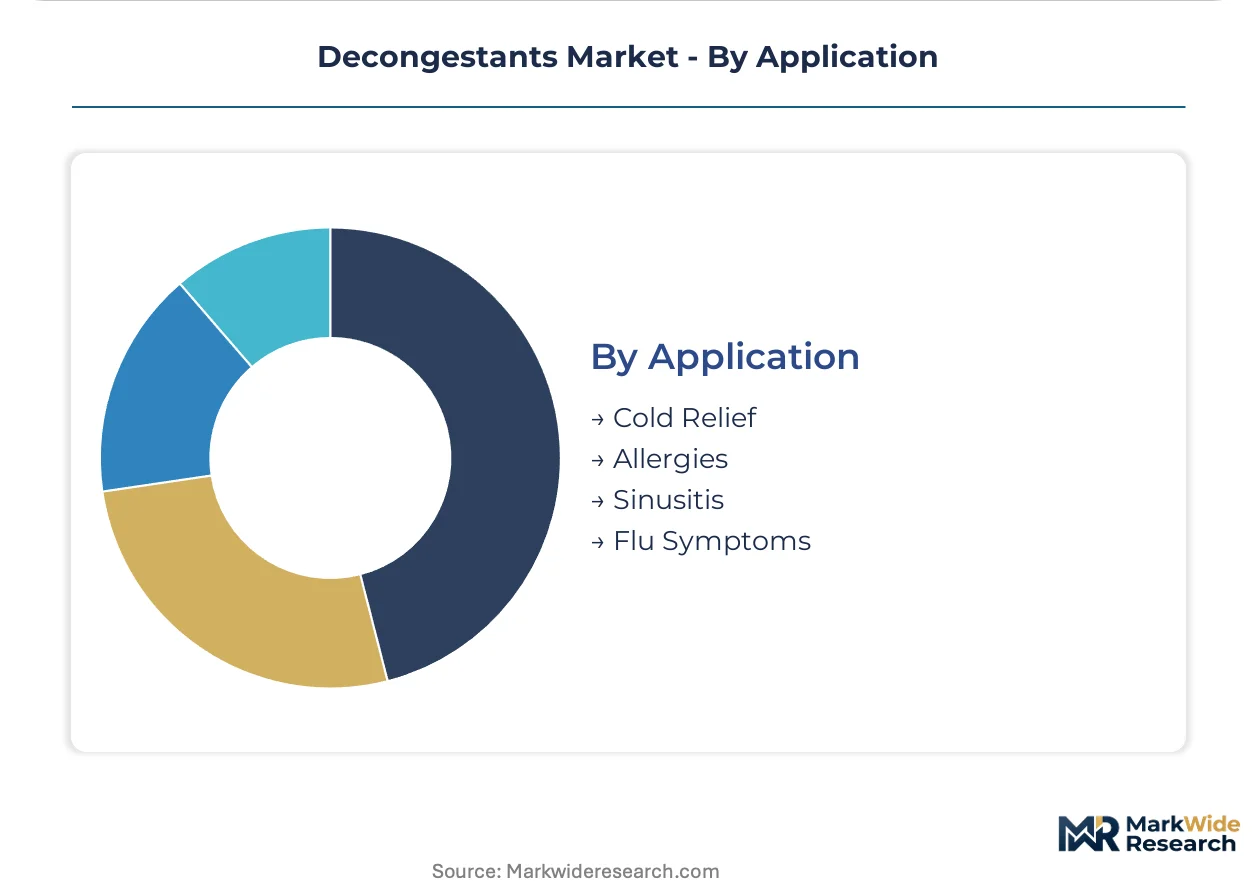
Allergic rhinitis management commands the most predictable annual purchase cycles, while cold relief shows higher episodic volatility.
- Allergies:Pollen seasonality in the United States generates recurring demand spikes from March through September. Intranasal corticosteroid-decongestant combinations are displacing monotherapy as first-line therapy in ENT and allergy practices, with micronized particle engineering compressing time-to-onset differentials.
- Cold Relief:Viral upper respiratory infection episodes drive impulse purchasing at retail during winter months. Multi-symptom products containing decongestant-analgesic-antitussive combinations capture basket expansion, though efficacy skepticism around oral phenylephrine is fragmenting brand loyalty.
- Sinusitis:Acute bacterial and chronic rhinosinusitis cases require longer-duration therapy and specialist referral pathways.
- Flu Symptoms:Influenza seasonality overlaps with cold relief but demands differentiation through fever-reducing co-formulation.
Allergies provide the most stable demand foundation; cold relief offers the highest episodic upside.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Decongestant formulation science traces its commercial roots to German pharmaceutical laboratories of the early twentieth century, where ephedrine isolation techniques first enabled systematic nasal vasoconstrictor development. United States manufacturers subsequently scaled production infrastructure during the postwar consumer health expansion, establishing the regulatory and distribution frameworks that persist today.
United States
Seasonal allergy prevalence in Texas and Florida sustains year-round demand for rapid-onset nasal sprays. FDA advisory committee scrutiny of oral phenylephrine efficacy is forcing domestic manufacturers toward reformulation investments. Johnson & Johnson and Pfizer Inc. anchor manufacturing and distribution operations across New Jersey and Michigan pharmaceutical corridors.
Germany
Allergic rhinitis diagnostic rates in Bavaria and North Rhine-Westphalia drive prescription-strength combination therapy adoption. EMA reflection papers on pediatric extrapolation mandate juvenile pharmacokinetic studies before label expansion. Bayer AG maintains formulation development facilities in Leverkusen and Berlin-Brandenburg.
United Kingdom
Micronized particle engineering for intranasal corticosteroid-decongestant combinations is displacing monotherapy in Greater London and Midlands allergy practices. MHRA post-Brexit regulatory autonomy permits accelerated approval pathways for novel delivery systems. GSK plc operates respiratory-specialist research infrastructure across Hertfordshire and Cambridge clusters.
France
Under-six pediatric indication gaps create white space for concentration-calibrated nasal drops in Île-de-France and Auvergne-Rhône-Alpes. ANSM pediatric formulation guidelines require adult-to-child dose bridging studies ahead of market authorization. Sanofi S.A. leverages consumer health infrastructure in Paris-Saclay for combination product development.
Japan
Non-sedating decongestant preference among Tokyo and Osaka office workers favors nasal spray formats with minimal systemic absorption. PMDA streamlined review pathways for OTC switch candidates compress time-to-market for reformulated actives. Teva Pharmaceutical Industries Ltd. participates in local distribution partnerships for generic substitution strategies.
Decongestants Market Competitive Environment
Capital-heavy producers with integrated manufacturing infrastructure compete with asset-light brand licensors and contract development organizations. The decongestants category shows moderate consolidation around legacy pharmaceutical conglomerates with consumer health divisions, supplemented by specialized generic manufacturers and private-label suppliers. Three archetypes dominate: diversified healthcare conglomerates with Rx-to-OTC switch expertise, respiratory-focused specialists with pediatric formulation capabilities, and scale-driven generic houses with cost-optimized production. Competitive maneuvering concentrates on portfolio diversification through active ingredient substitution and strategic partnerships for novel delivery technology access.
Among diversified healthcare conglomerates, Johnson & Johnson and Pfizer Inc. exemplify the integrated model spanning prescription development through retail distribution. GSK plc occupies a position within the respiratory-specialist tier, leveraging pediatric formulation science and sinus therapeutics heritage. These three entities anchor competitive dynamics across both established and emerging market segments.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Bayer AG |
| Pfizer Inc. |
| Sanofi S.A. |
| Viatris Inc. |
| GSK plc |
| Teva Pharmaceutical Industries Ltd. |
| Perrigo Company plc |
| Haleon plc |
| Others |
Value Chain & Pricing Dynamics
Micronized particle engineering for intranasal delivery is compressing manufacturing cost curves while concentrating formulation expertise among respiratory-specialist producers with captive polymer science capabilities. This technological transition simultaneously reduces per-unit production costs for established players and erects capital barriers for entrants lacking spray-drying infrastructure or bioadhesive polymer sourcing relationships.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments decongestant portfolios by onset speed and formulation complexity. Premium nasal sprays with sub-30-second vasoconstriction kinetics command shelf space premiums at CVS and Walgreens, while standard oral tablets face price erosion from FDA phenylephrine efficacy skepticism. Cost compression in the oral tablet tier is intensifying as manufacturers maintain parallel pseudoephedrine portfolios pending regulatory clarity. Hospital procurement committees show least price sensitivity for pediatric-calibrated concentrations, whereas convenience store channels exhibit acute elasticity for cold relief SKUs.
Supply Chain Analysis
Freight cost volatility for temperature-controlled API shipments from Indian and Chinese manufacturing clusters is compressing margin structures for formulators lacking regional buffer inventory. Pseudoephedrine precursor sourcing draws from concentrated Asian production hubs, exposing domestic manufacturers to import tariff exposure and geopolitical disruption. Oxymetazoline active pharmaceutical ingredient production rests on specialized chemical synthesis capabilities in Germany and Switzerland. Single-source vulnerability for pediatric-grade excipients creates formulation bottlenecks during pollen season demand spikes. Distribution runs through DEA-compliant warehousing networks for controlled substances, with retail pharmacy chains maintaining direct vendor-managed inventory programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The decongestants market functions as a stable compounder anchored by predictable seasonal allergy prevalence in the United States and recurring viral upper respiratory infection cycles.
For Market Incumbents: Anticipate FDA monograph revision timelines by accelerating reformulation investments toward pseudoephedrine-dominant portfolios and novel vasoconstrictor candidates. Secure backward integration into pediatric-grade excipient sourcing to preempt supply bottlenecks during Q1-Q2 pollen seasons. Channel control through direct pharmacy chain partnerships defends against private-label substitution. For New Entrants and Emerging Players: Launch via telehealth-integrated prescribing platforms to bypass retail shelf competition and capture prescription-strength combination therapy volumes. Target the under-six pediatric indication gap with concentration-calibrated nasal drops, leveraging EMA reflection paper compliance as competitive moat. White space exists in micronized corticosteroid-decongestant combinations for allergic rhinitis maintenance. For Investors and Strategic Acquirers: Valuations sit cheapest among generic manufacturers with underutilized DEA-compliant manufacturing infrastructure and dormant pediatric formulation capabilities. Long-term viability hinges on regulatory navigation expertise across FDA and EMA pediatric extrapolation frameworks. The signal to watch is FDA advisory committee final determination on oral phenylephrine efficacy, which would trigger portfolio revaluation across reformulation-ready assets.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Formulation Development | EMA-mandated juvenile pharmacokinetic studies unlock premium pricing in under-six segments. |
| Rx-to-OTC Switch Execution | PMDA streamlined review pathways in Japan compress time-to-market for reformulated actives. |
| Combination Therapy Convergence | Fixed-dose intranasal corticosteroid pairings differentiate portfolios in ENT practice settings. |
| Direct-to-Consumer Platform Launch | Symptom-checker algorithms fragment pharmacy consultation pathways toward subscription models. |
| Manufacturing Scale-Up | DEA-compliant containment infrastructure expansion secures pseudoephedrine production continuity. |
Study Parameters
Multiple input streams — regulatory filing databases, retail pharmacy audit data, and API trade flow records — were reconciled against primary interviews with formulary directors, regulatory affairs leads, and pharmacy benefit managers. Secondary validation drew from FDA advisory committee transcripts, EMA reflection papers, ClinicalTrials.gov enrollment data, and DEA production quota disclosures. Bottom-up patient-flow modeling and top-down pharmaceutical expenditure tracking were cross-referenced to establish volume baselines.
Data-stream reconciliation across the projection horizon applied treatment line, dosage form, and regional regulatory cluster segmentation. CAGRs were derived from epidemiological trend extrapolation, pricing elasticity coefficients, and channel shift assumptions. Forecast inputs incorporated pollen seasonality indices, viral respiratory infection surveillance data, and pediatric indication expansion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA phenylephrine monograph revision scenarios or sustained API import tariff escalation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Complement-Targeted Therapeutics Market
Pharmaceuticals
Global Varicella Vaccine Market
Pharmaceuticals
Performance Enhancing Drugs Market
Pharmaceuticals
Global Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
Cytomegalovirus Treatment Market
Pharmaceuticals
Asia-Pacific Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Chloramphenicol Eye Drops Market
Pharmaceuticals
Asia-Pacific Adenomyosis Drugs Market
Pharmaceuticals
Live Vaccines Market
Pharmaceuticals
Compound Acetaminophen Market
Pharmaceuticals
Global Central Nervous System (CNS) Stimulant Drugs Market
Pharmaceuticals
Conjunctivitis Drugs Market
Pharmaceuticals
Anti-Parasitic Drugs Market
Pharmaceuticals
Hypertriglyceridemia Therapeutics Market
Pharmaceuticals
Famotidine Market
Pharmaceuticals
Asia-Pacific Fatty Bases for Suppositories Market