
 Colombia Plastic Caps and Closures Market | 2026-2036
Colombia Plastic Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Plastic Caps and Closures Market Insights
Multi-sourced resin procurement is realigning how Colombian converters manage polyethylene and polypropylene feedstock costs. Berry Global Inc. leverages its Andean manufacturing footprint to serve regional beverage clients with standardized screw cap formats. Simex SAS anchors its position through specialized flip top and push-pull designs for personal care applications. RPM Colombia SAS competes on proximity, operating injection molding lines that supply Bogotá-based food processors with short-lead-time closure orders.
Plastic caps and closures are injection- or compression-molded dispensing and sealing devices, typically manufactured from polypropylene or polyethylene resins with torque specifications measured in inch-pounds, designed to preserve contents integrity and enable controlled consumer access across liquid and semi-solid packaged goods. Screw caps occupy the dominant volume position due to their ubiquity in carbonated soft drinks and edible oils, while child-resistant caps command premium positioning within pharmaceutical packaging where regulatory compliance creates defensible margin pools. Polypropylene leads material selection for its chemical resistance and living-hinge performance in flip top formats, whereas PET closures are gaining traction in bottled water segments seeking resin-to-bottle compatibility for recycling stream simplification.
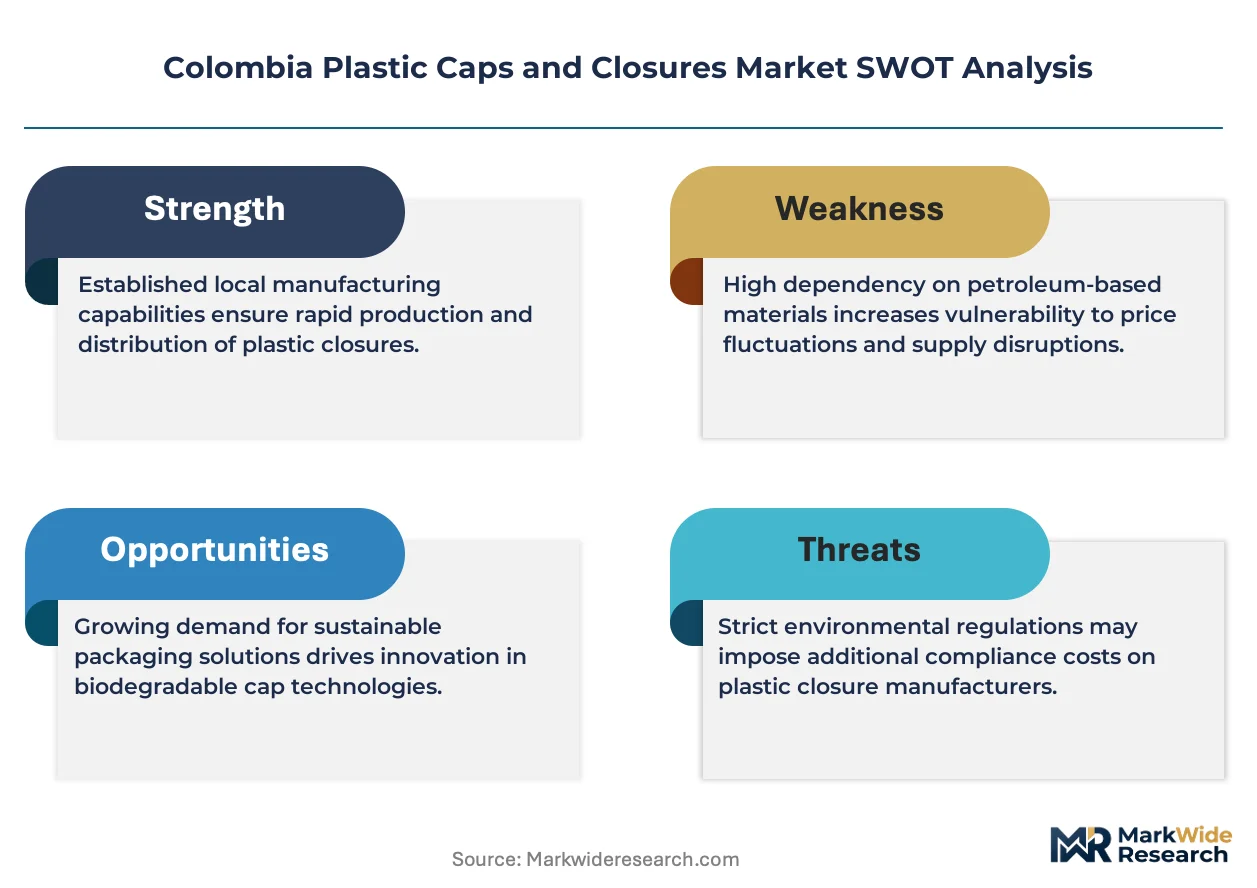
Colombia's Ministry of Environment enforces Law 2232 extended producer responsibility mandates that require closure-to-bottle recyclability, while INVIMA regulates pharmaceutical packaging through child-resistant certification standards that filter market access. The national technical regulator, ICONTEC, maintains NTC standards for food-contact plastics that shape resin grade specifications and migration testing protocols. Stakeholders must monitor whether impending single-use plastic restrictions in major Colombian municipalities will accelerate material substitution toward bio-based or recycled-content closure alternatives.
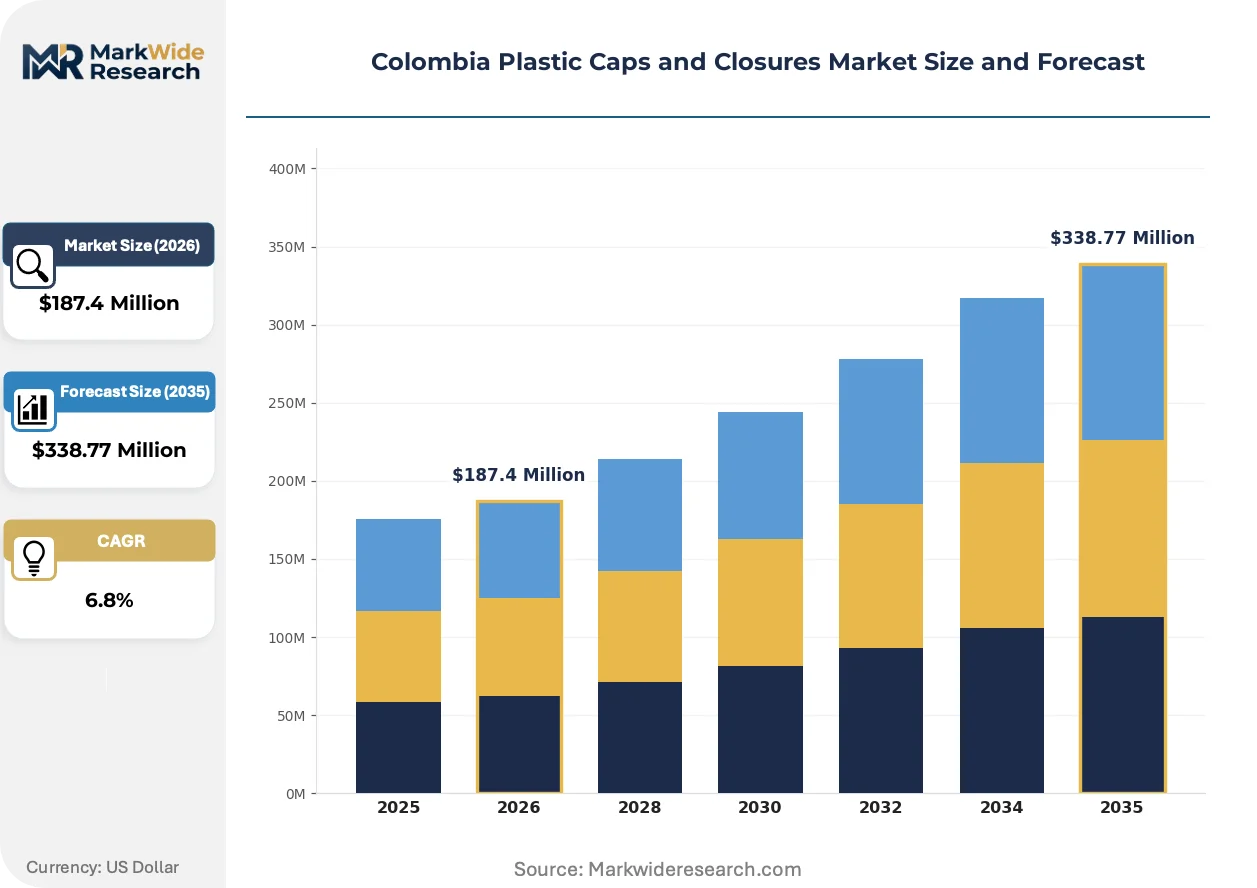
Market Dynamics
Extended producer responsibility mandates from Colombia's Ministry of Environment are forcing converters to redesign closure-to-bottle compatibility for recycling stream integration, compressing legacy single-material specifications and accelerating resin homogenization across the Andean supply base.
Growth Catalysts
- Law 2232 recyclability mandates:Closure-to-bottle material matching requirements are pulling PET closures into bottled water segments, expanding addressable volume for converters with co-injection capability.
- Andean beverage corridor expansion:Coffee and bottled-water processors around Caldas and Quindío are consolidating procurement of tamper-evident screw caps, creating demand density for regional molders.
- Child-resistant certification:INVIMA pharmaceutical packaging standards are filtering market access and sustaining premium positioning for certified converters serving Bogotá-based drug manufacturers.
Market Restraints
- Polypropylene feedstock volatility:Multi-sourced resin procurement exposes converters to polyethylene and polypropylene price swings that compress margin predictability on standardized screw cap contracts.
- Single-use plastic restrictions:Impending municipal bans in major Colombian cities threaten volume displacement for conventional petroleum-based closures without certified recycled content.
- Technical substitution ceiling:Living-hinge performance requirements in flip top formats lock polypropylene dominance, limiting bio-based resin penetration where fatigue resistance specifications are stringent.
Strategic Opportunities
- Pacific coast underpenetration:Buenaventura and Cali-based processors remain underserved by closure molders concentrated in Bogotá and Medellín, creating white space for proximity-based supply contracts.
- Bio-based resin convergence:Integration of sugarcane-derived polyethylene with existing injection molding infrastructure offers pathway to Law 2232 compliance without capital-intensive line replacement.
- Direct-to-bottler digital channels:E-procurement platforms are disintermediating traditional distributor networks, enabling shorter lead-time relationships with mid-sized Andean beverage processors.
Industry Challenges
- Migration testing expertise scarcity:ICONTEC NTC food-contact certification requires specialized analytical chemistry capabilities that concentrate in Bogotá, creating bottleneck for peripheral converters.
- Recycled-content integration complexity:Post-consumer resin feedstock inconsistency demands real-time torque specification adjustment, straining quality control systems calibrated for virgin material streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Plastic Caps and Closures Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Push-Pull Caps, Flip Top Caps, Screw Caps, Child-Resistant Caps Material: Polyethylene, Polypropylene, Polystyrene, PET End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Products Shape: Round, Square, Rectangular, Oval |
| Companies Covered | Berry Global Inc., Amcor Group GmbH, Simex SAS, Weener Plastic Group BV, Guala Closures SpA, Aptar Group Inc., RPM Colombia SAS, Amfora Packaging SAS, Proplas SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Plastic Caps and Closures Market Trends and Innovations
Material homogenization and regulatory compliance automation are compressing traditional specification diversity, while digital procurement interfaces reshape how converters capture share across Colombia's fragmented beverage and pharmaceutical packaging base.
Compression-molded PET closures with resin-to-bottle compatibility are overtaking polypropylene screw caps in premium bottled water segments. Andean bottlers seeking simplified recycling streams are specifying mono-material packages, compressing demand for multi-resin closure portfolios. This technology shift is enabling converters with co-injection lines to capture volume from legacy polypropylene specialists.
ICONTEC is tightening NTC migration testing protocols for food-contact plastics, expanding analytical documentation requirements for closure converters serving edible oil processors. The industrial consequence is certification timeline extension and testing cost absorption. Small and mid-sized molders in Medellín are responding by consolidating quality control functions through third-party laboratory partnerships.
Consolidated procurement by Bogotá-based beverage bottlers is compressing supplier rosters and extending contract durations. Distributor networks that historically fragmented demand across dozens of regional molders are losing share to direct manufacturer relationships with volume guarantees. This pattern is most visible in the carbonated soft drink segment, where three processors now account for the majority of tamper-evident screw cap volume.
Colombia Plastic Caps and Closures Market Segmentation
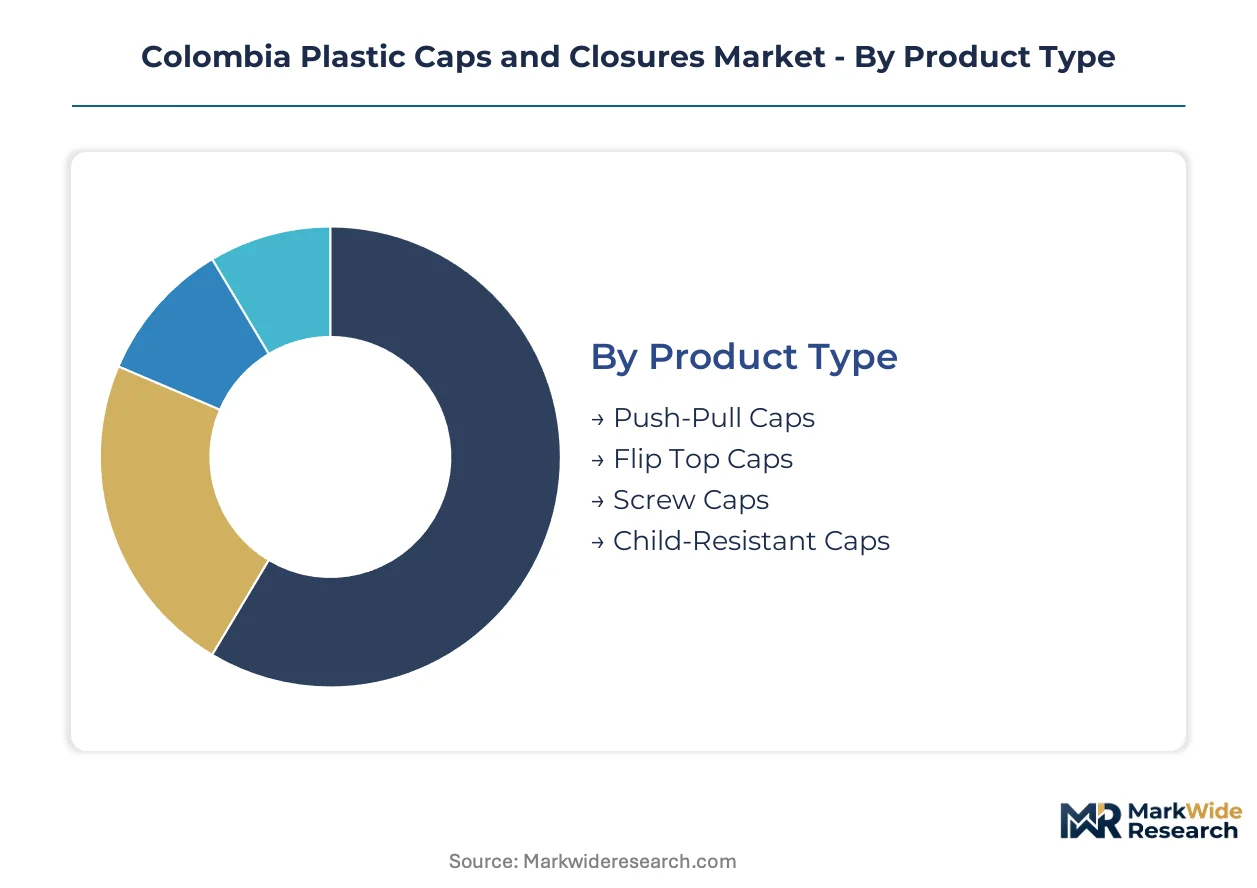
Closure specification diversity in Colombia compresses around torque performance, recyclability mandates, and bottler procurement consolidation. Segment boundaries blur where resin homogenization and mono-material packaging requirements reshape converter investment priorities.
Product Type:
Standardized formats dominate high-volume beverage contracts while specialized designs capture premium positioning in regulated applications.
- Screw Caps:Injection-molded polypropylene or polyethylene closures with tamper-evident bands and defined inch-pound torque specifications. Bogotá-based carbonated soft drink bottlers are consolidating procurement of these formats, driving demand density for regional molders with co-injection capability.
- Flip Top Caps:Living-hinge designs requiring polypropylene's fatigue resistance for repeated open-close cycles. Personal care processors in Medellín specify these for shampoo and conditioner bottles where consumer convenience commands price premiums.
- Push-Pull Caps:Sports-drink and bottled-water dispensing formats with integrated spout mechanisms. Simex SAS anchors regional supply through specialized molding lines.
- Child-Resistant Caps:INVIMA-certified pharmaceutical closures with dual-action opening mechanisms. Certification requirements filter market access to converters with analytical chemistry partnerships in Bogotá.
Most installed capacity flows through Screw Caps. Expansion is steepest in Child-Resistant Caps.
Material:
Resin selection locks around chemical resistance requirements, living-hinge performance, and Law 2232 recyclability mandates.
- Polypropylene:Dominates flip top and living-hinge applications through superior fatigue resistance and chemical stability. Quindío-based edible oil processors specify this grade for migration compliance under ICONTEC NTC protocols.
- PET:Compression-molded closures gaining share in bottled water segments seeking resin-to-bottle compatibility for recycling stream simplification. Caldas processors are specifying mono-material packages.
- Polyethylene:Sugar-cane derived variants offer bio-based pathway to extended producer responsibility compliance without line replacement.
- Polystyrene:Limited to cosmetic applications where rigidity and surface finish outweigh recyclability concerns.
Polypropylene commands the largest installed base. PET is climbing the fastest among converters with co-injection infrastructure.
End User:
Customer concentration and regulatory intensity segment the market between consolidated beverage procurement and fragmented specialty packaging.
- Food & Beverage:Coffee processors in Caldas and bottled-water bottlers around Quindío drive tamper-evident screw cap volume. Three Bogotá-based processors account for majority procurement.
- Pharmaceuticals:INVIMA child-resistant certification creates defensible margin pools for certified converters serving Bogotá drug manufacturers.
- Cosmetics:Flip top and push-pull demand concentrates in Medellín personal care clusters.
- Household Products:Cleaning chemical processors specify chemical-resistant polypropylene closures with venting features.
Beverage applications absorb the greatest mold-hour capacity. Pharmaceutical packaging shows the steepest margin expansion trajectory.
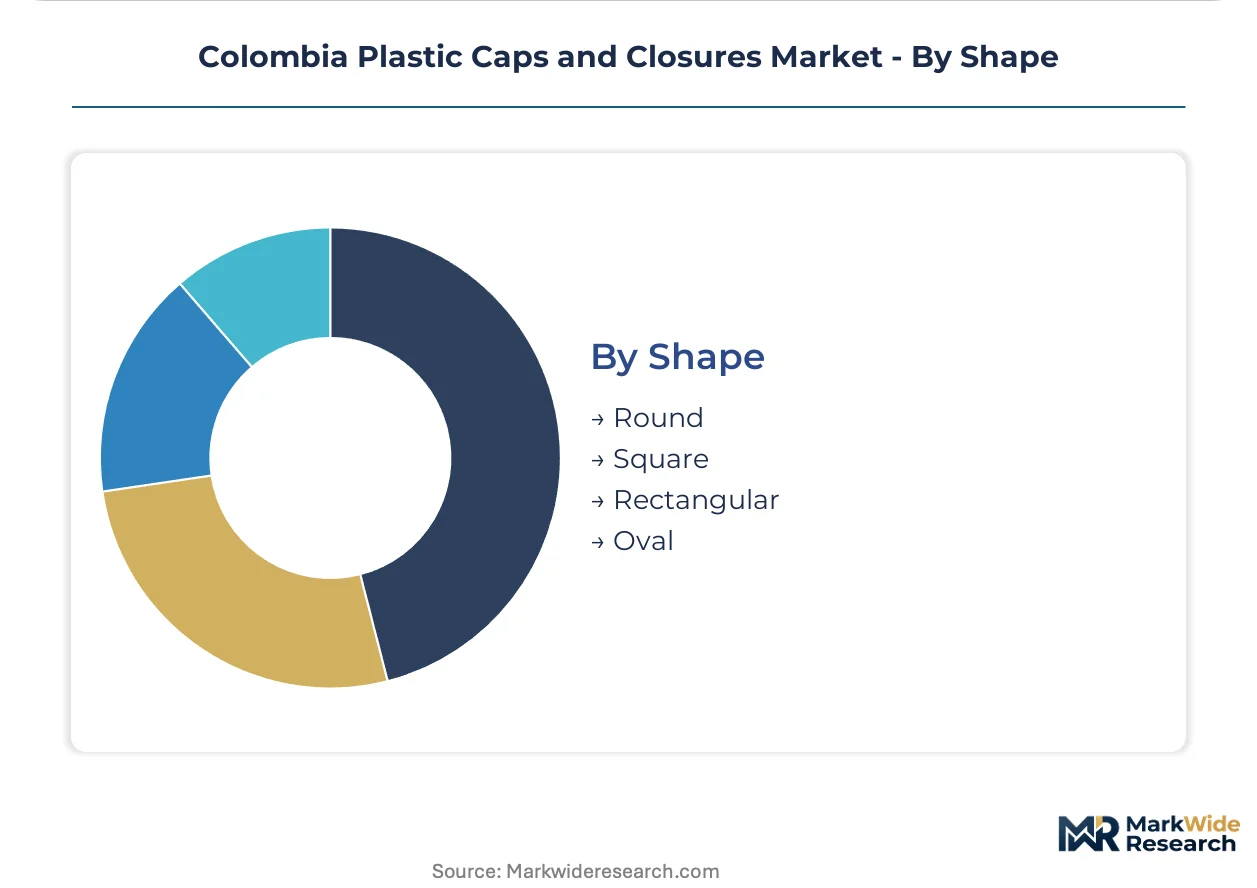
Shape:
Geometric specification diversity narrows as bottler line standardization and label adhesion requirements dominate design decisions.
- Round:Universal compatibility with capping equipment across carbonated soft drink and bottled water lines. Andean corridor processors standardize on 28mm and 38mm neck finishes.
- Square:Differentiation format for premium edible oils and specialty beverages where shelf presence justifies retooling costs.
- Rectangular:Limited adoption in industrial chemical packaging where stacking stability overrides equipment compatibility.
- Oval:Niche cosmetic applications with custom label integration requirements.
Round formats flow through nearly all installed capping equipment. Square shapes are gaining share fastest in premium edible oil segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Andean coffee and bottled-water corridor around Caldas and Quindío anchors national demand for tamper-evident screw caps, with Bogotá and Medellín serving as the twin procurement centers for beverage bottlers and pharmaceutical manufacturers.
Bogotá Capital District
Carbonated soft drink processors consolidate procurement of standardized screw caps with defined torque specifications. Colombia's Ministry of Environment enforces Law 2232 extended producer responsibility mandates that require closure-to-bottle recyclability. Three major bottlers headquartered in the capital now account for the majority of tamper-evident volume, compressing supplier rosters and extending contract durations.
Medellín Metropolitan Area
Personal care clusters drive demand for flip top and push-pull designs where consumer convenience commands price premiums. INVIMA regulates pharmaceutical packaging through child-resistant certification standards that filter market access. Specialized molders in Antioquia operate injection molding lines with short-lead-time capabilities for food processors.
Caldas and Quindío
Coffee processors and bottled-water bottlers specify mono-material packages seeking resin-to-bottle compatibility for recycling stream simplification. ICONTEC maintains NTC standards for food-contact plastics that shape resin grade specifications and migration testing protocols. Compression-molded PET closures are overtaking polypropylene formats among Andean corridor processors.
Pacific Coast Region
Buenaventura port logistics and Cali-based processors remain underserved by closure molders concentrated in the interior. The national technical regulator's certification requirements concentrate analytical chemistry capabilities in Bogotá, creating bottleneck for peripheral converters. White space exists for proximity-based supply contracts serving Pacific corridor beverage and chemical processors.
Colombia Plastic Caps and Closures Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized certification and regional proximity strategies. The market presents a bifurcated structure where multinational converters leverage co-injection infrastructure for beverage volume, while domestic specialists capture premium positioning through INVIMA-certified pharmaceutical supply. Three archetypes dominate: scale-driven multinationals with Andean manufacturing footprints, mid-sized regional molders competing on lead-time compression, and certified specialists serving regulated pharmaceutical segments. Competitive dynamics center on capacity expansion for PET closure lines and strategic partnerships with third-party laboratories for migration testing compliance.
Among multinational converters with Colombian presence, Berry Global Inc. and Amcor Group GmbH represent the scale-driven tier with standardized format capabilities. Simex SAS anchors the specialized segment through its Medellín-based operations. Domestic competitors RPM Colombia SAS and Amfora Packaging SAS occupy positions within the regional proximity tier serving Bogotá food processors. The competitive set reflects a pattern where international players capture beverage volume through co-injection infrastructure, while local specialists defend margin pools in regulated pharmaceutical and personal care applications.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Amcor Group GmbH |
| Simex SAS |
| Weener Plastic Group BV |
| Guala Closures SpA |
| Aptar Group Inc. |
| RPM Colombia SAS |
| Amfora Packaging SAS |
| Proplas SA |
| Others |
Pricing and Supply Chain Analysis
Backward integration into resin compounding anchors converter pricing power across Colombia's Andean manufacturing corridor. Captive polyethylene and polypropylene supply agreements insulate Bogotá-based molders from feedstock volatility while compressing procurement costs for standardized screw cap contracts.
Pricing Analysis
Polypropylene pellet cost pass-through dominates contract structures for beverage closure suppliers serving Bogotá bottlers. Three-tier pricing structure across INVIMA-certified pharmaceutical, food-grade standard, and economy industrial tiers separates margin pools by certification burden and torque specification precision. Cost compression in standard screw caps is intensifying because consolidated procurement by major carbonated soft drink processors extends volume commitments in exchange for price concessions. Pharmaceutical packaging buyers show least price sensitivity due to regulatory compliance barriers, while edible oil processors in Quindío exhibit highest sensitivity to resin-linked contract adjustments.
Supply Chain Analysis
Law 2232 domestic-content recyclability mandates are reshaping sourcing patterns toward regional resin homogenization. Feedstock supply draws from Saudi Arabian polyethylene, US Gulf Coast polypropylene, and domestic sugarcane-derived bio-resin pilot programs. Single-source vulnerability concentrates in virgin resin import channels through Buenaventura port logistics bottlenecks. Distribution runs through direct manufacturer relationships with volume guarantees, displacing traditional distributor networks that historically fragmented demand across regional molders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Colombia's plastic caps and closures market reads as a late-cycle quality story where premium specifications command durable margins. The shift toward INVIMA-certified pharmaceutical closures and mono-material PET beverage formats rewards converters with analytical chemistry partnerships and co-injection infrastructure.
For Market Incumbents: Hedge polypropylene price exposure through backward integration into resin compounding or long-term offtake agreements with Gulf Coast suppliers. Defend margin pools in pharmaceutical packaging by deepening ICONTEC NTC certification capabilities and expanding Bogotá laboratory partnerships. Capacity addition in Pacific coast proximity zones addresses underserved Cali and Buenaventura processors before regional competitors establish beachheads. For New Entrants and Emerging Players: Capture white space in Pacific coast beverage and chemical processor supply through proximity-based injection molding operations with short-lead-time positioning. Target child-resistant closure certification as the most penetrable premium segment given INVIMA analytical chemistry bottlenecks that filter incumbent competition. Pursue direct-to-bottler digital procurement channels that disintermediate traditional distributor networks serving mid-sized Andean coffee processors. For Investors and Strategic Acquirers: Consolidation pressure builds where migration testing expertise scarcity concentrates quality control functions among third-party Bogotá laboratories. Long-term viability favors converters with co-injection PET capability and established pharmaceutical certification pipelines over commodity screw cap specialists facing resin volatility and procurement consolidation. Watch for single-use plastic restriction implementation in major Colombian municipalities as the signal indicating accelerated bio-based resin substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polypropylene supply insulates margins from Gulf Coast price volatility. |
| INVIMA Certification Investment | Child-resistant closure approval creates defensible pharmaceutical packaging revenue pools. |
| Pacific Coast Manufacturing Footprint | Proximity to Cali and Buenaventura processors reduces logistics costs and lead times. |
| Co-injection Line Capacity Addition | PET closure capability captures mono-material bottled water specification shifts. |
| Third-party Laboratory Partnership | Outsourced ICONTEC NTC testing accelerates food-contact certification timelines. |
Research Methodology
Coverage spans Colombia's Andean interior, Pacific coast, and Caribbean processing corridors, with primary inputs from each region triangulated against secondary validation. Interviews with injection molding plant managers, beverage procurement leads at Bogotá bottlers, personal care brand managers in Medellín, and pharmaceutical packaging engineers informed demand-side dynamics. Secondary sources include ICONTEC NTC standard documentation, Ministry of Environment Law 2232 regulatory filings, INVIMA certification registries, and customs trade data on resin imports. Bottom-up volume modeling across product type, material grade, and end-use segments converged with top-down market sizing.
Rate-of-change decomposition structured the analytical framework, isolating volume drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include closure format, resin chemistry, end-use industry, and geographic procurement cluster. CAGRs were derived from trend-line extrapolation of historical resin consumption patterns adjusted for regulatory mandate implementation schedules. Forecast inputs incorporated co-injection line capacity expansion announcements and municipal single-use plastic restriction timelines.
Feedstock price volatility, regulatory enforcement variance across Colombian departments, and bio-resin substitution rate uncertainty are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding Law 2232 implementation consistency and INVIMA certification processing capacity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Tube Closures Market
Caps and Closures
Hinged Dual Flap Caps Market
Caps and Closures
Morocco Plastic Caps and Closures Market
Caps and Closures
India Plastic Caps and Closures Market
Caps and Closures
Hinged Dispensing Caps Market
Caps and Closures
Overcaps Market
Caps and Closures
China Plastic Caps and Closures Market
Caps and Closures
Snap-On Closures Market
Caps and Closures
Bag Closures and Seals Market
Caps and Closures
Brazil Plastic Caps and Closures Market
Caps and Closures
Poland Plastic Caps and Closures Market
Caps and Closures
Resealable Closures and Spouts Packaging Market
Caps and Closures
Tear-Tab Lids Market
Caps and Closures
Plastic Caps and Closure Market
Caps and Closures
Aerosol Caps Market
Caps and Closures
Laminated Tube Closure Market