
 Dual Flap Dispensing Closure Market | 2026-2036
Dual Flap Dispensing Closure Market Size, Share, and Industry Trends Forecast 2026-2036
Dual Flap Dispensing Closure Market Foresight
Multi-source procurement toward specialized closure molders is realigning supply chain economics in the dual flap dispensing closure sector. AptarGroup, Inc. leverages precision injection molding capabilities across North American and European plants. Guala Closures Group anchors its position through dedicated wine and spirits closure expertise that extends into premium dispensing formats. Silgan Holdings Inc. competes via high-volume manufacturing scale serving mass-market food and beverage accounts.
Dual flap dispensing closures are two-component hinged mechanisms engineered from polypropylene or polyethylene resins with silicone valve inserts, manufactured through multi-cavity injection molding to achieve hermetic seals and controlled product release. These closures serve primary commercial purposes in viscous liquid packaging where controlled dosing and resealability protect product integrity between uses. Flip top configurations lead volume demand in condiment and sauce applications where single-handed operation drives consumer preference. Plastic material formulations dominate structural economics due to lower per-unit costs and compatibility with existing recycling streams, though composite material development is accelerating as brands respond to EU Packaging and Packaging Waste Regulation targets. Pharmaceuticals and personal care end users concentrate margin pools in tamper-evident and child-resistant certified variants requiring specialized tooling investments.
FDA food-contact notification requirements govern resin selection and additive migration limits for closures serving US food and beverage markets, while EU REACH and the Packaging and Packaging Waste Regulation constrain substance use and mandate recyclability design standards. Germany's national packaging regulator enforces extended producer responsibility fees that incentivize lightweight closure designs. China's GB standards for food-contact plastics and SAMR market access rules shape import qualification pathways for foreign closure suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks and material certification timelines to align capital deployment with regulatory enforcement phases.
Market Dynamics
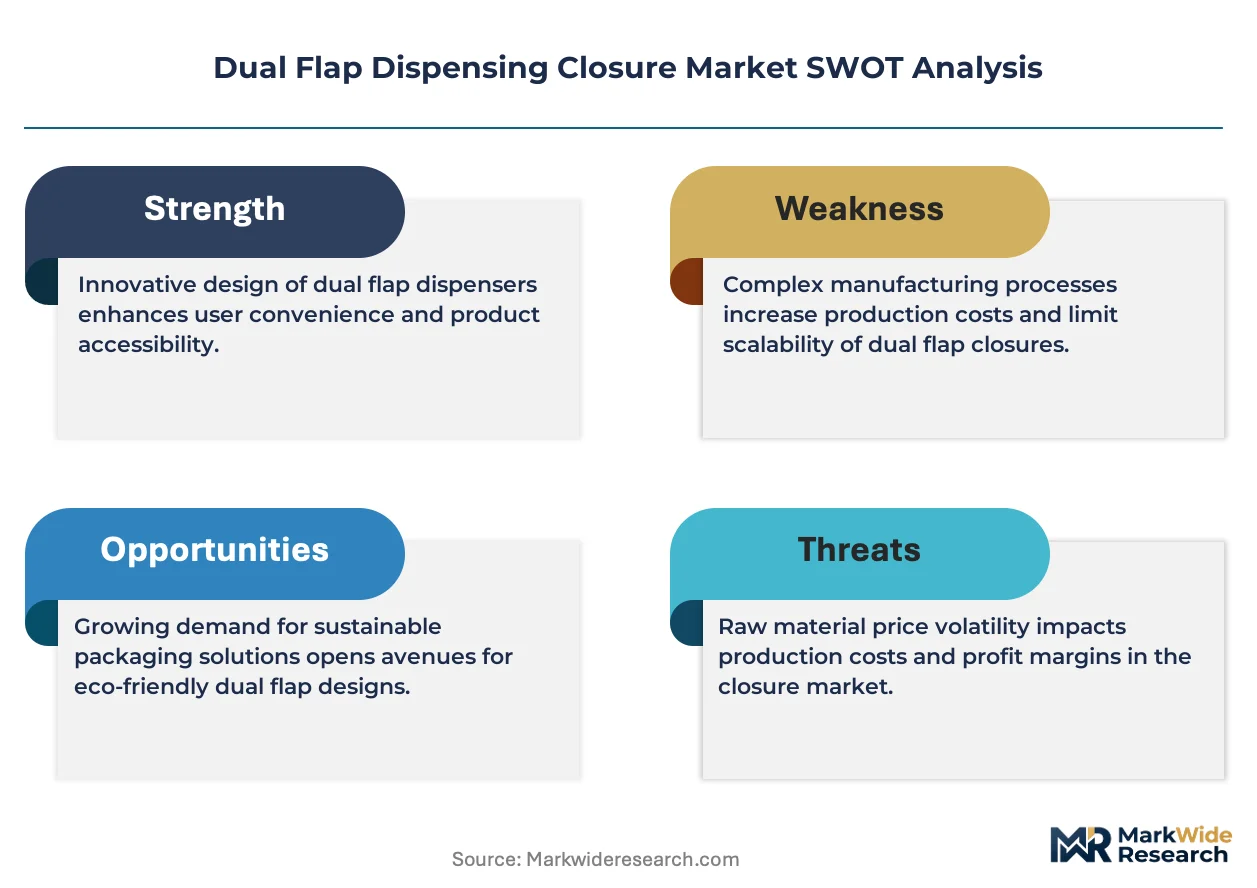
EU REACH substance restrictions and the Packaging and Packaging Waste Regulation are forcing resin reformulation across the dual flap dispensing closure supply chain, compressing lead times for material qualification and tooling recertification.
Growth Catalysts
- Food and Beverage Packaging Demand:Processed condiment and sauce brands are specifying dual flap closures for controlled dosing and resealability in single-handed consumer use cases.
- REACH Compliance Deadlines:The EU's phased substance restrictions are accelerating R&D investment in compliant polypropylene and silicone valve formulations ahead of enforcement windows.
- Extended Producer Responsibility:Germany's lightweighting fee structures incentivize closure redesigns that reduce material mass per unit while maintaining hermetic seal performance.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene and polyethylene resin prices fluctuate with crude oil and natural gas liquid markets, compressing margin predictability for high-volume molders.
- Specialized Tooling Concentration:Multi-cavity injection molds for dual flap mechanisms concentrate with a limited base of precision toolmakers in Germany and the United States.
- Recyclability Design Constraints:EU Packaging and Packaging Waste Regulation recyclability mandates limit material combinations that would otherwise optimize valve performance.
Strategic Opportunities
- Pharmaceutical Dosing Applications:Tamper-evident and child-resistant certified variants open margin pools in OTC liquid medication packaging requiring specialized closure engineering.
- Composite Material Convergence:Bio-based resin development combined with recycled content integration addresses brand sustainability commitments without sacrificing functional performance.
- China SAMR Market Access:GB standards compliance for food-contact plastics creates qualification pathways for foreign closure suppliers targeting processed food manufacturing clusters.
Industry Challenges
- Multi-Cavity Mold Engineering Talent:Precision injection molding expertise for hermetic seal geometries remains concentrated among aging specialist workforces in European tooling hubs.
- Regulatory Certification Timelines:FDA food-contact notification and EU REACH substance authorization processes extend product development cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dual Flap Dispensing Closure Market |
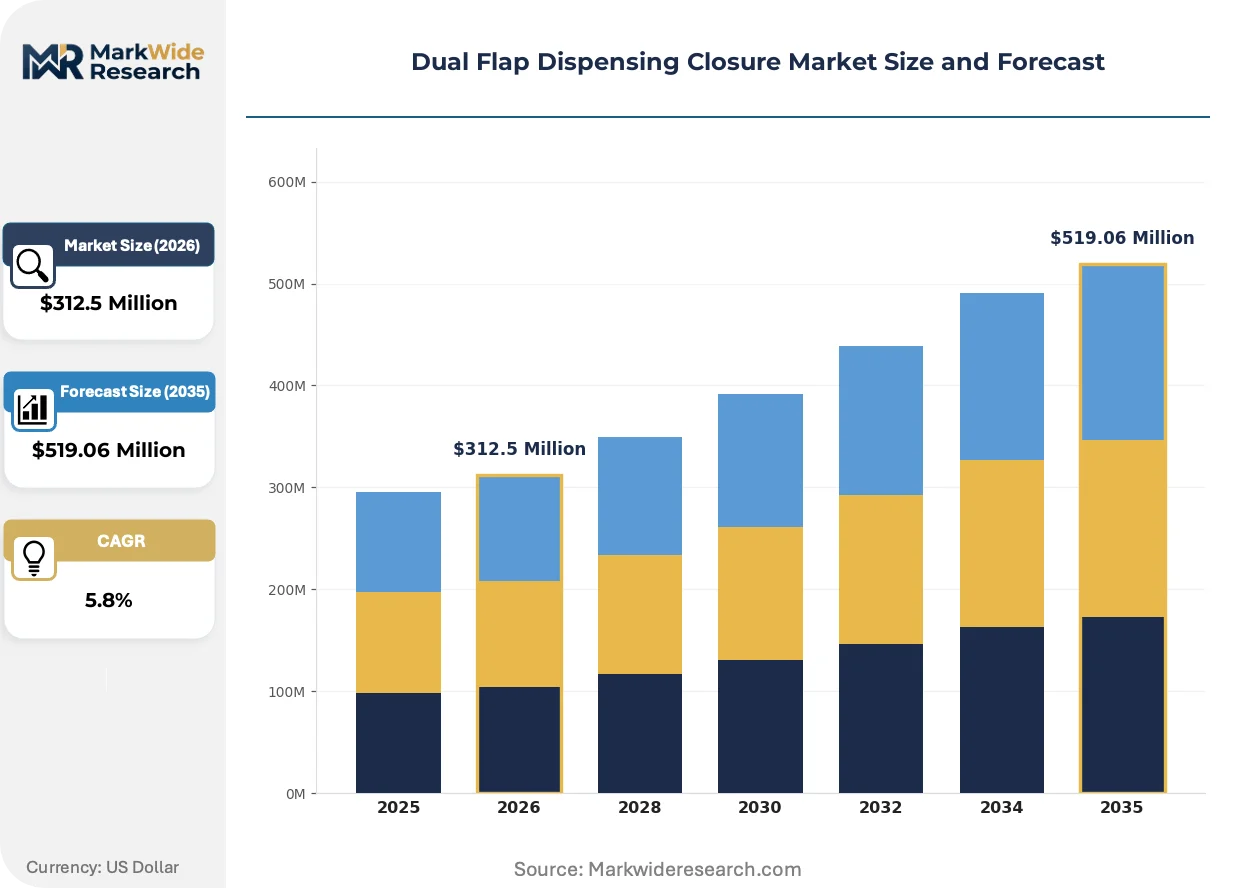
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flip Top, Squeeze Bottle, Pump Dispenser, Wide Mouth Material: Plastic, Metal, Glass, Composite End User: Food & Beverage, Personal Care, Pharmaceuticals, Household Application: Cosmetics, Sauces, Cleaning Products, Others |
| Companies Covered | Guala Closures Group, Albea Group, AptarGroup, Inc., Weener Plastics Group BV, O.Berk Company, LLC, Silgan Holdings Inc., RPC Group Plc, Mold-Rite Plastics, LLC, Berry Global, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dual Flap Dispensing Closure Market Shifts & Advancements
Material science advances and regulatory compliance architectures are restructuring competitive advantage in dual flap dispensing closure manufacturing, with sustainability credentials and precision dosing performance emerging as the primary differentiation vectors.
Silicone valve insert technology is decentralizing controlled-release performance across mid-tier closure suppliers who previously lacked proprietary elastomer formulation capabilities. Personal care and pharmaceutical packagers are adopting these inserts at accelerated rates for viscous product categories. The technology is decentralizing margin capture from specialized compounders to integrated closure molders capable of in-house valve production.
EU Packaging and Packaging Waste Regulation recyclability design standards are mandating mono-material construction and eliminating non-recyclable component combinations in closure assemblies. Industrial consequence includes accelerated R&D spending on polypropylene valve geometries that replicate silicone performance. Food and beverage applications in Germany and France face the most immediate compliance pressure, driving lightweighting redesigns ahead of 2030 targets.
Buyer concentration among multinational processed food and personal care conglomerates is compressing supplier qualification cycles and unbundling tooling ownership from manufacturing contracts. Brand procurement teams are demanding dedicated mold assets with contractual exclusivity rather than shared tooling pools. This pattern is most visible in United States and German supply relationships where volume commitments justify captive tooling investments.
Dual Flap Dispensing Closure Market Segmentation
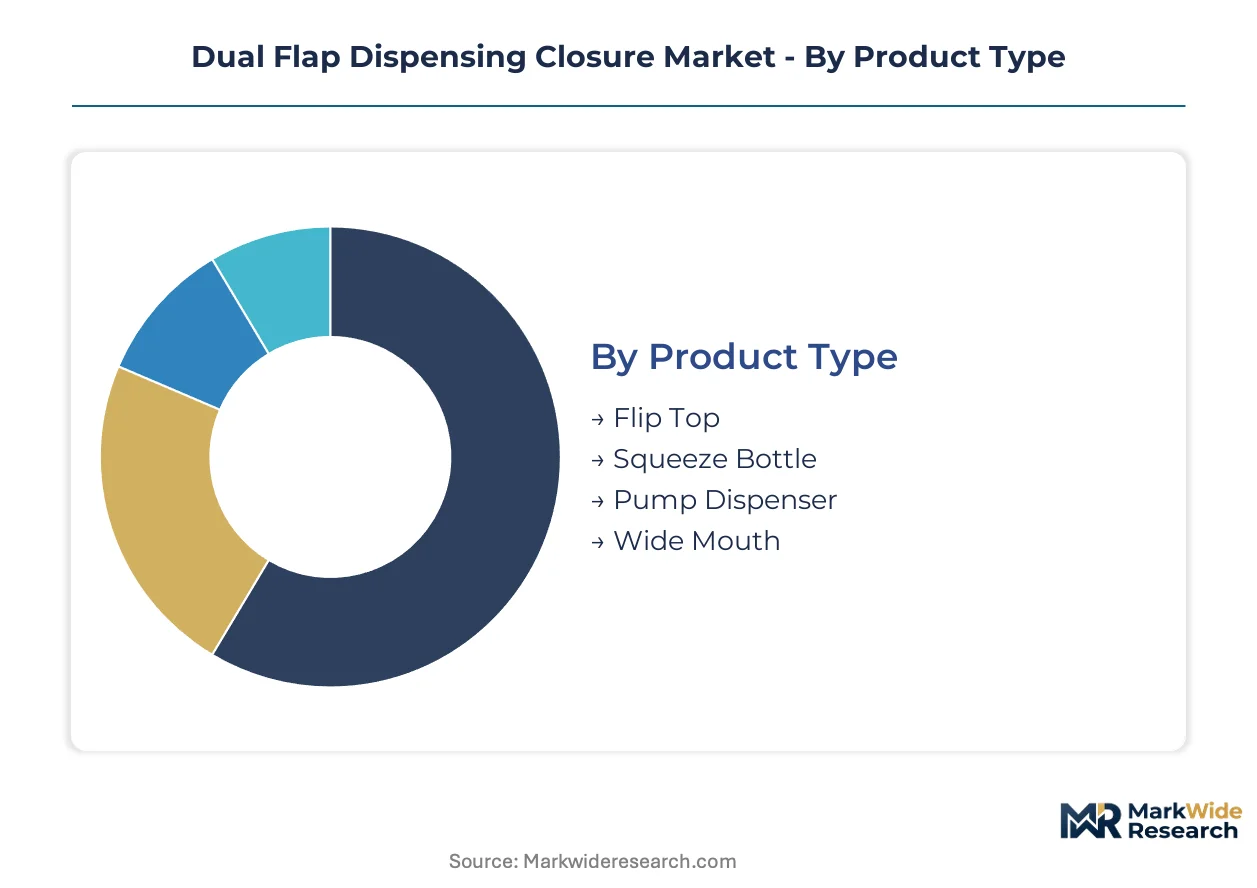
Dual flap dispensing closure procurement decisions hinge on material compatibility with product chemistries, regulatory compliance tiers, and manufacturing scale economics. Segment boundaries are blurring as pharmaceutical-grade specifications migrate into premium personal care applications.
Product Type:
Flip top configurations dominate standalone condiment packaging while pump dispensers embed into integrated personal care systems with secondary containment requirements.
- Flip Top:Hinged polypropylene lids with silicone valve inserts achieve single-handed operation for viscous sauces and condiments. Demand concentrates in United States processed food manufacturing where consumer convenience drives specification. FDA food-contact notification requirements govern resin selection for these high-volume applications.
- Squeeze Bottle:Integrated closure-body combinations with controlled-release geometries suit medium-viscosity personal care formulations. Germany's lightweighting fee structures incentivize material reduction in these designs without compromising hermetic seal performance.
- Pump Dispenser:Precision dosing mechanisms with calibrated stroke volumes serve pharmaceutical and cosmetic applications requiring repeatable unit delivery.
- Wide Mouth:Large-diameter apertures accommodate chunky or high-viscosity products in household and industrial cleaning segments.
Flip top leads volumes today; squeeze bottle configurations are gaining share fastest in European personal care markets.
Material:
Cost tiers separate commodity resin formulations from certified pharmaceutical-grade and emerging bio-based alternatives with divergent qualification timelines.
- Plastic:Polypropylene and polyethylene resins deliver lowest per-unit cost and compatibility with existing mechanical recycling infrastructure. REACH substance restrictions are forcing reformulation of additive packages ahead of enforcement windows.
- Metal:Aluminum and steel closures serve premium spirits and cosmetic applications where tactile weight signals quality positioning. China's SAMR import rules create compliance pathways for foreign suppliers targeting domestic manufacturing clusters.
- Glass:Borosilicate and soda-lime formulations provide inert contact surfaces for reactive pharmaceutical compounds.
- Composite:Multi-layer constructions combining bio-based resins with recycled content address EU Packaging and Packaging Waste Regulation targets while maintaining valve performance.
Plastic dominates unit economics across all tiers; composite materials are climbing the fastest as brand sustainability commitments harden into procurement specifications.
End User:
Application maturity separates established food and beverage specifications from emerging pharmaceutical compliance requirements with extended certification cycles.
- Food & Beverage:Processed condiment and sauce brands specify dual flap closures for controlled dosing and resealability. United States manufacturing concentration drives volume concentration with multinational procurement teams demanding dedicated mold assets.
- Personal Care:Premium cosmetic and hygiene product lines adopt tamper-evident variants with specialized tooling investments. EU REACH compliance deadlines are accelerating R&D spending on compliant silicone valve formulations.
- Pharmaceuticals:OTC liquid medication packaging requires child-resistant certified closures with margin pools concentrated among specialized engineering suppliers.
- Household:Industrial and consumer cleaning product applications prioritize chemical resistance and cost minimization over premium features.
Food and beverage leads volumes today; pharmaceutical applications are expanding most quickly as dosing precision requirements tighten.
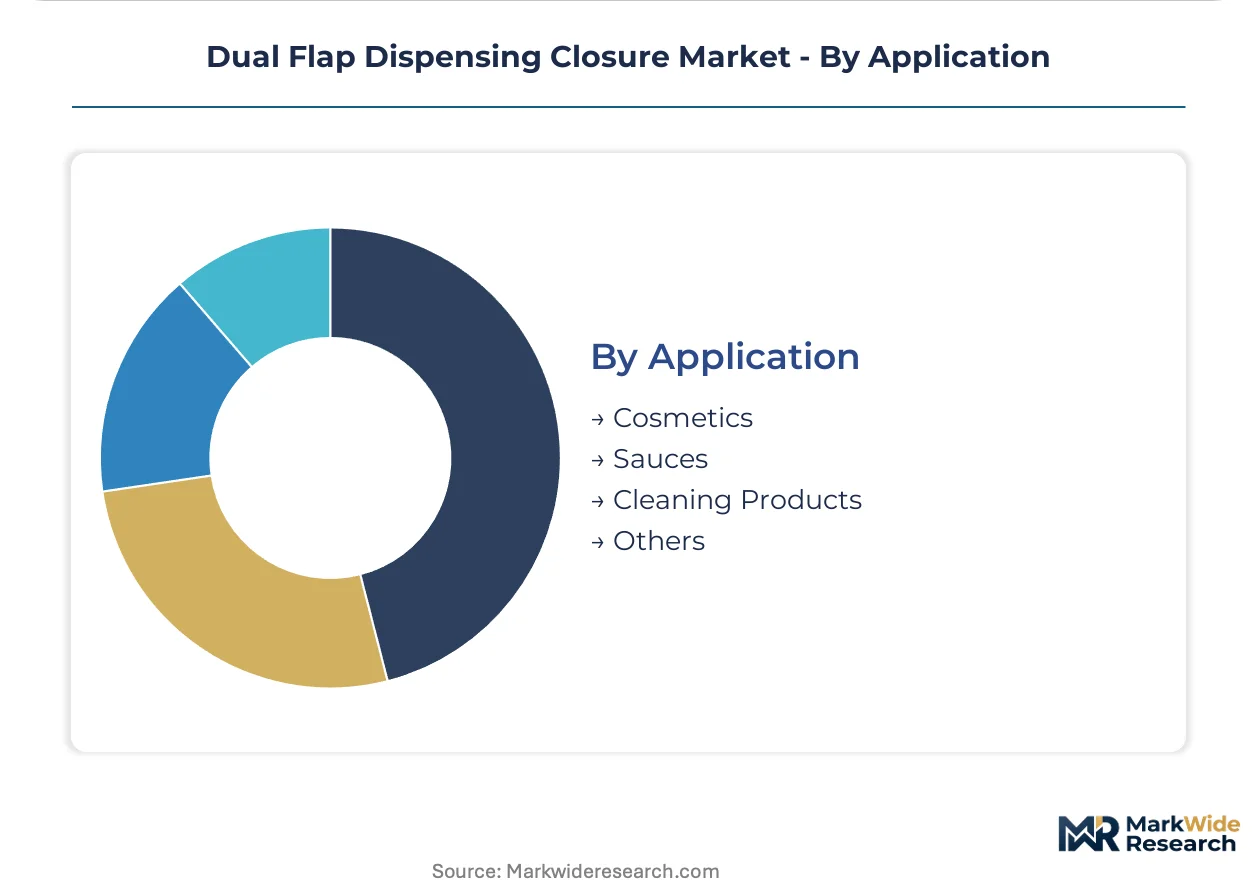
Application:
Supply concentration varies sharply between fragmented cosmetic brand portfolios and consolidated sauce manufacturing with captive tooling arrangements.
- Cosmetics:Premium skincare and haircare formulations demand precision valve performance with aesthetic surface finishes. Germany's extended producer responsibility fees incentivize lightweighting redesigns in this high-margin segment.
- Sauces:Ketchup, mayonnaise, and specialty condiment packaging drives highest absolute volume with standardized flip top specifications. United States and China host the largest manufacturing bases with concentrated buyer power.
- Cleaning Products:Aggressive chemical compatibility requirements favor polypropylene constructions with enhanced additive packages for long-term seal integrity.
- Others:Automotive fluids, adhesives, and industrial lubricants represent niche applications with specialized material requirements.
Sauces lead volumes today; cosmetics are gaining share fastest as premium personal care brands upgrade closure specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States processed food manufacturing clusters anchor regional demand concentration for dual flap dispensing closures, with regulatory frameworks and procurement patterns diverging sharply across major producing economies.
United States
Condiment and sauce packaging lines in Chicago and Pittsburgh drive specification volumes for flip top configurations. FDA food-contact notification requirements govern resin selection and additive migration limits for closures serving domestic food and beverage markets. Midwest manufacturing corridors host concentrated buyer power among multinational processed food conglomerates demanding dedicated mold assets.
Germany
Extended producer responsibility fee structures incentivize lightweight closure redesigns among personal care packagers in Hamburg and Düsseldorf. EU REACH substance restrictions and the Packaging and Packaging Waste Regulation constrain material combinations and mandate recyclability design standards. Bavarian precision tooling hubs concentrate multi-cavity injection mold engineering expertise for hermetic seal geometries.
China
Processed food manufacturing expansion in Guangdong and Jiangsu provinces generates import qualification pathways for foreign closure suppliers. SAMR market access rules and GB standards for food-contact plastics shape compliance requirements for polypropylene and polyethylene resin formulations. Yangtze River Delta clusters host the largest domestic sauce and condiment production bases.
France
Premium cosmetic brands in Paris and Lyon adopt tamper-evident dual flap variants with specialized tooling investments. EU Packaging and Packaging Waste Regulation recyclability mandates accelerate R&D spending on mono-material polypropylene valve geometries. Auvergne-Rhône-Alpes packaging corridors concentrate personal care manufacturing with stringent sustainability procurement specifications.
India
FSSAI food safety standards and BIS certification requirements govern closure material specifications for domestic and export-oriented food processors. Maharashtra and Gujarat industrial corridors host emerging condiment manufacturing capacity with growing closure specification activity. Western India packaging clusters increasingly source compliant polypropylene formulations for viscous liquid applications.
Dual Flap Dispensing Closure Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based material certifications and regional regulatory qualification pathways. The supplier base concentrates among precision injection molders with captive multi-cavity tooling assets and integrated valve production capabilities. Three archetypes dominate: scale-driven mass-market suppliers, premium-tier specialists in wine and spirits formats, and mid-tier integrated molders acquiring silicone valve technology. Competitive dynamics center on dedicated mold ownership contracts and backward integration into valve compound formulation.
Among European-origin specialists, Guala Closures Group and AptarGroup, Inc. exemplify divergent positioning archetypes—one anchored in premium dispensing formats, the other leveraging transatlantic precision molding networks. Silgan Holdings Inc. represents the scale-driven mass-market tier with high-volume manufacturing infrastructure. These three entities collectively illustrate how geographic manufacturing distribution and end-use specialization stratify competitive positioning across food, beverage, and personal care segments.
| Leading Market Players |
|---|
| Guala Closures Group |
| Albea Group |
| AptarGroup, Inc. |
| Weener Plastics Group BV |
| O.Berk Company, LLC |
| Silgan Holdings Inc. |
| RPC Group Plc |
| Mold-Rite Plastics, LLC |
| Berry Global, Inc. |
| Others |
Supply & Pricing Matrix
EU Packaging and Packaging Waste Regulation recyclability mandates gate qualified supply for dual flap dispensing closures, restricting premium-tier pricing access to molders with certified mono-material capabilities and in-house valve production. German extended producer responsibility fee structures compress margin pools for non-compliant suppliers while concentrating pricing power among integrated manufacturers with lightweighting expertise.
Pricing Analysis
Polypropylene and polyethylene resin cost pass-through dominates transactional pricing structures across the dual flap dispensing closure sector. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade certified variants from food-contact compliant and uncertified commodity tiers. Pricing pressure stems from petrochemical feedstock volatility compressing margin predictability for high-volume molders. Mass-market food and beverage buyers exhibit highest price sensitivity, while pharmaceutical and premium personal care segments absorb certification premiums with minimal volume elasticity.
Supply Chain Analysis
Single-source vulnerability sits with precision multi-cavity injection mold engineering concentrated in Germany and the United States. Raw material sourcing draws from Saudi Arabian and South Korean polypropylene suppliers, German silicone compounders, and Chinese polyethylene producers. Tariff exposure on specialized tooling imports from Bavarian hubs presents structural risk for North American closure manufacturers. Distribution runs through direct OEM supply contracts with multinational processed food and personal care conglomerates, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dual flap dispensing closure market represents a late-cycle quality story as pharmaceutical and premium personal care brands shift procurement specifications toward tamper-evident and child-resistant certified variants with extended qualification timelines.
For Market Incumbents: Lock in dedicated mold asset ownership through contractual exclusivity arrangements with multinational processed food conglomerates. Secure backward integration into silicone valve compound formulation to capture margin pools decentralizing from specialized elastomer suppliers. Prioritize certification investment for FDA food-contact notification and EU REACH substance authorization ahead of enforcement windows to defend against emerging bio-based material entrants. For New Entrants and Emerging Players: Enter via regional regulatory qualification pathways targeting China's SAMR GB standards compliance for food-contact plastics in Yangtze River Delta manufacturing clusters. White-space opportunity concentrates in mid-tier personal care brands seeking REACH-compliant silicone valve formulations without captive tooling investments. Pursue composite material convergence positioning combining bio-based resins with recycled content to differentiate against established polypropylene suppliers. For Investors and Strategic Acquirers: Roll-up economics work for precision injection molders with integrated valve production capabilities because buyer concentration among multinational conglomerates is unbundling tooling ownership from manufacturing contracts. Long-term viability favors mid-cap specialists with transatlantic manufacturing footprints and pharmaceutical certification pipelines. Watch EU Packaging and Packaging Waste Regulation enforcement phases as inflection indicator for accelerated lightweighting redesign demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Valve Production | Captures margin pools decentralizing from specialized silicone compounders to integrated molders. |
| Pharmaceutical Certification Investment | Opens margin pools in OTC liquid medication packaging requiring child-resistant closure engineering. |
| Lightweighting Redesign Program | Reduces material mass per unit to comply with Germany's extended producer responsibility fee structures. |
| Regional Regulatory Qualification | Creates market access pathways for foreign suppliers targeting China's SAMR GB standards compliance. |
| Composite Material Development | Addresses EU Packaging and Packaging Waste Regulation targets while maintaining valve performance specifications. |
Research Methodology
Bottom-up food and beverage procurement modeling reconciled against top-down precision injection molding capacity tracking forms the analytical core of this study. Primary interviews with closure design engineers, procurement leads at multinational processed food conglomerates, regulatory affairs specialists, and precision tooling program managers combined with secondary validation from FDA food-contact notification databases, EU ECHA substance restriction filings, SAMR GB standards documentation, and SEC 10-K disclosures from listed packaging suppliers. Top-down and bottom-up triangulation cross-checks volume assumptions against resin consumption patterns and installed mold capacity.
Historical trendline analysis of flip top, squeeze bottle, pump dispenser, and wide mouth configuration adoption rates informs the projection framework across the analysis window. Segmentation dimensions modeled include product type, material formulation tier, end-use industry vertical, application chemistry compatibility, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand curves incorporating petrochemical feedstock price scenarios and REACH compliance deadline impacts. Industry-specific forecast inputs encompass multi-cavity injection mold lead times and silicone valve insert technology diffusion rates.
Inputs from FDA notification databases and EU ECHA restriction timelines were available through the study window; gaps in real-time tooling capacity utilization data introduce uncertainty bands around precision molding supply assumptions. Forecasts reflect documented assumptions regarding regulatory enforcement sequencing and brand sustainability commitment translation into procurement specifications. Specific risk factors that could revise projections include accelerated EU recyclability mandate enforcement, polypropylene resin supply disruptions from feedstock volatility, and concentration of mold engineering talent in aging European specialist workforces. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Cork Stoppers Market
Caps and Closures
Sterile Lids Market
Caps and Closures
Gamma Seal Lids Market
Caps and Closures
Peelable Lid Stock Market
Caps and Closures
Aerosol Caps Market
Caps and Closures
Colombia Plastic Caps and Closures Market
Caps and Closures
Tear Tab Cap Market
Caps and Closures
Nordic Plastic Caps and Closures Market
Caps and Closures
Aluminium ROPP Closures Market
Caps and Closures
Pharmaceutical Caps and Closures Market
Caps and Closures
Sport Caps and Closures Market
Caps and Closures
Asia Pacific Metal Caps and Closures Market
Caps and Closures
Pressure Sensitive Wads Market
Caps and Closures
Plastic Caps and Closure Market
Caps and Closures
Benelux Plastic Caps and Closures Market
Caps and Closures
End Cap Market