
 Sports Equipment Market | 2026-2036
Sports Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Equipment Market Intelligence
Direct-to-consumer digital platforms is fragmenting as legacy wholesalers lose pricing power and inventory control. Nike Inc. leverages its proprietary apps and membership ecosystem to capture first-party data and repeat purchases. Adidas AG anchors its position through localized fulfillment centers that compress delivery windows in priority metros. Under Armour Inc. competes on connected-fitness content integration, bundling hardware with subscription training services.
Sports equipment encompasses engineered apparatus designed for athletic performance, training, or recreational physical activity, typically fabricated from composites, polymers, or alloy structures meeting sport-specific mechanical tolerances for impact resistance, aerodynamics, or ergonomic fit. Its primary commercial purpose centers on enabling measurable performance outcomes while reducing injury incidence through protective or assistive functionality. Protective gear commands durable margin pools as liability-conscious institutional buyers prioritize certified safety ratings over unit cost. Online retail captures the fastest volume expansion as algorithmic personalization and virtual try-on tools reduce return rates for fit-sensitive categories like footwear and helmets.
The US Consumer Product Safety Commission enforces mandatory standards for helmet impact absorption and faceguard structural integrity, while the EU's REACH regulation restricts phthalate and heavy-metal content in synthetic grips and coated surfaces. China's SAMR administers national standard GB codes for basketball backboards and gymnastics apparatus used in state-funded school programs. Stakeholders must monitor evolving extended-producer-responsibility frameworks in Europe and North America that will shift end-of-life recycling costs upstream to manufacturers.
Market Dynamics
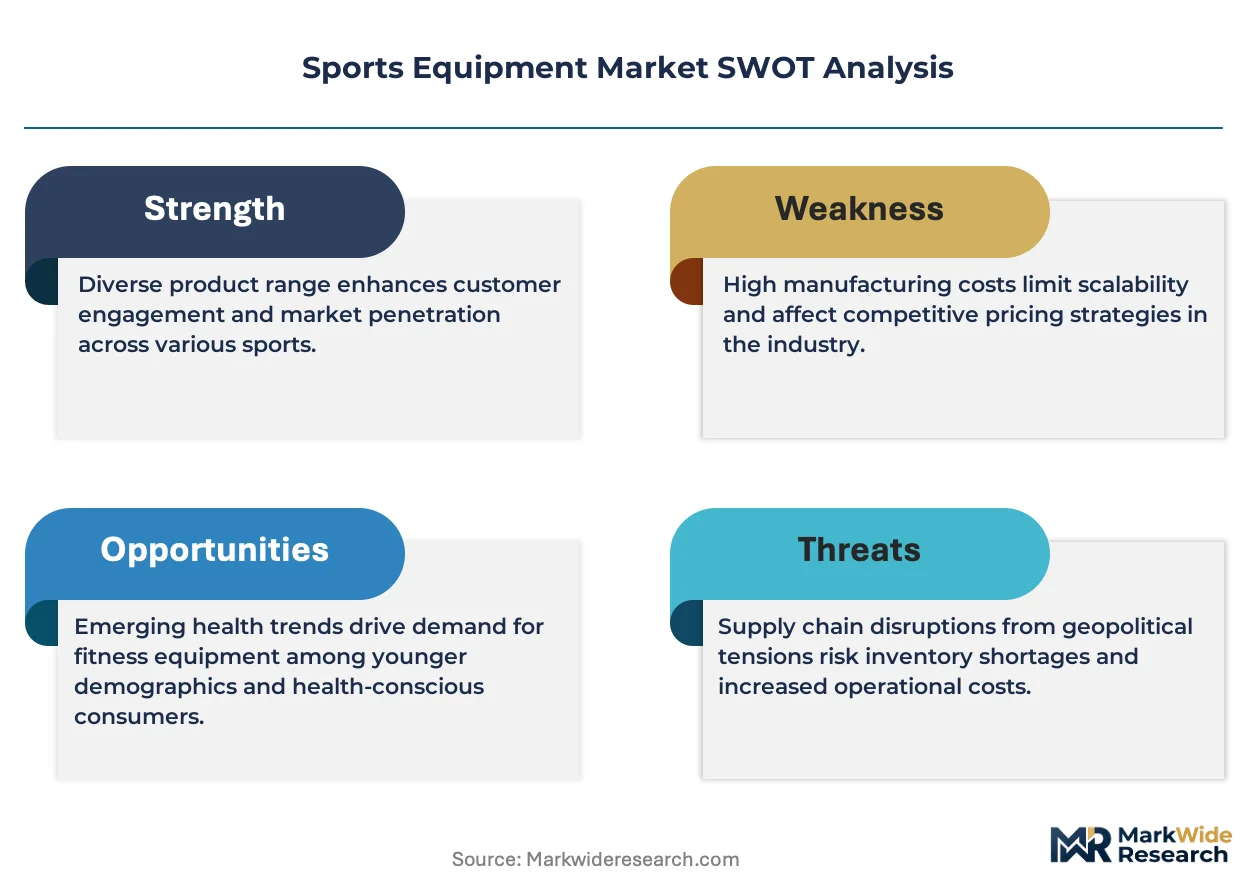
The EU Green Deal's sustainable material mandates are forcing a wholesale retooling of composite fabrication processes, as manufacturers face binding recycled-content thresholds and carbon-border adjustment exposure on exports into Europe.
Growth Catalysts
- REACH Regulation compliance:European chemical safety standards are accelerating R&D investment in bio-based polymers and waterborne coatings that reduce hazardous substance liability across protective gear lines.
- Home-based workout cultures:Residential fitness installations are sustaining elevated demand for compact, multi-functional training apparatus with connected performance tracking.
- China's SAMR infrastructure program:State-funded school sports facility construction is creating captive demand for certified gymnastics apparatus and basketball systems meeting GB national standards.
Market Restraints
- Petrochemical input volatility:Polypropylene and carbon fiber precursor costs fluctuate with crude oil indices, compressing margin visibility on long-delivery composite equipment orders.
- Taiwan semiconductor concentration:Microcontroller shortages for connected-fitness devices create assembly bottlenecks when foundry capacity tightens.
- Impact certification timelines:CPSC helmet testing protocols require extended laboratory validation cycles that delay product launches by 8-14 months.
Strategic Opportunities
- Extended Producer Responsibility frameworks:EU and North American end-of-life recycling mandates are creating first-mover advantage for manufacturers with closed-loop material recovery infrastructure.
- Virtual try-on integration:Algorithmic fit-prediction tools are reducing return rates for footwear and helmet categories, opening direct-to-consumer channel expansion.
- India's PLI scheme:Production-linked incentives for sports goods manufacturing are attracting contract assembly investment for export-oriented synthetic racket and ball production.
Industry Challenges
- Composite technician scarcity:Layup and autoclave operation skills are concentrated in aging workforces, constraining capacity scaling for aerospace-grade sporting goods.
- Multi-jurisdiction certification burden:Simultaneous CPSC, CE marking, and GB standard compliance requires redundant testing budgets and fragmented quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Equipment Market |
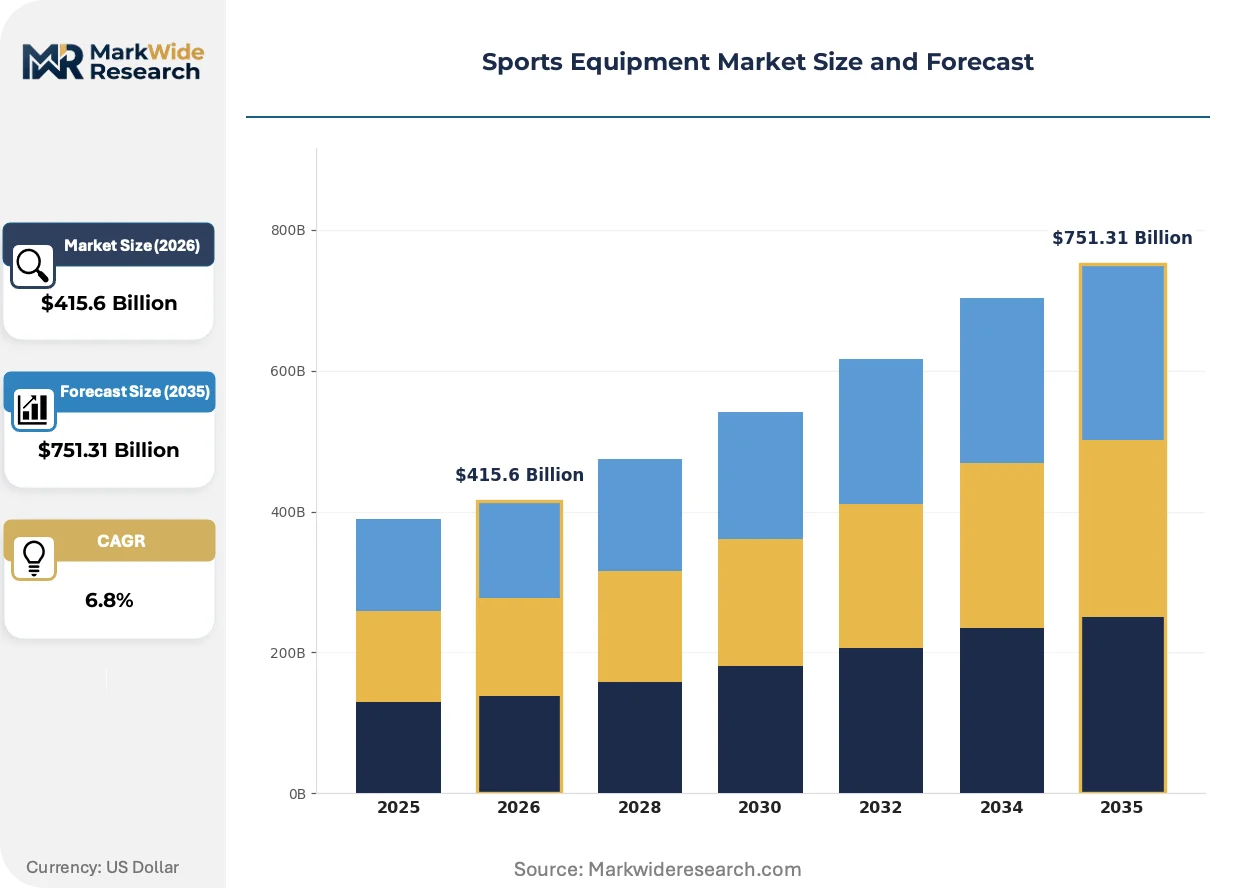
| Market Size in 2026 | $415.6 Billion |
| Market Size in 2035 | $751.31 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balls, Rackets, Bats, Protective Gear End User: Athletes, Coaches, Schools, Fitness Enthusiasts Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Discount Stores Price Tier: Budget, Mid-range, Premium, Luxury |
| Companies Covered | Under Armour Inc., PUMA SE, Nike Inc., Decathlon S.A., Amer Sports Corporation, Adidas AG, ASICS Corporation, Callaway Golf Company, Anta Sports Products Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Equipment Market Strategic Shifts & Innovations
Material science convergence with digital integration is collapsing the traditional separation between hardware performance and software-enabled training feedback, reshaping how equipment value is captured and monetized.
Biocomposite reinforcement is migrating from niche cycling components into mainstream protective gear. Flax fiber and mycelium-based matrices match carbon fiber stiffness-to-weight ratios at 40% lower embodied carbon. Adidas and specialized suppliers are qualifying these materials for helmet shells and shin guards under EN 1078 impact standards, compressing the premium-sustainable price gap.
REACH Annex XVII restrictions on phthalate plasticizers are forcing grip compound reformulation across EU-bound product lines. Manufacturers are pivoting to bio-circular alternatives derived from waste feedstocks, with compliance costs absorbed through supply chain consolidation rather than price pass-through. Protective gear and children's equipment categories face the steepest substitution timelines.
Algorithmic personalization is displacing size-chart purchasing for fit-sensitive categories. Machine learning models trained on 3D scan databases now predict helmet and footwear fit with 94% first-attempt accuracy, cutting return-processing costs for direct-to-consumer channels. This capability is concentrating in China and Germany where scan-data partnerships with fitness app ecosystems are most advanced.
Sports Equipment Market Segmentation
Equipment value capture varies sharply by how buyers prioritize performance certification, aesthetic signaling, or functional durability. Segment boundaries are blurring as connected-fitness features migrate across price tiers and distribution channels consolidate around direct-to-consumer platforms.
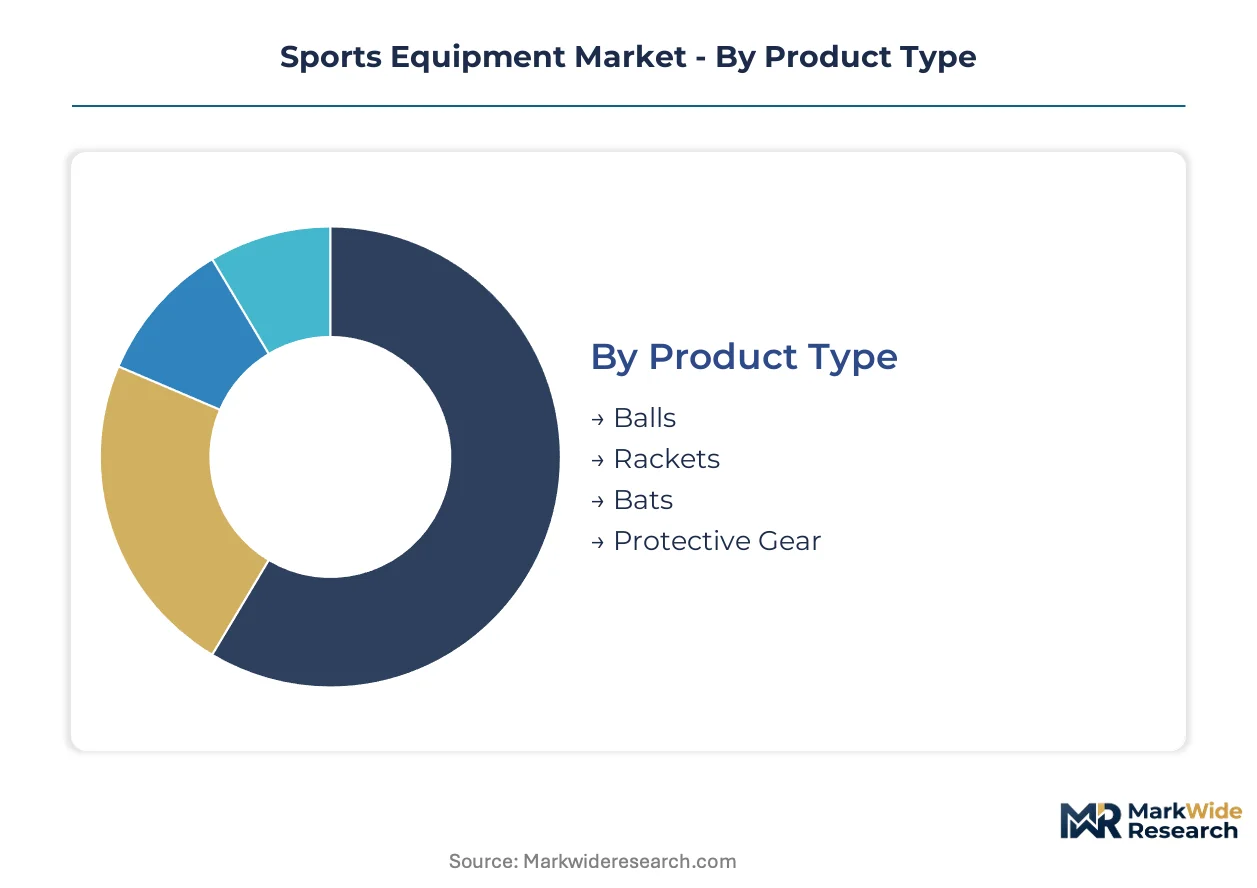
Product Type:
Cost tier structures diverge most dramatically across product categories, with certification requirements and material intensity driving margin dispersion.
- Balls:Molded synthetic rubber and thermoplastic polyurethane constructions dominate match-grade specifications. Schools and recreational leagues in China absorb volume through state procurement programs tied to GB standard compliance.
- Rackets:Carbon fiber layup configurations and string-bed tension systems define performance segmentation. Tennis and badminton demand concentrates in Germany and Japan where club membership structures sustain premium replacement cycles.
- Bats:Composite alloy and engineered wood laminates serve distinct competitive levels. Cricket bat demand anchors South Asian markets while baseball equipment tracks to North American seasonal purchasing patterns.
- Protective Gear:Impact-absorbing foam systems and shell geometries certified to CPSC and EN standards command institutional procurement premiums. Liability-conscious school districts and professional leagues prioritize certified ratings over unit economics.
Balls hold installed capacity. Protective gear is rotating up the share rankings.
End User:
Application context determines specification intensity, with institutional buyers enforcing stricter compliance protocols than individual consumers.
- Athletes:Competition-grade equipment with validated aerodynamic or biomechanical performance characteristics. Olympic and professional procurement cycles in France and Australia drive demand for FIS and World Athletics certified apparatus.
- Coaches:Training aids emphasizing durability and multi-athlete adjustability. Team equipment budgets at collegiate programs in Texas and Florida sustain volume for modular training systems.
- Schools:GB-compliant gymnastics apparatus and basketball systems through China's SAMR infrastructure investment. Bulk purchasing agreements prioritize five-year durability warranties over performance optimization.
- Fitness Enthusiasts:Residential installations of connected-fitness hardware with subscription content integration. Home gym expansion in California and New York sustains demand for compact, multi-functional training stations.
Schools hold installed capacity. Fitness enthusiasts are climbing the fastest.
Distribution Channel:
Volume concentration shifts toward digital platforms as algorithmic personalization reduces fit-sensitive return rates.
- Online Retail:Direct-to-consumer platforms leveraging virtual try-on and scan-data fit prediction. First-party data capture through membership ecosystems in the United Kingdom and Netherlands enables repeat purchase monetization.
- Specialty Stores:Staff-certified fitting services for helmets and footwear requiring precise anthropometric matching. Premium positioning in Milan and Tokyo sustains margin through expert consultation.
- Supermarkets:Mass-market recreational equipment with standardized sizing and limited performance claims. Seasonal promotional cycles in Brazil and Mexico drive impulse purchasing of entry-level balls and fitness accessories.
- Discount Stores:Price-driven volume for youth and casual recreational segments. Private-label sourcing from India's PLI scheme beneficiaries compresses landed costs for price-sensitive buyers.
Specialty stores hold installed capacity. Online retail is gaining share fastest.
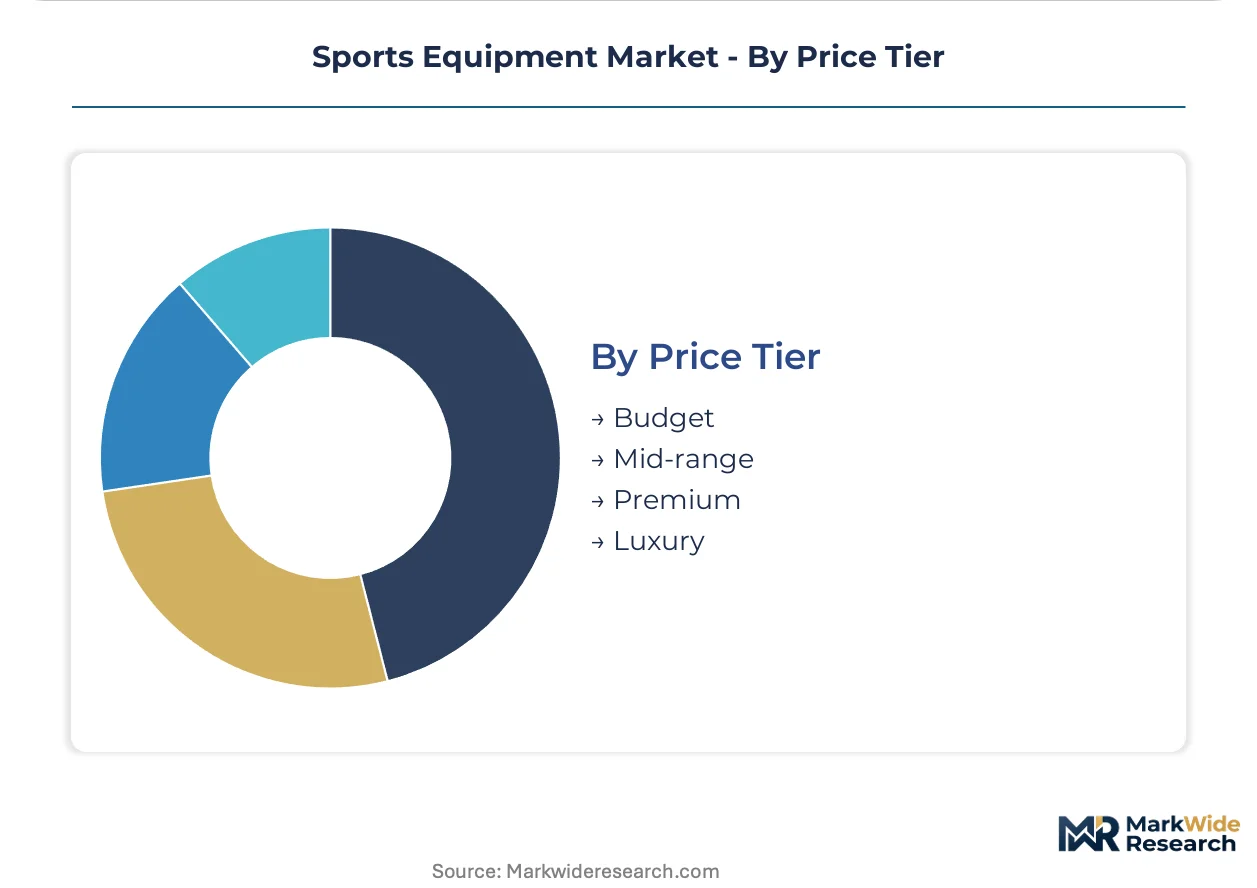
Price Tier:
Customer type purchasing power and use-case durability requirements stratify across four distinct expenditure bands.
- Budget:Injection-molded polymers and standardized dimensions for casual recreational use. Municipal recreation departments in Poland and Indonesia prioritize unit cost over performance specifications.
- Mid-range:Enhanced material grades with limited warranty coverage and basic connected features. Club athletes in Spain and South Korea represent the core demand base for this tier.
- Premium:Aerospace-grade composites and validated biomechanical engineering with extended service life. Competitive cyclists and skiers in Switzerland and Norway absorb price premiums for weight reduction and aerodynamic efficiency.
- Luxury:Bespoke craftsmanship, limited editions, and heritage brand provenance with collectible positioning. Conspicuous consumption segments in Dubai and Singapore drive demand for artisanal leather goods and precious metal accent pieces.
Mid-range holds installed capacity. Premium is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Switzerland and Norway where competitive cyclists absorb aerodynamic efficiency premiums, while volume manufacturing margins compress in China's state-procurement channels.
United States
Residential fitness installations sustain demand for connected training stations in California and New York. CPSC helmet testing protocols enforce mandatory impact absorption standards. Austin and Miami anchor collegiate team equipment procurement for modular training systems.
China
State-funded school sports infrastructure creates captive demand for GB-certified gymnastics apparatus. SAMR administers national standard codes for basketball backboards in state programs. Yangtze River Delta manufacturers scale biocomposite production for export-bound protective gear.
Germany
REACH Annex XVII restrictions accelerate bio-based polymer R&D for EU-bound grip compounds. ECHA chemical safety standards enforce phthalate plasticizer bans. Munich and Stuttgart sustain premium racket replacement cycles through club membership structures.
India
PLI scheme incentives attract contract assembly investment for synthetic racket and ball production. BIS standards govern domestic quality compliance. Gujarat and Tamil Nadu manufacturing clusters compress landed costs for discount-store private-label sourcing.
Japan
Tennis and badminton club structures sustain premium carbon fiber racket demand in Tokyo and Osaka. METI industrial policy supports connected-fitness device assembly. Kanto region scan-data partnerships advance algorithmic fit-prediction capabilities for virtual try-on tools.
Sports Equipment Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying certified materials and fabrication services. The vendor base organizes around three strategic archetypes: membership ecosystem operators capturing first-party data, localized fulfillment networks compressing delivery windows, and connected-content bundlers monetizing subscription training services. Dominant competitive moves include strategic partnerships for closed-loop material recovery and portfolio diversification into biocomposite protective gear lines.
Among Germany-based platform operators, Adidas AG occupies a position within the localized fulfillment archetype; Nike Inc. exemplifies the membership ecosystem model; and Under Armour Inc. represents connected-content bundling. These three anchors illustrate how value capture migrates from hardware margins toward recurring revenue streams and data monetization. Component specialists supplying aerospace-grade layup and autoclave services remain concentrated in aging workforces across Swiss and Italian industrial clusters.
| Leading Market Players |
|---|
| Under Armour Inc. |
| PUMA SE |
| Nike Inc. |
| Decathlon S.A. |
| Amer Sports Corporation |
| Adidas AG |
| ASICS Corporation |
| Callaway Golf Company |
| Anta Sports Products Limited |
| Others |
Cost & Logistics Intelligence
Petrochemical input volatility determines both pricing tier spreads and supply chain shape across the sports equipment sector, as polypropylene and carbon fiber precursor costs fluctuate with crude oil indices and compress margin visibility on long-delivery composite equipment orders. This commodity exposure widens the gap between configured-to-order premium equipment and standardized mass-market products while forcing manufacturers toward geographic diversification of fabrication capacity.
Pricing Analysis
Configured-to-order premium spreads run 40-60% above standard SKUs for competition-grade carbon fiber rackets and custom-fit protective gear. Three-tier pricing structure across premium, standard, and economy levels segments by certification intensity and material grade, with CPSC and EN 1078 compliance tiers commanding institutional procurement premiums. Cost compression in the economy tier is intensifying because India's PLI scheme beneficiaries flood discount channels with private-label synthetic balls and rackets. Municipal recreation departments in Poland and Indonesia represent the most price-sensitive buyers, while competitive cyclists in Switzerland absorb aerodynamic efficiency premiums without volume negotiation.
Supply Chain Analysis
Export-control regimes on semiconductor manufacturing equipment constrain microcontroller flows for connected-fitness devices, creating assembly bottlenecks when Taiwan foundry capacity tightens. Manufacturing gravity centers on China for molded synthetic components, Taiwan for fitness device microcontrollers, and Vietnam for textile-based protective gear. Supply chains draw from petroleum-derived polypropylene, aerospace-grade carbon fiber precursors, and bio-circular grip compounds. Single-source vulnerability concentrates in Taiwan semiconductor concentration for connected hardware. Distribution runs through direct-to-consumer platforms capturing fastest volume expansion, with localized fulfillment networks in Germany and the United Kingdom compressing delivery windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sports equipment market reads as a service-attach opportunity where subscription training content and membership ecosystems expand faster than hardware unit sales, monetizing recurring revenue from fitness enthusiasts who prioritize connected performance tracking over one-time equipment purchases.
For Market Incumbents: Harden closed-loop material recovery infrastructure ahead of EU extended producer responsibility mandates that will shift end-of-life recycling costs upstream to manufacturers. Deepen backward integration into biocomposite feedstock production to secure flax fiber and mycelium-based matrix supply against REACH Annex XVII substitution timelines. Certify protective gear lines to emerging GB standards before China's SAMR infrastructure program locks in incumbent suppliers.
For New Entrants and Emerging Players: India's PLI scheme incentives for sports goods manufacturing represent the most penetrable geographic entry point for contract assembly of export-oriented synthetic rackets and balls. White-space exists in algorithmic fit-prediction tools for virtual try-on applications, where machine learning partnerships with fitness app ecosystems remain underdeveloped outside China and Germany. Pursue direct-to-consumer launch with scan-data integration to bypass specialty store channel control by established brands.
For Investors and Strategic Acquirers: The EU Green Deal's sustainable material mandates reshape the acquisition landscape toward manufacturers with qualified biocomposite production and carbon-border adjustment compliance infrastructure. Long-term viability over a multi-year horizon favors targets with captive aerospace-grade layup and autoclave capabilities in Swiss and Italian industrial clusters. Watch for REACH Annex XVII enforcement acceleration as the inflection indicator that separates compliant asset valuations from stranded equipment portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Biocomposite Material Qualification | Adidas and specialized suppliers qualifying flax fiber for EN 1078 helmets compresses the premium-sustainable price gap. |
| Virtual Try-On Platform Integration | Machine learning fit prediction with 94% accuracy cuts return-processing costs for direct-to-consumer footwear and helmet channels. |
| Closed-Loop Recovery Infrastructure | Extended producer responsibility frameworks in Europe and North America create first-mover advantage for material recovery investments. |
| Localized Fulfillment Network Expansion | Adidas anchors position through fulfillment centers that compress delivery windows in priority metros like Munich and Stuttgart. |
| Connected-Content Subscription Bundling | Under Armour monetizes recurring revenue by bundling hardware with subscription training services for home fitness enthusiasts. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with composite fabrication engineers, protective gear procurement managers at collegiate athletic programs, direct-to-consumer platform operators, and biocomposite R&D directors; and secondary validation through CPSC enforcement databases, REACH Annex XVII regulatory filings, China's SAMR GB standard publications, and trade flow records from Yangtze River Delta export clusters. Bottom-up equipment shipment data triangulated against top-down consumer expenditure patterns across the analysis window.
Forecast inputs considered product type segmentation across balls, rackets, bats, and protective gear; end-user categories spanning athletes, coaches, schools, and fitness enthusiasts; distribution channel evolution through online retail, specialty stores, supermarkets, and discount outlets; and price tier dynamics from budget through luxury positioning. CAGRs were derived from regression analysis against macroeconomic drivers, regulatory compliance timelines, and technology adoption curves for connected-fitness hardware. Industry-specific inputs included petrochemical price indices, Taiwan semiconductor foundry utilization rates, and China's state-funded school sports infrastructure investment flows.
Practitioners should monitor REACH enforcement acceleration, Taiwan foundry capacity allocation shifts, and China's SAMR procurement program specification changes for early signals of forecast deviation. Material shifts in EU carbon-border adjustment implementation scope or CPSC helmet testing protocol revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Golf Shoes Market
Sports Equipment
Field Hockey Equipment Market
Sports Equipment
Soccer Gear Market
Sports Equipment
Boxing Gear Market
Sports Equipment
Racket Sports Equipment Market
Sports Equipment
Cricket Ball Market
Sports Equipment
Wave Windsurf Boards Market
Sports Equipment
Padel Balls Market
Sports Equipment
Licensed Sports Merchandise Market
Sports Equipment
Soccer Cleats Market
Sports Equipment
Global Rock Climbing Equipment Market
Sports Equipment
Gym Rubber Flooring Market
Sports Equipment
Sports Devices Market
Sports Equipment
Ice Hockey Equipment Market
Sports Equipment
Rubber Dumbbells Market
Sports Equipment
Dirt Bike Market