
 Padel Balls Market | 2026-2036
Padel Balls Market Size, Share, and Industry Trends Forecast 2026-2036
Padel Balls Market Analytics
A shift from single-source to multi-source rubber procurement is restructuring supply economics for padel ball producers. HEAD leverages captive testing facilities in Austria to sustain quality consistency across pressurized lines. Babolat competes through geographic dominance in Southern European club channels. Wilson differentiates via R&D intensity in core-pressure retention technologies.
Padel balls are hollow pressurized spheres comprising a rubber core encased in synthetic felt, manufactured through core molding, pressurization, and felt-winding processes designed to deliver controlled rebound and durability on enclosed glass-and-turf courts. Pressurized variants anchor volume demand among professional and club segments where bounce consistency governs playability, while eco-friendly packaging formats represent the fastest-growing structural pocket as retailers face Scope 3 disclosure requirements. Composite material blends command margin concentration due to proprietary formulations that extend pressure retention cycles.
ISO standards governing ball rebound and mass tolerances intersect with EU REACH chemical restrictions on rubber additives to shape product compliance costs and reformulation timelines. Spain's national sports federation and Germany's KBA-equivalent consumer safety office both enforce ball-pressure testing protocols that filter substandard imports from club supply chains. Stakeholders must monitor evolving bio-based material certifications and pressure-labeling mandates that will determine which suppliers retain access to premium club procurement channels.
Market Dynamics
The EU Green Deal is forcing padel ball manufacturers to restructure material sourcing and packaging formats, creating simultaneous pressure on cost structures and competitive positioning across European club supply chains.
Growth Catalysts
- Club Infrastructure Expansion:Municipal court installations across Spain, Italy, and Sweden are generating institutional procurement volumes that sustain recurring ball replacement cycles.
- REACH Chemical Reformulation:Rubber additive restrictions under EU REACH are accelerating bio-based felt adoption, creating first-mover advantages for compliant suppliers in German club channels.
- Pressurization Technology:Core-pressure retention improvements are extending playable life, reducing per-match ball consumption rates among competitive leagues.
Market Restraints
- Natural Rubber Volatility:Southeast Asian latex supply disruptions transmit directly to core molding cost structures, compressing margins on standard-grade lines.
- Import Testing Protocols:Spain's national sports federation and Germany's KBA-equivalent consumer safety office enforce ball-pressure testing that filters substandard shipments from Asian suppliers.
- Synthetic Felt Substitution Limits:Bio-based alternatives currently fail to match wool-nylon blends on abrasion resistance, constraining premium product differentiation.
Strategic Opportunities
- Nordic Market Underpenetration:Sweden and Norway exhibit court installation rates outpacing ball supplier presence, creating channel expansion white space.
- Reduced-Packaging Mandates:EU Green Deal packaging waste directives favor manufacturers with compressed bulk formats and recycled cardboard sleeves.
- Pressure-Labeling Convergence:ISO rebound standards and emerging national labeling requirements are creating certification bundling opportunities for integrated testing facilities.
Industry Challenges
- Reformulation Timeline Compression:REACH chemical restrictions demand 18-month additive substitution cycles that strain R&D bandwidth at mid-tier manufacturers.
- Multi-Source Rubber Integration:Shifting from single-source to multi-source procurement requires requalification of core molding parameters, risking batch consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Padel Balls Market |
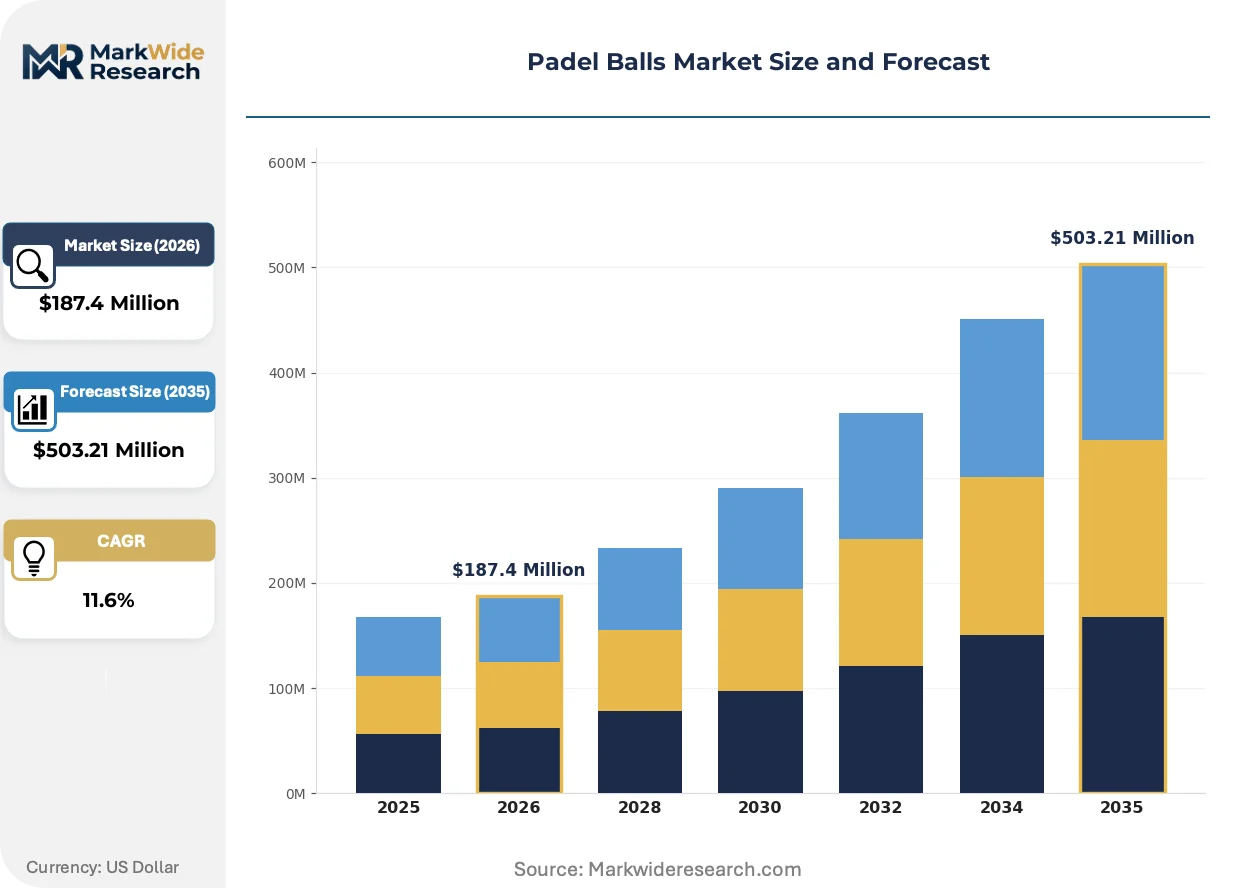
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressurized, Non-Pressurized, Premium, Budget Material: Rubber, Felt, Composite, Synthetic End User: Professional Players, Amateur Players, Clubs, Retail Outlets Packaging Type: Single Pack, Multi-Pack, Reusable, Eco-Friendly |
| Companies Covered | Babolat, DUNLOP, HEAD, Tretorn, NOX, Wilson, adidas, Franklin Sports, Bullpadel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Padel Balls Market Evolving Landscape
Material science advances and regulatory disclosure requirements are restructuring how padel balls are formulated, tested, and packaged for European club channels.
Composite rubber core blends incorporating proprietary pressure-retention polymers are consolidating competitive advantage among suppliers with captive formulation capabilities. Professional leagues and premium club segments are adopting these variants despite 15-20% unit cost premiums. The technology is consolidating market share around integrated manufacturers while marginalizing pure-assemblers dependent on commodity rubber inputs.
EU Green Deal bio-based material certifications are reshaping supplier qualification criteria for municipal procurement tenders. Manufacturers must demonstrate felt fiber sourcing from certified sustainable supply chains and packaging recyclability percentages to retain access to Spanish and Italian club channels. Mid-tier suppliers without sustainability documentation are experiencing systematic exclusion from institutional RFP processes.
Club procurement officers are consolidating purchase volumes through multi-year framework agreements with pressure-labeling transparency requirements. Traditional spot-market purchasing through retail distributors is contracting in favor of direct manufacturer relationships with batch testing documentation. This pattern is most pronounced in Spain, where competitive league standardization has created centralized procurement committees at regional federation levels.
Padel Balls Market Segmentation
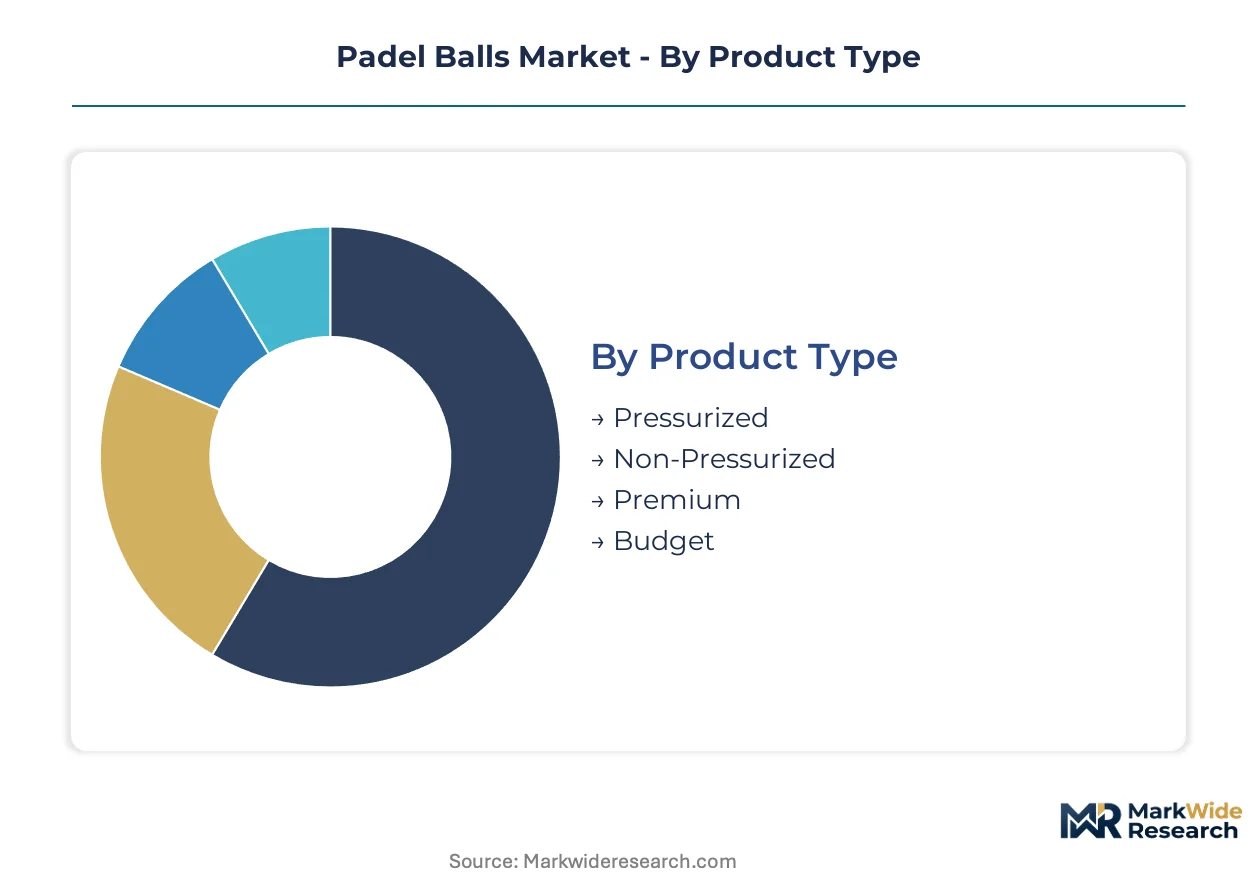
Padel ball segmentation maps directly to procurement channel requirements and regulatory compliance burdens across European club networks. Material specifications and pressure standards determine which suppliers qualify for institutional tenders versus retail distribution.
Product Type:
EU REACH chemical restrictions and ISO rebound certification requirements apply differentially across pressure categories, with professional leagues mandating documented pressure retention testing for competitive play.
- Pressurized:Hollow rubber cores inflated to specified internal pressure deliver consistent bounce characteristics demanded by competitive leagues and premium club segments. Spain's national sports federation enforces pressure-labeling protocols that filter non-compliant imports from institutional procurement channels.
- Non-Pressurized:Solid-core construction eliminates pressure degradation concerns, extending playable life for recreational and training applications where bounce consistency carries lower priority. Municipal court installations across Italy and Sweden specify these variants for public access programs with constrained replacement budgets.
- Premium:Proprietary composite formulations and extended warranties target tournament-grade performance requirements.
- Budget:Standard rubber cores with reduced felt specifications serve high-volume replacement cycles in entry-level club segments.
Leading the category by volume: Pressurized. Growing fastest: Premium.
Material:
Raw material cost structures diverge sharply between petroleum-derived synthetics and bio-based alternatives subject to EU Green Deal certification requirements.
- Rubber:Natural latex cores remain dominant for pressure retention properties, though Southeast Asian supply disruptions are forcing multi-source procurement restructuring. Core molding parameters require requalification when blending sources, risking batch consistency at mid-tier manufacturers.
- Felt:Wool-nylon blends face substitution pressure from bio-based alternatives that currently fail abrasion resistance benchmarks. German club channels prioritize suppliers with ECHA-compliant additive documentation.
- Composite:Proprietary polymer blends command margin concentration through extended pressure-retention cycles.
- Synthetic:Petrochemical-derived fibers offer cost advantages but face Scope 3 disclosure liabilities under CSRD-aligned retailer requirements.
Highest margin capture: Composite. Steepest cost pressure: Synthetic.
End User:
Procurement authority and volume concentration vary dramatically across player categories and institutional buyers.
- Professional Players:Tournament-grade specifications and batch testing documentation requirements concentrate demand around integrated manufacturers with captive testing facilities. Competitive leagues in Spain operate centralized procurement committees at regional federation levels.
- Amateur Players:Price-sensitive spot purchasing through retail distributors dominates, though direct-to-consumer channels are gaining share.
- Clubs:Multi-year framework agreements with pressure-labeling transparency requirements are displacing traditional distributor relationships across Southern Europe.
- Retail Outlets:Compressed margin structures and sustainability documentation demands favor suppliers with reduced-packaging formats and recycled cardboard sleeve capabilities.
Deepest volume concentration: Clubs. Fastest channel shift: Retail Outlets.
Packaging Type:
EU packaging waste directives are restructuring format preferences across procurement channels with diverging sustainability disclosure obligations.
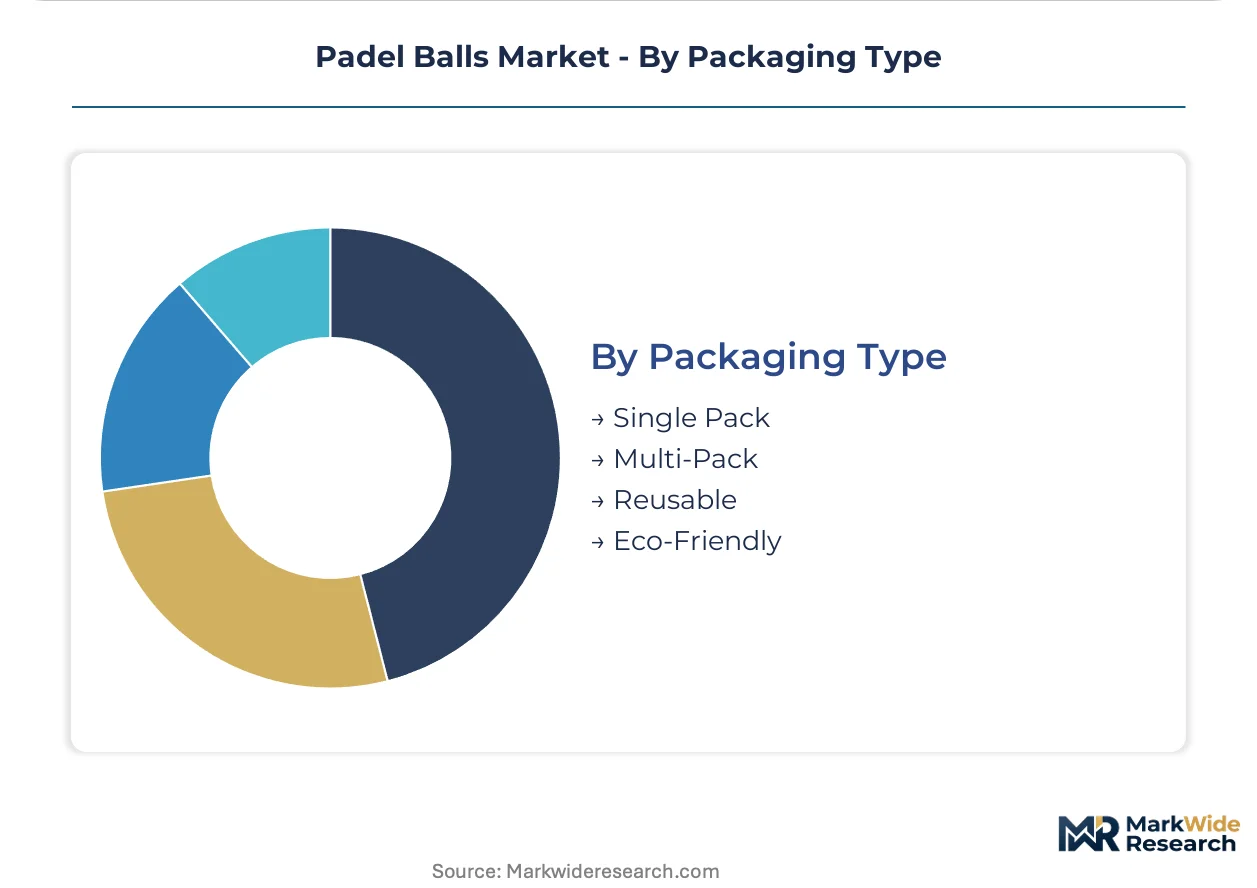
- Single Pack:Individual canisters serve replacement purchases and trial conversions, though unit economics compress margins.
- Multi-Pack:Bulk formats align with club procurement consolidation and reduced per-unit shipping costs.
- Reusable:Pressure-sealed containers extend ball shelf life and support premium positioning.
- Eco-Friendly:Recycled cardboard sleeves and bio-based materials satisfy municipal tender requirements in Spain and Italy, creating systematic exclusion risk for non-compliant suppliers.
Fastest regulatory tailwind: Eco-Friendly. Steepest volume: Multi-Pack.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Natural rubber harvesting clusters in Southeast Asia anchor raw material flows for European padel ball manufacturing, with latex processing facilities in Malaysia and Thailand supplying core molding compounds to specialized compounders across the continent.
Spain
Municipal infrastructure investments and competitive league standardization sustain the deepest institutional procurement volumes globally. The national sports federation enforces ball-pressure testing protocols that filter substandard imports from club supply chains. Madrid and Barcelona host centralized procurement committees at regional federation levels that consolidate multi-year framework agreements.
Germany
Club channel expansion and sustainability documentation requirements drive demand for ECHA-compliant additive formulations. The KBA-equivalent consumer safety office enforces pressure-labeling mandates that determine supplier access to premium procurement tiers. Industrial clusters in Bavaria and North Rhine-Westphalia concentrate testing facility investments from integrated manufacturers.
Italy
Public access court installations across Lombardy and Veneto generate recurring replacement cycles for budget-grade variants. Municipal tender requirements prioritize suppliers with EU Green Deal packaging compliance and bio-based felt certifications. The northern industrial corridor hosts compounders specializing in multi-source rubber blending for core molding applications.
Sweden
Court installation rates outpacing established supplier presence create channel expansion opportunities for compliant manufacturers. National procurement guidelines align with EU packaging waste directives favoring compressed bulk formats and recycled cardboard sleeves. Stockholm and Gothenburg municipal programs specify non-pressurized variants for recreational access initiatives.
France
Regulatory alignment with REACH chemical restrictions accelerates reformulation timelines for rubber additive substitution. The ANSM and national sports federation coordinate on emerging pressure-labeling standards that will reshape qualification criteria. The Île-de-France region concentrates retail distribution networks undergoing consolidation toward direct manufacturer relationships.
Padel Balls Market Competitive Landscape
Multi-source rubber procurement restructuring dominates the current landscape as manufacturers requalify core molding parameters to mitigate Southeast Asian latex volatility. The vendor base separates into integrated compounders with captive formulation capabilities and pure assemblers dependent on commodity inputs. Three archetypes occupy distinct positions: integrated manufacturers with testing facilities, regional specialists in club channel distribution, and scale-driven suppliers of standard-grade lines. Competitive moves concentrate on sustainability certification bundling and compressed packaging format development to satisfy municipal tender requirements.
Within the integrated manufacturing tier, HEAD and Babolat exemplify divergent geographic positioning strategies. HEAD leverages Austrian-based testing infrastructure to sustain quality consistency across pressurized product lines, while Babolat anchors Southern European club channel dominance through proximity to Spanish and Italian procurement committees. Wilson occupies a position on the technology-intensive vector, with its nomenclature suggesting specialization in performance engineering. These three manufacturers represent the consolidation pressure facing mid-tier suppliers lacking captive formulation or sustainability documentation capabilities.
| Leading Market Players |
|---|
| Babolat |
| DUNLOP |
| HEAD |
| Tretorn |
| NOX |
| Wilson |
| adidas |
| Franklin Sports |
| Bullpadel |
| Others |
Value Network & Pricing Analysis
Natural rubber latex from Southeast Asian plantations flows through Malaysian and Thai processing facilities into European core molding operations, with procurement concentration in Thailand and Vietnam transmitting volatility directly to pressurized ball cost structures and tier positioning downstream.
Pricing Analysis
Warranty bundling separates premium composite-core lines from unbundled budget variants, with extended pressure-retention guarantees commanding 15-20% unit premiums in Spanish and German club channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with ISO-rebound documentation and EU Green Deal compliance driving tier separation. Pricing pressure stems from REACH reformulation timelines compressing R&D cycles at mid-tier manufacturers. Amateur retail segments exhibit highest price sensitivity, while professional league procurement committees prioritize batch consistency over unit cost.
Supply Chain Analysis
Container freight rates from Port Klang and Laem Chabang to Rotterdam and Hamburg anchor landed cost calculations for rubber compound shipments. Supply concentrates in Thailand, Malaysia, and Vietnam for natural latex harvesting, with Indonesian plantations gaining share. Core molding draws from multi-source rubber blending, synthetic felt from European textile processors, and pressurization canisters from specialized metal forming suppliers. Single-source vulnerability persists in proprietary polymer formulations for pressure-retention composites. Distribution runs through direct manufacturer relationships with club procurement committees, displacing traditional retail distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive testing facilities and in-house formulation capabilities determine supplier survival against REACH-driven reformulation demands and sustainability documentation requirements.
For Market Incumbents: Deploy certification bundling as the primary defensive lever. Consolidate multi-year framework agreements with Spanish regional federation procurement committees to lock out mid-tier competitors lacking pressure-labeling transparency. Accelerate backward integration into bio-based felt supply chains to preempt EU Green Deal exclusion from municipal tenders. Counter emerging pure-assembler threats by restricting access to integrated testing infrastructure.
For New Entrants and Emerging Players: Begin with Nordic channel expansion where court installation rates outpace established supplier presence in Sweden and Norway. Target municipal recreational programs specifying non-pressurized variants with constrained replacement budgets. Pursue direct-to-club go-to-market positioning with compressed bulk packaging formats aligned with EU packaging waste directives.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier compounders with captive core molding capabilities but lacking sustainability documentation in Italy and Southern Germany. Long-term viability hinges on reformulation agility across the analysis window. Monitor REACH additive restriction announcements as inflection signals for consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Felt Supply | Secures EU Green Deal compliance for Spanish and Italian municipal tenders. |
| Captive Testing Facility Investment | Enables pressure-labeling transparency required by German KBA-equivalent protocols. |
| Multi-Source Rubber Procurement Restructuring | Mitigates Southeast Asian latex volatility affecting core molding cost structures. |
| Compressed Bulk Packaging Format Development | Aligns with EU packaging waste directives favoring reduced-format club procurement. |
| Direct Manufacturer-Club Relationship Building | Displaces retail distributors as procurement committees consolidate purchase volumes. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with padel ball manufacturing executives, club procurement officers, rubber compound procurement leads, and municipal sports facility directors. Secondary sources included Spanish national sports federation documentation, ECHA REACH substance restrictions, EU Green Deal packaging directives, and customs import records for rubber compound classifications. Bottom-up volume estimates triangulated against top-down market sizing from production capacity assessments.
Segment-level granularity modeled pressurized versus non-pressurized product categories, premium versus budget grade tiers, professional league versus amateur club end-use segments, and eco-friendly versus conventional packaging formats across the analysis window. CAGRs derived from regression analysis of historical court installation rates, ball replacement cycle frequencies, and procurement volume trends. Forecast inputs incorporated REACH reformulation timeline assumptions and municipal tender participation rates by supplier certification status.
Underlying measurement precision varies by segment; professional league procurement volumes carry tighter precision than amateur retail spot purchasing due to centralized committee documentation. Forecasts reflect assumptions about regulatory enforcement consistency and rubber supply disruption frequency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Wetsuits Market
Sports Equipment
Germany Horse Riding Equipment Market
Sports Equipment
Tetherball Market
Sports Equipment
Stadium Seating Market
Sports Equipment
Figure Skating Equipment Market
Sports Equipment
Power Sports Aftermarket Market
Sports Equipment
Sandbells Market
Sports Equipment
Global Sports Sunglasses Market
Sports Equipment
Sports and Athletic Insoles Market
Sports Equipment
Agility Ladders Market
Sports Equipment
Ankle Roll Guard Market
Sports Equipment
Squash Equipment Market
Sports Equipment
Gymnastic Hoops Market
Sports Equipment
Global Golf Accessories Market
Sports Equipment
Inflatable Sleds Market
Sports Equipment
Ergonomic Strap Systems Market