
 Ice Hockey Equipment Market | 2026-2036
Ice Hockey Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Hockey Equipment Market Intelligence
Modular equipment bundling is restructuring how parents and amateur leagues purchase starter kits, forcing brands to rethink SKU architecture and margin allocation. Bauer Hockey LLC leverages its vertical control over composite manufacturing to sustain price premiums across stick and skate lines. CCM Hockey anchors North American distribution through specialty retail partnerships, while True Temper Sports competes on material science leadership in lightweight shaft construction.
Ice hockey equipment encompasses protective and performance gear engineered to withstand puck impacts exceeding 100 mph while enabling agile skating maneuvers on frozen surfaces. Helmets incorporate multi-density foam liners and polycarbonate shells to manage rotational acceleration forces, while composite sticks layer carbon fiber and fiberglass to optimize flex profiles and shot velocity. Skates and sticks command the largest revenue pools among product types due to replacement frequency and technology turnover, whereas pads represent a mature segment with slower innovation cycles. The beginner skill level generates substantial volume through league-mandated starter packages, though professional-grade equipment sustains the highest per-unit margins.
FDA oversight applies to mouthguard materials classified as medical devices, while ISO 10256 governs international protective equipment standards for impact resistance and coverage zones. The EU's REACH regulation restricts certain chemical treatments in leather and foam components, compelling suppliers to reformulate pad interiors and glove palms. Stakeholders must monitor evolving concussion-protocol mandates from national sports federations, as stricter helmet certification requirements could accelerate replacement demand across all skill tiers.
Market Dynamics
Composite material substitution in stick and skate manufacturing is compressing replacement cycles while elevating performance thresholds across all skill tiers. This materials transition reshapes supplier relationships, certification requirements, and margin structures simultaneously.
Growth Catalysts
- REACH chemical compliance:The EU's REACH regulation mandates reformulation of leather treatments and foam additives in protective gear, accelerating R&D investment in synthetic alternatives across European manufacturing facilities.
- Youth league infrastructure:Municipal rink construction and school program expansion in Canada, the United States, and Sweden generates recurring equipment refresh demand through mandated starter kit procurement.
- Carbon fiber layering:Advanced composite weaving techniques enable variable flex profiles in stick shafts, allowing manufacturers to target specific shot mechanics and player biomechanics with precision-engineered products.
Market Restraints
- Petrochemical input volatility:Carbon fiber and epoxy resin prices fluctuate with crude oil markets, compressing margins on premium composite sticks and skates during supply disruptions.
- Asian manufacturing concentration:Protective pad production clusters in Chinese and Taiwanese facilities create vulnerability to shipping disruptions and tariff adjustments affecting North American inventory cycles.
- Helmet certification fragmentation:Divergent testing protocols between CSA (Canada), HECC (United States), and CE marking (Europe) force redundant certification investments for cross-border product lines.
Strategic Opportunities
- Indian subcontinent expansion:Ice hockey infrastructure investment in Ladakh and Gulmarg creates first-mover advantage for equipment brands establishing distribution partnerships in high-altitude cold-climate zones.
- Direct-to-team digital platforms:League and association bulk purchasing portals bypass traditional retail markup, capturing margin through volume commitments and customization services.
- Concussion protocol mandates:Stricter rotational acceleration standards from national sports federations in Canada and Sweden accelerate replacement demand for multi-density foam liner helmets across amateur tiers.
Industry Challenges
- Composite technician scarcity:Skilled laminators and mold operators for carbon fiber skate boot construction command premium wages, constraining production scaling for mid-tier manufacturers.
- ISO 10256 certification timelines:Impact testing and coverage zone validation for new protective gear designs extends product development cycles by 8-14 months before commercial launch.
- Legacy inventory reconciliation:Wood stick and leather skate remnants in distribution channels complicate product mix transitions and create price anchoring resistance among budget-conscious recreational players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Hockey Equipment Market |
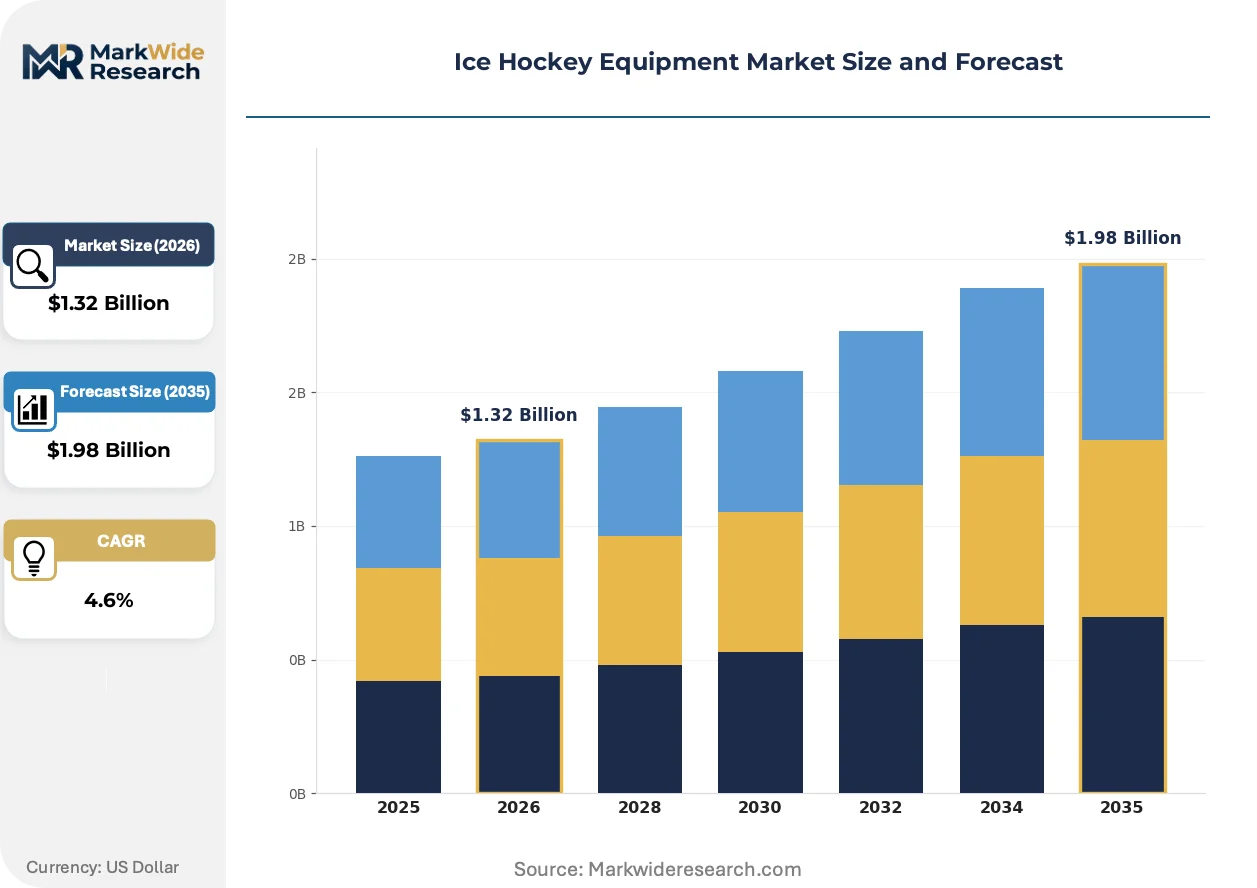
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $1.98 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skates, Sticks, Helmets, Pads Material: Composite, Aluminum, Foam, Leather Skill Level: Beginner, Intermediate, Advanced, Professional Distribution Channel: Online Retail, Specialty Stores, Mass Merchants, Direct Sales |
| Companies Covered | True Temper Sports, Graf Skates AG, Bauer Hockey LLC, Winnwell, Vaughn Hockey, CCM Hockey, Sher-Wood Hockey Inc., Brian’s Custom Sports, Warrior Sports Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Hockey Equipment Market Strategic Shifts & Innovations
Digital manufacturing integration and biometric customization are converging to transform how equipment is specified, produced, and fitted to individual athletes. These capabilities extend competitive differentiation beyond materials science into data-driven performance optimization.
3D foot scanning and automated last-matching is automating skate boot customization for elite and professional segments. NHL and NCAA programs now mandate digital fitting protocols, compressing traditional trial-and-error sizing from multiple store visits to single-session precision manufacture. This technology is automating the elimination of inventory carrying costs for specialty width and volume configurations previously stocked speculatively.
Health Canada's evolving helmet performance guidelines incorporate rotational acceleration metrics beyond linear impact testing, exceeding current HECC standards in the United States. Manufacturers serving Canadian amateur leagues must redesign liner geometries and retention systems to maintain market access. The youth and junior segments face accelerated replacement schedules as provincial hockey associations adopt these enhanced protocols ahead of federal mandate timelines.
Subscription-based equipment refresh programs are displacing outright purchase models in North American youth leagues. Parents pay monthly fees covering seasonal sizing exchanges and damage replacement, transferring obsolescence risk to manufacturers and retailers. This model concentrates most visibly in Minnesota, Ontario, and Alberta where league density supports logistics infrastructure for collection, refurbishment, and redistribution at scale.
Ice Hockey Equipment Market Segmentation
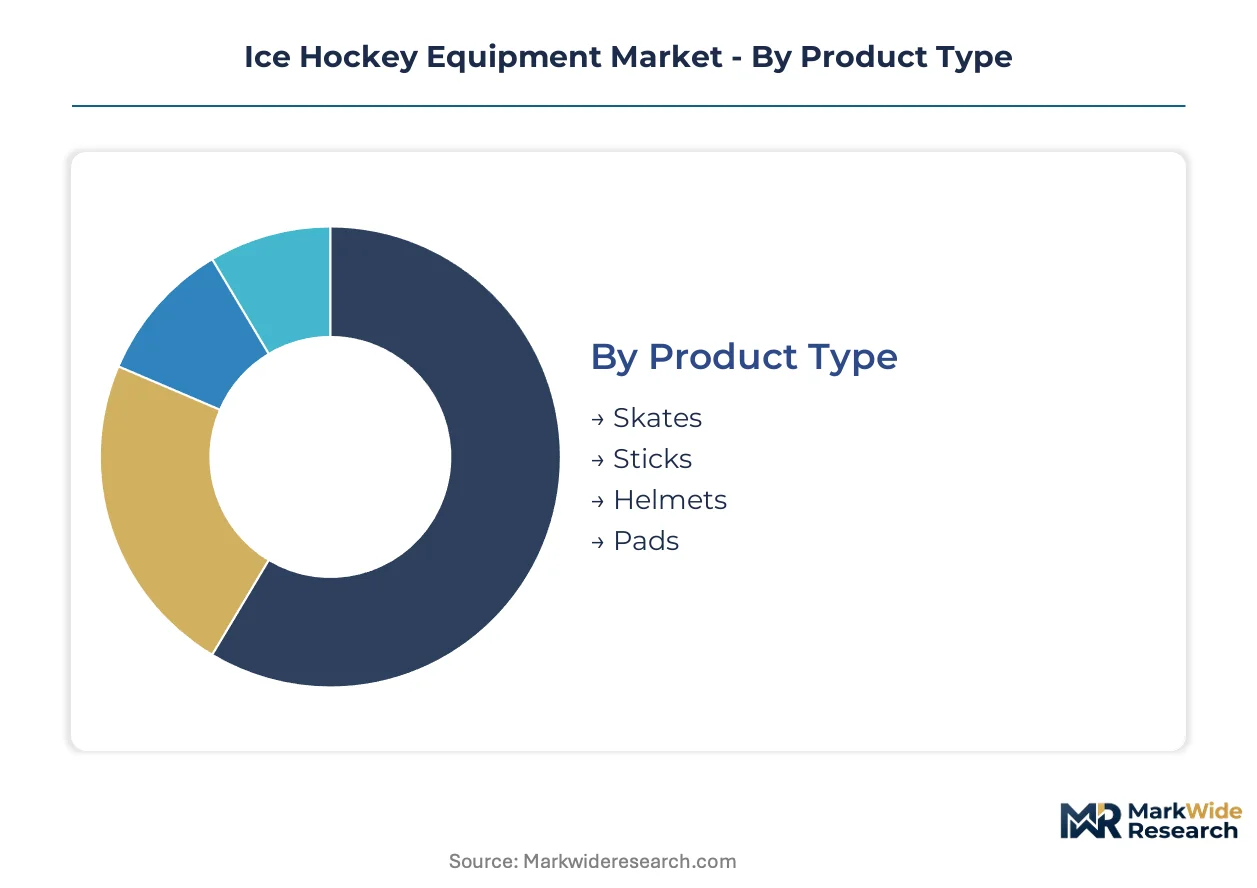
Equipment specification varies sharply across player development stages and competitive intensity. Manufacturers calibrate material selection, protective ratings, and price positioning to match distinct biomechanical demands and replacement cadences within each segment cluster.
Product Type:
Carbon fiber layering specifications and boot chassis geometries differentiate performance tiers across equipment categories.
- Skates:Thermoformable composite quarter panels and rigid carbon outsoles enable energy transfer optimization during stride mechanics. Demand clusters in Canadian junior leagues and Swedish elite programs where skate replacement cycles compress to 18-24 months under intensive ice exposure.
- Sticks:Variable flex profiles engineered through unidirectional carbon fiber layups target specific shot velocities and release points. North American youth leagues drive volume through seasonal breakage replacement, while professional procurement prioritizes custom curve and lie specifications.
- Helmets:Multi-density foam liners manage rotational acceleration forces per evolving certification standards.
- Pads:Thigh and chest protectors utilize closed-cell foam laminates for impact dispersion at lower velocity thresholds.
Mature deployment sits with Pads. Newer deployment is concentrated in Skates.
Material:
Raw material selection determines weight-to-strength ratios, certification compliance pathways, and supplier geography.
- Composite:Carbon fiber and fiberglass hybrid constructions dominate stick shafts and skate boots, enabling 30-40% weight reduction versus legacy alternatives. REACH-mandated resin reformulations are accelerating European manufacturing facility upgrades.
- Foam:Multi-density polyurethane and viscoelastic formulations absorb repetitive low-velocity impacts in helmet liners and protective pads. Health Canada rotational acceleration guidelines are forcing liner geometry redesigns.
- Aluminum:Shaft inserts and runner holders provide structural rigidity at mid-tier price points.
- Leather:Traditional skate boot uppers and glove palms face declining share under synthetic substitution pressure.
Volume concentration rests with Foam. Technology transition is accelerating fastest in Composite.
Skill Level:
Performance thresholds and replacement frequency scale with competitive intensity and organized league participation.
- Beginner:League-mandated starter kits bundle entry-level protective gear with standardized sizing. Municipal program expansion in Minnesota and Ontario generates recurring procurement cycles through seasonal enrollment waves.
- Professional:Custom-manufactured equipment with player-specific biomechanical mapping commands premium pricing. NHL and NCAA equipment managers coordinate direct manufacturer relationships bypassing retail markup.
- Intermediate:Players transitioning from recreational to competitive leagues upgrade protective ratings.
- Advanced:Elite amateur and junior leagues demand performance specifications approaching professional tiers.
Revenue margin peaks with Professional. Participant volume concentrates in Beginner.
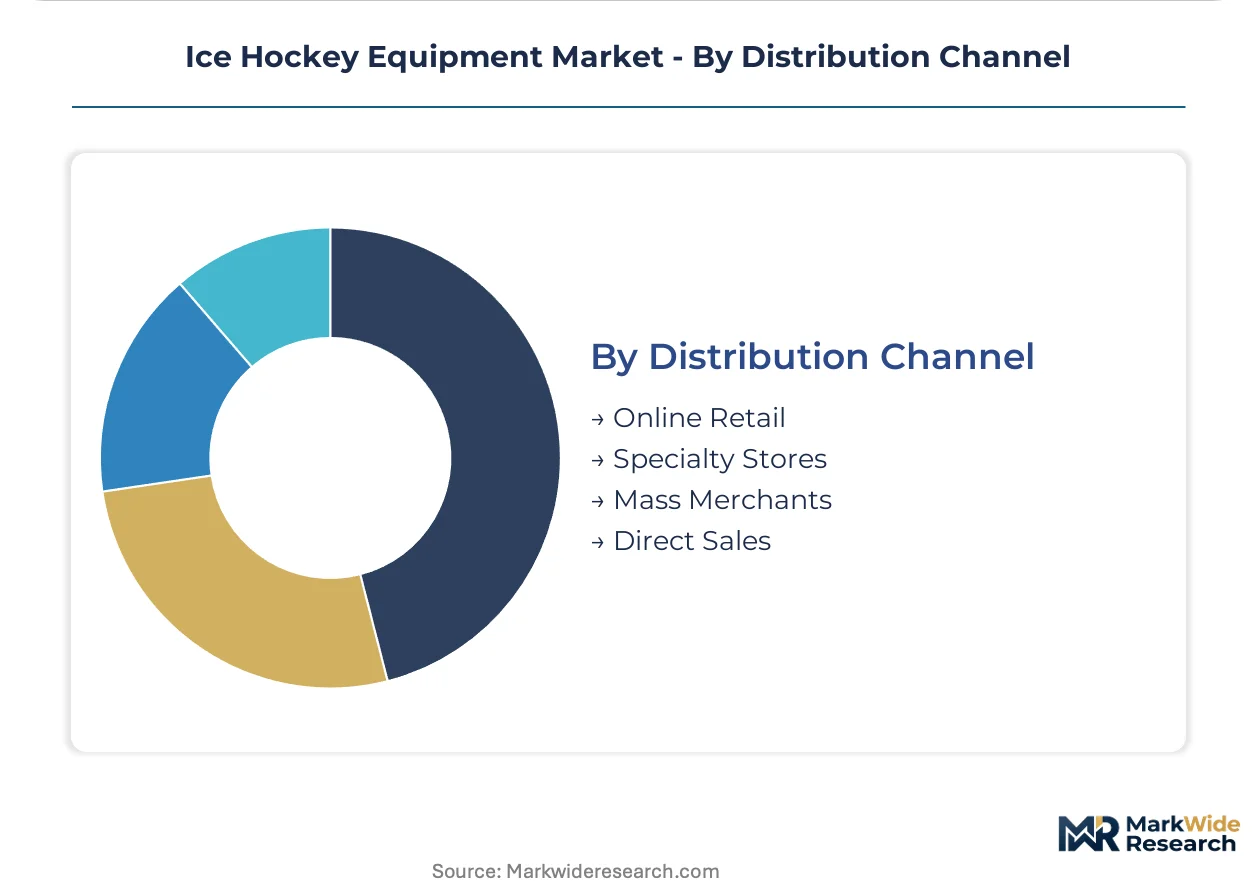
Distribution Channel:
Channel selection reflects purchase urgency, customization requirements, and league procurement structures.
- Specialty Stores:Fitting expertise and inventory depth for width variants and volume configurations sustain relevance despite digital encroachment. Canadian independent retailers maintain stronghold in skate heat-molding services.
- Online Retail:Direct-to-consumer platforms capture replacement stick and accessory purchases with standardized specifications. Subscription refresh programs in Alberta and Ontario route through proprietary digital portals.
- Mass Merchants:Entry-level protective gear and seasonal apparel reach recreational participants.
- Direct Sales:Team and association bulk purchasing bypasses retail intermediaries for volume commitments.
Service intensity differentiates Specialty Stores. Transaction velocity is climbing fastest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal rink construction tax credits in Minnesota and Ontario anchor equipment procurement concentration. Cold-climate access programs in Sweden and Finland sustain replacement demand. Emerging infrastructure investment in Ladakh creates new geographic expansion vectors.
United States
Minnesota's youth league density drives seasonal starter kit procurement through municipal program enrollment. USA Hockey's equipment safety mandates accelerate helmet replacement cycles across amateur tiers. Greater Boston's collegiate hockey concentration sustains direct-to-team equipment manager relationships.
Canada
Ontario and Alberta municipal rink subsidies compress equipment refresh timelines for beginner segments. Health Canada's rotational acceleration helmet guidelines exceed HECC standards, forcing liner redesigns. Montreal's specialty retail cluster maintains dominance in skate heat-molding services.
Sweden
Swedish Ice Hockey Association infrastructure grants expand junior league participation in Stockholm and Gothenburg. REACH chemical compliance mandates reformulate leather treatments in pad manufacturing. Malmö's composite materials research cluster advances carbon fiber weaving techniques for stick shafts.
Finland
Finnish Liiga development programs sustain elite amateur equipment specifications approaching professional tiers. National sports federation concussion protocols accelerate multi-density foam helmet adoption. Tampere's manufacturing facilities specialize in thermoformable skate boot quarter panels.
India
Ladakh and Gulmarg high-altitude ice hockey infrastructure investment creates first-mover distribution opportunities. The country's national sports regulator monitors protective equipment import standards for high-altitude cold-climate zones. Himalayan rink construction clusters concentrate equipment trial programs in Leh district.
Ice Hockey Equipment Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across equipment categories. The vendor base organizes around three strategic archetypes: vertically integrated composite manufacturers, specialty retail-anchored distributors, and material science-focused component suppliers. Consolidation pressure intensifies as carbon fiber layering capabilities concentrate among scaled producers. Dominant competitive moves include backward integration into resin formulation and direct-to-team digital platform deployment.
Within the vertically integrated tier, Bauer Hockey LLC and CCM Hockey represent scale-driven archetypes with captive manufacturing control. True Temper Sports exemplifies material science specialization through lightweight shaft construction expertise. Among European precision manufacturers, Graf Skates AG and Sher-Wood Hockey Inc. occupy positions emphasizing heritage craftsmanship and biomechanical fitting protocols. Warrior Sports Inc. anchors the performance-tier vector with composite-focused product development.
| Leading Market Players |
|---|
| True Temper Sports |
| Graf Skates AG |
| Bauer Hockey LLC |
| Winnwell |
| Vaughn Hockey |
| CCM Hockey |
| Sher-Wood Hockey Inc. |
| Brian's Custom Sports |
| Warrior Sports Inc. |
| Others |
Cost & Logistics Intelligence
Carbon fiber layering adoption in skate boot and stick shaft manufacturing simultaneously elevates unit production costs and concentrates supply among scaled composite processors with captive resin formulation capabilities. This materials transition forces mid-tier brands to absorb margin compression or cede share to vertically integrated leaders commanding thermoformable quarter panel and unidirectional layup expertise.
Pricing Analysis
Short lead time premiums dominate pricing architecture for custom curve sticks and thermoformed skates ordered through direct-to-team portals, while spot inventory of standardized youth starter kits trades at modest discounts. Three-tier pricing structure across premium, standard, and economy levels separates NHL-specification custom manufacturing from retail stock and municipal league bundles. Cost compression in mid-tier composite sticks is intensifying because epoxy resin and carbon fiber feedstock volatility erodes manufacturer margins. Recreational beginners exhibit highest price sensitivity, whereas professional equipment managers prioritize performance specifications over unit cost.
Supply Chain Analysis
Regional distribution centers in Minneapolis, Toronto, and Stockholm anchor hub-and-spoke patterns serving dense youth league clusters with compressed seasonal replenishment cycles. Manufacturing concentrates in China, Taiwan, and Finland, with thermoformable boot quarter panels and multi-density foam liners drawing from petrochemical and synthetic textile feedstocks. Single-source vulnerability sits with carbon fiber precursor supply from Asian facilities subject to shipping disruption. Distribution runs through specialty retail for fitting-intensive skates and direct digital portals for standardized stick replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as REACH-mandated reformulation investments and ISO 10256 certification timelines force sub-scale manufacturers toward exit or acquisition. Carbon fiber technician scarcity and redundant multi-jurisdictional helmet testing further disadvantage capital-constrained competitors.
For Market Incumbents: Hedge against petrochemical input volatility through backward integration into resin formulation or long-term offtake agreements with carbon fiber precursor suppliers. Secure specialty retail relationships in Montreal and Minneapolis to defend fitting-service differentiation against digital encroachment. Prioritize Health Canada rotational acceleration certification ahead of provincial mandate timelines to capture replacement demand. For New Entrants and Emerging Players: REACH in the European Union opens a window for synthetic leather and foam alternative suppliers to displace legacy pad and glove manufacturers dependent on reformulated chemical treatments. Target Ladakh and Gulmarg infrastructure investment through high-altitude cold-climate distribution partnerships with Himalayan rink operators. Pursue direct-to-team digital platform deployment in Alberta and Ontario subscription refresh programs. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified sporting goods conglomerates seeking composite manufacturing capabilities. Long-term viability favors scaled producers with captive carbon fiber weaving and thermoforming expertise over component assemblers. Watch Health Canada helmet guideline adoption velocity as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Captive epoxy supply insulates margin from petrochemical volatility affecting carbon fiber composite production. |
| Direct-to-Team Digital Platform Launch | Bypasses specialty retail markup in Minnesota and Ontario league procurement through bulk customization portals. |
| Health Canada Certification Pre-Positioning | Rotational acceleration liner redesign secures market access ahead of provincial mandate adoption. |
| Synthetic Material Substitution R&D | REACH-compliant foam and leather alternatives unlock European manufacturing continuity and margin recovery. |
| High-Altitude Distribution Partnership | Ladakh and Gulmarg first-mover positioning captures emerging cold-climate infrastructure investment. |
Research Approach
Independent corroboration across equipment manufacturer executives, specialty retail buyers, and municipal league procurement officers underwrites the qualitative findings in this study. Primary fieldwork with composite materials engineers, hockey association safety directors, and rink facility operators combined with secondary validation from customs trade data, national sports federation safety bulletins, and ISO certification registries. Bottom-up shipment analysis and top-down equipment spend estimates triangulate market sizing.
Rate-of-change decomposition across product type, material technology, skill tier, and distribution channel dimensions structures the analytical framework. CAGRs derive from replacement cycle modeling, enrollment trend extrapolation, and materials substitution velocity across the projection horizon. Modeled inputs include municipal rink construction tax credit utilization, REACH compliance cost pass-through assumptions, and concussion protocol mandate adoption curves.
Caveats apply where carbon fiber price volatility, shipping disruption severity, or regulatory timeline acceleration could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Kneeboard Market
Sports Equipment
Gym Bag Market
Sports Equipment
Inflatable Sleds Market
Sports Equipment
Gym Rubber Flooring Market
Sports Equipment
United States Running Gear Market
Sports Equipment
Basketball Gear Market
Sports Equipment
Global Sporting Goods Market
Sports Equipment
Football Equipment Market
Sports Equipment
Sports Mouthguard Market
Sports Equipment
UAE Horse Riding Equipment Market
Sports Equipment
Licensed Sports Merchandise Market
Sports Equipment
Rowing Boats Market
Sports Equipment
Global Golf Accessories Market
Sports Equipment
Squash Equipment Market
Sports Equipment
BMX Bikes Market
Sports Equipment
GCC Running Gear Market