
 Wave Windsurf Boards Market | 2026-2036
Wave Windsurf Boards Market Size, Share, and Industry Trends Forecast 2026-2036
Wave Windsurf Boards Market Analysis
Recreational surf schools and coastal rental fleets are pivoting toward higher-performance equipment as beginner-to-intermediate progression programs expand across European and Hawaiian coastlines. Starboard leverages in-house composite molding capabilities to control supply timelines for high-volume school contracts. Duotone anchors its position through deep ties to professional wave-riding circuits and athlete feedback loops. Goya differentiates via handcrafted construction methods that command premium positioning in specialty retail channels.
Wave windsurf boards are hydrodynamically optimized planing hulls, typically 65 to 95 liters in volume, constructed from sandwich composites of PVC foam core under epoxy resin with carbon or glass fiber reinforcement, designed to accelerate from displacement to planing mode in breaking swell. The Wave board type captures the performance apex of the category, where margin pools concentrate due to athlete endorsement dependencies and low production volumes. Composite material construction leads volume shipments for durability in rental and school abuse environments, while epoxy builds dominate the premium recreational tier where weight reduction justifies price escalation.
REACH regulation through ECHA governs chemical constituents in resin systems and core adhesives, pushing manufacturers toward lower-VOC formulations or imported compliance costs. CE marking requirements for watercraft safety create market access gates that favor established European producers with certification infrastructure already deployed. ISO 12217 small-craft stability standards influence hull design parameters that manufacturers must reconcile against pure performance objectives. Stakeholders should monitor evolving flammability and recycling mandates for composite watercraft as extended producer responsibility frameworks expand across coastal EU member states.
Market Dynamics
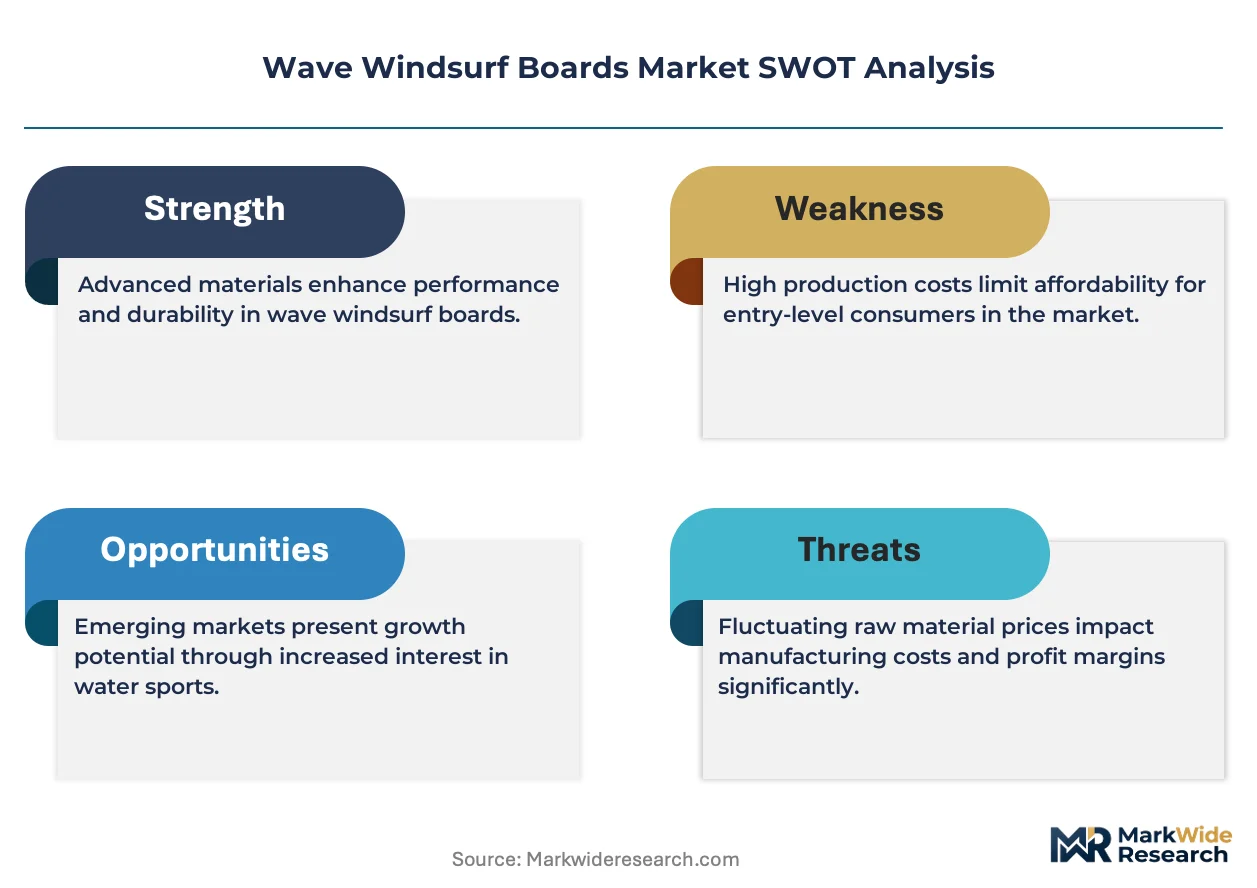
REACH chemical compliance mandates through ECHA are forcing epoxy resin reformulation across European manufacturing footprints, compressing margins for producers lacking in-house polymer chemistry capabilities while advantaging vertically integrated compounders.
Growth Catalysts
- Coastal tourism infrastructure:Wave-riding schools and rental fleets in Portugal's Nazaré-to-Peniche corridor are expanding equipment procurement volumes as destination tourism matures.
- Composite material durability:PVC foam core sandwich construction under epoxy resin systems withstands rental fleet abuse cycles, reducing total cost of ownership for commercial operators.
- CE marking harmonization:Watercraft safety certification infrastructure favors established producers with pre-deployed conformity assessment systems, accelerating market access timelines.
Market Restraints
- Epoxy resin input volatility:Petrochemical feedstock price swings for bisphenol-A and epichlorohydrin concentrate cost pressure on mid-tier manufacturers without captive resin supply.
- Carbon fiber supply concentration:Toray, SGL Carbon, and Hexcel control aerospace-grade fiber allocation, creating bottleneck risk for premium board layup schedules.
- Polyethylene terephthalate substitution:Inflatable wing foils and soft-top surf craft capture beginner recreational spend that previously flowed to hard-shell windsurf equipment.
Strategic Opportunities
- Extended producer responsibility frameworks:EU member state recycling mandates for composite watercraft create first-mover advantage for producers with closed-loop material recovery partnerships.
- Hydrofoil convergence:Wing-foil crossover designs integrating windsurf board architecture with mast and fuselage systems open adjacent revenue pools in coastal rental channels.
- Direct-to-school distribution:Bypassing specialty retail markup through bulk procurement contracts with municipal surf academies compresses customer acquisition cost.
Industry Challenges
- Composite laminator skill scarcity:Hand-layup craftsmanship for premium construction tiers resists automation, constraining output scaling at specialty manufacturers.
- ISO 12217 stability certification timelines:Small-craft seaworthiness testing protocols extend product development cycles by 8-14 months for new hull geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wave Windsurf Boards Market |
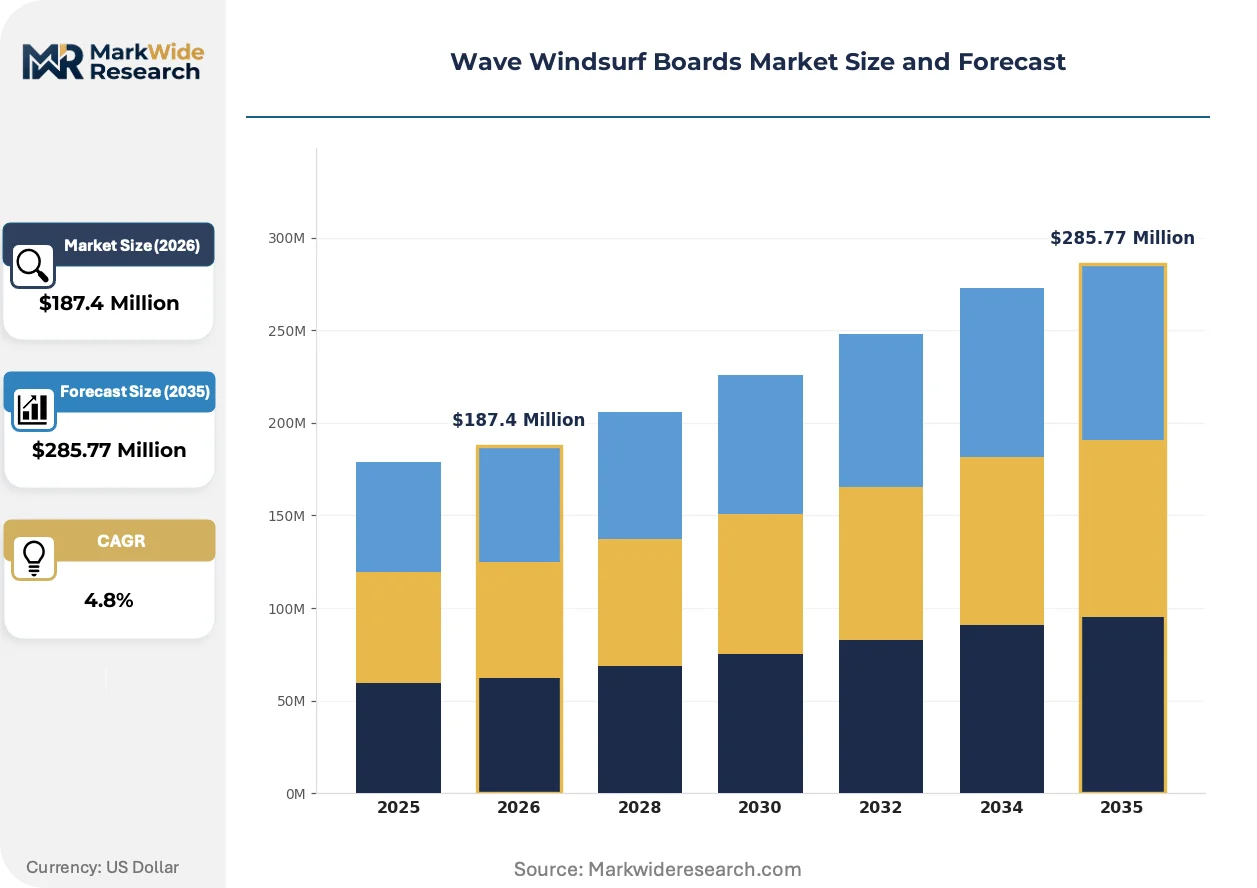
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Board Type: Freestyle, Slalom, Freeride, Wave Material: Epoxy, PVC, Wood, Composite Size: Small, Medium, Large, Extra Large End User: Recreational, Professional, Schools, Rentals |
| Companies Covered | Goya, Starboard, Duotone, Flikka, Severne, JP Australia, Patrik, Quatro, Tabou Boards, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wave Windsurf Boards Market Emerging Trajectories
Material science advances and regulatory chemistry mandates are compressing traditional construction hierarchies while hydrofoil integration opens adjacent equipment categories. These shifts are redrawing competitive boundaries between pure-play windsurf specialists and diversified watersports manufacturers.
Carbon fiber reinforcement is consolidating its position as the dominant high-performance layup material for athlete-tier boards. Professional wave-riding circuits and sponsored athletes specify carbon pre-preg construction for stiffness-to-weight ratios that glass fiber cannot match. This material tier consolidation is compressing mid-market positioning, forcing brands to choose between premium carbon builds and value-engineered glass configurations without viable intermediate offerings.
REACH Annex XVII restrictions on isocyanates and volatile organic compounds in adhesive systems are mandating water-based core bonding formulations across European production facilities. Manufacturers with integrated polymer laboratories are internalizing reformulation costs while smaller assemblers face imported compliance penalties or supplier dependency. Portuguese and French production clusters are most exposed given their concentration of mid-volume epoxy lamination shops.
Rental fleet operators are consolidating procurement decisions through multi-year framework agreements rather than seasonal spot purchasing. Coastal surf schools in Hawaii and Australia's Gold Coast are aggregating demand into centralized buying cooperatives that extract volume pricing and extended warranty terms. This buyer-side consolidation is compressing distributor margins and favoring manufacturers with direct institutional sales capabilities over specialty retail-dependent competitors.
Wave Windsurf Boards Market Segmentation
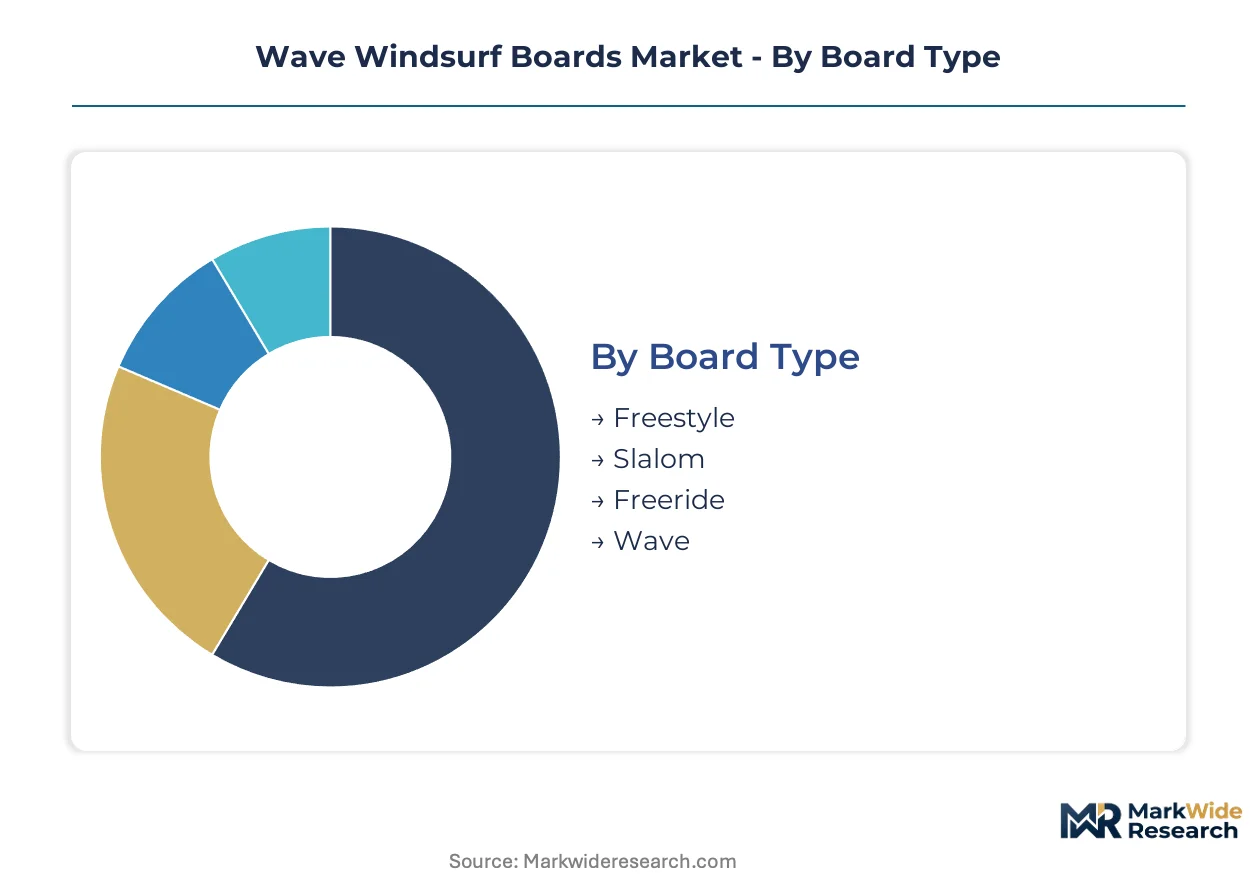
Wave windsurf board segmentation reflects divergent buyer priorities across performance tiers, construction durability requirements, and institutional procurement patterns. Manufacturers configure product lines around volume-to-weight ratios, material compliance costs, and fleet replacement cycles that vary sharply between rental operators and individual athletes.
Board Type:
Performance objectives and swell conditions separate buyers into distinct hull geometry preferences.
- Wave:Hydrodynamically optimized planing hulls, typically 65 to 95 liters in volume, accelerate from displacement to planing mode in breaking swell. Nazaré-to-Peniche corridor surf schools prioritize Wave boards for progression programs where students transition from rental fleets to personal equipment.
- Freestyle:Compact geometries with reinforced nose and tail sections withstand repeated aerial impact and rotation stresses. Flat-water lagoons in Brazil's Jericoacoara and Egypt's El Gouna concentrate demand where shallow, consistent wind enables trick-focused riding.
- Slalom:Narrow waterline beam and vee-bottom configurations maximize straight-line velocity in flat-water racing circuits.
- Freeride:Versatile rocker profiles balance early planing with maneuverability for recreational sailors across variable coastal wind regimes.
Wave leads volumes today; Freestyle is gaining share fastest.
Material:
Regulatory chemistry mandates and total cost of ownership calculations reshape procurement decisions across construction tiers.
- Composite:Sandwich laminates of PVC foam core under epoxy resin with carbon or glass fiber reinforcement dominate commercial fleet procurement. REACH Annex XVII compliance costs compress margins for assemblers without in-house polymer laboratories, favoring Portuguese and French producers with captive reformulation capabilities.
- Epoxy:Lower-VOC formulations satisfy ECHA mandates while delivering weight reduction that justifies price escalation in premium recreational tiers. Individual athletes and high-performance schools specify epoxy builds where gram savings translate to maneuverability gains.
- PVC:Closed-cell foam cores provide flotation and impact absorption in entry-level constructions.
- Wood:Natural fiber aesthetics and damping characteristics command positioning in specialty retail channels serving environmentally conscious buyers.
Composite leads volumes today; Epoxy climbs the fastest as regulatory deadlines tighten.
Size:
Sailor weight ranges and local wind strength distributions determine volume selection patterns.
- Small:Sub-75 liter configurations serve sub-70kg athletes and high-wind coastal zones where control supersedes flotation requirements.
- Medium:75-90 liter hulls capture the broadest recreational demand across Mediterranean and Hawaiian coastlines.
- Large:90-105 liter geometries enable heavier sailors to plane in marginal wind conditions common to Baltic Sea and North Sea summer sessions.
- Extra Large:105+ liter volumes support school instruction and rental fleet operations where student weight variance demands forgiving flotation margins.
Medium leads volumes today; Small expands most quickly as athlete-tier carbon construction concentrates in compact geometries.
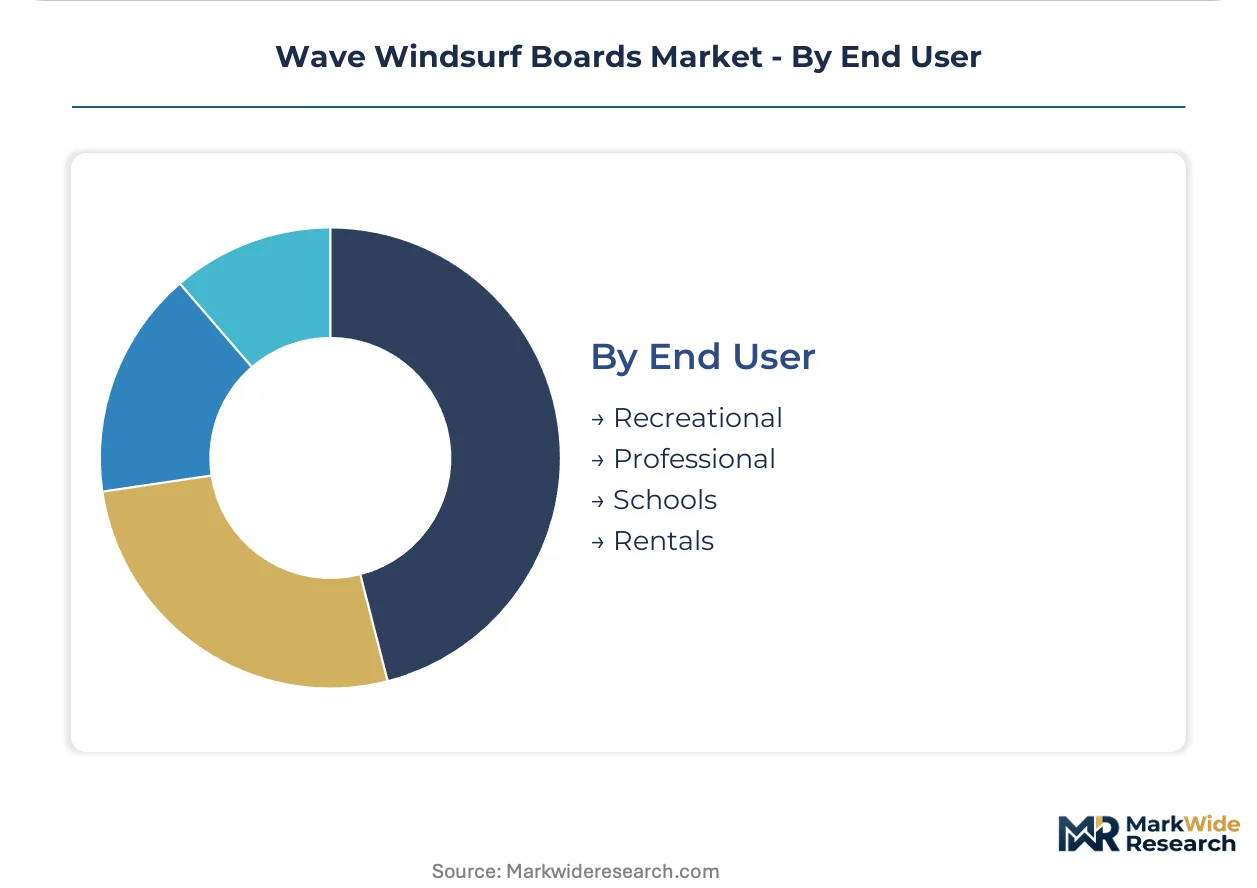
End User:
Procurement scale and replacement cycle length separate institutional buyers from individual purchasers.
- Rentals:Multi-year framework agreements aggregate demand through centralized buying cooperatives on Hawaii's Oahu and Australia's Gold Coast. Extended warranty terms and durability specifications outweigh upfront price in total cost of ownership calculations.
- Schools:Municipal surf academies in Portugal and France bypass specialty retail markup through direct manufacturer contracts. CE marking harmonization accelerates procurement timelines for established producers with pre-deployed conformity assessment systems.
- Recreational:Individual enthusiasts purchase through specialty retail channels where handcrafted construction methods command premium positioning.
- Professional:Sponsored athletes specify carbon pre-preg construction through feedback loops with wave-riding circuits.
Rentals lead volumes today; Schools show the steepest expansion trajectory as coastal tourism infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH chemical compliance mandates through ECHA are fragmenting manufacturing footprints across Europe, pushing production toward Portuguese and French facilities with captive polymer laboratories that internalize reformulation costs rather than absorbing imported compliance penalties.
Portugal
The Nazaré-to-Peniche corridor anchors European wave-riding tourism infrastructure, with surf schools expanding equipment procurement volumes as destination maturity accelerates. ECHA REACH Annex XVII restrictions on isocyanates concentrate compliance burdens on epoxy lamination shops concentrated in this coastal manufacturing cluster.
France
Municipal surf academies in Brittany and Landes bypass specialty retail markup through direct manufacturer contracts, aggregating demand into centralized procurement frameworks. CE marking harmonization for watercraft safety creates market access gates that favor established producers with pre-deployed conformity assessment systems in Atlantic coastal production zones.
Germany
Carbon fiber supply allocation from Toray and SGL Carbon flows through Bavarian and Baden-Württemberg distribution nodes, creating bottleneck risk for premium board layup schedules. The country's national chemical regulator enforces REACH lower-VOC formulation deadlines that compress margins for assemblers lacking in-house polymer chemistry capabilities.
Spain
Andalusian and Catalonian coastal tourism boards are expanding rental fleet procurement as Mediterranean destination infrastructure matures. Extended producer responsibility frameworks for composite watercraft recycling are creating first-mover advantage for producers with closed-loop material recovery partnerships in these manufacturing zones.
United States
Hawaiian Oahu surf schools aggregate demand through centralized buying cooperatives that extract volume pricing and extended warranty terms from manufacturers. EPA oversight of petrochemical feedstock emissions intersects with state-level coastal tourism subsidies that accelerate equipment procurement timelines for commercial operators.
Wave Windsurf Boards Market Vendor Landscape
Strategic partnerships dominate the current landscape as manufacturers seek to secure carbon fiber allocation and polymer chemistry capabilities without captive supply. The vendor base organizes around three tiers: vertically integrated compounders with in-house resin formulation, specialty assemblers dependent on external composite supply, and diversified watersports manufacturers leveraging cross-category distribution. Two competitive moves define current positioning: direct-to-school distribution bypassing retail markup, and hydrofoil convergence designs that open adjacent revenue pools in coastal rental channels.
Within the premium handcrafted tier, Goya and Quatro exemplify construction methods that command positioning in specialty retail channels serving individual enthusiasts. Starboard occupies a position among scale-driven fabricators leveraging composite molding capabilities to control supply timelines for high-volume school contracts. Duotone anchors the professional circuit vector through deep ties to athlete feedback loops and wave-riding sponsorship infrastructure.
| Leading Market Players |
|---|
| Goya |
| Starboard |
| Duotone |
| Flikka |
| Severne |
| JP Australia |
| Patrik |
| Quatro |
| Tabou Boards |
| Others |
Supply Flow & Price Mechanics
Composite laminator skill scarcity in Portugal's Nazaré-to-Peniche corridor widens labor-cost differentials between handcrafted premium tiers and molded commercial production, compressing mid-market positioning where neither craftsmanship premium nor scale efficiency applies.
Pricing Analysis
Distributor markup layers separate specialty retail channels from direct-to-school contracts, with three-tier pricing structure across premium, standard, and economy levels anchored by construction method and certification grade. Carbon pre-preg athlete-tier boards command brand premiums through sponsored athlete feedback loops, while rental fleet procurement extracts volume discounts that erode distributor margins. Price differentiation intensifies as REACH compliance costs concentrate on mid-tier epoxy assemblers without captive polymer laboratories. Commercial operators exhibit lowest price sensitivity where total cost of ownership calculations prioritize durability cycles over upfront spend.
Supply Chain Analysis
Refurbishment flows for rental fleet boards create secondary material recovery channels that extend composite component utilization before end-of-life processing. Raw material sourcing draws from German carbon fiber distribution nodes, Portuguese epoxy lamination clusters, and French PVC foam core suppliers. Bisphenol-A and epichlorohydrin petrochemical feedstocks hinge on volatile commodity markets that transmit cost swings through resin formulation tiers. Single-source vulnerability concentrates in aerospace-grade carbon fiber allocation controlled by Toray and SGL Carbon. Distribution runs through specialty watersports retail for individual enthusiasts and direct manufacturer contracts for institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Wave Windsurf Boards Market functions as a stable compounder where coastal tourism infrastructure investments generate recurring equipment replacement demand across mature destination corridors.
For Market Incumbents: Lock in carbon fiber supply allocation through long-term offtake agreements with Toray or SGL Carbon before aerospace demand tightens fiber availability. Deepen in-house polymer chemistry capabilities to internalize REACH reformulation costs that compress margins at dependent assemblers. Defend against inflatable wing foil substitution by accelerating hydrofoil convergence designs that capture crossover rental demand. For New Entrants and Emerging Players: Launch via direct-to-school distribution models that bypass specialty retail markup and extract volume pricing from municipal surf academies in Portugal and France. Target underpenetrated freestyle board demand in Brazil's Jericoacoara and Egypt's El Gouna where flat-water lagoon conditions concentrate trick-focused riding. White-space exists in closed-loop material recovery partnerships as extended producer responsibility frameworks expand. For Investors and Strategic Acquirers: Diversified watersports manufacturers with cross-category distribution infrastructure are the most active acquirer in this space, seeking composite molding capabilities and coastal rental channel relationships. Acquisition target archetypes include Portuguese mid-volume epoxy lamination shops with CE marking certification infrastructure already deployed. Monitor ECHA REACH enforcement intensity and carbon fiber allocation priority shifts as inflection indicators for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-School Distribution | Bypasses specialty retail markup and secures multi-year framework agreements with municipal surf academies. |
| Hydrofoil Convergence Design | Integrates windsurf board architecture with mast systems to capture wing-foil crossover rental demand. |
| In-House Polymer Laboratory Investment | Internalizes REACH Annex XVII reformulation costs that disadvantage dependent epoxy assemblers. |
| Closed-Loop Material Recovery Partnership | Creates first-mover advantage under EU extended producer responsibility mandates for composite watercraft. |
| Carbon Fiber Supply Agreement | Locks in aerospace-grade fiber allocation from Toray or SGL Carbon before demand tightening. |
Methodological Framework
Direct dialogue with surf school procurement directors, composite manufacturing plant managers, epoxy resin R&D leads, and specialty retail buyers combined with secondary validation from ECHA REACH substance databases, CE marking conformity records, and customs trade flow data. Bottom-up equipment shipment tallies from Portuguese and French production clusters triangulate against top-down coastal tourism expenditure estimates.
Segmentation outputs across board type, material construction tier, hull volume category, and end-user procurement mode feed into growth derivation over the projection horizon. Modeled inputs include REACH compliance cost trajectories, carbon fiber allocation priority shifts, and rental fleet replacement cycle patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt ECHA enforcement escalation or carbon fiber supply disruption scenarios. Practitioners should monitor coastal tourism subsidy program expansions and professional wave-riding circuit sponsorship commitments for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Volleyball Equipment Market
Sports Equipment
Racket Sports Equipment Market
Sports Equipment
Shooting Ranges Market
Sports Equipment
Stadium Seating Market
Sports Equipment
Windsurfing Equipment Market
Sports Equipment
Baseball Shoes Market
Sports Equipment
Golf Bags Market
Sports Equipment
Gymnastic Bars Market
Sports Equipment
Turbo Trainer Market
Sports Equipment
Windsurf Masts Market
Sports Equipment
US Sports Flooring Market
Sports Equipment
Asia-Pacific Kickboxing Equipment Market
Sports Equipment
Hunting Equipment and Accessories Market
Sports Equipment
One-Piece Carbon Fiber Badminton Racket Market
Sports Equipment
Cricket Ball Market
Sports Equipment
Sports Mouthguard Market