
 Soccer Gear Market | 2026-2036
Soccer Gear Market Size, Share, and Industry Trends Forecast 2026-2036
Soccer Gear Market Analytics
EU REACH chemical standards is broadening the addressable market for low-VOC synthetic leathers and water-based adhesives in soccer footwear manufacturing. Nike leverages its Flyknit precision-weaving R&D to sustain material efficiency advantages across European and North American supply chains. Adidas anchors its competitive position through backward integration into recycled ocean plastic yarn production for kit manufacturing. Puma differentiates via its proprietary evoKNIT compression-fit technology, which competes directly with traditional cut-and-sew construction methods.
Soccer gear encompasses protective, performance, and identification equipment designed for association football participation, including cleated footwear with stud configurations optimized for surface traction, moisture-wicking apparel engineered for thermoregulation during sustained exertion, and goalkeeping gloves incorporating latex foam palms for impact absorption and grip retention. Footwear commands the deepest margin pools due to biomechanical customization requirements and patent-protected soleplate architectures, while training equipment registers the fastest structural expansion as clubs professionalize youth development infrastructure. Synthetic materials displace leather across mid-tier price bands because polymer engineering delivers consistent batch performance and accelerated colorway cycling.
FIFA Equipment Regulations govern product certification for professional match use, while EU REACH restricts phthalate content in synthetic materials and California Proposition 65 mandates disclosure of chromium VI in leather tanning processes. These frameworks elevate compliance costs for smaller suppliers while creating certification barriers that favor established manufacturers with dedicated regulatory affairs functions. Stakeholders must monitor emerging extended producer responsibility mandates for textile waste recovery, as these will reshape post-consumer collection obligations and recycled content minimums across key sourcing jurisdictions.
Market Dynamics
EU REACH chemical standards are forcing a wholesale reformulation of synthetic leather and adhesive chemistries across soccer footwear supply chains, elevating compliance costs while opening premium positioning for certified low-VOC alternatives.
Growth Catalysts
- Grassroots Infrastructure Investment:Municipal governments in Brazil, Germany, and the United States are funding artificial turf installations and youth academy facilities, directly expanding addressable demand for training equipment and surface-specific cleat configurations.
- Recycled Polyester Mandates:Extended producer responsibility frameworks in the European Union are accelerating kit manufacturer adoption of ocean-recovered and post-consumer textile feedstocks.
- Biomechanical Customization:3D foot-scanning and stud-pattern optimization technologies are deepening average revenue per user in performance footwear segments.
Market Restraints
- Petrochemical Feedstock Volatility:Synthetic upper materials and TPU soleplates remain exposed to crude oil derivative price swings, compressing margin stability for mid-tier suppliers.
- Concentrated Latex Supply:Natural rubber latex for goalkeeper glove palms sources predominantly from Southeast Asian plantations, creating geographic concentration risk for grip-performance tiers.
- Chrome Tanning Disclosure Requirements:California Proposition 65 mandates on chromium VI are constraining leather sourcing flexibility and elevating documentation burdens.
Strategic Opportunities
- Underpenetrated Women's Segments:Brazil and the United States show significant white space in female-specific cleat lasts and protective gear sizing, with federation investment now accelerating.
- Wearable-Integrated Training Equipment:Convergence of GPS tracking vests with ball-striking sensors is creating new product categories for youth development programs.
- Direct-to-Club Distribution:Bypassing traditional retail through institutional procurement portals is capturing volume from professionalizing academy systems.
Industry Challenges
- Regulatory Affairs Talent Scarcity:Smaller suppliers struggle to hire specialists capable of navigating concurrent EU REACH, FIFA Equipment Regulations, and emerging textile waste recovery mandates.
- Certification Timeline Compression:FIFA's updated testing protocols for match-ball and equipment approval are extending product development cycles without corresponding pricing power recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soccer Gear Market |
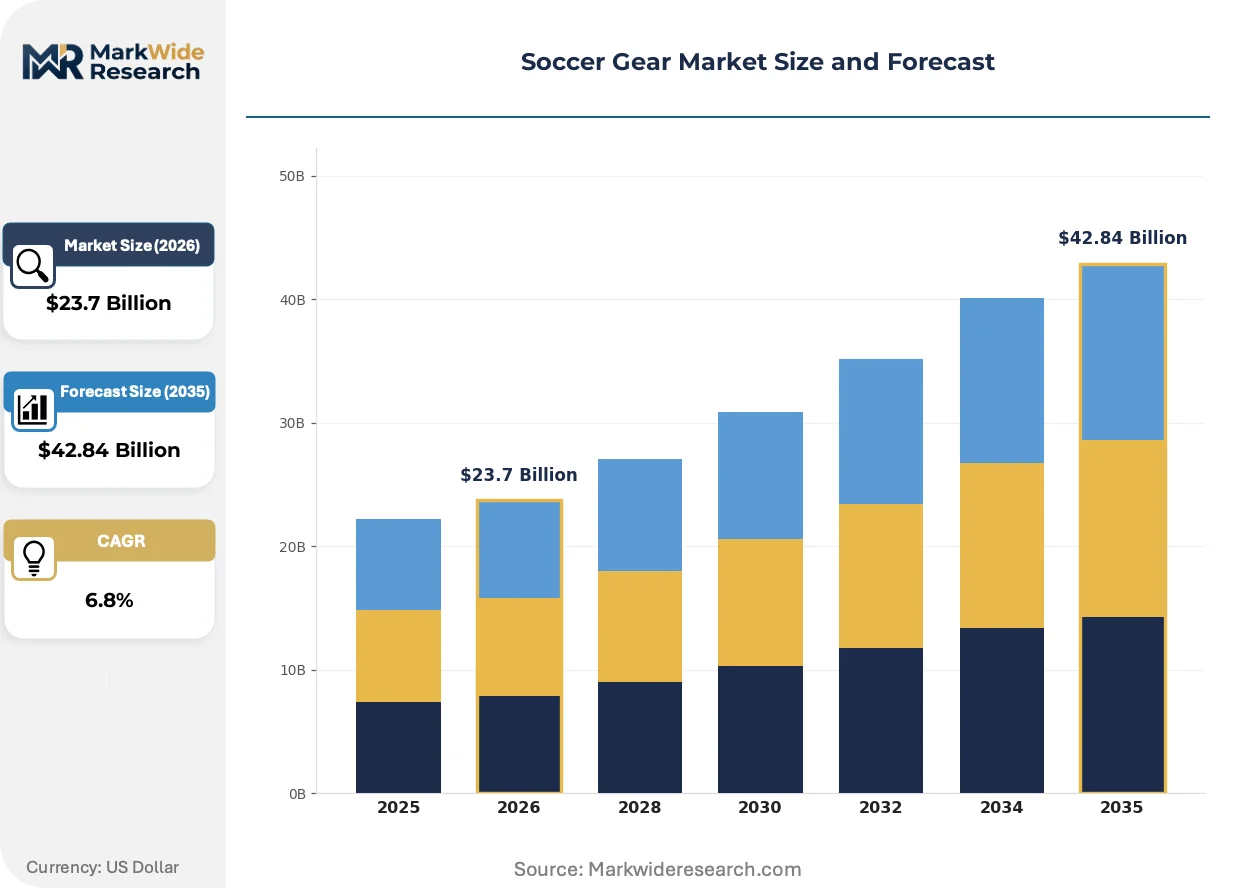
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Footwear, Apparel, Accessories, Training Equipment Material: Leather, Synthetic, Polyester, Rubber End User: Athletes, Coaches, Teams, Fans Distribution Channel: Online Retail, Sporting Goods Stores, Specialty Shops, Direct Sales |
| Companies Covered | New Balance, Joma, Nike, Under Armour, Kappa, Adidas, Macron, Umbro, Puma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soccer Gear Market Evolving Landscape
Material science breakthroughs and regulatory chemistry constraints are converging to reshape how soccer gear manufacturers formulate, certify, and distribute products across price tiers and geographies.
Precision-weaving technologies using recycled polymer yarns are electrifying upper construction methods in performance footwear. Elite clubs and national federations are specifying these materials in procurement contracts within eighteen-month adoption windows. This electrification is compressing batch-to-batch quality variation while enabling rapid colorway cycling that responds to club rebranding cycles.
EU REACH Annex XVII restrictions on phthalate plasticizers are forcing reformulation of synthetic leathers and PVC components across all imported soccer gear. Manufacturers with captive chemical R&D capabilities are internalizing compliance costs while externalizing certification documentation to smaller competitors. The footwear segment bears the heaviest burden, with suppliers accelerating water-based adhesive substitution programs.
Institutional procurement by youth academies and professional clubs is consolidating buying power away from traditional retail channels. Team equipment managers now negotiate multi-year kit and training gear contracts directly with manufacturers, displacing distributor margins. Germany and Brazil exhibit the most advanced channel migration, with academy systems centralizing specification authority at the federation level.
Soccer Gear Market Segmentation
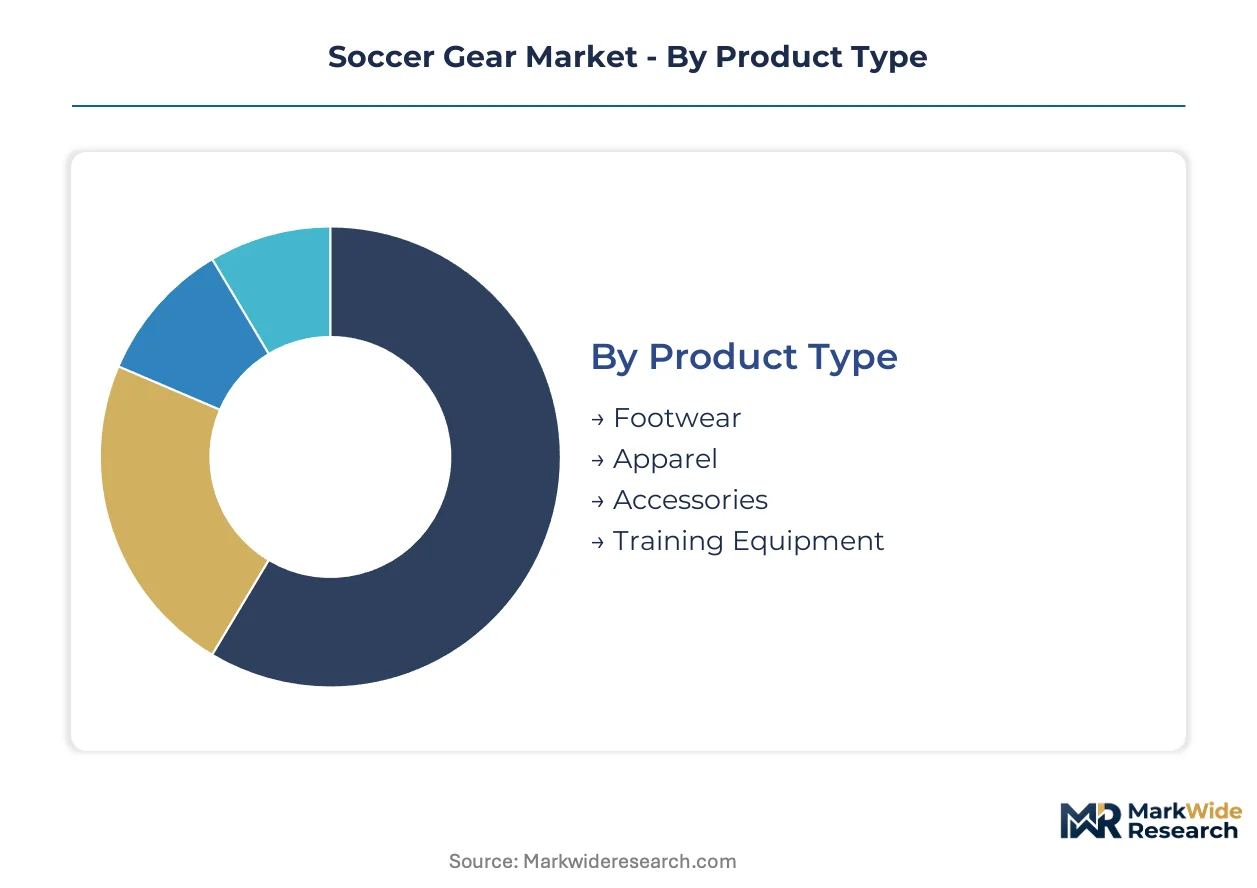
Soccer gear segmentation reveals how certification requirements, surface specifications, and procurement authority concentrate value across distinct product tiers. Manufacturers configure R&D investments and supply chain partnerships around the compliance burdens and margin profiles inherent to each category.
Product Type:
FIFA Equipment Regulations impose tiered certification timelines across product categories, with match-ball and footwear protocols demanding the most extensive laboratory validation cycles.
- Footwear:Biomechanical customization requirements and patent-protected soleplate architectures command the deepest margin pools. Demand concentrates in Brazil and Germany as municipal artificial turf installations accelerate surface-specific cleat configurations.
- Training Equipment:GPS tracking vests converging with ball-striking sensors create new product categories for youth development programs. Clubs in the United States professionalizing academy infrastructure drive the steepest expansion trajectory.
- Apparel:Moisture-wicking fabrics engineered for thermoregulation during sustained exertion.
- Accessories:Protective and identification equipment including shin guards and captain armbands.
Leading the category by volume: Footwear. Growing fastest: Training Equipment.
Material:
EU REACH Annex XVII restrictions on phthalate plasticizers and chromium VI disclosure mandates in California segment material strategies by regulatory exposure.
- Synthetic:Polymer engineering delivers consistent batch performance and accelerated colorway cycling across mid-tier price bands. EU REACH compliance costs favor manufacturers with captive chemical R&D capabilities.
- Leather:Natural hide materials face constrained sourcing flexibility from California Proposition 65 chromium VI documentation burdens. Premium positioning persists in heritage-focused European markets.
- Polyester:Recycled ocean plastic and post-consumer textile feedstocks mandated by extended producer responsibility frameworks.
- Rubber:Natural latex for goalkeeper glove palms sources predominantly from Southeast Asian plantations.
Synthetic materials dominate volume share. Recycled polyester feedstocks climb fastest as kit manufacturer mandates tighten.
End User:
Procurement authority and specification control vary sharply across user types, from individual biomechanical fitting to institutional multi-year contracts.
- Teams:Youth academies and professional clubs centralize buying power through direct manufacturer negotiations, displacing traditional retail channels. Federation-level specification authority in Germany and Brazil accelerates channel migration.
- Athletes:Individual players drive demand for 3D foot-scanning and stud-pattern optimization technologies.
- Coaches:Training curriculum requirements shape equipment specifications for development programs.
- Fans:Replica kit and merchandise demand follows club performance and rebranding cycles.
Teams command the largest procurement volume. Athletes generate the fastest technology adoption curve.
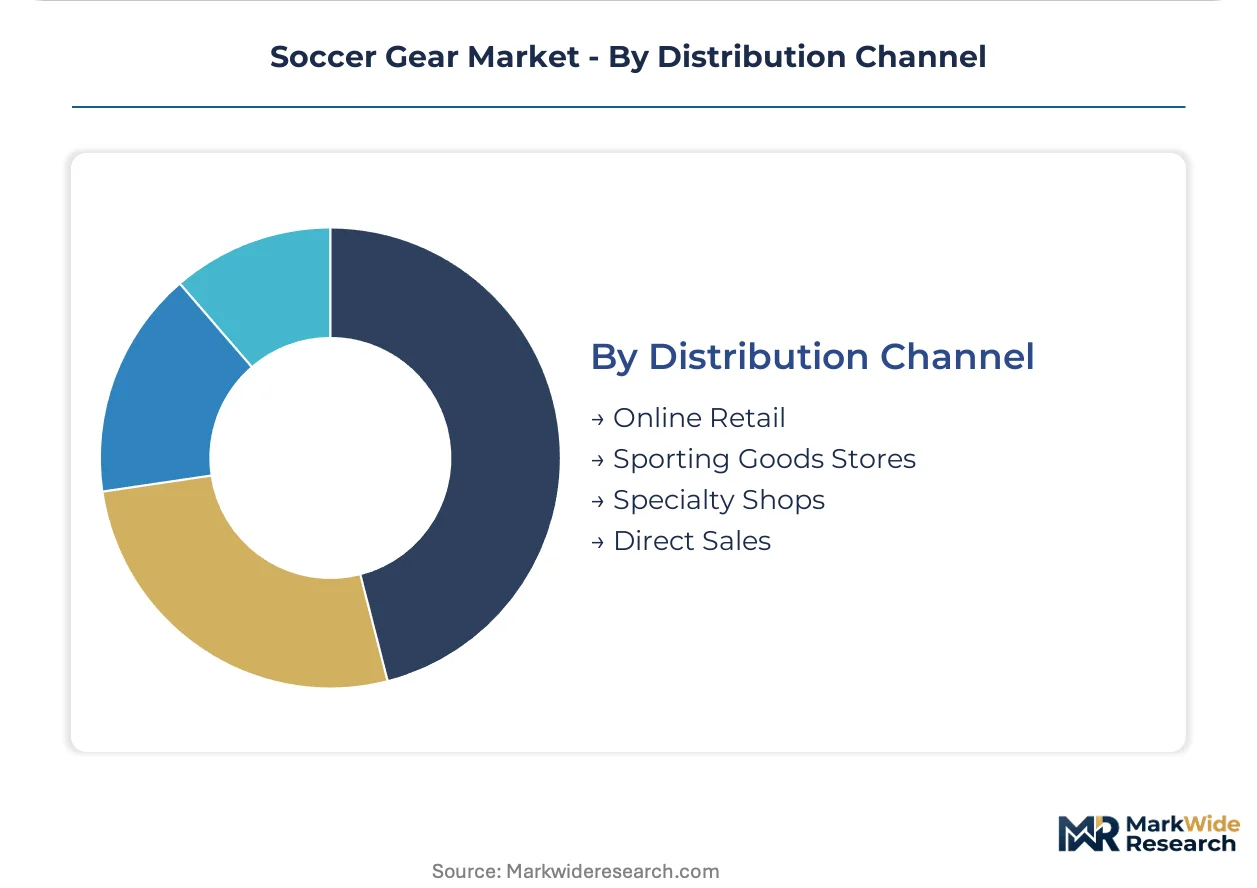
Distribution Channel:
Channel economics fragment according to institutional procurement sophistication and consumer preference for fitting services.
- Direct Sales:Multi-year kit and training gear contracts negotiated directly between team equipment managers and manufacturers capture volume from professionalizing academy systems. Germany exhibits the most advanced channel migration.
- Online Retail:E-commerce platforms serve fan merchandise and replacement equipment demand with rapid colorway cycling.
- Sporting Goods Stores:Big-box retailers maintain footwear fitting services and inventory breadth for recreational players.
- Specialty Shops:Independent retailers focus on elite player customization and local club relationships.
Direct Sales leads volume growth. Online Retail expands most quickly in fan segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Asia-Pacific while consumption concentrates in Western Europe and the Americas. Brazil, Germany, and the United States generate the steepest demand trajectories as municipal investment in artificial turf and youth academies accelerates.
United States
Municipal governments in Texas and California are funding artificial turf installations at youth academy facilities. The EPA oversees chemical safety in synthetic materials under TSCA while state-level disclosure mandates elevate compliance burdens. Greater Los Angeles hosts equipment distributors negotiating direct-to-club contracts with professionalizing academy systems.
Germany
Federation-level specification authority centralizes procurement for youth academies across Bavaria and North Rhine-Westphalia. ECHA enforces REACH Annex XVII restrictions on phthalate plasticizers in synthetic footwear components. The Munich-Düsseldorf corridor anchors kit manufacturer R&D facilities advancing recycled polyester feedstock integration.
Brazil
Grassroots club professionalization drives demand for surface-specific cleat configurations and GPS-integrated training vests. ANVISA regulates chemical content in imported sporting goods under national health surveillance protocols. São Paulo state concentrates manufacturer distribution hubs serving southeast regional academy networks.
China
Domestic consumption of performance footwear expands through tier-one city youth leagues while export manufacturing dominates global supply. SAMR enforces GB standards for product safety and labeling compliance. The Pearl River Delta hosts precision-weaving facilities supplying recycled polymer yarns to European kit manufacturers.
United Kingdom
Premier League academy investment filters into grassroots infrastructure upgrades across Greater London and the Midlands. The Health and Safety Executive coordinates with FIFA Equipment Regulations for match-ball certification protocols. Manchester and Liverpool anchor specialty retail clusters serving elite player customization demand.
Soccer Gear Market Competitive Landscape
The competitive structure tilts toward integrated sportswear conglomerates with captive chemical R&D and direct-to-club distribution capabilities. Mid-tier specialists survive through regional federation partnerships and rapid colorway cycling for replica markets. Three archetypes dominate: vertically integrated multinationals controlling recycled feedstock supply, biomechanical customization specialists leveraging 3D scanning technology, and private-label assemblers serving price-sensitive grassroots segments. Capacity expansion in Southeast Asian manufacturing and strategic partnerships with municipal academy systems represent the dominant competitive moves.
Among North American and European sportswear conglomerates, Nike, Adidas, and Puma occupy positions defined by material science investment and federation-level procurement relationships. Nike exemplifies the precision-weaving technology archetype through its Flyknit R&D infrastructure. Adidas represents backward integration into recycled ocean plastic yarn production. Puma sits within the compression-fit innovation tier competing with traditional cut-and-sew construction methods.
| Leading Market Players |
|---|
| New Balance |
| Joma |
| Nike |
| Under Armour |
| Kappa |
| Adidas |
| Macron |
| Umbro |
| Puma |
| Others |
Value Network & Pricing Analysis
EU REACH Annex XVII phthalate restrictions gate qualified supply for certified low-VOC synthetic leathers while elevating premium-tier pricing access for manufacturers with captive chemical R&D capabilities. Federation-level procurement contracts in Germany and Brazil concentrate buying power, compressing distributor margins and rewarding direct-to-club distribution scale.
Pricing Analysis
Biomechanical customization outcomes anchor value-based pricing in performance footwear tiers, with 3D foot-scanning and stud-pattern optimization commanding sustained premiums. Three-tier pricing structure across premium, standard, and economy levels separates FIFA-certified match gear from training-grade equipment and recreational entry points. Cost compression in mid-tier synthetic uppers intensifies because petrochemical feedstock volatility erodes margin stability. Grassroots clubs and municipal academies exhibit acute price sensitivity, while elite professional teams prioritize performance certification over unit cost.
Supply Chain Analysis
Skilled technician availability constraints in Vietnam and Indonesia shape precision-weaving capacity expansion timelines for recycled polymer yarn production. Manufacturing concentrates in China, Vietnam, and Bangladesh, with the Pearl River Delta hosting critical synthetic upper and precision-knit facilities. Raw material flows draw from Southeast Asian natural rubber plantations for goalkeeper glove latex, Middle Eastern petrochemical complexes for TPU soleplates, and European recycled polyester feedstock operations for kit manufacturing. Single-source vulnerability in Thai and Malaysian latex supply elevates geographic concentration risk for grip-performance tiers. Distribution runs through direct-to-club institutional portals in Germany and Brazil, bypassing traditional retail for professionalizing academy systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified chemical R&D talent scarcity props pricing power for compliant synthetic material suppliers, constraining rapid capacity expansion across mid-tier footwear manufacturers.
For Market Incumbents: Cement federation-level procurement relationships in Brazil and Germany through multi-year kit and training equipment contracts that displace distributor intermediaries. Accelerate backward integration into recycled ocean plastic yarn production to secure feedstock access as extended producer responsibility mandates tighten across European sourcing jurisdictions. Regulatory affairs capability gaps among smaller competitors create defensive moats for established players with dedicated compliance functions. For New Entrants and Emerging Players: Capture white space in female-specific cleat lasts and protective gear sizing across Brazil and the United States, where federation investment accelerates but product development lags male-equivalent depth. Target wearable-integrated training equipment segments combining GPS tracking vests with ball-striking sensors for youth development programs professionalizing in Texas and California. A direct-to-academy go-to-market approach bypasses entrenched retail relationships that favor incumbents. For Investors and Strategic Acquirers: FIFA Equipment Regulations timeline compression extending product development cycles without corresponding pricing power recovery is the leading indicator that consolidation pressure will intensify for mid-tier suppliers lacking captive R&D infrastructure. Long-term viability across the analysis window favors vertically integrated manufacturers controlling recycled feedstock supply and biomechanical customization technology. Acquisition target archetype: regional specialists with federation procurement relationships and rapid colorway cycling capabilities for replica markets. Federation-level specification authority centralization in Germany signals inflection toward institutional channel dominance.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Feedstock | Secures ocean-recovered polyester supply as EU extended producer responsibility mandates tighten kit manufacturer compliance. |
| Biomechanical Customization Technology Investment | Deepens average revenue per user through 3D foot-scanning and stud-pattern optimization for elite athlete segments. |
| Direct-to-Club Distribution Portal Development | Captures volume from professionalizing academy systems in Germany and Brazil while displacing traditional retail margins. |
| Regulatory Affairs Capability Buildout | Navigates concurrent EU REACH, FIFA Equipment Regulations, and emerging textile waste recovery mandates that strain smaller competitors. |
| Women's Segment Product Line Expansion | Addresses underpenetrated female-specific cleat lasts and protective gear sizing in Brazil and United States federation investment zones. |
Research Methodology
Independent corroboration across federation procurement officers, youth academy equipment managers, synthetic material R&D directors, and sporting goods distributors underwrites the qualitative findings in this study. Primary interviews with regulatory affairs specialists at major kit manufacturers, chemical compliance consultants, and institutional buyers in Germany and Brazil combined with secondary validation from FIFA Equipment Regulations documentation, ECHA REACH Annex XVII filings, and municipal artificial turf investment records. Bottom-up demand modeling across footwear, training equipment, apparel, and accessories segments triangulated with top-down market sizing from customs trade data and federation procurement disclosures.
Rate-of-change decomposition across product type, material composition, end user procurement authority, and distribution channel structure anchors the analytical framework over the projection horizon. Segmentation dimensions modeled include certification tier, surface specification, biomechanical customization level, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating municipal infrastructure investment trajectories, recycled content mandate compliance timelines, and youth academy professionalization rates. Industry-specific forecast inputs encompass artificial turf installation permits in Texas and California, EU textile waste recovery policy development, and Southeast Asian natural rubber plantation yield projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical feedstock price volatility, FIFA certification protocol revisions, and federation procurement centralization pace. Forecasts reflect documented assumptions regarding municipal budget allocation continuity, REACH enforcement intensity, and academy system professionalization trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Street Skateboards Accessories Market
Sports Equipment
Equestrian Equipment Market
Sports Equipment
Kiteboarding Equipment Market
Sports Equipment
Gym Bag Market
Sports Equipment
Cricket Ball Market
Sports Equipment
Shuffleboard Equipment Market
Sports Equipment
Crampon Market
Sports Equipment
Global Weighted Hula Hoop Market
Sports Equipment
Ice Hockey Stick Market
Sports Equipment
Rubber Fitness Flooring Market
Sports Equipment
PE Sports Turf Market
Sports Equipment
Playground Sets and Equipment Market
Sports Equipment
United States Running Gear Market
Sports Equipment
Soccer Cleats Market
Sports Equipment
Global Golf Rangefinders Market
Sports Equipment
Sports Flooring Market