
 North America Home Fitness Equipment Market | 2026-2036
North America Home Fitness Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Home Fitness Equipment Market Analytics
The EPA ENERGY STAR specification revision for consumer exercise equipment is hardening efficiency benchmarks across the industry. Peloton Interactive navigates this shift through captive supply chain investments in low-draw motor technology. Johnson Health Tech leverages its Taiwan-based manufacturing footprint to sustain cost advantages in manual machine categories. Core Health & Fitness specializes in commercial-grade components repurposed for residential durability standards.
North America home fitness equipment encompasses motorized and non-motorized apparatus designed for cardiovascular, resistance, and flexibility training within residential settings, typically featuring steel alloy frames, polymer-coated weight stacks, and belt-drive or magnetic resistance systems producing torque outputs between 150 and 500 watts. Treadmills and stationary bikes anchor the product type hierarchy, with smart equipment variants commanding margin premiums through subscription-locked software ecosystems. Connected devices within the technology dimension are displacing manual machines in metropolitan markets where digital coaching integration drives replacement cycles.
The Consumer Product Safety Commission enforces mechanical stability and pinch-point standards, while FCC certification governs wireless connectivity protocols in smart equipment, and California's Title 20 appliance efficiency regulations create a de facto baseline that manufacturers adopt across North American production runs. Health Canada and the EPA coordinate on electromagnetic emissions testing for connected fitness devices crossing the border. Stakeholders must weigh subscription revenue durability against hardware margin compression as the installed base of smart equipment matures and replacement intervals lengthen.
Market Dynamics
Remote work permanence in suburban Texas and Florida households is compressing replacement cycles for connected cardio equipment, while EPA energy efficiency mandates force motor system redesigns across the supply base.
Growth Catalysts
- EPA ENERGY STAR specification revision:The updated efficiency benchmarks for consumer exercise equipment are accelerating R&D investment in low-draw motor architectures. Manufacturers must redesign power systems to maintain market access.
- Migration-driven housing growth:Dense pockets of first-time home gym purchasers are forming in Texas and Florida metropolitan corridors. These buyers lack existing equipment and demonstrate higher willingness-to-pay for connected systems.
- Steel alloy frame durability standards:Commercial-grade component repurposing for residential use is extending product lifespans and justifying premium positioning. Core Health & Fitness and similar specialists leverage this materials evolution.
Market Restraints
- Rare earth magnet supply concentration:Belt-drive and magnetic resistance systems depend on neodymium sourcing concentrated in Chinese processing facilities. Tariff exposure and supply quota volatility compress margin predictability.
- FCC certification timeline friction:Wireless connectivity protocol approval for smart equipment averages 14-18 months. This regulatory lag delays product launches and truncates revenue recognition windows.
- Commercial gym substitution threat:Post-pandemic boutique fitness chain expansion in suburban markets siphons discretionary spending from residential equipment budgets. Orangetheory and similar operators target the same demographic profile.
Strategic Opportunities
- California Title 20 appliance efficiency regulations:The de facto baseline that manufacturers adopt across North American production runs creates compliance economies of scale. Early alignment with California Air Resources Board thresholds opens streamlined multi-state distribution.
- Health Canada electromagnetic emissions coordination:Cross-border testing harmonization with the EPA reduces certification duplication for connected devices. This regulatory convergence lowers market entry costs for US manufacturers.
- Subscription-locked software ecosystems:Digital coaching integration is displacing manual machines in metropolitan markets. Margin premiums from recurring revenue models offset hardware compression pressures.
Industry Challenges
- Embedded systems firmware talent scarcity:Smart equipment development requires specialized expertise in real-time operating systems and IoT security protocols. Compensation inflation in this function is elevating R&D overhead.
- Consumer Product Safety Commission mechanical stability testing:Pinch-point and structural integrity certification demands extended validation cycles. Product liability exposure necessitates conservative design margins that constrain innovation velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Home Fitness Equipment Market |
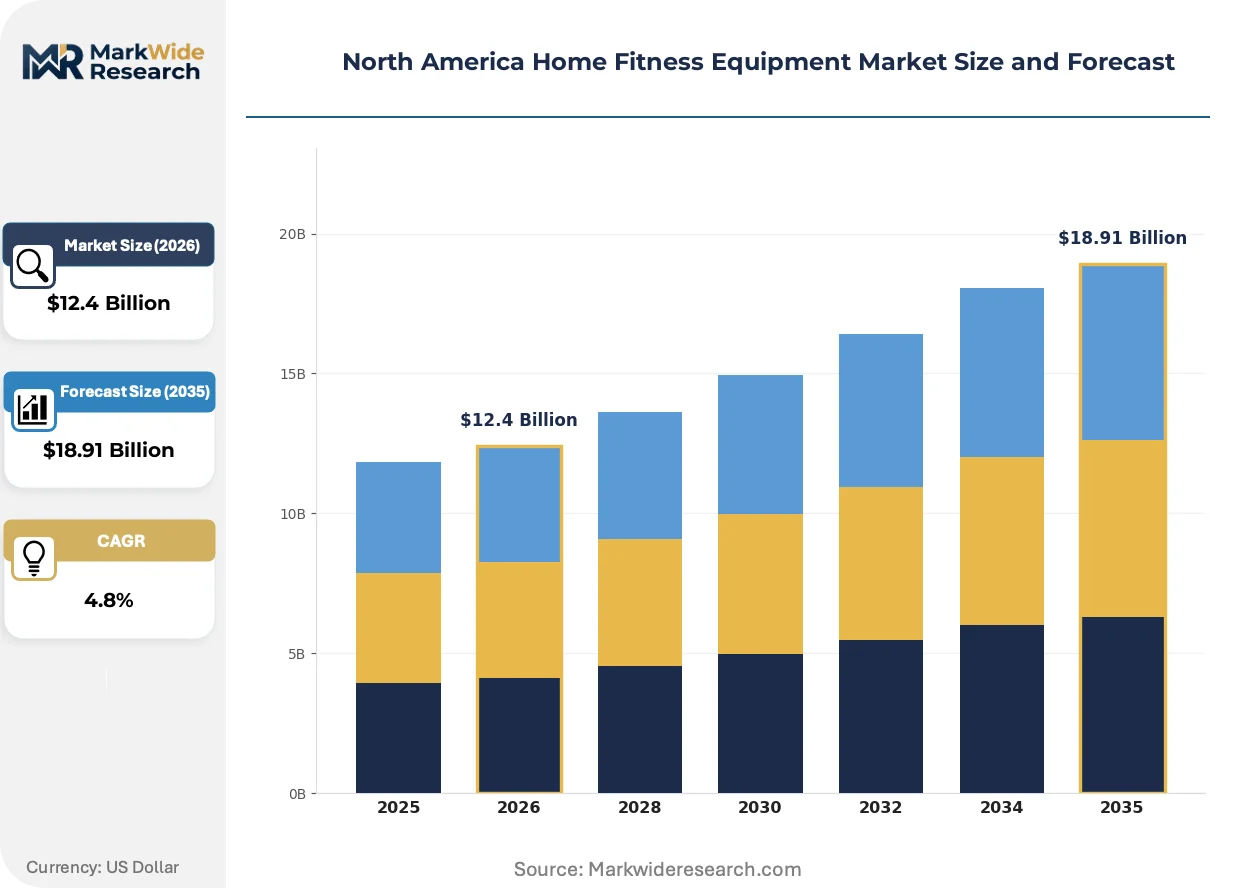
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $18.91 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
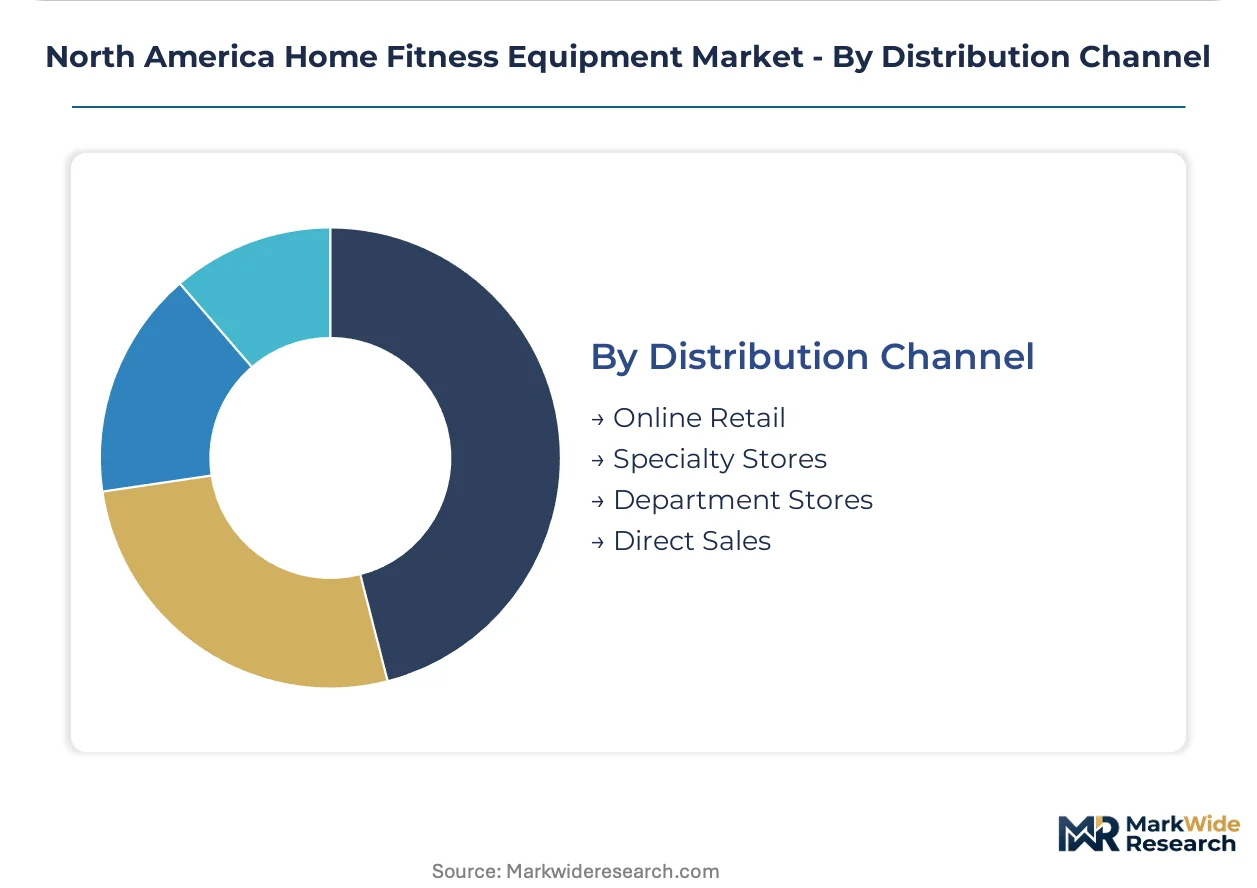
| Segmentation | Product Type: Treadmills, Stationary Bikes, Dumbbells, Resistance Bands End User: Fitness Enthusiasts, Casual Users, Professional Athletes, Seniors Technology: Smart Equipment, Manual Machines, Hybrid Solutions, Connected Devices Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | ICON Health & Fitness, Nautilus, Peloton Interactive, Johnson Health Tech, Technogym, Core Health & Fitness, Tonal Systems, Life Fitness, Hoist Fitness Systems, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Home Fitness Equipment Market Evolving Landscape
Digital coaching integration is compressing replacement intervals for cardiovascular equipment, while regulatory pressure on energy consumption and electromagnetic emissions reshapes hardware architecture priorities.
AI-powered form correction is integrating computer vision sensors into treadmill and stationary bike consoles. Suburban remote workers with disposable income are adopting these systems at twice the rate of urban apartment dwellers. The technology is integrating subscription retention mechanics that extend customer lifetime value beyond hardware margins.
The EPA's updated energy efficiency standards for consumer electronics are hardening power draw thresholds for connected exercise equipment. Manufacturers face redesign costs or market exclusion in states adopting California's Title 20 baseline. Texas and Florida markets, lacking state-level efficiency mandates, are becoming testbeds for tiered product lines that segment by regulatory jurisdiction.
Direct-to-consumer assembly and installation services are unbundling from traditional retail channels. First-time home gym purchasers in migration-heavy housing markets prefer white-glove delivery over big-box self-assembly. This channel shift is most visible in Dallas-Fort Worth and Miami-Dade counties, where housing starts outpace national averages.
North America Home Fitness Equipment Market Segmentation
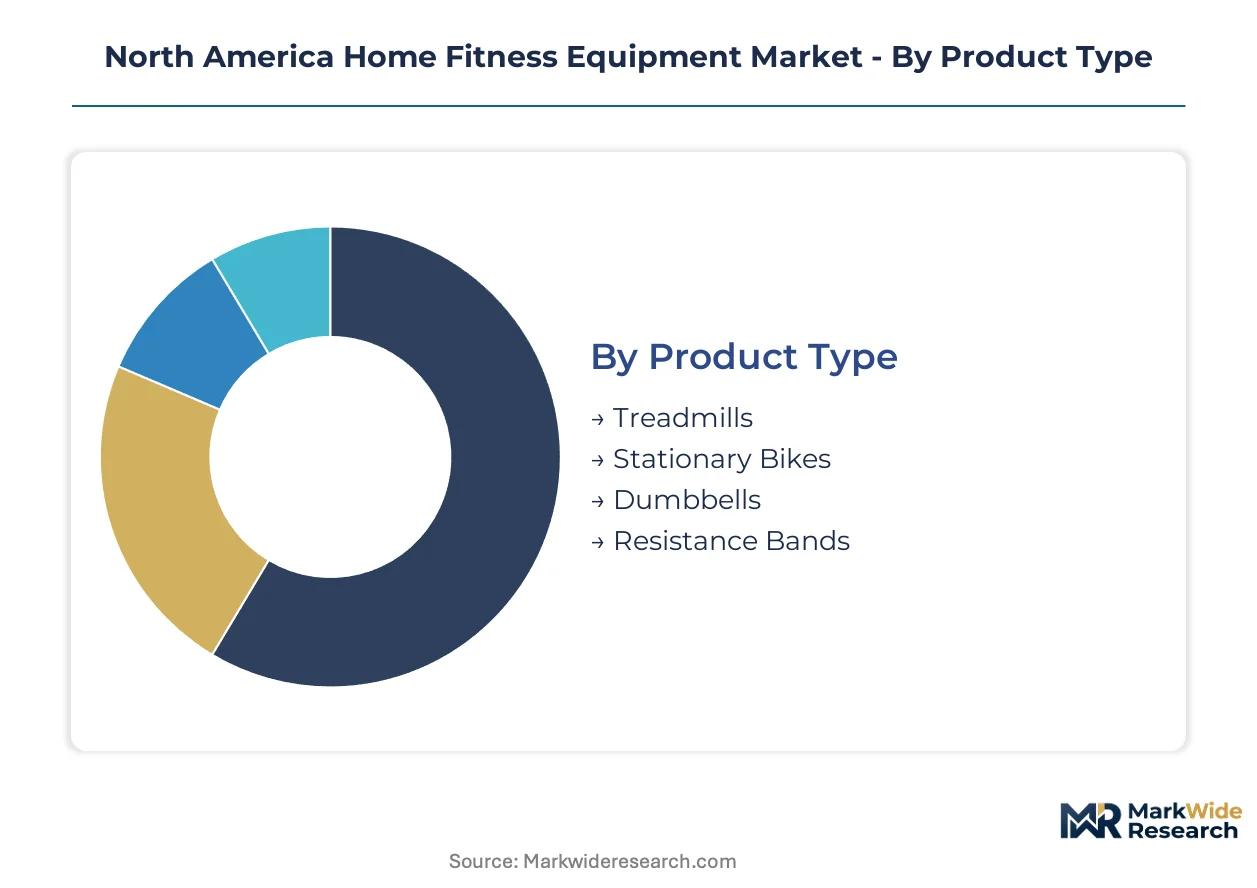
Segmentation in home fitness equipment reveals how purchase decisions split between performance requirements, space constraints, and connectivity expectations. Buyers in Texas and Florida migration corridors demonstrate distinct clustering patterns across these dimensions that reshape inventory allocation for manufacturers and retailers.
Product Type:
Space availability and workout intensity preferences drive equipment selection, with suburban remote workers prioritizing cardiovascular machines over compact strength tools.
- Treadmills:Steel alloy frames with belt-drive systems producing 150-500 watt torque outputs anchor residential cardio setups. Demand concentrates in Dallas-Fort Worth and Miami-Dade counties where first-time home gym purchasers prioritize running simulation over cycling.
- Stationary Bikes:Magnetic resistance variants with neodymium-dependent flywheels dominate connected equipment portfolios. These systems capture margin premiums through subscription-locked software ecosystems in metropolitan markets where digital coaching drives replacement cycles.
- Dumbbells:Polymer-coated weight stacks with commercial-grade durability standards serve space-constrained users seeking flexibility training without motorized footprint.
- Resistance Bands:Portable non-motorized apparatus appeals to casual users and travel-intensive remote workers prioritizing storage efficiency over resistance precision.
Volume sits with Treadmills; growth tilts toward Stationary Bikes.
End User:
Purchase frequency and price sensitivity diverge sharply across user commitment levels, with subscription retention mechanics favoring digitally engaged segments.
- Fitness Enthusiasts:High-frequency users demanding commercial-grade component durability and advanced performance metrics. This segment sustains replacement cycles for connected cardio equipment at compressed intervals.
- Casual Users:Sporadic exercisers prioritizing cost efficiency and minimal setup complexity. Manual machines and resistance bands dominate this tier where abandonment risk elevates warranty claim rates.
- Professional Athletes:Performance-calibrated equipment requiring torque output precision and biomechanical feedback integration. AI-powered form correction sensors penetrate this segment fastest.
- Seniors:Low-impact cardiovascular options with enhanced stability features and simplified console interfaces. EPA energy efficiency standards particularly influence motor system selection for this price-conscious demographic.
Volume sits with Casual Users; expansion concentrates among Fitness Enthusiasts.
Technology:
Regulatory pressure on electromagnetic emissions and power consumption is segmenting product architectures by jurisdiction-specific compliance requirements.
- Smart Equipment:Embedded systems with real-time operating systems and IoT security protocols enabling digital coaching integration. Firmware talent scarcity elevates R&D overhead for manufacturers developing these platforms.
- Manual Machines:Non-motorized apparatus exempt from FCC certification timelines and EPA efficiency mandates. These systems retain cost advantages through Taiwan-based manufacturing footprints serving price-sensitive segments.
- Hybrid Solutions:Dual-mode equipment switching between connected and offline operation. Texas and Florida markets lacking state-level efficiency mandates serve as testbeds for tiered product lines segmenting by regulatory jurisdiction.
- Connected Devices:Wireless-enabled equipment subject to 14-18 month FCC certification cycles. Health Canada electromagnetic emissions coordination with EPA reduces certification duplication for cross-border distribution.
Volume sits with Manual Machines; connected variants are climbing the fastest.
Distribution Channel:
Assembly complexity and buyer experience expectations are unbundling fulfillment models from traditional retail footprints.
- Online Retail:E-commerce platforms capturing suburban remote workers through direct-to-consumer logistics. White-glove delivery services penetrate migration-heavy housing markets where housing starts outpace national averages.
- Specialty Stores:Consultative selling environments with in-person biomechanical assessment and equipment trials. These channels retain premium positioning for commercial-grade component lines.
- Department Stores:Mass-market access points for entry-level manual machines and resistance training accessories. Inventory depth concentrates on price-competitive SKUs with minimal assembly requirements.
- Direct Sales:Manufacturer-controlled channels enabling subscription bundling and proprietary installation networks. Peloton Interactive leverages this structure for captive supply chain integration of low-draw motor technology.
Volume sits with Online Retail; Direct Sales shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States dominates consumption while manufacturing concentrates in Taiwan and China. Canada serves as a secondary demand hub with distinct regulatory harmonization requirements. Mexico functions as an emerging assembly corridor for North American distribution.
United States
Remote work permanence in suburban Texas and Florida households compresses replacement cycles for connected cardio equipment. The EPA's ENERGY STAR specification revision for consumer exercise equipment forces motor system redesigns to maintain market access. Dallas-Fort Worth and Miami-Dade counties form dense pockets of first-time home gym purchasers where housing starts outpace national averages.
Canada
Health Canada coordinates electromagnetic emissions testing with the EPA for connected fitness devices crossing the border. This regulatory convergence reduces certification duplication for US manufacturers seeking Canadian market entry. Toronto and Vancouver metropolitan areas concentrate demand among fitness enthusiasts seeking commercial-grade residential equipment.
Mexico
Assembly operations near the US border leverage tariff-advantaged positioning for North American distribution. The country's manufacturing footprint supports cost-competitive production of manual machine categories. Monterrey and Tijuana industrial corridors host facilities serving price-sensitive segments across the region.
North America Home Fitness Equipment Market Competitive Landscape
The competitive structure tilts toward subscription-integrated hardware specialists. The vendor base spans three tiers: premium connected equipment platforms, mid-market durability specialists, and value-oriented manual machine fabricators. Strategic archetypes include captive supply chain investors, Taiwan-based manufacturing scale players, and commercial-grade component repurposers. Dominant competitive moves center on low-draw motor technology development and direct-to-consumer installation network expansion.
Among North American headquartered platforms, Peloton Interactive exemplifies the subscription-locked ecosystem archetype. Johnson Health Tech occupies a position representing Taiwan-based manufacturing footprint advantages. Core Health & Fitness anchors the commercial-grade component repurposing specialist tier.
| Leading Market Players |
|---|
| ICON Health & Fitness |
| Nautilus |
| Peloton Interactive |
| Johnson Health Tech |
| Technogym |
| Core Health & Fitness |
| Tonal Systems |
| Life Fitness |
| Hoist Fitness Systems |
| Others |
Value Network & Pricing Analysis
First-time home gym purchasers in Texas and Florida migration corridors anchor volume-driven pricing negotiations, compressing margin structures for manufacturers serving these price-sensitive entry segments while subscription-integrated platforms command premium positioning elsewhere.
Pricing Analysis
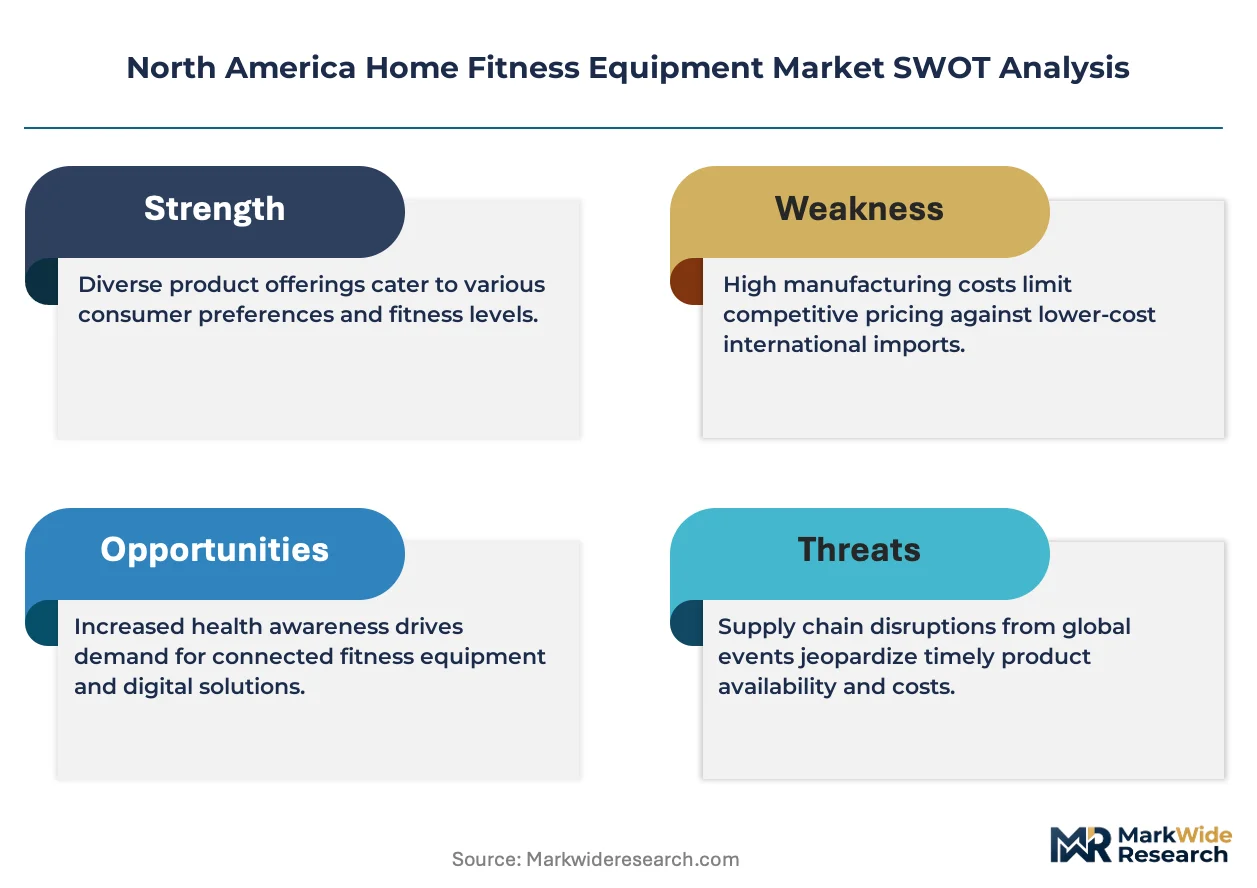
Cost-down pressure on connected cardio equipment accelerates because EPA ENERGY STAR compliance mandates force motor system redesigns that elevate bill-of-materials complexity. Three-tier pricing structure across premium, standard, and economy levels separates subscription-locked smart platforms from Taiwan-sourced manual machines and entry-level resistance tools. Price differentiation traces to certification grade—California Title 20 compliance versus non-compliant SKUs—and geographic delivery cost differentials between white-glove installation markets and self-assembly retail channels. Casual users in suburban migration corridors exhibit highest price sensitivity, while fitness enthusiasts sustain premium tolerance for AI-integrated form correction systems.
Supply Chain Analysis
Freight cost inflation from Asia-Pacific manufacturing hubs to North American distribution centers compresses landed cost advantages for Taiwan-based manual machine producers. Component sourcing draws from Taiwan for motor controllers, China for neodymium-dependent magnetic resistance flywheels, and Vietnam for polymer-coated weight stack housings. Raw material dependencies center on steel alloy frame stock, rare earth magnet supply, and embedded systems semiconductors. Tariff exposure on Chinese-processed neodymium creates margin predictability risk for magnetic resistance system manufacturers. Distribution runs through direct-to-consumer logistics platforms capturing suburban remote workers, specialty retail for consultative selling environments, and mass-market department stores for entry-level SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America home fitness equipment market operates as a cost-of-compliance arena where EPA ENERGY STAR specification revision erects regulatory moats favoring incumbents with captive R&D infrastructure and cross-border certification experience.
For Market Incumbents: Anticipate boutique fitness chain expansion in suburban Texas and Florida markets siphoning discretionary spending from residential equipment budgets by accelerating direct-to-consumer installation network density and deepening backward integration into low-draw motor technology development. Defend subscription retention through AI-powered form correction sensor integration that extends customer lifetime value beyond hardware replacement cycles. For New Entrants and Emerging Players: AI-native coaching platforms represent the most penetrable wedge for unbundling Peloton's subscription-locked ecosystem dominance. Target hybrid solution architectures for Texas and Florida testbed markets lacking state-level efficiency mandates, enabling tiered product lines that segment by regulatory jurisdiction. Pursue white-glove delivery partnerships with regional logistics specialists in Dallas-Fort Worth and Miami-Dade corridors where housing starts concentrate first-time purchaser demand. For Investors and Strategic Acquirers: The window for entry favors commercial-grade component repurposing specialists with established Taiwan manufacturing footprints and Health Canada electromagnetic emissions coordination capabilities. Long-term viability hinges on firmware talent acquisition and IoT security protocol development. Watch FCC certification timeline friction as inflection indicator—regulatory lag exceeding 18 months signals supply-constrained pricing power for compliant incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Draw Motor Technology Investment | EPA ENERGY STAR compliance secures market access across California-adopting states. |
| Direct-to-Consumer Installation Network Expansion | White-glove delivery captures first-time purchasers in migration-heavy housing markets. |
| Cross-Border Certification Harmonization | Health Canada EPA coordination reduces duplication costs for connected device distribution. |
| AI-Powered Form Correction Integration | Computer vision sensors extend subscription retention and customer lifetime value. |
| Taiwan Manufacturing Footprint Optimization | Cost advantages in manual machine categories sustain margin against connected equipment compression. |
Research Methodology
Trade association filings, EPA regulatory dockets, and FCC equipment authorization databases formed the secondary backbone for supply chain and compliance mapping. Primary interviews with connected fitness platform executives, Taiwan-based contract manufacturing procurement leads, specialty retail category buyers, and direct-to-consumer logistics operators validated demand segmentation assumptions. Bottom-up unit economics modeling triangulated against top-down macroeconomic indicators including housing starts data and remote work permanence surveys.
Bottom-up demand estimation by product type, end user commitment tier, technology architecture, and distribution channel anchored the analytical framework across the projection horizon. Top-down validation incorporated regional migration patterns and suburban household formation rates. CAGRs derived from replacement cycle compression analysis for connected equipment versus manual machine lifespan extension. Industry-specific forecast inputs included neodymium supply quota volatility and FCC certification queue duration trends.
Several conditions sit outside the modeled scope, including pandemic-scale demand shocks, rare earth export restriction escalations, and boutique fitness chain bankruptcy waves. Forecasts reflect assumptions about regulatory stability and suburban housing market continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Asia-Pacific Fitness Rings Market
Fitness Equipment
Yoga and Exercise Mats Market
Fitness Equipment
Fitness Equipment Market
Fitness Equipment
India Fitness Ring Market
Fitness Equipment
Muscle Oxygen Monitors Market
Fitness Equipment
Latin America Fitness Ring Market
Fitness Equipment
Leg Exercise Equipment Market
Fitness Equipment
Treadmill Ergometer Market
Fitness Equipment
Europe Home Fitness Equipment Market
Fitness Equipment
Smart Scales Market
Fitness Equipment
Resistance Bands Market
Fitness Equipment
Functional Fitness Equipment Market
Fitness Equipment
Europe E-Commerce Home Fitness Products Market
Fitness Equipment
Europe Fitness Rings Market
Fitness Equipment
South Africa Gym Accessories Market
Fitness Equipment
Pilates Equipment Market