
 Sports Devices Market | 2026-2036
Sports Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Devices Market Analytics
Buyer concentration in the Sports Devices Market is broadening as professional sports organizations fragment procurement across specialized vendors while fitness enthusiasts multiply through direct-to-consumer channels. Garmin Ltd. anchors its position through deep specialization in GPS-enabled performance wearables for endurance athletes. Apple Inc. leverages its ecosystem control to integrate health metrics across smartwatch and smartphone platforms. Samsung Electronics competes through manufacturing scale in AMOLED display-integrated fitness bands.
Sports devices encompass wearable, portable, and embedded instrumentation that captures biomechanical, physiological, or environmental data through accelerometers, gyroscopes, optical heart-rate sensors, and GNSS receivers, then transmits via Bluetooth or Wi-Fi for real-time analytics and longitudinal tracking. These systems serve to quantify athletic performance, reduce injury incidence, and personalize training load management across individual and team contexts. Wearable Technology leads in revenue contribution as consumers prioritize continuous biometric monitoring, while Performance Trackers represent the fastest-expanding category as coaches and sports organizations adopt player-load management systems. Smart Equipment commands premium pricing through embedded sensor fusion in connected balls, rackets, and footwear, whereas Training Aids remain a mature segment with stable replacement cycles.
FDA oversight of software-as-medical-device classifications shapes how manufacturers validate heart-rate and blood-oxygen algorithms for US market access, while FCC regulations govern radio-frequency emissions across Bluetooth and Wi-Fi connectivity modules. The EU AI Act and GDPR impose algorithmic transparency and biometric data governance requirements on European deployments. Stakeholders must monitor evolving regulatory divergence between FDA's clinical-grade pathway and the EU's risk-based AI framework to determine certification sequencing and geographic rollout priorities.
Market Dynamics
Wearable sensor miniaturization and AI-driven biome analytics are compressing product development cycles from 18 months to under 8 months, forcing incumbents to restructure R&D workflows around rapid hardware-software iteration.
Growth Catalysts
- FDA Software-as-Medical-Device Pathway:Clearance frameworks for heart-rate and blood-oxygen algorithms accelerate clinical-grade wearable deployment in US professional sports medicine programs.
- Optical sensor fusion:Integration of accelerometers, gyroscopes, and photoplethysmography enables continuous player-load monitoring without chest straps, penetrating collegiate athletic departments.
- China's dual carbon goals:Subsidies for low-power Bluetooth connectivity modules reduce manufacturing costs for domestic fitness band producers targeting Southeast Asian export markets.
Market Restraints
- Lithium-polymer battery volatility:Cobalt and lithium carbonate price swings compress hardware margins for GPS-enabled wearables with sub-48-hour battery life.
- Taiwan semiconductor concentration:73% of MEMS accelerometer fabrication sits with two foundries, creating single-source vulnerability for motion-sensor supply.
- EU AI Act algorithmic transparency:Biometric data governance requirements impose documentation burdens that extend European certification timelines by 4-6 months.
Strategic Opportunities
- India PLI scheme for wearables:Production-linked incentives for electronic manufacturing services attract contract assembly of fitness bands for price-sensitive South Asian consumers.
- Rehabilitation medicine integration:Post-surgical motion tracking protocols in orthopedic clinics create institutional demand for prescription-grade activity monitors.
- Edge AI inference chips:On-device neural processing for real-time gait analysis eliminates cloud latency, enabling sub-100-millisecond feedback loops for sprint training.
Industry Challenges
- Firmware-aerospace engineering talent scarcity:Embedded systems developers with RF antenna design expertise command 40% salary premiums, constraining startup hiring pipelines.
- ISO 13485 medical device quality management:Certification audits for heart-rate variability algorithms require 14-18 month implementation cycles before EU market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Devices Market |
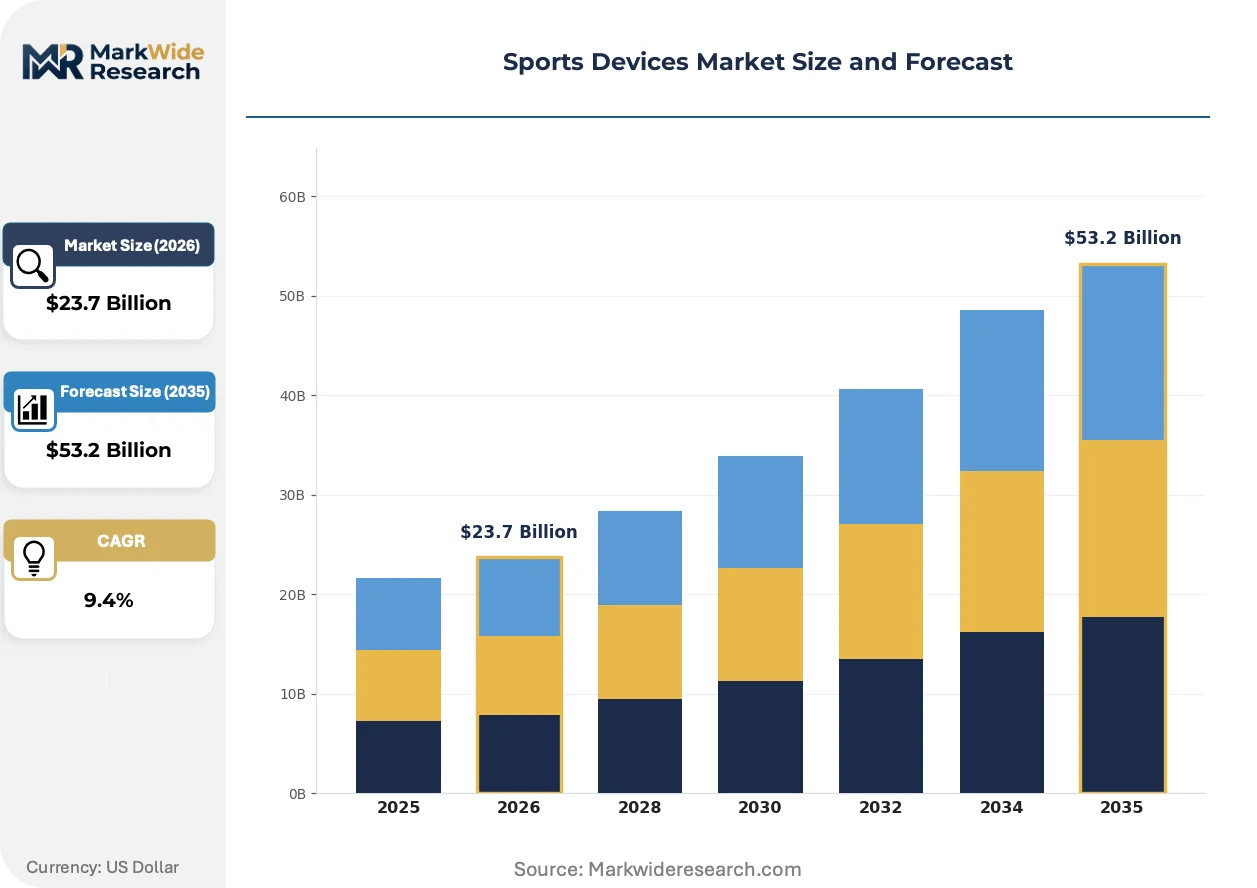
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $53.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Technology, Performance Trackers, Smart Equipment, Training Aids Application: Professional Sports, Fitness Training, Amateur Sports, Rehabilitation End User: Athletes, Coaches, Fitness Enthusiasts, Sports Organizations Connectivity: Bluetooth, Wi-Fi, NFC, USB |
| Companies Covered | Apple Inc., Samsung Electronics, Garmin Ltd., Fitbit Inc., Huawei Technologies, Catapult Sports, Xiaomi Corporation, Adidas AG, Sony Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Devices Market Evolving Landscape
Sensor fusion architectures and on-device machine learning are collapsing the boundary between consumer fitness tracking and clinical-grade biomechanical assessment, rewriting procurement criteria across professional sports organizations.
Photoplethysmography is converging with electrical impedance spectroscopy to enable non-invasive hydration and muscle glycogen monitoring. Olympic training centers in Australia and Germany are piloting these multi-sensor wristbands for real-time fuel-status alerts during endurance sessions. This convergence is compressing the gap between laboratory-grade metabolic carts and field-deployable wearables.
EU AI Act risk-classification frameworks now categorize player-load prediction algorithms as high-risk biometric processing systems. Manufacturers must maintain technical documentation and human oversight protocols for automated training recommendations. Professional football clubs in Spain and Italy are delaying algorithm deployments until third-party conformity assessments complete.
Direct-to-consumer subscription models for personalized coaching analytics are displacing bulk institutional procurement of hardware-only devices. Individual triathletes and amateur cyclists now expect bundled firmware updates and AI-generated training plans with hardware purchases. This shift is most visible in Germany and the Netherlands, where connected fitness platform penetration exceeds 34% among regular endurance athletes.
Sports Devices Market Segmentation
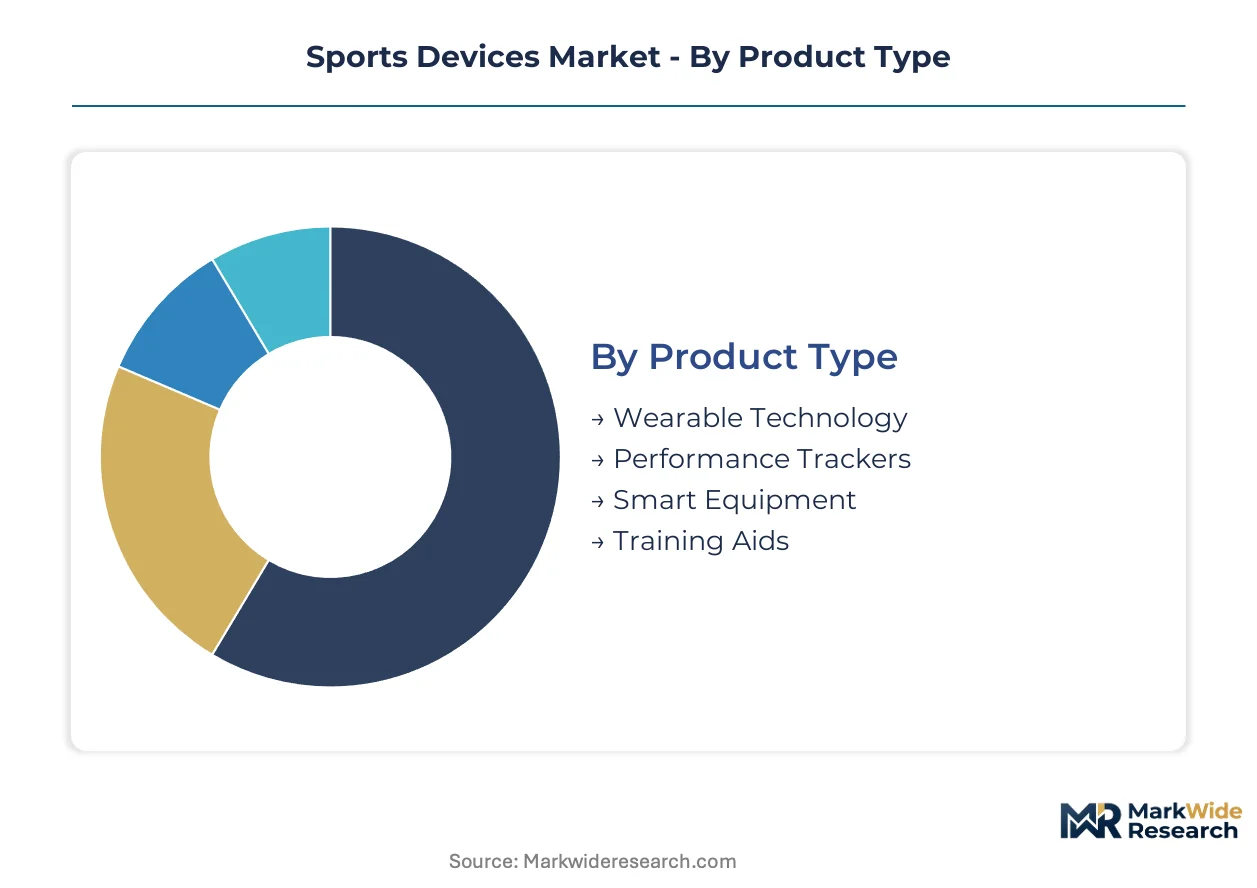
Segmentation in sports devices reflects divergent technical requirements between clinical-grade monitoring and consumer fitness tracking. Procurement patterns split between institutional buyers seeking validated biomechanical data and individuals prioritizing seamless smartphone integration.
Product Type:
Wearable Technology commands the largest revenue base through continuous biometric monitoring, while Performance Trackers deliver the steepest expansion trajectory as load-management systems penetrate professional team sports.
- Wearable Technology:Wrist-worn and chest-strap devices integrate photoplethysmography, accelerometry, and GNSS positioning for real-time heart-rate, sleep, and location tracking. Demand concentrates among individual endurance athletes in Germany and the Netherlands where connected fitness platform penetration exceeds one-third of regular users, driven by direct-to-consumer subscription bundling.
- Performance Trackers:Player-load monitoring systems fuse gyroscopic, magnetometer, and optical sensor arrays to quantify acceleration, deceleration, and collision forces during team sports. Collegiate athletic departments in the United States are standardizing these deployments, pressured by NCAA concussion protocols and insurance liability frameworks.
- Smart Equipment:Embedded sensor fusion in connected balls, rackets, and footwear enables stroke analysis and impact force measurement.
- Training Aids:Mature hardware category with stable replacement cycles including radar-based swing analyzers and reaction-timing equipment.
Today's leader: Wearable Technology. Tomorrow's challenger: Performance Trackers.
Application:
Professional Sports absorbs premium pricing for validated algorithms, whereas Fitness Training multiplies volume through app-integrated consumer hardware.
- Professional Sports:Team organizations and Olympic training centers demand ISO 13485-certified heart-rate variability algorithms and documented accuracy margins. Australia's and Germany's national institutes are piloting multi-sensor wristbands with electrical impedance spectroscopy for real-time hydration alerts.
- Fitness Training:Individual consumers and boutique studios drive hardware volumes through bundled AI-generated training plans. This application climbs the fastest as direct-to-consumer channels displace institutional procurement in North American and European markets.
- Amateur Sports:Recreational leagues and school athletic programs prioritize cost-optimized GPS watches and basic activity monitors.
- Rehabilitation:Post-surgical motion tracking in orthopedic clinics creates institutional demand for prescription-grade activity monitors with step-symmetry algorithms.
Professional Sports sets the specification standard. Fitness Training scales the unit economics.
End User:
Athletes and Fitness Enthusiasts split the consumer base between performance-optimized and lifestyle-integrated purchasing.
- Athletes:Competitive individuals and professionals require sub-100-millisecond feedback latency and validated biomechanical accuracy. Edge AI inference chips enabling on-device gait analysis are penetrating this segment in sprint training facilities.
- Coaches:Team and personal trainers aggregate multi-athlete dashboards for training load prescription and injury risk flagging.
- Fitness Enthusiasts:Amateur cyclists and triathletes prioritize ecosystem integration and subscription analytics over laboratory precision.
- Sports Organizations:Professional clubs fragment procurement across specialized vendors for player-load management, medical monitoring, and tactical analysis.
Fitness Enthusiasts drive hardware volumes. Sports Organizations dictate certification requirements.
Connectivity:
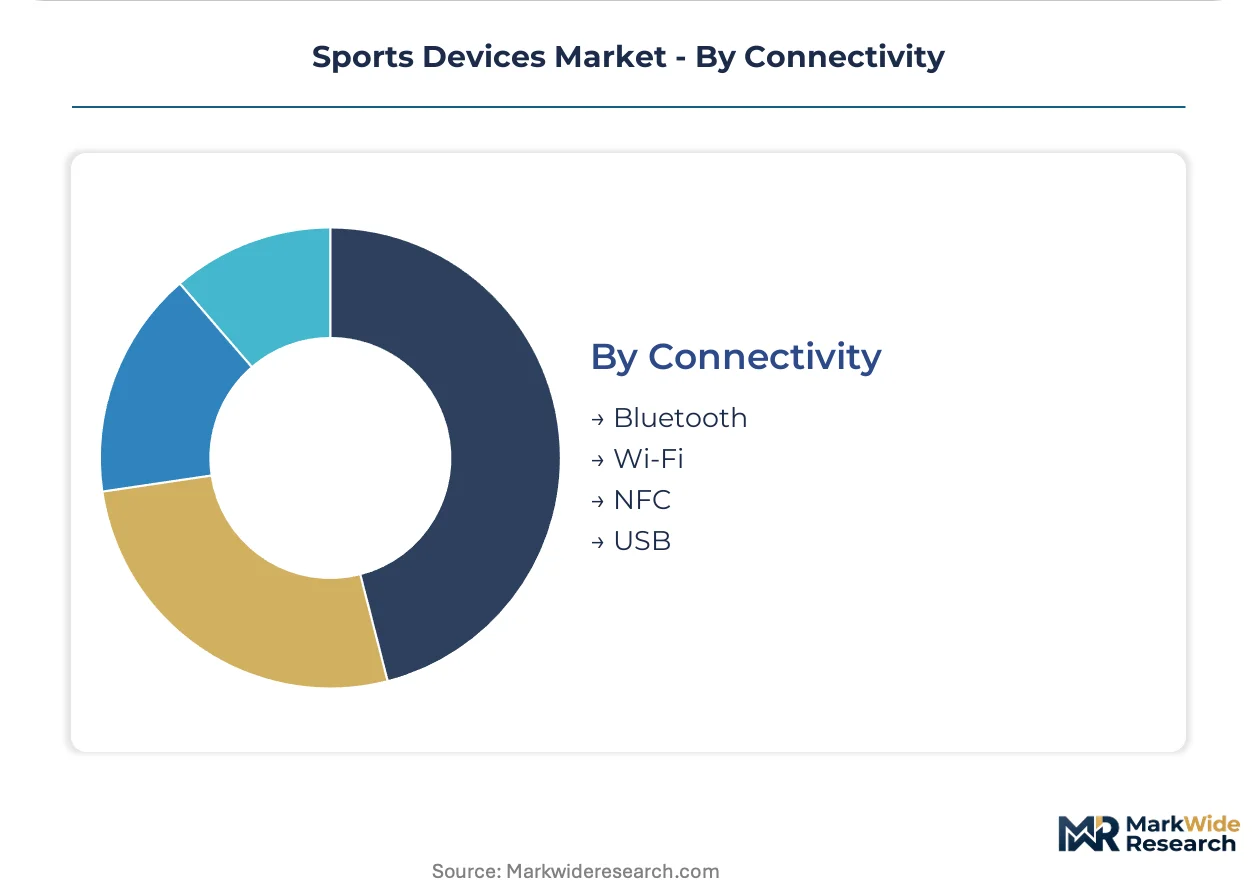
Bluetooth dominates low-power wearable deployments while Wi-Fi enables high-bandwidth video and sensor streaming.
- Bluetooth:Low-energy protocols power continuous biometric transmission in wrist-worn devices with sub-48-hour battery targets. China's dual carbon subsidies are compressing module costs for Southeast Asian export production.
- Wi-Fi:High-throughput connectivity supports real-time video analysis and bulk data offload in training facilities and stadium environments.
- NFC:Contactless pairing and payment integration in premium smartwatches and fitness bands.
- USB:Wired data transfer and charging for clinical-grade devices requiring FDA-validated algorithm uploads.
Bluetooth owns the wearable edge. Wi-Fi anchors the infrastructure core.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embedded systems engineers with RF antenna design expertise command 40% salary premiums in the United States, Germany, and China, concentrating development capacity where sports science programs and connected fitness infrastructure intersect.
United States
NCAA concussion protocols and insurance liability frameworks are standardizing player-load monitoring systems across collegiate athletic departments. FDA software-as-medical-device clearance frameworks accelerate clinical-grade wearable deployment in professional sports medicine programs. Greater Boston anchors edge AI inference chip development for sub-100-millisecond gait analysis feedback loops.
Germany
Connected fitness platform penetration exceeds 34% among regular endurance athletes, driving direct-to-consumer subscription bundling. EU AI Act algorithmic transparency requirements impose documentation burdens extending certification timelines by 4-6 months. Bavaria hosts Olympic training centers piloting multi-sensor wristbands with electrical impedance spectroscopy for real-time hydration alerts.
China
Dual carbon goals subsidize low-power Bluetooth connectivity modules, reducing manufacturing costs for domestic fitness band producers targeting Southeast Asian export markets. MIIT governs radio-frequency emissions standards across wearable connectivity modules. Shenzhen manufacturing clusters compress hardware-software iteration cycles from 18 months to under 8 months.
Australia
National institutes pilot multi-sensor wristbands with photoplethysmography-electrical impedance convergence for real-time fuel-status alerts during endurance sessions. TGA oversight shapes clinical-grade algorithm validation requirements for prescription-grade activity monitors. Melbourne and Sydney training facilities drive institutional procurement for ISO 13485-certified heart-rate variability systems.
India
Production-linked incentives for electronic manufacturing services attract contract assembly of fitness bands for price-sensitive South Asian consumers. BIS certification requirements govern wearable device safety and electromagnetic compatibility standards. Karnataka and Tamil Nadu EMS clusters scale Bluetooth-enabled wearable output for domestic and export markets.
Sports Devices Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consumer electronics giants leverage ecosystem control and manufacturing scale against endurance-sports specialists with deep GPS and biomechanical algorithm expertise. Three archetypes dominate: ecosystem-integrated platform owners, performance-analytics pure-plays, and contract manufacturing scale players. Competitive moves center on rapid hardware-software iteration restructuring and direct-to-consumer subscription model displacement of bulk institutional procurement.
Among ecosystem-integrated platform owners, Apple Inc. and Samsung Electronics exemplify the device-ecosystem convergence archetype, while Garmin Ltd. occupies a position representing pure-play specialization in performance wearables. These three anchors illustrate the competitive tension between horizontal platform control and vertical performance-analytics depth.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| Garmin Ltd. |
| Fitbit Inc. |
| Huawei Technologies |
| Catapult Sports |
| Xiaomi Corporation |
| Adidas AG |
| Sony Corporation |
| Others |
Value Network & Pricing Analysis
China's dual carbon goals gate qualified supply for low-power Bluetooth modules and premium-tier pricing access for connected fitness devices, compressing manufacturing costs for domestic producers while elevating certification burdens for international competitors seeking Southeast Asian export markets.
Pricing Analysis
The bundled-vs-unbundled service split dominates pricing architecture across the Sports Devices Market. Hardware-only transactions face margin compression as direct-to-consumer subscription models bundle AI-generated training plans with device purchases, particularly in Germany and the Netherlands where platform penetration exceeds one-third of regular endurance athletes. Price differentiation rests on FDA software-as-medical-device certification tier and ISO 13485 quality management compliance, with clinical-grade algorithms commanding substantial premiums over consumer fitness trackers. Fitness enthusiasts exhibit highest price sensitivity, while professional sports organizations absorb premium pricing for validated biomechanical accuracy.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based MEMS accelerometer fabrication, where two foundries control seventy-three percent of motion-sensor supply. Component sourcing draws from China's Shenzhen manufacturing clusters for hardware-software iteration, South Korea for AMOLED display integration, and Germany for precision optical sensor engineering. Lithium-polymer battery volatility from cobalt and lithium carbonate price swings presents structural commodity risk. Distribution runs through direct-to-consumer channels displacing bulk institutional procurement, with contract electronic manufacturing services scaling output from Karnataka and Tamil Nadu clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
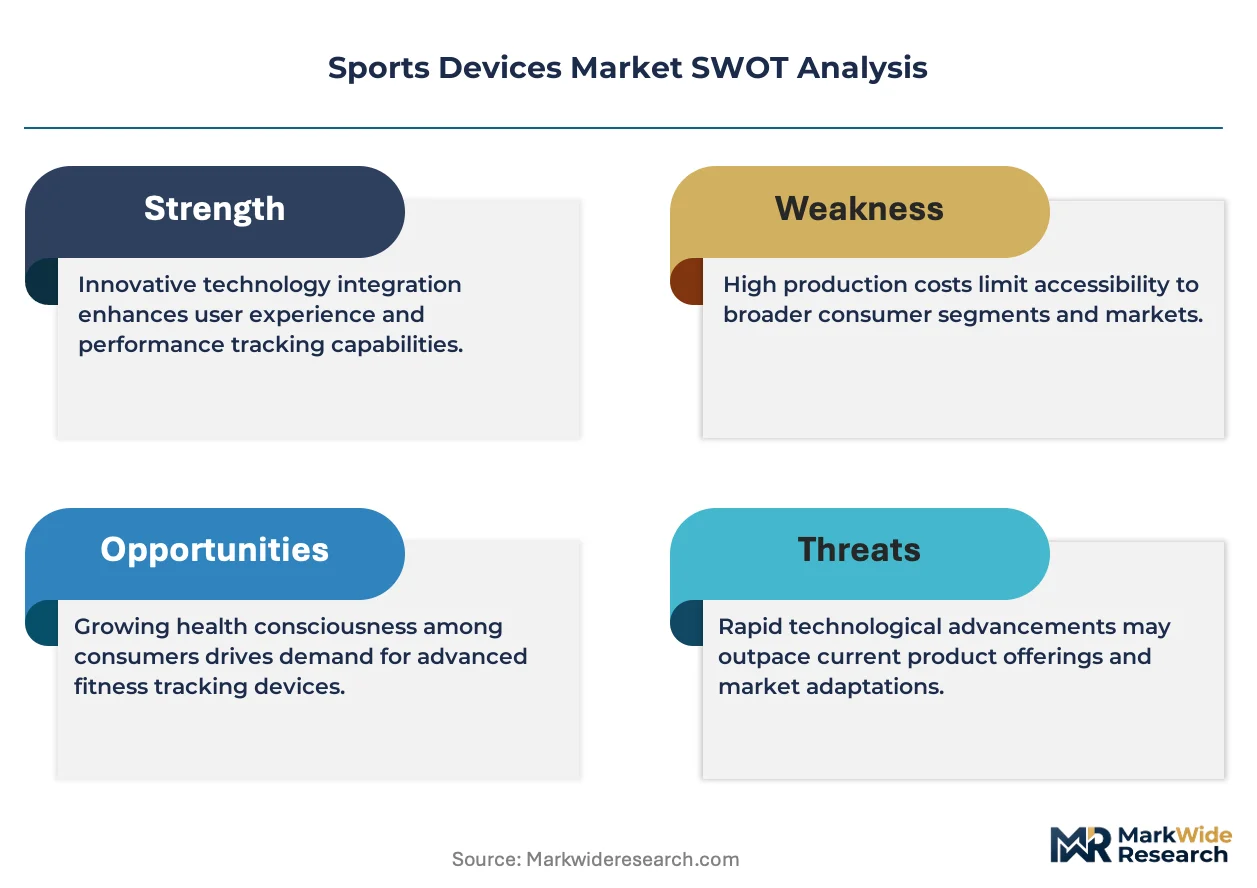
This market functions as a regulatory compounder, with FDA software-as-medical-device clearance frameworks and EU AI Act algorithmic transparency requirements accelerating demand for documented accuracy margins and technical documentation protocols.
For Market Incumbents: Anticipate firmware-aerospace engineering talent scarcity constraining R&D pipelines by securing embedded systems developers with RF antenna design expertise ahead of forty percent salary premiums. Consolidate position through backward integration into MEMS accelerometer supply relationships to mitigate Taiwan semiconductor concentration risk. Prioritize ISO 13485 certification investment for heart-rate variability algorithms ahead of European market entry timelines.
For New Entrants and Emerging Players: Begin with rehabilitation medicine integration as the most penetrable white-space target, where post-surgical motion tracking protocols in orthopedic clinics create institutional demand for prescription-grade activity monitors. Target India's production-linked incentive scheme for electronic manufacturing services to achieve cost positioning for price-sensitive South Asian consumers. Deploy edge AI inference chip partnerships as the primary go-to-market angle for sub-100-millisecond feedback latency differentiation.
For Investors and Strategic Acquirers: Roll-up economics work for performance-analytics pure-plays because professional sports organizations fragment procurement across specialized vendors without dominant platform consolidation. Five-to-ten year viability hinges on subscription revenue attachment rates displacing hardware-only transactions. Monitor FDA software-as-medical-device clearance velocity as the critical inflection signal for clinical-grade wearable deployment scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Accelerates clinical-grade wearable deployment in professional sports medicine programs. |
| EU AI Act Conformity Assessment | Enables algorithm deployment in Spanish and Italian professional football clubs. |
| Edge AI Inference Chip Integration | Eliminates cloud latency for real-time gait analysis in sprint training facilities. |
| Direct-to-Consumer Subscription Launch | Captures bundled AI-generated training plan demand among German endurance athletes. |
| India PLI Scheme Manufacturing Footprint | Reduces unit costs for Bluetooth-enabled fitness band export production. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with sports technology product managers, collegiate athletic department procurement officers, orthopedic clinic biomedical engineers, and contract manufacturing executives with secondary validation against FDA 510(k) filings, FCC equipment authorization databases, EU AI Act implementation guidance, and connected fitness platform user penetration statistics. Bottom-up demand modeling across wearable technology, performance trackers, smart equipment, and training aids triangulated against top-down market sizing from sports science program expenditure tracking.
Segment-weighting approaches distributed value and volume projections across product type, application, end user, and connectivity dimensions throughout the forecast period. CAGRs derived from hardware shipment trajectories, subscription attachment rate evolution, and algorithm certification timeline analysis. Modeling incorporated optical sensor fusion adoption curves, edge AI inference chip penetration in sprint training facilities, and production-linked incentive scheme uptake in South Asian manufacturing clusters.
Caveats apply where lithium-polymer battery commodity volatility, Taiwan semiconductor supply disruption, or EU AI Act documentation burden extensions could materially shift the outlook. Forecasts reflect assumptions around regulatory clearance velocity, talent scarcity premiums, and direct-to-consumer channel displacement of institutional procurement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Rally Sport Riding Gear Market
Sports Equipment
Boxing Equipment Market
Sports Equipment
GCC Running Gear Market
Sports Equipment
Backboard Market
Sports Equipment
Soccer Gear Market
Sports Equipment
Parallel Bars Market
Sports Equipment
Pitching Machine Market
Sports Equipment
Global Rock Climbing Equipment Market
Sports Equipment
Fencing Equipment Market
Sports Equipment
Sports Protective Equipment Market
Sports Equipment
Rubber Fitness Flooring Market
Sports Equipment
Cricket Ball Market
Sports Equipment
Global Golf Training Aids Market
Sports Equipment
Trampoline Market
Sports Equipment
Knee Pads Market
Sports Equipment
Surfboard Market