
 Boxing Gear Market | 2026-2036
Boxing Gear Market Size, Share, and Industry Trends Forecast 2026-2036
Boxing Gear Market Outlook
Buyer concentration among commercial gyms and franchise studios is pivoting toward mid-market operators that now represent the largest volume channel. Everlast Worldwide Inc. leverages its century-old brand equity to anchor shelf presence across North American sporting goods retailers. RDX Sports Ltd. competes aggressively on synthetic material innovation, while Venum Group dominates premium positioning through fight-sport authenticity and cage-side visibility.
Boxing gear encompasses protective and training equipment designed to absorb kinetic impact, distribute force across anatomical surfaces, and prevent acute trauma during striking activity. Competition-grade gloves typically incorporate multi-density foam laminates ranging from 8 to 16 ounces, with horsehide or microfiber outer shells stitched to withstand repetitive shear loads. Gloves and punching bags generate the bulk of current revenue, though hand wraps are gaining share as injury-prevention awareness spreads among amateur participants. The price tier structure separates luxury hand-crafted Mexican leather products from mass-market synthetic alternatives, with margin pools concentrating in premium mid-range segments where durability claims justify elevated price points.
The US Consumer Product Safety Commission and ASTM International govern impact-attenuation standards for headgear sold domestically, while Mexico's national standards body certifies competition gloves for professional bouts under NOM specifications. These frameworks elevate compliance costs for new entrants but protect established manufacturers with certified testing protocols. Stakeholders must monitor evolving state-level liability rulings on concussive injury claims and their downstream effect on insurance-driven equipment specifications.
Market Dynamics
Synthetic leather alternatives and multi-density foam laminates are compressing traditional material hierarchies across boxing gear supply chains. Boutique studio procurement volumes now rival established commercial gym channels, forcing manufacturers to recalibrate production runs and inventory positioning.
Growth Catalysts
- ASTM International impact-attenuation standards:Certification requirements for headgear sold in the United States create durable demand for compliant manufacturers with established testing protocols.
- Fitness studio proliferation:Boutique boxing concepts in urban centers drive recurring equipment refresh cycles and expand addressable buyer pools beyond traditional fight gyms.
- Microfiber outer shell technology:Advanced synthetic materials replicate horsehide performance at lower unit costs, enabling price-tier expansion into amateur segments.
Market Restraints
- Petrochemical input volatility:Synthetic leather and foam padding production remains exposed to polymer feedstock price swings that compress margin predictability.
- Concentrated artisan supply:Premium hand-crafted Mexican leather gloves depend on a limited cluster of Guadalajara-based workshops with finite capacity expansion.
- NOM certification friction:Mexico's national standards body maintains lengthy professional bout glove approval timelines that delay product launches for competition-grade lines.
Strategic Opportunities
- Thailand regulatory alignment:Muay Thai's international expansion creates demand for dual-certified gear meeting both Thai competition standards and import market requirements.
- Direct-to-studio distribution:Bypassing traditional sporting goods retailers allows manufacturers to capture margin and build subscription-based refresh programs with franchise operators.
- Hand wrap injury-prevention positioning:Amateur participation growth enables premium pricing for wrap systems marketed through orthopedic and physical therapy referral channels.
Industry Challenges
- Concussive injury liability exposure:State-level court rulings on equipment-related trauma claims drive insurance cost escalation and product specification uncertainty.
- Multi-density foam R&D talent scarcity:Formulation chemists with combat-sport specific expertise command premium compensation and limited geographic availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boxing Gear Market |
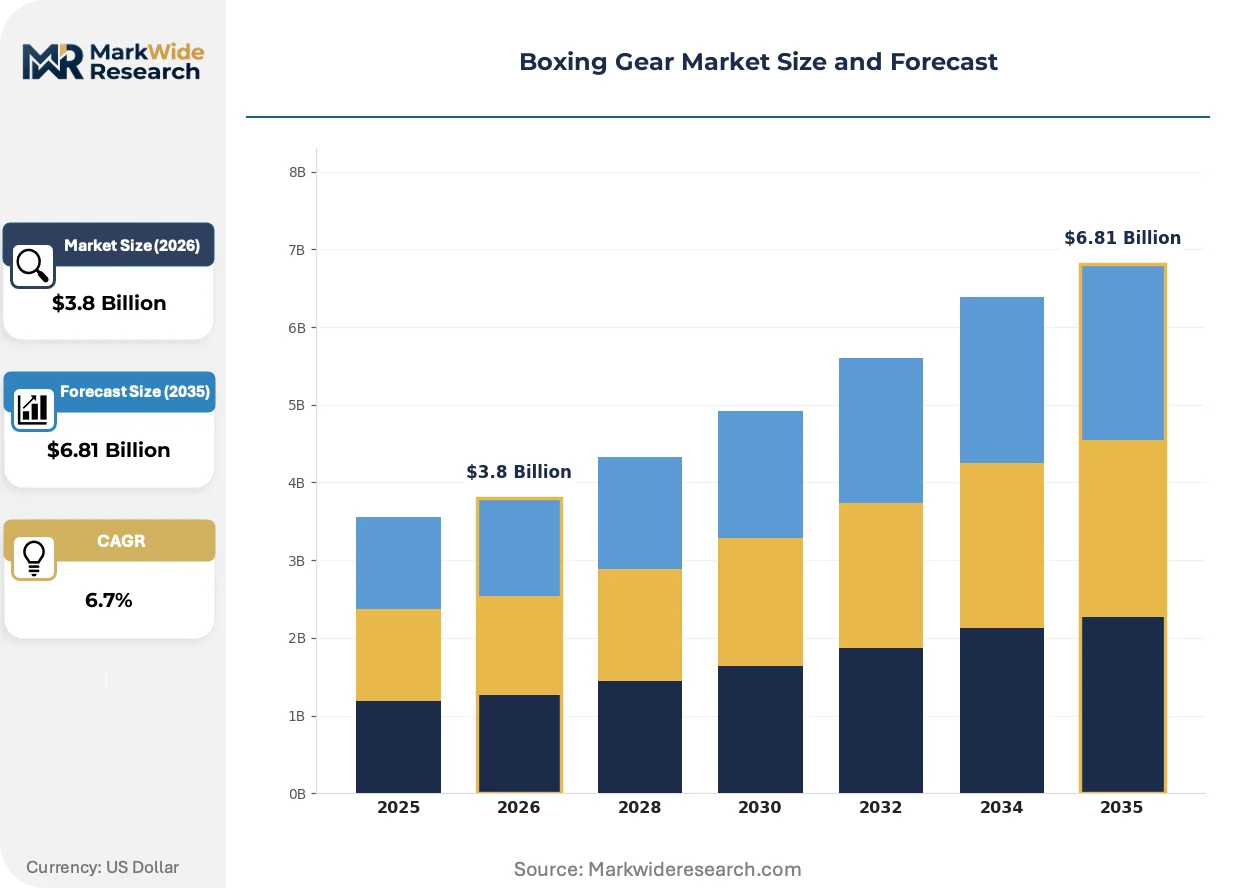
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gloves, Headgear, Punching Bags, Hand Wraps End User: Athletes, Trainers, Gyms, Fitness Enthusiasts Material: Leather, Synthetic, Cotton, Foam Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Ringside, Inc., Hayabusa Fightwear Inc., Everlast Worldwide Inc., Venum Group, RDX Sports Ltd., Adidas AG, Title Boxing LLC, Industrias Cleto Reyes S.A. de C.V., Century LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boxing Gear Market Strategic Shifts
Material science advances and liability-driven specification tightening are converging to reshape competitive differentiation. Manufacturers now compete on validated protection metrics rather than heritage branding alone.
Multi-density foam laminates is consolidating protective performance standards across glove and headgear categories. Commercial gym procurement teams now specify impact-attenuation test results as mandatory bid criteria. This technology compression is marginalizing single-density foam suppliers and elevating certified manufacturers into preferred vendor status.
ASTM International headgear standards enforcement is accelerating compliance investment across domestic supply chains. Manufacturers without certified testing partnerships face retailer delisting and liability exposure. Amateur and youth segments exhibit the fastest specification adoption as parental safety concerns reshape purchase criteria.
Boutique studio buyers now demand outcome-based equipment refresh guarantees rather than transactional purchase terms. Franchise operators in California and Texas lead this contractual innovation, replacing upfront capital outlays with per-member monthly fees. This shift transfers inventory risk upstream and rewards manufacturers with predictive maintenance capabilities and rapid fulfillment infrastructure.
Boxing Gear Market Segmentation
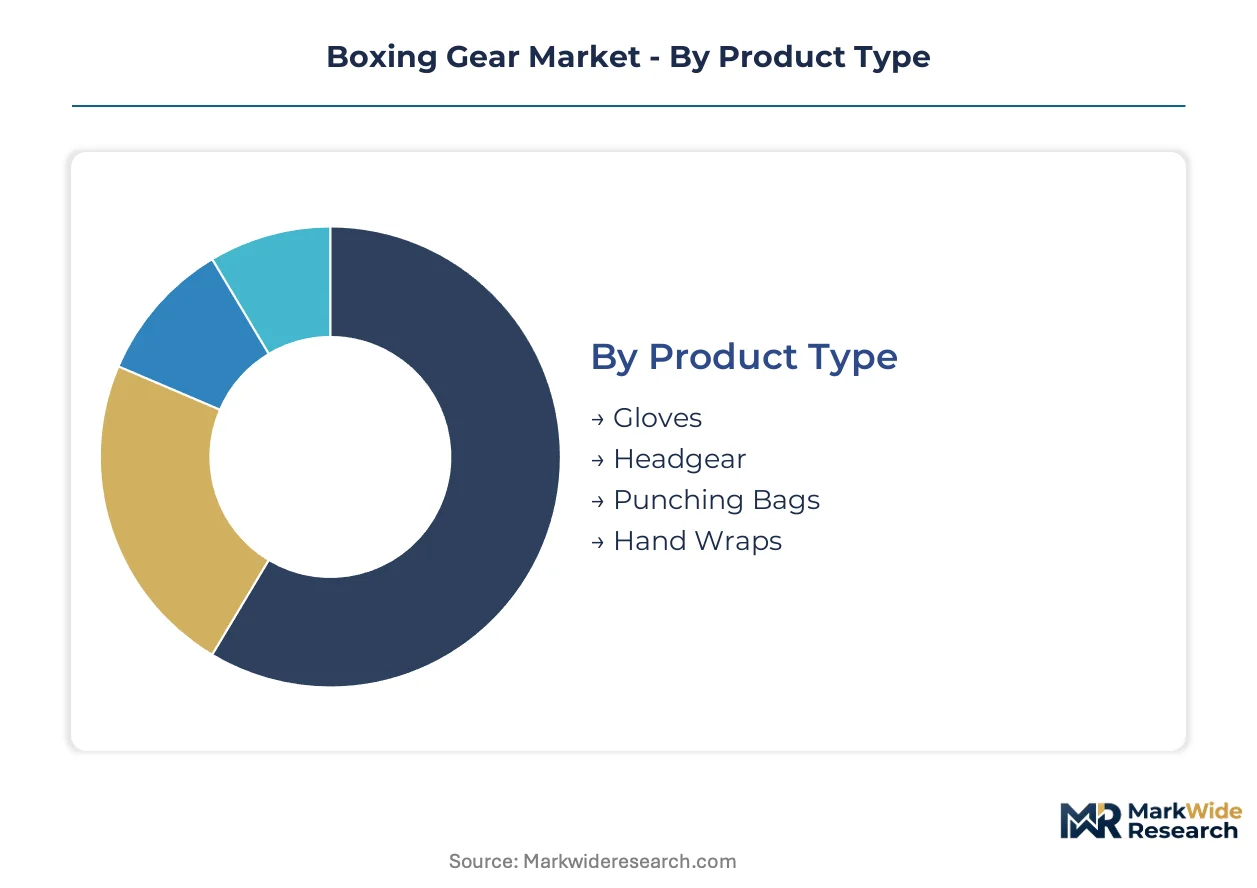
Equipment refresh cycles and injury-prevention mandates create divergent specification requirements across boxing gear categories. Procurement teams segment purchases by durability expectations, regulatory exposure, and end-user skill level rather than treating gear as interchangeable commodities.
Product Type:
Replacement timelines vary dramatically by product category, with competition-grade items requiring more frequent refresh than training equipment.
- Gloves:Multi-density foam laminates bonded to horsehide or microfiber shells absorb repetitive shear loads during striking. Professional bout specifications in Mexico and Thailand drive demand for NOM-certified and dual-standard competition models that command sustained premium positioning.
- Headgear:ASTM International impact-attenuation compliance now functions as a non-negotiable procurement filter across US commercial gym chains. Amateur and youth segments exhibit the steepest specification adoption as parental safety concerns reshape purchase criteria.
- Punching Bags:Synthetic leather surfaces over compressed foam cores serve high-volume studio environments with predictable replacement schedules.
- Hand Wraps:Cotton-elastic blends with hook-and-loop closures address injury-prevention positioning among amateur participants.
Gloves sit at the top of the volume ranking, with hand wraps climbing the fastest.
End User:
Volume concentration patterns diverge sharply between institutional procurement and individual purchase behaviors.
- Gyms:Franchise operators in California and Texas negotiate outcome-based equipment refresh guarantees rather than transactional purchase terms, transferring inventory risk upstream to manufacturers with predictive maintenance capabilities.
- Fitness Enthusiasts:Boutique studio membership growth expands addressable buyer pools beyond traditional fight gyms, with amateur participants prioritizing orthopedic-recommended wrap systems.
- Athletes:Competition-grade specification requirements limit supplier options to certified manufacturers with established testing protocols.
- Trainers:Individual practitioners maintain smaller equipment portfolios with emphasis on multi-purpose durability.
Gyms dominate current procurement volume, with fitness enthusiasts expanding most quickly.
Material:
Raw material hierarchies are compressing as synthetic alternatives replicate performance characteristics at lower unit costs.
- Synthetic:Advanced microfiber outer shells distribute force across anatomical surfaces while withstanding repetitive shear loads, enabling price-tier expansion into amateur segments previously served by leather.
- Leather:Premium hand-crafted Mexican products from Guadalajara-based workshops depend on finite artisan capacity that constrains volume expansion.
- Foam:Multi-density laminates consolidate protective performance standards and marginalize single-density suppliers.
- Cotton:Elastic-cotton blends serve hand wrap applications with emphasis on breathability and wash durability.
Synthetic materials lead current production volume, with foam formulations gaining share fastest.
Price Tier:
Margin pools concentrate where durability claims justify elevated price points above mass-market alternatives.
- Premium:Certified impact-attenuation performance and heritage branding anchor shelf presence across North American sporting goods retailers, with validated protection metrics displacing heritage alone as the competitive differentiator.
- Mid-Range:Synthetic material innovation captures boutique studio procurement volumes that now rival established commercial gym channels.
- Luxury:Hand-crafted Mexican leather products serve collectors and professional bout specifications with supply constrained by artisan workshop capacity.
- Budget:Mass-market synthetic alternatives serve entry-level participants with compressed margin structures.
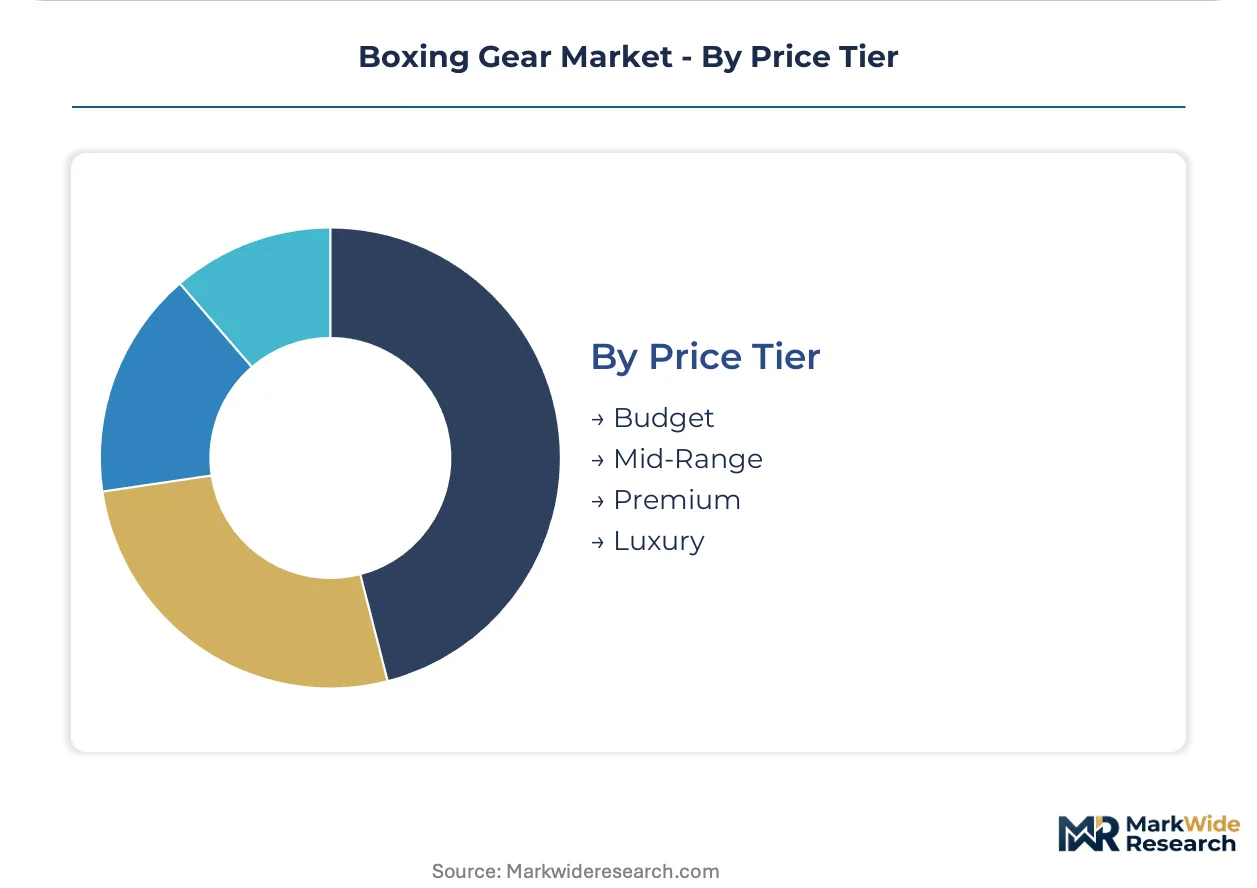
Mid-Range captures the largest addressable buyer pool, with Premium climbing fastest on certification-driven procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's professional bout certification requirements generate stricter compliance burdens than Thailand's dual-standard Muay Thai protocols, yet both markets reward manufacturers with established testing partnerships.
United States
ASTM International impact-attenuation standards for headgear create durable procurement filters across commercial gym chains. The US Consumer Product Safety Commission maintains active enforcement of youth segment safety mandates. Los Angeles and New York City boutique studio clusters drive recurring equipment refresh cycles with outcome-based contractual terms.
Mexico
NOM specifications for professional competition gloves sustain premium pricing for certified manufacturers serving bout-sanctioned events. The national standards body maintains lengthy approval timelines that delay product launches. Guadalajara-based artisan workshops constrain volume expansion for hand-crafted leather glove production.
Thailand
Muay Thai's international expansion generates demand for gear meeting both domestic competition standards and export market import requirements. The national boxing commission regulates equipment specifications for stadium-sanctioned events. Bangkok industrial zones concentrate synthetic material processing for mid-range glove production.
United Kingdom
Fitness studio proliferation in London and Manchester expands addressable buyer pools beyond traditional fight gyms. The British Boxing Board of Control mandates competition-grade specifications for licensed bouts. Midlands manufacturing clusters supply synthetic leather components to European distribution networks.
Japan
Amateur participation growth reshapes purchase criteria toward orthopedic-recommended injury-prevention systems. The Japan Boxing Commission enforces strict equipment standards for professional tournaments. Osaka-based suppliers specialize in microfiber outer shell technology for regional market distribution.
Boxing Gear Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base spans heritage brands with century-old equity, synthetic material innovators, and premium authenticity-positioned fight-sport specialists. Three archetypes dominate: certification-anchored incumbents, cost-optimized synthetic producers, and artisan-crafted luxury suppliers. Competitive moves concentrate on direct-to-studio distribution bypasses and predictive maintenance capability investments.
Among heritage-anchored specialists, Everlast Worldwide Inc. and Industrias Cleto Reyes S.A. de C.V. exemplify divergent geographic positioning strategies. Everlast occupies a position tied to North American retail shelf presence, while Cleto Reyes represents the artisan-capacity-constrained Mexican luxury tier. Synthetic-focused competitors include RDX Sports Ltd. and Hayabusa Fightwear Inc., both sitting within the innovation-driven mid-range segment where advanced material replication enables price-tier expansion.
| Leading Market Players |
|---|
| Ringside, Inc. |
| Hayabusa Fightwear Inc. |
| Everlast Worldwide Inc. |
| Venum Group |
| RDX Sports Ltd. |
| Adidas AG |
| Title Boxing LLC |
| Industrias Cleto Reyes S.A. de C.V. |
| Century LLC |
| Others |
Value Chain & Pricing Dynamics
Backward integration into foam formulation and synthetic leather production anchors margin control for manufacturers serving ASTM-certified headgear segments. This upstream control over multi-density laminate R&D and microfiber shell sourcing simultaneously insulates pricing power against petrochemical volatility and enables tiered positioning across amateur and competition-grade buyer pools.
Pricing Analysis
Capacity additions in Bangkok's industrial zones are reshaping price floors for mid-range synthetic glove production. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and impact-attenuation performance metrics. Price differentiation hinges on ASTM compliance status and artisan-crafted Mexican leather provenance. Cost compression in budget synthetic tiers is intensifying because microfiber replication advances compress traditional leather premiums, while boutique studio buyers exhibit lowest price sensitivity due to outcome-based refresh guarantee structures.
Supply Chain Analysis
Polymer feedstock supply rests on Thai petrochemical processors and Chinese synthetic fiber manufacturers for microfiber outer shell production. Guadalajara-based artisan workshops and Osaka specialty suppliers anchor premium leather and advanced foam laminate inputs. Single-source vulnerability concentrates in NOM-certified competition glove approval pathways that delay product launches. Distribution runs through direct-to-studio channels bypassing traditional sporting goods retailers for franchise operator procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Boxing gear functions as a regulatory compounder where ASTM International headgear standards enforcement creates durable demand for certified manufacturers with established testing protocols.
For Market Incumbents: Extend certification portfolio breadth into dual-standard Muay Thai competition lines before Thailand regulatory alignment hardens. Deepen captive supply of multi-density foam formulations to offset polymer price volatility. Counter synthetic-focused entrants by anchoring shelf presence through heritage brand equity and predictive maintenance service bundles. For New Entrants and Emerging Players: ASTM International impact-attenuation standards in the United States open a window for white-space capture in orthopedic-recommended hand wrap systems marketed through physical therapy referral channels. Target California and Texas boutique studio clusters with subscription-based refresh programs. Penetrate amateur segments fastest through microfiber-based price-tier expansion below heritage brand premiums. For Investors and Strategic Acquirers: Roll-up economics work for certified mid-range manufacturers because ASTM compliance creates defensible moats against uncertified competitors. Five-to-ten year viability concentrates on manufacturers with dual NOM and Thai certification capabilities. Monitor state-level concussive injury liability rulings as the primary inflection signal for insurance-driven specification tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Studio Distribution Launch | Bypasses sporting goods retailer margin capture and builds recurring refresh revenue with franchise operators. |
| Dual Certification Investment | Unlocks Mexico professional bout and Thailand Muay Thai stadium-sanctioned event procurement channels. |
| Predictive Maintenance Capability Build | Supports outcome-based equipment guarantee contracts transferring inventory risk from boutique studios. |
| Microfiber Outer Shell R&D Expansion | Replicates horsehide performance at lower unit costs for amateur segment price-tier penetration. |
| Orthopedic Channel Partnership Program | Captures injury-prevention positioning through physical therapy referral networks for hand wrap systems. |
Study Parameters
Bottom-up boutique studio and commercial gym procurement modeling reconciled against top-down synthetic material and foam laminate production tracking forms the analytical core. Primary interviews with equipment procurement managers at franchise operators, foam formulation chemists, NOM certification consultants, and orthopedic physical therapists combined with secondary validation against ASTM International standards documentation, US Consumer Product Safety Commission enforcement records, and Mexican NOM specification filings.
Historical trendline analysis across glove refresh cycle frequencies and headgear compliance adoption curves established baseline growth parameters. Segmentation dimensions modeled include product type, end-user archetype, material composition, and price tier positioning across the projection horizon. CAGRs derived from equipment procurement volume trajectories and synthetic material cost curves, incorporating Muay Thai international expansion rates and amateur participation growth as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under petrochemical price spike conditions and accelerated state-level liability rulings. Forecasts reflect assumptions on ASTM enforcement continuity and NOM approval timeline stability. A small set of triggers—concussive injury litigation precedents, artisan workshop capacity constraints, and Thailand regulatory harmonization progress—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Boxing Equipment Market
Sports Equipment
Sports Mouthguard Market
Sports Equipment
Premium Bicycle Market
Sports Equipment
Synthetic Ice Skating Rink Market
Sports Equipment
Knee Pads Market
Sports Equipment
Licensed Sports Merchandise Market
Sports Equipment
Sports Devices Market
Sports Equipment
Concussion Helmets Market
Sports Equipment
Kung Fu Uniform Market
Sports Equipment
Balance Bike Market
Sports Equipment
Field Hockey Equipment Market
Sports Equipment
Sports Fishing Equipment Market
Sports Equipment
Trail Shoes Market
Sports Equipment
Global Badminton Equipment and Facilities Market
Sports Equipment
Golf Bags Market
Sports Equipment
GCC Running Gear Market