
 Dirt Bike Market | 2026-2036
Dirt Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Dirt Bike Market Analysis
Buyer concentration among amateur riders and recreational users is rebalancing as professional racing sponsorships narrow and weekend trail riding expands. Kawasaki leverages its manufacturing scale across multiple displacement categories to maintain broad dealer coverage. Yamaha anchors its position through deep channel control in North American specialty retail networks. Honda competes by sustaining R&D intensity in four-stroke engine refinement for emission-sensitive jurisdictions.
A dirt bike is a lightweight, knobby-tired motorcycle engineered for unpaved terrain, typically featuring long-travel suspension with 250-450mm of wheel travel, high ground clearance exceeding 300mm, and power-to-weight ratios optimized for loose surfaces. These machines serve competitive racing, trail exploration, and agricultural utility across commercial and consumer applications. The engine type dimension shows four-stroke units dominating mature markets while electric powertrains capture the fastest growth in jurisdictions with strict noise and emission limits. Within product type, motocross machines command premium pricing through specialized suspension and minimal street equipment, whereas trail bikes generate volume through broader usability.
EPA emission regulations in the United States restrict two-stroke engine sales and push OEMs toward cleaner four-stroke and electric architectures. The EU Green Deal and associated F-Gas Regulation constrain refrigerants and lubricants used in manufacturing, raising compliance costs for European-market units. ISO standards for motorcycle safety and performance provide baseline technical benchmarks accepted across multiple export destinations. Stakeholders must monitor how battery energy density improvements and charging infrastructure expansion reshape the competitive viability of electric dirt bikes against established combustion platforms.
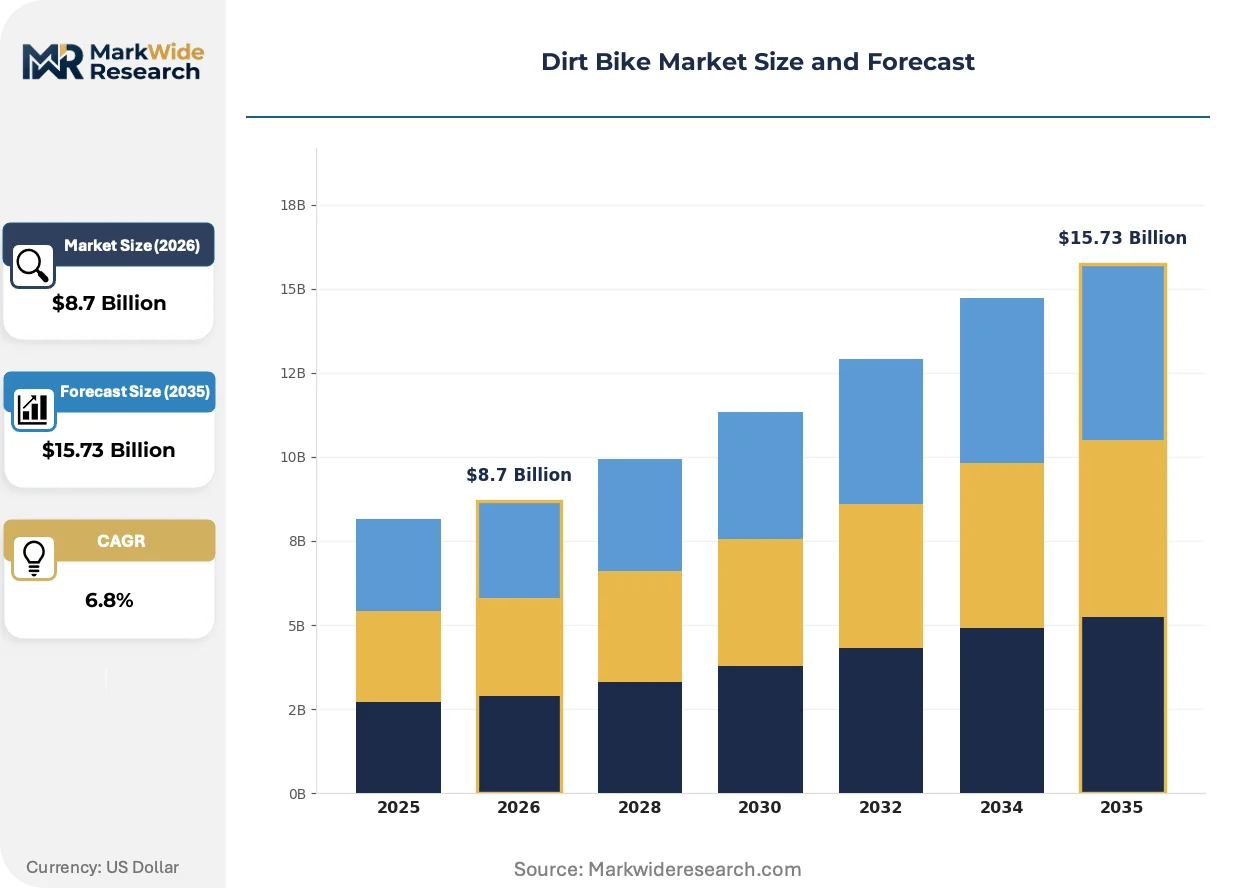
Market Dynamics
EPA emissions standards and the EU Green Deal are compressing two-stroke engine viability while battery energy density improvements accelerate electric powertrain substitution across recreational and competitive segments.
Growth Catalysts
- EPA Tier 4 and CARB standards:Regulatory pressure in the United States eliminates carbureted two-stroke engines from new sales, forcing OEMs to invest in cleaner four-stroke and electric architectures that attract environmentally conscious amateur riders.
- Weekend trail riding expansion:Recreational users in the United States are purchasing mid-displacement trail bikes at accelerating rates as dedicated off-road parks and forest service trail networks expand access.
- Lithium-ion cell cost curves:Falling battery pack economics enable electric dirt bike manufacturers to approach price parity with 250cc four-stroke machines in noise-restricted jurisdictions.
Market Restraints
- Rare earth magnet supply concentration:Permanent magnet motors for electric powertrains depend on Chinese-processed neodymium and dysprosium, creating geopolitical input vulnerability.
- Four-stroke engine weight penalties:Emission-compliant four-stroke architectures add 15-25 pounds versus legacy two-stroke equivalents, degrading handling characteristics in motocross competition.
- Trail access restrictions:U.S. Forest Service and Bureau of Land Management seasonal closures and sound-level ordinances limit ridable terrain in high-population western states.
Strategic Opportunities
- EU Green Deal battery passport requirements:European Union mandates for supply chain traceability create first-mover advantage for OEMs with vertically controlled cell sourcing and recycling partnerships.
- Agricultural utility applications:Ranch and farm operators in Australia and Brazil represent underserved demand for electric dirt bikes in livestock management and property maintenance roles.
- Direct-to-consumer digital sales:Bypassing traditional powersports dealer networks reduces margin compression and captures rider data for predictive maintenance subscription services.
Industry Challenges
- Powertrain calibration expertise scarcity:Electric motor control software and battery thermal management require skill sets rare in legacy combustion-engine engineering teams.
- ISO 6469-1 electrical safety certification:High-voltage system validation timelines extend product development cycles by 8-14 months versus conventional motorcycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dirt Bike Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motocross, Enduro, Trail, Mini-Bike Engine Type: Two-Stroke, Four-Stroke, Electric, Hybrid Customer Type: Amateur Riders, Professional Riders, Recreational Users, Trainers Distribution Channel: Online Retailers, Dealerships, Specialty Stores, Direct Sales |
| Companies Covered | Kawasaki, Beta, Honda, Fantic, Husqvarna, Yamaha, Suzuki, Sherco, KTM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dirt Bike Market Emerging Trajectories
Powertrain electrification, regulatory compliance automation, and shifting rider acquisition channels are restructuring competitive advantage away from engine displacement hierarchies toward software-defined performance and subscription-enabled ownership models.
Silicon carbide MOSFETs in motor controllers are rewriting thermal efficiency benchmarks for electric dirt bikes, enabling sustained peak power output previously unattainable with silicon-based inverters. Amateur racers in California and Colorado are adopting these machines for closed-course competition despite higher upfront acquisition costs. The technology is rewriting the traditional correlation between engine displacement and competitive tier classification, compressing the performance hierarchy that organized product lineups for decades.
The EU F-Gas Regulation constrains fluorinated greenhouse gas use in manufacturing processes, raising compliance costs for European-market units and accelerating relocation of final assembly to jurisdictions with less stringent process emissions oversight. OEMs serving EU member states must now document refrigerant and solvent usage across supplier tiers. Motocross-focused product lines face the steepest cost adjustments due to specialized lubricant and surface treatment requirements.
Subscription-based battery leasing is displacing outright powertrain ownership among urban recreational riders who lack residential charging infrastructure. Specialty retailers in Germany and the Netherlands are piloting swap-station networks that separate vehicle purchase from energy procurement. This model concentrates most visibly in metropolitan areas where apartment-dwelling riders constitute the fastest-expanding buyer segment.
Dirt Bike Market Segmentation
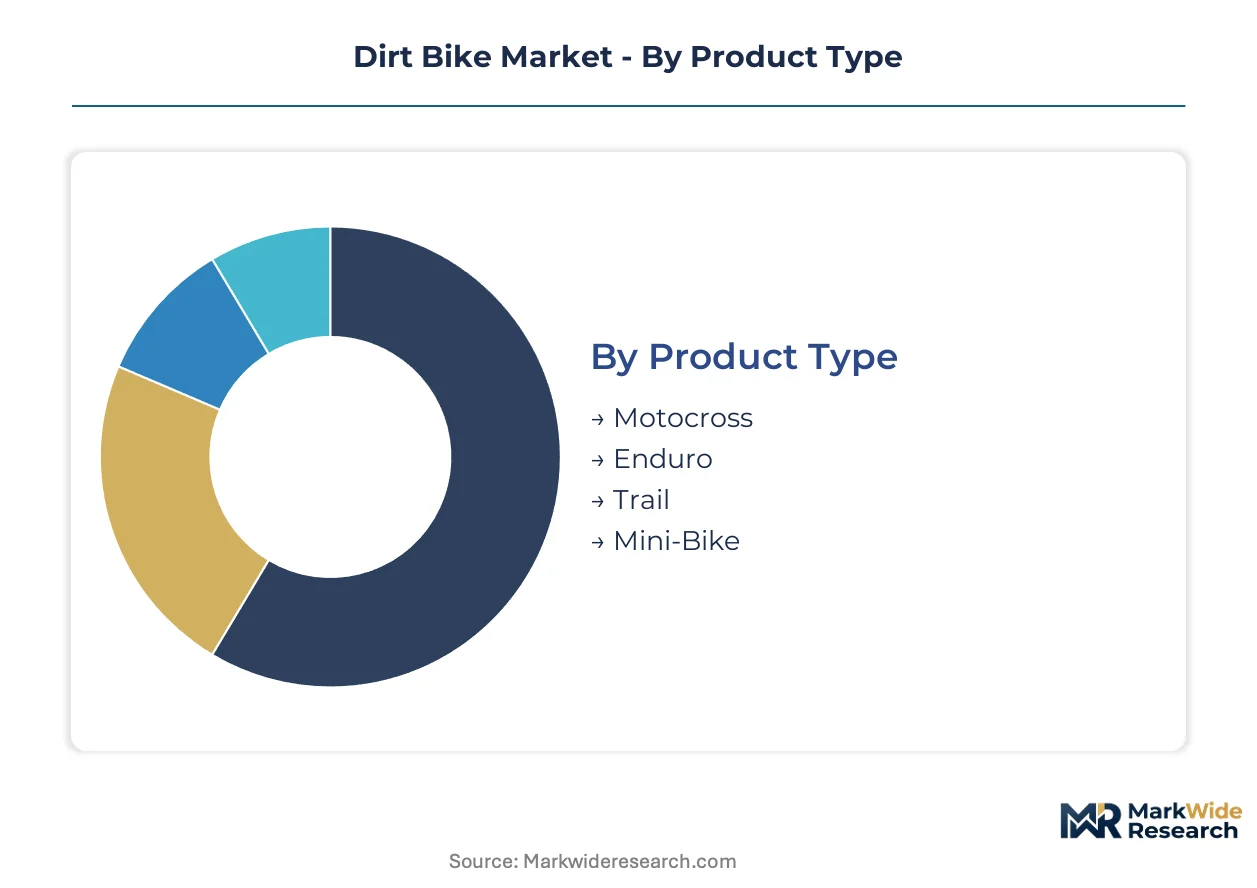
Dirt bike segmentation reveals how regulatory pressure and rider specialization fragment manufacturing priorities. Certification requirements vary sharply across engine architectures and competitive use cases, forcing OEMs to maintain parallel development tracks.
Product Type:
EPA Tier 4 and EU F-Gas Regulation impose divergent compliance burdens: motocross machines face sound-level ordinances and closed-course exemptions, while trail bikes navigate forest service access permits and agricultural equipment classifications.
- Motocross:Purpose-built machines with 310-450mm suspension travel and minimal street equipment dominate closed-course competition. Amateur racing circuits in California and Colorado drive demand despite CARB emission restrictions limiting two-stroke eligibility.
- Trail:Softer suspension tuning and EPA-compliant four-stroke engines expand ridable terrain across U.S. Forest Service networks. Weekend recreational users in the United States purchase these units at accelerating rates as dedicated off-road parks multiply.
- Enduro:Street-legal lighting and emission systems add regulatory complexity for dual-surface use.
- Mini-Bike:Displacement-restricted youth machines face parental safety certification requirements in most jurisdictions.
Leading the category by volume: Trail. Growing fastest: Motocross.
Engine Type:
Cost tier stratification separates premium electric powertrains from economy two-stroke remnants, with four-stroke architectures occupying the contested middle ground where battery energy density improvements threaten displacement-based pricing hierarchies.
- Four-Stroke:Emission-compliant architectures with dual overhead camshafts and fuel injection now dominate mature markets. Honda sustains R&D intensity in this segment to satisfy EPA requirements while preserving power-to-weight ratios for competitive riders.
- Electric:Silicon carbide MOSFET controllers and lithium-ion cell cost curves enable sustained peak output previously unattainable. Riders in noise-restricted German and Dutch metropolitan areas adopt battery leasing models to bypass residential charging limitations.
- Two-Stroke:Carbureted designs face effective prohibition under EPA Tier 4 and CARB standards.
- Hybrid:Range-extender architectures remain experimental with minimal commercial deployment.
Four-stroke units anchor current revenue. Electric architectures gain share fastest in jurisdictions with strict noise ordinances.
Customer Type:
Application focus distinguishes competitive racing investments from utility-oriented purchases, with amateur riders requiring financing accessibility and professional riders demanding factory-supported technical programs.
- Amateur Riders:Weekend competitors and club-level racers purchasing 250-450cc machines represent the volume foundation. This segment expands as dedicated off-road parks reduce barriers to entry in the United States.
- Recreational Users:Trail exploration and casual riding without competition licensing drives mid-displacement purchases. Forest service trail network expansion in western U.S. states concentrates demand geographically.
- Professional Riders:Factory-sponsored athletes with specialized technical support requirements.
- Trainers:Coaching professionals operating fleet vehicles for instruction programs.
Amateur riders generate the highest unit volumes. Recreational users expand most quickly as trail access improves.
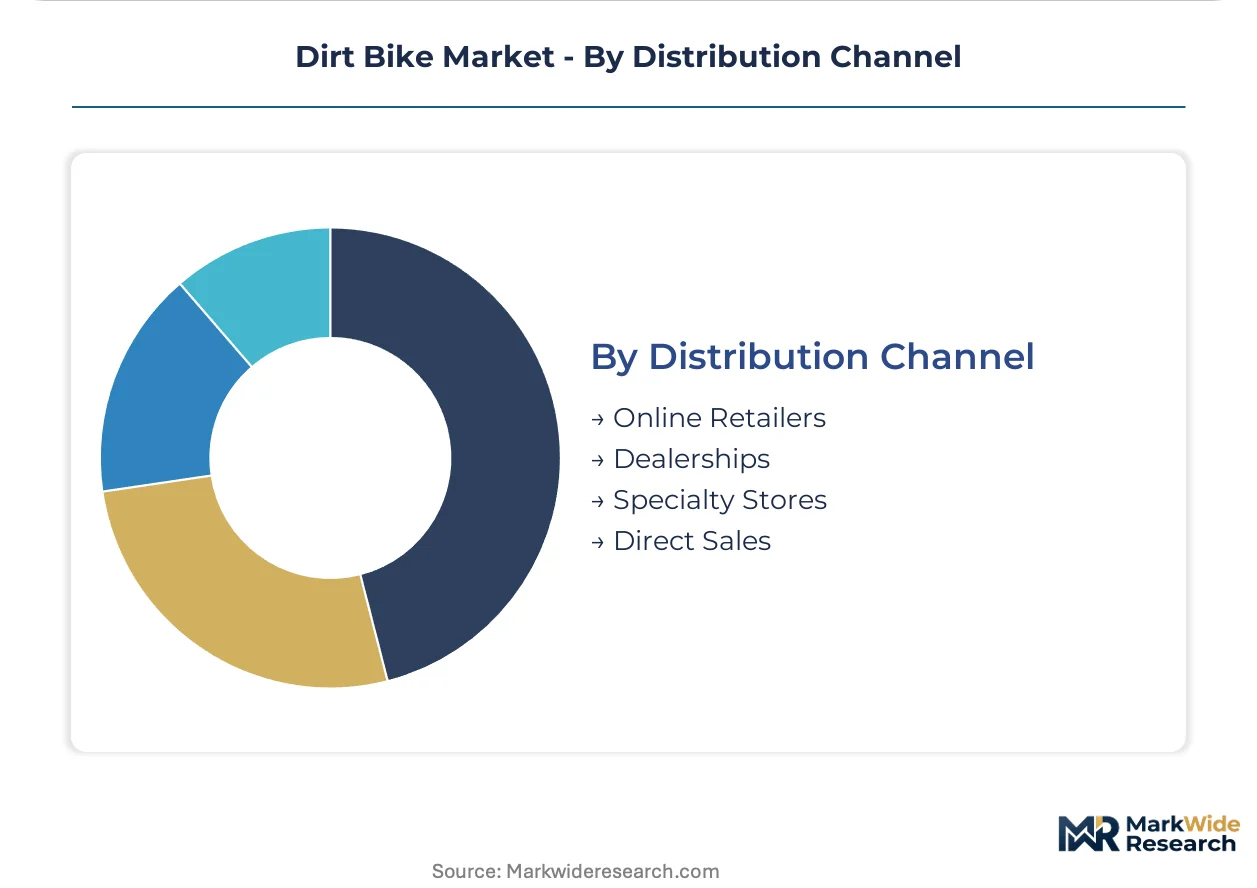
Distribution Channel:
Geography determines channel viability: rural markets sustain dealership networks while urban concentration enables direct-to-consumer digital models with subscription maintenance services.
- Dealerships:Full-service powersports retailers with factory-authorized service bays dominate warranty-eligible transactions. Yamaha anchors its competitive position through deep channel control in North American specialty retail networks.
- Specialty Stores:Off-road-focused retailers with terrain-specific expertise and demo fleet operations. These outlets capture enthusiast buyers seeking technical consultation unavailable through generalist channels.
- Online Retailers:Digital platforms with drop-shipping arrangements bypass inventory carrying costs.
- Direct Sales:Manufacturer-controlled transactions capturing rider data for predictive maintenance subscriptions.
Dealerships maintain volume leadership. Direct sales channels climb fastest as OEMs pilot battery-leasing models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recreational demand clusters most densely in the United States, where trail network expansion and amateur racing circuits concentrate purchasing power. Regulatory divergence between EPA Tier 4 standards and EU F-Gas compliance is fragmenting manufacturing footprints across export destinations.
United States
Weekend trail riding in California and Colorado drives accelerating purchases of mid-displacement machines as Forest Service access permits expand ridable terrain. EPA Tier 4 and CARB standards eliminate carbureted two-stroke eligibility, forcing OEMs toward four-stroke and electric architectures. Southern California's motocross circuit concentration anchors competitive racing demand despite noise ordinance restrictions in Orange County and Riverside jurisdictions.
Germany
Metropolitan riders in Berlin and Munich adopt battery-leasing models to bypass residential charging limitations for electric powertrains. The EU F-Gas Regulation and EU Green Deal battery passport requirements raise compliance costs for European-market assembly. Bavaria's specialty retail networks pilot swap-station infrastructure separating vehicle purchase from energy procurement.
Australia
Ranch and farm operators in Queensland and New South Wales generate underserved demand for electric dirt bikes in livestock management applications. The country's national environmental regulator constrains two-stroke emissions in sensitive watershed zones. Sydney's powersports distribution clusters concentrate import logistics for Asia-Pacific regional re-export.
Japan
Domestic manufacturers anchor engineering expertise in four-stroke engine refinement for emission-sensitive export markets. METI industrial standards and JIS certification requirements structure product development timelines for high-voltage electrical systems. The Nagoya industrial corridor concentrates precision machining capacity for suspension component supply to global OEMs.
Brazil
Agricultural utility applications in São Paulo and Minas Gerais states expand addressable market beyond recreational segments. ANVISA equipment classification frameworks and import tariff structures shape competitive positioning for foreign manufacturers. The São Paulo metropolitan area's dealer networks dominate Latin American distribution reach for premium displacement categories.
Dirt Bike Market Vendor Landscape
Japanese producers anchor one tier with manufacturing scale across multiple displacement categories; European specialists hold premium positioning through motocross-focused engineering depth. The vendor base fragments between volume-driven full-line manufacturers and single-purpose racing fabricators. Two strategic archetypes dominate: vertically integrated engine builders with captive component supply, and niche assemblers sourcing suspension and powertrain from tier-one suppliers. Competitive moves concentrate on direct-to-consumer digital channel expansion and battery-leasing subscription pilots.
Within the Japanese manufacturing tier, Kawasaki, Honda, and Yamaha exemplify scale-driven competitive positioning through broad dealer coverage and multi-category production efficiency. KTM and Husqvarna occupy the European specialist archetype with concentrated motocross pedigree and limited displacement range focus. These five names represent the structural split between volume-market anchoring and premium-segment specialization that defines current competitive dynamics.
| Leading Market Players |
|---|
| Kawasaki |
| Beta |
| Honda |
| Fantic |
| Husqvarna |
| Yamaha |
| Suzuki |
| Sherco |
| KTM |
| Others |
Supply Flow & Price Mechanics
EPA Tier 4 and CARB compliance mandates in the United States are forcing amateur riders toward four-stroke and electric architectures, compelling OEMs to absorb battery cell cost premiums and specialized component sourcing that compresses margins on mid-displacement trail bikes. This demand-side specification shift concentrates pricing power with suppliers of emission-compliant powertrains and silicon carbide motor controllers.
Pricing Analysis
Volume leadership in trail bikes generates thin margins through dealer network dependencies, while motocross machines capture premium returns via limited-production factory editions and racing-derived suspension technology. Three-tier pricing structure across premium, standard, and economy levels stratifies by engine displacement, certification grade for EPA/CARB compliance, and factory technical support inclusion. Cost compression in electric powertrains is intensifying because lithium-ion cell economics approach parity with 250cc four-stroke machines. Amateur riders exhibit highest price sensitivity, whereas professional racing teams prioritize performance specifications over acquisition cost.
Supply Chain Analysis
ISO 6469-1 electrical safety certification and EPA emission compliance create qualification gates that filter component suppliers and extend validation timelines. Manufacturing concentrates in Japan, Austria, and the United States for precision engine machining and suspension component fabrication. Permanent magnet motors draw from Chinese-processed neodymium and dysprosium, with rare earth supply concentration creating single-source vulnerability. Distribution runs through factory-authorized powersports dealerships with captive service bays, though direct-to-consumer digital channels are displacing traditional retail for electric powertrain sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
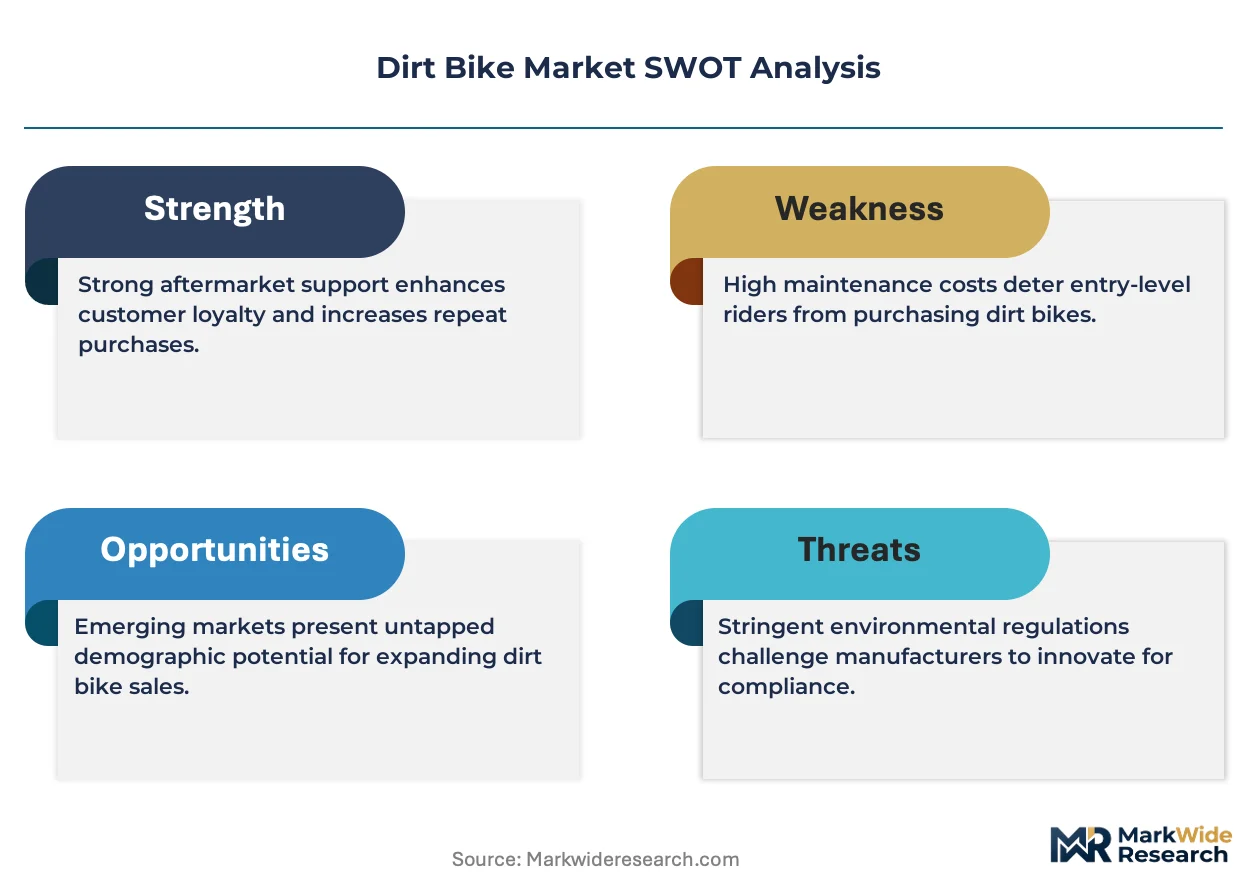
Consolidation pressure from EPA emission compliance and battery supply chain qualification requirements will eliminate smaller assemblers lacking capital for certification investment and vertical component control.
For Market Incumbents: Hedge against rare earth supply disruption by securing alternative magnet chemistry partnerships or backward integration into cell sourcing. Defensive consolidation moves include acquiring specialty suspension suppliers in the Nagoya industrial corridor and deepening dealer service bay penetration in California and Colorado to lock in amateur rider loyalty against electric entrants. Battery thermal management expertise represents the critical capability gap requiring immediate R&D allocation. For New Entrants and Emerging Players: EU Green Deal battery passport requirements in Germany and the Netherlands open a window for vertically integrated electric powertrain specialists with documented cell provenance. White-space targets include agricultural utility applications in Queensland and São Paulo states, plus battery-leasing subscription models for metropolitan apartment-dwelling riders lacking residential charging. Go-to-market execution should prioritize direct digital sales bypassing legacy dealer networks. For Investors and Strategic Acquirers: The window for entry favors mid-cap electric powertrain developers with captive battery recycling partnerships and ISO 6469-1 certification completion. Long-term viability hinges on five-to-ten year technology transition timelines as emission regulations tighten. Acquisition screening should prioritize firms with silicon carbide controller design capability and documented EU supply chain traceability. The inflection signal to monitor is EPA announcement of Tier 5 emission standards accelerating two-stroke phase-out.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Passport Compliance Program | EU Green Deal traceability mandates create first-mover certification advantage for European-market assembly. |
| Silicon Carbide Controller Integration | Thermal efficiency gains from SiC MOSFETs enable sustained peak power output for competitive electric motocross. |
| Direct-to-Consumer Digital Launch | Bypassing dealer networks captures rider data for predictive maintenance subscription revenue streams. |
| Rare Earth Alternative Sourcing | Reducing neodymium dependency hedges against Chinese supply concentration in permanent magnet motors. |
| Agricultural Utility Product Line | Ranch and farm operators in Australia and Brazil represent underserved demand beyond recreational segments. |
Methodological Framework
Trade association filings, EPA certification databases, and EU F-Gas Regulation compliance records formed the secondary backbone, supplemented by customs data on powersports equipment imports. Primary fieldwork engaged OEM platform engineers, Tier 1 suspension suppliers, specialty retail buyers, and amateur racing circuit operators across California, Colorado, and Bavaria. Bottom-up unit shipment analysis triangulated against top-down revenue estimates from manufacturer financial disclosures.
Bottom-up modeling aggregated displacement-category volumes across motocross, trail, enduro, and mini-bike segments, while top-down validation cross-referenced regional registration data and Forest Service access permit trends. Segmentation dimensions included engine architecture, competitive use case, customer application focus, and distribution channel structure. CAGRs were derived from regression analysis of historical shipment patterns against regulatory phase-in schedules and battery cost curve projections. Forecast inputs incorporated lithium-ion cell pricing trajectories and trail network expansion timelines in western U.S. states.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook for electric powertrain penetration timelines. Forecasts reflect assumptions regarding EPA enforcement consistency and EU battery passport implementation schedules. A model refresh is warranted upon material change in rare earth export restrictions or EPA announcement of subsequent emission tier standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
United States Archery Equipment Market
Sports Equipment
Global Rock Climbing Equipment Market
Sports Equipment
Turbo Trainer Market
Sports Equipment
Bicycle Crankset Market
Sports Equipment
Kickboxing Equipment Market
Sports Equipment
Field Hockey Equipment Market
Sports Equipment
Gymnastic Bars Market
Sports Equipment
Boxing Gear Market
Sports Equipment
US Sports Flooring Market
Sports Equipment
Global Pickleball Equipment Market
Sports Equipment
Global Sports Sunglasses Market
Sports Equipment
Europe Winter Sports Equipment Market
Sports Equipment
Fishing Rods Market
Sports Equipment
Global Golf Rangefinders Market
Sports Equipment
GCC Running Gear Market
Sports Equipment
Synthetic Ice Skating Rink Market