
 Cycling Sunglasses Market | 2026-2036
Cycling Sunglasses Market Size, Share, and Industry Trends Forecast 2026-2036
Cycling Sunglasses Market Analysis
The capital-intensity gap between premium lens manufacturers and mass-market assemblers is collapsing as in-house coating capabilities become table stakes. Oakley leverages proprietary Prizm lens technology to sustain pricing power across professional cycling teams. Rudy Project competes through Italian-designed interchangeable lens systems that anchor its triathlon and road racing presence. Uvex Sports dominates European regulatory certification processes, extending its occupational safety heritage into performance cycling eyewear.
Cycling sunglasses are impact-resistant eyewear engineered with polycarbonate or nylon frames and interchangeable, photochromic, polarized, or non-polarized lenses, typically meeting ANSI Z87.1 or EN 166 impact standards, designed to shield riders from UV radiation, wind debris, and variable light conditions during high-speed riding. Photochromic lenses lead unit growth as riders seek single-lens solutions for dawn-to-dusk training sessions, while polarized variants command margin pools among coastal and alpine cycling tourism operators. Specialty stores retain the highest conversion rates for fitted premium frames, though online retail captures volume in replacement lens and accessory categories.
FDA regulates impact claims and UV protection labeling for eyewear sold in the United States, while the EU Green Deal and REACH frameworks constrain chemical use in frame coatings and lens dyes across European supply chains. CE marking under the EU's Personal Protective Equipment directive shapes market access for cycling sunglasses positioned with safety-grade impact resistance. Stakeholders must monitor evolving extended producer responsibility rules for plastic frames and the pace at which photochromic chemistry patents expire in Asian manufacturing jurisdictions.
Market Dynamics
Photochromic lens chemistry patents are expiring across Asian manufacturing jurisdictions, collapsing the capital barrier between premium coating specialists and mass-market frame assemblers. This patent cliff is redistributing margin pools from proprietary technology holders toward integrated producers with captive polymer processing capabilities.
Growth Catalysts
- REACH framework compliance:European chemical safety mandates under REACH and the EU Green Deal are accelerating substitution of petroleum-based frame polymers with bio-derived nylon alternatives, opening certification premiums for early adopters.
- Amateur racing participation:Competitive amateur road cycling events are expanding across Germany, Belgium, and the Netherlands, creating fitted-eyewear demand through specialty retail channels that emphasize prescription compatibility and aerodynamic frame geometry.
- Photochromic chemistry:Advances in silver halide and naphthopyran dye stability are extending lens darkening cycle lifespans, reducing replacement frequency while improving dawn-to-dusk training utility for endurance cyclists.
Market Restraints
- Polycarbonate resin concentration:Optical-grade polycarbonate supply concentrates among three Asian petrochemical conglomerates, exposing frame manufacturers to feedstock price volatility and force majeure disruption risk.
- CE marking complexity:The EU Personal Protective Equipment directive's impact testing protocols create six-to-nine month certification timelines that freeze product launch cycles for safety-positioned eyewear entrants.
- Contact lens substitution:Daily disposable silicone hydrogel lenses combined with generic impact-resistant frames are capturing price-sensitive recreational cyclists, compressing volume in the sub-premium sunglass tier.
Strategic Opportunities
- Indian market underpenetration:India's Bureau of Indian Standards has yet to mandate cycling-specific impact standards, creating first-mover advantage for brands establishing localized assembly ahead of anticipated BIS regulatory expansion.
- Gravel cycling emergence:Mixed-terrain racing formats are generating demand for photochromic-polarized hybrid lenses that address variable canopy coverage and reflective surface glare simultaneously.
- Extended producer responsibility:The EU's evolving plastic frame take-back mandates are creating service-revenue streams for brands with reverse logistics infrastructure and chemical recycling partnerships.
Industry Challenges
- Optical metrology talent scarcity:Precision lens curvature measurement and aberration correction expertise concentrates among German and Japanese equipment specialists, constraining quality scale-up for new market entrants.
- Multi-standard compliance:Simultaneous ANSI Z87.1, EN 166, and AS/NZS 1337.1 certification requirements fragment testing budgets and delay unified product platform launches across North American, European, and Oceanian markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cycling Sunglasses Market |
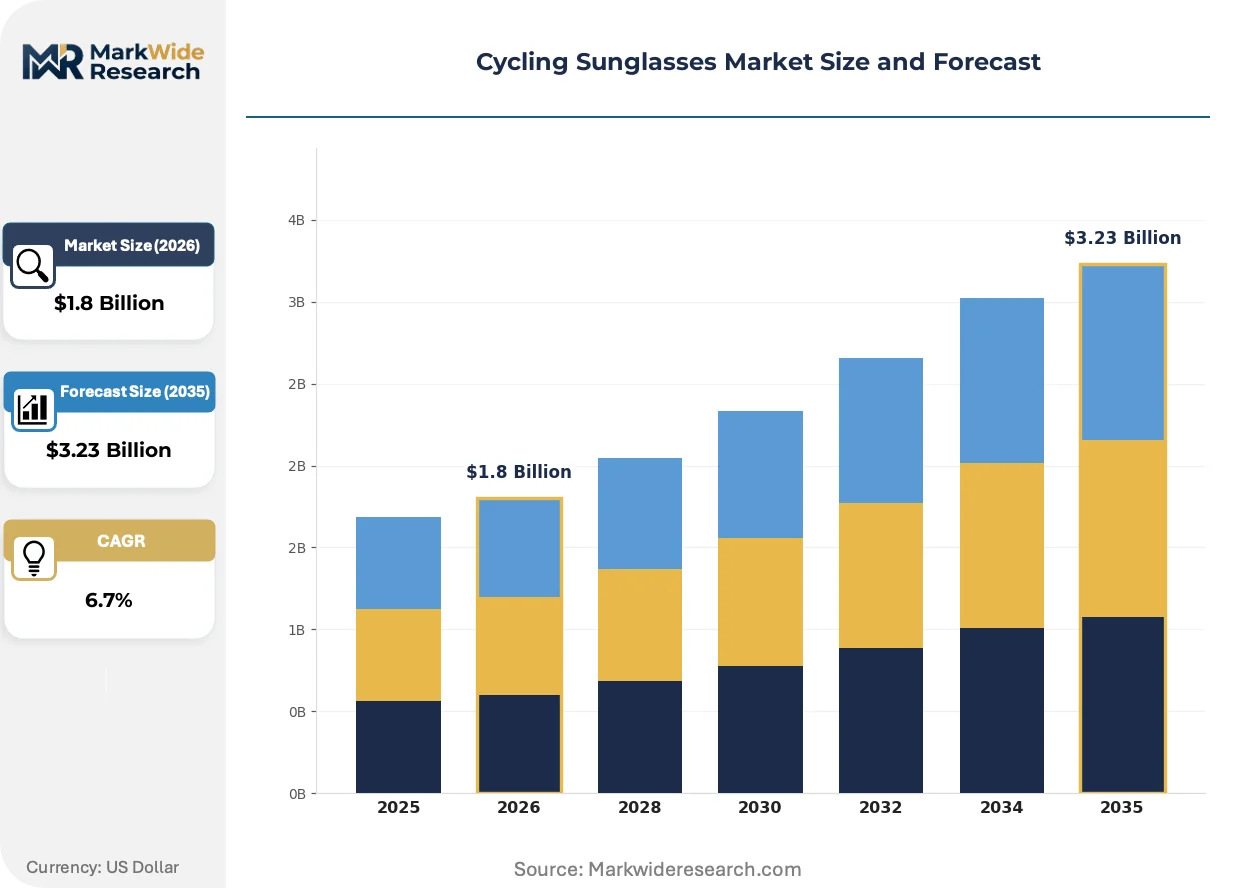
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interchangeable Lenses, Photochromic, Polarized, Non-Polarized Material: Plastic, Nylon, Polycarbonate, Glass Feature: UV Protection, Scratch Resistance, Anti-Fog, Lightweight Distribution Channel: Online Retail, Specialty Stores, Mass Merchants, Direct Sales |
| Companies Covered | Oakley, Nike Vision, Adidas Eyewear, Rudy Project, Uvex Sports, Under Armour, Smith Optics, POC Sports, Shimano, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cycling Sunglasses Market Emerging Trajectories
Functional integration between lens chemistry and frame architecture is displacing modular replacement-lens systems as the dominant product architecture. Manufacturers are embedding photochromic and polarization layers directly into substrate manufacturing rather than applying them as secondary coatings.
Photochromic molecular engineering is decomposing the historical trade-off between transition speed and optical clarity. Road cycling teams and competitive amateur associations are specifying sub-30-second darkening response times for training eyewear. This specification compression is collapsing the performance gap between single-lens solutions and multi-lens interchangeable systems, eroding the aftermarket replacement lens revenue model that sustained specialty retailers.
REACH authorization requirements for chromium-based anti-reflective coatings are forcing reformulation of lens stack architectures across European supply chains. Manufacturers serving the German and Benelux markets are migrating to sol-gel silica alternatives that satisfy ECHA substance restrictions. Premium positioning now requires explicit disclosure of coating chemistry, with safety-grade cycling eyewear carrying extended technical datasheets previously associated with industrial PPE.
Specialty retail conversion is fragmenting as direct-to-consumer prescription integration platforms capture fitted-frame volume. Cycling clubs and event organizers are emerging as curated purchasing channels, negotiating group pricing for members and distributing fitted eyewear through mobile optometry services at race expos. This channel displacement is most visible in France and Italy, where regional cycling federations maintain dense membership networks and sponsor compliance requirements create uniform eyewear mandates.
Cycling Sunglasses Market Segmentation
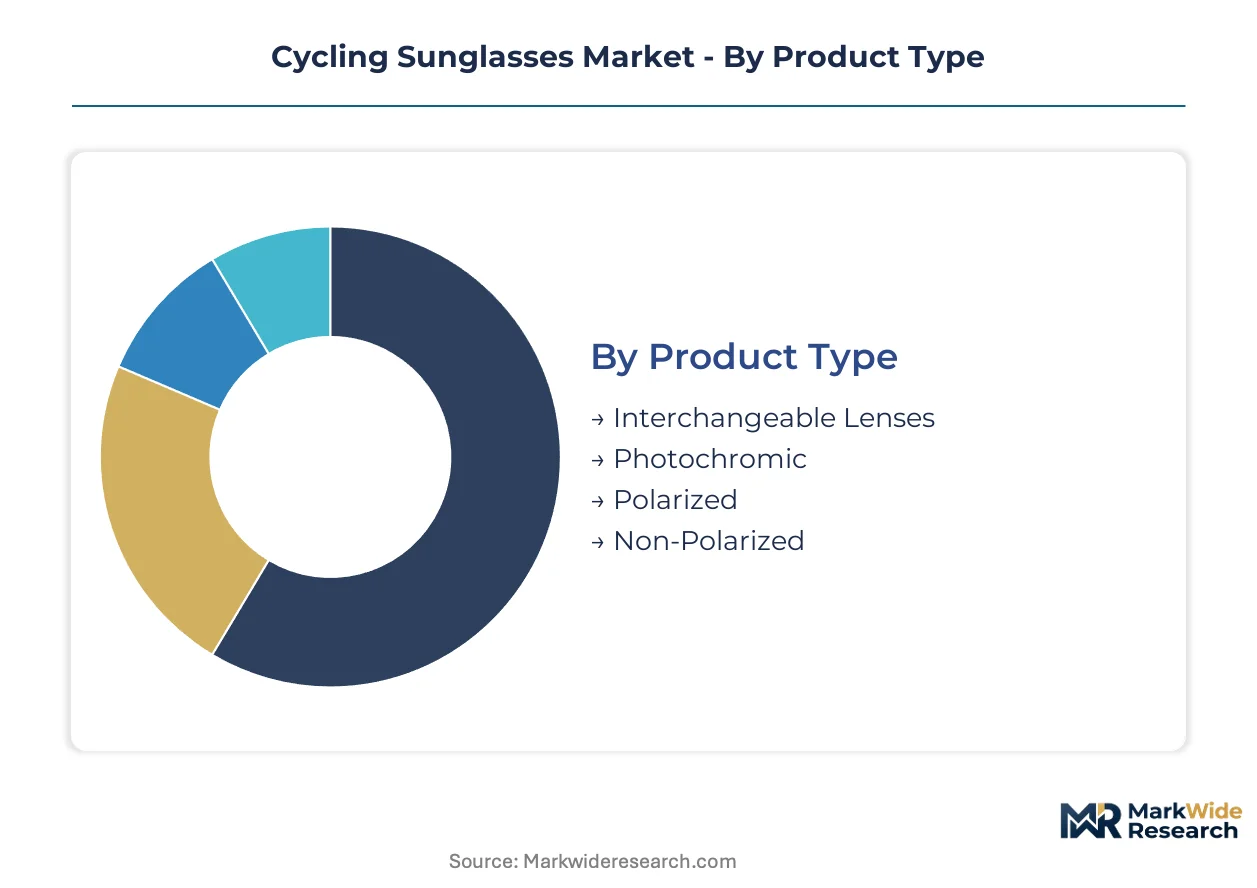
Segmentation in cycling sunglasses reveals how lens technology, frame materials, and retail channels align with distinct rider profiles from competitive amateurs to recreational tourists. Manufacturers calibrate product architecture and pricing tiers against these divisions to capture margin pools across specialty retail, direct-to-consumer platforms, and event-based distribution.
Product Type:
Channel mix varies sharply by lens technology: photochromic variants dominate specialty store conversions due to fitting complexity, while interchangeable systems capture volume through online replacement lens sales.
- Photochromic:Silver halide and naphthopyran dye systems embedded in substrate manufacturing enable single-lens dawn-to-dusk utility. Demand concentrates among German and Belgian road cyclists undertaking multi-hour training sessions where light conditions shift continuously.
- Interchangeable Lenses:Modular lens systems with snap-fit retention mechanisms allow riders to swap tints mid-ride. Italian-designed platforms anchor triathlon and stage racing presence where athletes prioritize rapid adaptation over automated transitions.
- Polarized:Coastal and alpine cycling tourism operators specify these for reflective surface glare management.
- Non-Polarized:Entry-level road and commuter segments favor these for LCD screen visibility and lower price points.
By volume, interchangeable systems lead due to aftermarket replacement cycles. By growth pace, photochromic lenses are expanding most quickly as patent cliffs democratize coating capabilities.
Material:
Cost tier stratification runs from petroleum-derived polymers at economy levels to bio-nylon and precision-molded compounds commanding certification premiums.
- Polycarbonate:Optical-grade resin meeting ANSI Z87.1 impact standards dominates performance cycling with superior strength-to-weight ratios. German manufacturing clusters source from Asian petrochemical supply chains, exposing frame producers to feedstock volatility.
- Nylon:Bio-derived alternatives from castor oil feedstocks are gaining REACH-compliant positioning for European markets. Italian and German brands leverage these for premium sustainability claims.
- Plastic:Standard petroleum-based polymers serve price-sensitive recreational segments.
- Glass:Mineral lenses retain niche presence among vintage-styled urban cycling segments prioritizing optical clarity over impact resistance.
By installed base, polycarbonate frames dominate. By margin expansion, bio-nylon alternatives show the steepest trajectory as ECHA restrictions tighten.
Feature:
Application context determines feature prioritization: competitive racing emphasizes aerodynamic lightweighting, while commuter and touring segments weight UV and anti-fog specifications.
- UV Protection:FDA-regulated labeling requirements for UVA/UVB blocking claims create compliance differentiation in US markets. Premium positioning requires explicit wavelength coverage disclosure.
- Lightweight:Sub-30-gram frame targets specified by professional teams drive carbon-reinforced polymer development and titanium hinge integration.
- Anti-Fog:Hydrophilic interior coatings address high-exertion climbing and variable temperature transitions.
- Scratch Resistance:Sol-gel silica alternatives to chromium-based coatings satisfy REACH authorization constraints.
By specification frequency, UV protection is universal. By upgrade willingness, lightweight frames command the highest price elasticity among competitive amateurs.
Distribution Channel:
Geography shapes channel performance: dense cycling club networks in France and Italy favor event-based direct sales, while German markets sustain specialty retail through prescription integration services.
- Specialty Stores:Fitted-frame expertise and prescription compatibility drive conversion for premium road racing eyewear. Mobile optometry services at Belgian and Dutch race expos extend this channel's reach.
- Online Retail:Replacement lens and accessory categories capture volume through direct-to-consumer platforms, eroding aftermarket revenue historically retained by physical retailers.
- Direct Sales:Cycling clubs and regional federations negotiate group pricing, creating uniform eyewear mandates through sponsor compliance requirements.
- Mass Merchants:Generic impact-resistant frames serve price-sensitive recreational cyclists facing contact lens substitution pressure.
By transaction volume, online retail leads. By customer lifetime value, specialty stores with prescription services show the strongest retention metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies: German buyers absorb premium pricing for prescription-integrated frames while price-sensitive recreational cyclists in India and Brazil gravitate toward generic alternatives. Belgium and the Netherlands occupy a middle position where club-organized group purchasing moderates individual cost burdens.
Germany
Road racing participation and cycling infrastructure investment sustain premium eyewear demand across amateur competitive segments. REACH authorization requirements for frame coatings and lens dyes constrain chemical formulations, pushing manufacturers toward bio-derived nylon alternatives. Manufacturing clusters in the Munich and Stuttgart regions host precision polymer processing facilities serving both domestic and export markets.
United States
FDA-regulated UV protection labeling and impact resistance claims create compliance differentiation for safety-positioned eyewear. Amateur cycling event growth in California and Colorado drives fitted-frame demand through specialty retail channels. The Pacific Northwest and Rocky Mountain states concentrate outdoor recreation retail networks that emphasize prescription compatibility services.
Belgium
Dense cycling club networks and classic race calendar density generate uniform eyewear mandates through sponsor compliance requirements. CE marking under the EU Personal Protective Equipment directive shapes product launch timelines for safety-grade positioning. The Flanders region anchors specialty retail distribution with mobile optometry services deployed at major race expos.
India
Bureau of Indian Standards has yet to mandate cycling-specific impact standards, creating first-mover positioning for brands establishing localized assembly. Price-sensitive recreational cyclists favor contact lens and generic frame combinations, compressing sunglass volume in sub-premium tiers. Maharashtra and Karnataka states concentrate emerging cycling communities with growing amateur event participation.
Italy
Regional cycling federations maintain dense membership networks that negotiate group pricing and distribute fitted eyewear through event-based channels. ECHA substance restrictions on chromium-based coatings force reformulation of lens stack architectures for domestic and export markets. The Lombardy and Veneto regions host design-focused manufacturers emphasizing interchangeable lens systems for triathlon and stage racing applications.
Cycling Sunglasses Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with proprietary lens technology and in-house coating capabilities determining margin capture. The capital-intensity gap between premium manufacturers and mass-market assemblers is narrowing as photochromic chemistry patents expire across Asian jurisdictions. Three archetypes dominate: technology-integrated leaders with captive polymer processing, design-specialist houses leveraging regional manufacturing heritage, and regulatory-compliance leaders extending occupational safety expertise. Competitive moves concentrate on backward integration into lens substrate manufacturing and strategic partnerships with cycling event organizers for channel access.
Among technology-integrated leaders, Oakley occupies a position exemplifying proprietary lens architecture and professional team sponsorship density. Rudy Project represents the design-specialist archetype with Italian-engineered interchangeable systems. Uvex Sports anchors the regulatory-compliance vector, leveraging European certification heritage into performance cycling positioning.
| Leading Market Players |
|---|
| Oakley |
| Nike Vision |
| Adidas Eyewear |
| Rudy Project |
| Uvex Sports |
| Under Armour |
| Smith Optics |
| POC Sports |
| Shimano |
| Others |
Supply Flow & Price Mechanics
Six-to-nine month CE marking timelines for the EU Personal Protective Equipment directive concentrate pricing power among incumbent manufacturers with pre-certified substrate inventories, while Asian frame assemblers absorb margin compression from photochromic chemistry patent expirations. This lead-time asymmetry stratifies the market between safety-grade positioning premiums and commodity frame tiers.
Pricing Analysis
Aftermarket replacement lens revenue sustains lifetime value for interchangeable system manufacturers, though photochromic single-lens solutions are collapsing this model. Three-tier pricing structure across premium, standard, and economy levels separates prescription-integrated fitted frames from modular sport systems and generic impact-resistant alternatives. Pricing pressure stems from contact lens substitution among recreational cyclists, compressing volume in sub-premium sunglass tiers. Competitive amateurs in Germany and Belgium show lowest price sensitivity, prioritizing aerodynamic geometry and prescription compatibility.
Supply Chain Analysis
Strait of Malacca transit vulnerability exposes optical-grade polycarbonate feedstock flows from South Korean and Taiwanese petrochemical conglomerates to force majeure disruption. Frame manufacturing draws from Chinese injection-molding clusters, Japanese precision coating specialists, and Italian design houses for triathlon-focused interchangeable platforms. Single-source vulnerability concentrates in silver halide and naphthopyran dye supply for photochromic substrates. Distribution runs through German specialty retail with prescription services, Belgian mobile optometry at race expos, and direct-to-consumer platforms for replacement lens categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where direct-to-consumer prescription integration platforms are displacing specialty retail's aftermarket capture, accelerated by cycling club group-purchasing mandates that standardize eyewear specifications across member networks.
For Market Incumbents: Fortify backward integration into lens substrate manufacturing to capture margin pools migrating from proprietary coating holders toward integrated producers with captive polymer processing. Deepen event-based channel control through exclusive partnerships with Belgian and Dutch race organizers to defend against mobile optometry disruption. Prioritize REACH-compliant bio-nylon frame certification to sustain premium positioning as ECHA restrictions tighten on petroleum-derived polymers. For New Entrants and Emerging Players: Anchor in India's underpenetrated cycling eyewear segment ahead of anticipated Bureau of Indian Standards regulatory expansion, where localized assembly creates first-mover advantage before impact standard mandates crystallize. Target gravel cycling's mixed-terrain racing formats with photochromic-polarized hybrid lens development. Pursue cycling federation group-purchasing contracts as the primary go-to-market channel, leveraging sponsor compliance requirements for uniform eyewear mandates. For Investors and Strategic Acquirers: Long-term, this sits as a specialty-chemical-platform play because photochromic dye stability and sol-gel silica coating expertise concentrate value capture in substrate manufacturing rather than frame assembly. Acquisition targets should display in-house coating capabilities and captive polymer processing infrastructure. Monitor CE marking timeline compression or BIS regulatory activation as the critical inflection signal for margin redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lens Substrate Manufacturing | Captures margin pools shifting from coating patent holders to integrated producers with captive polymer capabilities. |
| REACH-Compliant Bio-Nylon Certification | Opens certification premiums as ECHA restrictions eliminate chromium-based coating alternatives from European supply chains. |
| Event-Based Mobile Optometry Partnerships | Secures channel access at Belgian and Dutch race expos where club-organized group purchasing concentrates volume. |
| Direct-to-Consumer Prescription Integration Platforms | Displaces specialty retail aftermarket capture through seamless fitted-frame ordering and replacement lens subscription models. |
| Localized Assembly in Pre-Regulatory Markets | Establishes manufacturing footprint ahead of anticipated BIS cycling-specific impact standards in Maharashtra and Karnataka states. |
Methodological Framework
A standing panel of optical product development directors, specialty retail category managers, cycling club procurement officers, and ECHA regulatory affairs specialists provided ongoing calibration across primary fieldwork and secondary validation. Primary interviews combined with customs trade data, SEC eyewear division filings, CE marking notification databases, and cycling federation sponsorship records enabled bottom-up and top-down triangulation of installed base and replacement cycle estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including lens technology type, frame material grade, distribution channel structure, and regional regulatory cluster. CAGRs were derived from fitted-frame penetration rates, amateur racing participation trajectories, and photochromic lens replacement frequency assumptions calibrated against endurance cyclist training patterns.
Material uncertainties — patent cliff acceleration in Asian jurisdictions, REACH authorization scope expansion, and BIS regulatory timeline shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding coating chemistry stability and club-organized purchasing penetration. Practitioners should keep alternative scenarios live as extended producer responsibility mandates for plastic frame take-back programs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Bicycle Crankset Market
Sports Equipment
Parallel Bars Market
Sports Equipment
Middle East and Africa Stand-Up Paddleboard Market
Sports Equipment
Skating Shoes Market
Sports Equipment
Mouthguard Market
Sports Equipment
Tetherball Market
Sports Equipment
Pitching Machine Market
Sports Equipment
Boxing Equipment Market
Sports Equipment
Padel Balls Market
Sports Equipment
Carbon-Fiber Badminton Racquet Market
Sports Equipment
Global Sporting Goods Market
Sports Equipment
Stadium Seating Market
Sports Equipment
Europe Archery Equipment Market
Sports Equipment
Global Wakeboarding Equipment Market
Sports Equipment
Waist Support Belt Market
Sports Equipment
Sports Flooring Market