
 Spools Market | 2026-2036
Spools Market Size, Share, and Industry Trends Forecast 2026-2036
Spools Market Analytics
The EU Green Deal is recalibrating spool material specifications across European supply chains, pushing manufacturers toward recyclable and bio-based alternatives. Emerson Electric Co leverages its process automation expertise to optimize spool production lines for sustainability metrics. Schneider Electric SE anchors its spool sourcing strategy around circular-economy procurement mandates from industrial clients. Siemens AG differentiates through digital twin integration in spool inventory management systems.
Spools are cylindrical devices engineered to wind, store, and dispense flexible materials such as wire, cable, thread, or filament, typically manufactured with precision-machined flanges and load-bearing cores rated for specific tensile stresses and rotational speeds. Plastic spools dominate volume production due to injection-molding scalability and corrosion resistance, though metal spools retain premium positioning in heavy-load cable management applications where thermal stability and structural integrity are non-negotiable. Composite spools represent the fastest-expanding category as hybrid material formulations reduce weight without sacrificing load capacity, particularly in aerospace and offshore electrical wiring deployments where logistics costs amplify material choices.
The EPA oversees industrial emissions standards affecting spool manufacturing facilities in the United States, while REACH and RoHS frameworks in Europe restrict hazardous substances in polymer formulations used for plastic spool production. China's SAMR enforces GB standards for mechanical performance and dimensional tolerances in domestically produced spools serving electrical infrastructure buildouts. Stakeholders must monitor evolving extended-producer-responsibility frameworks that will reshape material selection, recycling obligations, and cross-border compliance costs for spool suppliers serving multinational OEMs.
Market Dynamics
REACH compliance and China's evolving GB standards are forcing spool manufacturers to reformulate polymer compositions and requalify supply chains for wire and cable customers across automotive and telecommunications verticals.
Growth Catalysts
- EU Green Deal mandates:Recyclability requirements are accelerating bio-based spool adoption in European wire harnessing operations serving automotive OEMs.
- Copper and fiber deployment waves:Telecommunications infrastructure buildouts are expanding procurement volumes for precision-machined cable spools rated for high-tensile applications.
- German precision engineering clusters:Concentrated automotive wire harnessing operations in Baden-Württemberg and Bavaria are anchoring regional demand for high-performance metal and composite spools.
Market Restraints
- Petrochemical feedstock volatility:Injection-molding operations for plastic spools face margin compression from fluctuating polymer resin costs tied to crude oil benchmarks.
- Single-source supply concentration:Aerospace-grade carbon fiber for composite spools concentrates among limited North American and Japanese suppliers, creating qualification bottlenecks.
- Heavy-load metal spool substitution ceiling:Thermal stability requirements in offshore electrical wiring prevent full displacement of steel and aluminum cores despite weight penalties.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Domestic cable and component production incentives are creating localized spool demand from contract manufacturers establishing assembly capacity.
- Digital twin integration:Spool inventory management systems converging with IoT-enabled tracking are opening premium pricing tiers for smart-logistics-enabled product lines.
- Extended producer responsibility frameworks:France and Germany's advancing EPR regulations for industrial packaging are creating first-mover advantages for closed-loop spool rental and refurbishment services.
Industry Challenges
- Polymer formulation chemist scarcity:REACH-compliant bio-based material development requires specialized expertise that outpaces current European technical education pipeline output.
- Multi-jurisdiction certification timelines:Simultaneous EPA emissions compliance, REACH substance restrictions, and SAMR GB standard adherence extend product launch cycles by twelve to eighteen months for multinational suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spools Market |
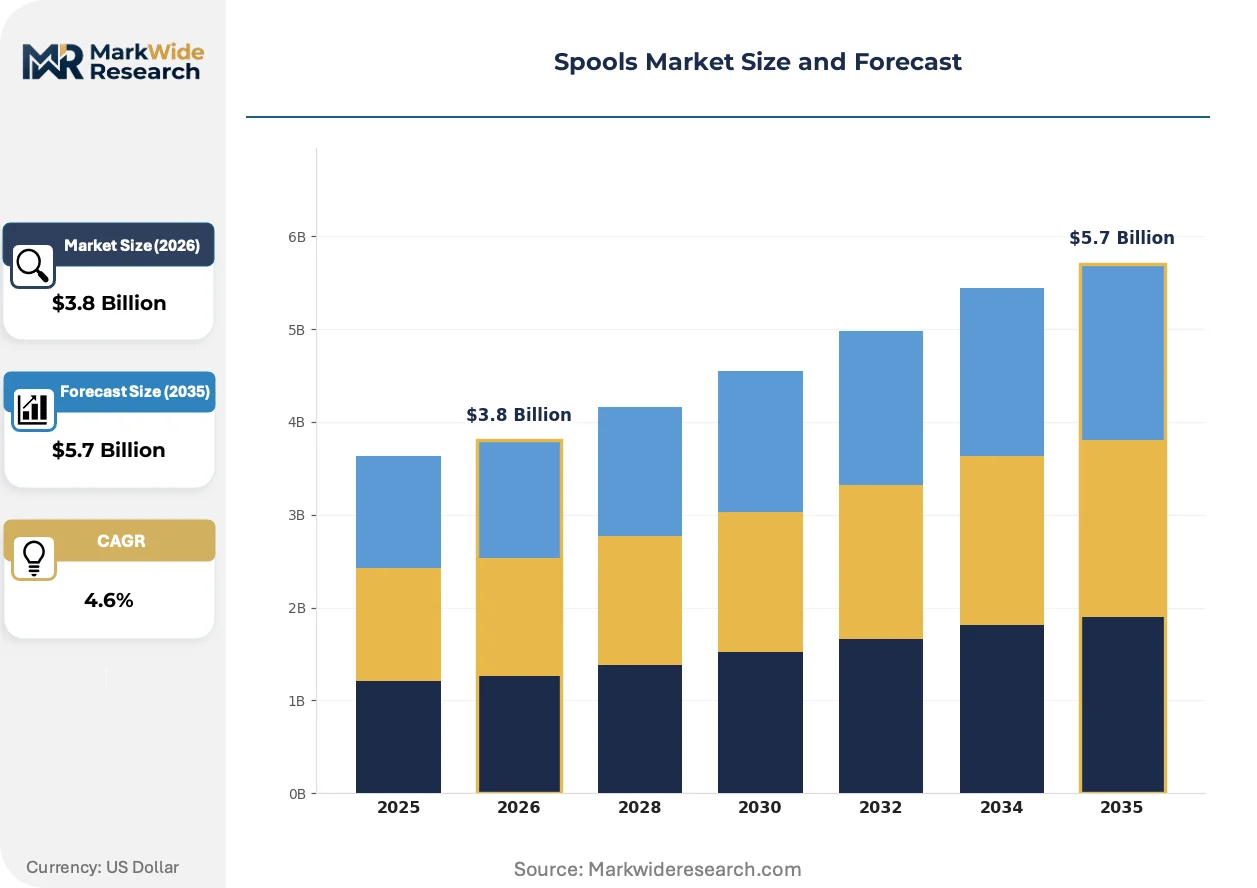
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Spools, Metal Spools, Wooden Spools, Composite Spools Application: Cable Management, Textile Manufacturing, Electrical Wiring, Fishing Size: Small, Medium, Large, Extra Large End User: Manufacturers, Retailers, Wholesalers, Service Providers |
| Companies Covered | Emerson Electric Co, Honeywell International Inc, Schneider Electric SE, Siemens AG, General Electric Company, Weir Group plc, United States Steel Corporation, Nucor Corporation, Tenaris S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spools Market Evolving Landscape
Material science breakthroughs and tightening environmental regulations are restructuring competitive advantage around weight reduction, circularity credentials, and embedded digital capabilities rather than purely mechanical performance.
Composite spool formulations integrating carbon fiber and glass-reinforced polymers are overtaking traditional metal cores in aerospace wire management applications where logistics costs amplify every kilogram. Tier-one harness manufacturers for commercial aviation programs have shifted procurement specifications to hybrid material stacks. This displacement is compressing addressable volume for aluminum spool foundries while expanding margin pools for advanced composite processors with AS9100 certification.
China's SAMR has tightened GB/T dimensional tolerance standards for spools deployed in state-backed electrical grid modernization, forcing domestic manufacturers to upgrade precision machining capabilities. Foreign suppliers must now undergo extended conformity assessment procedures at designated testing institutes. European and North American exporters with established Chinese joint ventures are absorbing compliance costs faster than pure-play importers, reshaping competitive access.
Wire and cable buyers are consolidating vendor relationships around full-service spool management programs encompassing reverse logistics, cleaning, and reconditioning. Distributors serving German automotive clusters have displaced transactional spool sales with multi-year rental agreements tied to usage metrics. This model compresses working capital requirements for harness manufacturers while locking in volume commitments for qualified spool service providers with regional refurbishment infrastructure.
Spools Market Segmentation
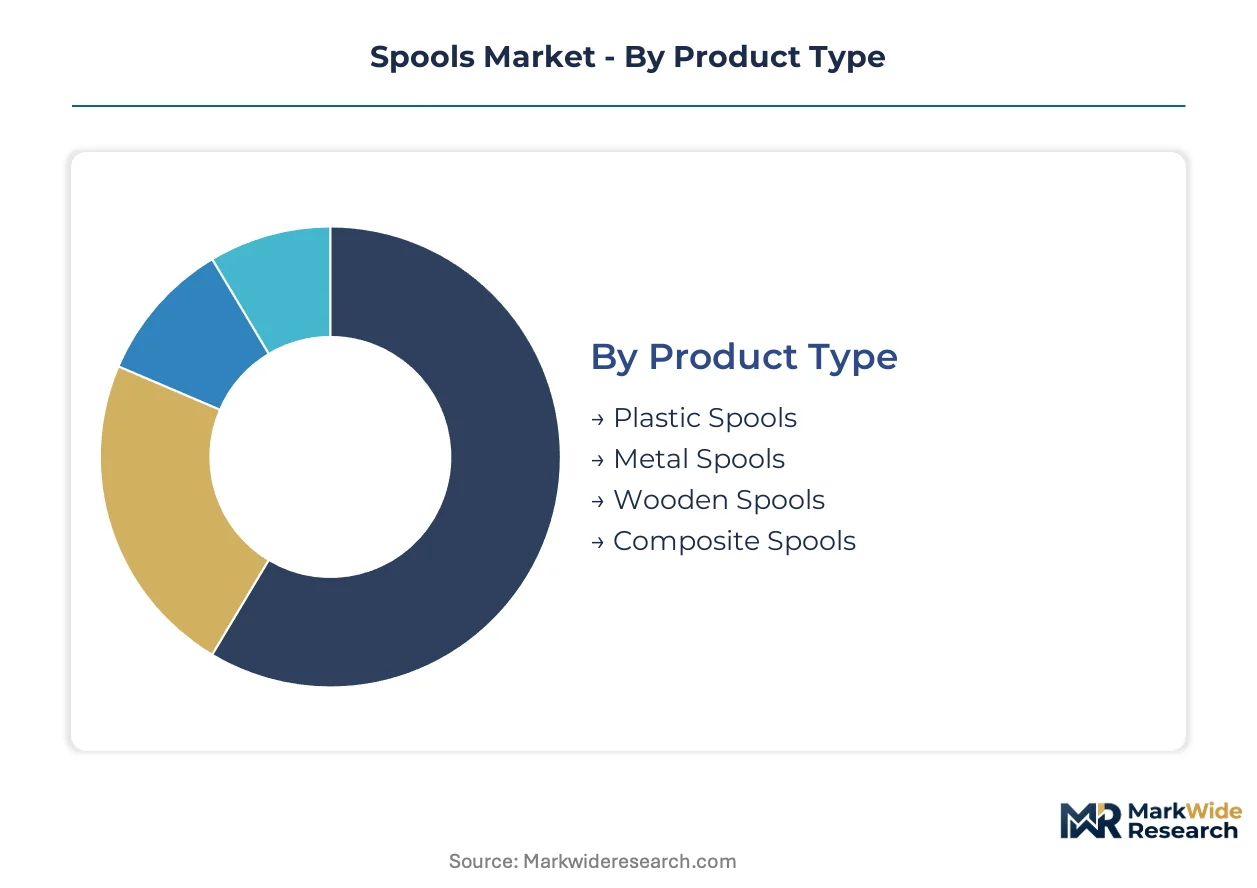
Spool specifications vary dramatically across load-bearing requirements, environmental exposure, and dispensing automation compatibility. Material selection and dimensional precision determine suitability for high-tensile cable deployment versus lightweight textile handling.
Product Type:
Injection-molding scalability and corrosion resistance separate commodity-grade offerings from engineered solutions rated for extreme thermal or mechanical stress.
- Plastic Spools:Polypropylene and ABS formulations dominate volume production through injection-molding economics. REACH-compliant bio-based polymers are gaining share in German automotive wire harnessing operations facing EU Green Deal recyclability mandates.
- Metal Spools:Steel and aluminum cores deliver thermal stability and structural integrity for heavy-load cable management in offshore electrical wiring where composite substitution hits performance ceilings. Aluminum foundries in Baden-Württemberg serve concentrated demand from precision engineering clusters.
- Wooden Spools:Traditional material retains niche positioning in specialty textile and decorative applications with sustainability credentials from renewable sourcing.
- Composite Spools:Carbon fiber and glass-reinforced polymer hybrids reduce weight without sacrificing load capacity. Aerospace wire management programs have shifted procurement specifications toward AS9100-certified composite processors.
Plastic spools lead on scale; composite spools lead on momentum.
Application:
End-use environments dictate flange geometry, core diameter tolerances, and surface finish requirements.
- Cable Management:Precision-machined flanges rated for high-tensile copper and fiber deployments dominate telecommunications infrastructure buildouts. German automotive OEMs specify tight dimensional tolerances for harness assembly automation.
- Electrical Wiring:State-backed grid modernization in China drives demand for GB/T-compliant spools with upgraded precision machining. SAMR conformity assessment procedures favor domestic manufacturers and established joint ventures.
- Textile Manufacturing:Lightweight plastic and wooden constructions predominate where rotational speed and thread tension control matter more than load capacity.
- Fishing:Corrosion-resistant polymer formulations serve commercial and recreational line storage with cost-sensitive specifications.
Cable management commands the largest volume commitment; electrical wiring shows the steepest specification upgrade trajectory.
Size:
Dimensional segmentation maps directly to material handling automation compatibility and logistics cost structures.
- Small:Compact cores serve precision electronics assembly and medical device wiring where space constraints dominate.
- Medium:Standardized dimensions align with automated cable cutting and coiling equipment in high-volume manufacturing.
- Large:Heavy-load construction for industrial power cable and offshore umbilical deployment requires reinforced flanges and steel or composite cores.
- Extra Large:Custom-engineered solutions for submarine cable and specialty industrial applications with project-based procurement.
Medium spools anchor manufacturing automation; large spools carry the highest per-unit value concentration.
End User:
Procurement sophistication varies from transactional volume purchasing to integrated spool-as-a-service models.
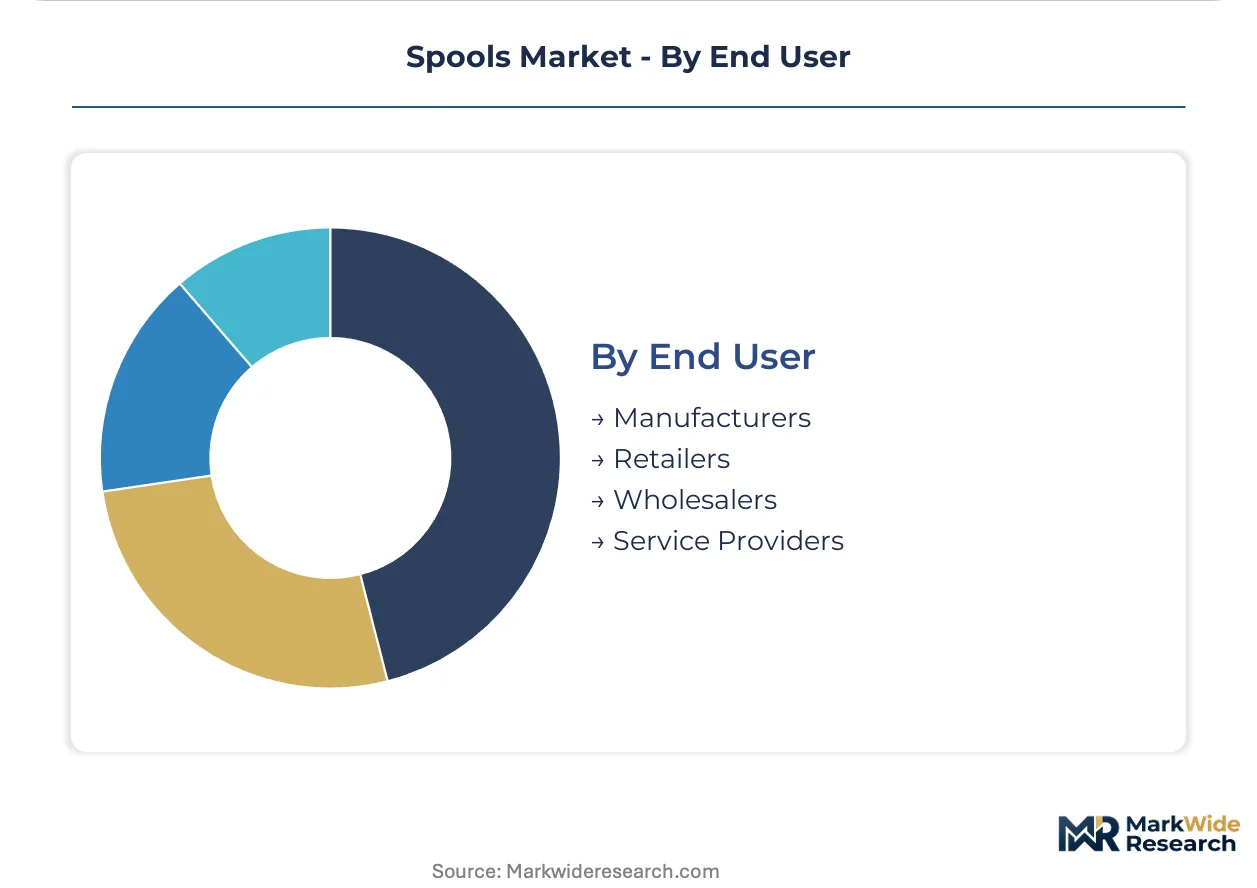
- Manufacturers:Wire and cable producers consolidate vendor relationships around full-service programs encompassing reverse logistics and reconditioning. German automotive clusters have shifted toward multi-year rental agreements tied to usage metrics.
- Service Providers:Specialized spool management companies capture margin pools from refurbishment infrastructure and closed-loop rental services advancing under France and Germany's EPR frameworks.
- Retailers:Consumer-facing distribution of hobbyist and light industrial spools with standardized SKU economics.
- Wholesalers:Inventory aggregation for fragmented downstream demand with limited value-add services.
Manufacturers drive specification intensity; service providers are expanding fastest through circular-economy business model innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering clusters anchor continental spool demand through automotive wire harnessing operations concentrated in Baden-Württemberg and Bavaria. Chinese state-backed grid modernization drives specification upgrades for electrical infrastructure spools. India's electronics manufacturing incentives reshape procurement patterns for cable management components.
United States
Telecommunications infrastructure buildouts accelerate copper and fiber deployment across Texas and California data center corridors. EPA emissions standards constrain polymer formulation choices for domestic injection-molding operations. Houston-based offshore electrical contractors sustain heavy-load metal spool demand for subsea cable management.
Germany
EU Green Deal recyclability mandates push Baden-Württemberg automotive OEMs toward bio-based spool specifications. REACH substance restrictions force polymer requalification across wire harnessing supply chains. Bavarian precision engineering clusters concentrate demand for AS9100-certified composite spools in aerospace applications.
China
State-backed electrical grid modernization drives GB/T-compliant spool procurement for high-voltage transmission projects. SAMR tightened dimensional tolerance standards force precision machining upgrades at domestic manufacturers. Yangtze River Delta cable producers absorb compliance costs faster than pure-play importers.
India
PLI scheme incentives for electronics manufacturing localize spool demand from contract assemblers in Tamil Nadu and Karnataka. BIS mechanical performance standards create entry barriers for unqualified imports. Gujarat chemical hubs supply REACH-compliant polymer feedstocks for export-oriented cable producers.
Japan
Aerospace wire management programs shift procurement toward carbon fiber composite spools from METI-supported advanced materials suppliers. JIS standards maintain tight quality benchmarks for precision-machined flanges. Nagoya aviation clusters concentrate demand for weight-reduced cable handling solutions.
Spools Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures in spool manufacturing. Metal foundries and injection-molding specialists anchor the consolidated upstream, while regional distributors and refurbishment service providers fragment the downstream. Three archetypes dominate: integrated materials processors with captive polymer supply, precision-machining specialists serving aerospace certification requirements, and circular-economy service providers operating closed-loop rental infrastructure. Competitive intensity centers on M&A-driven geographic expansion and strategic partnerships for composite material qualification.
Among diversified industrial conglomerates, Emerson Electric Co, Schneider Electric SE, and Siemens AG exemplify distinct strategic positioning within spool-adjacent automation and electrical infrastructure markets. Emerson leverages process automation expertise across industrial manufacturing verticals. Schneider anchors procurement strategies around circular-economy mandates from multinational industrial clients. Siemens differentiates through digital twin integration in inventory management systems. These players represent the tier where electrical infrastructure scale converges with sustainability-driven specification evolution.
| Leading Market Players |
|---|
| Emerson Electric Co |
| Honeywell International Inc |
| Schneider Electric SE |
| Siemens AG |
| General Electric Company |
| Weir Group plc |
| United States Steel Corporation |
| Nucor Corporation |
| Tenaris S.A. |
| Others |
Value Network & Pricing Analysis
EU Green Deal recyclability mandates gate both qualified supply and premium-tier pricing access, forcing wire harness manufacturers to pay certification premiums for bio-based polymer spools while excluding uncertified injection-molders from German automotive procurement pools. REACH-compliant material qualification costs compress margins for commodity producers but expand pricing power for AS9100-certified composite processors serving aerospace programs.
Pricing Analysis
Bundled spool-as-a-service rental agreements now command 15-25% pricing premiums over transactional unit sales in Baden-Württemberg automotive clusters. Three-tier pricing structure across premium, standard, and economy levels separates AS9100-certified composite spools from REACH-compliant bio-based plastics and commodity polypropylene. Price differentiation hinges on certification grade and after-sales refurbishment infrastructure. Cost compression in commodity plastic tiers is intensifying because petrochemical feedstock volatility erodes injection-molding margins. Small electronics assemblers in Tamil Nadu exhibit highest price sensitivity; German OEMs with circular-economy mandates show lowest.
Supply Chain Analysis
Carbon fiber supply rests on Japanese Toray-grade producers and limited North American specialty chemical manufacturers, creating single-source vulnerability for aerospace-grade composite spools. Raw material dependencies span Saudi petrochemical feedstocks for polypropylene, Yangtze River Delta precision machining capacity for GB/T-compliant metal flanges, and Gujarat chemical hubs for REACH-compliant polymer formulations. Distribution runs through German wire harnessing clusters, Chinese state grid contractors, and Indian PLI-scheme electronics assemblers. Tariff exposure on Japanese carbon fiber imports threatens composite spool cost structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Spools Market functions as a stable compounder anchored by infrastructure-driven wire and cable deployment cycles with predictable replacement demand. Copper and fiber telecommunications buildouts sustain procurement volumes regardless of macroeconomic volatility.
For Market Incumbents: To counter single-source carbon fiber concentration, secure long-term offtake agreements with Japanese specialty chemical producers or invest in glass-reinforced polymer hybrid formulations that reduce aerospace-grade dependency. Backward integration into REACH-compliant polymer compounding in Gujarat chemical hubs insulates margin structures from petrochemical volatility.
For New Entrants and Emerging Players: Regional refurbishment service providers represent the most penetrable white-space target, as France and Germany's advancing EPR frameworks create first-mover advantages for closed-loop rental infrastructure. India's PLI-scheme electronics manufacturing clusters offer localized demand entry with lower certification barriers than German automotive. Partner with Tamil Nadu contract assemblers for anchor volume commitments.
For Investors and Strategic Acquirers: Roll-up economics work for regional spool refurbishment specialists because fragmented service provider landscapes and EPR-mandated circular-economy transitions concentrate procurement authority with scaled closed-loop operators. Target AS9100-certified composite processors with established aerospace harness manufacturer relationships. Watch carbon fiber qualification timeline compression at Tier 2 Chinese suppliers as inflection indicator for supply-side competition intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Gujarat chemical hubs enable REACH-compliant captive supply for export-oriented cable producers. |
| AS9100 Certification Investment | Aerospace wire management programs have shifted procurement specifications toward certified composite processors exclusively. |
| Closed-Loop Rental Infrastructure Buildout | German automotive clusters have displaced transactional sales with multi-year usage-based agreements. |
| Joint Venture with Yangtze River Delta Machining | SAMR conformity assessment procedures favor domestic manufacturers and established joint ventures over pure-play importers. |
| Long-Term Carbon Fiber Supply Agreement | Single-source aerospace-grade concentration creates qualification bottlenecks that anchored contracts resolve. |
Research Methodology
Direct dialogue with wire harness procurement managers, polymer formulation chemists, aerospace Tier 1 supplier quality directors, and spool refurbishment service operators grounded qualitative findings in operational reality. Secondary validation drew from EPA emissions filings, ECHA REACH substance registrations, SAMR GB standard updates, and customs trade data for polymer resin imports. Bottom-up segment sizing triangulated against top-down infrastructure deployment forecasts across telecommunications and electrical grid verticals.
Segment-level outputs across material type, application environment, dimensional class, and end-user procurement model fed into analytical framework over the projection horizon. CAGRs were derived from infrastructure investment trajectories, regulatory compliance cost absorption curves, and substitution elasticity between metal, plastic, and composite formulations. Wire and cable OEM capex disclosures and state-backed grid modernization procurement schedules provided industry-specific demand anchors.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon fiber supply expansion, EPR framework adoption velocity, and petrochemical feedstock regime shifts. Forecasts reflect documented assumptions on material substitution rates and certification timeline standardization. Material deviation in aerospace program ramp schedules or REACH substance restriction amendments warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Automatic Webbing Cutting Machines Market
Textile Machinery and Equipment
Global Weaving Machinery Market
Textile Machinery and Equipment
Textile Tester Market
Textile Machinery and Equipment
Europe Fabric Shavers Market
Textile Machinery and Equipment
Portable Fabric Canopies Market
Textile Machinery and Equipment
Fabric Reversing Machines Market
Textile Machinery and Equipment
Global Rotary Clothes Dryer Market
Textile Machinery and Equipment
Warping Machines Market
Textile Machinery and Equipment
Dyeing Machine Market
Textile Machinery and Equipment
Hoarding Tarpaulin Market
Textile Machinery and Equipment
Tarpaulin Market
Textile Machinery and Equipment
Compact Spinning Machine Market
Textile Machinery and Equipment
Tarpaulin Sheets Market
Textile Machinery and Equipment
Textile Mill Electric Drives Market
Textile Machinery and Equipment
Automatic Fabric Folding Machines Market
Textile Machinery and Equipment
Embroidery Equipment Market