
 Fabric Reversing Machines Market | 2026-2036
Fabric Reversing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Fabric Reversing Machines Market Insights
The EU Green Deal is repositioning European textile finishers toward equipment with verified energy consumption profiles. Rieter Holding AG leverages its Swiss engineering heritage to dominate precision servo-driven reversing systems for technical fabric mills. Trützschler Group SE anchors its competitive stance through deep integration with downstream carding and drawing lines. Saurer Intelligent Technology AG differentiates via programmable automation platforms that reduce operator intervention in high-volume upholstery plants.
Fabric reversing machines mechanically invert textile rolls to enable uniform finishing, inspection, or coating on both sides, typically handling widths from 1.6 to 3.4 meters at speeds up to 120 meters per minute depending on fabric weight and tension control. The equipment serves as a critical bridge process between weaving or knitting and final finishing, eliminating manual handling that introduces creasing or edge damage. Automatic configurations command the largest installed base among product types due to labor cost pressures in South Asian garment export clusters, while servo-driven technology captures the fastest expansion as mills replace mechanical clutch systems for tighter tension control across technical fabrics and canvas processing. Electro-mechanical systems retain significant share in mid-scale upholstery production where capital constraints limit full automation.
CE marking under the EU Machinery Directive and REACH chemical compliance frameworks shape equipment specifications for European textile finishers, while India's BIS certification mandates electrical safety standards for imported automation components. The US OSHA lockout/tagout requirements influence guard design and emergency stop configurations for machines deployed in American apparel manufacturing. Stakeholders must monitor how evolving energy efficiency standards in multiple jurisdictions affect retrofit versus replacement decisions for existing mechanical reversing lines.
Market Dynamics
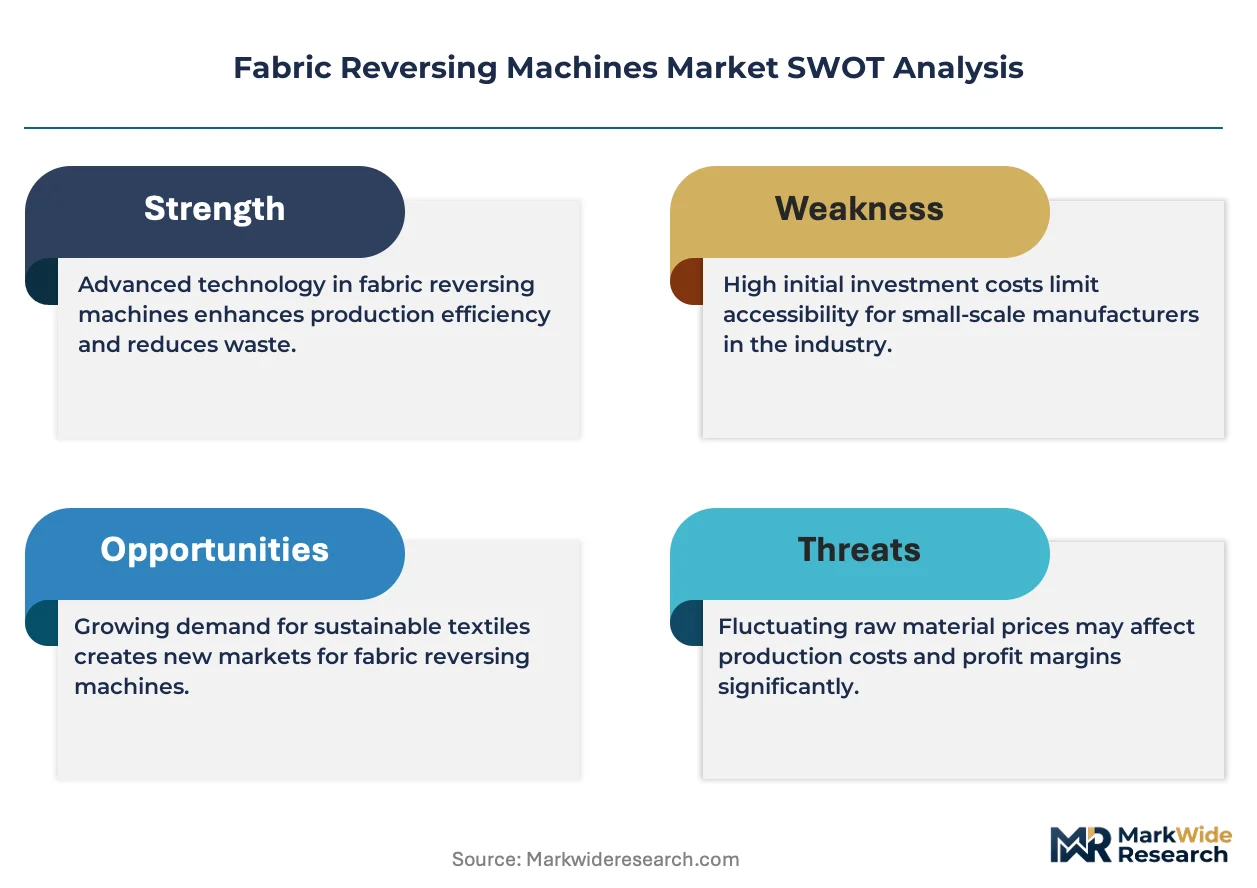
EU Green Deal compliance deadlines are forcing technical fabric mills to retire mechanical clutch systems in favor of servo-driven reversing equipment with verified energy consumption profiles, compressing replacement cycles across European finishing operations.
Growth Catalysts
- EU Green Deal energy mandates:Germany's technical textile producers face binding efficiency targets that accelerate automated reversing system deployment in finishing halls.
- Tamil Nadu export manufacturing:India's garment export belt concentrates demand for servo-driven systems as labor costs rise in Coimbatore and Tiruppur clusters.
- Servo motor precision:Tension control accuracy below 0.5% variance enables technical fabric processors to handle carbon fiber and aramid composites without edge damage.
Market Restraints
- Copper and rare-earth magnet costs:Servo motor bill-of-materials exposure to NdFeB magnet pricing volatility compresses OEM margins on precision systems.
- Component supply concentration:German and Swiss drive controller manufacturers dominate high-torque servo electronics, creating single-source risk for Asian system integrators.
- Mechanical clutch durability:Legacy electro-mechanical reversing units in mid-scale upholstery plants operate for 15-20 years, extending replacement timelines.
Strategic Opportunities
- US technical textile reshoring:Defense and aerospace fabric specifications are pulling finishing capacity back to South Carolina and North Carolina, opening greenfield equipment demand.
- REACH chemical compliance retrofit:European finishers must upgrade ventilation-integrated reversing lines to handle water-based coating chemistries, creating aftermarket attachment sales.
- IIoT predictive maintenance convergence:Vibration sensors and edge computing modules enable remote tension monitoring, shifting revenue from hardware to subscription diagnostics.
Industry Challenges
- Servo tuning expertise gap:Commissioning engineers with PID loop optimization skills for multi-axis tension control command premium wages in South Asian manufacturing hubs.
- CE marking timeline compression:EU Machinery Directive conformity assessment for programmable safety systems extends delivery lead times by 8-12 weeks for non-European OEMs.
- Legacy PLC integration friction:1990s-era finishing lines with proprietary fieldbus architectures require gateway hardware to connect modern servo drives, inflating retrofit scope.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fabric Reversing Machines Market |
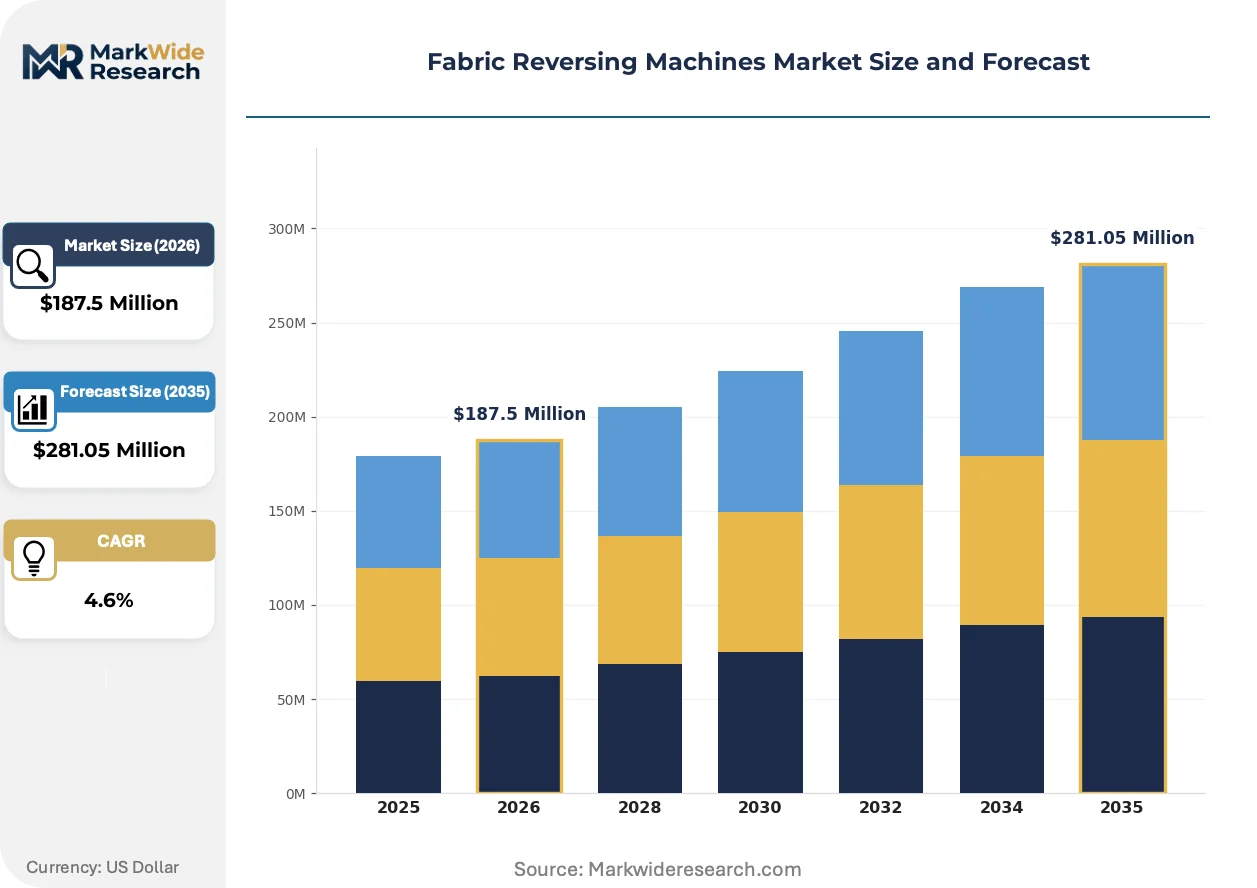
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $281.05 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Robotic, Hydraulic Technology: Mechanical, Electro-Mechanical, Pneumatic, Servo-Driven, Programmable Logic Controller Application: Textile Mills, Apparel Manufacturing, Upholstery Production, Technical Fabrics, Canvas Processing End User: Garment Manufacturers, Fabricators, Home Furnishing Makers, Industrial Stitchers, Export Houses |
| Companies Covered | Sarangal Steel Works, Shree Anjani Engineering, Guruson International, Seaman Power Steam, 3v International, Rieter Holding AG, Trützschler Group SE, Saurer Intelligent Technology AG, OC Oerlikon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fabric Reversing Machines Market Trends and Innovations
Digital thread technologies and closed-loop tension algorithms are absorbing capital investment that previously flowed into mechanical speed governors and pneumatic brakes, shifting competitive advantage toward software-defined control architectures.
Direct-drive torque motors are absorbing the clutch-brake assemblies that historically mediated speed transitions in heavy canvas and technical fabric processing. Turkish and Italian upholstery mills are retrofitting these motors at 15-20 units annually per mid-scale plant. The technology is absorbing maintenance labor pools while compressing mechanical spare parts revenue for traditional component suppliers.
REACH chemical authorization restrictions on per- and polyfluoroalkyl substances are compelling finishers to reformulate water-repellent coatings with silicone and hydrocarbon alternatives. Reversing machine OEMs must redesign doctor blade geometries and drying tunnel configurations to handle higher-viscosity aqueous formulations. German technical textile clusters are absorbing the bulk of this retooling burden, with BfR food-contact certification timelines extending equipment validation cycles.
Buyer consolidation among North American furniture brands is compressing supplier lists and unbundling after-sales service contracts from capital equipment purchases. Tier-one upholstery manufacturers now negotiate direct spare parts agreements with drive component vendors, bypassing reversing machine OEM service networks. This pattern concentrates procurement leverage in High Point, North Carolina and Grand Rapids, Michigan while fragmenting service revenue across component specialists.
Fabric Reversing Machines Market Segmentation
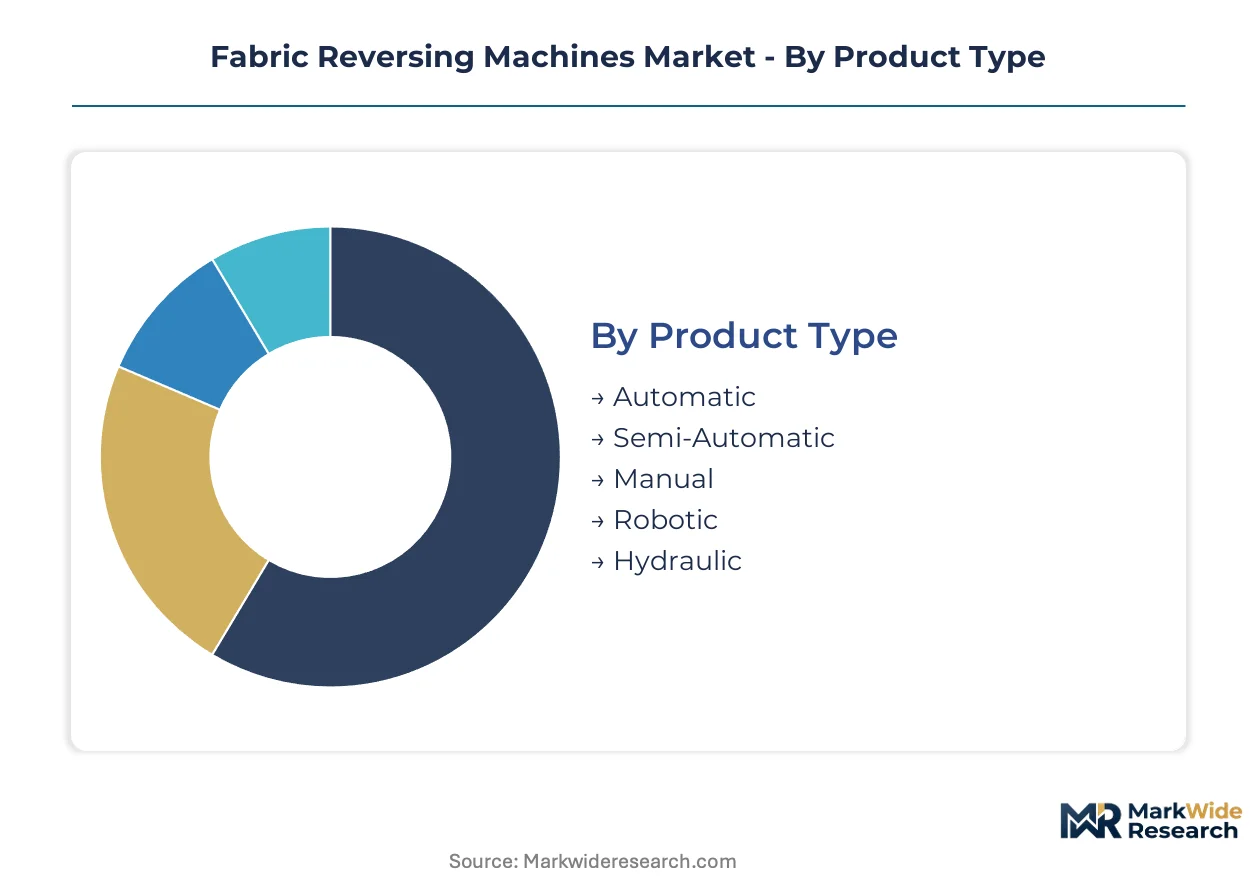
Segmentation in fabric reversing machines reflects divergent capital intensity and labor cost pressures across textile finishing operations. Equipment specification choices determine tension control precision, throughput capacity, and integration complexity with downstream coating or inspection lines.
Product Type:
Automation level determines labor substitution economics and maintenance burden for textile finishers.
- Automatic:These systems integrate programmable web guides and automated edge alignment for continuous operation at 80-120 meters per minute. South Asian garment export clusters in Tamil Nadu and Bangladesh absorb the bulk of new installations as wage inflation accelerates payback calculations for labor substitution.
- Servo-Driven:Precision motor control achieves sub-0.5% tension variance across technical fabrics including carbon fiber and aramid composites. German technical textile producers under EU Green Deal mandates are retiring mechanical systems for these energy-verified configurations despite 40% higher capital outlay.
- Semi-Automatic:Hybrid configurations retain manual loading with automated tension control, serving mid-scale upholstery plants in Turkey and Italy where batch sizes fluctuate.
- Manual:Hand-cranked or foot-pedal reversing units persist in small-batch artisan operations and developing market micro-enterprises with severe capital constraints.
- Robotic:Articulated arm systems handle heavy carpet and canvas rolls exceeding 500 kilograms, penetrating North American furniture manufacturing reshoring projects.
- Hydraulic:Fluid power actuation manages extreme fabric weights in industrial belting and conveyor manufacturing where mechanical clutches would fatigue rapidly.
Automatic configurations lead on scale; servo-driven systems lead on momentum.
Technology:
Drive architecture determines energy efficiency certification eligibility and control precision for specialized fabric handling.
- Servo-Driven:Closed-loop motor control with encoder feedback enables real-time tension adjustment across varying fabric weights and moisture content. European technical fabric mills facing binding efficiency targets under EU Green Deal compliance deadlines are absorbing these systems fastest.
- Mechanical:Clutch-brake assemblies with mechanical speed governors retain installed base in mature upholstery plants where 15-20 year replacement cycles delay capital redeployment.
- Electro-Mechanical:Hybrid systems combining electric motors with mechanical transmission dominate mid-market segments in India's Coimbatore and Tiruppur clusters balancing precision needs against capital constraints.
- Pneumatic:Compressed air actuation serves explosion-sensitive environments in solvent-based coating operations where electrical spark risk must be eliminated.
- Programmable Logic Controller:PLC-based architectures enable recipe-driven operation changeovers and IIoT connectivity for predictive maintenance subscriptions.
Mechanical systems retain legacy dominance; servo-driven architectures are expanding most quickly.
Application:
End-use fabric characteristics dictate width capacity, surface contact requirements, and contamination sensitivity.
- Technical Fabrics:Carbon fiber, glass fiber, and aramid processing demands zero-contamination handling with specialized contact roller materials. Aerospace and automotive composite supply chains in Germany and South Carolina drive specification intensity.
- Upholstery Production:Furniture fabric reversing requires gentle handling of pile and velvet surfaces to prevent crush marks. Turkish and Italian mid-scale plants are retrofitting direct-drive torque motors at 15-20 units annually per facility.
- Textile Mills:High-volume greige fabric inspection and preparation for continuous finishing lines.
- Apparel Manufacturing:Garment piece goods handling with frequent width changeovers and smaller batch sizes.
- Canvas Processing:Heavy-duty industrial textiles including sails, tents, and protective covers requiring robust tension frames.
Upholstery production leads on scale; technical fabrics lead on specification intensity.
End User:
Procurement sophistication and service integration expectations vary sharply across buyer categories.
- Garment Manufacturers:Export-oriented operations in Tamil Nadu and Bangladesh prioritize throughput maximization and labor reduction. These buyers negotiate bundled service contracts including spare parts availability guarantees.
- Export Houses:Trading companies coordinating multi-factory production networks demand standardized equipment specifications across dispersed supplier bases to simplify maintenance training.
- Home Furnishing Makers:Upholstery and curtain manufacturers in High Point and Grand Rapids are unbundling after-sales service from capital purchases, negotiating direct with drive component vendors.
- Fabricators:Cut-and-sew operations with intermittent reversing needs favor semi-automatic configurations.
- Industrial Stitchers:Manufacturers of technical sewn products including automotive airbags and medical textiles.
Garment manufacturers lead on volume concentration; export houses lead on procurement standardization pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German textile engineering heritage established precision reversing systems for technical fabrics during post-war industrial reconstruction. Swiss mechanical automation expertise followed, concentrating servo-drive innovation around Zurich and Winterthur. Italian upholstery machinery builders in Biella and Prato later specialized in gentle-handling configurations for furniture fabrics.
Germany
Technical fabric producers in Baden-Württemberg and North Rhine-Westphalia expand automated reversing capacity to meet binding EU Green Deal efficiency targets. CE marking under the EU Machinery Directive shapes equipment specifications with extended conformity assessment timelines. The Stuttgart industrial corridor hosts retrofit programs replacing mechanical clutch systems with energy-verified servo configurations.
India
Export-oriented garment manufacturers in Tamil Nadu's Coimbatore and Tiruppur clusters upgrade from manual to servo-driven reversing systems as labor costs accelerate. BIS certification mandates electrical safety standards for imported automation components. The state's textile belt concentrates demand for automatic configurations with programmable web guides.
United States
Defense and aerospace fabric specifications pull technical textile finishing capacity back to South Carolina and North Carolina. OSHA lockout/tagout requirements influence guard design and emergency stop configurations for deployed equipment. The Southeast manufacturing corridor opens greenfield demand for robotic systems handling heavy carpet and canvas rolls.
Italy
Mid-scale upholstery plants in Biella and Prato retrofit direct-drive torque motors at 15-20 units annually per facility. REACH chemical authorization restrictions on per- and polyfluoroalkyl substances compel doctor blade geometry redesigns for water-based coatings. The Piedmont textile district absorbs retooling burdens with extended BfR food-contact certification timelines.
Turkey
Furniture fabric finishers in Bursa and Gaziantep adopt servo-driven tension control for velvet and pile surface handling. The country's alignment with EU regulatory frameworks accelerates CE-marked equipment procurement. The Marmara industrial region concentrates hybrid semi-automatic configurations serving fluctuating batch sizes.
Fabric Reversing Machines Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the fabric reversing machines market. European engineering heritage concentrates precision servo-drive manufacturing, while South Asian metal fabricators dominate electro-mechanical assemblies for cost-sensitive segments. Three archetypes define competitive positioning: Swiss-German precision automation specialists, Indian subcontinent volume fabricators, and Italian-Turkish upholstery-focused builders. Consolidation pressure manifests through vertical integration into drive electronics and geographic expansion into reshoring markets.
Among Swiss-heritage precision automation houses, Rieter Holding AG, Trützschler Group SE, and Saurer Intelligent Technology AG exemplify the engineering-intensive tier. These entities anchor high-specification supply to European technical textile and aerospace composite processors. Indian market presence concentrates around metal-forming fabricators including Sarangal Steel Works and Shree Anjani Engineering, representing the volume-accessible segment serving domestic garment export infrastructure. The competitive terrain rewards servo-tuning expertise and programmable safety system integration capability.
| Leading Market Players |
|---|
| Sarangal Steel Works |
| Shree Anjani Engineering |
| Guruson International |
| Seaman Power Steam |
| 3v International |
| Rieter Holding AG |
| Trützschler Group SE |
| Saurer Intelligent Technology AG |
| OC Oerlikon |
| Others |
Pricing and Supply Chain Analysis
Garment manufacturer procurement consolidation in Tamil Nadu and Bangladesh is compressing supplier lists and forcing OEMs to absorb NdFeB magnet cost volatility into fixed-price contracts. This buyer-side concentration is reshaping how servo-drive component vendors negotiate long-term offtake agreements with system integrators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates CE-marked servo systems from electro-mechanical hybrids and basic clutch configurations. Price differentiation hinges on energy efficiency certification grade and bundled after-sales service scope. Cost compression in the economy tier is intensifying because Indian metal fabricators compete on bill-of-materials substitution. Export houses in Coimbatore demonstrate the highest price sensitivity, while German technical textile mills show least sensitivity due to EU Green Deal compliance deadlines.
Supply Chain Analysis
India's phased manufacturing program and domestic-content mandates for textile machinery components are reshaping sourcing patterns for drive electronics and precision bearings. Supply concentrates in Germany, Switzerland, and India, with high-torque servo controllers drawing from German and Swiss specialists. NdFeB rare-earth magnets, copper windings, and precision encoders constitute critical input dependencies. Single-source vulnerability in drive controller electronics creates structural risk for Asian system integrators. Distribution runs through OEM-direct channels for large installations and regional equipment distributors for mid-scale retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fabric reversing machines market functions as a regulatory compounder, with EU Green Deal energy efficiency mandates forcing replacement cycles that would otherwise extend 15-20 years.
For Market Incumbents: Acquire servo-tuning engineering talent pools to defend against emerging software-defined control entrants. Rieter Holding AG and Trützschler Group SE should deepen backward integration into drive electronics manufacturing to capture margin from NdFeB magnet cost volatility. CE marking capability and programmable safety system integration form essential defensive moats against Asian cost competitors. For New Entrants and Emerging Players: Launch via IIoT predictive maintenance subscription models to bypass capital equipment procurement committees. The US technical textile reshoring corridor in South Carolina and North Carolina offers the most penetrable geography, with defense and aerospace fabric specifications creating specification-intensive demand. Target robotic heavy-roll handling configurations for greenfield upholstery manufacturing facilities. For Investors and Strategic Acquirers: Asymmetric upside sits with servo-drive technology specialists possessing CE marking pathways and existing relationships with German technical textile clusters. The five-to-ten year viability window favors acquisition targets with software-defined control architectures and remote diagnostics capabilities. Watch BIS certification timeline compression in India as an inflection indicator for market access friction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Drive Electronics | Captures margin from NdFeB magnet volatility affecting servo motor OEMs. |
| CE Marking Pathway Investment | Accelerates EU market access for non-European system integrators facing conformity assessment delays. |
| IIoT Predictive Maintenance Platform Launch | Shifts revenue from hardware sales to recurring subscription diagnostics in South Asian garment clusters. |
| US Technical Textile Reshoring Partnership | Positions equipment vendors for defense and aerospace fabric finishing capacity expansion in the Southeast. |
| Direct-Drive Torque Motor Retrofit Program | Absorbs maintenance labor pools in Turkish and Italian mid-scale upholstery plants. |
Research Methodology
Bottom-up textile mill capacity modeling reconciled against top-down equipment shipment tracking forms the analytical core of this study. Primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads at technical fabric and upholstery manufacturers were validated against customs records, EU Machinery Directive filing databases, and SEC disclosures from listed textile machinery suppliers. Secondary sources include BIS certification registries, OSHA incident databases, and REACH chemical authorization timelines.
Historical trendline analysis of replacement cycle compression and servo-drive adoption rates informs the projection framework across the analysis window. Segmentation dimensions modeled include automation level, drive architecture, end-use application, and regional regulatory cluster. CAGRs derive from equipment unit economics and payback period sensitivity to labor cost inflation. Industry-specific forecast inputs incorporate EU Green Deal compliance deadline phasing and Tamil Nadu wage trajectory assumptions.
Several conditions sit outside the modeled scope, including unforeseen tariff escalations on Chinese automation components and abrupt REACH chemical authorization reversals. Forecasts reflect documented assumptions about rare-earth magnet price stability and CE marking timeline consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Textile Printer Market
Textile Machinery and Equipment
Fabric Cutting Machines Market
Textile Machinery and Equipment
Automatic Webbing Cutting Machines Market
Textile Machinery and Equipment
Industrial Laminating Machines Market
Textile Machinery and Equipment
Cotton Processing Equipment Market
Textile Machinery and Equipment
Automatic Fabric Folding Machines Market
Textile Machinery and Equipment
Textile Tester Market
Textile Machinery and Equipment
Global Warp Knitting Machine Market
Textile Machinery and Equipment
Global Digital Printing and Dyeing Machine Market
Textile Machinery and Equipment
Global Rotary Clothes Dryer Market
Textile Machinery and Equipment
United States Fabric Shavers Market
Textile Machinery and Equipment
T-Shirt Printing Machine Market
Textile Machinery and Equipment
Tarpaulin Sheets Market
Textile Machinery and Equipment
Asia Pacific Fabric Shavers Market
Textile Machinery and Equipment
Linen Supply and Management Services Market
Textile Machinery and Equipment
Technical Textile Production Equipment Market