
 Textile Mill Electric Drives Market | 2026-2036
Textile Mill Electric Drives Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Mill Electric Drives Market Analytics
IEC 61800-5-1 for adjustable speed electrical power drive systems is redrawing supplier eligibility across the Textile Mill Electric Drives landscape. ABB leverages its variable frequency drive portfolio to dominate high-speed weaving applications in European textile clusters. Siemens anchors its position through digital drive platforms that integrate with mill-wide automation architectures. Schneider Electric differentiates via energy-efficient servo solutions targeting dyeing and finishing lines with precise torque control requirements.
Textile mill electric drives are electromechanical systems that convert electrical power into controlled mechanical motion for spinning, winding, weaving, and finishing equipment, typically operating at 0.75 kW to 500 kW with vector control or direct torque control algorithms to maintain constant tension and synchronous speed across multi-axis processes. AC drives constitute the mature volume base in winding and weaving halls where induction motors prevail, while servo drives capture expanding share in precision finishing stations requiring sub-millimeter positional accuracy. Digital drives represent the fastest-growing technology segment as mills replace analog control cards with Ethernet-connected architectures that feed real-time energy and throughput data to mill management systems.
CE marking under the EU Machinery Directive and IEC 61800 series standards govern product safety and electromagnetic compatibility for drives deployed in European textile facilities, while India's BIS certification mandates specific efficiency grades for motors and drive systems sold into domestic mills. China's GB standards and NMPA-aligned quality supervision protocols shape import qualification for foreign drive suppliers targeting state-level textile upgrading programs. Stakeholders must monitor how efficiency tier migrations and digital connectivity mandates in multiple jurisdictions reshape R&D allocation and factory certification timelines.
Market Dynamics
IEC 61800-5-1 safety standard revisions are forcing drive suppliers to redesign thermal management and fault-tolerant architectures, compressing product development cycles while elevating qualification costs for entry into European and Asian textile parks.
Growth Catalysts
- Non-woven fabric expansion:Producers in Vietnam and India are modernizing carding and spinning lines, creating sustained demand for high-torque servo configurations in hygiene and medical textile segments.
- CE marking convergence:EU Machinery Directive alignment with IEC 61800 electromagnetic compatibility mandates is streamlining cross-border equipment approvals for integrated mill operators.
- Integrated textile park clustering:State-backed industrial zones in China concentrate procurement volume, enabling bulk drive installations with shared maintenance infrastructure and standardized voltage architectures.
Market Restraints
- Rare earth magnet cost volatility:Permanent magnet servo motors depend on neodymium supply chains concentrated in Chinese processing facilities, exposing margin structures to export quota fluctuations.
- Legacy analog replacement inertia:Established mills in Bangladesh and Pakistan face extended payback periods when retrofitting functional mechanical line shafts with digital drive architectures.
- IEC 61800-5-1 compliance burden:Extended thermal cycling and fault-mode testing requirements stretch certification timelines to 14-18 months for new product introductions.
Strategic Opportunities
- Digital thread integration:Ethernet-connected drive platforms converging with mill-wide SCADA systems enable predictive maintenance contracts and energy optimization services.
- Sub-regional upgrading in India:Gujarat and Tamil Nadu textile clusters receive central government PLI scheme incentives for efficiency-grade motor and drive replacements.
- Recycled fiber processing:Mechanical recycling lines for polyester and cotton blends require specialized torque control for contaminated feedstock handling, opening niche servo applications.
Industry Challenges
- Field commissioning expertise scarcity:Vector control parameter tuning for multi-axis tension regulation requires specialized technicians, with training pipelines failing to match installation growth in Southeast Asian markets.
- Legacy system protocol fragmentation:Proprietary fieldbus networks from 1990s-era DCS installations resist integration with modern EtherCAT and PROFINET drive interfaces, forcing costly gateway deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Mill Electric Drives Market |
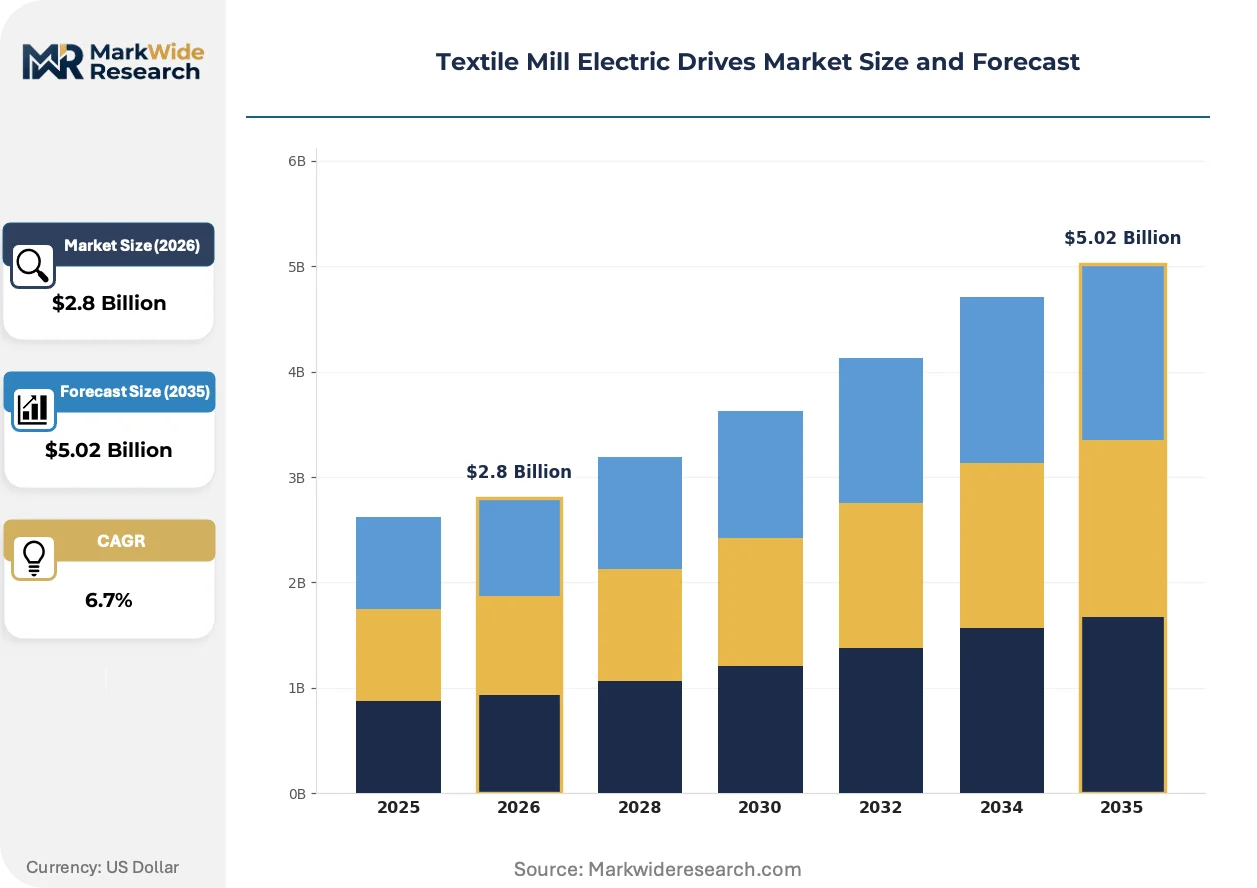
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Drives, DC Drives, Servo Drives, Stepper Drives Technology: Variable Frequency Drives, Direct Current Drives, Servo Technology, Digital Drives Application: Winding, Weaving, Dyeing, Finishing End User: Textile Manufacturers, Apparel Companies, Non-Woven Fabric Producers, Composite Fabric Makers |
| Companies Covered | ABB, Siemens, Schneider Electric, Rieter, Stäubli, Rockwell Automation, Danfoss, Nidec Corporation, Mitsubishi Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Mill Electric Drives Market Evolving Landscape
Digital drive architectures are displacing analog control cards across winding and finishing halls, while regulatory pressure on energy efficiency and safety certification compresses product lifecycles and reshapes supplier qualification pathways.
Vector control algorithms with embedded direct torque estimation are bifurcating the mid-power drive segment. High-speed weaving OEMs in Italy and Germany adopt these platforms for constant tension maintenance across warp beams. The technology is bifurcating supplier tiers, separating vendors with in-house motor modeling capabilities from those dependent on third-party IP cores.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant-free cooling designs in drive power modules. Thermal management engineers now specify heat pipe and liquid cold plate architectures for 75 kW and above installations. European finishing houses face accelerated retrofit deadlines, with Dutch and Portuguese mills already reporting compliance-driven replacement cycles.
After-sales service unbundling is disrupting traditional bundled maintenance contracts in South Asian markets. Bangladeshi and Pakistani mill operators now procure drives and commissioning support separately, sourcing spare parts through independent distributors. This pattern is most visible in Surat and Ludhiana, where local trading houses have captured significant post-warranty service revenue from European OEMs.
Textile Mill Electric Drives Market Segmentation
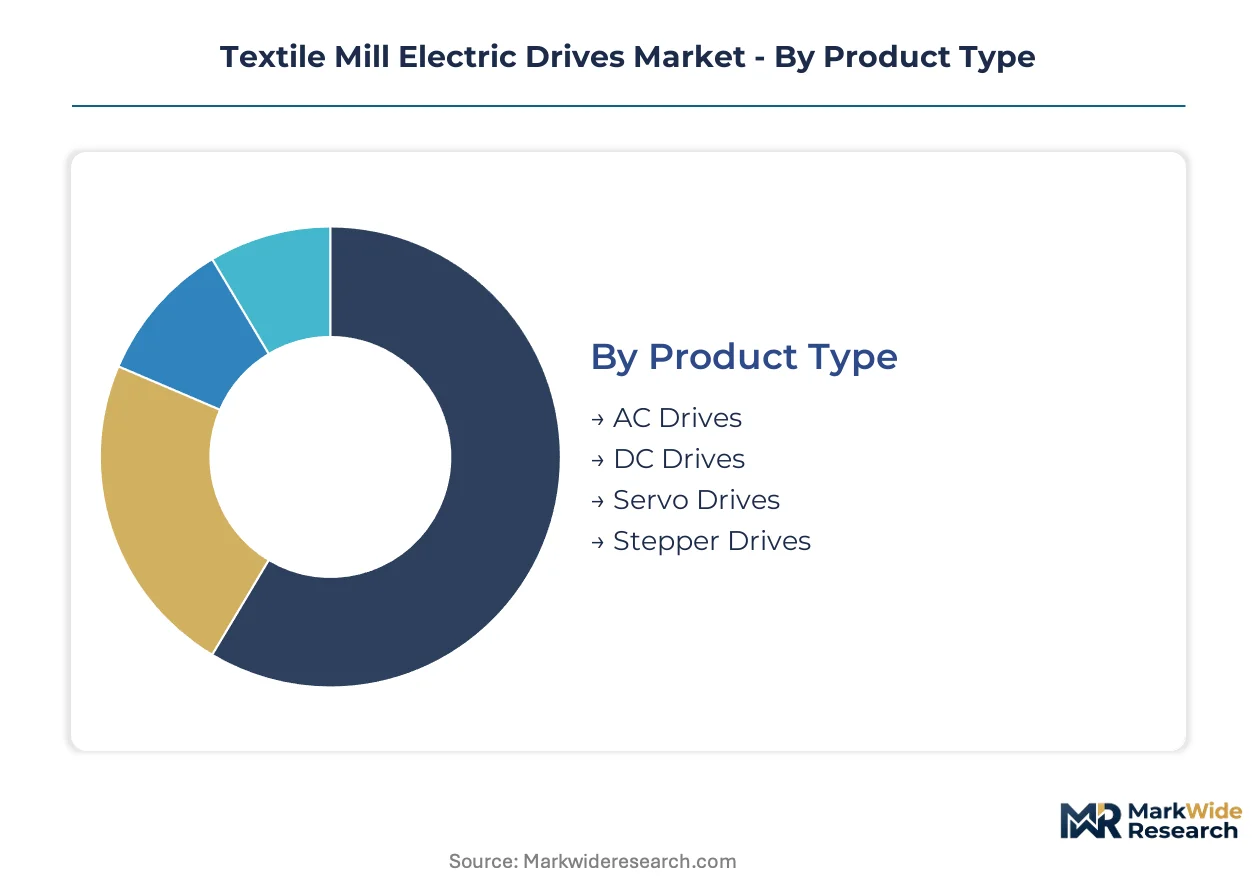
Segmentation in textile mill electric drives reveals how technology choices cascade through procurement decisions, with product type and application requirements dictating power architecture, control algorithms, and compliance pathways across mill installations.
Product Type:
AC drives face substitution pressure from digital servo platforms in precision finishing stations, while DC drives confront obsolescence risk from IEC 61800 efficiency mandates that favor inverter-fed induction systems.
- AC Drives:These variable frequency platforms dominate winding and weaving halls through 0.75 kW to 500 kW power ranges with vector control algorithms. Demand concentrates in China's integrated textile parks where bulk procurement favors standardized induction motor pairings and shared maintenance infrastructure.
- Servo Drives:Closed-loop systems with permanent magnet motors deliver sub-millimeter positional accuracy for dyeing and finishing lines. Non-woven fabric producers in Vietnam and India drive adoption for carding line modernization requiring precise torque control over contaminated feedstocks.
- DC Drives:Thyristor-based architectures persist in legacy mill retrofits where existing wound-field motors resist replacement economics. Pakistan and Bangladesh mills extend equipment life through spare part sourcing from independent distributors.
- Stepper Drives:Open-loop positioning systems serve low-power auxiliary equipment and laboratory-scale textile testing apparatus. These platforms occupy niche applications below 2 kW where cost minimization outweighs dynamic performance requirements.
AC drives anchor the volume base while servo drives gain share at the steepest rate.
Technology:
Cost tier separation is pronounced between mature variable frequency architectures and premium digital drive platforms that command pricing premiums through Ethernet connectivity and predictive maintenance integration.
- Variable Frequency Drives:PWM inverter technology with IGBT power modules constitutes the installed base across spinning and winding operations. European weaving OEMs in Italy and Germany specify these platforms for constant tension warp beam control.
- Digital Drives:Ethernet-connected architectures with embedded edge computing replace analog control cards in mill modernization programs. These systems feed real-time energy and throughput data to mill-wide SCADA infrastructure.
- Servo Technology:Multi-axis coordinated motion systems with absolute encoders enable synchronized operation in high-speed knitting and technical textile production. India's Gujarat and Tamil Nadu clusters receive PLI scheme incentives for efficiency-grade servo installations.
- Direct Current Drives:Ward-Leonard and static converter systems persist in aging mill infrastructure where complete line replacement faces capital constraints. Field commissioning expertise scarcity in Southeast Asian markets extends equipment lifecycles.
Variable frequency drives dominate installed capacity while digital drives expand most quickly through greenfield textile park deployments.
Application:
Volume concentration varies sharply by process stage, with weaving and winding halls representing repetitive high-volume demand versus finishing stations requiring precision motion control at lower unit counts.
- Winding:Tension-controlled take-up and let-off operations demand constant torque maintenance across varying roll diameters. High-speed weaving OEMs specify vector control platforms with direct torque estimation for beam handling.
- Weaving:Loom main drives and auxiliary motions require synchronized multi-axis coordination. European textile clusters drive specification of energy-efficient platforms compliant with EU F-Gas Regulation thermal management requirements.
- Dyeing:Winch and jet dyeing machines require precise speed control for fabric transport through chemical baths. Servo configurations with specialized torque profiles address low-speed high-torque demands.
- Finishing:Calendering, coating, and laminating lines demand sub-millimeter positional accuracy. Thermal management engineers specify heat pipe and liquid cold plate architectures for 75 kW and above installations in Dutch and Portuguese mills facing compliance-driven replacement cycles.
Weaving anchors procurement volume while finishing commands the highest per-unit technology investment.
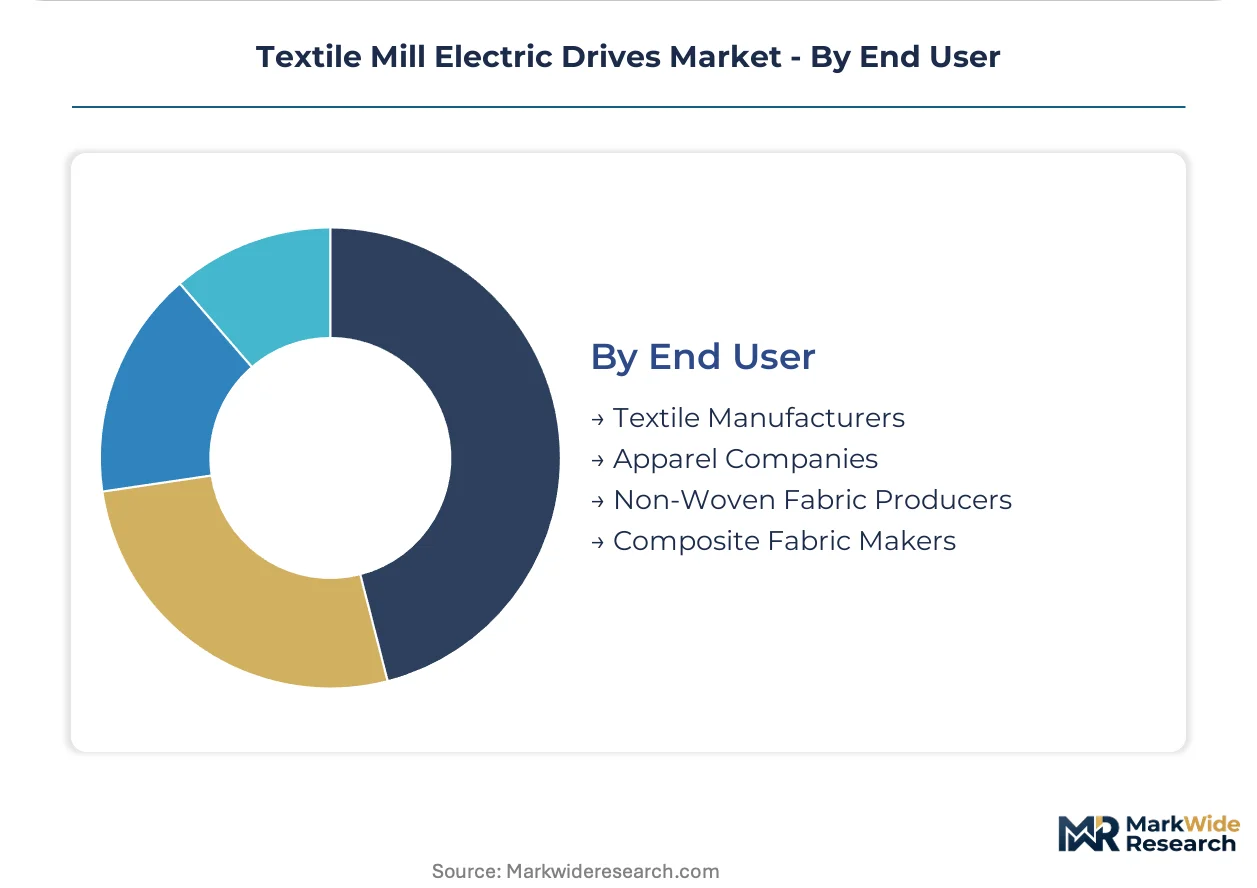
End User:
Customer type determines procurement sophistication, with integrated textile parks leveraging bulk purchasing power versus independent mills sourcing through fragmented distributor networks.
- Non-Woven Fabric Producers:Hygiene and medical textile manufacturers modernize carding and spinning lines with high-torque servo configurations. Vietnam and India concentrate capacity expansion requiring specialized torque control for synthetic fiber processing.
- Textile Manufacturers:Integrated spinning-weaving-dyeing operations drive standardized drive architecture adoption. China's state-backed industrial zones enable bulk installations with shared voltage infrastructures.
- Apparel Companies:Cut-and-sew operations with captive fabric production source drives for finishing and pre-treatment equipment. These end users prioritize digital connectivity for energy optimization services.
- Composite Fabric Makers:Technical textile producers serving automotive and aerospace applications require precision motion control for multiaxial weaving and preform manufacturing. Specialized servo configurations address carbon fiber and aramid handling requirements.
Textile manufacturers represent the largest procurement base while non-woven fabric producers demonstrate the steepest demand acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's dominance in textile machinery imports, while Vietnam's Cai Mep deep-water port complex enables just-in-time drive deliveries to Ho Chi Minh City industrial zones.
China
State-backed textile parks in Jiangsu and Zhejiang provinces concentrate bulk procurement of AC drives for integrated spinning-weaving operations. GB standards and NMPA-aligned quality supervision protocols shape import qualification for foreign suppliers targeting upgrading programs. The Yangtze River Delta cluster around Suzhou and Wuxi drives standardization of voltage architectures across shared maintenance infrastructure.
India
Gujarat and Tamil Nadu textile clusters receive central government PLI scheme incentives for efficiency-grade motor and drive replacements. BIS certification mandates specific efficiency grades for domestic mill installations. Surat's synthetic fiber processing hub sources drives through fragmented distributor networks, unbundling after-sales service from equipment procurement.
Vietnam
Non-woven fabric producers in Binh Duong and Dong Nai provinces modernize carding lines with high-torque servo configurations for hygiene and medical textile segments. The country's national industrial zone authority streamlines environmental permitting for drive-intensive finishing operations. Ho Chi Minh City industrial zones concentrate demand from export-oriented apparel manufacturers.
Germany
High-speed weaving OEMs in Italy and Germany specify vector control platforms with direct torque estimation for constant tension warp beam control. EU F-Gas Regulation phase-down schedules accelerate refrigerant-free cooling designs in drive power modules above 75 kW. The Baden-Württemberg textile machinery cluster around Stuttgart drives specification of energy-efficient platforms.
United States
Technical textile producers serving automotive and aerospace applications in North Carolina and South Carolina require precision motion control for multiaxial weaving. OSHA electrical safety standards and NFPA 79 industrial machinery regulations govern drive installations in modernized facilities. The Piedmont Triad region around Greensboro anchors carbon fiber and aramid handling equipment demand.
Textile Mill Electric Drives Market Competitive Landscape
Listed leaders compete with private specialists across capitalization and geographic reach, creating a tiered structure where scale-driven conglomerates anchor high-volume segments while regional fabricators capture service-intensive niches. European and Japanese electrical giants dominate premium digital drive architectures through integrated automation portfolios. Three archetypes define competitive positioning: full-range automation conglomerates with mill-wide system integration capabilities, drive-focused specialists leveraging thermal management expertise, and regional trading houses capturing post-warranty service revenue. Capacity expansion in Southeast Asian manufacturing zones and strategic partnerships with textile park developers constitute the dominant competitive moves.
Within the full-range automation tier, ABB and Siemens exemplify conglomerate positioning through variable frequency and digital drive portfolios respectively. Schneider Electric occupies a specialist position emphasizing energy-efficient servo configurations. These three anchors demonstrate how European electrical majors leverage CE marking convergence and IEC 61800 series compliance to maintain qualification advantages across integrated textile parks in China and Vietnam.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Schneider Electric |
| Rieter |
| Stäubli |
| Rockwell Automation |
| Danfoss |
| Nidec Corporation |
| Mitsubishi Electric |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with integrated textile park developers lock in both neodymium magnet supply access and price visibility for servo drive manufacturers serving Vietnam and India's non-woven fabric expansion. These arrangements insulate tier-one suppliers from rare earth export quota volatility while compressing margins for spot-market participants.
Pricing Analysis
Certification level under IEC 61800-5-1 and CE marking creates the primary spread between premium digital drive platforms and standard variable frequency architectures. Three-tier pricing structure across IEC-certified premium, BIS-compliant standard, and legacy analog economy levels stratifies procurement in China's state-backed textile parks. Pricing pressure stems from rare earth magnet cost volatility concentrated in Chinese processing facilities. Independent mills in Bangladesh and Pakistan exhibit highest price sensitivity, while European technical textile producers prioritize energy efficiency ratings over unit cost.
Supply Chain Analysis
China, Japan, and Germany anchor power module and IGBT semiconductor fabrication for textile drive systems. Permanent magnet servo motors draw from neodymium supply chains concentrated in Chinese rare earth processing facilities, with additional dependency on copper winding stock and aluminum heat sink extrusions. Single-source vulnerability in magnet alloy refining exposes margin structures to export quota fluctuations. Distribution runs through OEM-direct channels for integrated textile park bulk procurement, while fragmented distributor networks serve South Asian independent mill retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital servo architectures threaten to displace variable frequency drives in precision finishing applications, forcing incumbents to defend installed base through predictive maintenance service bundling and thermal management differentiation.
For Market Incumbents: Fortify qualification advantages under tightening IEC 61800-5-1 thermal cycling mandates by accelerating refrigerant-free cooling designs above 75 kW. Deepen backward integration into permanent magnet motor production to offset neodymium cost volatility exposure. Channel control through captive service networks in Gujarat and Tamil Nadu clusters resists unbundling pressure from independent distributors. For New Entrants and Emerging Players: Anchor in mechanical recycling line retrofits for polyester-cotton blend processing, where specialized torque control requirements create niche servo applications underserved by full-range automation conglomerates. Target Surat and Ludhiana distributor networks with unbundled commissioning support and spare part sourcing. Position through Ethernet-connected edge computing platforms that bypass legacy fieldbus protocol fragmentation. For Investors and Strategic Acquirers: Regional trading houses with captive post-warranty service revenue in Bangladesh and Pakistan represent consolidation targets as European OEMs retreat from direct aftermarket support. Long-term viability hinges on digital thread integration capabilities converging with mill-wide SCADA infrastructure. Monitor PLI scheme disbursement velocity in India's Gujarat and Tamil Nadu clusters as inflection indicator for efficiency-grade replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant-Free Thermal Management Transition | EU F-Gas Regulation compliance accelerates heat pipe and liquid cold plate adoption above 75 kW in Dutch and Portuguese finishing mills. |
| Digital Drive Architecture Migration | Ethernet-connected platforms displace analog control cards in China's Yangtze River Delta integrated textile parks. |
| Predictive Maintenance Service Bundling | Real-time energy and throughput data feeds enable contracted optimization services resisting South Asian price erosion. |
| Permanent Magnet Motor Backward Integration | In-house neodymium supply chain control insulates margin structures from Chinese export quota volatility. |
| Regional Trading House Acquisition | Post-warranty service revenue capture in Surat and Ludhiana defends against independent distributor encroachment. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from listed electrical equipment manufacturers, and IEC certification databases. Mill maintenance directors, OEM procurement teams at Italian and German high-speed weaving equipment builders, and aftermarket service heads at regional trading houses in Surat and Ludhiana provided stakeholder perspective. Bottom-up installation tracking across China's state-backed textile parks triangulates with top-down trade flow analysis.
Segmentation dimensions modeled span product type, technology architecture, application process stage, and end-user procurement sophistication across the projection horizon. CAGRs derive from installed base turnover rates, greenfield textile park development pipelines, and regulatory compliance deadline clustering. Vector control algorithm adoption curves and servo drive penetration in non-woven carding lines constitute industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained PLI scheme disbursement in India and stable rare earth export policy in China; material deviation would warrant model refresh. Recalibration cycles align with IEC 61800-5-1 revision schedules and EU F-Gas Regulation phase-down milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
United States Fabric Shavers Market
Textile Machinery and Equipment
Global Weaving Machinery Market
Textile Machinery and Equipment
Fiber Spinning Equipment Market
Textile Machinery and Equipment
Industrial Laundry Market
Textile Machinery and Equipment
Netted Fabrics Market
Textile Machinery and Equipment
Multifunctional Clothes Folding Machine Market
Textile Machinery and Equipment
Global Knitting Machinery Market
Textile Machinery and Equipment
Braiding Machine Market
Textile Machinery and Equipment
Global Textile Machinery Market
Textile Machinery and Equipment
Warping Machines Market
Textile Machinery and Equipment
Asia Pacific Fabric Shavers Market
Textile Machinery and Equipment
Textile Tester Market
Textile Machinery and Equipment
Industrial Laminating Machines Market
Textile Machinery and Equipment
US Textile Processing Machinery Market
Textile Machinery and Equipment
Cloth Cutting Machines Market
Textile Machinery and Equipment
Global Digital Printing and Dyeing Machine Market